
 Industrial Flexible Packaging Market | 2026-2036
Industrial Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Flexible Packaging Market Foresight
Asset-light leasing models for converting equipment are reshaping competitive entry in industrial flexible packaging. Amcor plc leverages its global film supply network to sustain cost advantages across multiple geographies. Mondi anchors its position through integrated pulp-to-paper packaging operations in European industrial zones. Sealed Air differentiates via proprietary barrier technologies that extend product protection cycles for manufacturers.
Industrial flexible packaging comprises engineered films, laminates, and formed substrates typically ranging from 50 to 250 microns in thickness, designed to protect bulk commodities and intermediate goods during storage, handling, and transport. These structures combine polyethylene, polypropylene, or aluminum layers to achieve moisture, oxygen, and mechanical resistance tailored to chemical, agricultural, and construction materials. Bags and pouches lead volume demand from food and pharmaceutical applications where contamination control is critical. Composite materials represent the fastest-expanding material category as converters balance performance requirements against recyclability mandates. Plastic substrates still dominate tonnage but face margin compression from regulatory pressure on single-use formats.
EMA chemical safety standards, REACH substance restrictions, and FDA food contact regulations collectively dictate material selection, migration limits, and labeling requirements across major supply corridors. ECHA scrutiny of perfluorinated compounds is forcing reformulation of high-barrier coatings used in pharmaceutical and chemical packaging. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in mono-material recyclable structures or advanced sorting-compatible multilayers before compliance deadlines tighten.
Market Dynamics
REACH substance restrictions and ECHA scrutiny of perfluorinated compounds are forcing rapid reformulation of high-barrier coatings across pharmaceutical and chemical packaging supply chains, redirecting capital toward mono-material recyclable structures before compliance deadlines tighten.
Growth Catalysts
- EU Packaging Waste Directive:Compliance mandates are redirecting investment toward recyclable composite structures in Germany and Central European manufacturing corridors, accelerating demand for sorting-compatible multilayer films.
- High-barrier pouch technology:Food manufacturers are expanding deployment of extended shelf-life formats for perishable and intermediate goods, creating sustained pull for engineered laminates with oxygen and moisture resistance.
- Industrial packaging clusters:Concentrated converter networks in Germany serve cross-border manufacturing demand from Poland, Czech Republic, and Austria, generating regional scale economies for bulk film supply.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene and polypropylene resin prices fluctuate with crude oil and natural gas benchmarks, compressing converter margins and complicating long-term contract pricing.
- Aluminum layer dependency:High-barrier applications require foil laminates that face supply concentration from limited European smelter capacity and import exposure to energy-cost-sensitive producers.
- Recyclability-performance tradeoff:Mono-material structures meeting EEA sorting standards often sacrifice barrier properties versus legacy multilayer formats, limiting substitution in pharmaceutical and aggressive chemical applications.
Strategic Opportunities
- Extended producer responsibility frameworks:Advance recycling fee structures in France and Italy create first-mover advantages for converters with certified circular material flows and mass-balance accounting systems.
- Agricultural bulk packaging:Fertilizer and seed treatment applications in Eastern Europe remain underpenetrated by high-performance barrier formats, offering volume expansion for moisture-resistant woven laminates.
- Digital printing convergence:Integration of inline flexographic and inkjet systems with form-fill-seal lines enables short-run customization for private-label food manufacturers, collapsing minimum order quantity constraints.
Industry Challenges
- Migration testing capacity:FDA and EFSA food contact compliance requires specialized analytical laboratories with extended queue times, delaying new product launches and reformulation cycles.
- Legacy equipment retrofit costs:Existing converting lines designed for solvent-based adhesives require capital-intensive upgrades to handle water-based or UV-cured alternatives meeting VOC regulations.
- Perfluorinated compound phase-out timeline:ECHA restriction proposals for PFAS coatings lack definitive sunset dates, creating planning paralysis for pharmaceutical barrier film investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Flexible Packaging Market |
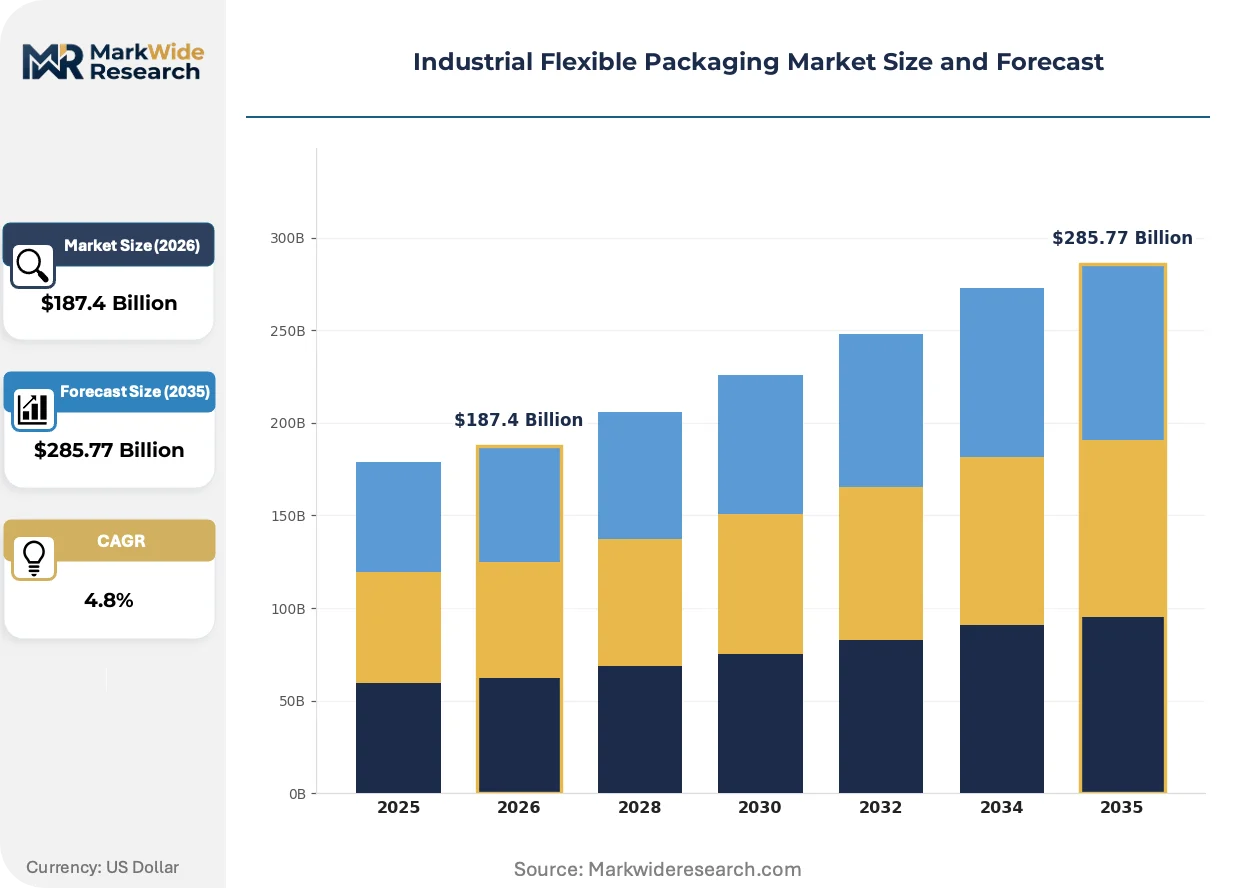
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Wraps, Tapes Material: Plastic, Paper, Aluminum, Composites Application: Food, Beverage, Pharmaceutical, Consumer Goods End User: Manufacturers, Distributors, Retailers, Exporters |
| Companies Covered | Amcor plc, Smurfit Westrock, Mondi, Sealed Air, Huhtamaki, Transcontinental Inc., Sonoco Products Company, Constantia Flexibles, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Flexible Packaging Market Shifts & Advancements
Digital manufacturing integration and material science advances are compressing development cycles while regulatory pressure on chemical coatings accelerates substitution toward bio-based and mechanically recyclable alternatives.
Mono-material polyethylene barrier films with enhanced ethylene vinyl alcohol copolymer layers are collapsing the traditional performance gap between recyclable and multilayer structures. Food processors in dairy and ready-meal segments are adopting these formats at accelerated pace to preempt EPR fee structures. The structural consequence is collapsing demand for aluminum-foil laminates in medium-barrier applications previously considered technically locked.
REACH authorization requirements for substances of very high concern are tightening migration limits for chemical contact materials. Industrial consequence includes forced reformulation of adhesive systems and surface treatments across converter networks. Pharmaceutical primary packaging and agricultural chemical containment applications face the steepest compliance burdens, with manufacturers accelerating qualification of fluorine-free barrier coatings.
Equipment-as-a-service models are displacing conventional capital purchase for form-fill-seal and pouch-making machinery. Contract packers and mid-sized food manufacturers in Spain and Portugal are adopting leased converting capacity with bundled maintenance and upgrade provisions. This shift is most visible in private-label segments where volume volatility and SKU proliferation favor operational flexibility over asset ownership.
Industrial Flexible Packaging Market Segmentation
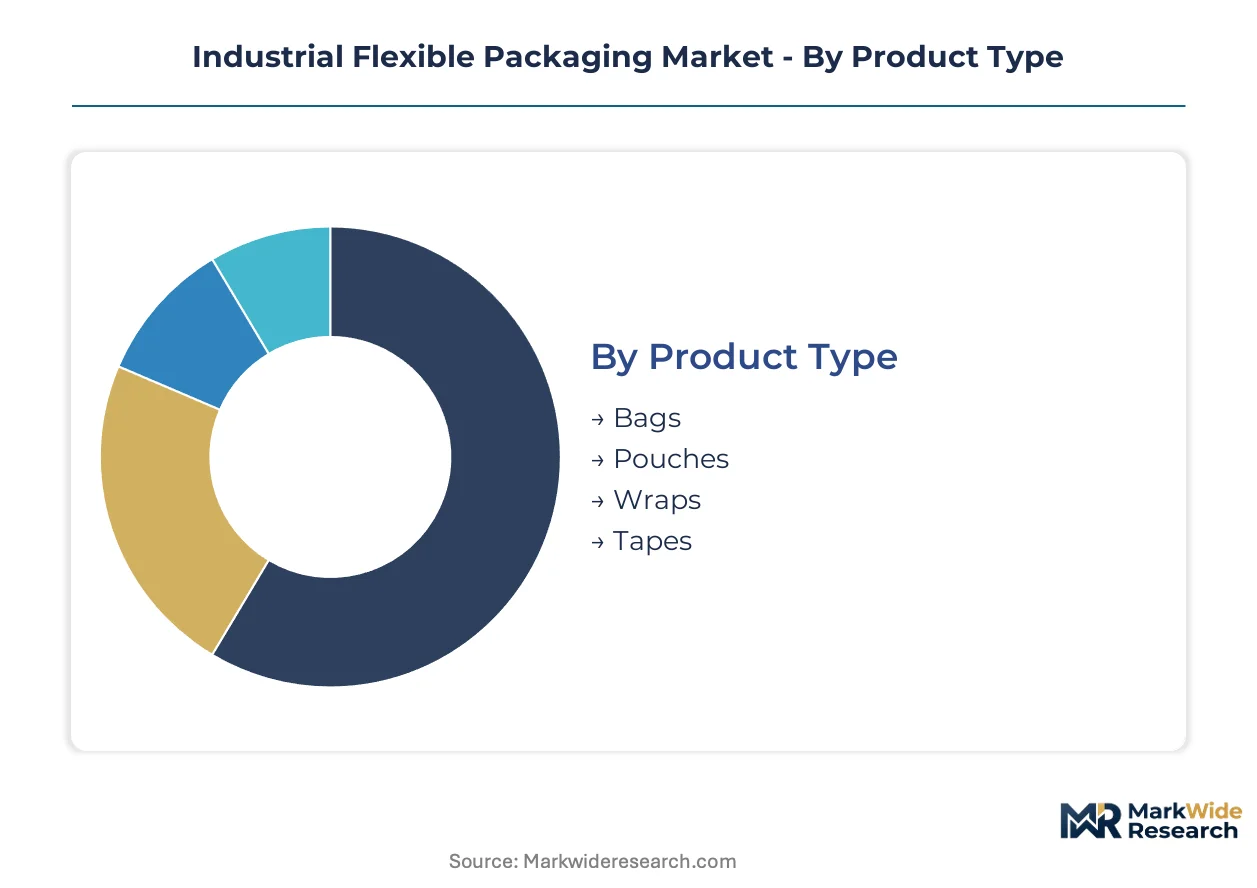
Industrial flexible packaging serves divergent protection requirements across bulk commodities, perishable goods, and sensitive chemical products. Segmentation reveals how material science, barrier specifications, and supply chain integration shape competitive positioning among converters and end-users.
Product Type:
Converters align product configurations with filling equipment compatibility, shelf-life extension targets, and handling automation requirements across manufacturing corridors.
- Bags:Open-mouth and valve-sealed configurations in woven polypropylene or multiwall paper constructions protect cement, fertilizers, and agricultural commodities. German industrial packaging clusters supply Central European manufacturing demand with moisture-resistant laminates that withstand palletized stacking stresses.
- Pouches:Stand-up and flat formats with zipper or spout closures combine polyethylene terephthalate, aluminum foil, and oriented polyamide layers for oxygen and moisture barrier performance. Food manufacturers deploy high-barrier pouches for extended shelf-life dairy and ready-meal applications where EPR fee structures accelerate mono-material adoption.
- Wraps:Stretch and shrink films in linear low-density polyethylene formulations secure palletized loads during transit and warehousing operations.
- Tapes:Pressure-sensitive adhesive films in biaxially oriented polypropylene or PVC substrates seal corrugated cases and bundle lightweight industrial products.
Established volume favors bags; emerging adoption favors pouches.
Material:
Raw material selection balances barrier performance, regulatory compliance burden, and recyclability certification requirements under evolving EEA frameworks.
- Plastic:Polyethylene, polypropylene, and polyethylene terephthalate substrates dominate tonnage through coextruded and laminated constructions. REACH substance restrictions and ECHA scrutiny of perfluorinated compounds force rapid reformulation of high-barrier coatings across pharmaceutical supply chains.
- Composites:Multi-layer structures combining plastic, aluminum, and paper substrates deliver tailored barrier properties for aggressive chemical and oxygen-sensitive applications. Composite materials are gaining share fastest as converters balance performance specifications against sorting-compatible recyclability mandates.
- Paper:Kraft and extensible sack papers with polyethylene extrusion coatings provide breathable yet moisture-resistant containment for cement and agricultural products.
- Aluminum:Foil laminates in 6-12 micron gauges deliver near-zero oxygen and moisture transmission for pharmaceutical blister packs and sensitive chemical pouches.
Plastic substrates anchor current volume; composite structures command reformulation investment.
Application:
End-use sectors impose distinct migration limits, sterilization compatibility, and labeling requirements that filter converter qualification and material certification.
- Food:Primary and secondary packaging for dairy, meat, bakery, and ready-meal products demands FDA and EFSA food contact compliance with specialized analytical testing. Private-label manufacturers in Spain and Portugal adopt leased converting capacity with digital printing integration for short-run customization.
- Pharmaceutical:Primary blister packs, sachets, and strip packaging for solid dose and sterile products require EMA chemical safety standards and barrier integrity against moisture and oxygen ingress.
- Beverage:Bag-in-box and pouch formats for wine, juice, and dairy alternatives utilize metallized films and spout fitments for dispensing convenience.
- Consumer Goods:Detergent pods, personal care sachets, and household chemical pouches combine child-resistant features with chemical compatibility testing.
Food applications drive laminate volume; pharmaceutical specifications command premium positioning.
End User:
Procurement sophistication and volume scale differentiate customer segments from commodity spot buyers to integrated supply chain partners.
- Manufacturers:Food processors, chemical producers, and agricultural compounders specify barrier performance, line speed compatibility, and lot traceability for inbound packaging materials. Equipment-as-a-service models displace capital purchase for mid-sized manufacturers seeking operational flexibility.
- Distributors:Third-party logistics operators and packaging wholesalers aggregate demand across multiple manufacturing accounts with inventory holding and just-in-time delivery services.
- Retailers:Private-label program managers at grocery and mass-merchandise chains specify sustainable packaging credentials and shelf-ready display formats.
- Exporters:Cross-border commodity traders require ISPM-15 compliant wood-free alternatives and moisture protection for ocean container transit.
Manufacturer direct procurement dominates contract value; distributor intermediation sustains spot market liquidity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redirecting flexible packaging capacity toward manufacturing corridors with surplus resin supply and converting infrastructure. Net importers in Eastern Europe and Southeast Asia are attracting greenfield investments from Western converters seeking tariff-advantaged production bases.
Germany
REACH compliance deadlines are accelerating converter consolidation around Düsseldorf and Hamburg industrial zones. The EU Packaging Waste Directive mandates sorting-compatible multilayer films by 2030, forcing reformulation of legacy adhesive systems. Bavarian film extruders are expanding ethylene vinyl alcohol copolymer capacity to serve dairy and ready-meal processors preempting extended producer responsibility fee structures.
United States
FDA food contact migration testing backlogs are delaying new product launches for mid-sized converters serving private-label manufacturers. The EPA's evolving per- and polyfluoroalkyl substances scrutiny is pressuring pharmaceutical barrier film suppliers toward fluorine-free alternatives. Chicago-area converting clusters are integrating digital printing with form-fill-seal lines to collapse minimum order quantities for regional food processors.
China
Dual carbon goals are restricting coal-based polyethylene capacity expansions in Shandong and Jiangsu provinces. SAMR food safety standards are tightening additive migration limits for dairy and beverage pouch applications. Yangtze River Delta converters are backward-integrating into biobased polybutylene adipate terephthalate to meet brand owner sustainability specifications for export markets.
India
FSSAI packaging material notifications are mandating heavy metal migration testing for food contact laminates ahead of enforcement dates. BIS certification requirements for woven polypropylene bags are filtering informal sector suppliers from fertilizer and seed treatment procurement channels. Gujarat-based extruders are expanding metallized film capacity to serve domestic snack food manufacturers reducing import dependence.
Brazil
ANVISA pharmaceutical packaging regulations are requiring barrier integrity documentation for tropical climate stability testing. Agricultural commodity export growth is driving demand for moisture-resistant woven laminates at Santos port logistics corridors. São Paulo state converters are leasing equipment-as-a-service models to mid-sized food manufacturers seeking operational flexibility amid currency volatility.
Industrial Flexible Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive resin or film supply. The vendor base stratifies between multinational converters with integrated pulp-to-film operations and regional specialists focused on single-material formats. Three archetypes dominate: integrated materials-science conglomerates, equipment-integrated contract packers, and mono-material technology licensors. Capacity expansion and strategic partnerships represent the dominant competitive vectors as converters secure feedstock access and brand owner qualification pipelines.
Within the integrated tier, Amcor plc and Mondi occupy positions spanning multiple geographies and substrate categories. Sealed Air exemplifies the equipment-integrated archetype through proprietary barrier technologies and form-fill-seal machinery bundling. These three entities represent contrasting strategic postures: global film network leverage, pulp-to-paper vertical control, and differentiated protection-cycle extension for manufacturing clients.
| Leading Market Players |
|---|
| Amcor plc |
| Smurfit Westrock |
| Mondi |
| Sealed Air |
| Huhtamaki |
| Transcontinental Inc. |
| Sonoco Products Company |
| Constantia Flexibles |
| Berry Global |
| Others |
Supply & Pricing Matrix
Petrochemical feedstock volatility determines both pricing tier spreads and supply chain shape across industrial flexible packaging, as resin cost fluctuations compress converter margins while forcing contract structures that shift inventory risk downstream to food and pharmaceutical manufacturers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-commitment pricing that separates certified food-contact grades from standard industrial specifications. Price differentiation rests on REACH compliance certification and ethylene vinyl alcohol copolymer barrier performance tiers. Cost compression in mid-tier laminates is intensifying because mono-material recyclable formats sacrifice margin for EPR fee avoidance. Small-scale private-label manufacturers exhibit highest price sensitivity, while multinational pharmaceutical buyers absorb premium for fluorine-free barrier guarantees.
Supply Chain Analysis
Tariff exposure between Germany and Eastern European manufacturing corridors dominates supply chain risk calculations for Central European converter networks. Raw material sourcing draws from Saudi Arabian polyethylene resin, German ethylene vinyl alcohol copolymer production, and Belgian adhesive specialists. Distribution runs through Düsseldorf and Hamburg industrial clusters with cross-border fulfillment to Polish and Czech manufacturing plants. Single-source vulnerability concentrates in aluminum foil laminates where European smelter capacity limits create import dependence on energy-cost-sensitive producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified migration testing capacity sits at a structural deficit, with FDA and EFSA compliance queues extending qualification timelines for new barrier formulations and creating bottlenecks that filter market participation.
For Market Incumbents: Build regulatory certification moats by accelerating in-house analytical laboratory capacity to collapse FDA food contact testing queues. Secure backward integration into ethylene vinyl alcohol copolymer supply through dedicated offtake agreements with Bavarian film extruders. Amcor plc and Mondi demonstrate how captive resin networks defend margin position against petrochemical volatility. For New Entrants and Emerging Players: Establish a beachhead in agricultural bulk packaging for Eastern European fertilizer and seed treatment applications where moisture-resistant woven laminates remain underpenetrated by high-performance barrier formats. Lease equipment-as-a-service models from Spanish and Portuguese contract packers to bypass capital-intensive form-fill-seal machinery investments. Digital printing integration enables short-run customization for private-label food manufacturers with collapsed minimum order quantities. For Investors and Strategic Acquirers: ECHA restriction proposals for PFAS coatings reshape the acquisition landscape by devaluing pharmaceutical barrier film assets dependent on perfluorinated compound formulations. Target converters with certified fluorine-free coating pipelines and mass-balance accounting systems for extended producer responsibility frameworks. Watch EEA sorting-compatible multilayer film adoption rates as the inflection signal separating qualified circular material flows from stranded legacy assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Resin | Bavarian extruders secure captive barrier film supply for dairy processors preempting EPR fees. |
| Fluorine-Free Coating Qualification | Pharmaceutical converters accelerate EMA-compliant barrier alternatives ahead of PFAS phase-out deadlines. |
| Equipment-as-a-Service Expansion | Leased form-fill-seal capacity reduces capital barriers for mid-sized Spanish and Portuguese food manufacturers. |
| Digital Printing Convergence | Inline flexographic and inkjet systems collapse minimum order constraints for private-label SKU proliferation. |
| Migration Testing Laboratory Buildout | In-house FDA and EFSA compliance capacity accelerates new product launch timelines against analytical queue bottlenecks. |
Research Methodology
Operator-level perspectives from converter plant managers, food manufacturer procurement leads, pharmaceutical packaging engineers, and chemical company supply chain directors anchored the qualitative base. Primary fieldwork combined with secondary validation from ECHA substance restriction databases, FDA food contact notifications, EU Packaging Waste Directive implementation reports, and customs trade data for polyethylene and polypropylene resin flows. Bottom-up volume modeling triangulated against top-down spending analysis across the analysis window.
Scenario-bracketing framed projections across regulatory compliance intensity, petrochemical feedstock volatility bands, and mono-material adoption pace assumptions. Segmentation dimensions modeled include product type, material substrate, application sector, and end-user procurement sophistication tier. CAGRs derived from weighted average of historical trajectory and structural shift elasticity, with specific inputs from REACH authorization timelines and EPR fee structure implementation schedules.
Stress conditions across resin price volatility, ECHA PFAS restriction acceleration, and Eastern European manufacturing demand growth were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance deadlines and substitution technology readiness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
Egypt Flexible Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Japan Flexible Plastic Packaging Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Canada Flexible Packaging Market