
 Canada Flexible Plastic Packaging Market | 2026-2036
Canada Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Flexible Plastic Packaging Market Insights
Polyethylene is shifting toward recycled-content and bio-based alternatives across Canadian converter lines as resin economics and brand sustainability commitments reshape procurement calculus. Winpak Ltd leverages its integrated film extrusion and converting footprint to control resin pass-through costs across dairy and protein packaging. Transcontinental Inc anchors national distribution through its Quebec-based gravure and flexographic printing network serving private-label retail chains. Cascades Flexible Packaging differentiates via post-consumer recycled content integration aligned with extended producer responsibility timelines in Ontario and British Columbia.
Canada flexible plastic packaging encompasses polymer-based films, pouches, wraps, and bags engineered with controlled barrier properties against oxygen, moisture, and light, typically manufactured through blown or cast film extrusion followed by lamination, printing, and conversion. The primary commercial purpose centers on protecting perishable and non-perishable goods through distribution while minimizing material weight versus rigid alternatives. Stand-up pouches now command premium positioning in shelf-stable food segments where resealability and vertical display drive retail placement economics. Food Packaging dominates application-level demand as meat, snack, and frozen categories convert from rigid trays and cans to flexible formats. Polyethylene retains material-level volume leadership though polypropylene gains in high-clarity and retort applications requiring thermal resistance.
Health Canada sets food-contact material safety standards under the Food and Drugs Act, while the Canadian Environmental Protection Act governs chemical substance management including polymer additives subject to toxicity screening. Provincial extended producer responsibility programs in British Columbia, Ontario, and Quebec mandate recycled content thresholds and packaging recyclability labeling that directly shape converter product development roadmaps. The Competition Bureau monitors environmental claims to prevent greenwashing in packaging marketing. Stakeholders must track pending federal plastics registry requirements and harmonization pressures between provincial EPR schemes to anticipate compliance cost allocation across the value chain.
Market Dynamics
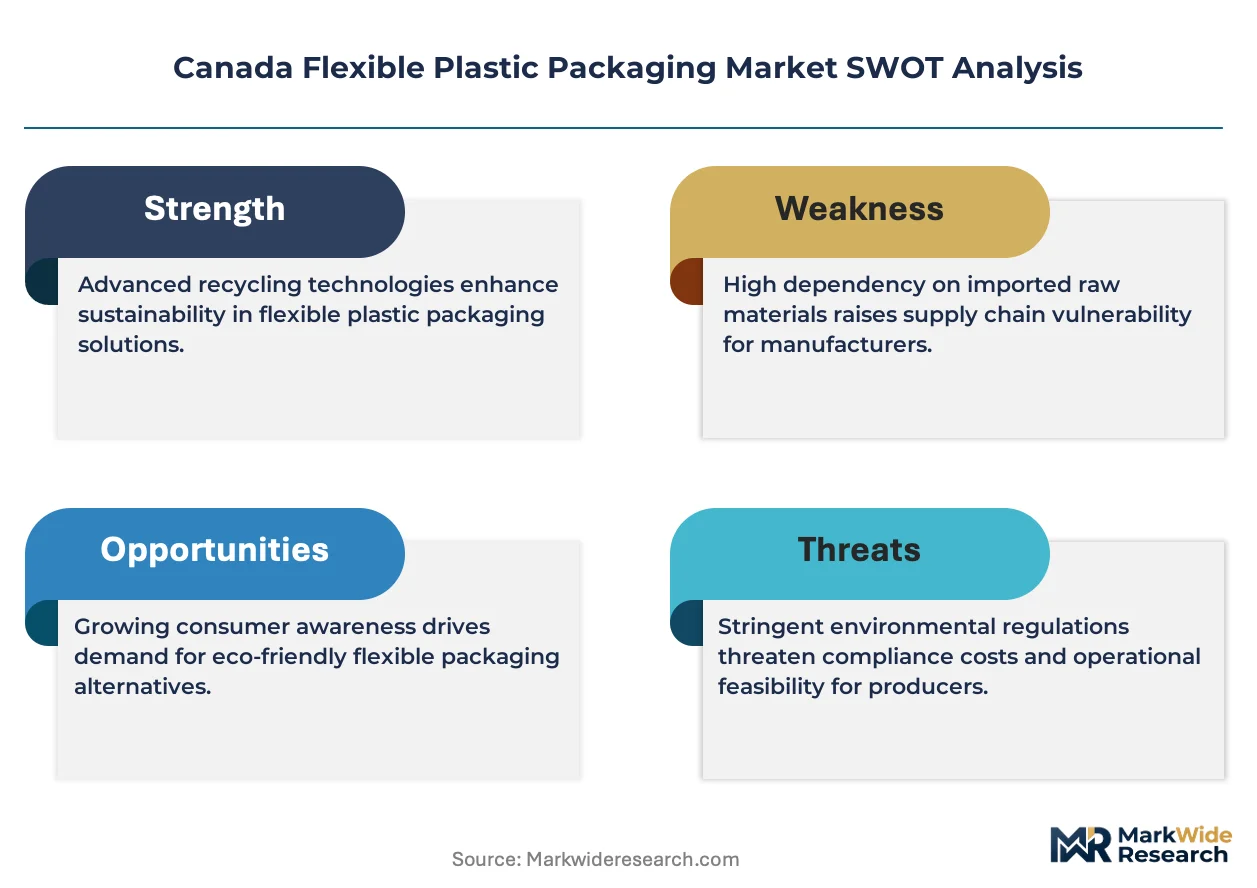
Extended producer responsibility mandates across British Columbia, Ontario, and Quebec are forcing converters to redesign film structures for recyclability, compressing development timelines and reshaping resin procurement priorities.
Growth Catalysts
- Retort pouch adoption:Protein processors in Alberta and Manitoba are converting canned goods to high-barrier flexible formats for shelf-stable meal solutions. Thermal resistance requirements drive polypropylene lamination demand.
- Health Canada migration thresholds:Tighter chemical safety standards for food-contact materials accelerate investment in compliant adhesive and barrier coating technologies across converter operations.
- Ontario Golden Horseshoe cluster density:Converter proximity to Toronto-area CPG headquarters enables just-in-time fulfillment and reduces logistics costs for private-label retail programs.
Market Restraints
- Post-consumer resin supply scarcity:Limited domestic rPE and rPP collection infrastructure constrains recycled content targets under provincial EPR schemes.
- Petrochemical feedstock volatility:Ethylene and propylene price swings from Alberta oil sands and US Gulf Coast supply disruptions compress converter margins.
- Mechanical recycling incompatibility:Multi-layer barrier films containing EVOH or metallized layers resist standard reprocessing, creating end-of-life liability.
Strategic Opportunities
- Chemical recycling infrastructure:Pyrolysis and depolymerization investments in Sarnia and Montreal could unlock circular feedstock for flexible packaging films.
- Pharmaceutical unit-dose formats:Blister foil and strip pouch demand from Health Canada-regulated drug packaging represents underpenetrated volume for barrier film specialists.
- Quebec organic waste diversion:Compostable film mandates for food service packaging create certified biodegradable polymer demand that conventional converters can capture.
Industry Challenges
- Film metallization technician shortage:Vacuum deposition and holographic finishing expertise concentrates among retiring specialists in Montreal and Vancouver.
- Legacy gravure cylinder inventory:Transcontinental and smaller Quebec converters face stranded asset risk as brands demand shorter-run digital printing for SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Flexible Plastic Packaging Market |
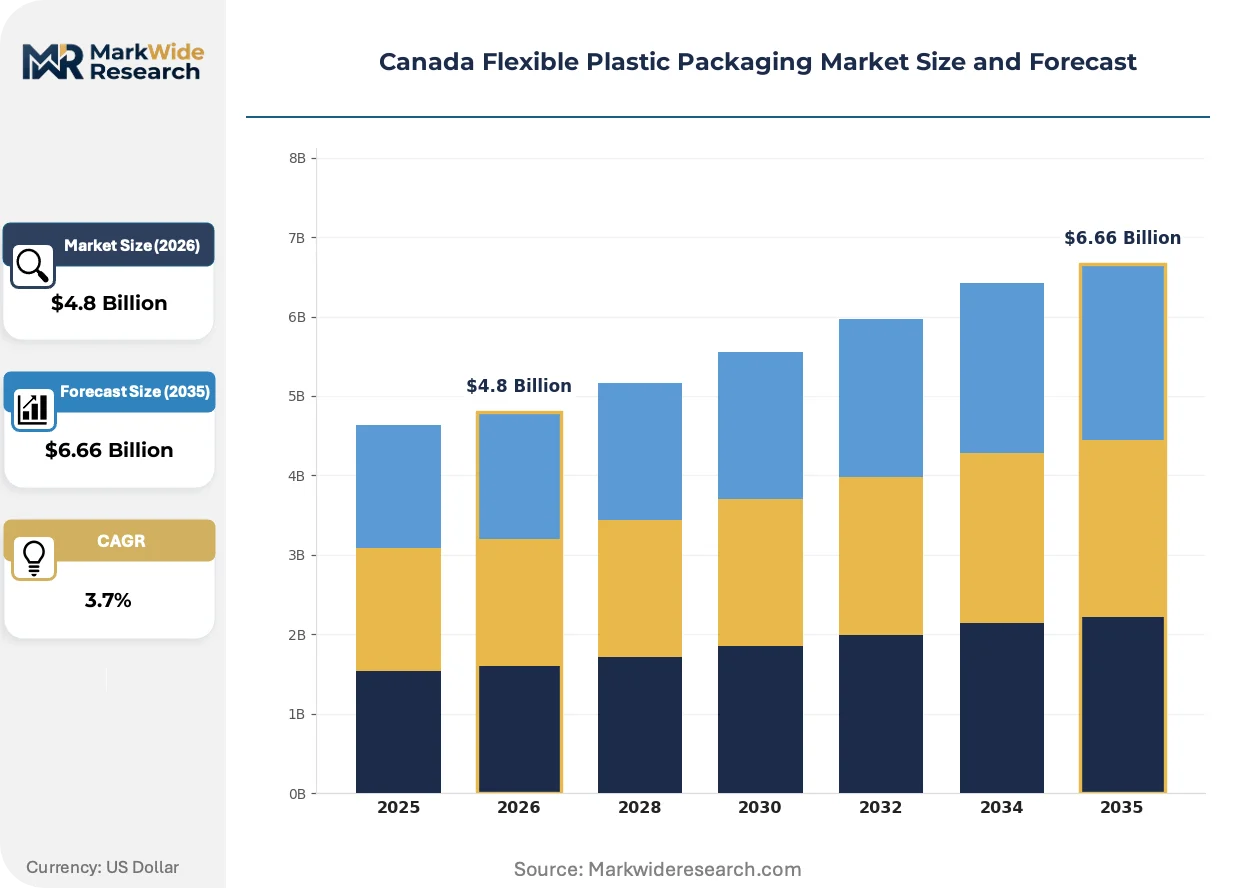
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Bags, Wraps, Films Application: Food Packaging, Personal Care, Electronics, Medical Supplies Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Others End User: Food Industry, Healthcare, Retail, Consumer Goods |
| Companies Covered | Winpak Ltd, Transcontinental Inc, Cascades Flexible Packaging, Flair Flexible Packaging Corporation, C-P Flexible Packaging Inc, Emmerson Packaging Holdings Inc, Sigma Plastics Group, Amcor PLC, ProAmpac LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Flexible Plastic Packaging Market Trends and Innovations
Material science advances and regulatory compliance pressures are converging to transform how Canadian converters engineer barrier properties and manage end-of-life obligations for flexible packaging.
Mono-material polyethylene structures are unifying previously multi-layer barrier designs through advanced coextrusion and surface coating technologies. Dairy and fresh produce packagers in Ontario and British Columbia are piloting these formats to meet provincial recyclability labeling requirements. The shift is compressing demand for conventional adhesive lamination while expanding slot-die coating equipment orders.
Health Canada's pending federal plastics registry will mandate detailed reporting on packaging composition and fate, extending beyond current provincial EPR programs. Converters must reconfigure data collection systems and supplier certification workflows to comply. Small and mid-size Ontario operators face disproportionate compliance cost burdens relative to integrated national players.
CPG brand sustainability scorecards are altering procurement evaluation criteria for flexible packaging suppliers. Major Canadian retailers now require recycled content verification and carbon footprint disclosures alongside unit cost metrics. This behavioral shift concentrates contract awards with converters demonstrating third-party chain-of-custody certification, particularly in Toronto and Vancouver metropolitan sourcing regions.
Canada Flexible Plastic Packaging Market Segmentation
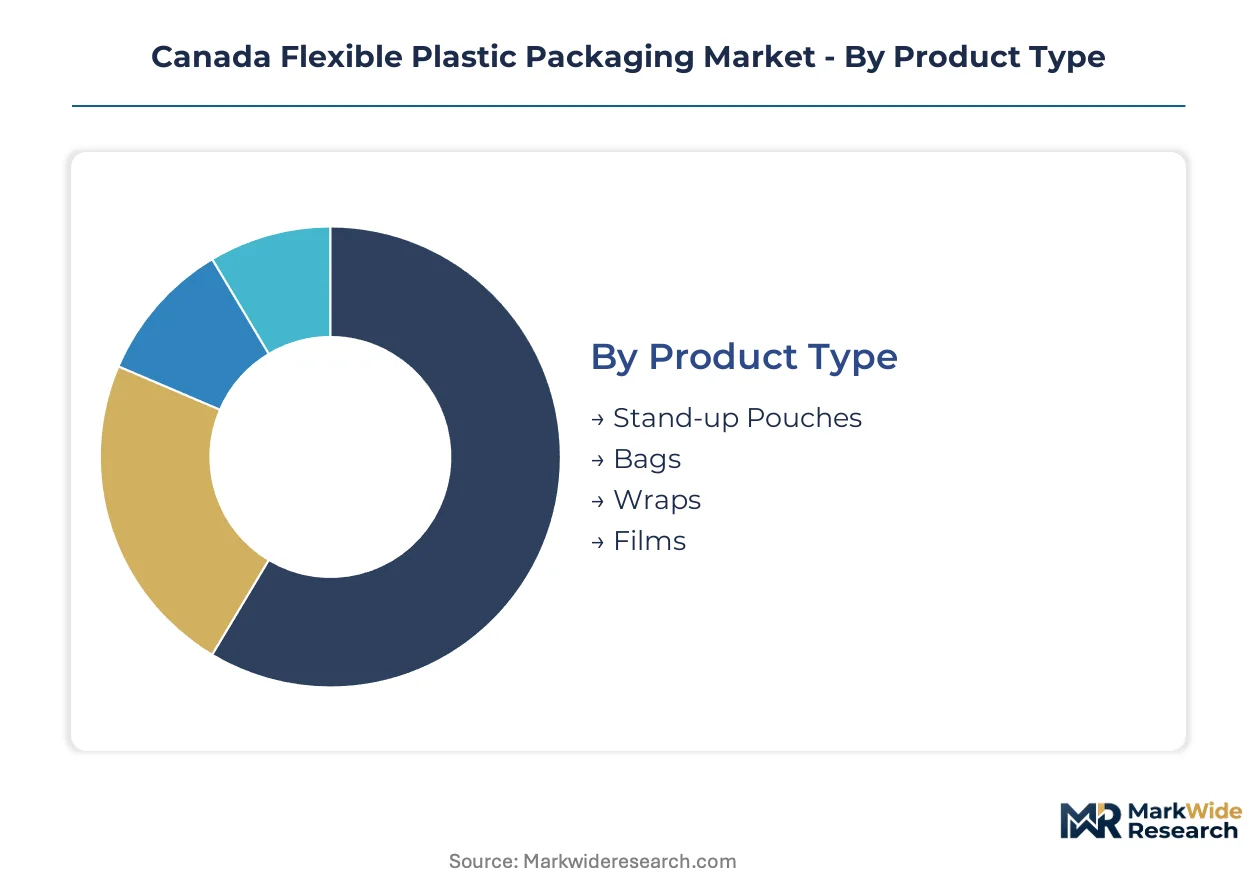
Flexible packaging converters in Canada configure production lines around specific product geometries and barrier requirements. Segmentation choices directly determine capital equipment allocation, resin procurement contracts, and compliance pathways under provincial extended producer responsibility programs.
Product Type:
Capital intensity peaks with stand-up pouch lines requiring precision forming and resealable zipper integration, while film extrusion demands continuous high-volume resin throughput.
- Stand-up Pouches:These structures combine bottom gusset forming with multi-layer lamination for vertical shelf display. Dairy processors in Ontario's Golden Horseshoe specify high-barrier metallized versions for extended shelf-life yogurt formats.
- Bags:Conventional side-seal and wicketed configurations dominate high-volume produce and bakery applications. British Columbia's fresh vegetable shippers favor perforated polyethylene bags for modified atmosphere packaging of salad greens.
- Wraps:Stretch and shrink films protect palletized goods through distribution. Alberta protein exporters rely on polyolefin shrink bundles for frozen meat consolidation.
- Films:Rollstock formats supply form-fill-seal operations across snack and frozen food plants. Converter margins compress on commodity blown film sold into private-label retail programs.
Most installed capacity flows through Films. Expansion is steepest in Stand-up Pouches.
Application:
Application segmentation reveals divergent margin profiles, with pharmaceutical-adjacent formats commanding certification premiums versus commodity food service volumes.
- Food Packaging:Meat, snack, and frozen categories drive format conversion from rigid to flexible. Quebec's protein processors specify retort pouches for shelf-stable meal solutions requiring Health Canada-compliant migration testing.
- Personal Care:Unit-dose sachets and flow-wrap formats package cosmetics and hygiene products. Toronto-area contract manufacturers source high-clarity polypropylene for premium shampoo samples.
- Electronics:Anti-static films and moisture barrier bags protect semiconductors during shipping. Vancouver's technology distribution corridor generates demand for metallized polyester laminates.
- Medical Supplies:Sterile barrier systems for devices and pharmaceuticals require validated sealing processes. Health Canada oversight of medical device packaging elevates quality system requirements beyond food-contact standards.
Food Packaging absorbs the majority of polyethylene and polypropylene resin volume. Medical Supplies is climbing the fastest on a percentage basis.
Material:
Material selection governs equipment compatibility, with polyolefin extrusion lines representing distinct capital commitments versus PVC calendering or solvent-based coating systems.
- Polyethylene:LDPE, LLDPE, and HDPE grades provide sealability and toughness across frozen food and produce applications. Ontario converters are retrofitting lines for recycled-content rPE to meet provincial EPR thresholds.
- Polypropylene:Cast and oriented films deliver clarity and thermal resistance for retort and microwaveable formats. Alberta's ready-meal processors specify biaxially oriented PP for high-temperature stability.
- Polyvinyl Chloride:Shrink film and blister pack applications persist in medical and consumer goods despite recyclability challenges. Quebec's pharmaceutical packaging sector maintains PVC demand for unit-dose formats.
- Others:Polyester, polyamide, and bio-based polymers address niche barrier and sustainability requirements. British Columbia's organic waste diversion mandates are piloting certified compostable films for food service.
Polyethylene commands the largest share of resin tonnage. Polypropylene is gaining share fastest in high-performance thermal applications.
End User:
End user segmentation shapes converter sales organization structure, with food industry accounts demanding technical service proximity versus healthcare's regulatory documentation intensity.
- Food Industry:Meat packers, snack manufacturers, and frozen food processors constitute the core demand base. Toronto and Montreal CPG headquarters concentrate procurement decision-making for national retail programs.
- Healthcare:Hospitals, pharmacies, and medical device manufacturers require validated sterile packaging. Health Canada's medical device regulations impose documentation burdens that filter out smaller converters.
- Retail:Private-label chains and e-commerce fulfillment centers specify custom-printed formats for brand differentiation. Vancouver's grocery cooperatives are driving recycled-content labeling requirements.
- Consumer Goods:Household products and electronics brands source protective and display-oriented formats. Ontario's automotive parts distributors use VCI films for corrosion protection during storage.
The Food Industry channels the majority of flexible packaging volume through converter plants. Healthcare is expanding most quickly as unit-dose pharmaceutical formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Golden Horseshoe manufacturing corridor anchors Canadian flexible packaging demand through converter density and logistics infrastructure serving Toronto-area CPG headquarters.
Ontario
Dairy processors and meat packers in the Golden Horseshoe drive high-barrier pouch demand for extended shelf-life formats. Health Canada's food-contact material regulations under the Food and Drugs Act mandate migration testing compliance. Converter clusters in Mississauga and Brampton supply just-in-time delivery to private-label retail programs.
Quebec
Protein processors specify retort pouches for shelf-stable meal solutions requiring thermal resistance. Provincial extended producer responsibility programs mandate recycled content thresholds and recyclability labeling. Montreal's gravure and flexographic printing network anchors national distribution for retail chains.
British Columbia
Fresh produce shippers favor perforated polyethylene bags for modified atmosphere packaging of salad greens. The province's organic waste diversion mandates pilot certified compostable films for food service packaging. Vancouver's technology distribution corridor generates demand for metallized polyester laminates in electronics protection.
Alberta
Ready-meal processors specify biaxially oriented polypropylene for high-temperature stability in microwaveable formats. Petrochemical feedstock from oil sands operations influences regional resin economics. Calgary and Edmonton protein exporters rely on polyolefin shrink bundles for frozen meat consolidation.
Manitoba
Protein processors convert canned goods to high-barrier flexible formats for shelf-stable meal solutions. Provincial regulations align with federal plastics registry requirements pending implementation. Winnipeg serves as a logistics hub connecting Prairie agricultural output to Ontario and Quebec converter networks.
Canada Flexible Plastic Packaging Market Competitive Landscape
Global majors compete with regional champions across resin procurement and converter capacity. The vendor base spans integrated film extrusion operators, specialized printing networks, and recycled-content specialists. Three archetypes dominate: vertically integrated resin-to-package converters, print-centric flexible packaging specialists, and sustainability-focused post-consumer recycled content integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms respond to extended producer responsibility mandates.
Among Canadian-based converters, Winpak Ltd, Transcontinental Inc, and Cascades Flexible Packaging exemplify distinct strategic positions. Winpak Ltd occupies the integrated manufacturing tier with captive film extrusion capabilities. Transcontinental Inc anchors the print-centric specialist archetype through gravure and flexographic infrastructure. Cascades Flexible Packaging represents the sustainability-focused tier with post-consumer recycled content integration aligned to provincial extended producer responsibility timelines.
| Leading Market Players |
|---|
| Winpak Ltd |
| Transcontinental Inc |
| Cascades Flexible Packaging |
| Flair Flexible Packaging Corporation |
| C-P Flexible Packaging Inc |
| Emmerson Packaging Holdings Inc |
| Sigma Plastics Group |
| Amcor PLC |
| ProAmpac LLC |
| Others |
Pricing and Supply Chain Analysis
Toronto-area CPG headquarters concentration enables just-in-time procurement models that compress converter pricing power and enforce contract-based long-term offtake structures across Ontario's Golden Horseshoe corridor. Health Canada's tightening migration thresholds and provincial EPR mandates add compliance cost layers that converters must absorb or pass through.
Pricing Analysis
Ethylene and propylene cost pass-through from Alberta oil sands and US Gulf Coast supply disruptions anchors converter pricing models, with resin volatility absorbed through quarterly contract adjustments. Three-tier pricing structure across premium barrier films, standard commodity laminates, and economy-grade polyethylene separates certified recyclable formats from conventional multi-layer structures. Pricing pressure stems from post-consumer resin supply scarcity as provincial EPR schemes outpace domestic rPE and rPP collection infrastructure. Private-label retail chains exhibit highest price sensitivity, while pharmaceutical unit-dose formats tolerate premium positioning for Health Canada-compliant barrier certification.
Supply Chain Analysis
Single-source vulnerability sits with US Gulf Coast petrochemical feedstock and Alberta oil sands resin production that Canadian converters draw from under NAFTA-integrated supply terms. Raw material dependencies center on ethylene, propylene, and specialty adhesive polymers subject to tariff exposure from cross-border trade policy shifts. Distribution runs through Ontario's Golden Horseshoe logistics hubs serving Quebec and British Columbia converter networks via rail and highway corridors. Chemical recycling infrastructure gaps in Sarnia and Montreal create circular feedstock bottlenecks that compound end-of-life liability risks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ontario's stricter EPR timelines versus Quebec's retort pouch demand growth create geographic-arbitrage opportunities for converters optimizing recycled-content integration and thermal barrier capacity placement.
For Market Incumbents: Cement converter positioning through captive film extrusion investments in Mississauga and Brampton clusters that control resin pass-through costs against petrochemical volatility. Winpak Ltd's integrated manufacturing model demonstrates how backward integration into blown film production defends margin compression from multi-layer barrier film obsolescence. Prioritize Health Canada migration testing certification to lock out smaller Ontario operators facing disproportionate compliance burdens. For New Entrants and Emerging Players: Chemical recycling technology licensing offers entry into circular feedstock supply gaps left by incumbent mechanical recycling limitations. Quebec's pharmaceutical packaging sector presents the most penetrable white-space target, with unit-dose blister foil demand outpacing validated sterile barrier converter capacity. Pursue hospital system partnerships requiring Health Canada medical device packaging documentation that filters out commodity competitors. For Investors and Strategic Acquirers: Integrated CPG brands are the most active acquirer in this space, seeking captive flexible packaging supply to secure EPR compliance and carbon footprint disclosure capabilities. Target mid-size Ontario converters with post-consumer recycled content integration and Golden Horseshoe logistics assets for five-to-ten year holding windows. Monitor federal plastics registry implementation progress as the signal indicating compliance cost allocation shifts across the value chain.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Infrastructure Investment | Pyrolysis capacity in Sarnia unlocks circular feedstock for EPR-compliant film structures. |
| Backward Integration into Film Extrusion | Captive resin processing insulates converter margins from Alberta oil sands price volatility. |
| Health Canada Migration Testing Certification | Validated barrier coatings secure pharmaceutical unit-dose contracts with documentation moats. |
| Post-Consumer Recycled Content Integration | rPE and rPP sourcing aligns converter roadmaps with British Columbia and Ontario EPR thresholds. |
| Digital Printing Platform Conversion | Short-run SKU flexibility replaces stranded gravure cylinder inventory at Transcontinental-scale operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with converter operations managers, CPG procurement directors, resin distribution specialists, and Health Canada regulatory affairs leads with secondary validation against Canadian plastics trade association filings, provincial EPR program reports, and SEC disclosures from listed packaging firms. Bottom-up resin throughput estimates and top-down CPG packaging spend analysis provided cross-check triangulation.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across product type, application, material grade, and end-user vertical. CAGRs derived from fitted growth curves incorporating retort pouch adoption rates, recycled-content mandate phase-ins, and chemical recycling capacity buildout assumptions. Forecast inputs included Alberta petrochemical feedstock cost indices and Health Canada regulatory implementation timelines.
The model holds under stable provincial EPR harmonization and resin trade flow continuity; deviation in federal plastics registry enforcement intensity or US-Canada tariff policy would shift converter compliance cost allocation and circular feedstock economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market
Flexible Packaging
Stretch Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
India Flexible Plastic Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Canada Flexible Packaging Market