
 Mexico Flexible Plastic Packaging Market | 2026-2036
Mexico Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Flexible Plastic Packaging Market Insights
Wholesale distribution through Mexico's regional packaging distributors is tilting toward direct mill relationships in the Central Plateau. Amcor PLC leverages its Monterrey extrusion complex to sustain supply continuity for beverage clients across five states. Berry Global Inc. anchors its position through backward integration into resin compounding, while SigmaQ Packaging competes on short-run flexibility for mid-tier food processors in Guadalajara.
Flexible plastic packaging comprises pliable polymer structures—typically polyethylene or polypropylene films between 12 and 150 microns—manufactured through blown film extrusion, cast extrusion, or multilayer lamination to protect, preserve, and display consumer and industrial goods. Pouches command the widest margin pools as brand owners convert from rigid formats, while wraps retain volume leadership in fresh produce and bakery applications. Polyethylene dominates material tonnage due to cost-performance balance, though polypropylene is displacing it in retort and hot-fill segments where thermal resistance matters.
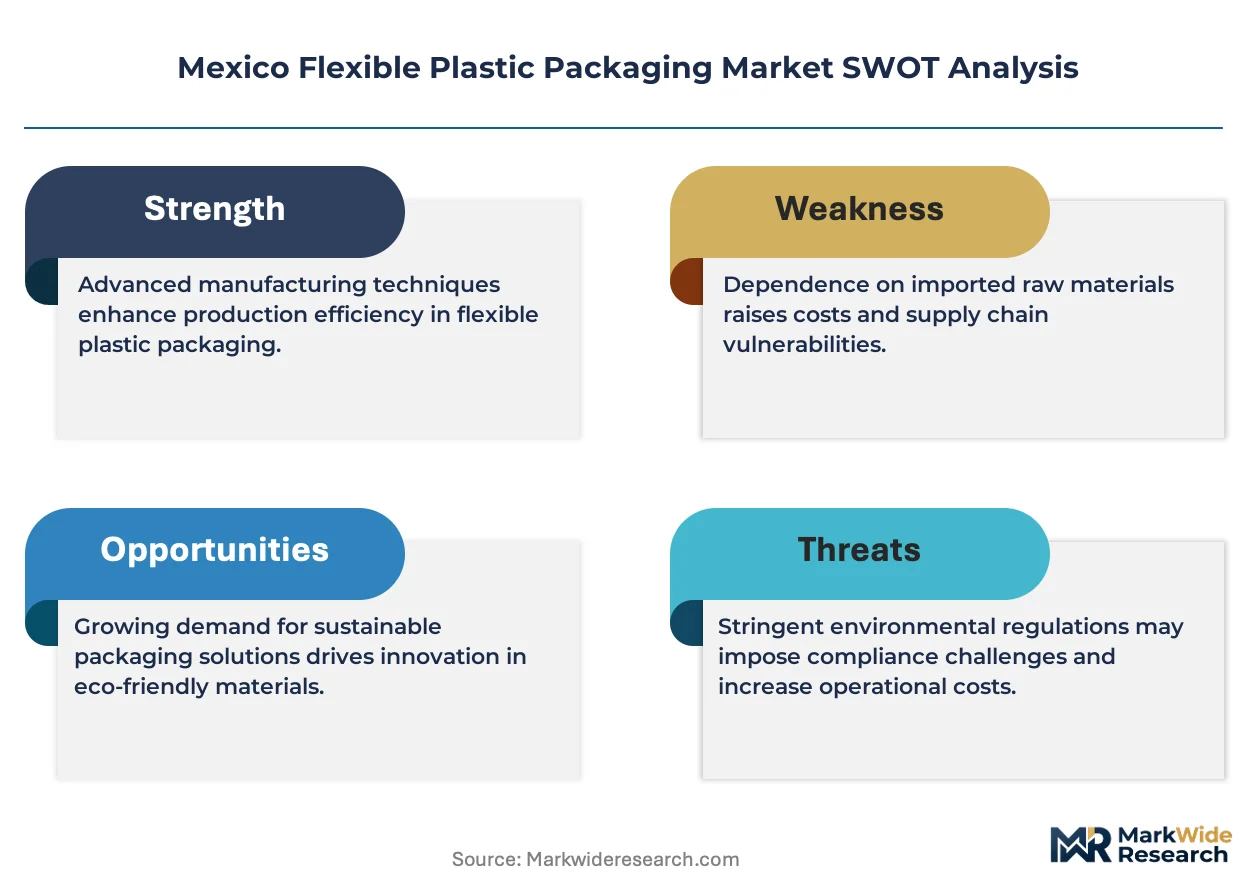
SEMARNAT's extended producer responsibility framework and NOM-252-SSA1-2011 hygiene standards jointly shape resin selection, recycling infrastructure investment, and import compliance for foreign suppliers. COFEPRIS oversight of pharmaceutical and food-contact materials adds a second compliance layer that favors certified converters with in-house testing laboratories. Stakeholders must monitor how pending state-level plastic bans in Veracruz and Oaxaca alter regional demand patterns and force format redesigns.
Market Dynamics
SEMARNAT's extended producer responsibility framework is compressing converter margins while forcing rapid format redesign toward recyclable polyethylene structures. The regulatory pressure coincides with resin price volatility and concentrated supply in the Bajío corridor, creating a squeeze that favors backward-integrated suppliers with captive compounding capabilities.
Growth Catalysts
- NOM-252-SSA1-2011 hygiene standards:Food-contact certification requirements are elevating demand for converters with in-house testing laboratories, filtering out smaller regional players and consolidating volume toward certified suppliers in Jalisco and Nuevo León.
- Automotive parts clustering:The Bajío industrial corridor's co-location of automotive suppliers with packaging converters is generating integrated supply contracts for protective films and barrier pouches serving just-in-time parts distribution.
- Blown film extrusion advances:Down-gauging to sub-25-micron polyethylene films is reducing resin consumption per unit while maintaining seal integrity, allowing processors to offset raw material cost pressure through yield improvements.
Market Restraints
- Ethylene feedstock volatility:Pemex petrochemical output fluctuations and import dependency for high-density polyethylene grades expose converters to margin compression during price spike cycles.
- Monterrey-Tampico supply corridor concentration:Overreliance on extrusion capacity within a 200-kilometer radius creates vulnerability to localized logistics disruptions and weather-related port closures.
- Mechanical recycling contamination limits:Multilayer laminated structures incorporating metallized or adhesive-bonded layers face technical barriers to closed-loop recovery under current Mexican sorting infrastructure.
Strategic Opportunities
- Veracruz and Oaxaca state bans:Pending subnational plastic restrictions are creating first-mover advantage for converters developing paper-film hybrid formats and certified compostable alternatives ahead of enforcement timelines.
- Retort pouch conversion:Processed seafood and ready-meal manufacturers are migrating from metal cans to polypropylene-based retort pouches, opening premium margin pools for heat-resistant barrier film specialists.
- Direct mill procurement models:Mid-tier food processors in Guadalajara are bypassing regional distributors to negotiate volume contracts directly with extrusion complexes, enabling price transparency and custom specification development.
Industry Challenges
- COFEPRIS pharmaceutical certification timelines:Extended approval cycles for food-contact and medical-grade materials are delaying new product launches and locking working capital in qualification inventories.
- Legacy extrusion asset retrofitting:Converting existing blown film lines to handle post-consumer recycled content requires screw and die modifications that strain capex budgets for mid-cap processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Flexible Plastic Packaging Market |
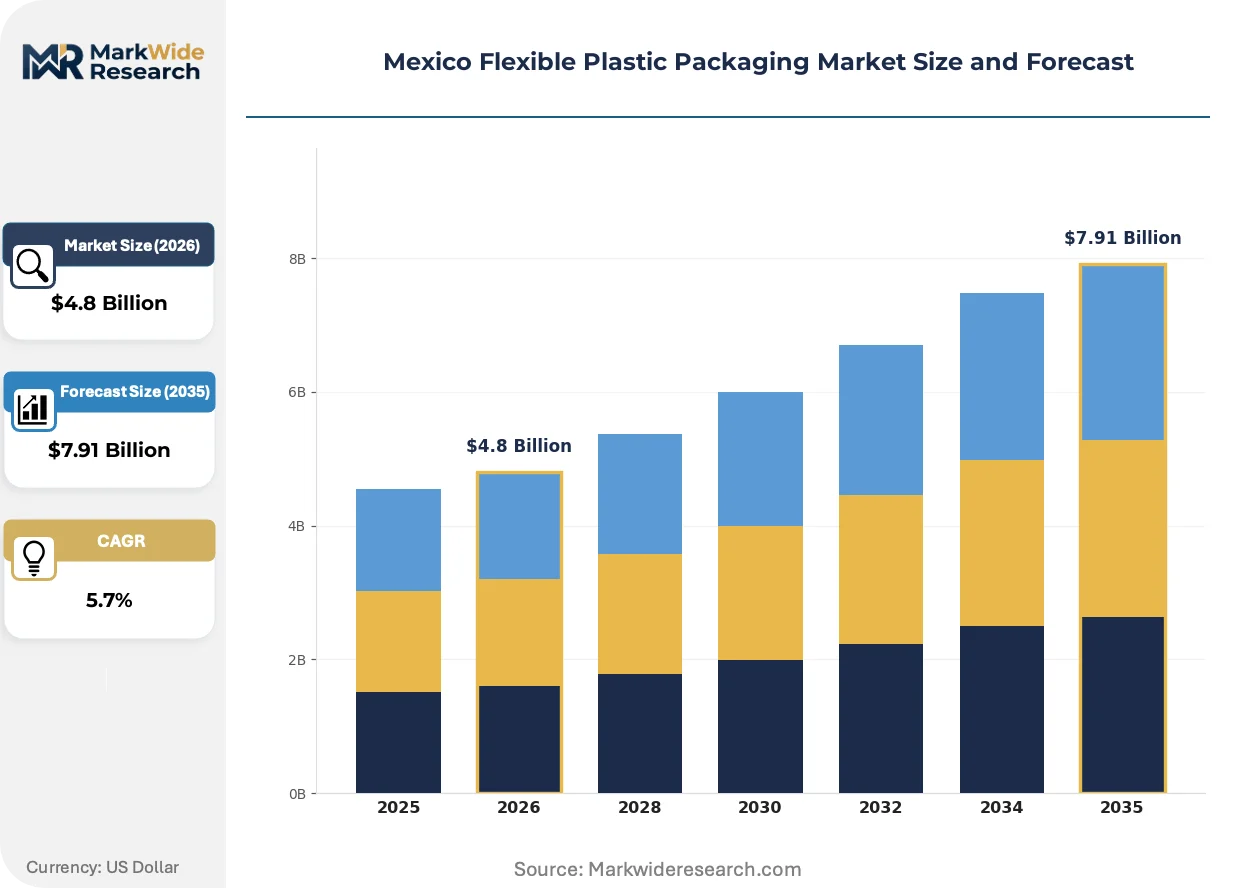
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Tapes, Pouches, Wraps End Use Industry: Food, Beverages, Pharmaceuticals, Personal Care Material: Polyethylene, Polypropylene, PVC, Nylon Technology: Extrusion, Printing, Coating, Lamination |
| Companies Covered | Amcor PLC, Huhtamaki Oyj, Berry Global Inc., Sonoco Products Company, Galas De Mexico, GURPA, Sealed Air Corporation, Innovia Films, SigmaQ Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Flexible Plastic Packaging Market Trends and Innovations
Material science convergence and regulatory compliance automation are redefining competitive capability in Mexican flexible packaging. Converters are racing to integrate circular design principles ahead of enforcement deadlines while preserving the cost-performance balance that polyethylene structures provide.
Multilayer coextrusion technology is hybridizing barrier and sealant functions within unified film structures, eliminating adhesive lamination steps and improving recyclability. Food manufacturers in the processed meat and dairy segments are specifying these unified structures for shelf-stable pouch formats. The technology is hybridizing converter capabilities, merging what were historically separate extrusion and lamination specializations into integrated production workflows that reduce lead times and defect rates.
SEMARNAT's 2024 extended producer responsibility amendments are mandating recycled content minimums and standardized labeling for flexible packaging sold in Mexican territory. Large-format retailers are now requiring supplier documentation traceable to certified recycling streams, with non-compliance risking delisting. The processed food and beverage segments are responding by consolidating supplier bases toward converters with established post-consumer resin supply agreements and third-party chain-of-custody certification.
Buyer concentration among multinational food manufacturers is compressing quoting cycles and demanding just-in-time delivery guarantees that strain regional distributor networks. Direct contracting between brand owners and extrusion complexes is displacing traditional wholesale distribution in the Central Plateau, particularly for high-volume polyethylene film specifications. This channel restructuring is most visible in Nuevo León and Jalisco, where automotive and food processing clusters have sufficient scale to justify dedicated mill relationships and on-site inventory programs.
Mexico Flexible Plastic Packaging Market Segmentation
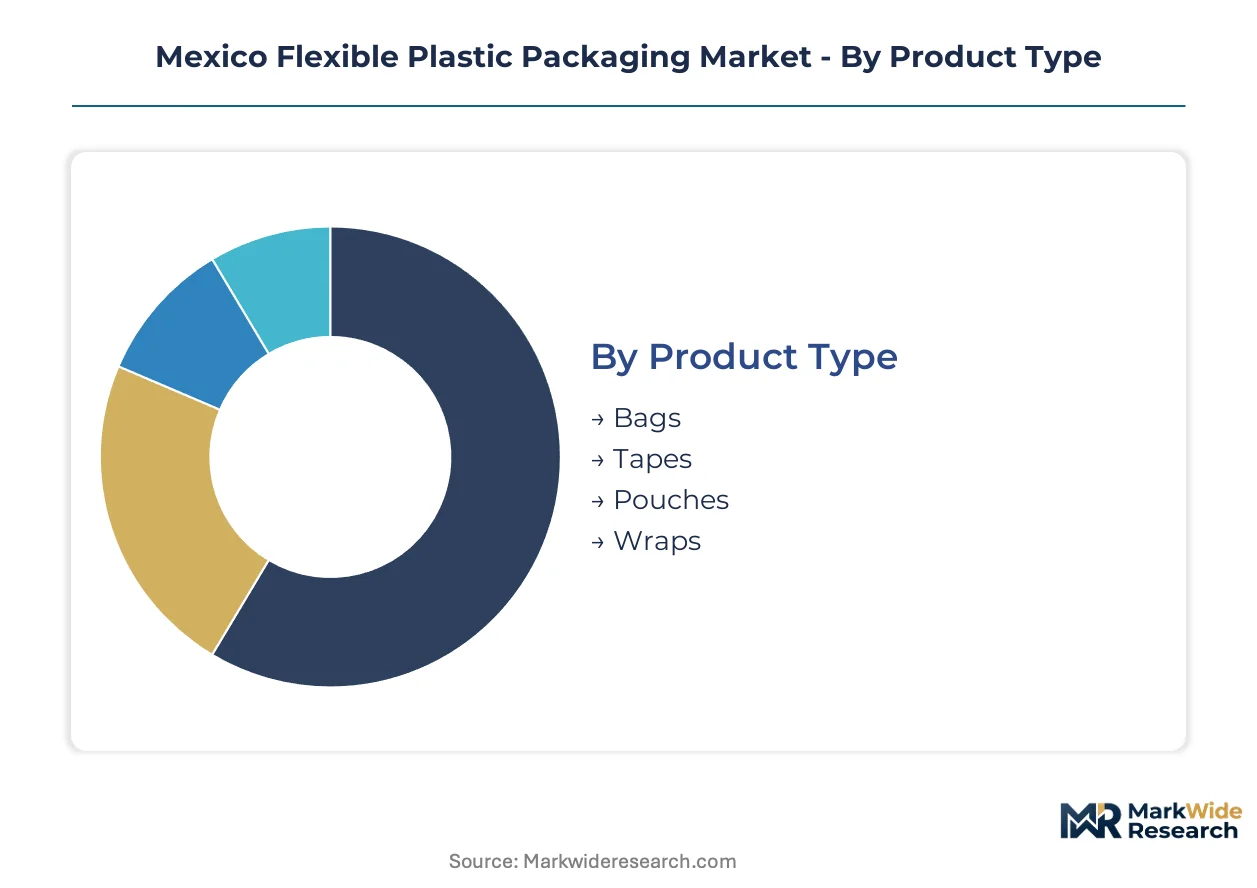
Segmentation in Mexico's flexible packaging market tracks how regulatory pressure, resin selection, and format conversion reshape procurement patterns across Jalisco and Nuevo León manufacturing clusters. Understanding these divisions clarifies where SEMARNAT compliance investments concentrate and which technologies capture redesign budgets.
Product Type:
Format selection spans protective containment through unit-dose dispensing, with each structure commanding distinct margin profiles and equipment requirements.
- Pouches:Multilayer laminated or coextruded structures with resealable zippers and spouts, typically 80-150 microns thick. Shelf-stable food manufacturers in Jalisco are converting rigid formats to stand-up pouches to reduce logistics cube and meet retailer sustainability scorecards. This shift absorbs premium equipment investment but unlocks higher per-unit margins.
- Wraps:Single or multilayer films between 12-50 microns, applied through manual, semi-automatic, or stretch-wrapping equipment. Fresh produce distributors in the Bajío corridor specify high-clarity polyethylene wraps to extend shelf visibility while minimizing gram-weight per unit. Volume concentration here pressures converters to optimize resin yield through down-gauging.
- Bags:Gusseted or flat configurations with heat-sealed bottoms, serving industrial and consumer applications from 5 to 50 kilogram capacities. Agricultural chemical and resin compounders in Nuevo León specify UN-certified flexible intermediate bulk containers with liner bags.
- Tapes:Pressure-sensitive adhesive films on polypropylene or PVC backings, applied for carton sealing and pallet unitization. Automotive parts clusters in Guanajuato consume high-tack tapes for just-in-time shipment consolidation.
Established volume favors wraps; emerging adoption favors pouches.
End Use Industry:
Demand concentration aligns with Mexico's processed food dominance and emerging pharmaceutical packaging requirements under COFEPRIS oversight.
- Food:The largest demand pool, spanning processed meats, dairy, baked goods, and shelf-stable staples. Processors in Jalisco and Nuevo León specify high-barrier coextruded films with oxygen transmission rates below 5 cc/m²/day to extend refrigerated shelf life. SEMARNAT's recycled content mandates are forcing rapid supplier consolidation toward certified converters.
- Beverages:Pouch and bag-in-box formats for juices, dairy alternatives, and alcoholic drinks. Amcor's Monterrey complex supplies five-state beverage clients with aseptic-fill-compatible structures. Hot-fill and retort applications favor polypropylene over polyethylene for thermal resistance.
- Pharmaceuticals:Blister lidding, sachets, and unit-dose pouches requiring COFEPRIS certification and in-house testing laboratories. Extended approval timelines lock working capital but filter competition toward established medical-grade converters.
- Personal Care:Sachets, sample packets, and flexible tubes for cosmetics and hygiene products. Guadalajara-based mid-tier processors drive short-run flexibility requirements.
Food retains volume leadership; pharmaceuticals present the steepest expansion trajectory.
Material:
Resin selection balances cost-performance against recyclability mandates and thermal processing requirements.
- Polyethylene:Low-density and linear low-density grades dominate tonnage due to sealability, clarity, and cost position. Blown film extrusion lines across the Monterrey-Tampico corridor process polyethylene for 60-plus percent of flexible packaging output. SEMARNAT's push for recyclable mono-material structures reinforces polyethylene's position.
- Polypropylene:Cast and oriented films for retort pouches, hot-fill applications, and high-strength tapes. Processed seafood manufacturers migrating from metal cans specify polypropylene-based retort structures for thermal resistance above 120°C. This displacement is gaining share fastest in premium shelf-stable segments.
- PVC:Shrink films and blister packaging for pharmaceutical and personal care visibility requirements. Environmental pressure and recycling incompatibility constrain growth in food-contact applications.
- Nylon:High-barrier coextrusions for vacuum packaging and oxygen-sensitive proteins. Premium meat processors specify nylon-ethylene vinyl alcohol laminates for extended chilled distribution.
Polyethylene anchors current supply; polypropylene captures conversion momentum.
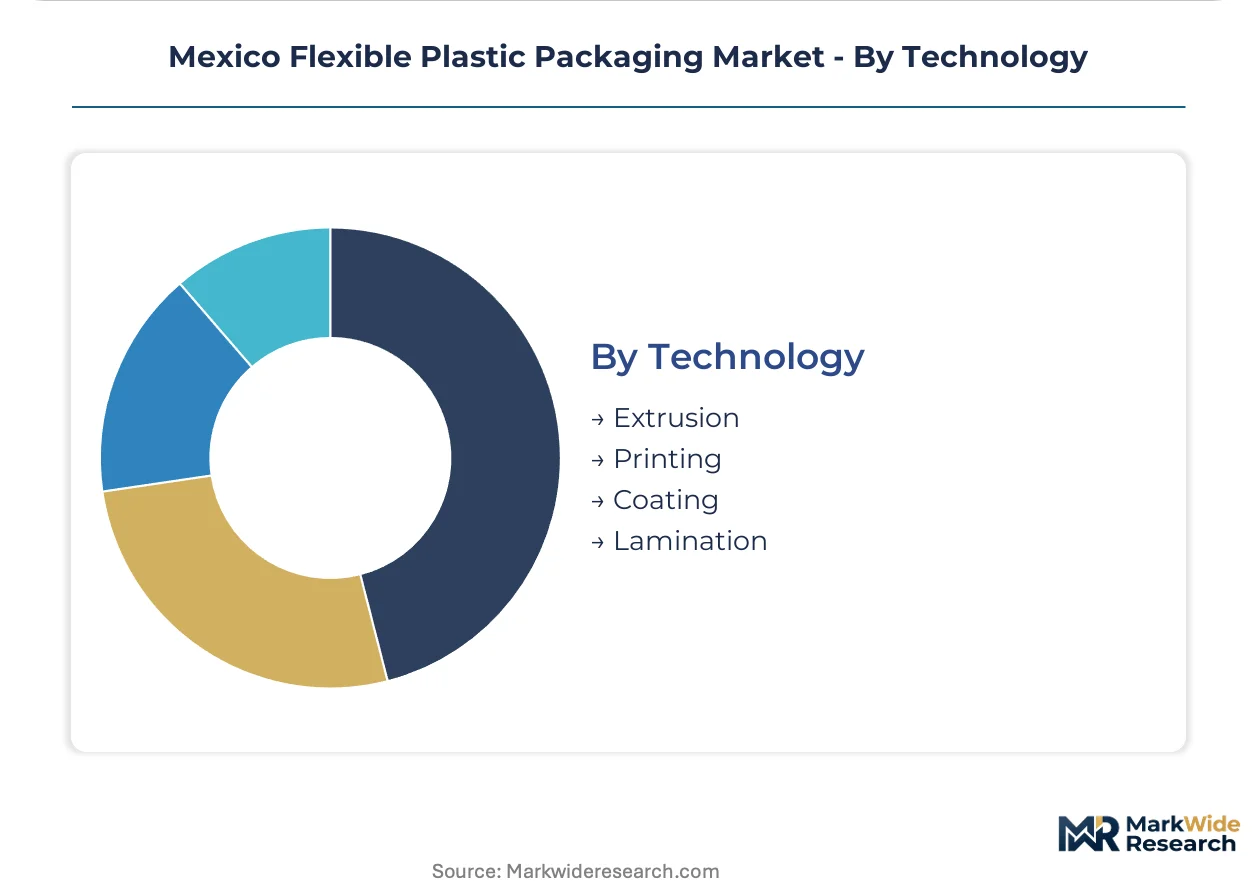
Technology:
Process capabilities determine barrier performance, print quality, and recyclability credentials.
- Extrusion:Blown and cast film production forms the foundational capability, with blown lines dominating 25-150 micron structures. Down-gauging to sub-25-micron films reduces resin consumption while maintaining seal integrity. Bajío corridor converters retrofit legacy assets for post-consumer recycled content.
- Lamination:Adhesive and extrusion lamination bond dissimilar films for combined barrier and mechanical properties. Multilayer coextrusion is displacing adhesive lamination for improved recyclability.
- Printing:Flexographic and rotogravure systems apply brand graphics and regulatory labeling. SEMARNAT's standardized labeling mandates drive investment in print-to-register accuracy.
- Coating:Barrier coatings of aluminum oxide or silicon oxide applied through vacuum deposition or solution coating. High-performance meat and cheese packaging specifies metallized coatings for oxygen and moisture resistance.
Extrusion commands installed base; coextrusion integration reshapes capability investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Lázaro Cárdenas anchors Mexico's Pacific packaging supply chain, handling resin imports and finished film exports that sustain converter operations across the Central Plateau.
Nuevo León
Automotive parts manufacturers in Monterrey drive demand for protective films and barrier pouches serving just-in-time distribution networks. SEMARNAT's extended producer responsibility rules pressure converters toward recyclable polyethylene structures. The Monterrey extrusion complex sustains supply continuity for beverage clients across five neighboring states.
Jalisco
Processed food manufacturers in Guadalajara expand pouch and wrap purchases for shelf-stable goods, converting rigid formats to reduce logistics cube. NOM-252-SSA1-2011 hygiene standards elevate demand for converters with in-house testing laboratories. Mid-tier food processors bypass regional distributors to negotiate direct volume contracts with extrusion complexes.
Bajío Region
Automotive parts and processed food clusters co-locate with packaging suppliers, generating integrated supply contracts for protective films. Down-gauging to sub-25-micron polyethylene films reduces resin consumption per unit while maintaining seal integrity. Blown film extrusion lines across Guanajuato and Querétaro process material for industrial and consumer applications.
Northern Border States
Maquiladora operations in Tamaulipas and Chihuahua consume high volumes of stretch wrap and industrial bags for cross-border shipment consolidation. Pemex petrochemical output fluctuations expose converters to ethylene feedstock price volatility. The Monterrey-Tampico supply corridor concentrates extrusion capacity within a 200-kilometer radius, creating vulnerability to localized logistics disruptions.
Veracruz and Oaxaca
Pending state-level plastic bans in these jurisdictions create first-mover advantage for converters developing paper-film hybrid formats. Environmental pressure accelerates format redesign ahead of enforcement timelines. Coastal processors face additional compliance layers as SEMARNAT tightens extended producer responsibility rules for packaging sold in Mexican territory.
Mexico Flexible Plastic Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin compounding and film extrusion. The market structure tilts toward backward-integrated suppliers with captive compounding capabilities, filtering volume away from smaller regional players. Two strategic archetypes dominate: multinational converters with established post-consumer resin supply agreements, and mid-cap specialists competing on short-run flexibility for regional food processors. Competitive moves concentrate on direct mill procurement relationships and retrofitting legacy extrusion assets for recycled content handling.
Among the multinational tier, Amcor PLC and Berry Global Inc. anchor positions through scale and integration depth, while SigmaQ Packaging occupies a specialist niche serving mid-tier processors in Guadalajara. Amcor leverages its Monterrey complex for supply continuity across multiple states. Berry Global's backward integration into resin compounding insulates margin pressure during price spike cycles. SigmaQ competes on flexibility rather than volume, capturing redesign budgets from regional food manufacturers converting from rigid formats.
| Leading Market Players |
|---|
| Amcor PLC |
| Huhtamaki Oyj |
| Berry Global Inc. |
| Sonoco Products Company |
| Galas De Mexico |
| GURPA |
| Sealed Air Corporation |
| Innovia Films |
| SigmaQ Packaging |
| Others |
Pricing and Supply Chain Analysis
Pemex ethylene feedstock volatility determines both pricing tier spreads and supply chain shape in Mexican flexible packaging. Converters absorbing resin price spike cycles compress margins on standard-grade polyethylene film while premium barrier structures command wider spreads.
Pricing Analysis
Volume-discount tiering structures separate certified food-contact converters from commodity film suppliers. Three-tier pricing stratifies across premium certified, standard industrial, and economy-grade tiers based on NOM-252-SSA1-2011 compliance status and volume scale. Pricing pressure stems from SEMARNAT's extended producer responsibility mandates forcing rapid format redesign. Mid-tier food processors in Guadalajara exhibit highest price sensitivity, while pharmaceutical clients under COFEPRIS oversight accept premium positioning for certified materials.
Supply Chain Analysis
Export-control regimes on advanced coextrusion and metallization equipment limit technology flows into Mexican converter operations. Supply concentrates in the Monterrey-Tampico corridor within Mexico, with resin feedstock drawing from US Gulf Coast petrochemical complexes and Pemex domestic output. Raw material dependencies include ethylene, propylene, and specialty barrier resins. Single-source vulnerability runs through the 200-kilometer extrusion corridor. Distribution runs through direct mill relationships displacing regional distributors in Jalisco and Nuevo León.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's flexible plastic packaging market represents early-cycle expansion as SEMARNAT regulations force format conversion from rigid to flexible structures. Pouch adoption among processed food manufacturers accelerates penetration beyond historical wrap-dominated consumption patterns.
For Market Incumbents: Pre-empt margin compression by retrofitting Monterrey and Guadalajara extrusion assets for post-consumer recycled content handling before enforcement deadlines tighten. Lock direct procurement relationships with multinational food manufacturers in the Bajío corridor to defend volume against backward-integrated resin compounders. Certification investment in COFEPRIS-compliant testing laboratories filters competition and sustains premium positioning. For New Entrants and Emerging Players: Veracruz and Oaxaca state-level plastic bans present geographic underpenetration for paper-film hybrid formats ahead of enforcement timelines. Target coastal processors lacking compliant alternatives with certified compostable structures and SEMARNAT documentation support. White-space exists in short-run flexibility for mid-tier personal care sachet producers in Guadalajara seeking faster turnaround than multinational converters provide. For Investors and Strategic Acquirers: The market sits at a regulatory-inflection phase that favors converters with captive resin compounding and established recycling stream certifications. Long-term viability hinges on post-consumer resin supply agreements and chain-of-custody documentation capabilities. Watch for Pemex petrochemical output stabilization as inflection indicator for margin recovery in polyethylene-dependent operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Berry Global's captive supply insulates margin pressure during ethylene price spike cycles. |
| Direct Mill Procurement Relationships | Amcor's Monterrey complex sustains five-state beverage client continuity through dedicated contracts. |
| Post-Consumer Recycled Content Retrofit | Legacy blown film line modifications enable SEMARNAT compliance ahead of recycled content mandates. |
| COFEPRIS Certification Investment | In-house testing laboratories filter competition toward medical-grade converters with extended approval capabilities. |
| Paper-Film Hybrid Format Development | First-mover positioning in Veracruz and Oaxaca captures redesign budgets ahead of state plastic bans. |
Research Methodology
A standing panel of blown film extrusion plant managers, procurement leads at Jalisco food processors, SEMARNAT compliance officers, and automotive parts packaging engineers provided ongoing calibration. Primary interviews combined with secondary validation against Mexican customs records, COFEPRIS pharmaceutical filings, and SEC disclosures from listed packaging multinationals. Bottom-up resin consumption estimates and top-down converter capacity assessments triangulated market sizing.
Scenario-bracketing anchored projections across conservative, baseline, and accelerated regulatory enforcement pathways. Segmentation dimensions modeled include product type, end-use industry, material resin, and technology process across the analysis window. CAGRs derived from resin demand elasticity, format conversion rates, and regional industrial cluster expansion. Forecast inputs incorporated SEMARNAT extended producer responsibility amendment timelines and Pemex petrochemical output volatility assumptions.
Practitioners should monitor state-level plastic ban enforcement schedules and post-consumer recycling infrastructure buildout for early signals. Forecasts reflect assumptions on regulatory implementation pace and resin price normalization. Material shifts in Pemex ethylene supply stability or accelerated state ban adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Flexible Film Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
Canada Flexible Plastic Packaging Market
Flexible Packaging
Italy Flexible Plastic Packaging Market
Flexible Packaging
GCC Shrink Sleeves Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
Flexible Lid Stock Packaging Market
Flexible Packaging
Morocco Flexible Packaging Market
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Flexible Detergent Packaging Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market