
 China Electric Vehicle Vrla Batteries Market | 2026-2036
China Electric Vehicle Vrla Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Vehicle Vrla Batteries Market Insights
The China electric vehicle VRLA battery market is decoupling into two distinct supply tiers. Premium absorbed glass mat lines serving start-stop contracts now command separate qualification protocols from commodity flooded units bound for low-speed EV replacement channels. Leoch International Technology Limited anchors the aftermarket through its dominance in Guangdong and Jiangsu manufacturing bases. BYD Company Ltd. leverages captive demand from its electric bus and passenger vehicle divisions to sustain vertical integration into VRLA auxiliary systems. Clarios competes on valve-regulated design leadership for micro-hybrid applications, while East Penn Manufacturing Company navigates export-oriented production from its Chinese joint ventures.
China electric vehicle VRLA batteries are sealed lead-acid cells utilizing pressure-regulated valves and immobilized electrolyte in either gel or AGM matrices, typically operating at 12V nominal with 30-100Ah capacity ranges for auxiliary and start-stop functions. Their primary purpose is to deliver reliable cyclic durability for hybrid electrical architectures where deep discharge tolerance outweighs energy density requirements. The AGM product category leads unit volume due to its superior vibration resistance in commercial vehicle chassis, while the start-stop application segment captures the deepest margin pools as OEMs tighten cycle-life specifications under GB/T 31484 testing protocols. Flooded technology occupies the replacement-driven two-wheeler channel where cost minimization dominates procurement criteria.
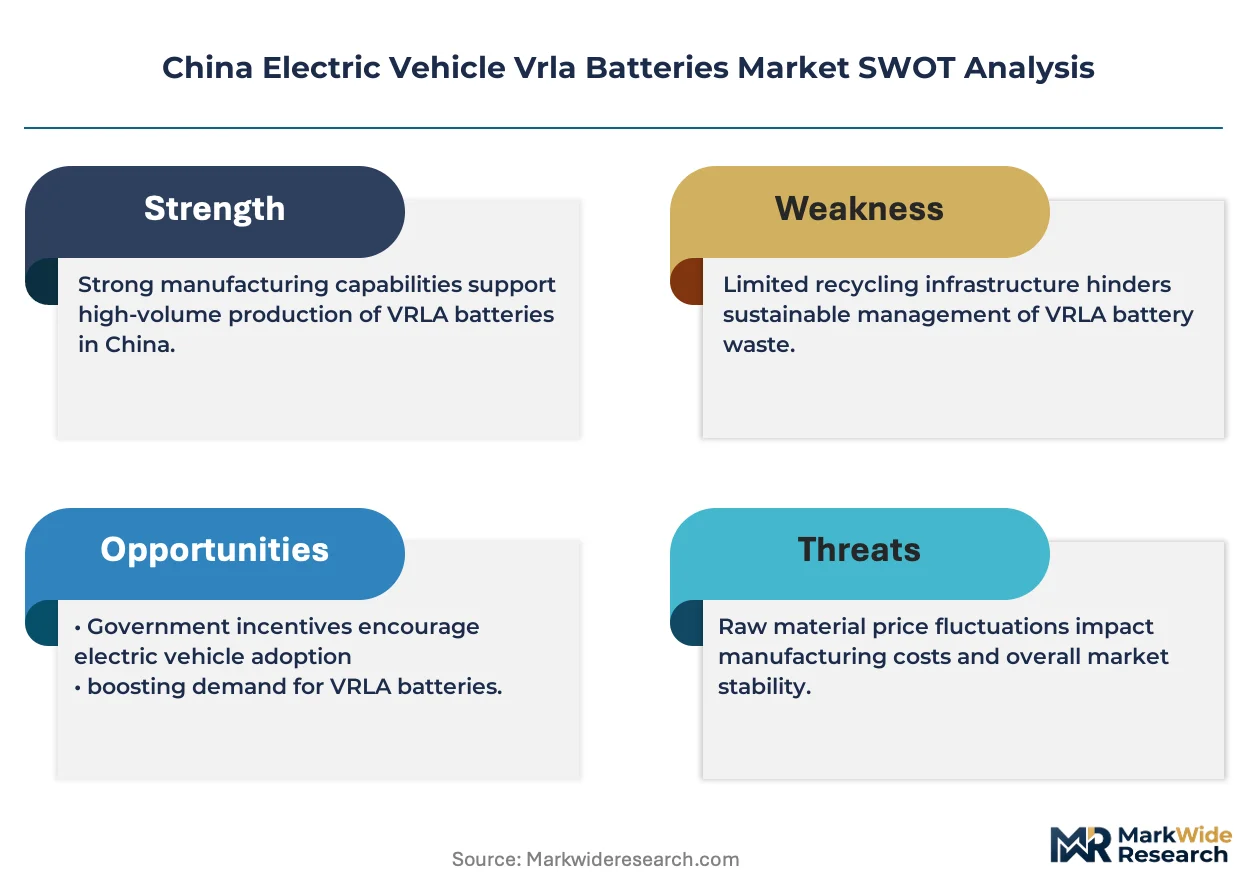
MIIT certification requirements and GB/T national standards govern cell format approval, while SAMR oversees market access and quality compliance for aftermarket battery distribution. The dual carbon goals framework is forcing manufacturers to document recycled lead content percentages and carbon intensity per kilowatt-hour produced. Stakeholders must decide whether to absorb the capital burden of closed-loop smelting partnerships or cede position to competitors with certified circular supply chains.
Market Dynamics
GB/T standards for lead-acid battery recycling are forcing manufacturers to restructure smelting partnerships and carbon accounting systems, compressing margins for uncertified producers while rewarding closed-loop operators with MIIT procurement preferences.
Growth Catalysts
- Dual carbon goals framework:Recycled lead content mandates are accelerating certified circular supply chain investments among Shandong and Hebei low-speed EV manufacturers.
- Start-stop system proliferation:Domestic passenger car OEMs are expanding AGM procurement for micro-hybrid architectures under tightened GB/T 31484 cycle-life specifications.
- Hebei fleet electrification:Cost-sensitive commercial operators are standardizing VRLA auxiliary systems for electric logistics vehicles operating in cold-climate conditions.
Market Restraints
- Lead price volatility:Raw material input costs fluctuate with London Metal Exchange pricing, squeezing margin buffers for flooded battery producers serving replacement channels.
- Guangdong supply concentration:Manufacturing gravity centers on Pearl River Delta facilities, creating single-point vulnerability for national distribution networks.
- Lithium-ion substitution:Falling lithium iron phosphate pack costs are displacing VRLA in premium start-stop applications above 50Ah capacity thresholds.
Strategic Opportunities
- Western China penetration:Sichuan and Chongqing logistics hubs remain underdeveloped for VRLA aftermarket service networks.
- SAMR-certified remanufacturing:Quality compliance pathways for refurbished auxiliary batteries create new revenue streams in circular economy pilots.
- AGM-gel hybrid chemistries:Converged electrolyte immobilization technologies are opening temperature-resilient applications for northern provincial bus fleets.
Industry Challenges
- GB/T certification timelines:Extended cell format approval cycles delay product launches by 8-14 months for new entrants.
- Smelter integration complexity:Legacy lead-acid producers face capital intensity barriers when retrofitting facilities for MEE emissions compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Vehicle Vrla Batteries Market |
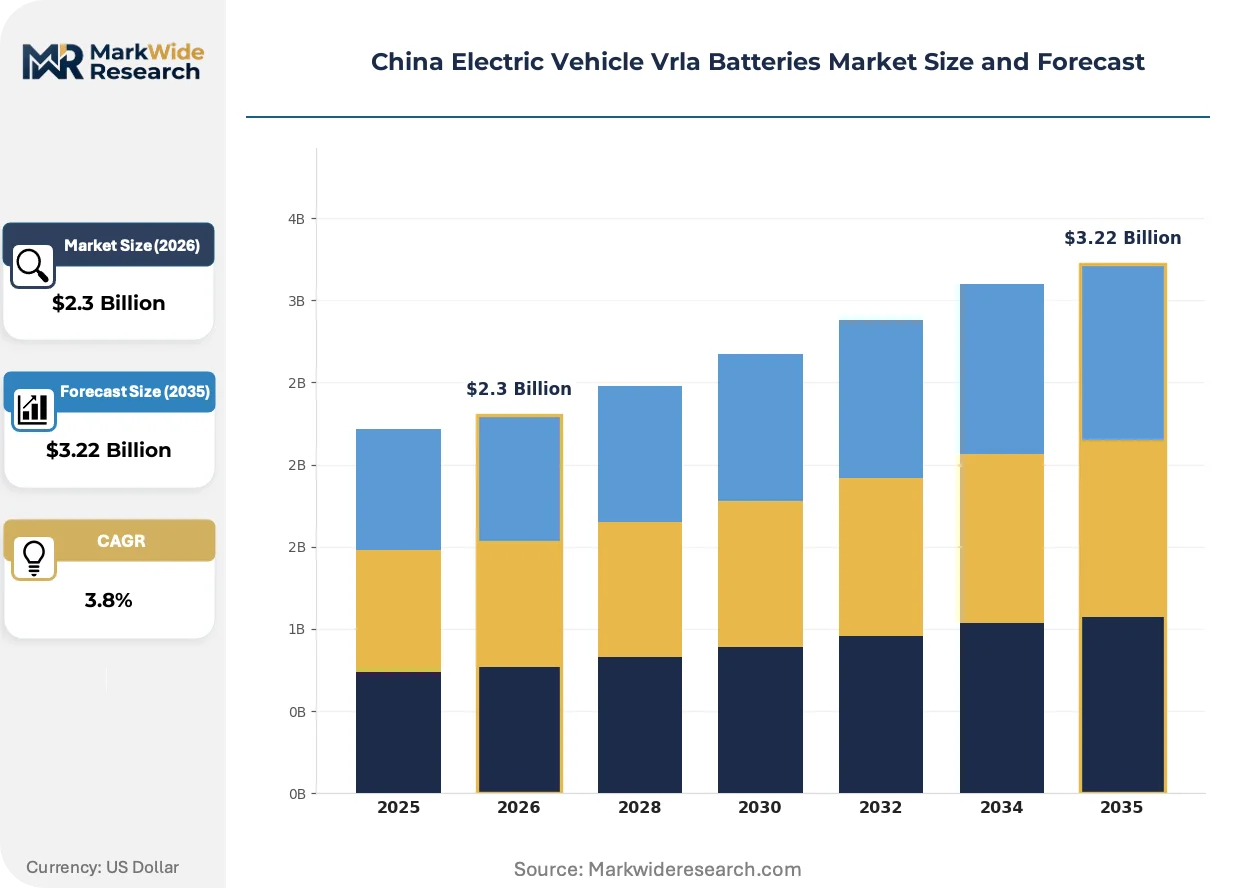
| Market Size in 2026 | $2.3 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AGM, Gel, Flooded, Others End User: Passenger Cars, Commercial Vehicles, Two-Wheelers, Buses Technology: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Others Application: Power Backup, Energy Storage, Start-Stop Systems, Hybrid Vehicles |
| Companies Covered | Leoch International Technology Limited, CATL, BYD Company Ltd., GS Yuasa Corporation, Exide Technologies, EnerSys, Clarios, East Penn Manufacturing Company, Amara Raja Energy and Mobility Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Vehicle Vrla Batteries Market Trends and Innovations
Carbon-intensity documentation requirements are reshaping competitive positioning around verified recycled content claims, while electrolyte chemistry advances target thermal stability gaps in northern climate operations.
Carbon fiber reinforced AGM separators are integrating into high-vibration commercial vehicle applications, delivering enhanced mechanical stability for start-stop duty cycles. Domestic truck OEMs in Shandong are adopting these configurations for mining and construction fleets. The technology is integrating pressure-regulated valve designs with improved gas recombination efficiency, extending service intervals in severe-duty environments.
MIIT's updated battery traceability regulations now mandate blockchain-verified material origin records for cells entering vehicle supply chains. Manufacturers must document smelter source data and carbon intensity per production batch. The start-stop segment faces the steepest compliance burden, with OEMs demanding third-party audit certificates for GB/T 31484-qualified suppliers.
Fleet operators in Hebei and Jiangsu are consolidating procurement through authorized distributor networks, abandoning fragmented wholesale channels. Direct contracting with SAMR-registered battery assemblers is replacing spot-market purchasing for municipal electric bus operators. This concentration is most visible in Shijiazhuang and Xuzhou logistics hubs, where volume commitments now determine pricing tiers and technical support access.
China Electric Vehicle Vrla Batteries Market Segmentation
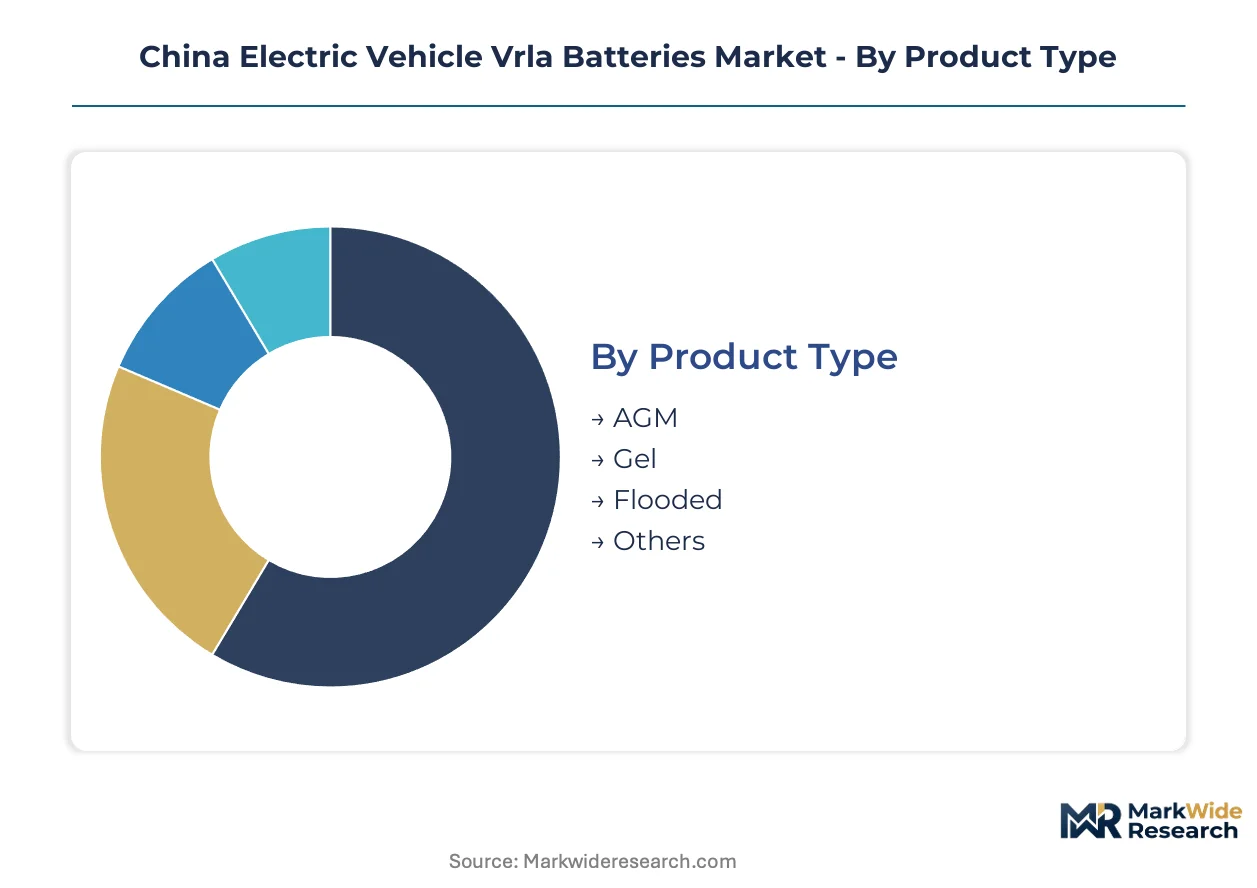
China's EV VRLA battery market segments along four distinct axes that reflect divergent technical requirements and procurement logics. Upgrade cycles vary dramatically across these divisions, from the 3-4 year replacement intervals in commercial vehicle auxiliary systems to the 6-8 year lifespans in stationary energy storage installations.
Product Type:
Replacement-cycle economics favor technologies with proven field durability over those requiring premature decommissioning.
- AGM:Absorbed glass mat construction immobilizes electrolyte in fiberglass separators, delivering superior vibration resistance for Shandong mining fleets and Hebei construction vehicles. Start-stop system OEMs specify AGM configurations under GB/T 31484 protocols due to their deep discharge recovery performance in micro-hybrid architectures.
- Gel:Silica-thickened electrolyte formulations tolerate broader temperature extremes, attracting procurement from northern provincial bus operators in Harbin and Changchun where cold-cranking reliability outweighs cost premiums. Gel cells sustain longer service intervals in municipal electric bus auxiliary systems.
- Flooded:Conventional liquid electrolyte designs dominate Guangdong two-wheeler replacement channels where cost minimization governs procurement decisions.
- Others:Thin-plate pure lead and carbon-enhanced variants serve niche high-rate discharge applications in premium commercial vehicle segments.
Volume placements concentrate in AGM configurations; the faster expansion belongs to gel formulations addressing northern climate resilience gaps.
End User:
Customer-type procurement maturity separates fleet operators with technical specifications from price-driven replacement buyers.
- Passenger Cars:Domestic OEMs integrate AGM auxiliary batteries into micro-hybrid start-stop systems, with MIIT traceability mandates requiring blockchain-verified smelter documentation for each production batch.
- Commercial Vehicles:Shandong and Hebei logistics fleets standardize VRLA auxiliary systems for electric light trucks operating in cold-climate distribution networks, prioritizing cycle-life performance over energy density metrics.
- Two-Wheelers:Cost-sensitive replacement demand concentrates in Guangdong and Jiangsu manufacturing clusters serving fragmented aftermarket channels.
- Buses:Municipal operators in Shijiazhuang and Xuzhou consolidate procurement through SAMR-registered assemblers, abandoning spot-market purchasing for volume-contracted technical support access.
Fleet-scale contracting dominates commercial vehicle and bus procurement; individual replacement transactions sustain two-wheeler channel liquidity.
Technology:
Cost-tier positioning determines competitive exposure to lithium-ion substitution pressures across capacity thresholds.
- Lead-Acid:Sealed VRLA architectures retain cost advantages in sub-50Ah auxiliary applications where deep discharge tolerance outweighs gravimetric energy density requirements.
- Lithium-Ion:Falling lithium iron phosphate pack costs displace VRLA in premium start-stop applications above 50Ah capacity thresholds, particularly in BYD's integrated passenger vehicle divisions.
- Nickel-Metal Hydride:Legacy hybrid architectures in select commercial vehicle platforms sustain limited procurement volumes.
- Others:Sodium-ion and solid-state experimental chemistries occupy pre-commercial evaluation phases for next-generation auxiliary systems.
Lead-acid retains volume dominance in cost-optimized segments; lithium-ion gains fastest in premium start-stop specifications.
Application:
Margin structure separates OEM-integrated system sales from aftermarket replacement transactions.
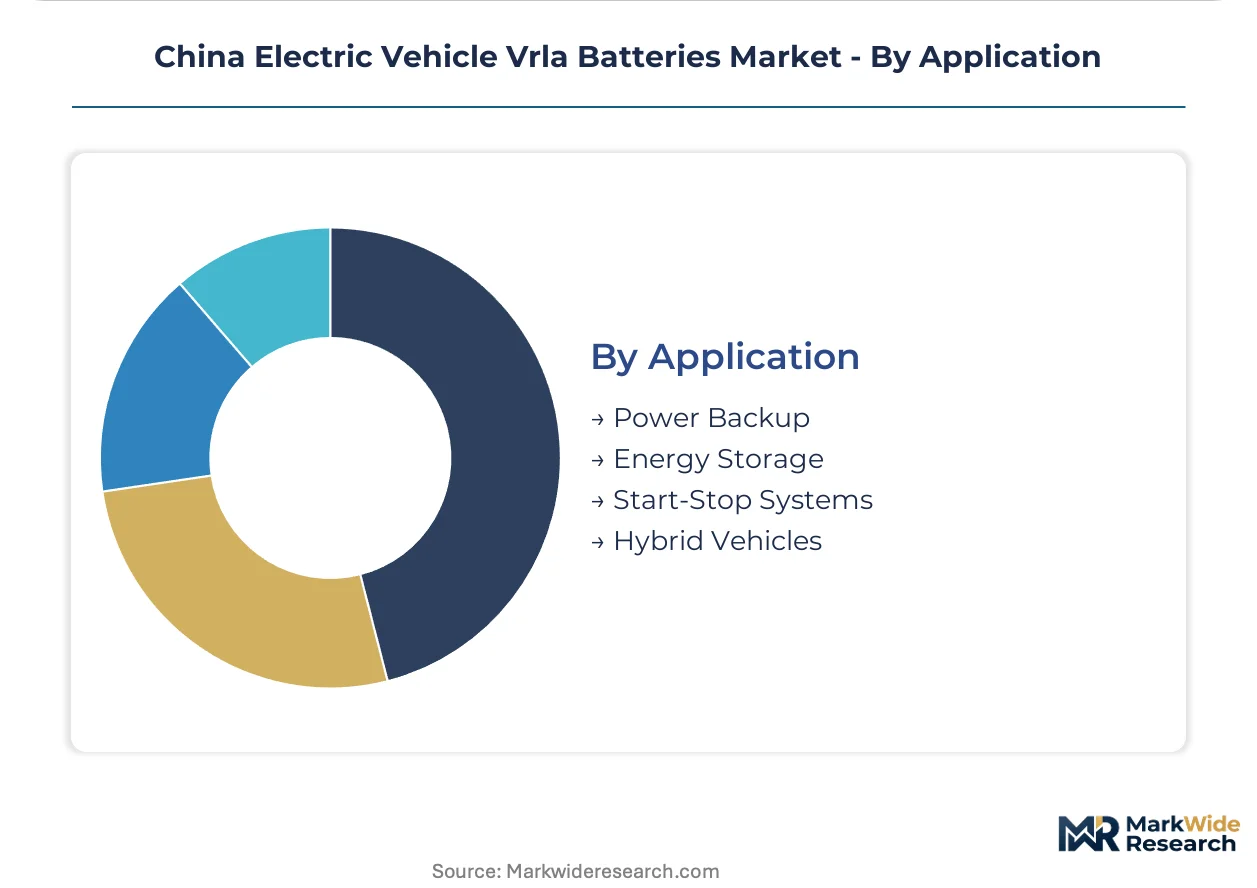
- Power Backup:Telecommunications and data center operators in Sichuan and Chongqing specify VRLA configurations for uninterruptible power supply redundancy, with service intervals extending to 8-10 years in controlled environments.
- Energy Storage:Grid-scale installations favor lithium-ion alternatives, constraining VRLA to residential and small commercial backup applications in western provincial markets.
- Start-Stop Systems:GB/T 31484 cycle-life specifications tighten qualification protocols for AGM suppliers serving domestic passenger car OEMs, concentrating margin pools in certified producer networks.
- Hybrid Vehicles:Mild-hybrid architectures in Shandong commercial fleets utilize VRLA auxiliary systems for cost-optimized electrification pathways.
Start-stop system integration commands premium positioning; power backup sustains the most predictable replacement revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors China's EV VRLA battery manufacturing through its dense concentration of low-speed electric vehicle assemblers and lead-acid cell producers. Provincial industrial parks in Heze and Jining host integrated supply chains linking smelters to battery pack integrators. The Yangtze River Delta and Pearl River Delta corridors complete the national production map with specialized AGM and gel cell facilities.
Shandong Province
Shandong's low-speed EV manufacturers in Heze and Jining drive VRLA procurement volumes for cost-optimized fleet applications. MIIT certification requirements enforce GB/T 31484 cycle-life testing for cells entering vehicle supply chains. The province's closed-loop smelting partnerships in Zibo are retrofitting for MEE emissions compliance under dual carbon goals mandates.
Hebei Province
Hebei's electric logistics fleet operators in Shijiazhuang specify VRLA auxiliary systems for cold-climate distribution networks. SAMR oversees aftermarket battery distribution quality compliance, tightening market access for uncertified producers. Tangshan industrial clusters are consolidating procurement through authorized distributor networks for municipal bus operators.
Guangdong Province
Guangdong's two-wheeler replacement channels concentrate flooded battery demand in Shenzhen and Dongguan manufacturing bases. The province's SAMR-registered assemblers face carbon-intensity documentation requirements for recycled lead content verification. Pearl River Delta facilities supply national distribution networks with commodity VRLA units.
Jiangsu Province
Jiangsu's start-stop system suppliers in Xuzhou and Changzhou procure AGM configurations under tightened OEM qualification protocols. GB/T standards for lead-acid battery recycling are restructuring smelting partnerships across the province. Nanjing-based technical service networks support fleet-scale contracting for commercial vehicle operators.
Sichuan-Chongqing Region
Sichuan and Chongqing logistics hubs remain underdeveloped for VRLA aftermarket service networks despite growing commercial vehicle populations. The region's telecommunications operators specify VRLA configurations for uninterruptible power supply redundancy in Chengdu data centers. Local procurement patterns favor cost-minimized flooded technology over AGM premium positioning.
China Electric Vehicle Vrla Batteries Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and recycled-content verification tiers. The market structures around three distinct supply archetypes: vertically integrated automotive OEMs with captive battery divisions, specialized lead-acid producers with certified circular supply chains, and export-oriented joint ventures serving international brand requirements. Competitive dynamics center on M&A activity targeting smelter integration and strategic partnerships for GB/T certification acceleration.
Within the specialized producer tier, Leoch International Technology Limited and East Penn Manufacturing Company exemplify distinct geographic anchoring strategies. BYD Company Ltd. occupies a position representing automotive OEM backward integration into auxiliary power systems. Clarios sits within the premium-tier vector for valve-regulated design specialization. These three archetypes—specialized lead-acid fabricators, automotive-integrated suppliers, and technology-differentiated designers—capture the competitive spectrum without exhaustive enumeration.
| Leading Market Players |
|---|
| Leoch International Technology Limited |
| CATL |
| BYD Company Ltd. |
| GS Yuasa Corporation |
| Exide Technologies |
| EnerSys |
| Clarios |
| East Penn Manufacturing Company |
| Amara Raja Energy and Mobility Ltd. |
| Others |
Pricing and Supply Chain Analysis
Dual carbon goals documentation requirements gate qualified supply access and premium-tier pricing power for VRLA battery producers serving China's electric vehicle sector. GB/T recycling mandates and MIIT traceability protocols separate certified circular operators from commodity flooded producers, compressing margins for uncertified players while rewarding closed-loop smelting partnerships with OEM procurement preferences.
Pricing Analysis
Cycle-life performance under GB/T 31484 testing protocols anchors value-based pricing for AGM configurations serving start-stop system OEMs. Pricing stratifies across certified premium, standard qualification, and economy replacement tiers, with carbon-intensity documentation and recycled lead content verification driving price differentiation. Cost compression in flooded two-wheeler channels intensifies because of lead price volatility on the London Metal Exchange. Guangdong aftermarket buyers exhibit the highest price sensitivity, while Hebei fleet operators prioritize cycle-life specifications over unit cost.
Supply Chain Analysis
Domestic-content mandates under MIIT certification requirements are reshaping sourcing toward Shandong and Jiangsu manufacturing clusters with verified smelter partnerships. Raw material flows draw from Zibo lead smelters, Pearl River Delta separator suppliers, and Hebei carbon additive producers. Single-source vulnerability concentrates in Guangdong's flooded battery assembly capacity serving national distribution networks. Distribution runs through SAMR-registered assemblers and authorized distributor networks replacing fragmented wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certified circular supply chains, with GB/T recycling compliance forcing uncertified producers toward exit or acquisition. Dual carbon goals enforcement separates viable operators from margin-compressed commodity players.
For Market Incumbents: Lock in smelter integration partnerships in Shandong and Hebei to secure MIIT procurement preferences under tightened material recovery mandates. Invest in blockchain-verified traceability systems to defend start-stop contract positions against lithium-ion substitution above 50Ah capacity thresholds. Carbon fiber reinforced AGM separator R&D protects mining fleet applications from emerging thermal stability competitors. For New Entrants and Emerging Players: Enter via Sichuan-Chongqing logistics hubs where VRLA aftermarket service networks remain underdeveloped despite growing commercial vehicle populations. Target power backup applications in Chengdu data centers where 8-10 year service intervals sustain predictable replacement revenue. Pursue SAMR-certified remanufacturing pathways as a circular economy go-to-market angle with lower capital barriers than greenfield cell production. For Investors and Strategic Acquirers: MIIT decertification announcements for non-compliant smelters are the leading indicator that consolidation momentum is accelerating toward closed-loop operators. Five-to-ten year viability favors specialized lead-acid fabricators with certified circular supply chains over export-oriented joint ventures exposed to lithium-ion displacement. Watch for Tangshan and Xuzhou municipal bus fleet procurement consolidation through direct assembler contracting as the signal that distributor-level acquisition targets are reaching exit windows.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Smelter Integration | Secures MIIT procurement preferences under GB/T recycling mandates for start-stop system suppliers. |
| Blockchain Traceability Implementation | Enables carbon-intensity documentation required by domestic passenger car OEMs under dual carbon goals. |
| AGM-Gel Hybrid Chemistry Development | Opens temperature-resilient applications for Harbin and Changchun municipal bus fleet procurement. |
| Western China Service Network Expansion | Captures underserved commercial vehicle populations in Sichuan-Chongqing logistics corridors. |
| SAMR-Certified Remanufacturing Launch | Creates circular economy revenue streams with lower capital intensity than virgin cell production. |
Research Methodology
Multi-period observation of GB/T certification timelines, MIIT traceability adoption rates, and smelter partnership formations anchored the trend analysis, supplemented by interviews with lead-acid cell engineering directors, OEM platform procurement managers, aftermarket distributor principals, and MEE compliance officers. Secondary validation drew from MIIT battery industry bulletins, SAMR quality compliance registries, Shanghai Metals Market lead price data, and provincial industrial park investment disclosures. Bottom-up unit shipment modeling triangulated against top-down value estimates across product type and application segments.
Segment-weighting approaches distributed value projections across AGM, gel, flooded, and emerging chemistry configurations, with application-level modeling for start-stop systems, power backup, hybrid vehicles, and energy storage. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking OEM platform plans. Key forecast inputs included lithium iron phosphate cost curves displacing VRLA above 50Ah thresholds and Hebei fleet electrification penetration rates for cold-climate logistics applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt lithium-ion cost declines or accelerated dual carbon goals enforcement. Forecasts reflect documented assumptions about smelter retrofit completion rates and SAMR certification queue processing times. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Asia-Pacific Battery Market
Batteries
East Africa Battery Market
Batteries
3D-Printed Battery Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
West Africa Battery Market
Batteries
Cobalt-Free Battery Market
Batteries
Li-Ion Pouch Battery Market
Batteries
Portable Battery Station Market
Batteries
US Solar Battery Market
Batteries
Wide Temperature Battery Market
Batteries
DMC for Battery Market
Batteries
Advanced Batteries Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
Power Battery Sealant Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Southeast Asia Battery Market