
 Yacht Battery Market | 2026-2036
Yacht Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Yacht Battery Market Analytics
The EU Green Deal is restructuring marine propulsion and auxiliary power requirements across European waterways. Corvus Energy leverages its Oslo-based engineering heritage to dominate large-format lithium-ion systems for superyachts. Siemens Energy sustains a competitive edge through integrated power management architectures that bridge battery storage with shore connection protocols. Leclanché SA anchors its position in Swiss-German yacht builds through specialized deep-cycle modules.
Yacht batteries are electrochemical storage systems engineered for cyclic discharge in marine environments, typically specified with IP67 ingress protection and salt spray resistance to IEC 60068-2-11 standards. Their primary purpose is to supply silent hotel loads, electric winches, and hybrid propulsion without diesel generator dependency. Lithium-ion chemistry leads value capture due to energy density advantages, while lead-acid retains share in cost-sensitive recreational boating segments. Deep cycle technology occupies the fastest-expanding margin pool as owners extend overnight anchoring durations without generator noise.
EMA marine equipment directives, the EU F-Gas Regulation, and ISO 16315 standards collectively dictate battery safety certification, thermal runaway containment, and installation compliance for vessels over 24 meters. These frameworks elevate product development costs but simultaneously lock out uncertified suppliers, concentrating procurement among validated vendors. Stakeholders must monitor pending amendments to the EU AI Act for autonomous battery management systems before committing to platform architectures.
Market Dynamics
The EU F-Gas Regulation is forcing superyacht builders to abandon diesel generators for auxiliary power, compressing installation timelines and elevating lithium-ion chemistry specifications across Mediterranean shipyards.
Growth Catalysts
- EU Green Deal marine mandates:The framework tightens emissions thresholds for vessels over 24 meters, compelling owners to retrofit auxiliary systems with electrochemical storage before charter season deadlines.
- Silent anchoring protocols:Charter operators in Monaco, Antibes, and Palma de Mallorca now mandate zero-generator overnight stays to meet guest expectations, accelerating deep-cycle battery procurement.
- Lithium-ion energy density gains:Cell chemistry advances enable 40% footprint reduction versus lead-acid equivalents, freeing valuable engine room volume for owners of 30-50 meter vessels.
Market Restraints
- Cobalt and lithium carbonate volatility:Raw material price swings from DRC and Chilean supply nodes compress module margins for European integrators.
- Norwegian cell production concentration:Corvus Energy and a limited Oslo-Bergen supplier cluster create single-source vulnerability for 500+kWh superyacht systems.
- Thermal runaway containment costs:ISO 16315 fire suppression requirements add 15-20% to system BOM, deterring cost-sensitive recreational boaters from lithium conversion.
Strategic Opportunities
- Greek and Croatian charter expansion:Athens and Split-based operators lack electrified fleets versus western Mediterranean peers, creating first-mover installation windows.
- Shore power integration convergence:Battery systems paired with high-voltage marina connections enable full diesel elimination in port, a configuration now specified by Amsterdam and Barcelona marinas.
- EU AI Act autonomous management:Pending amendments to battery management system certification create regulatory runway for predictive cycling algorithms in 2026-2028 builds.
Industry Challenges
- Marine electrical engineering talent scarcity:Shipyards in Genoa and Viareggio struggle to recruit technicians certified for high-voltage DC installation and IEC 60068-2-11 salt spray validation.
- Retrofit integration complexity:Legacy 12V and 24V auxiliary architectures in 1990s-2000s hulls resist modular lithium drop-in without complete distribution panel replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yacht Battery Market |
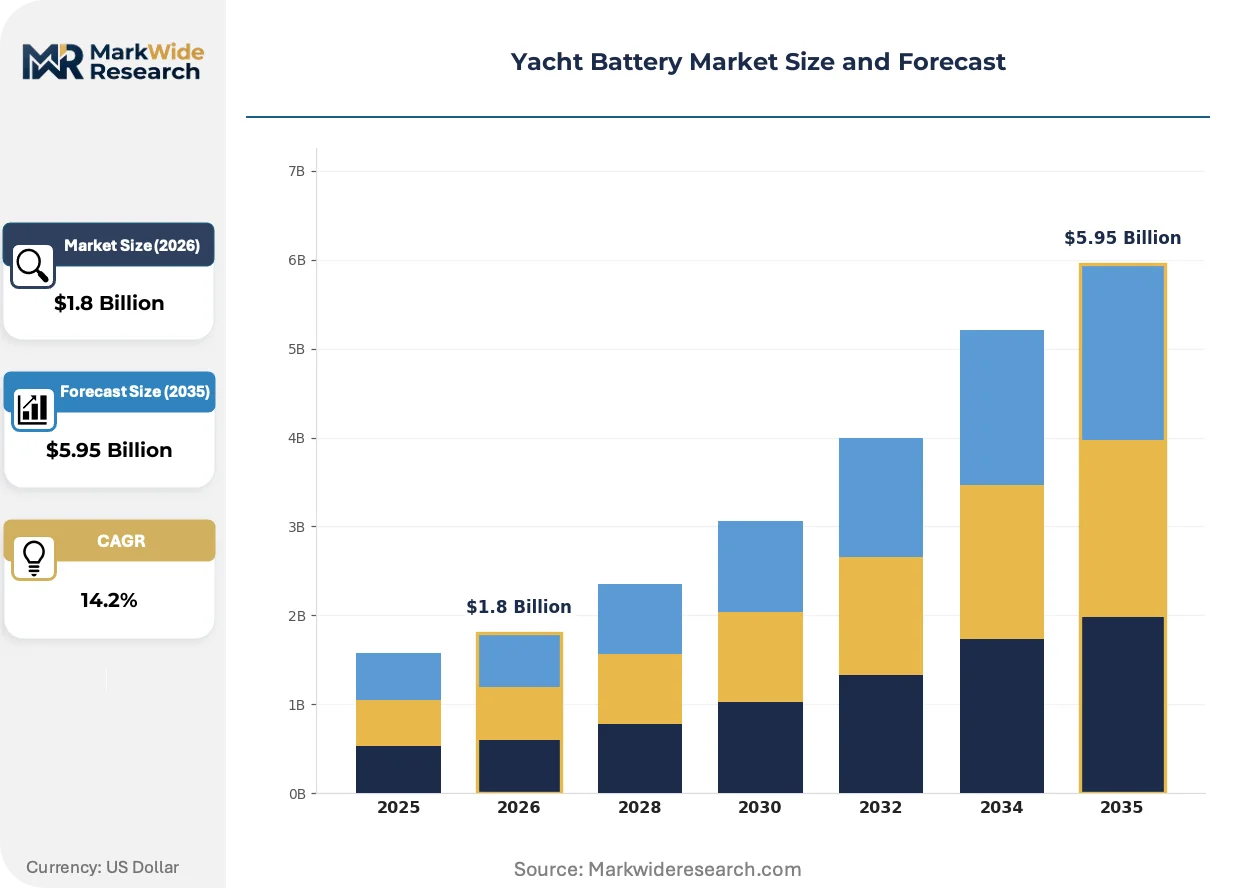
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-acid, Lithium-ion, Absorbent Glass Mat, Gel Cells Application: Recreational Boating, Commercial Vessels, Luxury Yachts, Offshore Energy Technology: Deep Cycle, Starting, Solar Hybrid, Power Management End User: Boat Owners, Fleet Operators, Marine Dealers, Yacht Charters |
| Companies Covered | Corvus Energy, Siemens Energy, Leclanché SA, EnerSys, EST-Floattech, Victron Energy, CATL, Relion Battery, AYK Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yacht Battery Market Evolving Landscape
Electrochemical storage architectures are fragmenting into application-specific configurations, while regulatory pressure and owner behavior compress procurement cycles from specification to sea trial.
Solid-state lithium-metal chemistry is modularizing. The technology replaces flammable liquid electrolytes with ceramic or polymer matrices, eliminating thermal propagation risks. Dutch and Italian builders of 60-meter-plus vessels are specifying pilot installations for 2026-2027 delivery slots. This shift is modularizing system architecture into discrete, hot-swappable cell blocks that reduce yard time and enable incremental capacity expansion.
The EU AI Act is extending certification requirements to autonomous battery management systems. Marine integrators must now document algorithmic decision pathways for charge balancing and fault isolation. Superyacht segments above 3,000 gross tonnage face the steepest compliance burden, with classification societies in Rotterdam and Hamburg developing interim verification protocols ahead of formal enforcement.
Buyer committees now specify batteries directly rather than delegating to shipyard procurement departments. Charter management companies in the Balearics and Côte d'Azur are consolidating purchasing across fleets to extract volume terms from integrators. This concentration is most visible in Palma de Mallorca, where three operators control 40% of 40-meter-plus Mediterranean charter capacity and negotiate master supply agreements with Oslo-based system houses.
Yacht Battery Market Segmentation
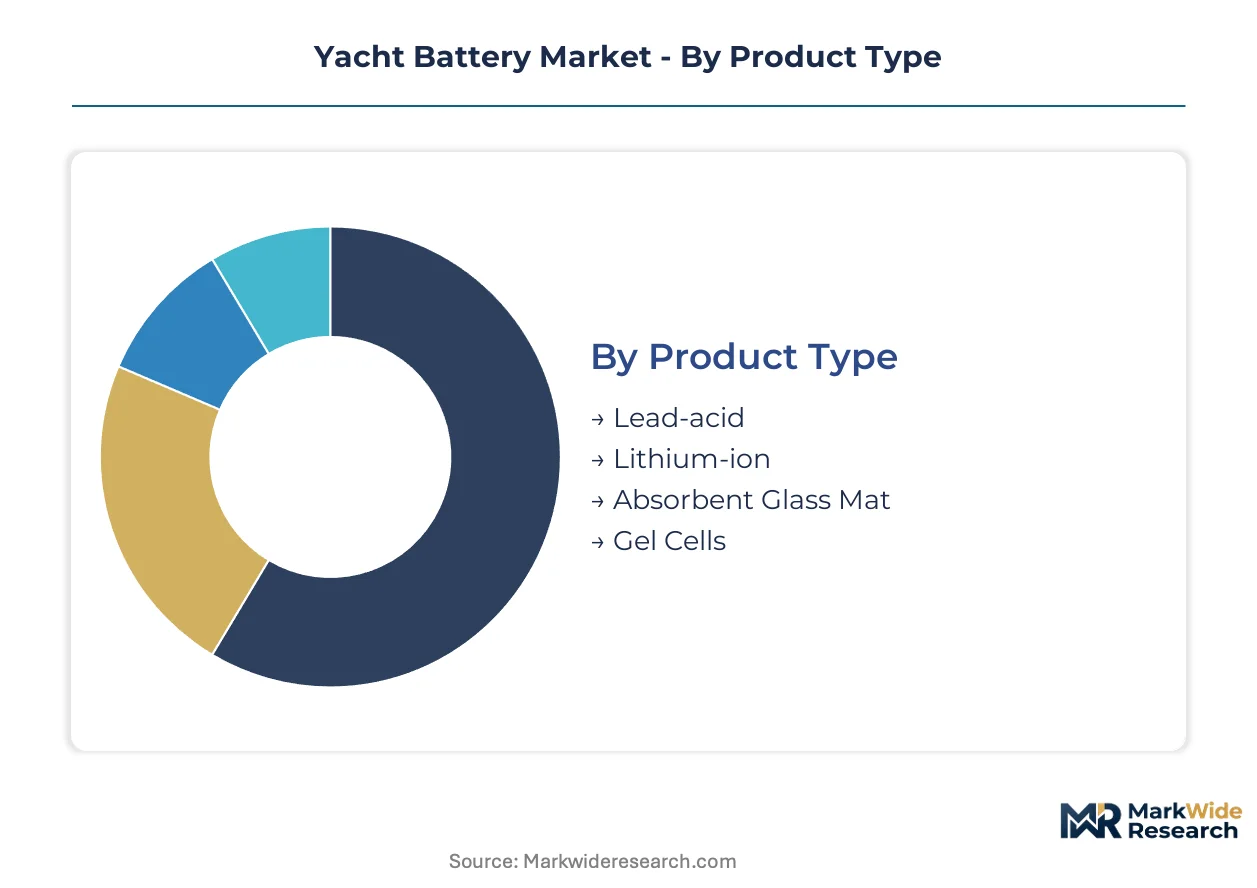
Yacht battery procurement splits sharply between legacy chemistries and advanced lithium systems, with each segment commanding distinct supply chains and certification requirements. Understanding these fault lines reveals where margin pools concentrate and which specifications will dominate Mediterranean and Nordic build schedules.
Product Type:
Supply concentration in lithium-ion cell production centers on Norwegian and South Korean manufacturing nodes, while lead-acid retains distributed European foundry capacity.
- Lithium-ion:NMC and LFP cell architectures deliver energy densities above 250 Wh/kg, enabling 40% footprint compression in engine rooms. Demand clusters in 40-meter-plus superyacht builds from Dutch and Italian yards where EU F-Gas Regulation mandates diesel generator displacement.
- Lead-acid:Flooded and VRLA variants persist in sub-15 meter recreational craft where capital constraints override cycle life considerations. Spanish and Portuguese coastal fleets represent residual demand pockets.
- Absorbent Glass Mat:Valve-regulated designs with fiberglass mat separators tolerate vibration in planing hull applications. Greek charter operators specify AGM for RIB tender fleets requiring maintenance-free reliability.
- Gel Cells:Silica-thickened electrolyte formulations resist deep discharge damage in seasonal-use vessels. Baltic Sea cruising grounds favor gel chemistry for winter lay-up tolerance.
Today's leader: Lithium-ion. Tomorrow's challenger: Absorbent Glass Mat.
Application:
Cost tier stratification separates charter-fleet specifications from owner-operator discretionary purchases.
- Luxury Yachts:Custom 50-meter-plus builds specify modular lithium racks with active thermal management. Monaco and Antibes-based management companies mandate silent hotel load capability for overnight anchoring protocols.
- Recreational Boating:Mass-market 8-15 meter cruisers drive lead-acid volume through marine retail channels. Italian and French Mediterranean marinas service the largest installed base replacement cycles.
- Commercial Vessels:Workboat and patrol craft applications prioritize starting battery reliability over cycle depth. Croatian and Greek island ferry operators represent emerging electrification demand.
- Offshore Energy:Crew transfer and service vessels require hybrid propulsion buffers for dynamic positioning. North Sea wind farm logistics contracts specify Norwegian-integrated battery systems.
Luxury Yachts capture premium pricing. Recreational Boating commands unit volume leadership.
Technology:
Volume concentration in deep cycle systems reflects charter industry operational requirements for extended generator-off operation.
- Deep Cycle:Thick-plate designs sustain 80% depth-of-discharge without capacity degradation. Balearic and Côte d'Azur charter fleets specify deep cycle banks for 12-hour silent anchoring mandates.
- Power Management:Integrated battery management systems with CAN bus monitoring enable cell-level balancing. Classification societies in Rotterdam and Hamburg certify these architectures for autonomous fault isolation.
- Starting:High-cranking-amp designs deliver short-duration burst current for diesel ignition. Remains standard specification in emergency generator backup circuits.
- Solar Hybrid:MPPT-integrated charging controllers optimize photovoltaic input for liveaboard cruisers. Croatian charter operators pilot solar-battery hybrids for Adriatic island-hopping routes.
Deep Cycle dominates current procurement. Power Management exhibits steepest expansion trajectory.
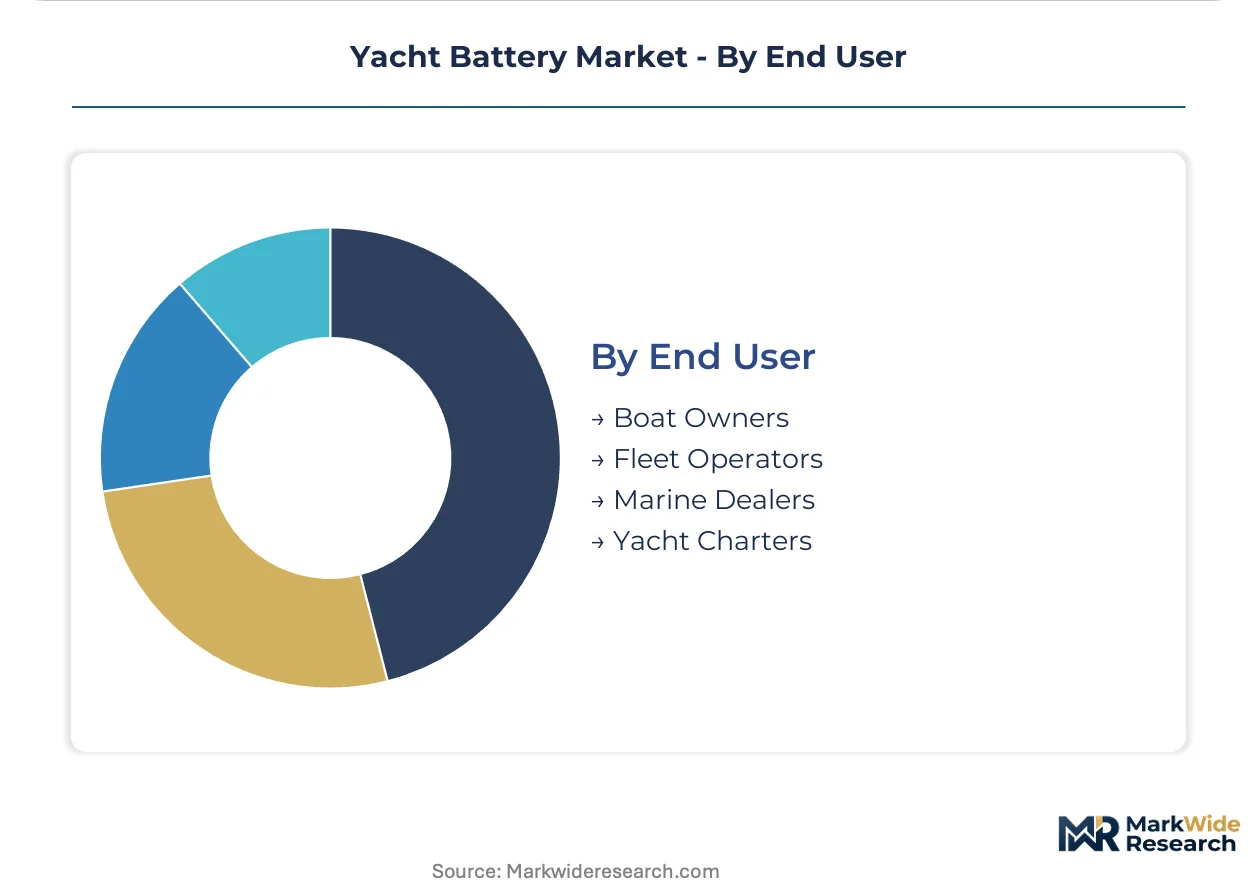
End User:
Customer type determines specification authority and procurement channel structure.
- Yacht Charters:Fleet management companies in Palma de Mallorca and Antibes consolidate purchasing across 40-meter-plus vessels. Three operators control substantial Mediterranean capacity and negotiate master supply agreements directly with Oslo-based integrators.
- Boat Owners:Individual purchasers rely on yard recommendations for retrofit specifications. Italian and Dutch superyacht owners increasingly specify batteries independent of shipyard procurement departments.
- Fleet Operators:Commercial and government vessel managers prioritize lifecycle cost over initial capital outlay. Greek and Croatian state maritime agencies tender for standardized electrification packages.
- Marine Dealers:Retail distribution networks service recreational replacement demand. French Riviera chandleries maintain the densest stocking points for emergency lead-acid replacement.
Yacht Charters concentrate specification authority. Fleet Operators represent emerging direct procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Superyacht electrification traces its commercial lineage to Dutch and Italian shipyards that pioneered lithium-ion auxiliary systems during the 2010s EU emissions tightening. Those early installations established the technical and regulatory templates now diffusing across Mediterranean and North Sea build centers.
Netherlands
Feadship and Oceanco drive demand for 500+kWh lithium systems in 60-meter-plus builds. The Dutch Human Environment and Transport Inspectorate enforces strict IEC 60068-2-11 salt spray certification for North Sea operations. Amsterdam and Rotterdam marinas now mandate shore-power-compatible battery configurations for new berth allocations.
Italy
Benetti and Sanlorenzo specify modular lithium racks for silent anchoring protocols in Monaco and Antibes charter circuits. The EU F-Gas Regulation compresses installation timelines for auxiliary system electrification. Viareggio and La Spezia shipyards cluster the densest superyacht battery integration capacity outside Norway.
Norway
Oslo and Bergen host the dominant cell production cluster for European marine lithium systems. The Norwegian Maritime Authority aligns with EU MRV regulations for vessel emissions reporting. Corvus Energy anchors its engineering operations here, supplying integrated power management to Dutch and Italian builders.
Spain
Balearic charter operators in Palma de Mallorca consolidate fleet purchasing for 40-meter vessels. The Spanish Ministry of Transport implements EU Green Deal marine mandates through port authority directives. Barcelona marina infrastructure investments prioritize high-voltage shore connection compatibility for hybrid vessels.
United Kingdom
Southampton and Plymouth service centers handle retrofit demand from legacy hull owners seeking lithium conversion. The Maritime and Coastguard Agency enforces ISO 16315 thermal runaway containment standards. British charter operators in the Solent lag Mediterranean peers in electrification penetration, creating installation backlog.
Yacht Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and integration depth. Norwegian and Swiss-German specialists dominate the high-kilowatt-hour superyacht segment where EU regulatory compliance elevates product development costs. Three archetypes populate the vendor map: integrated power management architects, large-format lithium system houses, and distributed marine electronics suppliers. Consolidation pressure intensifies as charter fleet purchasing concentrates procurement authority, while backward integration into cell production remains rare due to capital intensity.
Within the integrated systems tier, Corvus Energy and Siemens Energy exemplify the engineering-heavy positioning required for 500+kWh superyacht installations. Leclanché SA occupies a specialized position in Swiss-German build channels. These three represent distinct geographic anchoring strategies—Oslo-based cell production, German power electronics integration, and Swiss precision manufacturing—each calibrated to different segments of the Mediterranean and North Sea order books.
| Leading Market Players |
|---|
| Corvus Energy |
| Siemens Energy |
| Leclanché SA |
| EnerSys |
| EST-Floattech |
| Victron Energy |
| CATL |
| Relion Battery |
| AYK Energy |
| Others |
Value Network & Pricing Analysis
Fleet purchasing consolidation across Mediterranean charter operators forces integrators toward volume discount structures while elevating certification-grade specifications that compress margins for uncertified vendors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with ISO 16315 thermal runaway containment and IEC 60068-2-11 salt spray certification separating premium Norwegian-integrated systems from commodity lead-acid replacements. Price differentiation rests on active thermal management inclusion and shore-power protocol compatibility. Cost compression in recreational boating tiers intensifies because lithium carbonate volatility feeds through cell contract renegotiations. Charter fleet managers exhibit lowest price sensitivity, while individual boat owners in Spanish and Portuguese coastal markets resist premium conversion.
Supply Chain Analysis
Single-source vulnerability sits with the Oslo-Bergen cell production cluster, where Corvus Energy and limited Norwegian suppliers anchor 500+kWh superyacht system output. Geographic supply concentration spans Norway, South Korea, and China for lithium-ion cell manufacturing, with European foundry capacity retaining lead-acid production. Raw material dependencies draw from Chilean lithium carbonate and DRC cobalt nodes. Tariff exposure on Chinese cell imports creates procurement uncertainty for Dutch and Italian integrators. Distribution runs through shipyard procurement departments and direct fleet operator agreements, with Palma de Mallorca-based charter managers consolidating master supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in deep-cycle lithium systems as EU F-Gas Regulation mandates displace diesel generator dependency and extend overnight anchoring specifications.
For Market Incumbents: Deploy backward integration into cell supply agreements to lock cobalt and lithium carbonate offtake before price volatility transmits to module costs. Incumbent Norwegian and Swiss-German specialists must accelerate solid-state lithium-metal pilot certifications to defend against emerging South Korean cell producers entering marine certification pathways. Certification investment in EU AI Act autonomous battery management compliance creates switching costs against uncertified challengers. For New Entrants and Emerging Players: Marine electrical engineering talent scarcity in Genoa and Viareggio shipyards creates partnership openings for specialized installation service providers. Greek and Croatian charter expansion presents the most penetrable geography, with Athens and Split-based operators lacking electrified fleets versus western Mediterranean peers. Direct technical training partnerships with classification societies in Rotterdam and Hamburg offer credible market entry without incumbent certification heritage. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap integrators possessing IEC 60068-2-11 validation and active thermal management IP but lacking fleet-scale procurement relationships. Long-term viability favors vendors positioned across both superyacht auxiliary electrification and offshore wind crew transfer vessel hybridization. The signal to watch is Palma de Mallorca charter operator consolidation accelerating toward single-source master agreements that freeze out sub-scale competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Pilot Certification | Dutch and Italian builders of 60-meter-plus vessels specify ceramic electrolyte installations for 2026-2027 delivery slots. |
| EU AI Act Compliance Investment | Classification societies in Rotterdam and Hamburg develop interim verification protocols for autonomous battery management algorithms. |
| Shore Power Integration Partnership | Amsterdam and Barcelona marinas now mandate high-voltage shore connection compatibility for new berth allocations. |
| Fleet Master Supply Agreement | Three Palma de Mallorca operators controlling substantial Mediterranean charter capacity consolidate procurement authority. |
| Marine Electrical Talent Acquisition | Genoa and Viareggio shipyards struggle to recruit technicians certified for high-voltage DC installation and salt spray validation. |
Research Methodology
Bottom-up yacht charter and fleet operator modeling reconciled against top-down lithium cell production tracking forms the analytical core of this study. Primary interviews with superyacht build specification managers, marine electrical integrators, classification society surveyors, and charter fleet procurement directors combined with secondary validation from EU maritime regulatory filings, ISO certification databases, and Norwegian Maritime Authority emissions reports. Shipyard order book analysis and marina infrastructure investment disclosures provided installation timeline calibration.
Historical trendline analysis of superyacht electrification adoption from early Dutch and Italian lithium auxiliary installations through current EU F-Gas Regulation compliance windows informed projection architecture. Segmentation dimensions modeled include chemistry type, vessel length tier, application configuration, and end-user procurement channel. CAGRs derived from install-base replacement cycles, new-build specification penetration, and regulatory deadline clustering across the analysis window. Forecast inputs incorporated cobalt and lithium carbonate price volatility bands and solid-state chemistry commercialization timelines.
Revisions become necessary when EU AI Act enforcement timelines shift, solid-state lithium-metal manufacturing yields miss commercial thresholds, or Norwegian cell production concentration triggers supply disruption. Forecasts reflect documented assumptions on regulatory compliance cost transmission and charter operator consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Primary Lithium Battery Market
Batteries
Europe Lead-Acid Battery Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
West Europe Battery Market
Batteries
Aluminum Wire Battery Market
Batteries
Europe Automotive Lead-Acid Battery Market
Batteries
Southeast Asia Battery Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
South America Primary Battery Market
Batteries
Marine Powerboat Battery Market
Batteries
Asia-Pacific Battery Market
Batteries
Portable Battery Market
Batteries
Silicon Battery Market
Batteries
48 Volt Battery System Market
Batteries
Global Marine Battery Market