
 Global Lithium-Ion Battery Energy Storage System Market | 2026-2036
Global Lithium-Ion Battery Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
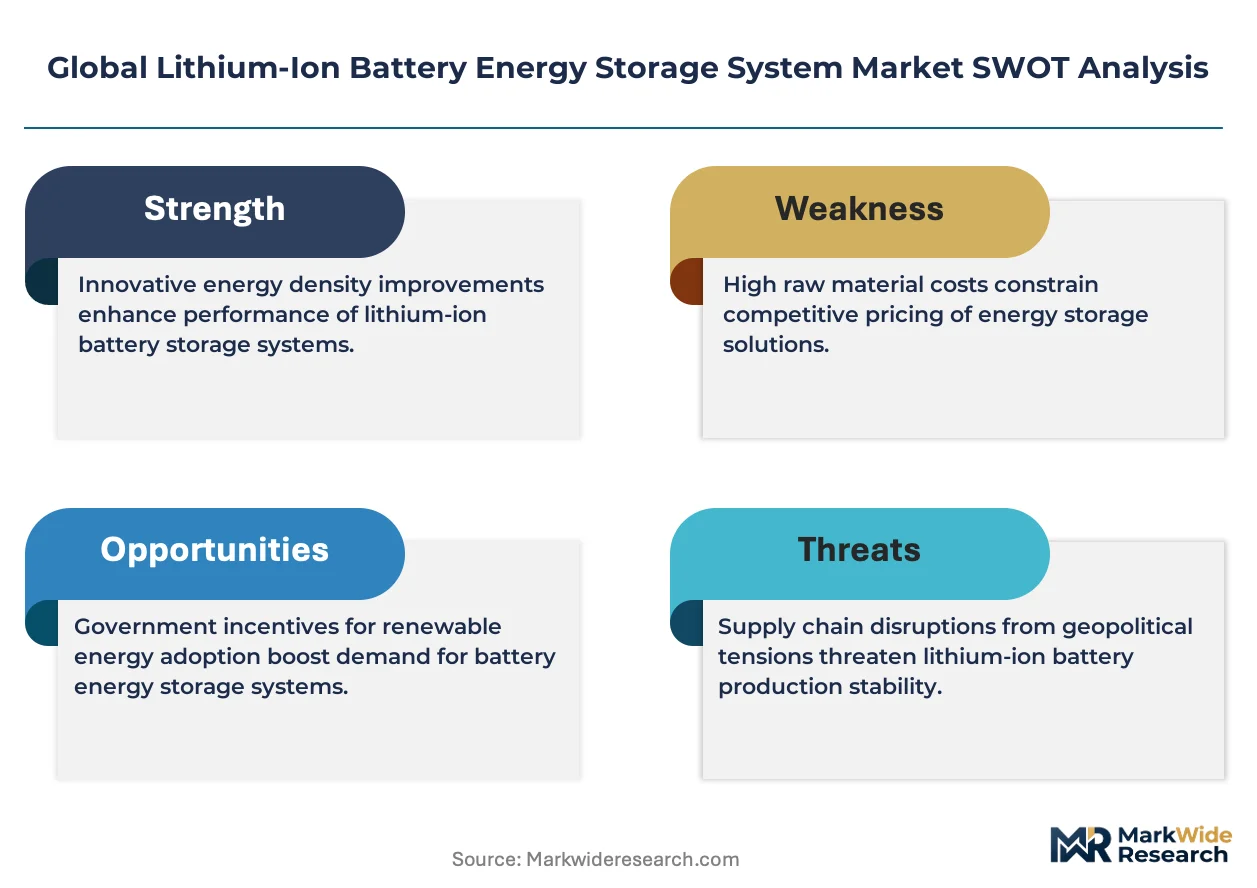
Global Lithium-Ion Battery Energy Storage System Market Analysis
UL 9540A certification for thermal runaway fire propagation is rotating the competitive landscape toward suppliers with in-house testing infrastructure. CATL leverages its integrated cell-to-system manufacturing to control qualification timelines and cost structures. Tesla anchors its position through vertical software-hardware coupling at its Megapack production facilities. Siemens competes on utility-scale project execution across European and Middle Eastern grid operators.
A lithium-ion battery energy storage system comprises electrochemical cells, typically lithium iron phosphate or nickel manganese cobalt oxide chemistry, arranged in modules with battery management systems and power conversion hardware to store and dispatch electrical energy. These systems buffer intermittent renewable generation, stabilize grid frequency, and defer transmission infrastructure investment. Containerized solutions now dominate utility-scale procurement due to factory-integrated quality control and reduced on-site commissioning risk. Rack-mounted units sustain margin pools in commercial and industrial deployment where space constraints and modular expansion requirements favor standardized form factors. Residential segments remain fragmented across regional installer networks with limited brand consolidation.
FERC Order 841 in the United States mandates wholesale market access for storage resources, while the EU Battery Regulation imposes carbon footprint disclosure and recycled content thresholds on cells deployed in European member states. China's GB/T 36276 standard for electrochemical energy storage system technical requirements shapes product design for suppliers targeting domestic grid tenders. Stakeholders must monitor evolving fire codes and circular economy mandates as procurement criteria shift from capital cost per kilowatt-hour toward total lifecycle compliance cost.
Market Dynamics
Containerized factory integration is compressing commissioning timelines and concentrating procurement decisions among buyers with in-house technical qualification teams, reshaping vendor selection criteria toward integrated system architects.
Growth Catalysts
- FERC Order 841:Wholesale market access mandates in the United States unlock revenue stacking for battery storage operators, accelerating utility procurement pipelines.
- India's renewable integration mandates:State electricity boards tender multi-gigawatt storage capacity to firm solar and wind generation, creating sustained demand visibility.
- Lithium iron phosphate chemistry:Thermal stability advantages and supply chain localization are displacing nickel manganese cobalt oxide in utility-scale deployments.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings compress margin predictability for cell manufacturers without captive mining offtake.
- Chinese cell supply concentration:Overreliance on domestic production clusters creates geopolitical exposure and qualification bottlenecks for non-Chinese project developers.
- GB/T 36276 compliance timelines:China's updated grid interconnection standards extend product certification cycles, delaying market entry for new suppliers.
Strategic Opportunities
- Australia's transmission deferral market:Network operators procure storage to avoid remote grid reinforcement, opening merchant revenue streams outside regulated utility channels.
- Second-life automotive batteries:Retired electric vehicle packs are entering stationary applications, creating circular economy value pools for integrators with refurbishment capabilities.
- EU Battery Regulation carbon footprint thresholds:Mandated disclosure requirements favor suppliers with verified low-carbon cell production, creating differentiation for European manufacturing investments.
Industry Challenges
- UL 9540A thermal runaway testing backlog:Limited third-party lab capacity extends certification timelines, constraining product launch velocity for module suppliers.
- Power conversion system integration complexity:Grid-forming inverter capabilities require specialized firmware engineering, creating talent scarcity in control systems development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lithium-Ion Battery Energy Storage System Market |
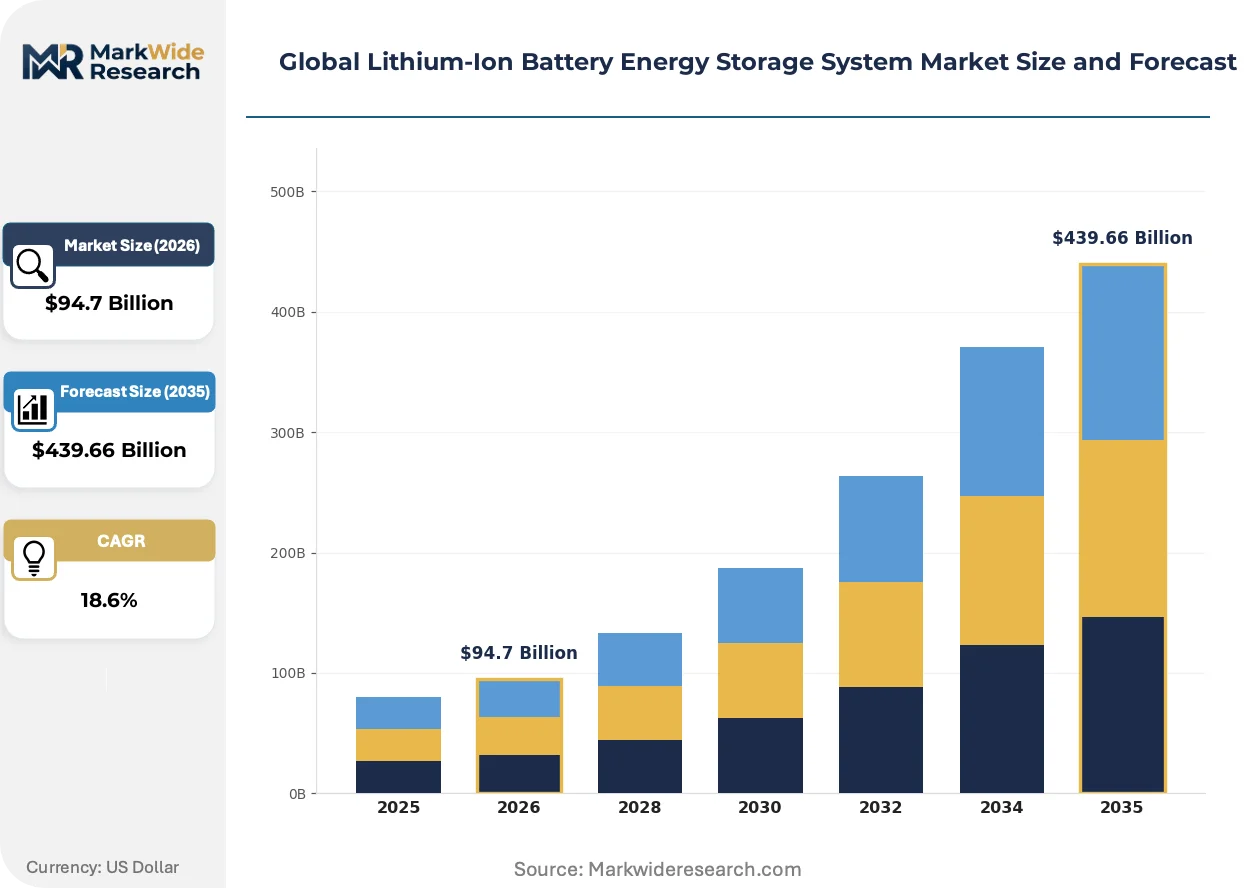
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $439.66 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Battery Systems, Rack-Mounted Units, Containerized Solutions, Stationary Batteries Application: Grid Stabilization, Renewable Integration, Frequency Regulation, Peak Shaving Deployment: Utility-Scale, Commercial & Industrial, Microgrid, Residential End User: Electric Utilities, Telecom Providers, Data Centers, Commercial Enterprises |
| Companies Covered | Siemens, Pylontech, CATL, General Electric, EVE Energy, BYD, LG Energy Solution, Delta Electronics, Tesla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lithium-Ion Battery Energy Storage System Market Emerging Trajectories
Solid-state electrolyte development and software-defined energy management architectures are converging to redefine system performance benchmarks and operational flexibility expectations across utility and commercial segments.
Solid-state battery technology is fragmenting the conventional lithium-ion landscape by replacing flammable liquid electrolytes with ceramic or polymer alternatives. Automotive and stationary storage developers are piloting production lines at limited scale. The technology is fragmenting incumbent supply relationships as cell makers rebuild qualification partnerships around solid-state manufacturing equipment.
The EU Battery Regulation imposes carbon footprint disclosure and recycled content mandates on cells deployed across European member states. Industrial consequence includes mandatory supply chain auditing and lifecycle documentation requirements. Utility-scale project developers in Germany and the Netherlands are restructuring procurement contracts to pass compliance liability upstream to cell suppliers.
Merchant offtake agreements are displacing traditional power purchase contract structures for utility-scale storage assets. Independent power producers and infrastructure funds now underwrite projects based on arbitrage and ancillary service revenue forecasts rather than utility offtake guarantees. This shift concentrates most visibly in Texas and California, where nodal pricing volatility supports merchant economics without regulated cost recovery mechanisms.
Global Lithium-Ion Battery Energy Storage System Market Segmentation
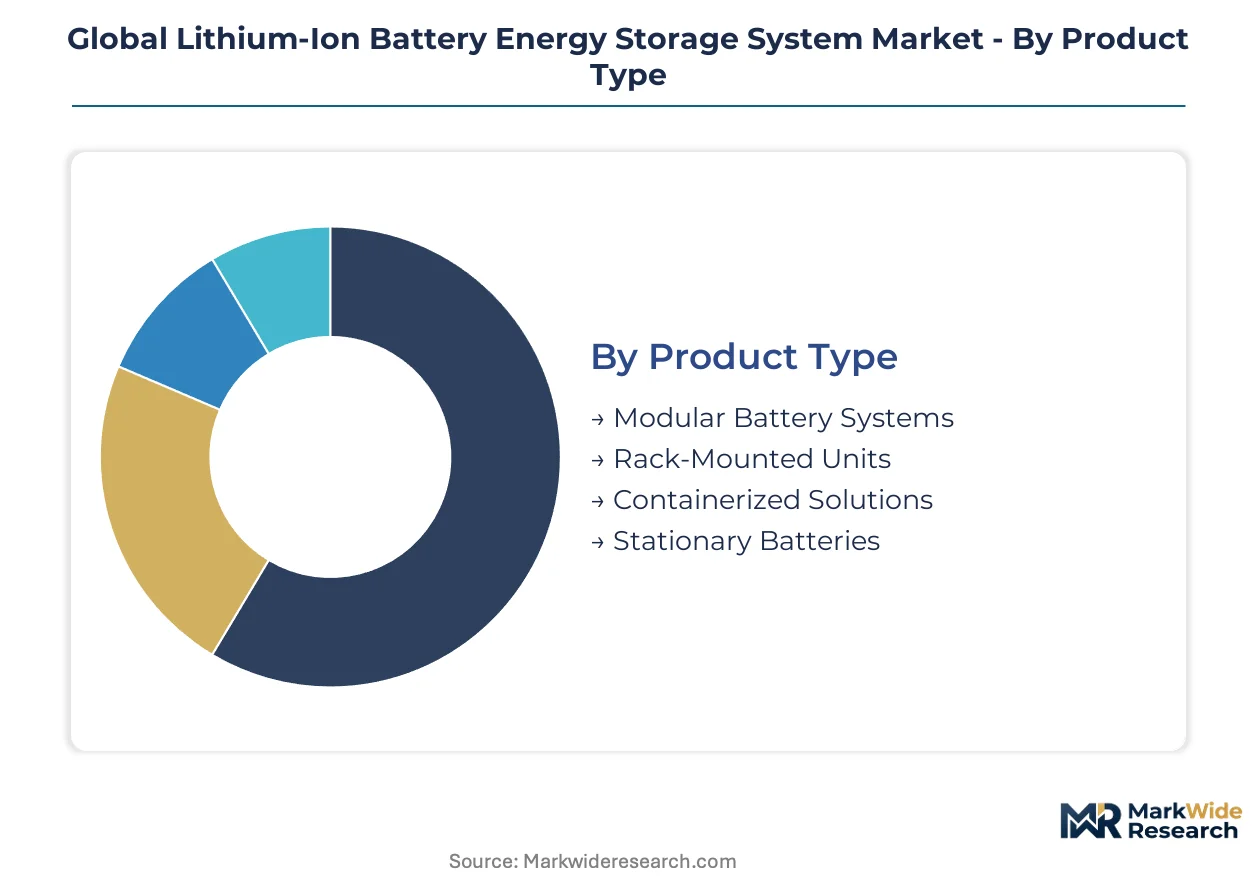
Segmentation in the lithium-ion battery energy storage system market reveals how procurement criteria diverge across deployment scales and application requirements. Product form factors, grid service types, and end-user sophistication levels each command distinct pricing structures and qualification standards.
Product Type:
Margin pools concentrate in factory-integrated formats where quality control and certification bundling justify premium positioning.
- Containerized Solutions:Factory-integrated enclosures arrive pre-tested with battery management systems and thermal management pre-installed. Electric utilities across India and Australia tender these for multi-hundred-megawatt projects where commissioning speed determines project economics.
- Rack-Mounted Units:Standardized 19-inch or proprietary rack formats suit commercial and industrial deployments with space constraints and phased expansion needs. Data centers in Germany and the Netherlands specify these for behind-the-meter peak shaving where modularity outweighs energy density optimization.
- Modular Battery Systems:Skid-mounted or cabinet configurations serve microgrid developers requiring transportable units for remote installations.
- Stationary Batteries:Building-integrated or pad-mounted systems persist in early deployments and retrofit markets with limited standardization.
The dominant share belongs to containerized solutions, while rack-mounted units are closing the gap fastest.
Application:
Revenue visibility varies sharply by application based on regulatory compensation mechanisms and contract duration.
- Renewable Integration:Battery systems buffer solar and wind intermittency through time-shifting and firming services. State electricity boards in India mandate storage co-location for renewable tenders, creating procurement pipelines with decade-long visibility.
- Grid Stabilization:Transmission operators deploy storage for voltage support and congestion management in lieu of infrastructure reinforcement. Australia's network operators procure these assets under merchant structures that capture locational marginal price differentials.
- Frequency Regulation:Fast-responding battery arrays provide primary frequency response to grid operators under performance-based remuneration schemes.
- Peak Shaving:Commercial enterprises and industrial facilities reduce demand charges through battery discharge during tariff peak periods.
Renewable integration commands the largest committed capital, though grid stabilization is expanding most quickly.
Deployment:
Scale economics and customer procurement sophistication stratify margin capture across deployment tiers.
- Utility-Scale:Centralized installations exceeding 10 megawatts dominate capital deployment and manufacturing volume. Procurement concentrates among integrated project developers with in-house engineering teams capable of technical qualification.
- Commercial & Industrial:Behind-the-meter deployments serve manufacturing facilities, logistics centers, and retail chains seeking demand charge reduction. Energy service companies and solar installers compete for these contracts through leasing and power purchase structures.
- Microgrid:Islanded or weak-grid installations combine storage with solar or diesel generation for remote communities, mining operations, and military bases.
- Residential:Single-family and small commercial systems remain fragmented across regional installer networks with limited brand consolidation.
Utility-scale deployments absorb the dominant investment flow, while commercial and industrial segments are gaining share fastest.
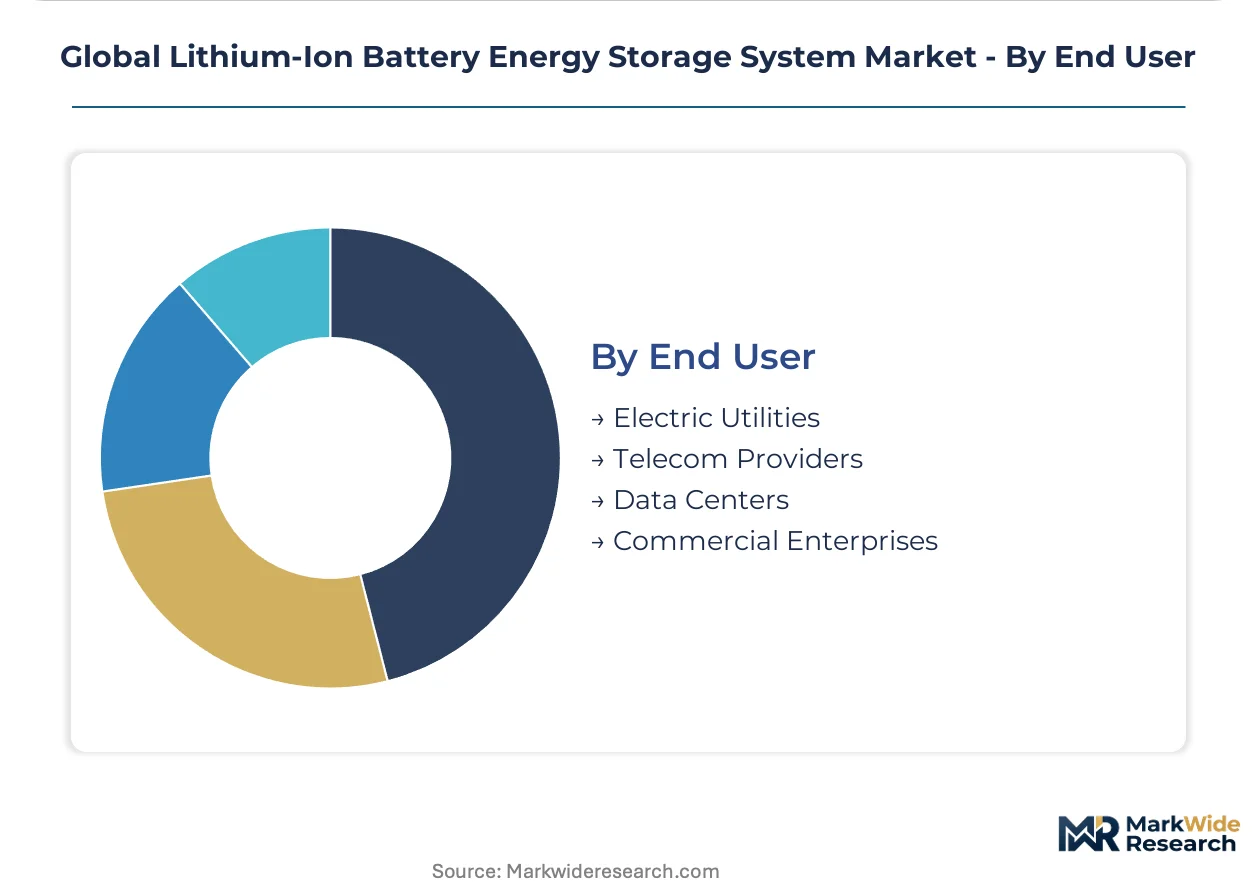
End User:
Technical specification authority and procurement cycle length differ materially across end-user categories.
- Electric Utilities:Vertically integrated and independent power producers tender storage through competitive procurement with detailed technical specifications. FERC Order 841 in the United States and India's renewable purchase obligations mandate storage acquisition with defined performance metrics.
- Data Centers:Hyperscale cloud providers and colocation operators specify storage for backup power and sustainability targets. Carbon footprint disclosure requirements under the EU Battery Regulation reshape supplier qualification for European facilities.
- Telecom Providers:Mobile network operators deploy storage for tower backup power in markets with unreliable grid supply.
- Commercial Enterprises:Manufacturing, retail, and logistics firms procure storage through energy service contracts or direct capital expenditure with payback thresholds.
Electric utilities retain the dominant procurement volume, while data centers are expanding their share most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 841 mandates wholesale market access for storage resources across the United States, accelerating utility procurement pipelines. India's renewable purchase obligations require state electricity boards to tender multi-gigawatt capacity. Germany's network operators procure storage under merchant structures that capture locational marginal price differentials.
United States
Independent power producers underwrite utility-scale projects based on arbitrage and ancillary service revenue forecasts rather than regulated cost recovery. FERC Order 841 unlocks revenue stacking for battery storage operators in Texas and California. Tesla anchors its Megapack production through vertical software-hardware coupling at facilities serving nodal pricing markets.
Germany
Transmission operators deploy storage for voltage support and congestion management in lieu of infrastructure reinforcement. The EU Battery Regulation imposes carbon footprint disclosure and recycled content thresholds on cells deployed across member states. Project developers in the Netherlands and Germany restructure procurement contracts to pass compliance liability upstream to cell suppliers.
China
Dual carbon goals and updated GB/T 36276 grid interconnection standards tighten product qualification requirements for domestic tenders. CATL leverages integrated cell-to-system manufacturing to control certification timelines and cost structures. Manufacturing clusters in Fujian and Guangdong provinces concentrate capacity for suppliers targeting Southeast Asian utility procurement.
India
State electricity boards tender multi-gigawatt storage capacity to firm solar and wind generation under decade-long visibility contracts. The Ministry of Power mandates storage co-location for renewable tenders through updated tariff regulations. Industrial corridors in Gujarat and Tamil Nadu attract containerized solution deployments for manufacturing facility peak shaving.
Australia
Network operators procure storage to avoid remote grid reinforcement, opening merchant revenue streams outside regulated utility channels. The Australian Energy Market Commission reforms dispatch mechanisms to recognize fast frequency response services. Mining operations in Western Australia combine storage with solar generation for diesel displacement in weak-grid installations.
Global Lithium-Ion Battery Energy Storage System Market Vendor Landscape
Player mix skews toward integrated cell-to-system manufacturers and specialized power conversion suppliers. Market structure concentrates procurement decisions among buyers with in-house technical qualification teams capable of navigating evolving fire codes and circular economy mandates. Three strategic archetypes dominate: captive chemistry producers controlling raw material cost structures, factory-integrated system architects compressing commissioning timelines, and software-defined platform operators coupling hardware with energy management algorithms. Capacity expansion and strategic partnerships represent the dominant competitive moves as vendors secure mining offtake and qualification lab access.
Among integrated manufacturing specialists, CATL and BYD exemplify the cell-to-system archetype through captive control over qualification timelines. Tesla occupies a position at the software-hardware coupling vector with its Megapack production architecture. Siemens represents the utility-scale project execution tier across European and Middle Eastern grid operators.
| Leading Market Players |
|---|
| Siemens |
| Pylontech |
| CATL |
| General Electric |
| EVE Energy |
| BYD |
| LG Energy Solution |
| Delta Electronics |
| Tesla |
| Others |
Supply Flow & Price Mechanics
Gigawatt-scale manufacturing utilization in Chinese cell production clusters compresses unit economics while anchoring global price floors for containerized storage systems. This concentration simultaneously tightens qualification timelines for non-captive suppliers and amplifies procurement leverage among utilities with technical vetting capabilities in India, Australia, and Germany.
Pricing Analysis
UL 9540A certification tier creates the primary spread between premium containerized solutions and standard rack-mounted units, with factory-integrated thermal management bundling commanding 15-25% markups. Three-tier pricing structure across certified-premium, standard-compliant, and economy-modular levels stratifies procurement pools, though lithium carbonate volatility is compressing margins for cell manufacturers without captive mining offtake. Price erosion runs through the residential segment where regional installer fragmentation intensifies competition, while utility-scale buyers with in-house engineering teams exhibit lowest sensitivity due to lifecycle cost optimization frameworks.
Supply Chain Analysis
Inventory buffers at 90-120 days for power conversion systems and 60-75 days for lithium iron phosphate cells reflect procurement lead-time compression as containerized factory integration accelerates. Cell production concentrates in China, South Korea, and Japan, with cathode active material supply drawing from Indonesian nickel and Chilean lithium processing. Single-source vulnerability around Chinese BMS firmware and power electronics creates geopolitical exposure for Western project developers. Distribution runs through integrated EPC contractors and direct utility procurement channels with factory-to-site logistics coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Merchant revenue stacking and circular economy mandates are fragmenting procurement criteria, creating specialized niches for second-life battery integrators and carbon-verified cell suppliers alongside incumbent volume manufacturers.
For Market Incumbents: Fortify qualification infrastructure by securing captive UL 9540A testing capacity and backward integration into cathode material refining. CATL's cell-to-system architecture demonstrates how controlling certification timelines defends margin pools against emerging challengers facing 12-18 month compliance backlogs. Capacity addition in European manufacturing clusters addresses EU Battery Regulation carbon footprint thresholds while reducing tariff exposure. For New Entrants and Emerging Players: Software-defined energy management gaps in legacy hardware architectures offer entry points for control-system specialists with grid-forming inverter firmware capabilities. Australia's transmission deferral market and India's state-level tender fragmentation present the most penetrable procurement channels outside concentrated utility-scale auctions. Go-to-market positioning should emphasize merchant revenue optimization algorithms rather than capital cost competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among energy service companies with long-term O&M contracts and software platform subscriptions. Long-term viability over the next decade hinges on circular economy infrastructure for battery refurbishment and recycling. Acquisition targets should display verified low-carbon supply chains and qualification lab partnerships. The signal to watch is FERC Order 841 implementation pace across additional US grid regions as merchant market depth indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Captive nickel and lithium processing insulates margin structures from raw material volatility in Chinese spot markets. |
| UL 9540A Certification Infrastructure Buildout | In-house thermal runaway testing accelerates product launch velocity while third-party lab queues extend to 18 months. |
| Second-Life Battery Refurbishment Capability | Automotive pack repurposing creates circular economy revenue streams under EU Battery Regulation recycled content mandates. |
| Grid-Forming Inverter Firmware Development | Specialized control algorithms for weak-grid applications command talent scarcity premiums in Australian and Southeast Asian tenders. |
| European Manufacturing Footprint Expansion | Localized cell production satisfies carbon footprint disclosure requirements for German and Dutch utility procurement. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across India, Germany, Australia, and the United States; and secondary validation through FERC filings, IEA reports, EIA capacity databases, and project development registries. Bottom-up unit economics modeling triangulated against top-down market sizing from regulatory mandate quantification and tender pipeline aggregation.
Across the projection horizon, the analytical framework modeled volume and value outputs by product form factor, application service type, deployment scale tier, and regional regulatory cluster. CAGRs were derived from segment-level growth rate blending anchored to renewable integration timelines and storage procurement mandates. Key forecast inputs included lithium carbonate price trajectory assumptions and GB/T 36276 compliance timeline elasticity for market entry velocity.
Forecasts assume regulatory continuity in FERC Order 841 implementation, EU Battery Regulation enforcement, and India's renewable purchase obligation frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
Aluminium Ion Battery Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Silicon Anode Battery Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market
Lithium-ion Battery
Lithium-Ion Battery Materials Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market