
 Germany SLI Battery Market | 2026-2036
Germany SLI Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Germany SLI Battery Market Insights
The EU Battery Regulation is decoupling legacy cost structures from viable market participation by mandating recycled content quotas and supply chain due diligence. Clarios leverages its European recycling infrastructure to preempt compliance burdens. Varta AG sustains domestic manufacturing scale across its Ellwangen and Dischingen facilities. Hoppecke Batteries GmbH & Co. KG specializes in industrial-grade SLI derivatives for commercial vehicle fleets.
Starting, lighting, and ignition (SLI) batteries deliver short-duration high-current bursts to crank internal combustion engines and stabilize vehicle electrical loads, typically employing lead-acid chemistry with pasted flat-plate or tubular positive electrodes and sulfuric acid electrolyte. The automotive application segment dominates volume as passenger car parc renewal and mild-hybridization sustain replacement cycles. AGM product types capture expanding share within premium OEM fitments and stop-start systems where vibration resistance and cyclic durability command price premiums. Low-capacity and medium-capacity tiers anchor aftermarket demand for compact and mid-size vehicle classes.
KBA type-approval requirements and Germany's Battery Act shape product standards by enforcing collection targets and prohibiting certain hazardous substances in new units. REACH compliance and ECHA substance restrictions further constrain material sourcing for domestic assemblers. Stakeholders must monitor evolving EU Battery Regulation delegated acts on performance and durability criteria, as these will determine which chemistries and formats retain market access without costly redesign cycles.
Market Dynamics
Germany's SLI battery sector is contending with the EU Battery Regulation's mandatory recycled content quotas, which are forcing domestic assemblers to reconfigure supply chains and secure certified lead recovery streams before the 2030 compliance deadlines.
Growth Catalysts
- EU Green Deal decarbonization mandates:Fleet operators in Baden-Württemberg face binding carbon disclosure requirements that accelerate replacement of conventional flooded batteries with lower-emission AGM designs.
- Stop-start system proliferation:Mild-hybrid powertrains in premium passenger vehicles demand enhanced cyclic durability, expanding the addressable market for absorbed glass mat technology.
- KBA type-approval stringency:Germany's Federal Motor Transport Authority enforces rigorous vibration and cold-cranking performance standards that disqualify inferior imports and protect domestic manufacturing share.
Market Restraints
- Lead price volatility:Primary lead smelter concentration in China and Australia exposes German battery assemblers to input cost swings that compress margin visibility across quarterly procurement cycles.
- Lithium-ion substitution in adjacent segments:Deep-cycle and auxiliary power applications in commercial vehicles are migrating to lithium iron phosphate chemistry, narrowing the residual growth perimeter for lead-acid SLI derivatives.
- ECHA substance restrictions:REACH candidate list expansions for cadmium and certain stabilizer compounds constrain formulation flexibility and force costly material qualification programs.
Strategic Opportunities
- Bavaria industrial cluster densification:Supplier network proximity to Munich and Ingolstadt OEM assembly plants enables just-in-sequence battery delivery contracts with compressed logistics costs.
- EU Battery Regulation remanufacturing provisions:Delegated acts on second-life criteria create a regulatory pathway for refurbished SLI units in non-automotive standby power applications.
- Digital battery management convergence:Integration of IoT-enabled state-of-health monitoring with traditional SLI hardware opens recurring revenue streams through predictive replacement services.
Industry Challenges
- Skilled electrochemist scarcity:German technical universities produce insufficient lead-acid battery specialists to staff expanding R&D facilities in Ellwangen and Dischingen.
- Recycling infrastructure capex intensity:Compliance with the Battery Act's collection and recovery targets requires substantial investment in automated dismantling lines and closed-loop acid neutralization systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany SLI Battery Market |
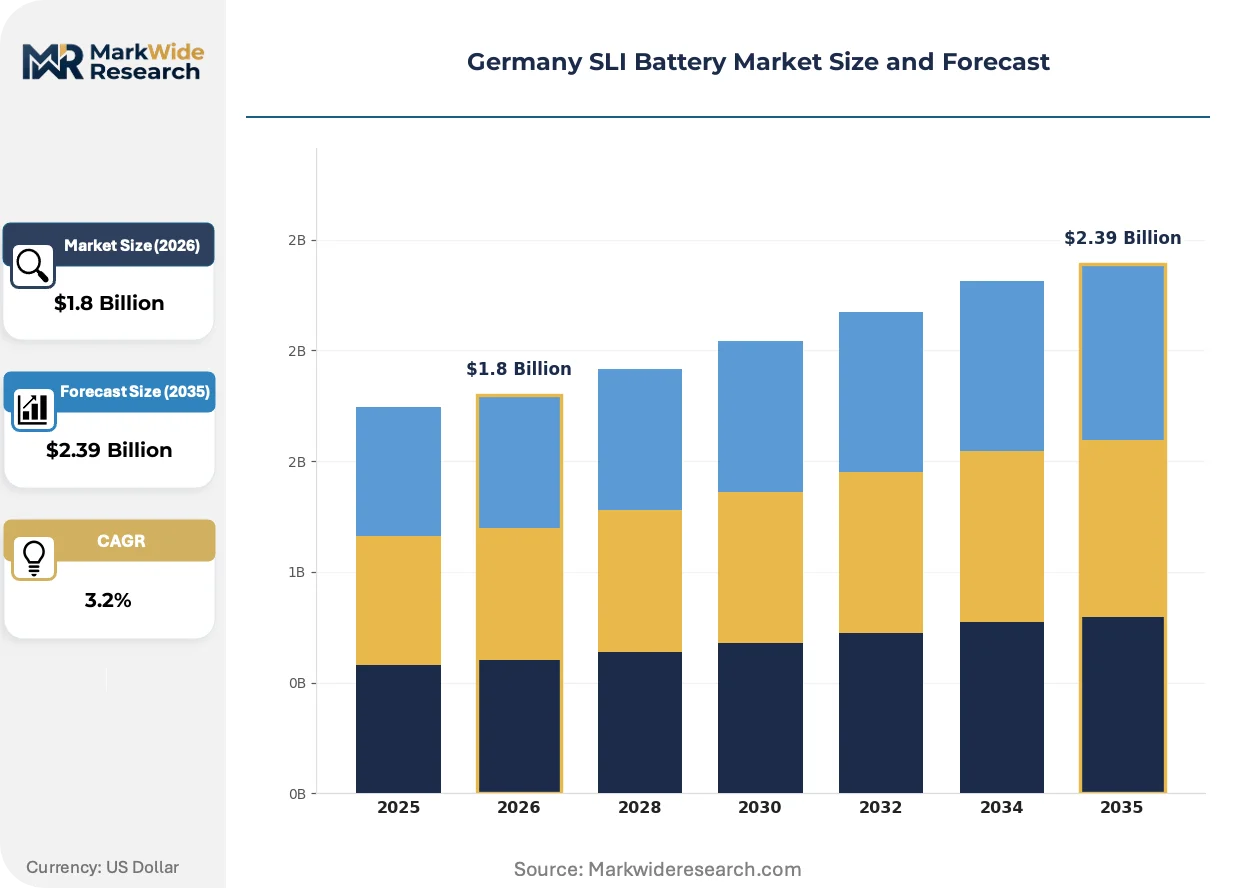
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, AGM, Gel Application: Automotive, Commercial, Marine, Construction Capacity: Low-Capacity, Medium-Capacity, High-Capacity, Ultra-High-Capacity Installation: OEM, Aftermarket, DIY, Professional |
| Companies Covered | Clarios, Exide Technologies, Varta AG, EnerSys, East Penn Manufacturing Co., Hoppecke Batteries GmbH & Co. KG, GS Yuasa Corporation, FIAMM Energy Technology, Banner GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany SLI Battery Market Trends and Innovations
Active materials engineering and regulatory compliance automation are converging to redefine competitive advantage in German SLI manufacturing, compressing product development cycles while elevating sustainability verification requirements.
Carbon-enhanced negative electrode formulations are unifying the performance gap between standard flooded and premium AGM constructions. Tier-one suppliers serving Munich-based OEMs have accelerated adoption of these hybrid paste recipes. The technology is unifying mid-tier pricing segments by delivering stop-start compatibility without full AGM cost structures.
Germany's Battery Act amendments are tightening producer responsibility frameworks for collection and recycling logistics. Domestic manufacturers must now finance reverse supply chain infrastructure proportionate to market share. Premium OEM fitment suppliers face the steepest compliance cost escalation as they manage complex aftermarket battery return streams.
Fleet procurement departments are consolidating supplier relationships around single-source agreements with integrated recycling provisions. Independent distributors in North Rhine-Westphalia are losing share to direct manufacturer contracts with large logistics operators. This concentration pattern is most pronounced among parcel delivery fleets operating under Scope 3 emissions reporting obligations.
Germany SLI Battery Market Segmentation
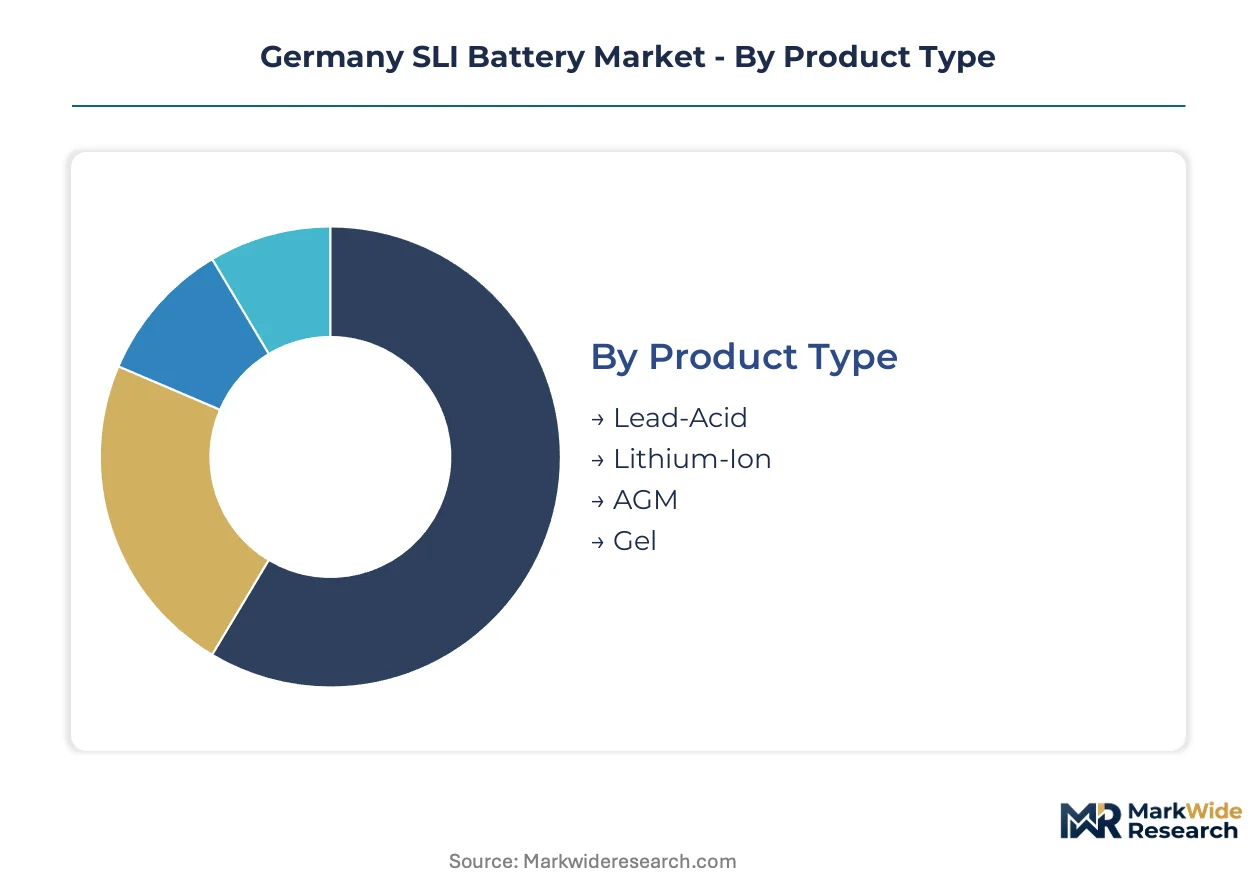
German SLI battery procurement splits across chemistry, use case, and installation channel, with each dimension carrying distinct margin profiles and compliance obligations under the Battery Act. Fleet operators and OEMs prioritize different performance tiers, creating parallel demand tracks that suppliers must serve through segmented product lines.
Product Type:
Integration depth varies sharply: flooded lead-acid and AGM dominate standalone automotive replacement cycles, while lithium-ion remains embedded in mild-hybrid architectures as a supplementary power source rather than primary SLI function.
- Lead-Acid:Flooded flat-plate construction with pasted positive electrodes and sulfuric acid electrolyte remains the baseline for passenger vehicle starting applications. Demand concentrates in North Rhine-Westphalia independent aftermarket channels where price-sensitive fleet operators prioritize unit cost over cyclic durability.
- AGM:Absorbed glass mat separators immobilize electrolyte to enable vibration resistance and deep-cycling capability for stop-start systems. Bavarian premium OEM fitments drive procurement volumes as Munich-based assemblers specify enhanced durability for mild-hybrid powertrains.
- Lithium-Ion:Lithium iron phosphate chemistry delivers weight reduction and charge acceptance advantages in hybrid auxiliary applications.
- Gel:Thixotropic silica additives create maintenance-free constructions for marine and off-road vibration environments.
Lead-acid leads volumes today; AGM is gaining share fastest.
Application:
Cost tier stratification separates premium OEM fitments from aftermarket replacement cycles, with commercial fleets occupying a mid-tier band defined by total-cost-of-ownership calculations rather than upfront unit economics.
- Automotive:Passenger car starting, lighting, and ignition functions dominate unit demand across Baden-Württemberg and Bavaria manufacturing clusters. KBA type-approval requirements enforce cold-cranking amperage and reserve capacity minimums that protect domestic supplier share against inferior imports.
- Commercial:Heavy-duty truck and bus applications require enhanced cyclic durability for hotel loads and auxiliary systems. Fleet procurement departments in Hesse logistics hubs consolidate supplier relationships around single-source agreements with integrated recycling provisions under Scope 3 reporting obligations.
- Marine:Deep-cycle derivatives serve trolling motor and house bank functions in recreational boating segments.
- Construction:Equipment starting applications demand vibration-resistant constructions for excavator and loader fleets.
Automotive anchors revenue concentration; commercial is expanding most quickly.
Capacity:
Volume distribution tracks vehicle parc composition, with compact and mid-size classes sustaining replacement density while premium electrification shifts capacity requirements upward.
- Low-Capacity:Sub-45 Ah constructions serve compact passenger vehicles and urban delivery vans. Urban aftermarket channels in Berlin and Hamburg sustain steady replacement pull for aging city car fleets.
- Medium-Capacity:45-70 Ah range addresses mid-size sedans and crossover utility vehicles. Bavarian OEM assembly plants specify these tiers for volume production lines serving domestic and export markets.
- High-Capacity:70-100 Ah units support premium SUVs and light commercial vehicles with elevated electrical loads.
- Ultra-High-Capacity:Exceeding 100 Ah for heavy-duty commercial and specialized applications.
Medium-capacity leads volumes today; high-capacity is climbing the fastest.
Installation:
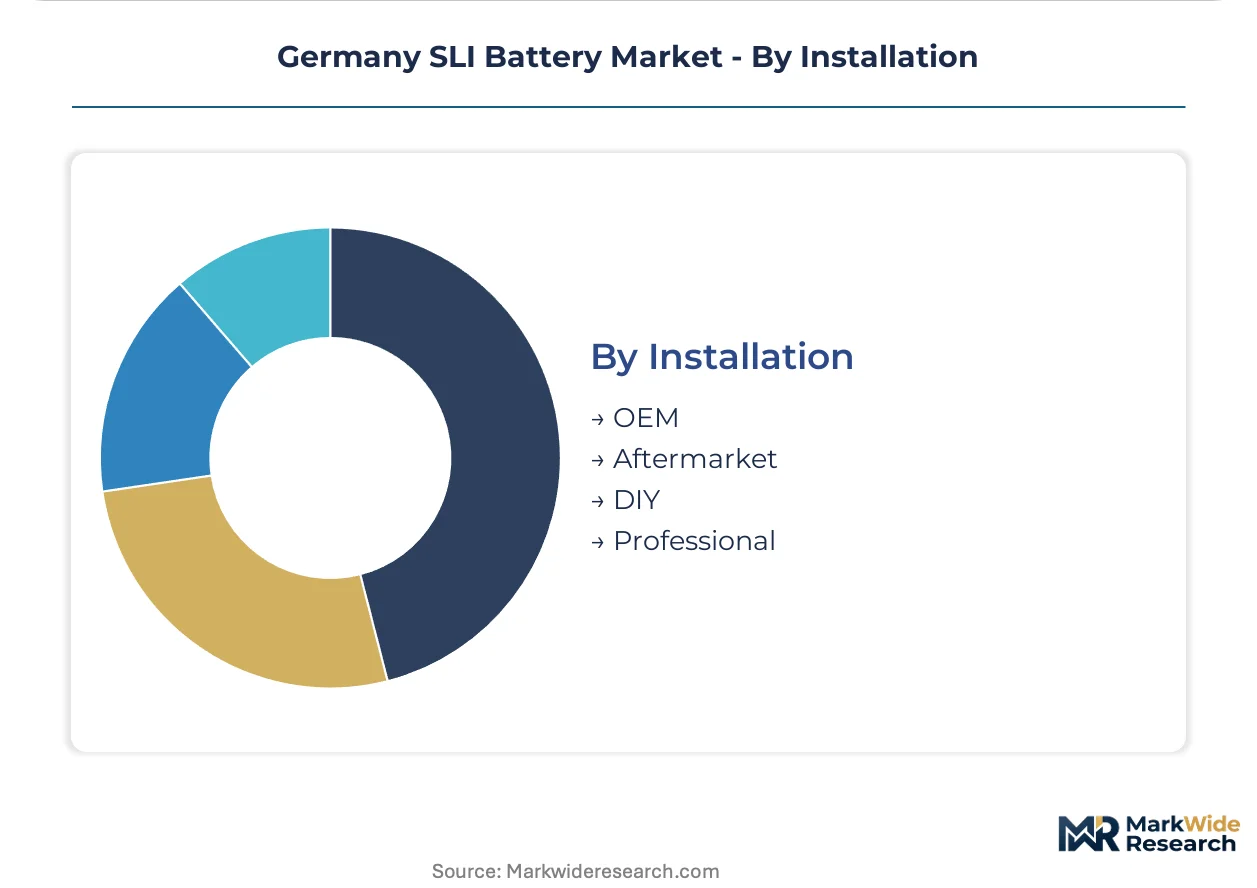
Customer type fragmentation separates professional channel discipline from price-driven DIY procurement, with OEM fitments commanding premium positioning through specification control.
- OEM:Factory-fit installations at Ingolstadt and Stuttgart assembly plants require just-in-sequence delivery and zero-defect quality protocols. Direct manufacturer contracts with premium vehicle assemblers capture margin through specification lock-in and warranty bundling.
- Aftermarket:Replacement sales through branded distributor networks serve independent repair shops and fleet maintenance facilities. Professional installation channels in Baden-Württemberg dominate as battery registration and disposal documentation requirements deter casual procurement.
- DIY:Retail counter sales to consumer installers face regulatory friction from Battery Act collection obligations.
- Professional:Certified technician installation with diagnostic verification and warranty registration.
Aftermarket leads volumes today; OEM is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled electrochemists and battery engineers concentrate in southwestern Germany, anchoring the country's lead-acid research and manufacturing capabilities. This talent density supports specialized production facilities and compliance expertise for EU regulatory frameworks. Regional procurement patterns reflect proximity to automotive assembly clusters and aftermarket distribution networks.
Baden-Württemberg
Premium vehicle manufacturing at Stuttgart and Neckarsulm drives OEM fitment demand for AGM and enhanced flooded batteries. The KBA enforces type-approval standards that protect domestic suppliers against inferior imports. Supplier networks around Ellwangen sustain just-in-sequence delivery contracts with assembly plants.
Bavaria
Munich-based luxury automakers specify high-capacity AGM units for mild-hybrid powertrains with stop-start functionality. EU Green Deal carbon disclosure requirements accelerate fleet replacement cycles among logistics operators. Ingolstadt assembly corridors anchor procurement volumes for volume-production battery tiers.
North Rhine-Westphalia
Independent aftermarket channels serve price-sensitive fleet operators prioritizing unit cost over cyclic durability. The Battery Act mandates producer-financed collection infrastructure that disadvantages smaller distributors. Cologne-Düsseldorf logistics hubs consolidate supplier relationships around single-source agreements with integrated recycling provisions.
Hesse
Commercial vehicle fleet procurement departments calculate total-cost-of-ownership metrics favoring enhanced durability specifications. REACH compliance and ECHA substance restrictions constrain formulation flexibility for regional assemblers. Frankfurt-Rhine-Main distribution centers manage battery return streams under Scope 3 emissions reporting obligations.
Lower Saxony
Heavy-duty truck and bus applications require deep-cycling capability for hotel loads and auxiliary electrical systems. Germany's Battery Act tightens producer responsibility frameworks proportionate to market share. Wolfsburg automotive corridors sustain replacement pull for aging commercial vehicle parc renewal.
Germany SLI Battery Market Competitive Landscape
The competitive structure tilts toward integrated manufacturers with captive recycling infrastructure. Three tiers define participation: multinational suppliers with European closed-loop lead recovery, domestic specialists serving premium OEM fitments, and regional distributors consolidating around fleet service contracts. Capacity alignment and compliance automation represent the dominant competitive moves as assemblers reconfigure supply chains for 2030 recycled content deadlines.
Within the integrated multinational tier, Clarios leverages its European recycling footprint to preempt regulatory compliance burdens. Varta AG and Hoppecke Batteries GmbH & Co. KG occupy positions anchoring domestic manufacturing scale across southwestern production facilities. These three exemplify divergent strategic postures: Clarios represents recycling-integrated global supply, Varta AG exemplifies premium OEM specification control, and Hoppecke Batteries GmbH & Co. KG anchors industrial-grade specialization for commercial vehicle applications.
| Leading Market Players |
|---|
| Clarios |
| Exide Technologies |
| Varta AG |
| EnerSys |
| East Penn Manufacturing Co. |
| Hoppecke Batteries GmbH & Co. KG |
| GS Yuasa Corporation |
| FIAMM Energy Technology |
| Banner GmbH |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange lead futures volatility cascades through German SLI battery manufacturing tiers, compressing margins in flooded lead-acid segments while insulating AGM suppliers through premium pricing power anchored to stop-start system specifications. Input cost swings from Chinese and Australian smelter concentration force assemblers to renegotiate quarterly procurement contracts with tier-one distributors in North Rhine-Westphalia, fragmenting pricing discipline across aftermarket channels.
Pricing Analysis
Bundled recycling services versus unbundled unit sales split the German SLI battery market into divergent pricing architectures. OEM fitment contracts incorporate reverse logistics and Battery Act compliance costs, commanding premium positioning over aftermarket transactions where independent distributors compete on stripped-down unit economics. Price differentiation separates AGM constructions with KBA type-approval certification from economy flooded alternatives sourced through spot-market lead. Cost compression in standard flooded tiers intensifies as Chinese imports pressure domestic assemblers, while fleet procurement departments in Hesse demonstrate lowest price sensitivity due to total-cost-of-ownership frameworks.
Supply Chain Analysis
Skilled electrochemist availability constrains production scaling in Ellwangen and Dischingen manufacturing corridors, tethering capacity expansion to technical university pipeline output. Primary lead supply concentrates in China, Australia, and South Korea, exposing German assemblers to maritime logistics chokepoints through Rotterdam and Hamburg port complexes. Sulfuric acid electrolyte and polypropylene casing materials draw from regional chemical clusters in Ludwigshafen and Antwerp. Single-source vulnerability in lead concentrate smelting elevates procurement risk. Distribution runs through captive OEM just-in-sequence contracts and branded aftermarket networks serving Baden-Württemberg repair facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German SLI battery manufacturing operates as a geographic-arbitrage play between EU regulatory compliance costs and Eastern European production alternatives, with Battery Act collection obligations creating a cost wedge that favors domestic integrated recyclers over import-dependent distributors.
For Market Incumbents: Anticipate lithium-ion substitution in commercial vehicle auxiliary applications by accelerating carbon-enhanced negative electrode R&D at southwestern facilities. Secure captive lead recovery streams through backward integration into automated dismantling infrastructure before EU Battery Regulation recycled content mandates tighten. Defend OEM fitment share through specification lock-in with Munich-based luxury automakers.
For New Entrants and Emerging Players: Independent marine and off-road equipment operators represent an underserved buyer archetype with tolerance for gel battery premiums and limited price transparency. Target construction equipment fleets in Lower Saxony with vibration-resistant constructions absent from mainstream distributor catalogs. Enter through direct fleet service contracts bypassing consolidated North Rhine-Westphalia wholesale channels.
For Investors and Strategic Acquirers: Asymmetric upside sits with recycling-integrated mid-cap specialists possessing Battery Act-compliant collection infrastructure and established OEM relationships. Long-term viability hinges on chemistry diversification capability across the next decade. Monitor EU Battery Regulation delegated acts on second-life criteria as the inflection signal for refurbished unit market formation.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Infrastructure Expansion | Clarios leverages European lead recovery footprint to preempt EU Battery Regulation compliance burdens. |
| AGM Capacity Buildout | Varta AG scales Ellwangen production to capture Munich OEM stop-start system specifications. |
| Digital Battery Management Integration | IoT-enabled state-of-health monitoring opens predictive replacement revenue streams with fleet operators. |
| Carbon-Enhanced Formulation Adoption | Tier-one suppliers accelerate hybrid paste recipes unifying flooded-AGM performance gaps. |
| Fleet Single-Source Consolidation | Direct manufacturer contracts displace independent distributors under Scope 3 reporting obligations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM procurement managers, aftermarket distributor operators, fleet maintenance directors, and recycling facility engineers alongside secondary validation. KBA type-approval databases, EU Battery Regulation delegated act drafts, customs trade records for lead concentrate imports, and automotive production statistics from Stuttgart and Munich assembly corridors anchored the data foundation. Bottom-up unit shipment estimates triangulated against top-down value reconstructions.
Historical reference periods spanning vehicle parc renewal cycles and lead price commodity waves anchored the projection horizon. Segmentation dimensions modeled include chemistry type, application tier, capacity band, and installation channel across the analysis window. CAGRs derived from trend extrapolation of replacement cycle frequency and mild-hybrid penetration curves. Forecast inputs incorporated EU Green Deal carbon disclosure enforcement timelines and ECHA substance restriction candidate list expansions.
Underlying measurement precision varies by segment; OEM fitment volumes carry tighter precision than fragmented DIY aftermarket transactions due to registration documentation requirements. Forecasts reflect assumptions around regulatory enforcement consistency and lead smelter supply concentration. Material deviation in EU Battery Regulation implementation timelines or Chinese environmental policy enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Global Pin Type Lithium-Based Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Cobalt Oxide Market
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Lithium Cobalt Oxide Battery (LCO) Market
Lithium-ion Battery
Lithium Battery in Myanmar Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
Ultra Low Temperature Lithium Battery Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Lithium Solid-State Battery Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market