
 Cylindrical Lithium-Ion Battery Market | 2026-2036
Cylindrical Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Cylindrical Lithium-Ion Battery Market Intelligence
South Korean cell producers is realigning cylindrical capacity toward high-nickel chemistries for automotive contracts. Panasonic Corporation leverages its Nevada partnership with Tesla to sustain North American supply continuity. LG Energy Solution anchors its cylindrical portfolio through Michigan-based output, while Samsung SDI competes in European power tool segments with specialized 18650 and 21700 lines.
Cylindrical lithium-ion batteries are rechargeable electrochemical cells manufactured in standardized tubular formats, typically featuring spirally wound electrode assemblies with aluminum or copper current collectors and organic electrolyte systems; their primary purpose is to deliver high-rate discharge capability in mechanically robust enclosures. The 21700 product type is displacing legacy 18650 cells in electric bicycle and power tool packs due to superior energy density per cell. Lithium iron phosphate technology dominates medical device and stationary applications where cycle life and thermal stability outweigh gravimetric energy targets. Consumer electronics manufacturers represent the most mature end user industry, while aviation sector demand for certified cylindrical packs remains nascent but structurally high-margin.
China's SAMR enforces GB/T standards for cell safety and labeling, while the EU Battery Regulation mandates recycled content thresholds and digital passports for industrial and electric vehicle batteries placed on the European market. The US FAA and DOT impose separate hazmat shipping and air cargo restrictions that fragment cross-border logistics for cylindrical cells. Stakeholders must monitor how divergent carbon accounting rules between Beijing, Brussels, and Washington reshape sourcing decisions and qualification timelines for new cell platforms.
Market Dynamics
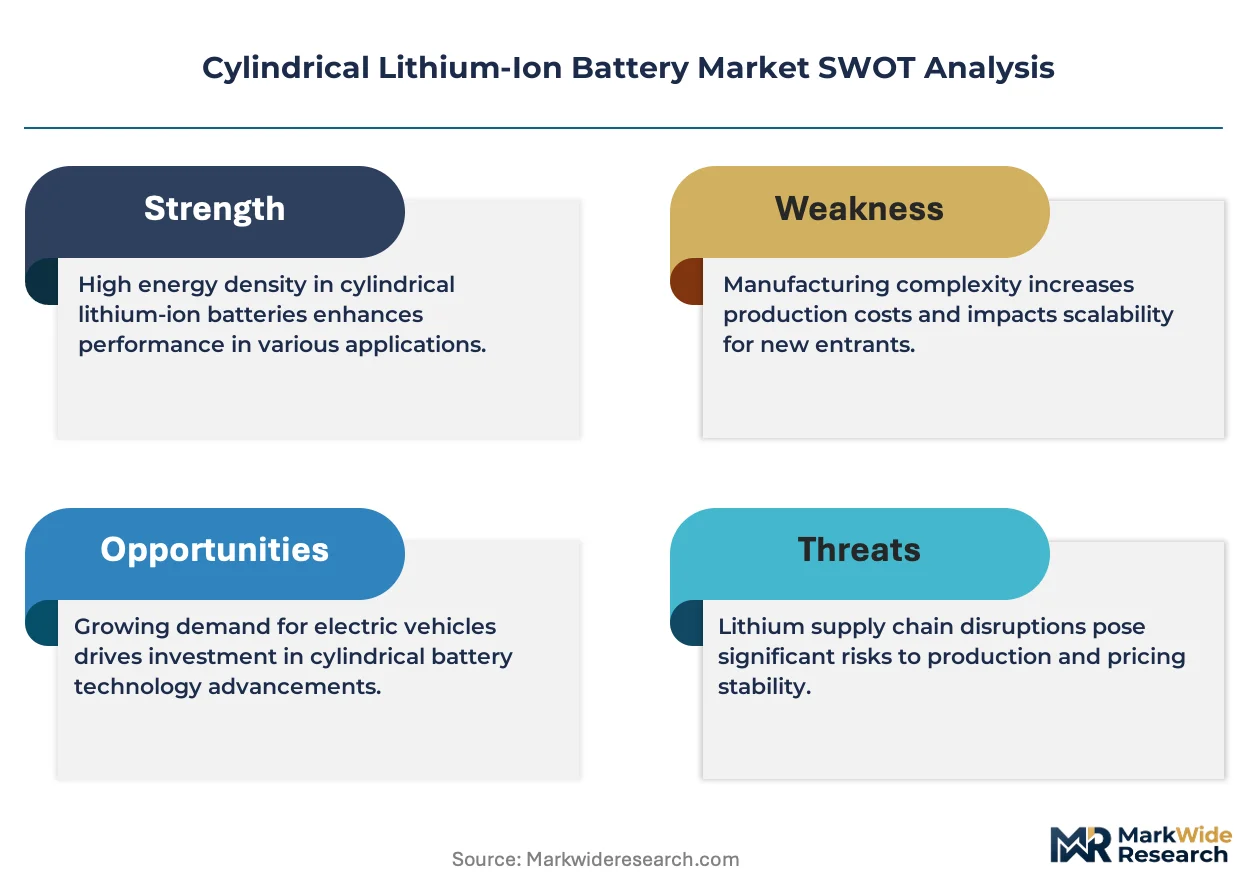
Automotive OEMs are consolidating cylindrical cell procurement around large-format 21700 and 4680 platforms, compressing qualification timelines and forcing chemistry standardization across tiered supplier bases. This demand concentration is reshaping capacity allocation decisions at cell producers worldwide.
Growth Catalysts
- EU Battery Regulation:Mandatory recycled content thresholds and digital passports are accelerating investment in closed-loop material recovery infrastructure for industrial and electric vehicle cells placed on the European market.
- Aviation electrification:Certified cylindrical packs for electric vertical take-off aircraft are opening structurally high-margin demand segments with stringent thermal runaway containment requirements.
- South Korean production clusters:Concentrated cathode active material and cell manufacturing around Ulsan and Gwangju are shortening logistics lead times for nickel-rich chemistry platforms.
Market Restraints
- Cobalt and nickel price volatility:Cathode material cost swings compress cell producer margins and complicate long-term contract pricing with automotive OEMs.
- Supply concentration in East Asia:Separator and electrolyte additive production remains concentrated in China and South Korea, creating single-source vulnerability for non-integrated cell manufacturers.
- Gravimetric energy ceiling:Silicon anode integration faces cycle stability limitations that constrain energy density gains in cylindrical formats versus prismatic alternatives.
Strategic Opportunities
- US Inflation Reduction Act:Domestic content credits are incentivizing North American cell and component manufacturing investments that qualify for consumer EV tax credits.
- Stationary energy storage:Lithium iron phosphate cylindrical cells are penetrating residential and commercial backup power applications where cycle life outweighs pack-level energy density.
- Power tool cordless transition:Professional-grade equipment manufacturers are replacing nickel-cadmium and nickel-metal hydride platforms with 18650 and 21700 lithium-ion systems.
Industry Challenges
- Dry electrode process engineering:Scaling solvent-free coating technology for high-nickel cathodes requires specialized equipment and process control expertise that remains scarce.
- UN 38.3 certification timelines:Extended testing protocols for air transport compliance delay new cell platform launches and fragment logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cylindrical Lithium-Ion Battery Market |
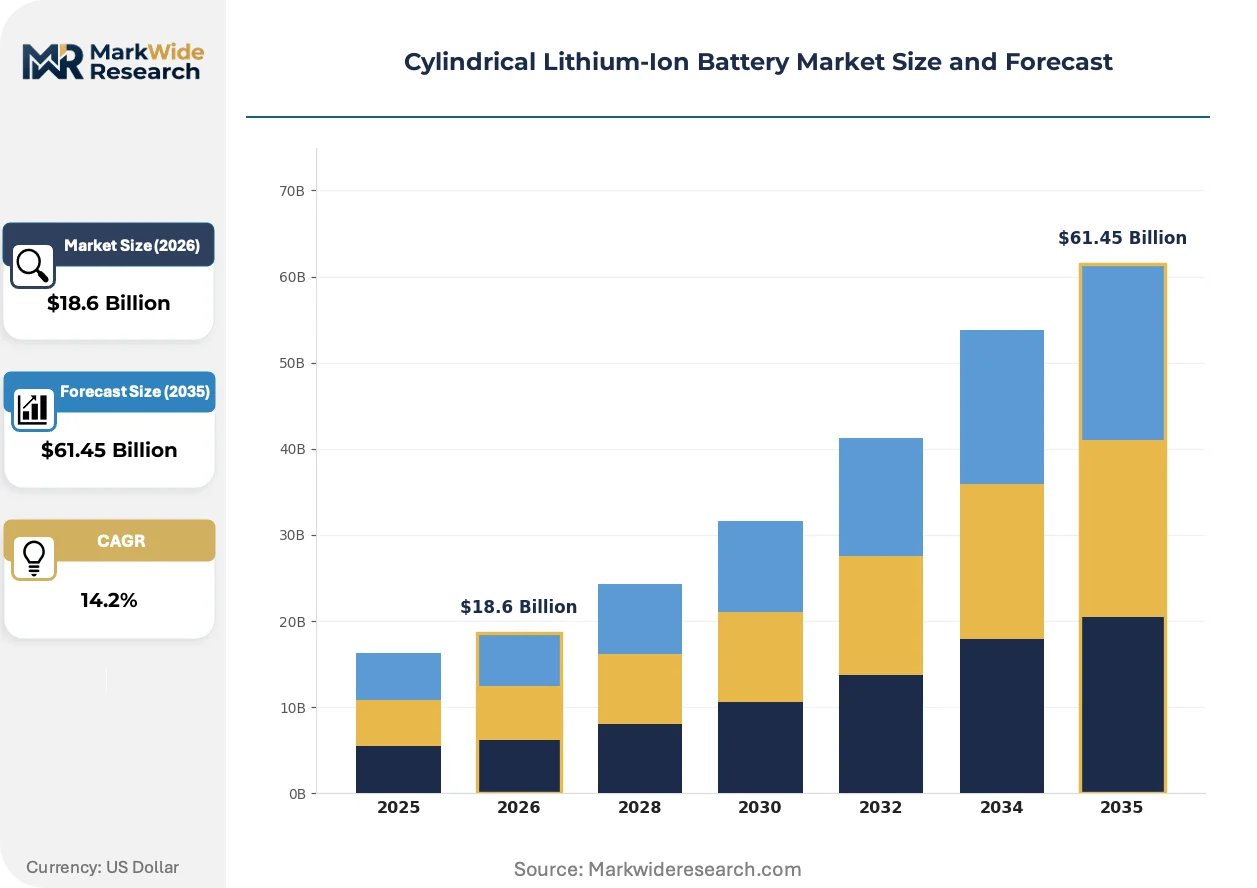
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $61.45 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 18650, 21700, 14500, 26650, 32650 Technology: Lithium Nickel Manganese Cobalt Oxide, Lithium Iron Phosphate, Lithium Cobalt Oxide, Lithium Manganese Oxide Application: Power Tools, Electric Bicycles, Medical Devices, Aerospace, Consumer Electronics End User Industry: Consumer Electronics Manufacturers, Tool Makers, Healthcare Providers, Aviation Sector |
| Companies Covered | Panasonic Corporation, EVE Energy Co., Ltd., Contemporary Amperex Technology Co., Limited, Jiangsu Tenpower Lithium Co., Ltd., E-One Moli Energy Corporation, LG Energy Solution, Samsung SDI Co., Ltd., SVOLT Energy Technology Co., Ltd., BYD Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cylindrical Lithium-Ion Battery Market Strategic Shifts & Innovations
Cell architecture and manufacturing process innovations are converging to reduce cost per kilowatt-hour while tightening safety margins. These developments are compressing product lifecycles and forcing asset retooling decisions.
Tabless electrode designs are unifying current collection pathways across 4680 format cells. Tesla and Panasonic are deploying this architecture at scale in Nevada production lines. The technology is unifying manufacturing steps by eliminating tab welding and enabling faster winding speeds.
China's SAMR enforcement of updated GB/T standards is tightening nail penetration and overcharge test requirements for cells sold domestically. Cell producers must redesign venting mechanisms and separator formulations to maintain market access. Medical device and power tool exporters to China face accelerated retest obligations.
Automotive OEMs are consolidating cell procurement through direct long-term offtake agreements rather than tiered pack supplier relationships. Battery pack integrators are losing margin capture to cell producer-OEM direct contracts. This pattern is most visible in European electric vehicle programs where BMW and Volkswagen have established direct supply frameworks.
Cylindrical Lithium-Ion Battery Market Segmentation
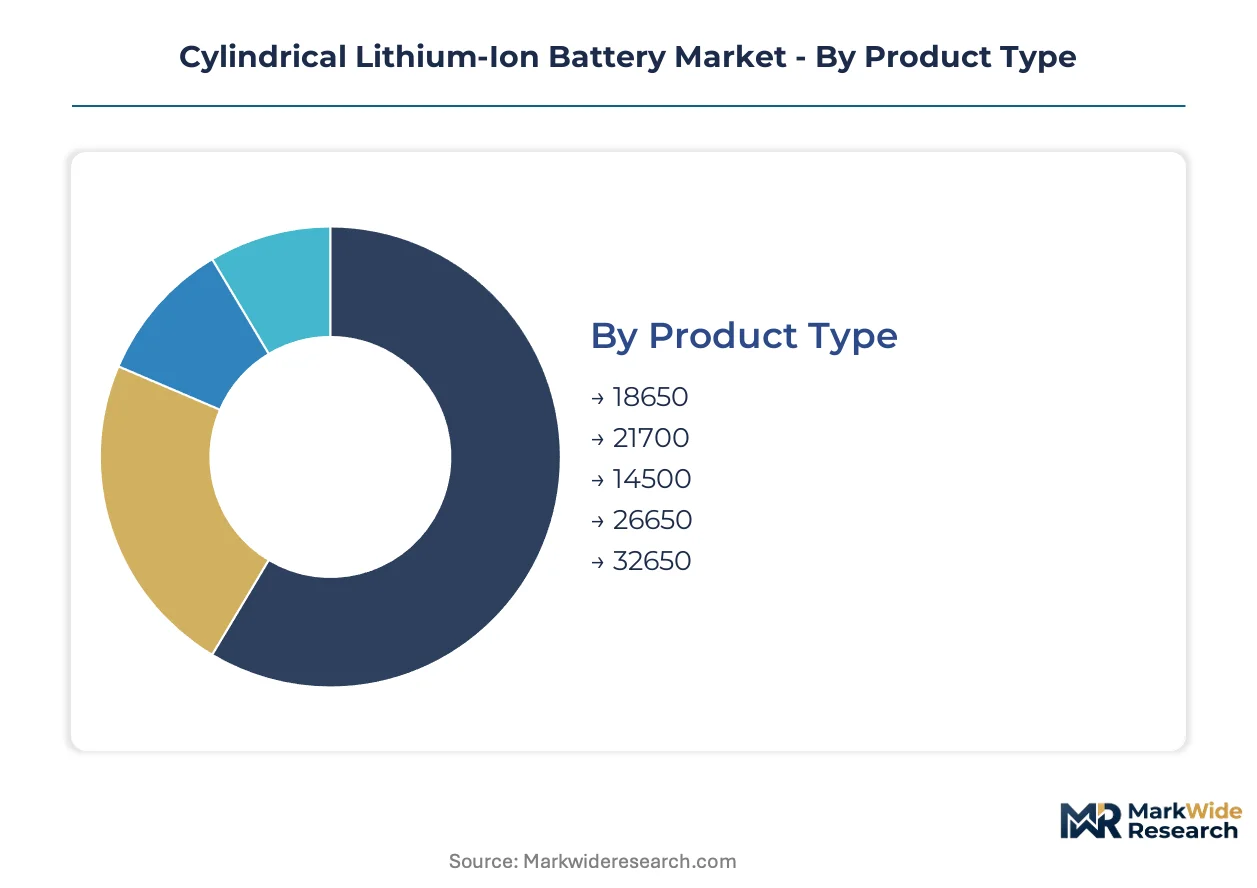
Cylindrical lithium-ion batteries fragment across four intersecting dimensions that determine pricing power and qualification barriers. Cell format and chemistry choices lock customers into specific supply chains, while application certification requirements create segment-specific moats.
Product Type:
Standardization dominates at the high-volume end, with custom tooling investments required for emerging large-format platforms.
- 18650:The legacy 18mm diameter by 65mm length format established cylindrical cell manufacturing economics. Demand concentrates in power tool battery packs and laptop computers where mature supply chains and established UN 38.3 certification reduce procurement risk.
- 21700:The 21mm by 70mm format delivers 40-50% higher energy density than 18650 cells. Electric bicycle and premium power tool manufacturers are displacing legacy formats, though pack redesign costs slow adoption among conservative industrial buyers.
- 14500:Compact 14mm by 50mm cells serve flashlight and portable electronics niches where cylindrical robustness outweighs prismatic energy density advantages.
- 26650:The 26mm diameter format targets high-discharge applications in professional lighting and medical equipment where thermal management margins matter.
- 32650:Large 32mm by 65mm cells penetrate solar street lighting and low-speed electric vehicle segments in China where cost-per-kilowatt-hour drives purchasing decisions.
Leading the category by volume: 18650. Growing fastest: 21700.
Technology:
Cathode chemistry selection trades energy density against thermal stability and raw material cost exposure.
- Lithium Nickel Manganese Cobalt Oxide:NMC layered oxide cathodes dominate automotive and power tool applications requiring 200+ Wh/kg cell-level energy density. South Korean producers anchor capacity around Ulsan for high-nickel variants.
- Lithium Iron Phosphate:Olivine-structured LFP cathodes sacrifice gravimetric density for cycle life and thermal runaway resistance. Stationary storage and medical device manufacturers prioritize the chemistry where safety certification costs dominate lifetime economics.
- Lithium Cobalt Oxide:High-voltage LCO cells retain premium consumer electronics positioning where cobalt cost pass-through remains acceptable.
- Lithium Manganese Oxide:Spinel-structured LMO chemistry serves cost-sensitive power tool segments with moderate cycle life requirements.
Widest adoption: Lithium Nickel Manganese Cobalt Oxide. Steepest expansion trajectory: Lithium Iron Phosphate.
Application:
Certification intensity varies dramatically, with aviation and medical segments imposing multi-year qualification timelines that freeze supplier relationships.
- Power Tools:Professional-grade cordless equipment demands 20A+ continuous discharge capability. Milwaukee and DeWalt battery platforms standardize on 18650 and 21700 formats with proprietary pack electronics.
- Electric Bicycles:European pedelec regulations mandate specific cell safety documentation. Pack integrators in the Netherlands and Germany source predominantly from South Korean cell producers.
- Medical Devices:Portable diagnostic and surgical equipment requires IEC 60601-1 collateral compliance. LFP chemistry dominates where sterilization cycles stress cell longevity.
- Aerospace:Electric vertical take-off aircraft developers specify cylindrical formats for thermal runaway containment. FAA certification pathways extend 3-5 years for new cell platforms.
- Consumer Electronics:Laptop and portable power bank applications represent mature demand with compressed margins and rapid format obsolescence.
Highest margin capture: Aerospace. Volume concentration: Power Tools.
End User Industry:
Procurement sophistication diverges between consolidated automotive-scale buyers and fragmented industrial purchasers.
- Consumer Electronics Manufacturers:Laptop and smartphone OEMs negotiate annual volume contracts with 5-10% price-down clauses. Foxconn and Quanta Computer aggregate demand across multiple brand customers.
- Tool Makers:TTI, Stanley Black & Decker, and Bosch Power Tools maintain dedicated cell qualification teams. Direct relationships with Panasonic and Samsung SDI bypass traditional battery pack intermediaries.
- Healthcare Providers:Hospital procurement consortiums specify backup power systems with 10-year service life guarantees. Philips and Medtronic integrate cylindrical cells into portable diagnostic platforms.
- Aviation Sector:Joby Aviation and Archer Aviation pursue FAA Part 23 certification for electric aircraft propulsion. Cell producers must demonstrate statistical thermal runaway containment across full state-of-charge ranges.
Most consolidated buying power: Tool Makers. Longest qualification cycles: Aviation Sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate and nickel sulfate refining capacity anchors cylindrical cell production geography. Cathode precursor plants cluster near raw material terminals to minimize logistics friction. Regulatory divergence between Beijing, Brussels, and Washington fragments qualification pathways for new cell platforms.
China
Electric bicycle and low-speed electric vehicle manufacturers drive 21700 and 32650 cell consumption. SAMR enforces updated GB/T standards tightening nail penetration and overcharge test requirements. The Yangtze River Delta hosts cathode active material plants feeding cylindrical cell assembly lines in Jiangsu and Zhejiang provinces.
South Korea
High-nickel NMC chemistry demand from European automotive OEMs concentrates procurement decisions. MFDS coordinates with industrial policymakers on cell safety certification reciprocity agreements. The Ulsan-Gwangju corridor houses integrated cathode and cell manufacturing complexes serving export markets.
United States
Electric vehicle tax credit eligibility rules under the Inflation Reduction Act reshape domestic content sourcing. FAA and DOT impose separate hazmat shipping restrictions fragmenting air cargo logistics for cylindrical cells. Panasonic operates cylindrical cell production at its Nevada facility supplying North American automotive programs.
Germany
Power tool OEMs and electric bicycle pack integrators source predominantly from South Korean cell producers. The EU Battery Regulation mandates recycled content thresholds and digital passports for industrial and EV batteries placed on the European market. Industrial clusters in Bavaria and North Rhine-Westphalia host battery pack assembly operations serving European demand.
Japan
Consumer electronics and specialized industrial equipment manufacturers sustain demand for legacy 18650 formats. METI coordinates standardization efforts for next-generation cylindrical cell safety protocols. Manufacturing concentration in the Kanto region around Tokyo maintains proximity to precision equipment suppliers and materials research institutes.
Cylindrical Lithium-Ion Battery Market Key Industry Players
Global majors compete with regional champions across cathode chemistry specialization and automotive qualification timelines. The market structure concentrates around integrated cell producers with captive cathode supply and independent specialists serving niche certification segments. Three archetypes dominate: diversified energy conglomerates with automotive-scale capacity, mid-tier specialists focused on power tool and consumer electronics segments, and emerging challengers leveraging cost-optimized LFP platforms. Capacity expansion and direct OEM offtake agreements represent the dominant competitive moves reshaping supplier relationships.
Among Asia-Pacific-based producers, Panasonic Corporation exemplifies the diversified conglomerate archetype with established North American manufacturing presence. LG Energy Solution and Samsung SDI Co., Ltd. occupy positions within the premium-tier automotive supply vector, anchoring high-nickel chemistry output for European and North American EV programs. Contemporary Amperex Technology Co., Limited represents the scale-driven challenger model with integrated vertical control across the cell value chain.
| Leading Market Players |
|---|
| Panasonic Corporation |
| EVE Energy Co., Ltd. |
| Contemporary Amperex Technology Co., Limited |
| Jiangsu Tenpower Lithium Co., Ltd. |
| E-One Moli Energy Corporation |
| LG Energy Solution |
| Samsung SDI Co., Ltd. |
| SVOLT Energy Technology Co., Ltd. |
| BYD Company Ltd. |
| Others |
Cost & Logistics Intelligence
Automotive OEM direct procurement teams concentrate buying power around 21700 and 4680 format cells, forcing contract structures that bundle long-term offtake pricing with performance warranties and recycling service commitments.
Pricing Analysis
Warranty and end-of-life service bundling separates premium automotive contracts from unbundled power tool transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from cathode material cost volatility compressing cell producer margins. Power tool OEMs exhibit highest price sensitivity due to mature pack electronics and rapid format turnover, while aviation developers accept premium positioning for thermal runaway containment guarantees.
Supply Chain Analysis
Reverse logistics flows for end-of-life cylindrical cells remain underdeveloped outside China's Yangtze River Delta pilot programs. Cathode active material production concentrates in China, South Korea, and Japan, drawing from nickel sulfate refineries and lithium carbonate conversion facilities. Single-source vulnerability persists for separator films and electrolyte additives tethered to East Asian chemical processors. Distribution runs through direct OEM contracts rather than traditional battery pack integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified dry electrode coating capacity represents the binding constraint propping cell pricing, as solvent-free process expertise remains scarce across major production regions.
For Market Incumbents: To counter emerging LFP challengers from China's integrated conglomerates, Panasonic and LG Energy Solution should deepen backward integration into cathode precursor manufacturing and accelerate Nevada and Michigan capacity additions. Securing FAA certification reciprocity for aviation cell platforms locks in high-margin segment control. For New Entrants and Emerging Players: Enter via residential stationary storage applications where cycle life requirements favor LFP chemistry and qualification barriers remain lower than automotive programs. European pedelec pack integrators present penetrable demand concentration in the Netherlands and Germany. Pursue direct relationships with solar inverter manufacturers as anchor channel partners. For Investors and Strategic Acquirers: The window for entry favors specialists with captive silicon anode process IP and automotive qualification timelines already initiated. Mid-tier producers with dry electrode pilot lines and South Korean or North American manufacturing footprints offer acquisition exposure to capacity-constrained premium segments. Monitor FAA Part 23 certification progress for electric aircraft propulsion as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Process Scale-Up | Solvent-free coating technology reduces manufacturing energy intensity and enables high-nickel cathode integration for automotive contracts. |
| Cathode Precursor Backward Integration | Captive nickel sulfate and lithium hydroxide supply hedges raw material volatility for European and North American EV programs. |
| Aviation Certification Partnership | FAA thermal runaway containment demonstration opens structurally high-margin demand from Joby Aviation and Archer Aviation. |
| EU Battery Regulation Compliance Infrastructure | Digital passport systems and recycled content verification maintain market access for industrial and EV cells placed in Germany. |
| North American Manufacturing Footprint Expansion | Domestic content qualification under the Inflation Reduction Act secures consumer EV tax credit eligibility for automotive OEM customers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cylindrical lithium-ion battery assessment. Primary interviews with cell producer procurement directors, automotive OEM battery platform engineers, power tool pack integrators, and aviation certification specialists combined with SAMR GB/T documentation, FAA hazmat guidance, and EU Battery Regulation implementation texts. Bottom-up cell shipment aggregation and top-down cathode material demand reconciliation validated segment splits.
Shipments, capacity utilization, and pricing streams were reconciled across product type, chemistry, and application dimensions over the projection horizon. Modeled segmentation spanned cell format, cathode technology, end-use application, and regional production cluster. CAGRs derived from logistic curve fitting to electric vehicle adoption patterns and power tool cordless transition rates. Silicon anode integration timelines and dry electrode yield curves served as technology-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cobalt price spike scenarios or accelerated solid-state battery substitution. Practitioners should monitor FAA certification timelines for electric aircraft propulsion and EU digital passport implementation enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Anode Market
Lithium-ion Battery
Germany Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Lithium-Ion Battery Materials Market
Lithium-ion Battery
United States Battery Cell Market
Lithium-ion Battery
Lithium Manganate Battery Market
Lithium-ion Battery
Consumer Lithium-Ion Battery Market