
 Lab-Grown Rough Diamond Market | 2026-2036
Lab-Grown Rough Diamond Market Size, Share, and Industry Trends Forecast 2026-2036
Lab-Grown Rough Diamond Market Insights
The lab-grown rough diamond sector is repositioning around a stark split between premium gem-quality stones and commodity industrial grit. De Beers Group leverages its Lightbox brand to anchor consumer-facing transparency at the premium tier, while Henan Huanghe Whirlwind CO., Ltd. dominates bulk HPHT production for industrial applications. WD Advanced Materials, LLC differentiates through specialized CVD wafer substrates that serve semiconductor and optical end-uses rather than gem markets.
Lab-grown rough diamonds are crystalline carbon structures synthesized through high-pressure high-temperature or chemical vapor deposition methods, typically achieving gem-quality clarity grades of VS or higher and industrial grades with controlled nitrogen content for thermal conductivity applications. HPHT output sustains the largest volume footprint across jewelry applications, while CVD material captures expanding share in electronics and optical devices where uniform crystal orientation matters. The wholesale end-user channel currently occupies the deepest margin pools, though e-commerce distribution is accelerating direct-to-manufacturer transactions that compress traditional intermediary positions.
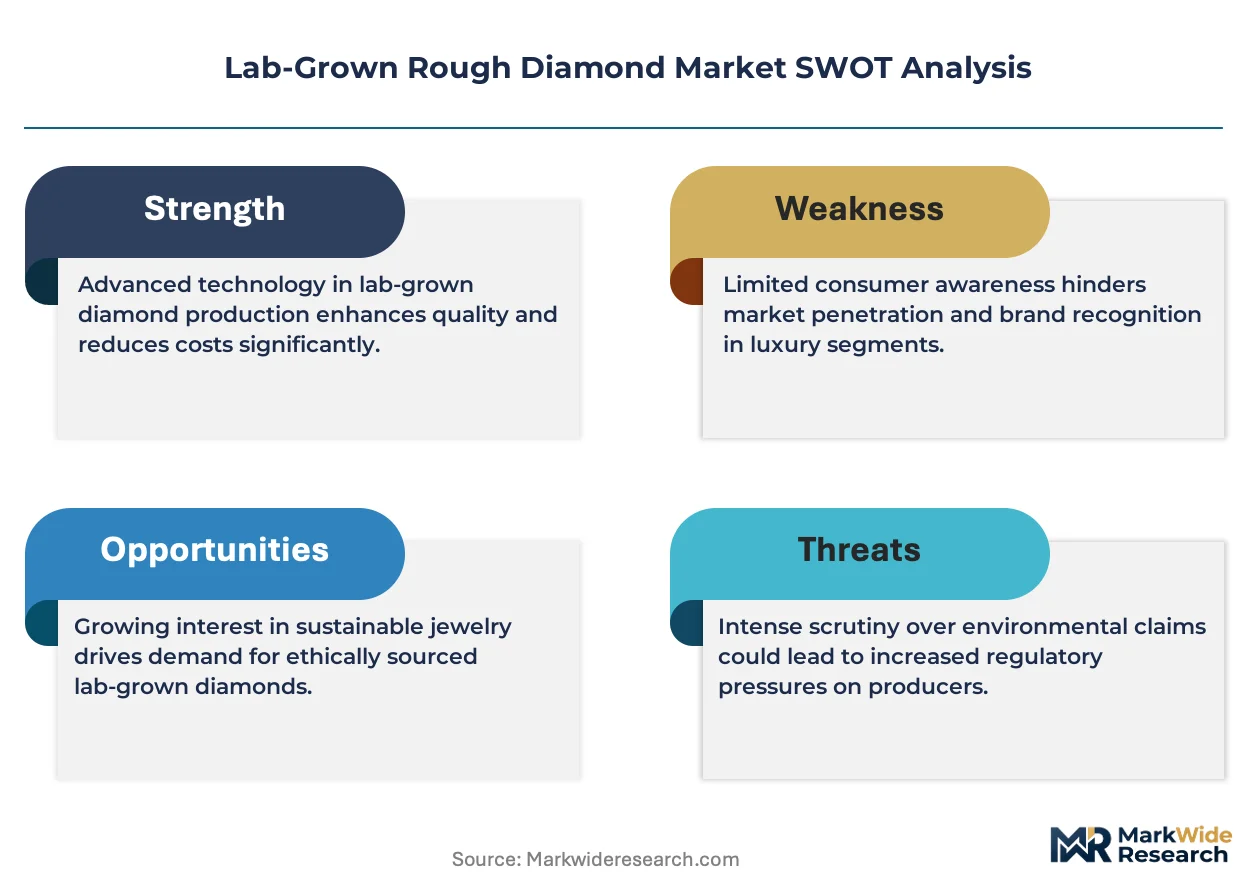
The FTC's jewelry guides in the United States mandate explicit non-deceptive labeling of lab-grown origin, while India's BIS certification requirements and China's GB standards for synthetic diamond classification create multi-jurisdictional compliance burdens for exporters. The EU's REACH framework and emerging due diligence rules under the CSRD are beginning to touch carbon-source verification and energy-disclosure claims for European-bound material. Stakeholders must monitor whether regulatory divergence between consumer-protection labeling and sustainability-certification schemes fragments market access or creates first-mover advantages for producers with pre-built compliance architecture.
Market Dynamics
HPHT and CVD synthesis methods are diverging into distinct supply tiers, with CVD material capturing premium gem applications while HPHT output floods industrial grit markets. This technological bifurcation is compressing margins at the commodity end while concentrating value capture among certified CVD wafer producers.
Growth Catalysts
- FTC Jewelry Guides:The United States' updated disclosure mandates for lab-grown origin are eliminating consumer confusion and accelerating retailer adoption of clearly labeled synthetic stones.
- Semiconductor substrate demand:CVD diamond wafers with controlled crystal orientation are displacing silicon carbide in high-frequency power electronics and quantum sensing applications.
- Surat cutting cluster concentration:India's diamond processing hub has scaled specialized infrastructure for lab-grown rough, reducing finishing costs by half versus traditional cutting centers.
Market Restraints
- Energy input volatility:HPHT synthesis requires sustained electricity loads of 50-60 kWh per carat, exposing producers to grid price spikes in manufacturing-intensive regions.
- Single-source equipment dependency:High-pressure press anvils and precision CVD reactor chambers are manufactured by a concentrated base of German and Japanese specialty engineering firms.
- Natural diamond price anchoring:De Beers' Lightbox pricing strategy caps consumer willingness-to-pay for unbranded lab-grown gems at the premium tier.
Strategic Opportunities
- China's dual carbon goals:MIIT incentives for low-carbon manufacturing are channeling state-backed capital into solar-powered CVD production facilities in Henan and Ningxia.
- Direct-to-manufacturer e-commerce:Alibaba and specialized B2B platforms are compressing traditional wholesale layers, enabling cutters in Surat to source rough directly from growers.
- Optical window applications:CVD diamond's thermal conductivity and infrared transparency are expanding into aerospace sensor domes and high-power laser optics.
Industry Challenges
- Multi-jurisdictional certification timelines:Producers must simultaneously satisfy BIS grading in India, GB standards in China, and FTC disclosure in the United States, fragmenting quality assurance workflows.
- CVD reactor scale-up capital intensity:Expanding from pilot to commercial wafer production requires proprietary microwave plasma source engineering that few equipment vendors can deliver.
- Carbon-source verification complexity:EU CSRD emerging rules on energy-disclosure claims are forcing producers to document methane feedstock origins and renewable electricity procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab-Grown Rough Diamond Market |
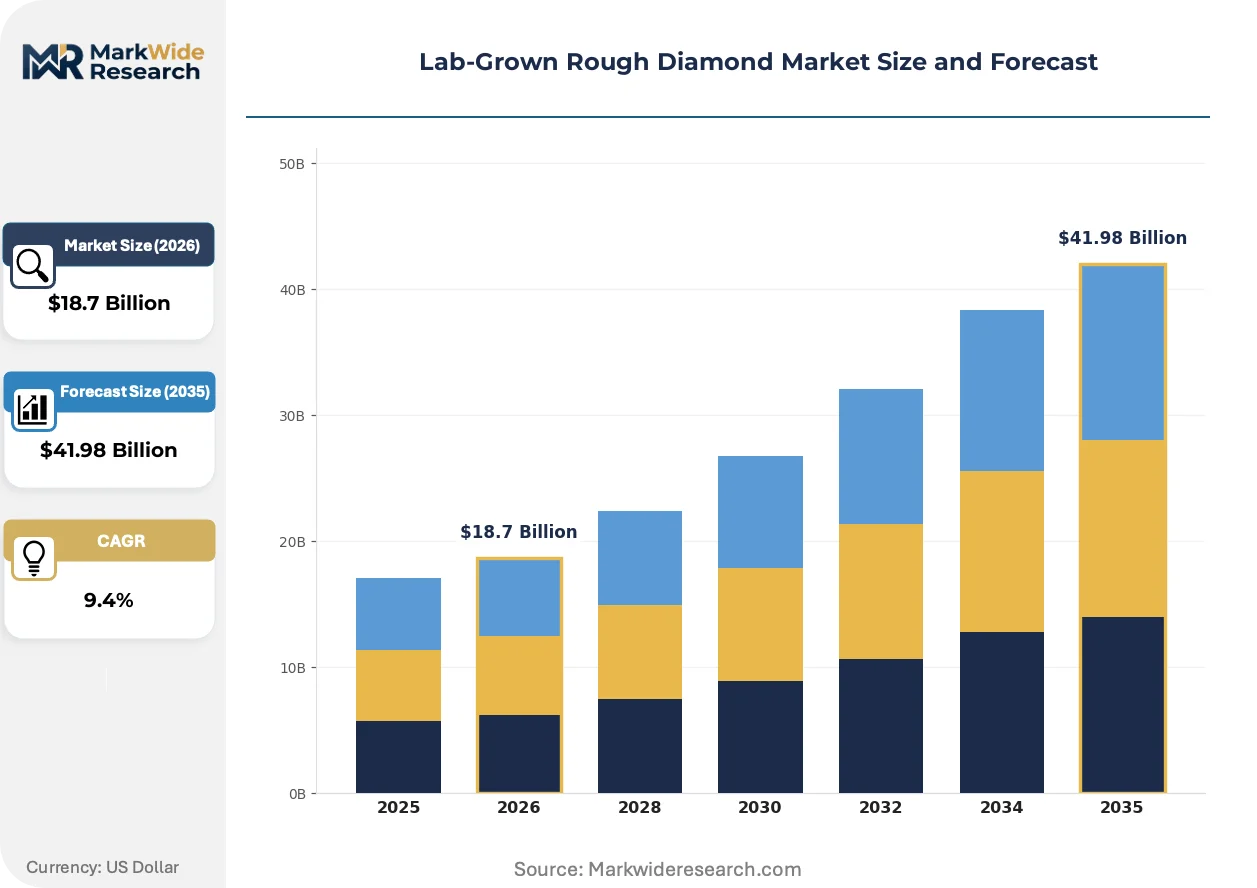
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HPHT, CVD, Synthetic Diamond, Moissanite Application: Jewelry, Industrial Use, Electronics, Optical Devices End User: Retail, Wholesale, Manufacturers, E-commerce Distribution Channel: Online, Offline, Direct Sales, Third-party Vendors |
| Companies Covered | De Beers Group, ABD Diamonds, WD Advanced Materials, LLC, Adamas One Corp, Henan Huanghe Whirlwind CO., Ltd., Bhanderi Lab Grown Diamonds, Mini Diamonds (I) Ltd., New Diamond Technology, SP3 Diamond Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab-Grown Rough Diamond Market Trends and Innovations
Technological maturation is splitting the lab-grown diamond sector into precision-engineered materials science and volume commodity production. Regulatory frameworks are hardening around origin transparency while end-use applications fragment across jewelry, electronics, and industrial thermal management.
Multi-wafer CVD reactor designs are expanding into commercial-scale production of single-crystal diamond substrates. Semiconductor foundries in Japan and the United States are qualifying these wafers for gallium nitride power device integration. The technology is expanding into thermal management layers that silicon carbide cannot match, compressing the addressable market for legacy ceramic substrates.
REACH and the EU's emerging CSRD due diligence framework are mandating carbon-source verification for synthetic diamond imports into Europe. Industrial users must now document methane feedstock origins and renewable energy procurement in supplier declarations. German automotive and French aerospace OEMs are most affected, pressing growers to install third-party electricity metering and blockchain traceability systems.
Bridal jewelry retailers are consolidating supplier relationships around vertically integrated growers with captive cutting operations. United States and Chinese retailers are bypassing traditional Antwerp and Dubai trading hubs, contracting directly for certified rough with guaranteed polish yields. This channel compression is most visible in mid-market engagement ring segments where price transparency and rapid restocking matter more than speculative inventory appreciation.
Lab-Grown Rough Diamond Market Segmentation
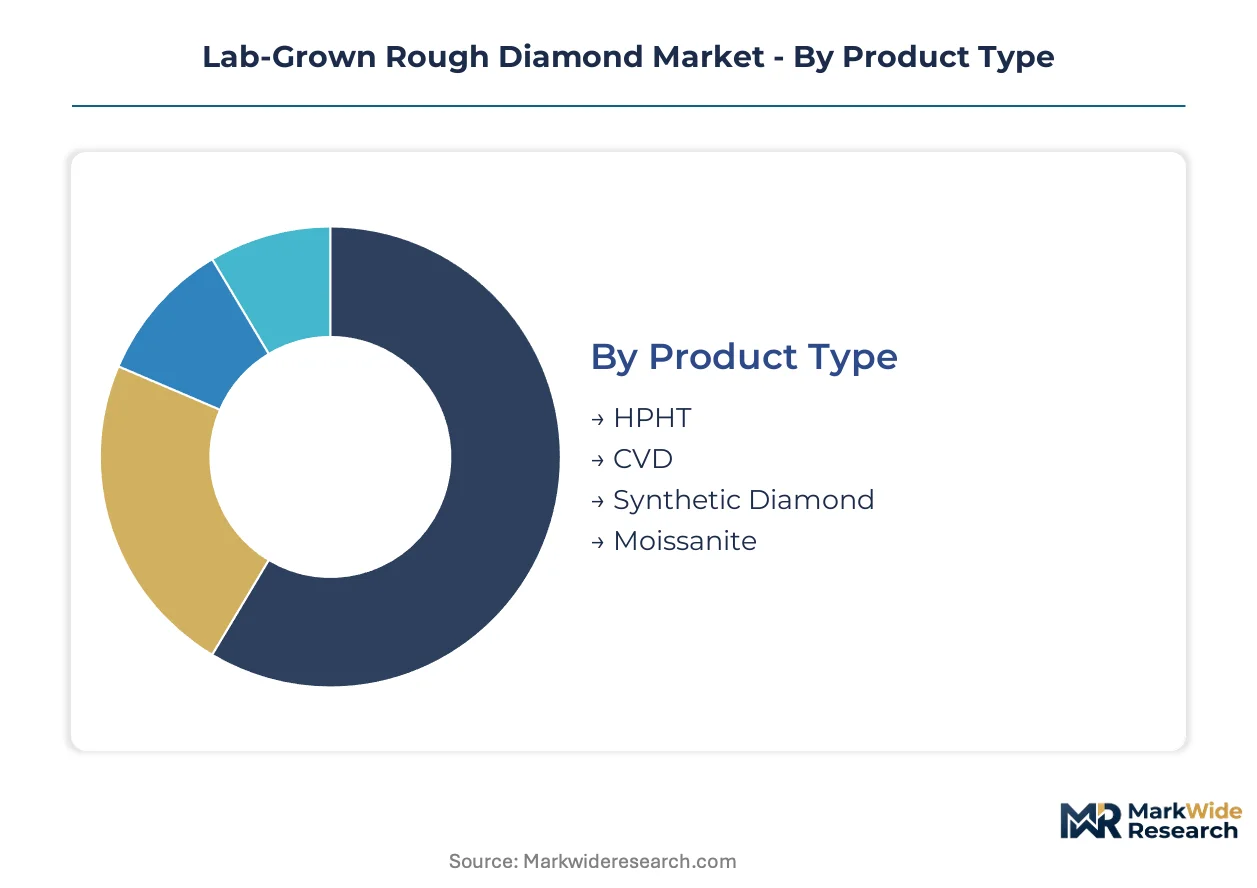
Segmentation in the lab-grown rough diamond market reveals how capital intensity, regulatory exposure, and end-use specifications fragment value capture across distinct supply tiers. Producers must align synthesis method and distribution channel with margin structure and compliance burden.
Product Type:
HPHT synthesis demands the heaviest upfront capital, with high-pressure presses consuming 50-60 kWh per carat and requiring specialized anvil assemblies from German and Japanese engineering suppliers.
- HPHT:High-pressure high-temperature synthesis produces gem-quality crystals with controlled nitrogen content for thermal conductivity applications. India's Surat cutting cluster processes the majority of HPHT rough for bridal jewelry, drawn by finishing costs half those of traditional centers. FTC disclosure mandates in the United States accelerate retailer procurement of clearly labeled HPHT stones.
- CVD:Chemical vapor deposition achieves uniform crystal orientation critical for semiconductor substrates and optical windows. Japan's semiconductor foundries and United States power electronics manufacturers qualify CVD wafers for gallium nitride device integration. MIIT incentives under China's dual carbon goals channel state capital into solar-powered CVD facilities in Henan and Ningxia.
- Synthetic Diamond:Broad-category material spans industrial grit to gem-grade specifications per BIS, GB, and FTC grading frameworks.
- Moissanite:Silicon carbide simulant competes at lower price points with distinct optical properties and refractive indices.
Most installed capacity flows through HPHT. Expansion is steepest in CVD.
Application:
Application segmentation tracks how material specifications diverge between aesthetic valuation and functional performance requirements.
- Jewelry:Bridal collections in the United States and China drive procurement of VS-clarity and higher grades. Retailers consolidate around vertically integrated growers with captive cutting operations, bypassing Antwerp and Dubai trading hubs for direct rough contracts with guaranteed polish yields.
- Industrial Use:Thermal management applications leverage controlled nitrogen content for heat sink and cutting tool substrates. EU REACH and emerging CSRD due diligence rules mandate carbon-source verification and renewable energy disclosure for European-bound industrial material.
- Electronics:CVD diamond wafers displace silicon carbide in high-frequency power electronics and quantum sensing. Scale-up from pilot to commercial production requires proprietary microwave plasma source engineering with concentrated equipment vendor bases.
- Optical Devices:Infrared transparency and thermal conductivity expand deployment into aerospace sensor domes and high-power laser optics. German automotive and French aerospace OEMs press growers for third-party electricity metering and blockchain traceability.
Jewelry commands the deepest margin pools. Electronics is climbing the fastest as semiconductor qualification accelerates.
End User:
End-user structure reflects channel compression as direct sourcing displaces traditional intermediary layers.
- Retail:United States and China bridal jewelry retailers scale procurement of certified lab-grown stones with clear origin disclosure per FTC guides. Vertical integration into captive cutting secures supply continuity and polish yield guarantees.
- Wholesale:Traditional Antwerp and Dubai trading hubs face volume pressure as manufacturers source directly from growers. Margin compression is most acute in mid-market segments where price transparency outweighs speculative inventory appreciation.
- Manufacturers:Surat-based cutters leverage specialized infrastructure to reduce finishing costs by half versus legacy centers. Direct-to-manufacturer e-commerce via Alibaba and specialized B2B platforms accelerates rough sourcing bypass.
- E-commerce:Direct-to-consumer channels require explicit non-deceptive labeling compliance across multi-jurisdictional frameworks including FTC, BIS, and GB standards.
Wholesale retains the largest transaction volume. E-commerce is gaining share fastest as platform infrastructure matures.
Distribution Channel:
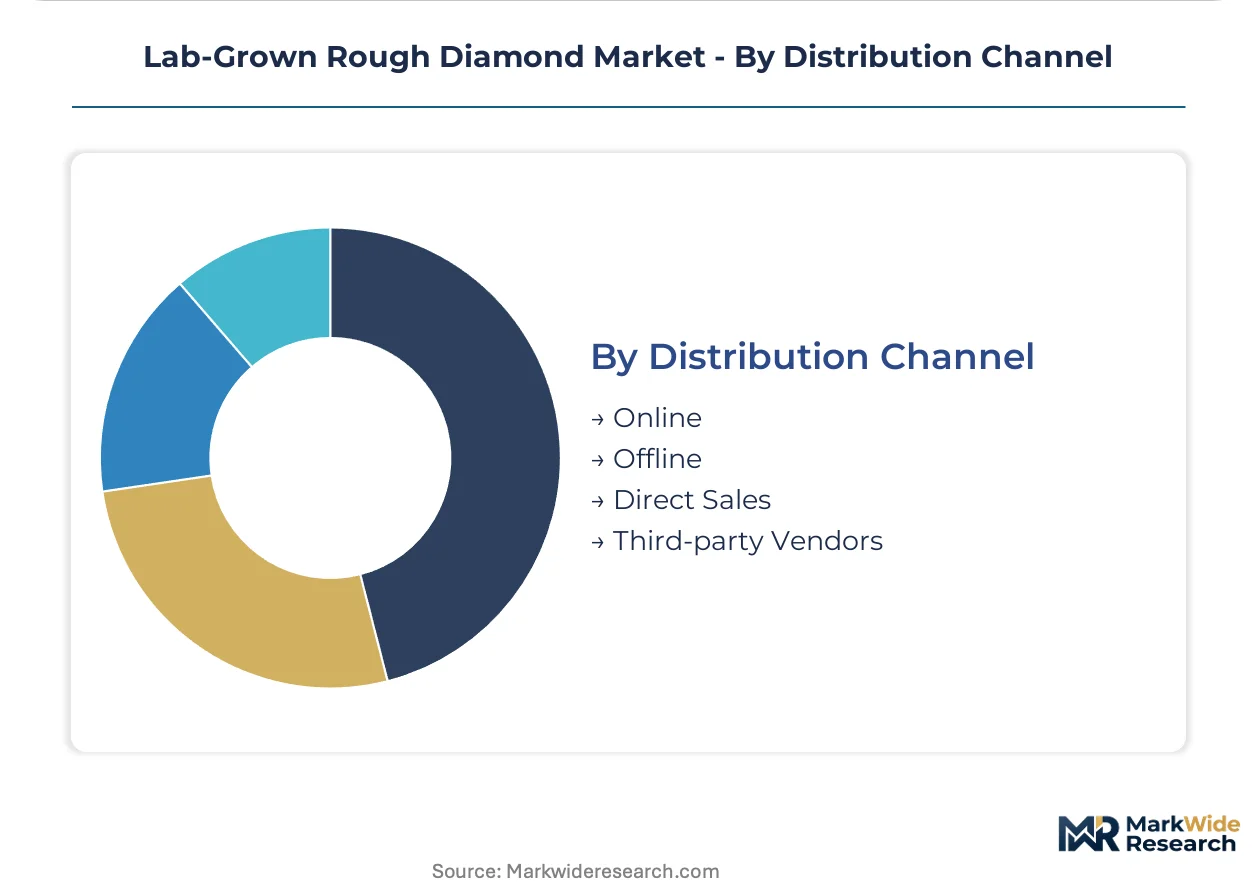
Channel configuration determines compliance burden and margin retention for producers navigating fragmented certification requirements.
- Online:Alibaba and specialized B2B platforms enable Surat cutters to source rough directly from growers, compressing traditional wholesale layers. Multi-jurisdictional labeling mandates from FTC, BIS, and GB standards require automated compliance architecture.
- Offline:Physical trading hubs in Antwerp and Dubai retain relevance for speculative inventory and large-lot transactions with established counterparty relationships.
- Direct Sales:Vertically integrated growers with captive cutting operations contract directly with United States and China retailers, securing premium positioning through supply chain control.
- Third-party Vendors:Independent distributors aggregate small-lot supply for fragmented industrial end-users with diverse specification requirements.
Offline channels handle the largest rough volumes. Direct sales is expanding most quickly as retailer consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Surat-facing export infrastructure processes more lab-grown rough than any other single node, while the United States retail channel absorbs the highest-value finished goods per carat. India, Belgium, and the United Arab Emirates concentrate intermediary functions that bridge these two poles.
United States
Bridal jewelry retailers in New York and Los Angeles consolidate procurement around vertically integrated growers with captive cutting operations. FTC jewelry guides mandate explicit non-deceptive labeling of lab-grown origin, eliminating consumer confusion and accelerating retailer adoption of certified synthetic stones. Direct-to-retailer contracts now bypass traditional Antwerp trading hubs for mid-market engagement ring segments.
China
Henan Province anchors HPHT synthesis capacity serving both gem-quality and industrial thermal management applications. MIIT incentives under dual carbon goals channel state-backed capital into solar-powered CVD production facilities in Ningxia. Zhengzhou-based equipment fabricators supply high-pressure press anvils to domestic and export markets.
India
Surat's diamond processing hub has scaled specialized infrastructure for lab-grown rough, reducing finishing costs by half versus legacy cutting centers. BIS certification requirements create compliance burdens for exporters serving multi-jurisdictional markets. Direct-to-manufacturer e-commerce via Alibaba and specialized B2B platforms accelerates rough sourcing from Chinese growers.
Belgium
Antwerp's traditional trading hub retains relevance for speculative inventory and large-lot transactions with established counterparty relationships. EU REACH framework and emerging CSRD due diligence rules mandate carbon-source verification and renewable energy disclosure for synthetic diamond imports. German automotive and French aerospace OEMs press suppliers for third-party electricity metering and blockchain traceability.
United Arab Emirates
Dubai's free trade zones facilitate re-export of lab-grown rough to Indian cutting centers and finished goods to European retail channels. The emirate's logistics infrastructure supports just-in-time inventory management for United States and Chinese bridal jewelry retailers. Regional regulatory frameworks remain less prescriptive on origin disclosure than FTC or BIS standards.
Lab-Grown Rough Diamond Market Competitive Landscape
Top-tier vendors anchor premium gem-quality and specialized substrate tiers, while commodity industrial grit producers compete on scale and energy cost arbitrage. The vendor base spans diversified mining conglomerates with synthetic divisions, pure-play growers with captive cutting, and equipment-integrated material science specialists. Strategic archetypes include: vertically integrated jewelry brands, semiconductor substrate pure-plays, and bulk HPHT industrial suppliers. Competitive moves concentrate on backward integration into reactor manufacturing and geographic expansion of solar-powered CVD capacity.
Within the diversified conglomerate tier, De Beers Group exemplifies premium consumer-facing transparency through its Lightbox brand architecture. Henan Huanghe Whirlwind CO., Ltd. occupies a position among scale-driven HPHT producers serving bulk industrial applications. WD Advanced Materials, LLC represents the specialized substrate archetype, with its corporate structure indicating Delaware-registered material science orientation toward non-gem end-uses. These three anchors illustrate how competitive positioning fragments across consumer branding, commodity scale, and technical specialization vectors.
| Leading Market Players |
|---|
| De Beers Group |
| ABD Diamonds |
| WD Advanced Materials, LLC |
| Adamas One Corp |
| Henan Huanghe Whirlwind CO., Ltd. |
| Bhanderi Lab Grown Diamonds |
| Mini Diamonds (I) Ltd. |
| New Diamond Technology |
| SP3 Diamond Technologies |
| Others |
Pricing and Supply Chain Analysis
Electricity input costs of 50-60 kWh per carat flow from HPHT reactor operations through Surat cutting margins to United States retail price floors, with renewable energy procurement emerging as the decisive cost differentiator between Chinese state-backed CVD facilities and legacy European producers.
Pricing Analysis
Capacity additions in Henan Province are reshaping price floors across gem-quality HPHT tiers. Three-tier pricing structure across premium, standard, and economy levels separates De Beers Lightbox certified stones from unbranded Indian-polished goods and bulk industrial grit. Price differentiation hinges on BIS certification grade and captive cutting integration. Cost compression in mid-market bridal segments intensifies as Alibaba B2B platforms enable direct Surat sourcing. Wholesale traders in Antwerp and Dubai exhibit highest price sensitivity; semiconductor foundries in Japan and the United States show lowest.
Supply Chain Analysis
Domestic-content mandates under China's MIIT dual carbon incentives are reshaping sourcing toward Ningxia solar-powered CVD facilities. Supply concentrates in China, India, and Belgium. Raw material flows draw from German and Japanese high-pressure press anvils, methane feedstock for CVD reactors, and specialized polishing compounds. Single-source equipment vulnerability from concentrated engineering vendors creates structural risk. Distribution runs through direct-to-manufacturer e-commerce platforms compressing traditional Antwerp and Dubai wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FTC jewelry guide disclosure mandates are accelerating retailer procurement of certified lab-grown stones and fragmenting competitive advantage around compliance architecture.
For Market Incumbents: Cement supply continuity through backward integration into captive cutting operations in Surat, insulating against direct-to-manufacturer e-commerce disintermediation. Invest in third-party electricity metering and blockchain traceability systems to preempt EU CSRD carbon-source verification requirements. Defensive positioning against HPHT commodity margin erosion requires CVD wafer qualification for semiconductor substrate tiers.
For New Entrants and Emerging Players: The gap between premium gem-grade CVD wafers and economy industrial HPHT grit offers white-space entry points. Target optical device applications in German automotive and French aerospace OEM supply chains where thermal conductivity specifications outpace incumbent capacity. Pursue MIIT incentive alignment for solar-powered CVD facilities in Ningxia as the go-to-market anchor.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdictional certification burdens fragment quality assurance workflows for sub-scale producers. Long-term viability favors vertically integrated growers with captive cutting and pre-built FTC-BIS-GB compliance architecture. Watch CVD reactor scale-up capital intensity as the inflection signal separating qualified semiconductor substrate suppliers from stranded gem-only capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reactor Manufacturing | Reduces dependency on German and Japanese high-pressure press anvil suppliers for HPHT operations. |
| Solar-Powered CVD Facility Expansion | Aligns with MIIT dual carbon incentives while securing renewable energy cost advantages in Ningxia. |
| Blockchain Traceability Implementation | Satisfies EU CSRD carbon-source verification demands from German automotive and French aerospace OEMs. |
| Direct-to-Retailer Contracting | Bypasses Antwerp and Dubai wholesale compression for United States bridal jewelry procurement. |
| Semiconductor Substrate Qualification | Opens gallium nitride power electronics and quantum sensing applications beyond gem markets. |
Research Methodology
Bottom-up electronics and jewelry end-use modeling reconciled against top-down HPHT and CVD synthesis capacity tracking forms the analytical core. Primary interviews with CVD reactor engineers, Surat cutting house operators, United States bridal jewelry procurement directors, and BIS certification auditors combined with secondary validation from FTC jewelry guide filings, Indian customs trade data, MIIT policy circulars, and SEC equipment supplier disclosures. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map reactor capacity by synthesis method against application-specific yield coefficients and certification tier premiums across the projection horizon. Segmentation dimensions include synthesis technology, clarity grade tier, end-use application, and regional regulatory cluster. CAGRs derive from installed capacity expansion rates qualified against semiconductor foundry qualification timelines and bridal jewelry retailer inventory turnover patterns. Feedstock methane sourcing and renewable electricity procurement emerge as critical forecast inputs.
Caveats apply where EU CSRD implementation timelines or FTC enforcement intensity could materially shift the outlook. Forecasts reflect assumptions around BIS-GB regulatory alignment and CVD wafer scale-up engineering feasibility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Buckminsterfullerene Market
Advanced Materials
Lithium Tantalate Crystal Market
Advanced Materials
Global Advanced Phase Change Materials Market
Advanced Materials
Europe Next Generation Anode Materials Market
Advanced Materials
Boron Nitride Market
Advanced Materials
Global Thermal Interface Materials Market
Advanced Materials
Borophene Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Thermal Spray Market
Advanced Materials
2D Materials Market
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Nomex Honeycomb Market
Advanced Materials
Si-C Anode Material Market