
 North America Next Generation Anode Materials Market | 2026-2036
North America Next Generation Anode Materials Market Size, Share, and Industry Trends Forecast 2026-2036
North America Next Generation Anode Materials Market Analytics
Electric vehicle OEMs is reorganizing procurement priorities around silicon-dominant anode chemistries, displacing traditional graphite sourcing from consumer electronics buyers. Sila Nanotechnologies leverages its vertical integration into silicon nanoparticle synthesis to secure long-term automotive contracts. Amprius Technologies anchors its position through proprietary silicon nanowire architectures that sustain higher energy densities than conventional alternatives. Enovix Corporation differentiates via three-dimensional cell architectures that compete on volumetric efficiency for premium electronics applications.
North America next generation anode materials encompass engineered active substances—primarily silicon composites, lithium titanate spinels, and conductive polymer matrices—that replace conventional graphite in lithium-ion battery negative electrodes, typically achieving specific capacities above 1,000 mAh/g through nanostructuring or alloying mechanisms. These materials enable extended driving ranges in electric vehicles and longer cycle life in grid storage systems by accommodating higher lithium-ion insertion densities without catastrophic mechanical failure. Silicon product types dominate current investment flows due to their theoretical capacity advantage, though lithium titanate retains structural importance in fast-charging bus and industrial segments where cycle stability outweighs energy density priorities. Chemical and composite processing technologies attract disproportionate capital allocation as manufacturers seek scalable routes to stabilize silicon volume expansion during lithiation.
The US Inflation Reduction Act and EPA vehicle emissions standards collectively mandate domestic battery content thresholds that reshape supplier qualification criteria across the value chain. Canada's federal clean fuel regulations and provincial zero-emission vehicle mandates in Quebec and British Columbia reinforce North American demand localization requirements. Stakeholders must monitor how NHTSA battery safety protocols and evolving UL certification standards for thermal runaway containment will filter market access for emerging anode architectures.
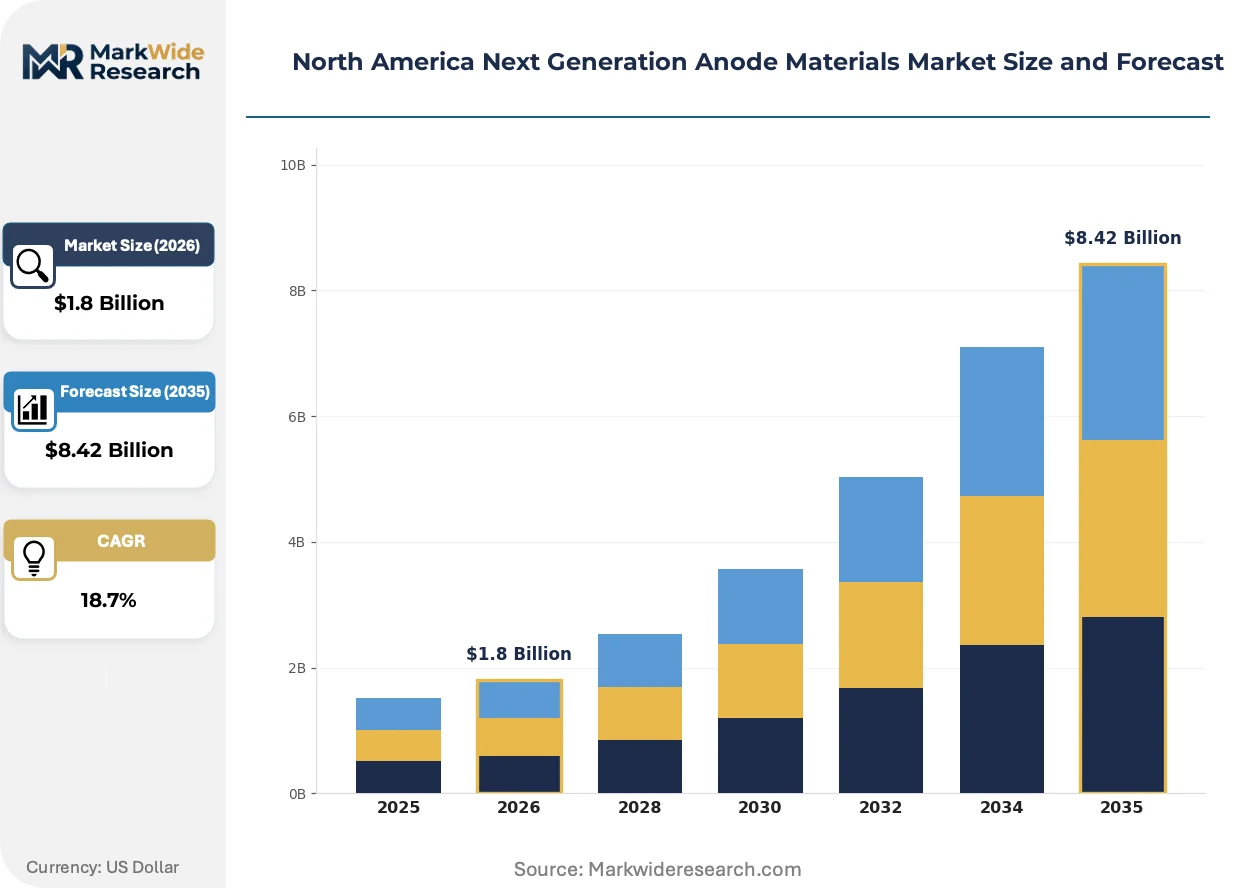
Market Dynamics
Silicon-dominant anode chemistries are compressing procurement timelines as electric vehicle OEMs demand higher energy densities than graphite can deliver, forcing suppliers to requalify manufacturing processes around nanoparticle synthesis and nanowire architectures.
Growth Catalysts
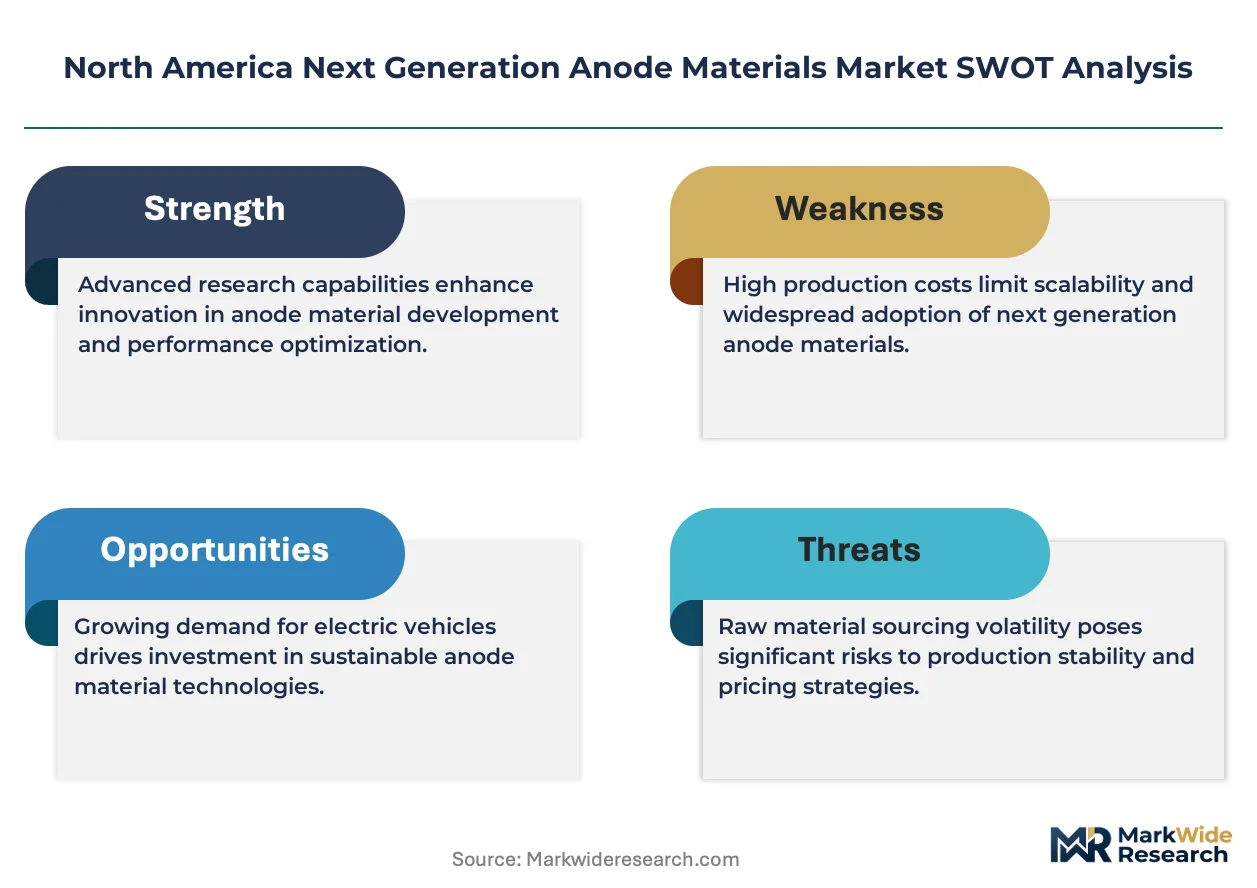
- US IRA domestic content thresholds:Battery component localization mandates redirect capital toward Michigan, Ohio, and Kentucky manufacturing corridors.
- Silicon nanostructuring advances:Scalable routes to stabilize volume expansion during lithiation unlock automotive contract eligibility.
- EPA vehicle emissions standards:Stringent fleet-average requirements accelerate OEM adoption of high-capacity anode materials.
Market Restraints
- Purified metallurgical-grade silicon supply:Concentrated upstream mining and refining in southwestern US creates input cost volatility.
- Electrolyte compatibility limitations:Silicon anodes require novel electrolyte formulations that remain underdeveloped at commercial scale.
- NHTSA battery safety protocol uncertainty:Evolving thermal runaway containment standards delay product certification timelines.
Strategic Opportunities
- Quebec and British Columbia zero-emission mandates:Provincial vehicle adoption targets create localized demand nodes for Canadian suppliers.
- Grid storage system integration:Utility-scale battery deployments prioritize cycle stability over energy density, opening lithium titanate applications.
- Silicon-polymer composite convergence:Hybrid architectures combining conductive matrices with active nanoparticles address mechanical degradation.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized expertise in solid-electrolyte interphase management remains concentrated among limited research institutions.
- UL 9540A thermal runaway certification:Third-party testing bottlenecks extend product validation cycles beyond customer qualification windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Next Generation Anode Materials Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphite, Silicon, Lithium Titanate, Conductive Polymers Technology: Mechanical, Chemical, Composite, Electrochemical End User: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Industrial Applications Application: Smartphones, Laptops, Battery Packs, Renewable Energy Solutions |
| Companies Covered | Sila Nanotechnologies Inc., Amprius Technologies, Enovix Corporation, NanoGraf Corporation, Albemarle Corporation, Cuberg, OneD Battery Sciences, Nexeon Ltd., Talga Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Next Generation Anode Materials Market Evolving Landscape
Active materials engineering is compressing traditional qualification pathways as automotive buyers impose simultaneous requirements for energy density gains and manufacturing scalability.
Silicon nanowire architectures are displacing conventional composite approaches in premium electric vehicle segments. Automotive OEMs in the US Midwest battery corridor now specify wire-based morphologies for 2027 platform launches. This displacement is compressing graphite anode market share in long-range vehicle categories.
The US Inflation Reduction Act's domestic content bonus credit reshapes supplier qualification criteria. Battery component manufacturers must demonstrate North American provenance to maintain OEM contract eligibility. Material processors in Kentucky and Ohio are responding by integrating nanoparticle synthesis steps previously outsourced to Asia-Pacific.
Long-term offtake agreements are replacing spot purchasing for active anode materials. Tier-one automotive buyers now contract directly with silicon precursor suppliers, bypassing traditional trading intermediaries. This pattern concentrates most visibly in Michigan-based OEM procurement organizations managing 2026-2028 model year transitions.
North America Next Generation Anode Materials Market Segmentation
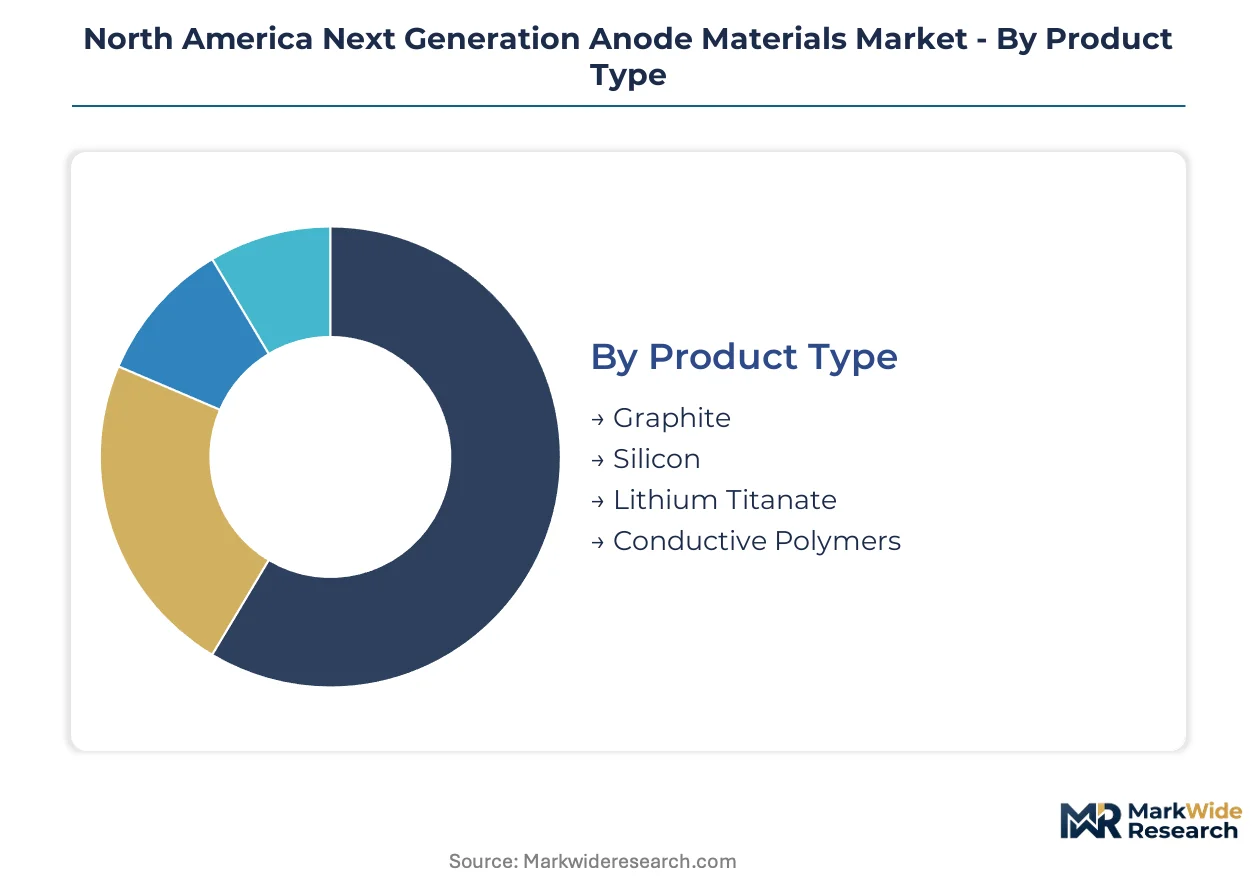
Segmentation in North American next generation anode materials reveals how procurement priorities diverge across battery chemistry families and manufacturing process technologies. Understanding these divisions exposes where capital allocation concentrates and which technical specifications determine contract eligibility for automotive and grid storage buyers.
Product Type:
Margin pools concentrate in silicon-dominant formulations where automotive OEMs pay premiums for energy density gains unavailable from conventional graphite.
- Silicon:Nanostructured silicon composites achieve specific capacities exceeding 3,000 mAh/g through nanoparticle or nanowire architectures. Procurement from Michigan and Ohio OEMs concentrates here as EPA fleet standards force energy density upgrades beyond graphite limits.
- Graphite:Synthetic and natural graphite anodes retain cost advantages in consumer electronics and entry-level vehicle segments. Kentucky processors maintain capacity for hybrid vehicles where cycle stability requirements moderate.
- Lithium Titanate:Spinel-structured oxide enables ultra-fast charging with minimal degradation for bus and industrial applications.
- Conductive Polymers:Polyaniline and polypyrrole matrices address mechanical stress in silicon-polymer hybrid architectures.
The dominant share belongs to Silicon, while Lithium Titanate is closing the gap fastest in commercial transit electrification.
Technology:
Volume leadership sits with chemical processing routes that scale silicon nanoparticle production for automotive qualification timelines.
- Chemical:Vapor-phase and solution-based synthesis controls particle size distribution for stable solid-electrolyte interphase formation. Ohio and Michigan facilities are expanding chemical vapor deposition capacity to meet IRA domestic content thresholds.
- Mechanical:Ball milling and mechanical alloying reduces silicon to sub-micron dimensions for composite blending with carbon matrices.
- Composite:Hybrid architectures integrate active silicon with conductive binders and buffer matrices to accommodate volume expansion.
- Electrochemical:Electrodeposition and electrochemical exfoliation routes remain pre-commercial for specialized nanowire morphologies.
Chemical processing holds the dominant share, with Composite technology expanding most quickly as manufacturers address silicon mechanical degradation.
End User:
Application-driven cost tiers separate premium automotive contracts from price-sensitive consumer electronics procurement.
- Electric Vehicles:Long-range passenger and commercial vehicle platforms specify silicon-dominant anodes for 300+ mile range targets. Midwest battery corridor OEMs in Michigan, Ohio, and Kentucky drive qualification requirements for 2027-2028 model year launches.
- Consumer Electronics:Premium smartphones and laptops prioritize volumetric energy density for compact form factors.
- Energy Storage Systems:Utility-scale deployments favor cycle stability over energy density, sustaining lithium titanate demand.
- Industrial Applications:Forklifts, mining equipment, and marine systems require fast-charging capability with extended operational lifespan.
Electric Vehicles command the dominant share, while Energy Storage Systems are gaining share fastest as grid-scale deployments accelerate under FERC interconnection reforms.
Application:
Supply concentration tracks customer scale, with automotive battery pack volumes dwarfing individual device categories.
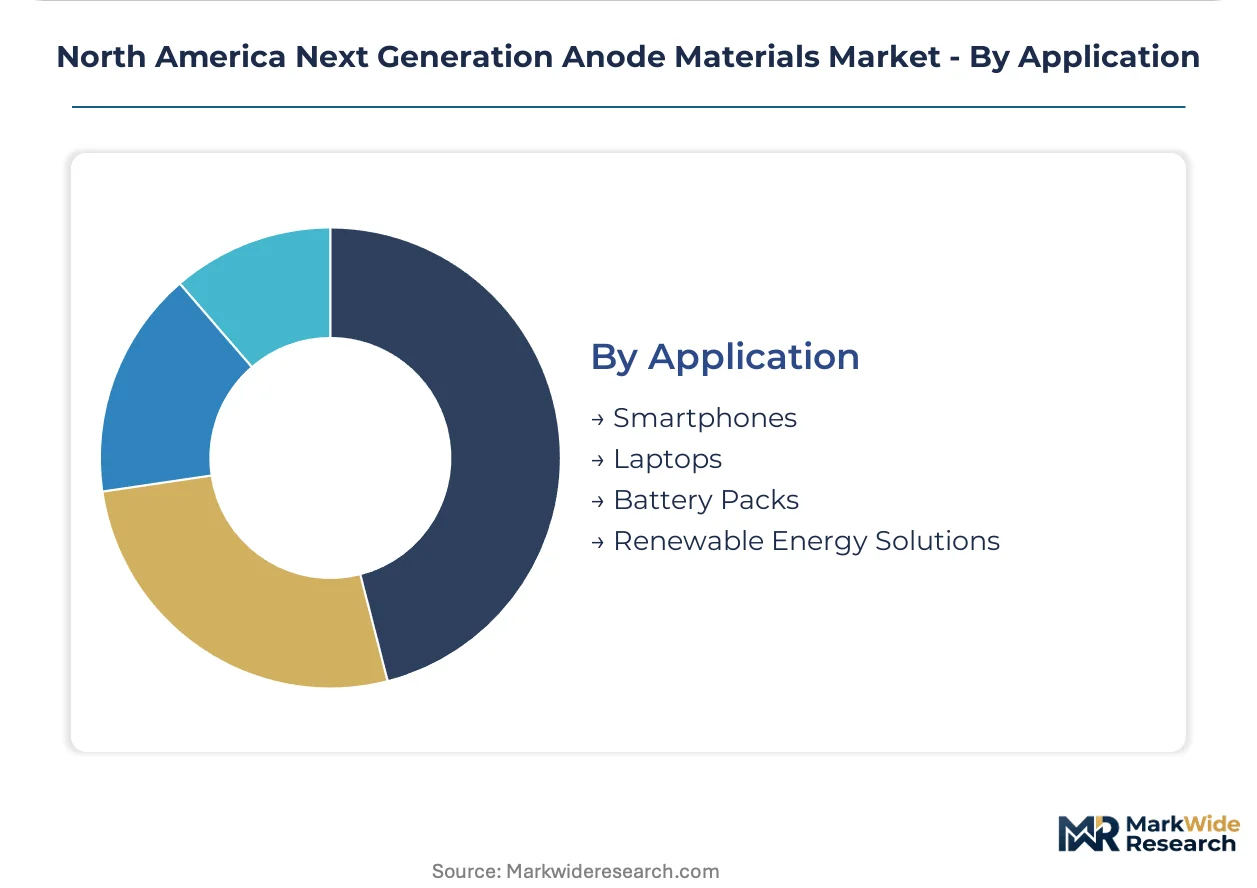
- Battery Packs:Integrated module and pack-level procurement from tier-one suppliers specifies anode active materials directly. Michigan-based OEM procurement organizations now contract silicon precursor suppliers for 2026-2028 production ramps.
- Renewable Energy Solutions:Solar-plus-storage and wind integration projects specify anode materials for 4-8 hour duration systems.
- Smartphones:Premium handset manufacturers specify three-dimensional cell architectures maximizing volumetric efficiency.
- Laptops:Thin-and-light computing devices drive demand for high-capacity anodes in compact cylindrical and pouch formats.
Battery Packs represent the dominant application, with Renewable Energy Solutions climbing the fastest as state-level clean energy mandates expand storage procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian silicon precursor producers now ship engineered nanoparticles to Michigan and Ohio battery gigafactories, establishing a cross-border supply corridor that bypasses Asia-Pacific intermediaries.
United States
Michigan, Ohio, and Kentucky anchor the Midwest battery corridor where OEM procurement organizations contract directly with anode material suppliers. The US Inflation Reduction Act's domestic content bonus credit redirects capital toward Kentucky chemical processing facilities previously dependent on overseas nanoparticle synthesis. Ohio manufacturers are expanding vapor-phase deposition capacity to meet IRA qualification thresholds for 2027 model year launches.
Canada
Quebec and British Columbia zero-emission vehicle mandates generate localized demand nodes for silicon-dominant anode suppliers serving cross-border automotive customers. Federal clean fuel regulations reinforce provincial adoption targets, pressuring material processors to demonstrate North American provenance. Ontario-based suppliers are integrating backward into metallurgical-grade silicon refining to capture IRA-compliant supply chain positions.
Mexico
Baja California and Sonora manufacturing clusters attract battery component investment as US OEMs seek nearshore capacity that satisfies domestic content requirements through USMCA trade provisions. Mexican processors specialize in mechanical alloying and composite blending steps that feed finished anode materials to Texas and California battery plants. Nuevo León is emerging as a chemical processing hub for silicon-carbon hybrid architectures.
North America Next Generation Anode Materials Market Competitive Landscape
Listed leaders compete with private specialists across capital access and technology development timelines, producing a tiered structure where public companies anchor automotive qualification pathways while private firms pursue niche applications. Market concentration sits with vertically integrated material processors controlling nanoparticle synthesis and electrode formulation. Three archetypes dominate: silicon nanowire specialists, composite architecture developers, and precursor chemical suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms race to secure Midwest OEM offtake agreements.
Within the nanostructured silicon tier, Sila Nanotechnologies Inc. and Amprius Technologies occupy positions exemplifying divergent technical approaches to volume expansion management. Enovix Corporation represents the three-dimensional cell architecture specialization competing on volumetric efficiency metrics. These three California-based developers anchor the competitive landscape for premium automotive and electronics applications.
| Leading Market Players |
|---|
| Sila Nanotechnologies Inc. |
| Amprius Technologies |
| Enovix Corporation |
| NanoGraf Corporation |
| Albemarle Corporation |
| Cuberg |
| OneD Battery Sciences |
| Nexeon Ltd. |
| Talga Group |
| Others |
Value Network & Pricing Analysis
UL 9540A thermal runaway certification gates both supplier qualification and price differentiation simultaneously, separating premium silicon nanowire suppliers from commodity composite processors while compressing margins for uncertified entrants unable to meet OEM safety mandates.
Pricing Analysis
Next-generation silicon nanowire architectures command substantial premiums over conventional silicon-carbon composites and legacy graphite formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, with UL-tested nanowire materials at the top and unqualified mechanical alloys at the base. Pricing pressure stems from purified metallurgical-grade silicon supply volatility in southwestern US mining corridors. Consumer electronics buyers exhibit highest price sensitivity, while Michigan and Ohio OEM procurement organizations absorb premiums for IRA-compliant domestic content.
Supply Chain Analysis
Canada and the United States anchor engineered nanoparticle production, with Ontario suppliers integrating backward into metallurgical-grade silicon refining and Kentucky processors expanding chemical vapor deposition capacity. Raw material dependencies center on southwestern US metallurgical-grade silicon, Canadian graphite precursors, and specialized electrolyte formulations from South Korean chemical suppliers. Single-source vulnerability concentrates in purified silicon refining, where limited North American capacity creates chokepoint exposure. Distribution runs through direct long-term offtake agreements between OEM procurement organizations and material processors, bypassing traditional trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery architectures pose a credible substitution threat that silicon-dominant anode incumbents must navigate through performance differentiation and cost compression.
For Market Incumbents: Fortify automotive qualification pathways by securing UL 9540A certification ahead of 2027-2028 model year procurement windows. Deepen backward integration into metallurgical-grade silicon refining to insulate margins from southwestern US supply volatility. Prioritize Michigan and Ohio manufacturing corridor expansion to capture IRA domestic content bonus credits before competitor capacity comes online. For New Entrants and Emerging Players: UL 9540A certification fast-track programs offer the most penetrable entry vector for uncredentialed processors seeking automotive contract eligibility. Target grid storage system integration where lithium titanate cycle stability requirements create lower barriers than silicon nanowire automotive qualification. Pursue Quebec and British Columbia zero-emission vehicle mandates as localized demand nodes with less entrenched incumbent presence. For Investors and Strategic Acquirers: EPA vehicle emissions standard stringency reshapes the acquisition landscape toward processors with proven OEM qualification relationships and scalable chemical synthesis capacity. Five-to-ten year viability hinges on demonstrated solid-electrolyte interphase management expertise rather than laboratory-scale performance metrics. Watch NHTSA battery safety protocol finalization as the critical inflection signal determining which pre-revenue architectures achieve commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Refining | Ontario and Kentucky facilities capture IRA-compliant supply chain positions against Asia-Pacific competitors. |
| UL 9540A Certification Investment | Third-party validation unlocks Michigan and Ohio OEM procurement channels for nanowire architectures. |
| Long-term Supply Agreement | Direct offtake contracts with tier-one automotive buyers displace spot purchasing and trading intermediaries. |
| Quebec Manufacturing Footprint | Provincial zero-emission mandates create localized demand nodes serving cross-border battery gigafactories. |
| Solid-Electrolyte Interphase R&D Partnership | University collaborations address talent scarcity in specialized electrochemical engineering domains. |
Research Methodology
Operator-level perspectives from OEM procurement directors, tier-one battery supplier technical leads, silicon precursor plant managers, and UL certification engineers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, US Customs and Border Protection trade data, EPA regulatory dockets, and FERC interconnection queue records. Bottom-up capacity buildout estimates triangulated with top-down demand projections from vehicle production databases.
Sensitivity analysis tested forecast robustness across the projection horizon against silicon feedstock price volatility, IRA domestic content threshold modifications, and NHTSA safety protocol timing. Segmentation dimensions modeled include product type, processing technology, end-user application, and regional manufacturing corridor. CAGRs derived from installed capacity ramps, OEM platform launch schedules, and grid storage procurement pipelines under state-level clean energy mandates.
Underlying assumptions cover IRA credit continuity, EPA fleet standard enforcement, and UL certification timeline stability, with deviation risk concentrated in electrolyte formulation commercialization delays and NHTSA rulemaking uncertainty. Recalibration cycles align with material shifts in federal battery safety regulations and provincial zero-emission vehicle mandate revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Borophene Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Global Advanced Materials Market
Advanced Materials
Bioactive Glass Market
Advanced Materials
APAC Advanced Building Materials Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Buckminsterfullerene Market
Advanced Materials
Corundum Market
Advanced Materials
Global Advanced Phase Change Materials Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Transparent Wood Market
Advanced Materials
Magnetic Shielding Sheets Market