
 Sodium Dichloroisocyanurate Market | 2026-2036
Sodium Dichloroisocyanurate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Dichloroisocyanurate Market Outlook
Buyer concentration among municipal water authorities is restructuring procurement patterns across developing regions. Lonza Group Ltd. leverages its European manufacturing base to supply certified-grade tablets to WHO-prequalified programs. Heze Huayi Chemical Co., Ltd. anchors Chinese domestic demand through backward integration into cyanuric acid feedstock. Jiheng Chemical Co., Ltd. competes on granule specialization for industrial cooling towers.
Sodium dichloroisocyanurate (NaDCC) is a chlorinated derivative of cyanuric acid, typically formulated as C3Cl2N3NaO3 with available chlorine content of 56–60% by weight, manufactured through controlled chlorination of sodium cyanurate followed by drying and compaction into stable solid forms. The compound releases hypochlorous acid upon dissolution, delivering residual disinfection for potable water, swimming pools, and food-contact surfaces without the pH volatility of liquid bleach alternatives. Tablet formats dominate institutional procurement due to dosing precision and reduced handling risk, while powder variants sustain margin pools in agricultural and emergency-relief applications where bulk flexibility outweighs convenience premiums. Water treatment commands the largest application share, though pool sanitization segments in warm-climate tourism economies show faster volume acceleration as hospitality operators replace unstable calcium hypochlorite inventories.
EPA registration under FIFRA governs NaDCC sale for drinking-water treatment in the United States, while REACH compliance and EU BPR authorization shape market access across European member states. China's MEE enforces discharge limits on cyanuric acid byproducts from chlorinated isocyanurate manufacturing, raising compliance costs for unintegrated producers. Stakeholders must monitor evolving residue limits in food-contact applications and prequalification requirements from multilateral health procurement bodies.
Market Dynamics
Municipal water authorities in tropical climates are consolidating procurement around tablet-form NaDCC as WHO prequalification requirements harden, compressing supplier margins while favoring integrated manufacturers with certified production lines.
Growth Catalysts
- Emerging Market Infrastructure:Sub-Saharan African utilities are expanding chlorinated isocyanurate capacity under World Bank sanitation financing, replacing unstable calcium hypochlorite stocks.
- REACH Authorization Pathways:EU Biocidal Products Regulation compliance is accelerating substitution of liquid bleach in institutional food-contact applications across member states.
- Tropical Storage Stability:NaDCC's superior shelf life versus hypochlorite alternatives is absorbing procurement share in Southeast Asian disaster-relief stockpiles and hospitality supply chains.
Market Restraints
- Cyanuric Acid Feedstock Concentration:Chinese producers control upstream sodium cyanurate supply, exposing non-integrated formulators to input cost volatility and export quota restrictions.
- Discharge Compliance Burden:China's MEE enforcement of cyanuric acid byproduct limits is raising capital requirements for effluent treatment at chlorination facilities.
- Electrochemical Disinfection Substitution:On-site sodium hypochlorite generators are displacing delivered chemicals in large-scale desalination plants and industrial cooling systems.
Strategic Opportunities
- Rural Dispensing Innovation:Point-of-use tablet distribution through community health worker networks in India and Bangladesh bypasses centralized water infrastructure gaps.
- EU Green Deal Alignment:Carbon footprint disclosure requirements under CSRD are creating preference for solid-form disinfectants with lower transport emissions versus liquid alternatives.
- Smart Dosing Convergence:Integration of NaDCC tablets with IoT-enabled residual chlorine monitors enables automated replenishment in remote municipal systems.
Industry Challenges
- Prequalification Timeline Compression:WHO PQT certification for emergency-relief procurement now requires 18-24 month stability documentation, delaying market entry for new formulations.
- Cross-Contamination Protocols:Food-contact surface applications demand segregated production lines and HACCP validation that smaller compounders struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Dichloroisocyanurate Market |
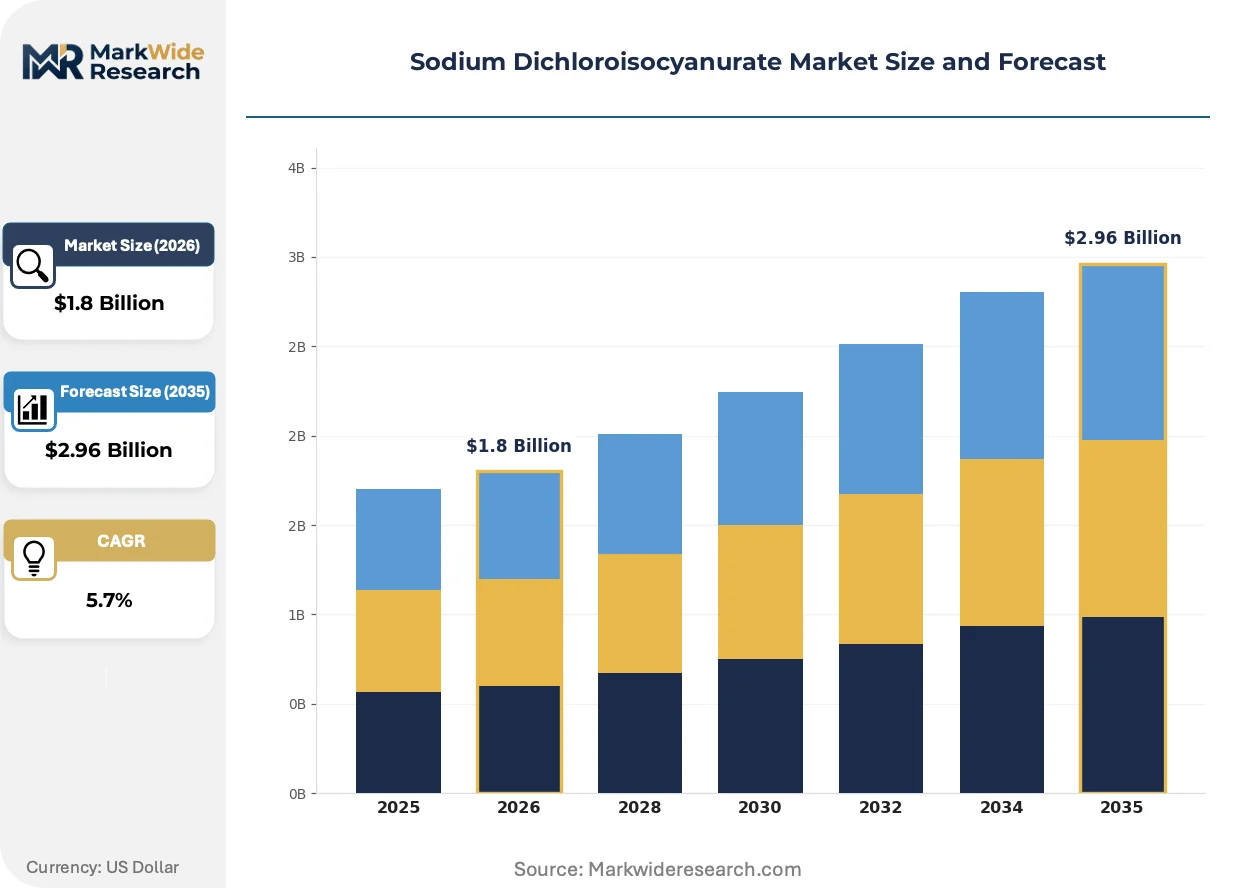
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Tablets, Powder, Liquid Application: Water Treatment, Pool Sanitization, Food Processing, Wastewater Treatment End User: Agriculture, Healthcare, Residential, Industrial Packaging Type: Bags, Drums, Bottles, Pails |
| Companies Covered | Occidental Petroleum Corporation, Heze Huayi Chemical Co., Ltd., Jiheng Chemical Co., Ltd., Haihang Industry, Zeel Product, Inner Mongolia Lantai Industrial Co., Ltd., Shikoku, Puyang Cleanway Chemicals, Lonza Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Dichloroisocyanurate Market Strategic Shifts
Formulation stability and dosing precision are becoming primary competitive differentiators as buyers shift from commodity procurement to certified supply agreements with documented chain-of-custody.
Effervescent tablet technology is absorbing market share from traditional granule formats in institutional water treatment applications. UNHCR and UNICEF procurement divisions are specifying rapid-dissolution tablets for refugee camp deployment. This absorption is compressing margins for powder-specialist compounders while rewarding integrated manufacturers with pharmaceutical-grade compaction capability.
EPA's revised FIFRA registration requirements for drinking-water disinfectants are tightening toxicological data standards for cyanurate residuals. The agency's 2023 guidance on cumulative exposure assessment is forcing reformulation of high-concentration tablets. Small-scale US registrants are responding by withdrawing from potable-water segments rather than absorbing new study costs.
Hospital procurement consortia are consolidating chemical purchasing through centralized pharmacy committees, displacing decentralized maintenance department buying. Group purchasing organizations in Brazil and Mexico are negotiating multi-year NaDCC supply contracts with price-indexing clauses. This concentration is most visible in Latin American tertiary care networks seeking to standardize infection control protocols across facility clusters.
Sodium Dichloroisocyanurate Market Segmentation
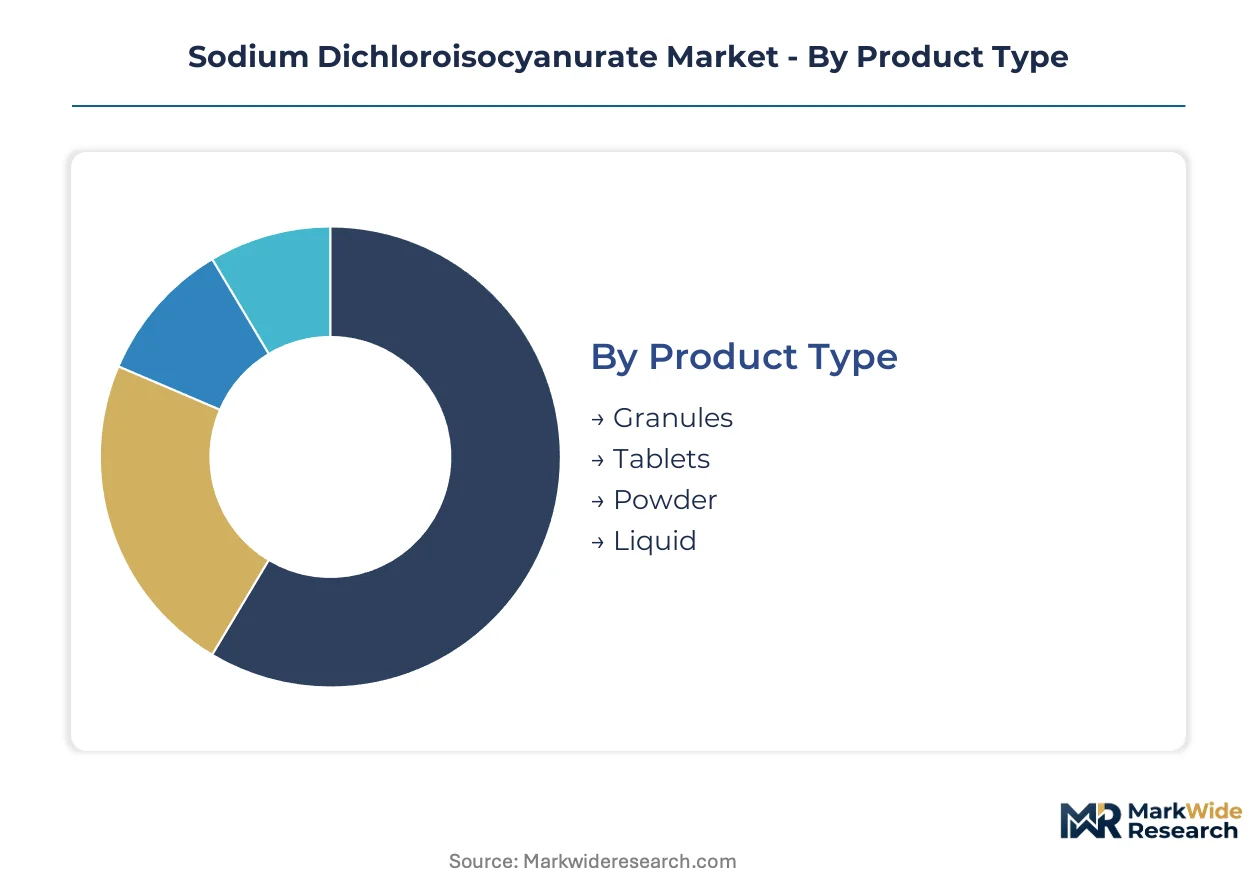
Formulation format dictates procurement economics and supply chain configuration across sodium dichloroisocyanurate applications. Tablet and granule variants command distinct margin profiles versus powder and liquid alternatives, with stability during tropical storage becoming the primary selection criterion for institutional buyers.
Product Type:
Volume deployment clusters around solid formats, while premium pricing attaches to precision-dosing configurations with certified stability documentation.
- Tablets:Compressed formulations with 56-60% available chlorine content enable exact dosing in municipal water systems and refugee camp deployments. WHO prequalification programs in sub-Saharan Africa specify rapid-dissolution tablets for emergency stockpiles, compressing margins for uncertified producers while rewarding integrated manufacturers with pharmaceutical-grade compaction lines.
- Granules:Irregular particle sizing between 0.5-2mm supports controlled dissolution in industrial cooling towers and agricultural irrigation systems. Southeast Asian hospitality operators prefer granule formats for pool maintenance, absorbing procurement share from calcium hypochlorite alternatives due to superior shelf life in humid climates.
- Powder:Fine-mesh formulations sustain margin pools in agricultural disinfection and bulk emergency-relief applications where handling flexibility outweighs dosing precision requirements.
- Liquid:Aqueous solutions occupy niche positions in automated dosing systems and food-contact surface applications requiring immediate availability without dissolution lag.
Mature deployment sits with granule formats in industrial cooling infrastructure. Newer deployment is concentrated in effervescent tablet configurations for institutional water treatment programs.
Application:
End-use concentration follows regulatory stringency gradients, with potable water certification requirements filtering supplier participation.
- Water Treatment:Municipal utilities deploy NaDCC as primary and secondary disinfectant under WHO drinking-water quality guidelines, with tablet formats dominating procurement in emerging economies replacing unstable hypochlorite stocks.
- Pool Sanitization:Warm-climate tourism economies show steepest expansion trajectory as hospitality operators standardize on chlorinated isocyanurates, particularly in Brazilian and Mexican resort clusters seeking to reduce inventory spoilage rates.
- Food Processing:HACCP-validated production lines and segregated manufacturing protocols constrain supplier entry for surface disinfection in meat and dairy processing facilities.
- Wastewater Treatment:Industrial effluent disinfection applications prioritize cost efficiency over certification grade, absorbing lower-specification powder formulations from secondary compounders.
Established volume flows through municipal water contracts. Accelerating uptake is visible in pool sanitization segments across Latin American tourism corridors.
End User:
Buyer sophistication varies sharply across sectors, with healthcare and industrial purchasers demanding documented chain-of-custody while agricultural buyers prioritize unit economics.
- Industrial:Cooling tower operators and process water managers specify granule formats with corrosion-inhibitor compatibility, negotiating multi-year supply contracts with price-indexing clauses through centralized procurement committees.
- Healthcare:Hospital pharmacy committees in Brazil and Mexico are consolidating chemical purchasing, displacing decentralized maintenance department buying and standardizing infection control protocols across facility clusters.
- Agriculture:Bulk powder procurement dominates irrigation system disinfection and livestock facility sanitation, with price sensitivity limiting penetration of premium tablet formats.
- Residential:Consumer-packaged tablets and granules for pool maintenance represent fragmented demand with seasonal concentration patterns.
Contractual depth is greatest in industrial accounts. Expansion opportunity concentrates in healthcare procurement consolidation across Latin American tertiary care networks.
Packaging Type:
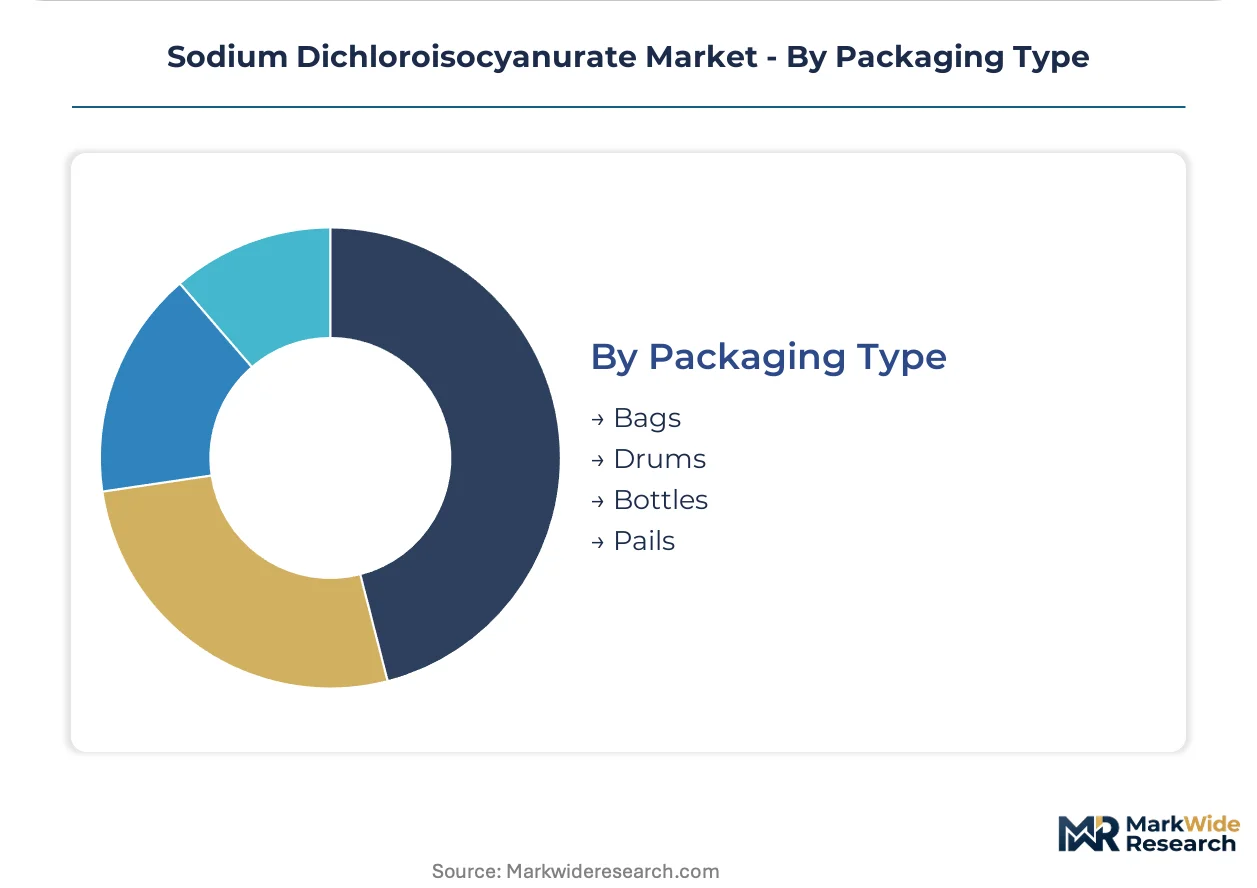
Handling requirements and inventory turnover rates determine format selection, with institutional buyers optimizing for storage density and dispensing automation.
- Drums:25-50kg steel and fiber containers serve municipal utilities and industrial facilities with automated dosing infrastructure, minimizing per-unit handling costs at volume scale.
- Bags:Multi-layer laminated sacks dominate agricultural and bulk relief-agency procurement, with UNHCR and UNICEF specifying tear-resistant constructions for tropical distribution.
- Bottles:Consumer-oriented tablet and granule packaging for residential pool maintenance and point-of-use water treatment in distributed retail channels.
- Pails:Intermediate 5-10kg plastic containers bridge institutional and commercial applications requiring moderate volume with manual handling convenience.
Standardized procurement runs through drum formats for integrated utilities. Emerging preference is visible in bag configurations for disaster-relief stockpiles and rural dispensing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal water authorities in tropical climates are consolidating procurement around certified tablet formulations as WHO prequalification requirements harden across emerging economies.
China
Heze Huayi Chemical Co., Ltd. and Jiheng Chemical Co., Ltd. anchor domestic production through backward integration into cyanuric acid feedstock. MEE enforcement of discharge limits on cyanuric acid byproducts raises capital requirements for effluent treatment at chlorination facilities. Shandong Province chemical clusters concentrate granule specialization for industrial cooling tower applications.
United States
EPA registration under FIFRA governs NaDCC sale for drinking-water treatment as the agency's 2023 guidance on cumulative exposure assessment forces reformulation of high-concentration tablets. Small-scale registrants withdraw from potable-water segments rather than absorbing new toxicological study costs. Texas and California municipal utilities drive tablet procurement for secondary disinfection compliance.
Brazil
Warm-climate tourism economies in São Paulo and Rio de Janeiro resort clusters show steepest pool sanitization expansion as hospitality operators replace unstable calcium hypochlorite inventories. Hospital procurement consortia consolidate chemical purchasing through centralized pharmacy committees across tertiary care networks. ANVISA food-contact surface regulations constrain supplier entry for meat and dairy processing applications.
Germany
Lonza Group Ltd. leverages its European manufacturing base to supply certified-grade tablets to WHO-prequalified programs across sub-Saharan Africa. REACH authorization pathways and EU Biocidal Products Regulation compliance accelerate substitution of liquid bleach in institutional food-contact applications. Bavarian chemical production clusters serve as distribution hubs for emergency-relief stockpiles.
India
Point-of-use tablet distribution through community health worker networks in Maharashtra and Gujarat bypasses centralized water infrastructure gaps in rural districts. BIS standards for drinking-water disinfectants filter supplier participation as procurement shifts from commodity buying to certified supply agreements. Agricultural irrigation systems in Punjab and Haryana absorb bulk powder formulations for livestock facility sanitation.
Sodium Dichloroisocyanurate Market Competitive Environment
Chinese producers anchor one tier; European specialists hold certified-grade positions for institutional procurement. The vendor base spans integrated chemical conglomerates with captive cyanuric acid supply and formulation-focused compounders serving niche applications. Three archetypes dominate: backward-integrated feedstock controllers, pharmaceutical-grade compaction specialists, and regional powder compounders competing on unit economics. Capacity expansion and WHO prequalification certification represent the dominant competitive moves as procurement consolidation favors documented chain-of-custody suppliers.
Among China-based producers, Heze Huayi Chemical Co., Ltd., Jiheng Chemical Co., Ltd., and Inner Mongolia Lantai Industrial Co., Ltd. exemplify the integrated manufacturing archetype with upstream control over sodium cyanurate supply. Lonza Group Ltd. occupies a position within the premium-tier certification vector, supplying WHO-prequalified tablets to multilateral health procurement bodies. Occidental Petroleum Corporation represents diversified chemical portfolio exposure to chlorinated isocyanurate demand through industrial chemicals divisions.
| Leading Market Players |
|---|
| Occidental Petroleum Corporation |
| Heze Huayi Chemical Co., Ltd. |
| Jiheng Chemical Co., Ltd. |
| Haihang Industry |
| Zeel Product |
| Inner Mongolia Lantai Industrial Co., Ltd. |
| Shikoku |
| Puyang Cleanway Chemicals |
| Lonza Group Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sodium cyanurate feedstock indices in Shandong Province cascade through chlorinated isocyanurate manufacturing into three distinct pricing tiers: WHO-prequalified tablet grades command certification premiums, industrial granule formats compete on unit economics, and bulk powder variants absorb residual demand from price-sensitive agricultural buyers.
Pricing Analysis
Volume-mass tablets for municipal water utilities trade at thin margins certified by WHO prequalification timelines, while precision-dosing effervescent formats for emergency relief capture premium spreads. Price differentiation rests on stability documentation depth and tropical-storage validation. Pricing pressure stems from Chinese MEE discharge compliance costs passing through to unintegrated compounders. Agricultural buyers in South Asia exhibit highest price sensitivity; Latin American hospital consortia show lowest.
Supply Chain Analysis
Skilled chemical process operator availability constrains expansion in Shandong and Jiangsu manufacturing clusters, capping output growth for integrated producers. Supply concentrates in China, Germany, and India, with cyanuric acid feedstock drawing from captive sodium cyanurate operations. Single-source vulnerability sits with Chinese upstream control over cyanuric acid supply. Distribution runs through drum formats for municipal utilities and multi-layer laminated bags for relief-agency procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA FIFRA registration and WHO PQT certification erect barrier-to-entry moats that reward incumbent investment in toxicological documentation and stability validation.
For Market Incumbents: Cement WHO prequalification positions by extending stability documentation to 24-month horizons before timeline compression hardens further. Defend against electrochemical disinfection substitution by integrating IoT-enabled residual monitoring into tablet dispensing systems. Prioritize backward integration into cyanuric acid feedstock to neutralize Chinese export quota volatility.
For New Entrants and Emerging Players: Begin with rural point-of-use distribution in Indian and Bangladeshi districts where centralized infrastructure gaps bypass incumbent utility relationships. Target community health worker networks as the most penetrable channel. Pursue BIS certification as the go-to-market anchor for institutional procurement migration.
For Investors and Strategic Acquirers: Distressed-cycle entries favor pharmaceutical-grade compaction specialists in European manufacturing corridors where REACH authorization sunk costs deter new competition. Five-to-ten year viability hinges on consolidation of certified supply agreements with multilateral health procurement bodies. Watch for MEE enforcement intensity in Shandong as the inflection signal for Chinese supply restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive cyanuric acid supply neutralizes feedstock quota exposure for Shandong producers. |
| WHO Prequalification Investment | Eighteen-month stability documentation opens emergency-relief procurement to UNHCR and UNICEF. |
| Effervescent Tablet Capacity | Pharmaceutical-grade compaction lines absorb share from traditional granule formats in institutional water treatment. |
| IoT Dosing Integration | Residual chlorine monitor convergence enables automated replenishment in remote municipal systems. |
| EU Green Deal Alignment | Carbon footprint disclosure under CSRD creates preference for solid-form transport efficiency versus liquid alternatives. |
Study Parameters
Independent corroboration across plant managers at chlorinated isocyanurate facilities, procurement leads at Brazilian hospital consortia, and distribution channel partners in Southeast Asia underwrites the qualitative findings. Primary interviews with technical R&D directors and downstream OEM procurement teams combined with secondary validation from customs/trade data, ACC/Cefic chemical industry reports, and SEC 10-K filings. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to historical municipal procurement cycles and industrial cooling tower maintenance patterns shaped the projection framework. Segmentation dimensions span formulation format, application end-use, and regional production hub clustering. CAGRs derive from installed base turnover rates and substitution elasticity between chlorinated isocyanurates and hypochlorite alternatives. Forecast inputs incorporate WHO prequalification timeline trajectories and MEE enforcement intensity scenarios.
Underlying measurement precision varies by segment; WHO-prequalified tablet volumes carry tighter precision than agricultural powder estimates given documentation transparency. Forecasts reflect assumptions on regulatory timeline adherence and feedstock quota stability. Material deviation in EPA FIFRA guidance revision or Chinese environmental enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Sodium Bisulphite Market
Disinfectants and Preservatives
Disinfectant Chemicals Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
Disinfectants Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Alcohol Based Disinfectants Market
Disinfectants and Preservatives
Global Cosmetic Preservatives Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
Surface Disinfectant Chemicals Market
Disinfectants and Preservatives
Disinfecting Wipes Market
Disinfectants and Preservatives
Preservatives Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
Sterilization Markers Market
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Fumigant Products Market