
 Italy Electric Vehicle Battery Materials Market | 2026-2036
Italy Electric Vehicle Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Electric Vehicle Battery Materials Market Insights
High-nickel cathode formulations are rotating toward dominance as Italian OEMs demand energy densities above 300 Wh per kilogram for next-generation electric platforms. Umicore leverages its European precursor supply network to anchor regional cathode active material flows. BASF competes through integrated R&D hubs in Germany that feed Italian battery cell pilot operations. Samsung SDI specializes in cylindrical cell architectures that constrain material purity specifications across Southern European supply chains.
Italy electric vehicle battery materials encompass refined active substances, electrolyte salts, separator coatings, and conductive additives engineered to precise electrochemical tolerances for lithium-ion cell fabrication, where nickel manganese cobalt cathodes currently occupy the largest value share due to their balance of energy density and cycle stability. Lithium iron phosphate segments are accelerating fastest among energy storage system applications, where thermal safety and extended cycle life outweigh gravimetric energy priorities. Pouch packaging formats dominate passenger vehicle procurement, while prismatic configurations concentrate within commercial vehicle contracts where volumetric efficiency and modular repairability command premium positioning.
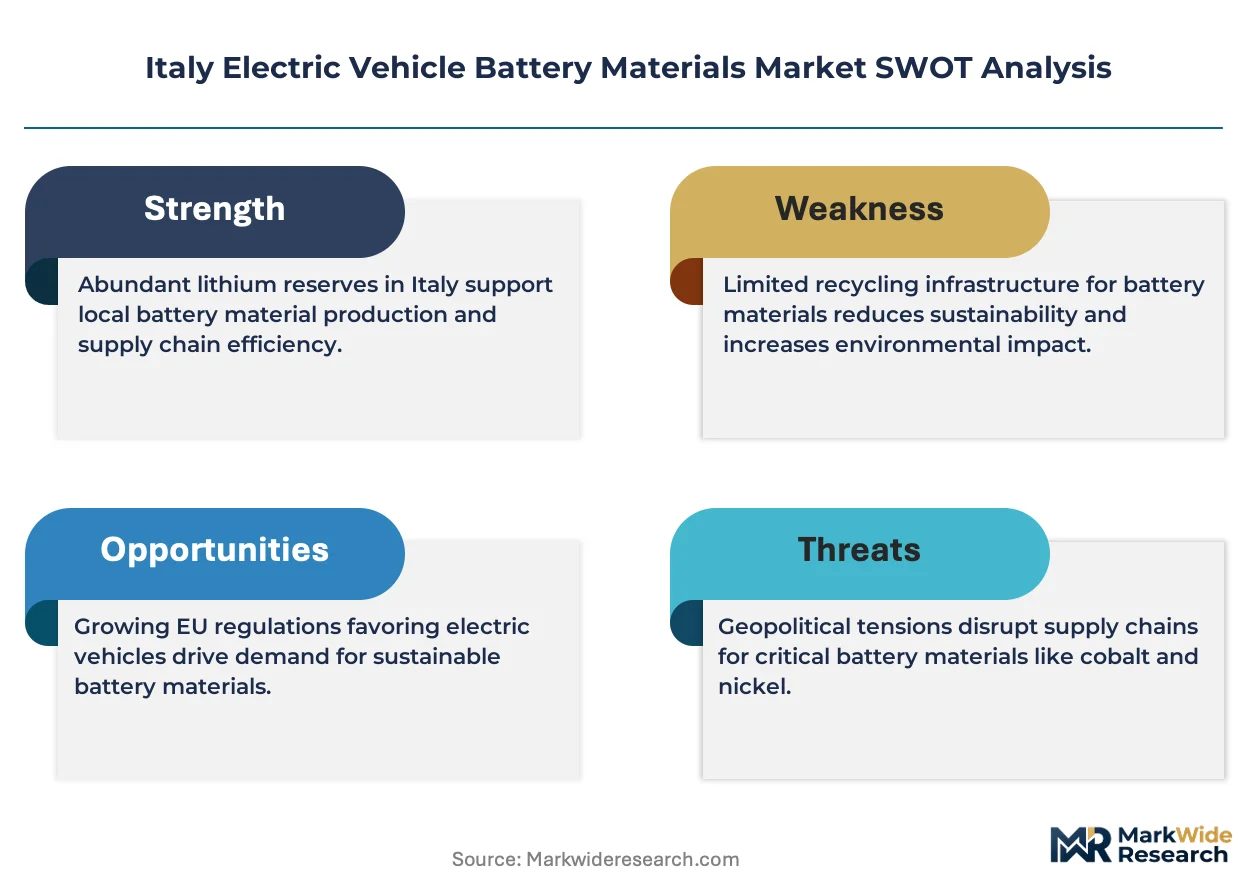
EU Battery Regulation mandates and CE marking requirements enforced by Italian market surveillance authorities are tightening carbon footprint disclosure and recycled content quotas for imported cell materials. REACH compliance administered by ECHA governs chemical substance registration across cathode precursor and electrolyte additive supply chains. Stakeholders must monitor how delegated acts under the EU Critical Raw Materials Act reshape sourcing obligations for nickel, cobalt, and lithium before committing to long-term offtake agreements or domestic refining investments.
Market Dynamics
The EU Battery Regulation's carbon footprint disclosure mandates and recycled content quotas are restructuring procurement protocols across Italian cathode and anode supply chains, forcing material suppliers to reconfigure precursor sourcing and certification workflows before 2027 compliance deadlines.
Growth Catalysts
- EU Critical Raw Materials Act:Delegated acts under this framework are accelerating domestic refining investments for nickel and lithium, reducing import dependency for Lombardy-based cell manufacturers.
- High-nickel cathode chemistry:Italian OEM specifications demanding energy densities above 300 Wh per kilogram are pulling advanced NMC formulations into pilot production lines faster than phosphate alternatives.
- Piedmont-Turin cluster concentration:Proximity to Stellantis and Ferrari engineering centers creates localized demand pull for automotive-grade separator coatings and conductive additives.
Market Restraints
- Lithium carbonate price volatility:Spot market swings for battery-grade lithium salts compress margin visibility for Italian electrolyte formulators locked into annual offtake contracts.
- Cathode precursor import concentration:Reliance on Finnish and German refiners for nickel sulfate and cobalt hydroxide exposes Italian material processors to single-source disruption risks.
- REACH compliance latency:ECHA substance registration timelines for novel electrolyte additives extend qualification cycles by 18-24 months, delaying commercialization of next-generation formulations.
Strategic Opportunities
- Sicily renewable energy corridor:Grid-scale storage deployments linked to solar and wind installations are creating dedicated demand channels for lithium iron phosphate cathode materials with 6,000+ cycle specifications.
- CE marking integration services:Third-party certification providers can capture value by bundling carbon footprint verification with recycled content auditing for imported cell materials.
- Solid-state electrolyte convergence:Sulfide and oxide ceramic separator technologies are opening qualification pathways for Italian specialty chemical producers with existing high-purity manufacturing assets.
Industry Challenges
- Electrochemical engineering talent scarcity:Italian universities produce insufficient graduates with lithium-ion cell design expertise to staff expanding R&D operations in Milan and Turin.
- Multi-standard certification complexity:Simultaneous compliance with EU Battery Regulation, REACH, and UN 38.3 transport testing creates documentation bottlenecks for material exporters serving both automotive and stationary storage segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Electric Vehicle Battery Materials Market |
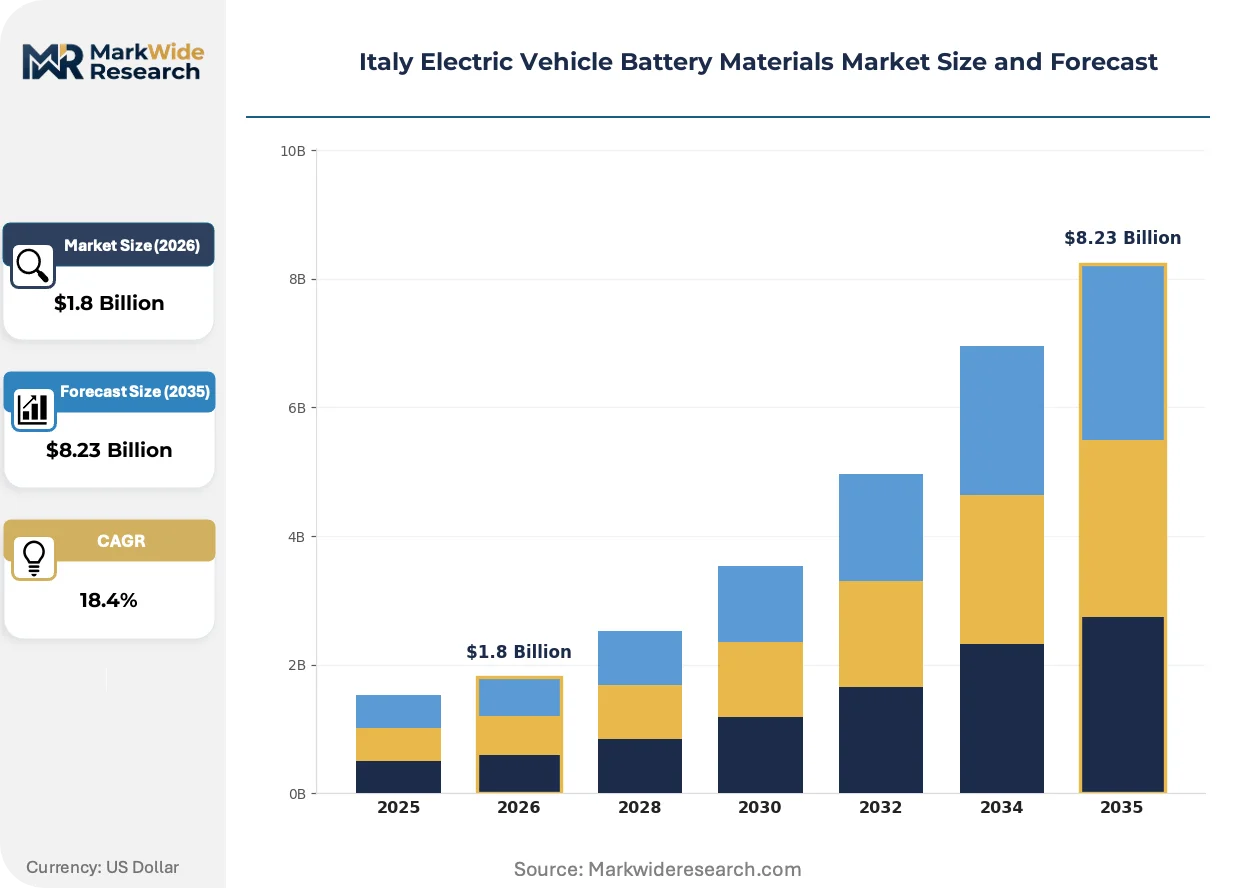
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium-Ion, Nickel Manganese Cobalt, Lithium Iron Phosphate, Graphite Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage Systems Packaging Type: Pouches, Cylindrical, Prismatic, Modules End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Sumitomo Chemical, BASF, Arkema, Solvay, Umicore, LG Chem, Samsung SDI, CATL, BYD, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Electric Vehicle Battery Materials Market Trends and Innovations
Material innovation trajectories in Italy are bifurcating between high-performance automotive specifications and cost-optimized stationary storage grades, with processing equipment and quality protocols diverging accordingly.
Solid-state electrolyte development is fragmenting the incumbent liquid electrolyte supply base. BMW and Stellantis engineering teams in Munich and Turin are qualifying sulfide-based ceramic separators for 2028 platform introductions. This chemistry transition is compressing demand for conventional carbonate solvents and lithium hexafluorophosphate salts in premium vehicle segments.
REACH authorization requirements for nickel compounds are tightening precursor handling standards across European refining operations. Italian cathode material importers must now document closed-loop wastewater treatment for nickel sulfate processing. Battery cell pilot lines in Lombardy are responding by qualifying Finnish and Belgian suppliers with pre-certified environmental management systems.
Long-term offtake contracting is displacing spot purchasing for lithium hydroxide and nickel sulfate. Tier-one Italian cathode producers are locking five-year supply agreements directly with Australian and Canadian mining operations, bypassing traditional trader intermediaries. This pattern is most visible in Piedmont, where Umicore and BASF feeding operations require volume certainty for high-nickel precursor production.
Italy Electric Vehicle Battery Materials Market Segmentation
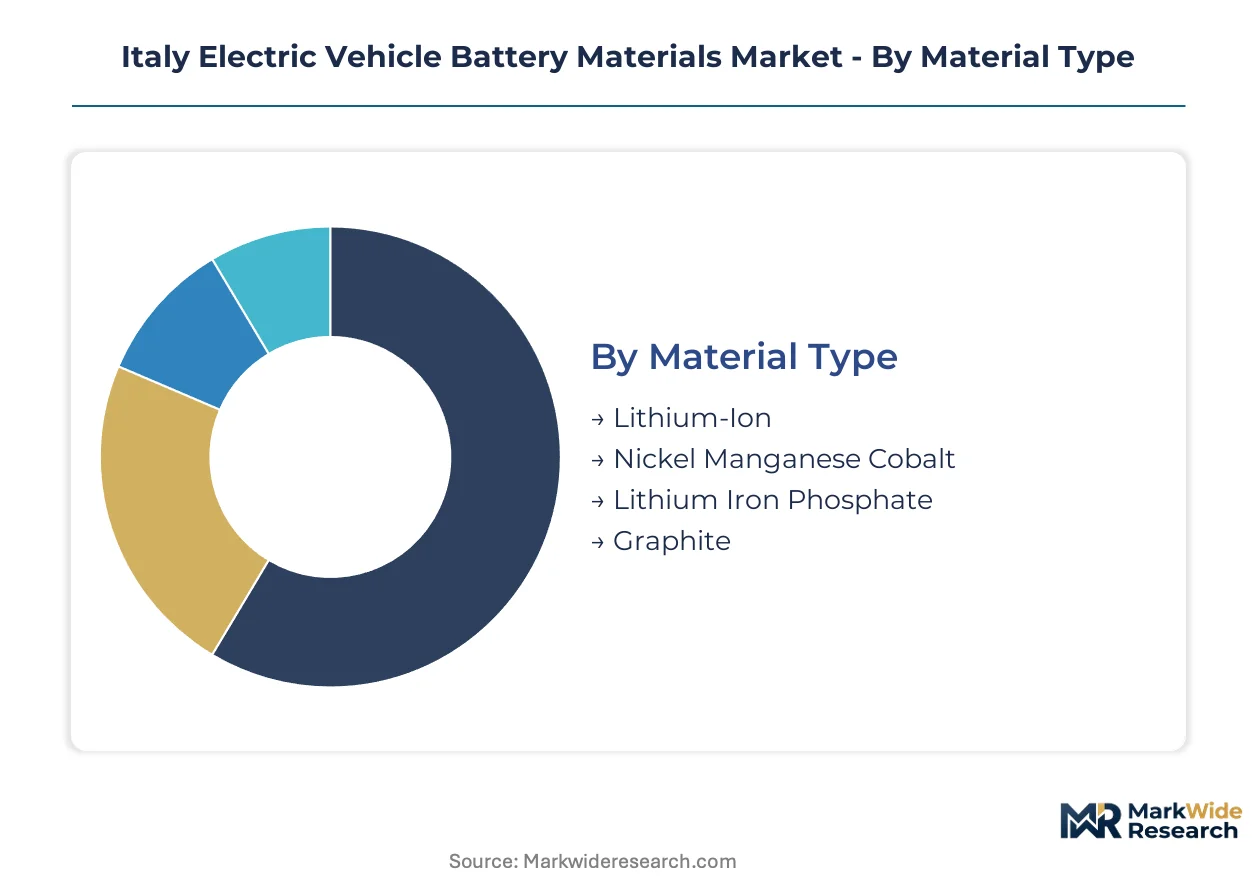
Material heterogeneity across the Italian battery supply chain demands precise segmentation mapping. Each dimension reveals distinct procurement patterns, certification requirements, and margin structures that shape supplier strategy.
Material Type:
Cathode and anode materials flow through differentiated channels—automotive OEMs procure high-nickel formulations via direct offtake, while energy storage developers source phosphate grades through distributor networks.
- Nickel Manganese Cobalt:High-nickel formulations exceeding 80% nickel content dominate premium automotive specifications. Stellantis and Ferrari engineering centers in Piedmont are pulling these materials into pilot production lines for next-generation platforms. Energy density requirements above 300 Wh per kilogram constrain supplier qualification to Umicore and BASF feeding operations.
- Lithium Iron Phosphate:Thermal stability and extended cycle life position this chemistry for stationary storage deployments. Sicily's renewable energy corridor is creating dedicated demand channels for 6,000+ cycle specifications. Grid-scale developers prioritize cost-per-kWh over gravimetric energy density.
- Lithium-Ion:Umbrella category encompassing liquid electrolyte systems with lithium hexafluorophosphate salts. Lombardy-based cell pilot lines consume these materials through annual volume contracts with German formulators.
- Graphite:Synthetic and natural anode materials processed to 99.95% purity for automotive-grade cells. Piedmont-Turin clustering supports localized qualification of spherical graphite suppliers.
By volume, Nickel Manganese Cobalt leads. By growth pace, Lithium Iron Phosphate is expanding most quickly.
Application:
End-use segmentation correlates directly with performance tiering—passenger vehicles demand premium energy density while commercial applications prioritize modular serviceability.
- Passenger Vehicles:Italian OEM specifications drive cathode material purity to six-nines standards. Pouch cell architectures dominate procurement, with Stellantis engineering teams in Turin qualifying separator coatings for 2028 platform introductions.
- Energy Storage Systems:Stationary deployments across Lombardy and Sicily favor lithium iron phosphate for thermal safety. Extended cycle specifications reduce lifetime cost calculations for grid-scale developers.
- Commercial Vehicles:Prismatic configurations enable modular repairability for bus and truck fleets. Volumetric efficiency commands premium positioning in this segment.
- Two-Wheelers:Cost-optimized cylindrical cells constrain material specifications to standard-grade cathode powders. Aftermarket battery replacement cycles create recurring demand channels.
Passenger vehicles generate the largest revenue pool. Energy storage systems show the steepest expansion trajectory.
Packaging Type:
Cell geometry determines material handling requirements and quality protocols—pouch formats demand precision coating while cylindrical cells standardize around purity specifications.
- Pouches:Laminated aluminum-plastic enclosures dominate Italian passenger vehicle procurement. Separator coating uniformity becomes critical for cycle life performance in Milan-based pilot lines.
- Prismatic:Hard-shell aluminum housings concentrate within commercial vehicle contracts. Modular stacking enables repairability that fleet operators value.
- Cylindrical:Standardized 21700 and 4680 formats constrain material purity tolerances. Samsung SDI supply chains across Southern Europe favor this geometry.
- Modules:Pre-assembled cell groups with integrated battery management systems. Tier-1 suppliers in Piedmont specialize in module-level integration for OEM direct delivery.
Pouch formats hold revenue leadership. Cylindrical cells are gaining share fastest in cost-sensitive applications.
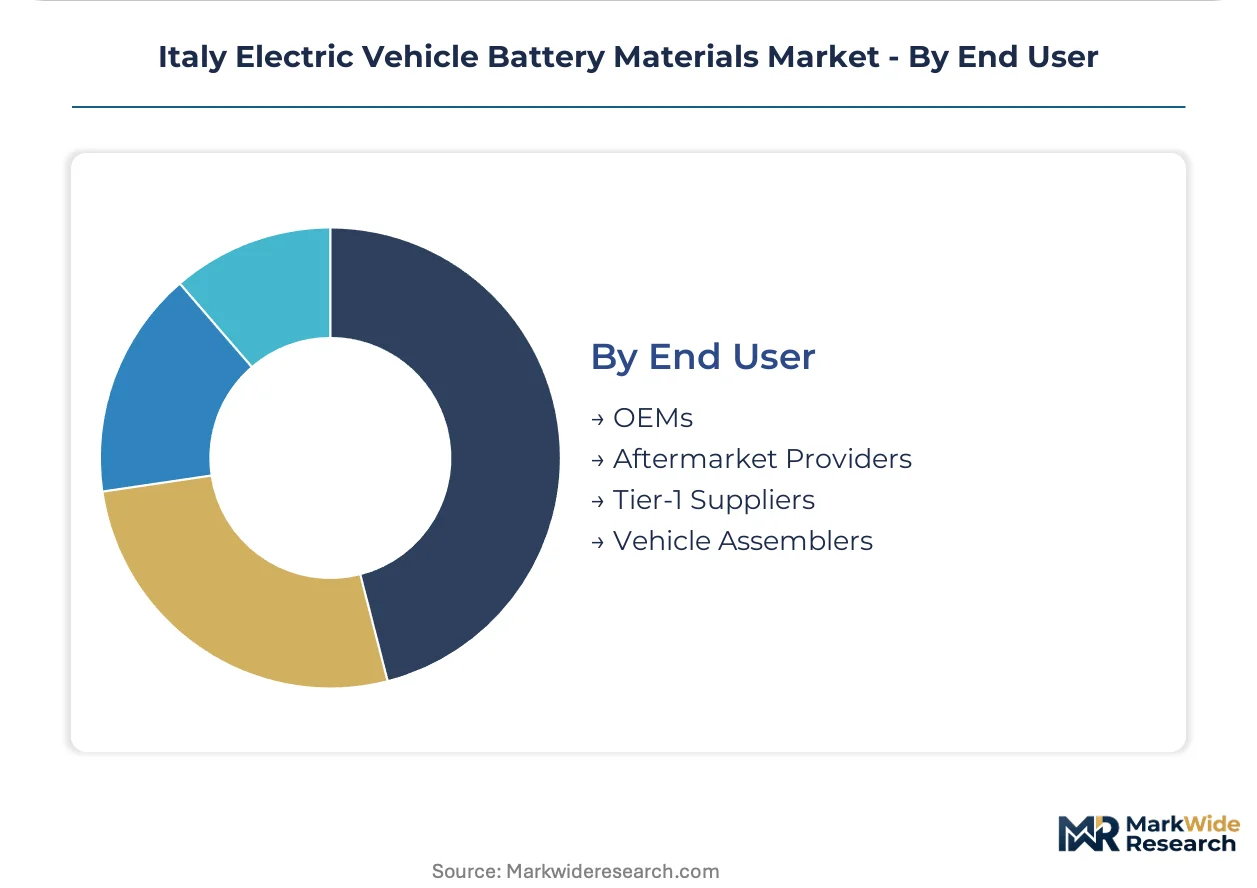
End User:
Customer type segmentation reveals procurement power concentration—OEMs negotiate multi-year offtake while aftermarket channels fragment across distributor networks.
- OEMs:Stellantis and Ferrari maintain direct cathode material relationships with European precursor suppliers. Five-year volume agreements bypass traditional trader intermediaries for nickel sulfate and lithium hydroxide.
- Tier-1 Suppliers:Battery system integrators in Lombardy purchase separator coatings and conductive additives through qualified vendor lists. REACH compliance documentation gates supplier approval.
- Vehicle Assemblers:Smaller automotive manufacturers procure pre-qualified cell modules. CE marking requirements enforced by Italian market surveillance authorities constrain sourcing flexibility.
- Aftermarket Providers:Independent service networks source replacement cells through distributor channels. Price sensitivity limits material specification tiers in this segment.
OEMs command the largest procurement volumes. Aftermarket providers exhibit the most rapid channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish refiners export nickel sulfate to Lombardy-based cathode producers, establishing the dominant trade corridor for Italy's battery material supply chain. German precursor suppliers feed Piedmont-Turin automotive clusters through dedicated rail and road logistics networks. Belgian environmental management certification is becoming a gatekeeping standard for Italian importers.
Germany
BASF operates integrated R&D hubs that supply Italian battery cell pilot lines with qualified cathode precursors. REACH compliance administered by ECHA governs chemical substance registration for electrolyte additives crossing the border. Stuttgart and Ludwigshafen engineering centers coordinate directly with Turin-based Stellantis teams on next-generation material specifications.
Finland
Nickel sulfate refineries serve as the primary upstream source for Italian high-nickel cathode formulations. The country's national mining regulator enforces closed-loop wastewater treatment standards that Italian importers now demand in supplier contracts. Harjavalta processing facilities maintain dedicated output allocations for Lombardy cell manufacturers.
Belgium
Umicore leverages its European precursor supply network to anchor regional cathode active material flows into Northern Italy. CE marking integration services bundled with carbon footprint verification are emerging from Antwerp-based certification providers. Hoboken refining operations pre-qualify environmental management systems that satisfy Italian market surveillance authority requirements.
France
Arkema and Solvay specialty chemical operations supply separator coatings and electrolyte salts to Milan-based pilot production lines. The EU Battery Regulation's delegated acts are reshaping French exporter documentation workflows for recycled content quotas. Lyon chemical engineering clusters coordinate with Piedmont automotive R&D centers on solid-state electrolyte qualification pathways.
China
CATL and BYD cell manufacturing scale creates price benchmarks that constrain Italian material procurement negotiations. The Ministry of Industry and Information Technology's dual carbon goals are tightening export documentation for lithium hydroxide shipments. Fujian and Guangdong precursor producers compete for Italian offtake through trader intermediaries despite growing direct contracting trends.
Italy Electric Vehicle Battery Materials Market Competitive Landscape
Listed leaders compete with private specialists across material purity tiers, creating a bifurcated supply base where scale advantages clash with customization capabilities. European chemical conglomerates anchor the premium cathode precursor segment through integrated refining networks. Asian battery specialists occupy the cylindrical cell material channel with standardized purity specifications. Three archetypes dominate: integrated chemical majors, battery-dedicated material suppliers, and automotive-captive processors. Competitive moves concentrate on long-term offtake contracting and REACH pre-certification investments.
Among European-integrated chemical groups, BASF and Umicore exemplify the precursor-to-cathode value chain archetype with established feeding operations. Solvay and Arkema occupy positions within the specialty electrolyte and separator coating tier, representing French chemical engineering capabilities. Samsung SDI anchors the Asian battery specialist archetype, its cylindrical cell focus constraining material specifications across Southern European supply chains. Sumitomo Chemical sits within the diversified Japanese material supplier tier, its position reflecting cross-regional qualification protocols.
| Leading Market Players |
|---|
| Sumitomo Chemical |
| BASF |
| Arkema |
| Solvay |
| Umicore |
| LG Chem |
| Samsung SDI |
| CATL |
| BYD |
| Others |
Pricing and Supply Chain Analysis
Sixty-day nickel sulfate inventory buffers at Lombardy cathode plants concentrate pricing power with Finnish and German refiners, compressing margin negotiation leverage for Italian formulators locked into annual offtake structures. This lead-time exposure ties procurement cost volatility directly to the geographic clustering of European precursor capacity.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake as the dominant pricing structure, with Stellantis and Ferrari procurement teams negotiating five-year volume agreements for high-nickel cathode materials. Price differentiation stems from REACH certification tier and volume scale, with pre-qualified suppliers commanding premium positioning over spot-market alternatives. Cost compression in standard-grade phosphate materials is intensifying because grid-scale storage developers prioritize cost-per-kWh over energy density specifications. Aftermarket providers exhibit the highest price sensitivity, while automotive OEMs accept premium positioning for six-nines purity cathode formulations.
Supply Chain Analysis
Finland and Germany anchor nickel sulfate and cobalt hydroxide refining for Italian cathode production, with Harjavalta and Ludwigshafen facilities maintaining dedicated output allocations for Lombardy cell manufacturers. The supply chain draws from Australian spodumene concentrate and Canadian lithium hydroxide for lithium inputs, alongside Belgian environmental management certification as a gatekeeping standard. Single-source vulnerability concentrates in Finnish nickel sulfate supply, where Harjavalta processing disruptions would cascade through Piedmont-Turin automotive clusters. Distribution runs through qualified vendor lists managed by Tier-1 battery system integrators in Milan and Turin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as solid-state electrolyte chemistry threatens to displace conventional liquid electrolyte and separator coating demand from 2028 platform introductions onward.
For Market Incumbents: Compound REACH pre-certification investments with backward integration into lithium hydroxide refining to secure volume certainty for high-nickel precursor production. Lock five-year offtake agreements directly with Australian and Canadian mining operations before delegated acts under the EU Critical Raw Materials Act reshape sourcing obligations. Solid-state electrolyte convergence represents the primary technology substitution threat requiring qualification pathway diversification. For New Entrants and Emerging Players: Differentiate on CE marking integration services bundled with carbon footprint verification and recycled content auditing for imported cell materials. White-space targets concentrate in Sicily's renewable energy corridor, where grid-scale storage deployments create dedicated demand channels for lithium iron phosphate cathode materials with extended cycle specifications. Target energy storage system developers through distributor networks rather than competing for automotive OEM direct relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from European chemical conglomerates seeking to divest non-core specialty chemical operations with existing high-purity manufacturing assets applicable to sulfide and oxide ceramic separator technologies. Long-term viability favors suppliers with demonstrated qualification pathways for solid-state electrolyte convergence and pre-established environmental management certification. The signal to watch is BMW and Stellantis engineering team qualification timelines for 2028 platform introductions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Refining | Volume certainty for Lombardy high-nickel precursor production secures against spot market volatility. |
| REACH Pre-Certification Investment | ECHA substance registration timelines for novel electrolyte additives compress competitive qualification cycles. |
| Long-Term Supply Agreement | Five-year offtake contracts with Australian mining operations bypass trader intermediaries for nickel sulfate. |
| CE Marking Integration Service | Carbon footprint verification bundled with recycled content auditing captures value from EU Battery Regulation mandates. |
| Solid-State Electrolyte Qualification | Sulfide-based ceramic separator pathways open for Italian specialty chemical producers with high-purity assets. |
Research Methodology
A spread of perspectives from cathode material procurement directors, electrolyte formulation R&D leads, Tier-1 battery system integrators, and Italian market surveillance authority officials converged on the working assumptions. Primary fieldwork combined with secondary validation from ECHA substance registration databases, EU Battery Regulation delegated acts documentation, and customs trade data for nickel sulfate and lithium hydroxide flows. Bottom-up cell production capacity modeling triangulated against top-down automotive OEM platform introduction timelines.
Material type, application, packaging format, and end-user segmentation dimensions shaped the analytical framework across the projection horizon. CAGRs derived from volume-weighted average growth trajectories for high-nickel cathode formulations and lithium iron phosphate storage grades. Forecast inputs incorporated Stellantis and Ferrari engineering center qualification timelines alongside Sicily renewable energy corridor deployment schedules.
Decision-makers should treat outputs as directional under base assumptions of EU Battery Regulation compliance timeline adherence and solid-state electrolyte platform introduction schedules; material deviation would warrant model refresh. Recalibration cycles align with shifts in ECHA substance authorization timelines and delegated acts under the EU Critical Raw Materials Act.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Prismatic Lithium Cobalt Oxide (LiCoO2) Battery Market
Lithium-ion Battery
France SLI Battery Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Lithium Iodide Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Aluminium Ion Battery Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
Ternary Lithium Battery Market
Lithium-ion Battery
Silicon Anode Battery Market