
 Global Hydraulic Submersible Pump Market | 2026-2036
Global Hydraulic Submersible Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulic Submersible Pump Market Outlook
API 610 and ISO 2858 compliance tiers is redrawing competitive boundaries in hydraulic submersible pump procurement. Xylem Inc. leverages its vertical integration in hydraulic power unit manufacturing to control lead times on high-specification slurry configurations. Sulzer Ltd. anchors its position through R&D intensity in wear-resistant metallurgy for mining dewatering applications. Weir Group PLC dominates the project pump segment through manufacturing scale at its foundry operations in Scotland and Malaysia.
A hydraulic submersible pump converts pressurized hydraulic fluid from a surface power unit into mechanical rotation at the pump end, operating at depths where electric motors risk seal failure or explosion; typical specifications range from 5 to 500 horsepower with discharge heads exceeding 150 meters, purpose-built for abrasive slurry handling and high-volume dewatering in confined excavations. Sewage pumps and slurry pumps carry the deepest margin pools due to metallurgical complexity and aftermarket parts dependency, while utility pumps face commoditization pressure from Asian manufacturers. The dewatering application segment leads volume, though flood control installations in coastal municipalities are expanding fastest as climate adaptation budgets harden.
The EPA enforces Clean Water Act effluent standards that mandate sealed submersible designs in U.S. municipal wastewater systems, while China's MEE implements GB standards for groundwater extraction that restrict pump efficiency thresholds in Yellow River watershed projects. The EU's F-Gas Regulation and Ecodesign Directive progressively constrain hydraulic fluid formulations and motor efficiency classes, forcing redesign cycles among European suppliers. Stakeholders must monitor how regional carbon border adjustments reshape sourcing economics for cast iron housings and high-chrome impellers sourced from divergent regulatory jurisdictions.
Market Dynamics
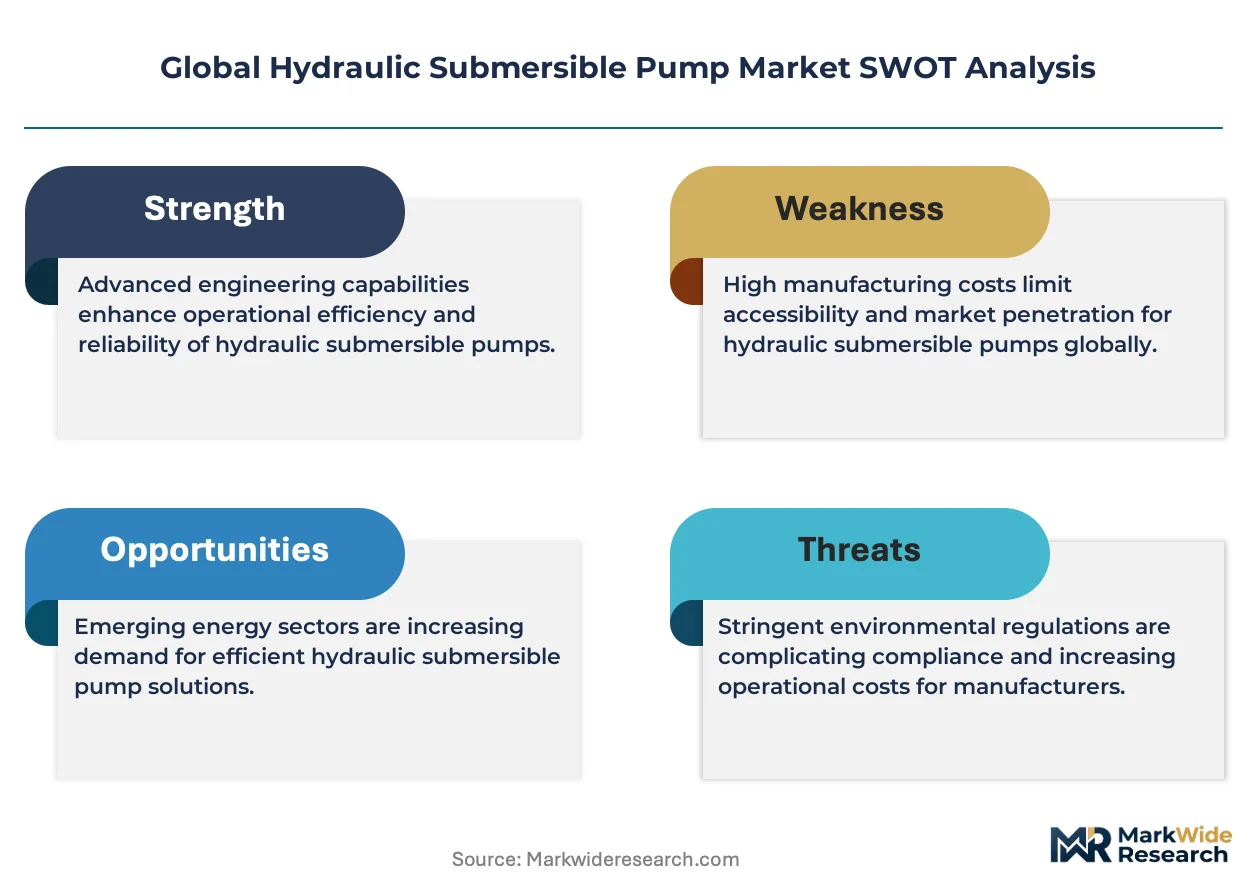
The hydraulic submersible pump market is experiencing structural pressure from API 610 and ISO 2858 compliance tiers that are redrawing competitive boundaries, forcing manufacturers to consolidate certification capabilities or exit high-specification segments entirely.
Growth Catalysts
- EPA Clean Water Act enforcement:Municipal wastewater systems across the United States are accelerating replacement cycles of sealed submersible designs to meet effluent standards, creating sustained equipment refresh demand.
- China's Yellow River Basin water conservancy:Large-scale infrastructure deployment under national water security mandates is driving procurement of higher-capacity hydraulic units for flood control and irrigation.
- India's National Jal Jeevan Mission:Rural water supply schemes are expanding distributed pumping networks, requiring robust submersible solutions for groundwater extraction in remote locations.
Market Restraints
- High-chrome alloy cost volatility:Abrasive slurry applications depend on wear-resistant metallurgy whose input costs fluctuate with nickel and chromium commodity markets, compressing margin stability.
- European foundry concentration:Critical cast iron housing supply clusters in Germany and Italy create geographic single-point vulnerability for just-in-time manufacturing.
- Hydraulic fluid formulation constraints:The EU's F-Gas Regulation progressively restricts acceptable fluid chemistries, forcing costly reformulation cycles without performance guarantees.
Strategic Opportunities
- Indonesia's coastal flood defense expansion:Climate adaptation budgets in Jakarta and Surabaya are hardening, opening municipal dewatering procurement to international suppliers with slurry-handling expertise.
- Remanufacturing and aftermarket services:Mining dewatering operators in Australia's Pilbara region are unbundling maintenance contracts, creating recurring revenue streams independent of new equipment sales.
- Hybrid hydraulic-electric architectures:Convergence of surface power unit efficiency gains with submersible pump durability is enabling new product categories for confined excavation safety.
Industry Challenges
- API 610 certification timeline compression:Third-party verification queues for high-specification slurry configurations now extend 14-18 months, delaying project revenue recognition.
- Legacy system integration complexity:Municipal utilities in older European infrastructure zones face hydraulic power unit incompatibility with existing surface equipment, raising total cost of ownership.
- Specialized welding technician scarcity:Duplex stainless steel fabrication for corrosion-resistant pump ends requires certified ASME Section IX welders whose training pipelines remain underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulic Submersible Pump Market |
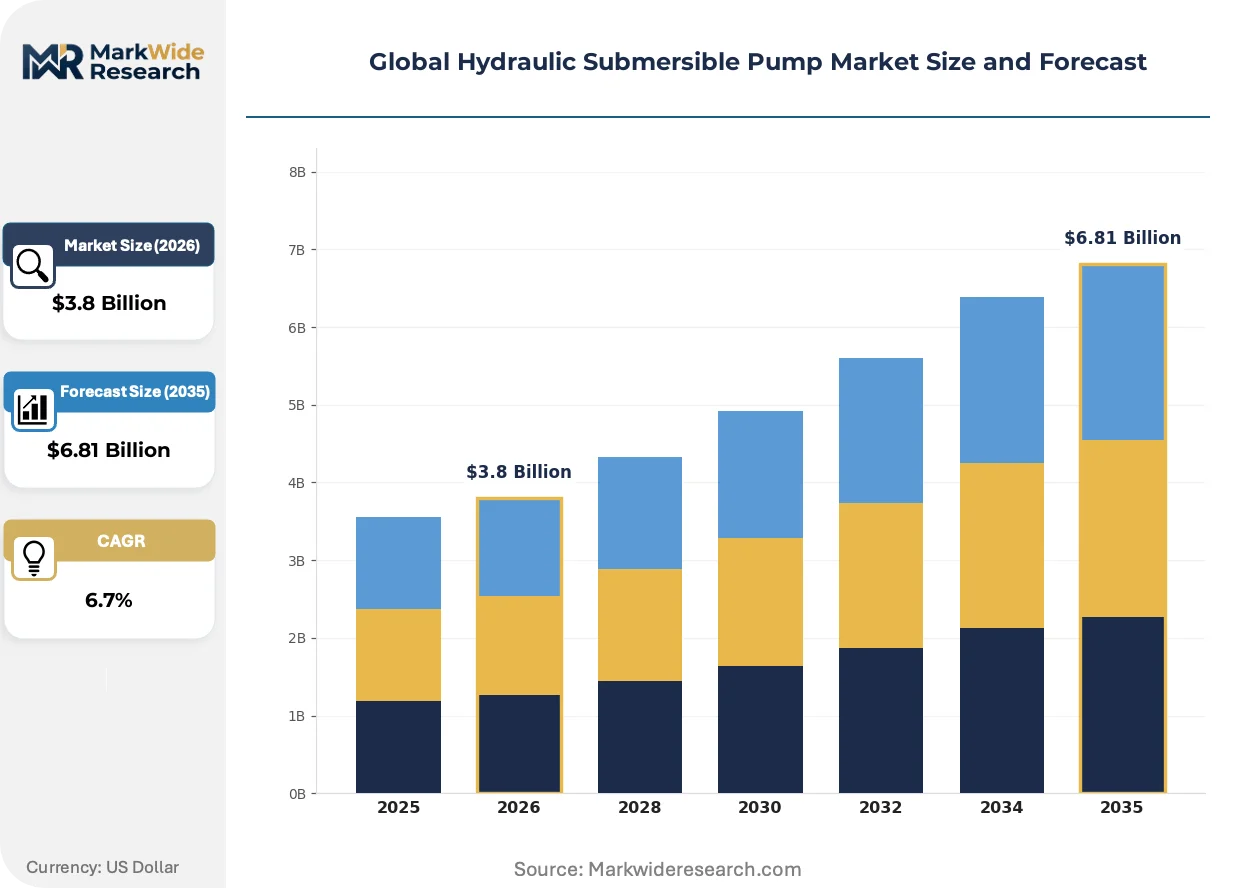
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Utility Pumps, Sewage Pumps, Slurry Pumps, Project Pumps End User: Agriculture, Mining, Construction, Municipal Application: Water Supply, Flood Control, Irrigation, Dewatering Technology: Electric, Diesel, Solar, Hybrid |
| Companies Covered | Xylem Inc., Sulzer Ltd., Weir Group PLC, Atlas Copco AB, Tsurumi Manufacturing Co., Ltd., Grindex AB, Gorman-Rupp Company, Franklin Electric Co. Inc., KSB SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulic Submersible Pump Market Strategic Shifts
Material science advances and regulatory chemistry constraints are actively reshaping product development priorities, while buyer behavior shifts toward unbundled service models are restructuring vendor economics across the value chain.
Ceramic-matrix composite impeller coatings are fragmenting traditional metallurgy hierarchies in abrasive slurry applications. Mining dewatering operators in Western Australia's iron ore districts are piloting these surfaces at scale, displacing high-chrome white iron in high-wear zones. The technology is fragmenting aftermarket parts dependency patterns that previously locked buyers into OEM service contracts.
The EU's Ecodesign Directive and F-Gas Regulation are jointly constraining hydraulic fluid formulations and motor efficiency classes, forcing European suppliers into simultaneous redesign cycles. Industrial consequence includes accelerated R&D spend on biodegradable hydraulic fluids with equivalent viscosity indexes. Mining and municipal segments in Germany, France, and the Netherlands face the steepest compliance cost absorption.
Rental and lease-to-own arrangements are displacing outright equipment purchase in North American municipal dewatering procurement. Equipment distributors in Texas and Florida are building captive service fleets, capturing recurring revenue streams previously retained by manufacturer service arms. This shift is most visible in flood-prone coastal municipalities where capital budget volatility makes operational expenditure models preferable.
Global Hydraulic Submersible Pump Market Segmentation
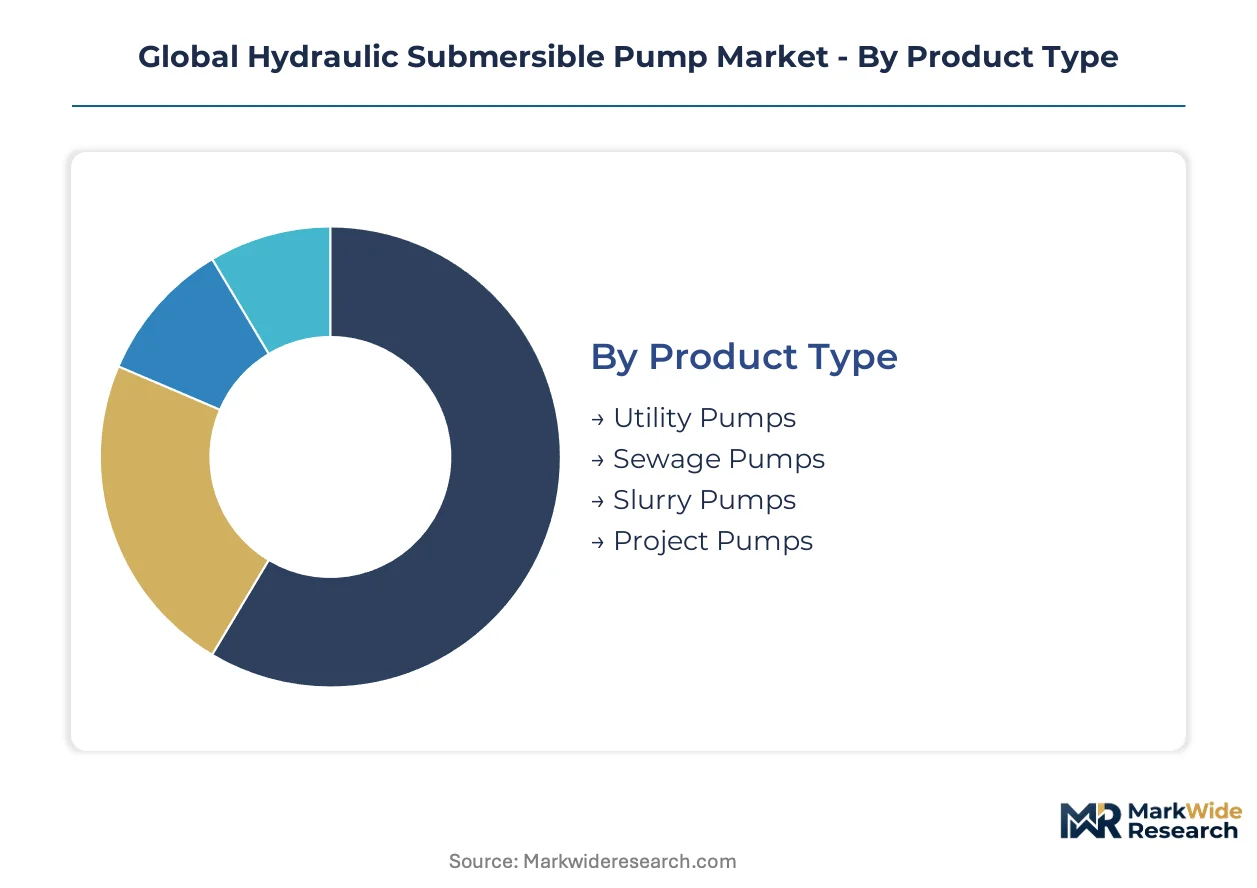
Segmentation in hydraulic submersible pumps reveals how channel economics fragment across specification tiers. Distribution pathways diverge sharply between commoditized utility units and engineered project pumps requiring application engineering support.
Product Type:
Channel mix splits between stock-and-ship distributors for standardized units and direct manufacturer engagement for engineered configurations. Utility and sewage pumps flow through regional equipment distributors with local inventory, while slurry and project pumps route through manufacturer-direct channels with embedded technical sales.
- Utility Pumps:Compact units rated below 50 horsepower for general dewatering and drainage tasks. Procurement concentrates through rental fleet operators in Texas and Florida municipalities where flood response requires rapid equipment deployment. Asian manufacturers compress margins through high-volume production of standardized cast iron housings.
- Sewage Pumps:Sealed submersible designs handling raw wastewater with solids passage capability above 75 millimeters. Municipal procurement in coastal U.S. cities accelerates replacement cycles under EPA Clean Water Act enforcement, creating sustained demand for explosion-proof configurations.
- Slurry Pumps:High-chrome alloy impellers engineered for abrasive iron ore and copper tailings.
- Project Pumps:Custom-engineered units above 500 horsepower for major infrastructure deployments.
By volume, utility pumps lead. By growth pace, sewage pumps are expanding most quickly.
End User:
Cost tier segmentation separates price-sensitive agricultural buyers from specification-driven mining operators. Municipal procurement sits between these poles, balancing capital constraints with regulatory compliance mandates.
- Mining:Underground and open-pit dewatering operations demanding continuous-duty reliability in abrasive conditions. Australia's Pilbara iron ore districts and Chile's copper belt concentrate procurement of high-chrome slurry configurations with wear-resistant metallurgy. Unbundled maintenance contracts in Western Australia create aftermarket revenue independence from new equipment sales.
- Municipal:Wastewater collection systems and stormwater infrastructure requiring sealed submersible designs. Coastal municipalities in the United States and Indonesia's Jakarta flood defense expansion drive procurement of higher-capacity units as climate adaptation budgets harden.
- Construction:Temporary dewatering for foundation excavations and tunneling projects.
- Agriculture:Groundwater extraction for irrigation networks, primarily in India's National Jal Jeevan Mission rural schemes.
By revenue contribution, mining dominates. By expansion trajectory, municipal is gaining share fastest.
Application:
Volume concentration in dewatering reflects construction and mining cyclicality, while application maturity varies across flood control infrastructure buildouts.
- Dewatering:Groundwater control for excavations, tunnels, and mine shafts. Construction activity in Germany and foundation work in China's Yellow River Basin water conservancy projects sustain equipment utilization rates. Rental penetration runs highest here as project-based demand favors operational expenditure models.
- Flood Control:Emergency and permanent installations for coastal protection and urban stormwater management. Municipal procurement in Surabaya and U.S. Gulf Coast cities accelerates as climate adaptation budgets shift from capital planning to committed spending.
- Water Supply:Potable water extraction and distribution network boosting.
- Irrigation:Agricultural water delivery systems, particularly in India's rural schemes.
By installed base, dewatering leads. By policy tailwinds, flood control shows the steepest expansion trajectory.
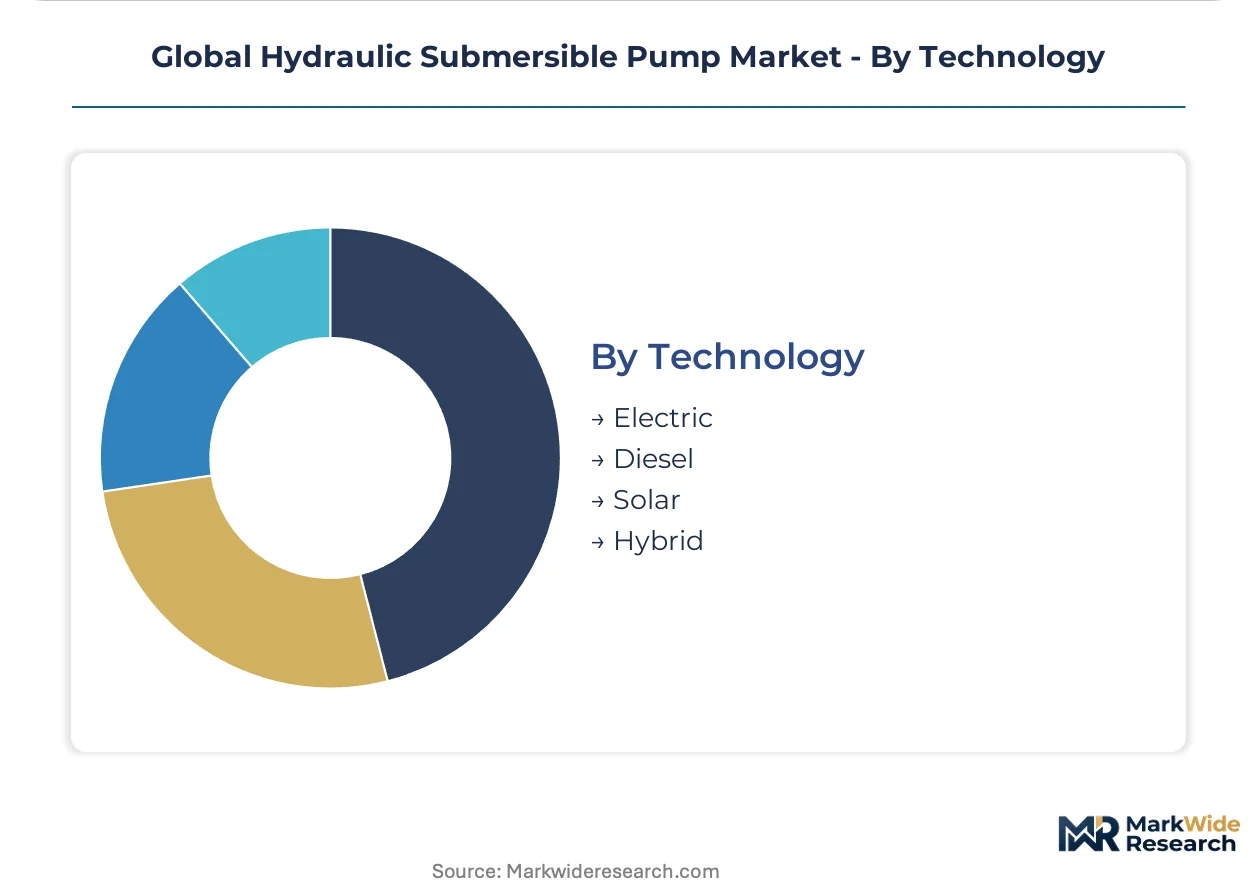
Technology:
Supply concentration in diesel power units is fragmenting as solar-hybrid architectures gain technical viability for remote deployment.
- Diesel:Surface power units delivering hydraulic fluid to submersible pump ends through umbilical lines. Mining operations in Western Australia and municipal fleets in Florida rely on diesel for mobility and independence from grid infrastructure. Emissions regulations in the EU and California compress deployment timelines for non-compliant engines.
- Hybrid:Convergent architectures combining diesel prime movers with electric regeneration or solar augmentation. Pilots in Australia's Pilbara and remote Indian water supply schemes test operational viability where fuel logistics dominate total cost of ownership calculations.
- Electric:Grid-tied or generator-backed surface power units for fixed installations.
- Solar:Photovoltaic-powered surface units for off-grid groundwater extraction.
By current deployment share, diesel leads. By technology transition momentum, hybrid is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's rural water schemes demonstrate acute price sensitivity on standardized utility pumps, while mining operators in Western Australia absorb premium pricing for wear-resistant slurry configurations without volume elasticity.
United States
Coastal municipalities from Houston to Miami are accelerating procurement of higher-capacity flood control units as stormwater infrastructure budgets harden. The EPA enforces Clean Water Act effluent standards that mandate sealed submersible designs in municipal wastewater systems. Equipment distributors in Texas and Florida are building captive rental fleets to capture recurring revenue from flood-prone cities.
China
The Yellow River Basin water conservancy projects are driving sustained demand for large-scale hydraulic units in flood control and irrigation applications. The MEE implements GB standards for groundwater extraction that restrict pump efficiency thresholds in watershed projects. Manufacturing clusters in Shandong Province are scaling foundry capacity for cast iron housings serving domestic infrastructure deployment.
Germany
Municipal utilities in older industrial zones face hydraulic power unit incompatibility with existing surface equipment, raising total cost of ownership for replacement cycles. The EU's F-Gas Regulation and Ecodesign Directive constrain hydraulic fluid formulations and motor efficiency classes, forcing costly redesign cycles. Foundry operations in North Rhine-Westphalia remain critical supply nodes for European pump manufacturers.
Australia
Mining dewatering operators in Western Australia's Pilbara iron ore districts are unbundling maintenance contracts, creating aftermarket revenue streams independent of new equipment sales. The country's national environmental regulator enforces strict groundwater management protocols that favor durable submersible configurations. Perth-based equipment distributors are piloting ceramic-matrix composite impeller coatings at scale.
Indonesia
Climate adaptation budgets in Jakarta and Surabaya are hardening, opening municipal dewatering procurement to international suppliers with slurry-handling expertise. The national infrastructure ministry is channeling funds into permanent flood control installations after repeated seasonal inundations. Local contractors are partnering with foreign manufacturers to meet technical specifications for high-volume coastal protection systems.
Global Hydraulic Submersible Pump Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with specification-driven mining applications rewarding metallurgical R&D intensity while municipal utility procurement favors manufacturing scale and distribution reach. The market structure consolidates around three tiers: integrated multinationals with captive foundry capacity, specialized slurry engineers with deep aftermarket penetration, and Asian volume manufacturers competing on standardized cast iron housings. Dominant competitive moves include backward integration into hydraulic power unit production and geographic expansion through rental fleet partnerships.
Within the integrated multinational tier, Xylem Inc. and Sulzer Ltd. occupy positions anchored by vertical control over critical component supply chains. Weir Group PLC exemplifies the project pump specialist archetype through manufacturing scale at named foundry locations. Among Japanese precision manufacturers, Tsurumi Manufacturing Co., Ltd. represents the durable utility pump segment with established distribution density in Asian municipal markets.
| Leading Market Players |
|---|
| Xylem Inc. |
| Sulzer Ltd. |
| Weir Group PLC |
| Atlas Copco AB |
| Tsurumi Manufacturing Co., Ltd. |
| Grindex AB |
| Gorman-Rupp Company |
| Franklin Electric Co. Inc. |
| KSB SE & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
Ceramic-matrix composite impeller coatings displacing high-chrome white iron in Western Australia's mining districts simultaneously fragment traditional metallurgy hierarchies and compress aftermarket parts dependency, redrawing supply geography toward coating technology licensors while eroding the pricing power of legacy foundry clusters in Germany and Italy.
Pricing Analysis
Aftermarket parts and service contracts generate the deepest lifetime value pools, with mining operators in Australia's Pilbara absorbing premium pricing for wear-resistant configurations without volume elasticity while municipal buyers in India's National Jal Jeevan Mission demonstrate acute price sensitivity on standardized utility units. Pricing stratifies across API 610-certified project pumps, ISO 2858-compliant municipal units, and commoditized Asian-manufactured utility pumps. Cost compression in the utility tier intensifies because rental fleet operators in Texas and Florida consolidate procurement volume. Mining operators show least price sensitivity; agricultural buyers in India show most.
Supply Chain Analysis
Just-in-time manufacturing preferences dominate European supply chains, though foundry concentration in Germany and Italy creates geographic single-point vulnerability that forces strategic stockpiling of critical cast iron housings among project pump specialists. Supply clusters center on Shandong Province for cast iron housings, North Rhine-Westphalia for precision-machined components, and Scotland and Malaysia for Weir Group's project pump foundry operations. Raw material dependencies rest on nickel and chromium for high-chrome alloys, hydraulic fluid base stocks, and duplex stainless steel feedstock. Tariff exposure on Chinese cast iron imports threatens margin stability. Distribution runs through manufacturer-direct channels for engineered slurry configurations and regional equipment distributors for standardized utility units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydraulic submersible pump market is experiencing high-growth disruption as hybrid hydraulic-electric architectures converge surface power unit efficiency with submersible durability, creating new product categories while the EU's F-Gas Regulation forces simultaneous fluid reformulation and motor redesign cycles.
For Market Incumbents: Consolidate certification capabilities to defend API 610 and ISO 2858 compliance tiers against specialized slurry engineers encroaching on project pump segments. Backward integration into hydraulic power unit production controls lead times and protects margin pools from captive foundry competitors. Foundry capacity expansion in Southeast Asia reduces European supply chain vulnerability.
For New Entrants and Emerging Players: API 610 certification fast-track programs unlock municipal flood control procurement in Indonesia's Jakarta and Surabaya where climate adaptation budgets are hardening. Target ceramic-matrix composite coating partnerships with Australian mining distributors to displace high-chrome aftermarket dependencies. Lease-to-own fleet partnerships with Texas and Florida municipalities bypass capital budget constraints.
For Investors and Strategic Acquirers: The EU's F-Gas Regulation reshapes the acquisition landscape by forcing costly redesign cycles that favor targets with biodegradable hydraulic fluid R&D pipelines and Ecodesign Directive pre-certification. Long-term viability centers on aftermarket service revenue independence from new equipment sales. Watch for unbundling maintenance contracts in Western Australia's Pilbara as the signal that recurring revenue models are achieving scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Power Units | Xylem's captive manufacturing compresses lead times on high-specification slurry configurations for mining dewatering. |
| Ceramic-Matrix Composite Coating Partnerships | Perth-based distributors piloting these surfaces fragment traditional high-chrome aftermarket parts dependency patterns. |
| Biodegradable Hydraulic Fluid R&D Investment | European suppliers absorbing steepest compliance costs from EU F-Gas Regulation constraints on fluid chemistries. |
| Lease-to-Own Fleet Expansion | Texas and Florida equipment distributors capture recurring revenue streams from flood-prone coastal municipalities. |
| API 610 Certification Capability Buildout | Third-party verification queues extending 14-18 months create bottlenecks that certified manufacturers exploit. |
Study Parameters
A spread of perspectives from maintenance directors at mining dewatering operations, municipal procurement officers in flood-prone coastal zones, plant engineers at foundry operations, aftermarket service heads, and OEM procurement teams converged on the working assumptions that shape this analysis. Primary interview insights combined with secondary validation from EPA enforcement records, MEE GB standard filings, EU Ecodesign Directive implementation documents, and customs trade data on cast iron housing imports. Bottom-up equipment deployment estimates and top-down infrastructure budget allocations were triangulated to cross-validate volume assumptions.
Segmentation dimensions modeled include product type tier, end-user industry, application maturity, and technology architecture across the analysis window. CAGRs were derived from infrastructure budget trajectories, replacement cycle acceleration patterns, and regulatory enforcement timelines. Forecast inputs incorporated climate adaptation spending hardening in Indonesia, China's Yellow River Basin water conservancy deployment schedules, and India's National Jal Jeevan Mission rural network expansion.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Clean Water Act enforcement, continued EU F-Gas Regulation stringency, and stable nickel-chromium alloy pricing; material deviation would warrant model refresh. Revision becomes warranted when hybrid technology adoption rates in Australia's Pilbara or ceramic-matrix composite coating scale thresholds cross inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
Intelligent Pump Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Screw Pumps Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Double Diaphragm Pump Market
Pumps and Control Devices
Plate Heat Exchanger Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
United States Positive Displacement Pumps Market
Pumps and Control Devices
Global Solar Water Pump Systems Market