
 On the Go Packaging Market | 2026-2036
On the Go Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
On the Go Packaging Market Outlook
FSC chain-of-custody and ISO 18606 compostability certification is bifurcating the supplier base into qualified and non-qualified tiers. Amcor plc leverages its integrated film extrusion network to sustain supply security for flexible pouch lines. Mondi Group anchors European demand through kraft-paper barrier innovations that compete with conventional plastic laminates.
On the go packaging denotes portable, single-serve or small-format containers engineered for consumption away from home, typically incorporating heat-sealable barrier layers of EVOH or metallized PET to preserve shelf stability under ambient distribution. The category serves food service operators, convenience retailers, and brand owners requiring portion control with minimal utensil dependency. Flexible pouches dominate volume in beverage and sauce applications where lightweight logistics offset material costs. Rigid containers capture premium placement in prepared salad and fresh-cut fruit segments where structural integrity protects visual appeal. Biodegradable films represent the fastest-expanding material class as European and North American brands navigate extended producer responsibility frameworks.
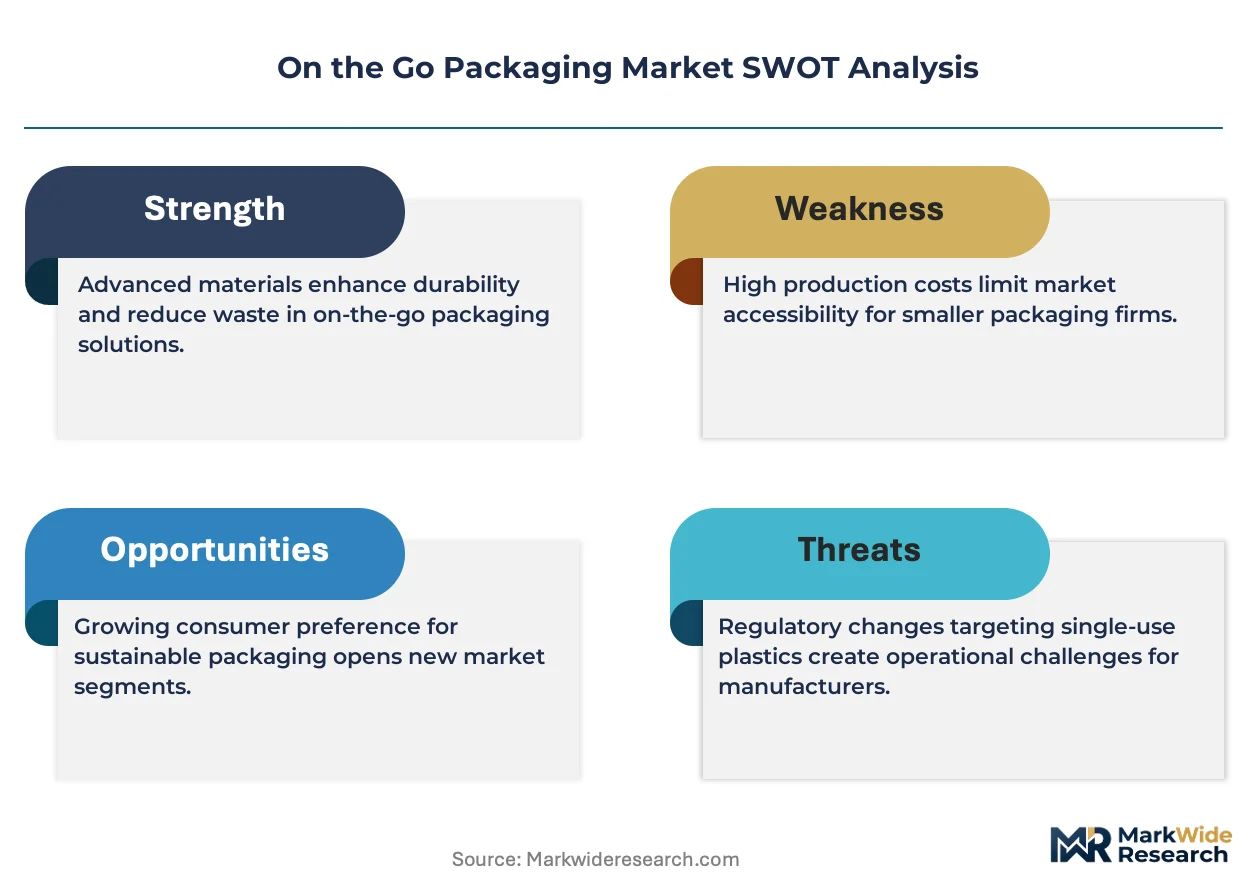
The US EPA guides material recovery targets for municipal streams, while the EU Packaging and Packaging Waste Regulation mandates recyclability-by-design standards that reshape substrate selection across export-oriented converters. India's BIS certification for food-contact materials adds a compliance layer for suppliers targeting its organized retail expansion. Stakeholders must track how harmonization between these frameworks influences capital allocation for recycling infrastructure and whether regional divergence in compostability standards fragments mold investments.
Market Dynamics
Mono-material packaging architectures are restructuring converter capital allocation as the EU Packaging and Packaging Waste Regulation tightens recyclability mandates and quick-service chains demand supply security.
Growth Catalysts
- Urban commuter density:Cold-chain retail penetration in Indian and Vietnamese metropolitan corridors is expanding addressable demand for ambient-stable single-serve formats.
- REACH chemical restrictions:ECHA substance evaluations are accelerating substitution of conventional barrier coatings with bio-based alternatives across European export supply chains.
- Quick-service restaurant format proliferation:Drive-through and mobile-ordering infrastructure investments by US and Chinese food service operators are standardizing pouch-based portion control.
Market Restraints
- EVOH resin supply concentration:Asian petrochemical complexes control critical oxygen-barrier polymer output, exposing converters to feedstock volatility and allocation constraints.
- Composting infrastructure gaps:ISO 18606-certified films require industrial composting facilities that remain absent across most US municipal waste systems.
- Aluminum foil substitution pressure:Metallized PET and silicon oxide coatings are eroding foil's share in premium barrier applications despite inferior oxygen transmission performance.
Strategic Opportunities
- Indonesian organized retail expansion:Modern trade penetration in Jakarta and Surabaya is creating first-mover positioning for cold-chain-compatible flexible formats.
- FSSAI compliance integration:India's food-contact material certification requirements favor suppliers with established analytical testing partnerships over opportunistic exporters.
- Digital printing-barrier film convergence:HP Indigo and electron-beam curing technologies are enabling short-run customization without laminate delamination risks.
Industry Challenges
- Multi-standard certification complexity:Simultaneous FSC chain-of-custody, ISO 18606, and BIS compliance demands specialized audit talent scarce among mid-tier converters.
- Legacy thermoforming asset stranding:Rigid container tooling with decade-long depreciation schedules resists reconfiguration for flexible pouch production.
- Recyclate quality inconsistency:Post-consumer polyolefin streams exhibit batch-to-batch contamination that disrupts mono-material film extrusion yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On the Go Packaging Market |
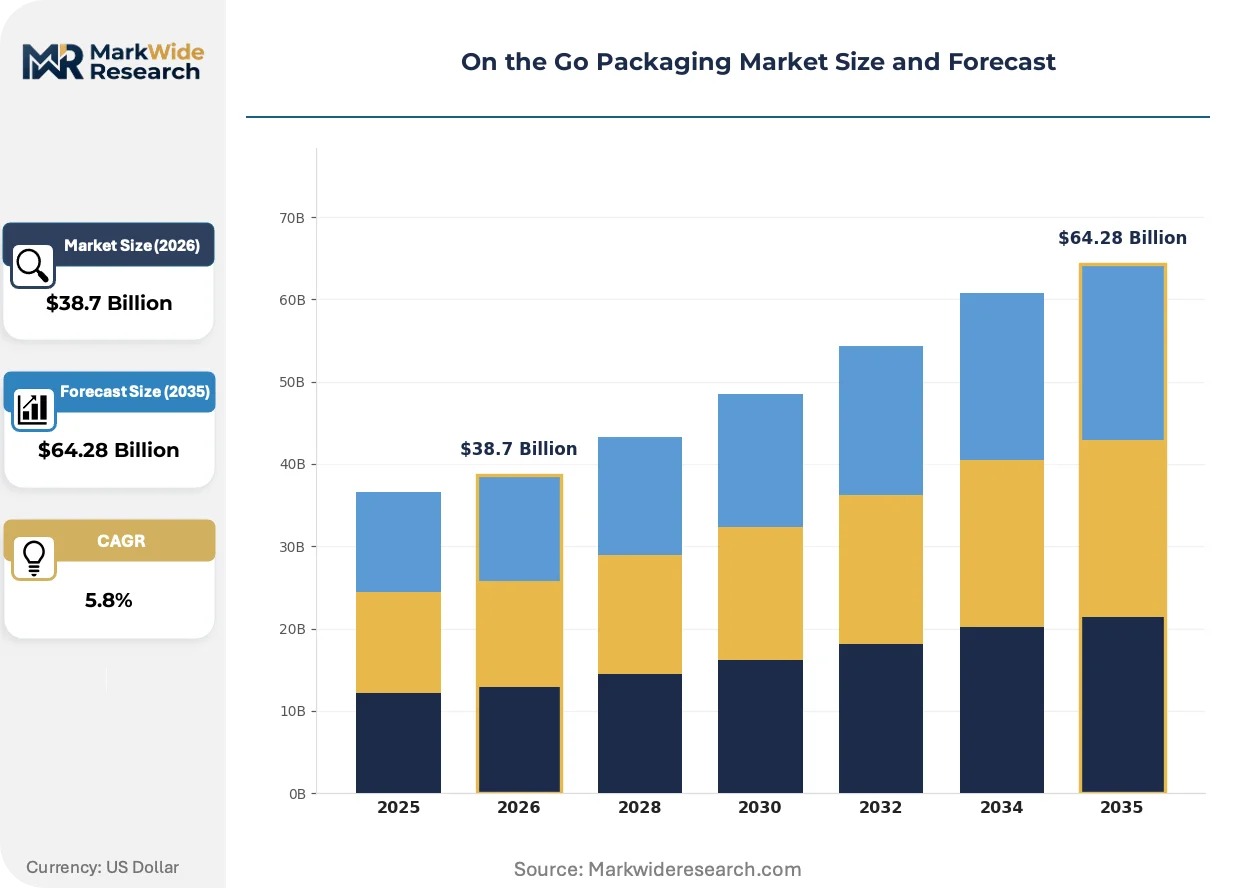
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Pouches, Rigid Containers, Trays, Cups Material: Plastic, Aluminum, Paperboard, Biodegradable Films End User: Food & Beverage, Personal Care, Consumer Electronics, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Vending Machines |
| Companies Covered | Amcor plc, Berry Global Group, Sealed Air Corporation, Mondi Group, Sonoco Products Company, Smurfit Kappa Group, WestRock Company, Huhtamaki Oyj, Tetra Pak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On the Go Packaging Market Strategic Shifts
Material science breakthroughs and regulatory harmonization pressures are compressing development cycles for next-generation barrier substrates while reshaping how brands validate sustainability claims.
Water-based barrier coatings derived from cellulose nanofibrils are supplanting conventional extruded EVOH layers in ambient beverage pouch applications. European dairy and juice brand owners are qualifying these substrates at accelerated timelines to preempt EU recyclability mandates. The shift is compressing margins for conventional multilayer laminate suppliers while rewarding integrated pulp-film converters with captive nanocellulose supply.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant paperboard treatments across food service packaging. Converters serving EU export markets are migrating toward silicone and clay-based alternatives despite higher unit coating costs. Quick-service chains with transcontinental supply footprints are consolidating specifications to avoid dual-SKU complexity.
Direct-store-delivery logistics models are displacing traditional distributor intermediaries in North American convenience retail. Beverage and fresh snack suppliers are building captive delivery fleets to control temperature integrity and capture point-of-sale data. The restructuring is most visible in California and Texas metropolitan clusters where fuel cost volatility and driver availability constrain third-party capacity.
On the Go Packaging Market Segmentation
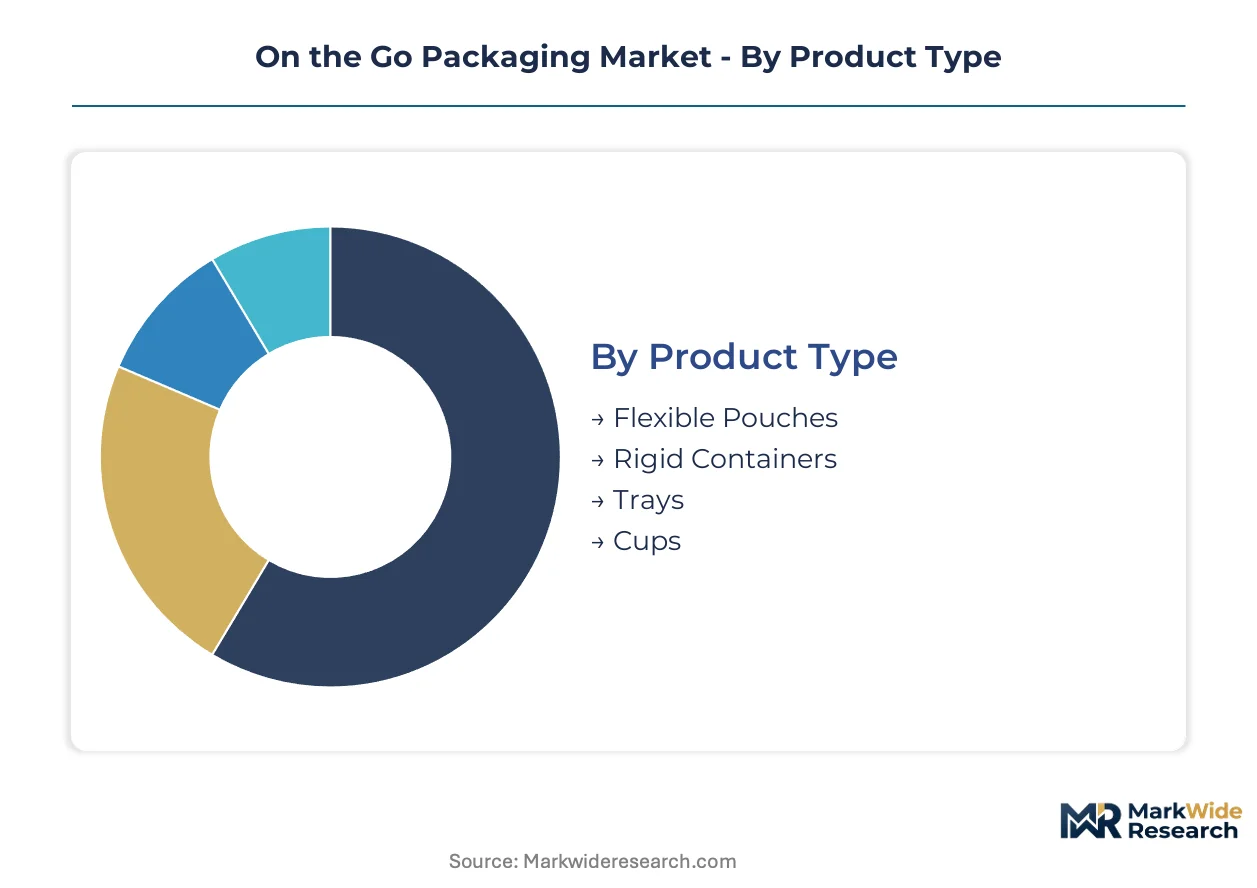
Segmentation in on-the-go packaging reveals how substrate choices and channel access determine margin capture. Each dimension carries distinct substitution threats and regulatory exposure that reshape converter investment priorities.
Product Type:
Flexible pouch formats face intensifying substitution pressure from rigid alternatives in premium fresh-food segments where structural integrity commands price premiums.
- Flexible Pouches:Multi-layer laminates incorporating EVOH or metallized PET barriers deliver lightweight oxygen protection for ambient beverages and sauces. Quick-service chains in India and Vietnam are standardizing these formats for drive-through portion control as cold-chain retail penetration expands.
- Rigid Containers:Injection-molded polypropylene or thermoformed PET structures preserve visual appeal for prepared salads and fresh-cut fruit. US convenience retailers favor these for grab-and-go placement where shelf presence influences impulse purchase.
- Trays:Sealed barrier trays with modified atmosphere capabilities extend protein shelf life in European retail. The format struggles against flexible alternatives in logistics cost but retains position in hot-fill applications.
- Cups:Single-serve beverage and snack vessels dominate vending machine and food service fountain deployment. Paperboard barrier versions are capturing share from conventional plastic in EU markets navigating extended producer responsibility frameworks.
Flexible pouches retain volume leadership; biodegradable film cups hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity substrates from certified alternatives that command supply security premiums.
- Plastic:Polyethylene and polypropylene dominate unit economics across high-volume beverage and sauce applications. Asian petrochemical complexes control critical resin supply, exposing converters to feedstock allocation constraints.
- Aluminum:Foil laminates provide superior oxygen barrier for premium shelf-stable segments but face erosion from metallized PET and silicon oxide coatings. The material retains position in pharmaceutical blister and retort applications.
- Paperboard:Kraft-paper barrier innovations compete with plastic laminates in European quick-service packaging. REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant treatments.
- Biodegradable Films:Cellulose nanofibril and polylactic acid substrates are gaining fastest in EU dairy and juice qualifications. Industrial composting infrastructure gaps across most US municipal systems constrain deployment scale.
Conventional plastic retains volume leadership; biodegradable films hold the steepest expansion curve.
End User:
Application maturity determines whether segments face margin compression or technology upgrade cycles.
- Food & Beverage:Ambient-stable single-serve formats serve quick-service operators and convenience retailers requiring portion control. Cold-chain infrastructure expansion in Jakarta and Surabaya is creating positioning for flexible formats.
- Personal Care:Sample-size sachets and travel formats demand moisture barrier precision for cosmetic and hygiene products. Digital printing convergence enables short-run customization without laminate delamination.
- Consumer Electronics:Anti-static and moisture-barrier pouches protect components during distribution. The segment trails food applications in sustainability certification pressure.
- Pharmaceuticals:Blister packs and unit-dose formats require compliance with national pharmaceutical regulators. India's CDSCO and US FDA standards bifurcate supplier qualification tiers.
Food and beverage retains volume leadership; personal care holds the steepest expansion curve.
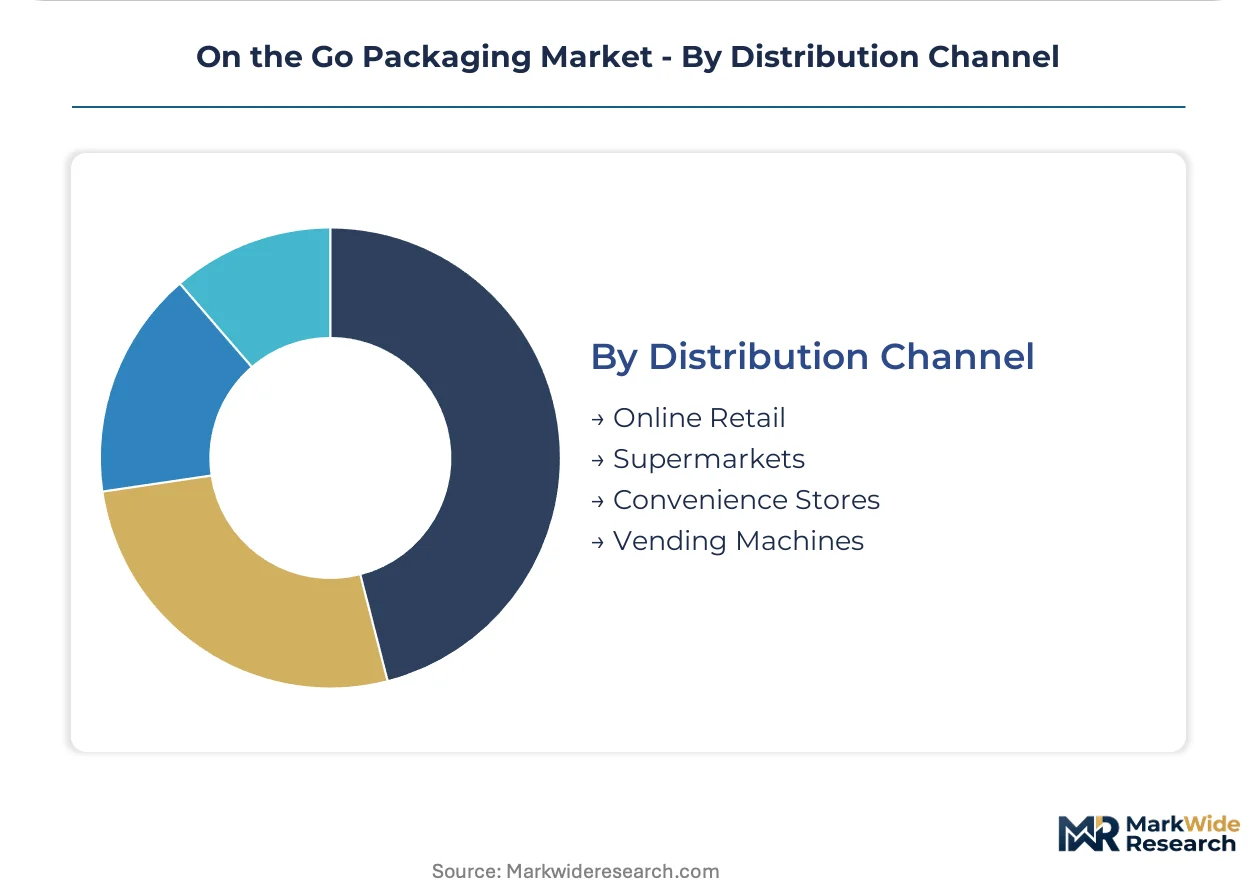
Distribution Channel:
Customer type concentration shapes whether segments prioritize logistics efficiency or point-of-sale customization.
- Online Retail:E-commerce fulfillment demands damage-resistant formats optimized for last-mile handling. California and Texas metropolitan clusters show direct-store-delivery models displacing traditional distributor intermediaries.
- Supermarkets:Organized retail in India and Indonesia requires cold-chain-compatible formats with extended shelf stability. FSSAI compliance integration favors suppliers with established analytical testing partnerships.
- Convenience Stores:Grab-and-go placement prioritizes visual appeal and rapid consumption ergonomics. Temperature integrity requirements are driving captive delivery fleet investments.
- Vending Machines:Mechanical dispensing constraints favor rigid cup and container geometries. The channel lags in sustainable substrate adoption due to equipment retrofit costs.
Supermarkets retain volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service chains and convenience retailers concentrate purchasing power in commuter-dense metropolitan corridors across five major economies. Cold-chain infrastructure maturity and regulatory stringency determine format preferences and supplier qualification requirements in each market.
United States
Drive-through format proliferation and mobile-ordering infrastructure at quick-service chains sustain pouch-based portion control demand. EPA material recovery targets guide municipal stream specifications for converters serving national food service accounts. California and Texas metropolitan clusters show direct-store-delivery logistics displacing traditional distributor intermediaries.
Germany
Kraft-paper barrier innovations compete with plastic laminates in European quick-service packaging as REACH restrictions force reformulation of grease-resistant treatments. ECHA substance evaluations accelerate substitution of conventional barrier coatings with bio-based alternatives. The country's organized retail sector drives qualification timelines for cellulose nanofibril substrates.
India
Cold-chain retail penetration in Mumbai and Delhi metropolitan corridors expands addressable demand for ambient-stable single-serve formats. FSSAI certification for food-contact materials adds compliance layers favoring suppliers with established analytical testing partnerships. Organized retail expansion in Bangalore and Hyderabad creates positioning for flexible pouch converters.
China
Mobile food vendor format standardization and quick-service restaurant infrastructure investments drive pouch-based portion control adoption. SAMR food-contact material standards and dual carbon goals reshape substrate selection among export-oriented converters. Yangtze River Delta manufacturing clusters concentrate flexible film extrusion capacity.
Indonesia
Modern trade penetration in Jakarta and Surabaya creates first-mover positioning for cold-chain-compatible flexible formats. The country's national food safety agency certification requirements favor integrated converters over opportunistic exporters. Urban commuter culture maturation in Bandung and Medan expands grab-and-go placement opportunities.
On the Go Packaging Market Competitive Environment
Player mix skews toward integrated multinational converters with captive film extrusion networks and regional specialists with certified substrate capabilities. Market structure shows tiered consolidation around FSC chain-of-custody and ISO 18606 qualification thresholds. Two strategic archetypes dominate: integrated pulp-film converters leveraging nanocellulose supply security, and flexible packaging specialists with digital printing-barrier film convergence capabilities. Competitive moves concentrate on mono-material architecture R&D partnerships and selective capacity expansion in Indian and Southeast Asian corridors.
Within the integrated multinational tier, Amcor plc and Mondi Group exemplify contrasting geographic anchoring strategies. Amcor leverages its film extrusion network footprint to sustain supply security for flexible pouch lines serving quick-service chains. Mondi anchors European demand through kraft-paper barrier innovations that compete with conventional plastic laminates. Berry Global Group occupies a position among North American converters navigating EPA material recovery targets and quick-service format proliferation simultaneously.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group |
| Sealed Air Corporation |
| Mondi Group |
| Sonoco Products Company |
| Smurfit Kappa Group |
| WestRock Company |
| Huhtamaki Oyj |
| Tetra Pak |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with Asian petrochemical suppliers lock in EVOH resin access for converters while capping feedstock price volatility exposure. These arrangements bind quick-service chains to minimum volume commitments that secure pouch supply security against spot market fluctuations.
Pricing Analysis
Cost-plus contracts indexed to ethylene and propylene benchmarks dominate flexible pouch procurement between converters and quick-service chains. Three-tier pricing structure across FSC-certified premium, ISO 18606-qualified standard, and uncertified economy grades separates supplier tiers. Pricing pressure stems from REACH-driven barrier coating reformulation costs eroding margins on European export orders. Quick-service chains exhibit highest price sensitivity in high-volume beverage applications, while pharmaceutical blister pack buyers tolerate premium foil laminates.
Supply Chain Analysis
Port congestion on Shanghai-Rotterdam trade lanes elevates inbound logistics costs for European converters sourcing metallized PET films. Manufacturing gravity centers on China, South Korea, and Germany for barrier film extrusion and coating operations. Raw material dependencies span ethylene-vinyl alcohol copolymers, cellulose nanofibrils, and metallized polyethylene terephthalate substrates. Single-source vulnerability concentrates in Asian EVOH resin complexes controlling oxygen-barrier polymer output. Distribution runs through direct-store-delivery fleets displacing traditional distributor intermediaries in North American convenience retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery as quick-service restaurant format proliferation drives pouch standardization demand. Cold-chain infrastructure buildout in Indian and Southeast Asian corridors sustains the upswing phase.
For Market Incumbents: Shield flexible pouch margins by securing captive cellulose nanofibril supply through backward integration into pulp-film operations. Accelerate mono-material architecture R&D partnerships to preempt EU Packaging and Packaging Waste Regulation recyclability mandates. Lock in FSC chain-of-custody certification ahead of mid-tier competitor qualification attempts.
For New Entrants and Emerging Players: Anchor in Indonesian organized retail expansion where modern trade penetration in Jakarta and Surabaya creates first-mover positioning for cold-chain-compatible formats. Target biodegradable film cup segments constrained by US industrial composting infrastructure gaps. Pursue FSSAI compliance integration as the go-to-market angle for Indian supermarket channel access.
For Investors and Strategic Acquirers: Integrated converters with digital printing-barrier film convergence capabilities present the most defensible acquisition profile over the long-term viability window. Monitor HP Indigo and electron-beam curing technology adoption rates as the inflection signal for short-run customization demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Architecture R&D Partnership | EU Packaging and Packaging Waste Regulation recyclability mandates reshape substrate selection for export-oriented converters. |
| Backward Integration into Nanocellulose Supply | Captive pulp-film operations reward converters qualifying water-based barrier coatings for accelerated dairy brand timelines. |
| FSSAI Compliance Integration Investment | India's food-contact material certification requirements favor suppliers with established analytical testing partnerships. |
| Direct-Store-Delivery Fleet Buildout | California and Texas metropolitan clusters show captive delivery displacing third-party distributors for temperature integrity control. |
| Digital Printing-Barrier Film Convergence | HP Indigo and electron-beam curing technologies enable short-run customization without laminate delamination risks. |
Study Parameters
A spread of perspectives from packaging procurement managers at quick-service chains, flexible film extrusion plant engineers, retail category buyers, and regulatory compliance officers converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation against EPA material recovery guidelines, EU ECHA substance evaluations, FSSAI certification databases, and customs trade records. Bottom-up volume builds across product type, material, and end-user segments triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled include flexible pouch versus rigid container formats, plastic versus biodegradable film substrates, food and beverage versus personal care applications, and supermarket versus online retail channels. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and infrastructure buildout timelines across the projection horizon. Forecast inputs incorporated cold-chain penetration rates in Indian metropolitan corridors and REACH authorization timelines for per- and polyfluoroalkyl substance substitutions.
Underlying assumptions cover sustained quick-service restaurant format proliferation, EU recyclability mandate enforcement timelines, and Asian petrochemical supply stability, with deviation risk concentrated in composting infrastructure deployment gaps and EVOH resin allocation constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Compression Baggers Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Cassava Bags Market
Bags and Containers
Ventilated FIBC Market
Bags and Containers
Block Sack Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Bag Clips Market