
 Global Operational Technology Market | 2026-2036
Global Operational Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Operational Technology Market Outlook
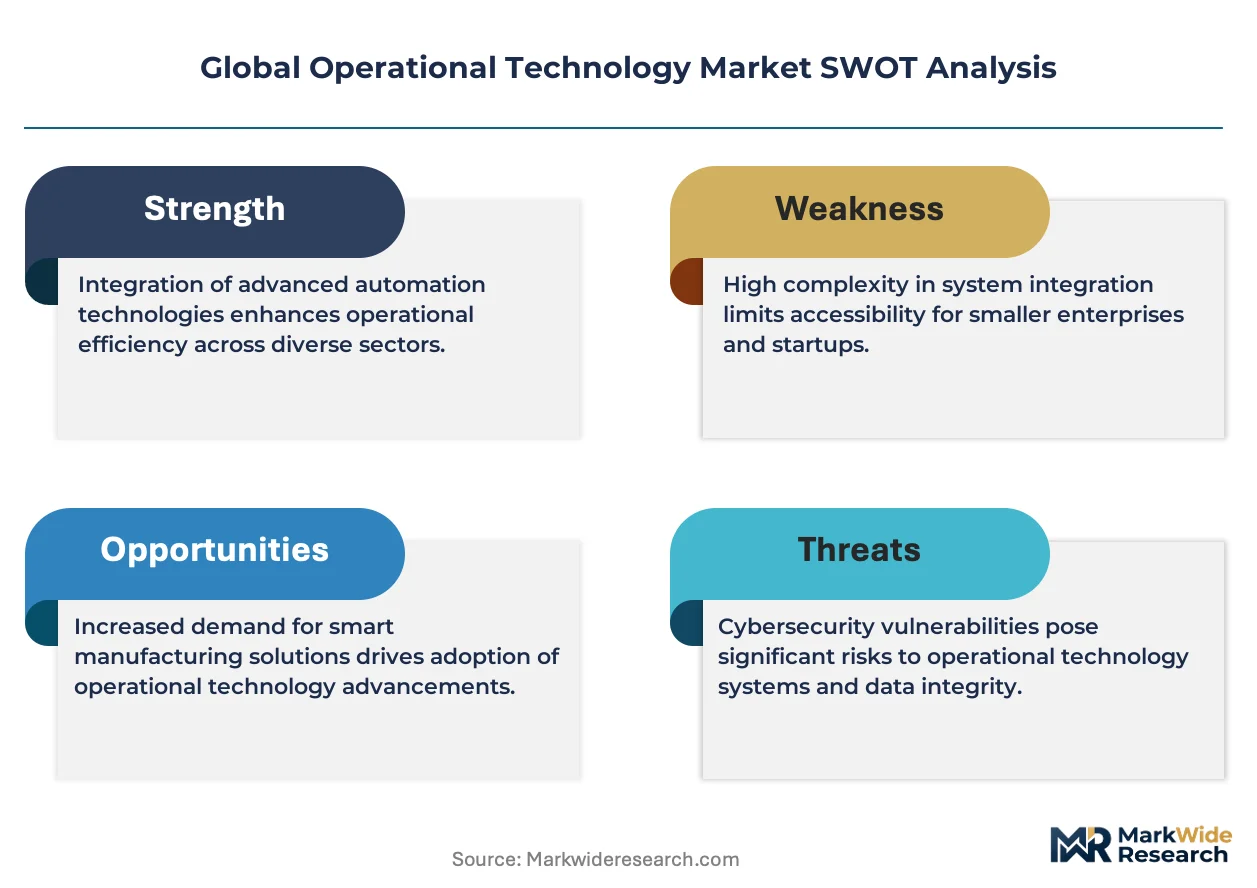
IEC 62443 certification is redrawing competitive boundaries for industrial cybersecurity suppliers. Siemens AG leverages its integrated automation portfolio to anchor European manufacturing upgrades. Honeywell International Inc. competes through deep specialization in process control systems for energy and refining. Schneider Electric SE extends its edge computing footprint to sustain leadership in distributed energy management.
Operational technology encompasses hardware and software systems that monitor, control, and automate physical industrial processes through real-time data acquisition, typically operating at sub-second latency thresholds to maintain production continuity. SCADA architectures remain the dominant revenue layer across utilities and pipeline infrastructure, while edge computing deployments represent the fastest structural expansion as latency-sensitive workloads migrate from centralized cloud nodes. Manufacturing end users command the largest installed base, though predictive maintenance applications are capturing disproportionate investment as asset-intensive sectors prioritize uptime economics over capital replacement cycles.
ISA/IEC 62443 standards, NIST SP 800-82 guidance, and EU Cyber Resilience Act requirements are converging to mandate security-by-design across connected industrial products, effectively raising barriers for uncertified entrants. The EU AI Act adds algorithmic accountability obligations for AI-enabled process control systems deployed in European facilities. Stakeholders must evaluate certification roadmaps against regional enforcement timelines to avoid market exclusion as procurement specifications harden around verified cybersecurity postures.
Market Dynamics
Edge-to-cloud workload migration is compressing capital deployment cycles as manufacturers prioritize sub-second latency for predictive control systems over multi-year infrastructure refresh timelines.
Growth Catalysts
- EU Cyber Resilience Act mandates:Security-by-design requirements for connected industrial products are accelerating procurement specifications toward certified vendors across European manufacturing facilities.
- Predictive maintenance economics:Asset-intensive sectors including oil refining and power generation are redirecting capital from replacement cycles toward condition-monitoring sensor networks.
- German industrial cluster concentration:Automotive and heavy machinery producers in Baden-Württemberg and Bavaria are synchronizing production lines through integrated OT-IT architectures.
Market Restraints
- Semiconductor supply concentration:Industrial-grade processor and FPGA sourcing remains concentrated among Taiwan-based foundries, exposing automation vendors to geopolitical disruption risk.
- IEC 62443 certification friction:Multi-year compliance timelines for component-level security ratings are delaying product launches for uncertified entrants.
- Legacy protocol interoperability:Proprietary fieldbus standards from the 1990s continue to fragment system architectures, complicating unified security policy enforcement.
Strategic Opportunities
- India PLI scheme for manufacturing:Production-linked incentives for semiconductor and electronics fabrication are attracting OT infrastructure investment into Gujarat and Tamil Nadu industrial corridors.
- Digital twin convergence:Physics-based simulation layers merged with real-time SCADA data streams are opening new service revenue models for system integrators.
- China dual carbon enforcement:MEE mandates for energy intensity reduction are forcing steel and cement producers toward AI-enabled process optimization platforms.
Industry Challenges
- OT cybersecurity workforce scarcity:Cross-trained engineers possessing both industrial control expertise and threat detection skills command premium compensation, constraining vendor scaling.
- brownfield integration complexity:Retrofitting 20-year-old DCS installations with edge analytics without disrupting continuous operations requires phased commissioning approaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Operational Technology Market |
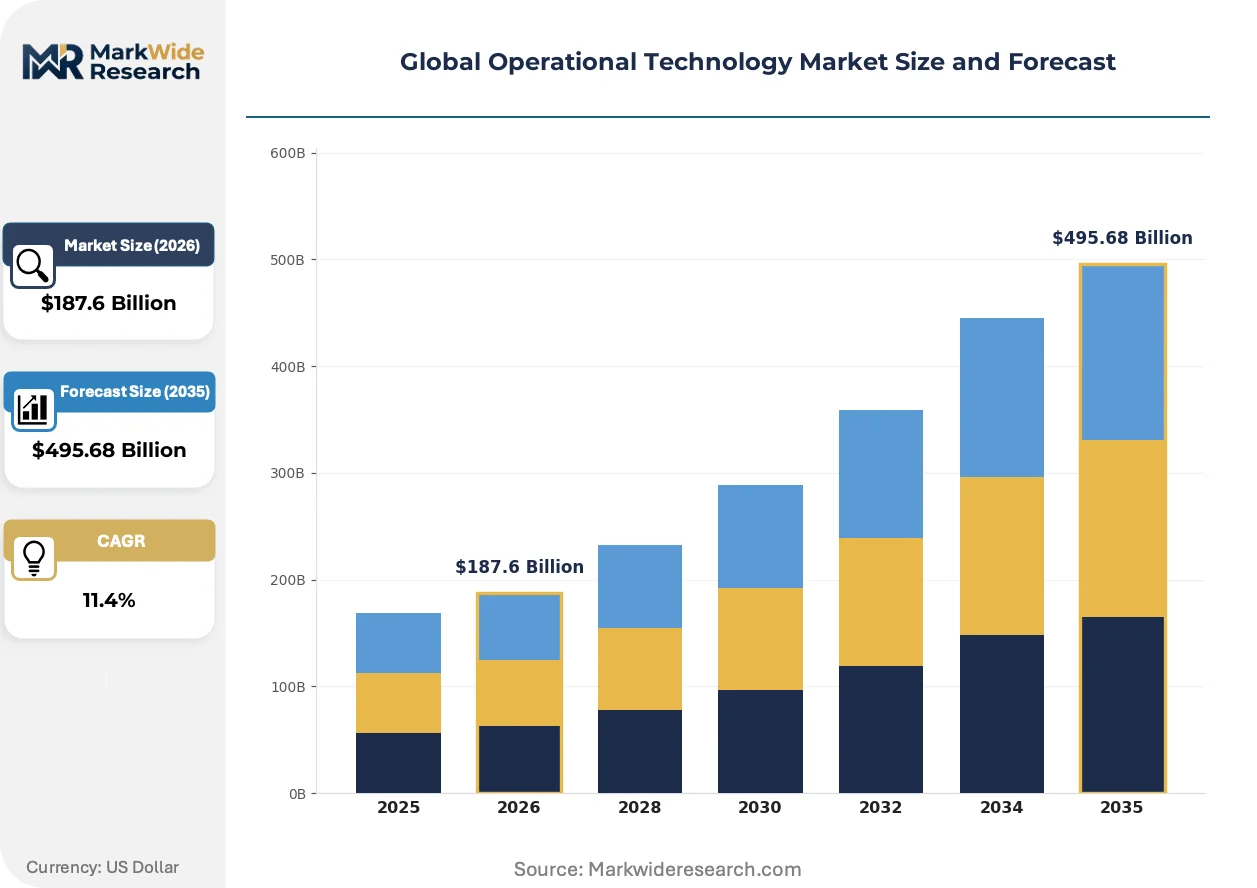
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SCADA, DCS, HMI, PLC Technology: IoT, Cloud Computing, AI, Edge Computing End User: Manufacturing, Energy, Transportation, Utilities Application: Industrial Automation, Process Control, Predictive Maintenance, Asset Management |
| Companies Covered | Siemens AG, Honeywell International Inc., Schneider Electric SE, ABB Ltd., Emerson Electric Co., Rockwell Automation, General Electric, IBM, Hewlett Packard Enterprise Development LP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Operational Technology Market Strategic Shifts
Real-time analytics architectures are displacing scheduled maintenance regimes as the organizing principle for industrial capital allocation, compressing the feedback loop between operational data and physical intervention.
Software-defined PLCs are fragmenting the traditional hardware-controller market by decoupling control logic from proprietary silicon, allowing automotive manufacturers to deploy standardized compute nodes across mixed-vendor environments while reducing spare parts inventory. Tier-one suppliers in Germany and the United States are piloting these virtualized controllers on containerized edge platforms, collapsing the distinction between IT infrastructure and operational control layers.
The EU AI Act's risk classification framework is forcing process industries to document algorithmic decision trails for safety-critical control systems, compelling vendors to embed audit logging and human-in-the-loop override mechanisms into AI-enabled optimization software. Chemical and pharmaceutical manufacturers operating in the European Economic Area face the steepest compliance burdens, with enforcement timelines accelerating procurement toward pre-certified solution providers.
Asset owners are unbundling long-term service contracts from initial hardware purchases, shifting toward performance-based agreements where system integrators retain operational responsibility for uptime metrics. This reconfiguration is most pronounced in North American oil and gas midstream operations, where pipeline operators now procure SCADA functionality as a managed service rather than capital equipment, transferring cyber liability and maintenance burden to vendor balance sheets.
Global Operational Technology Market Segmentation
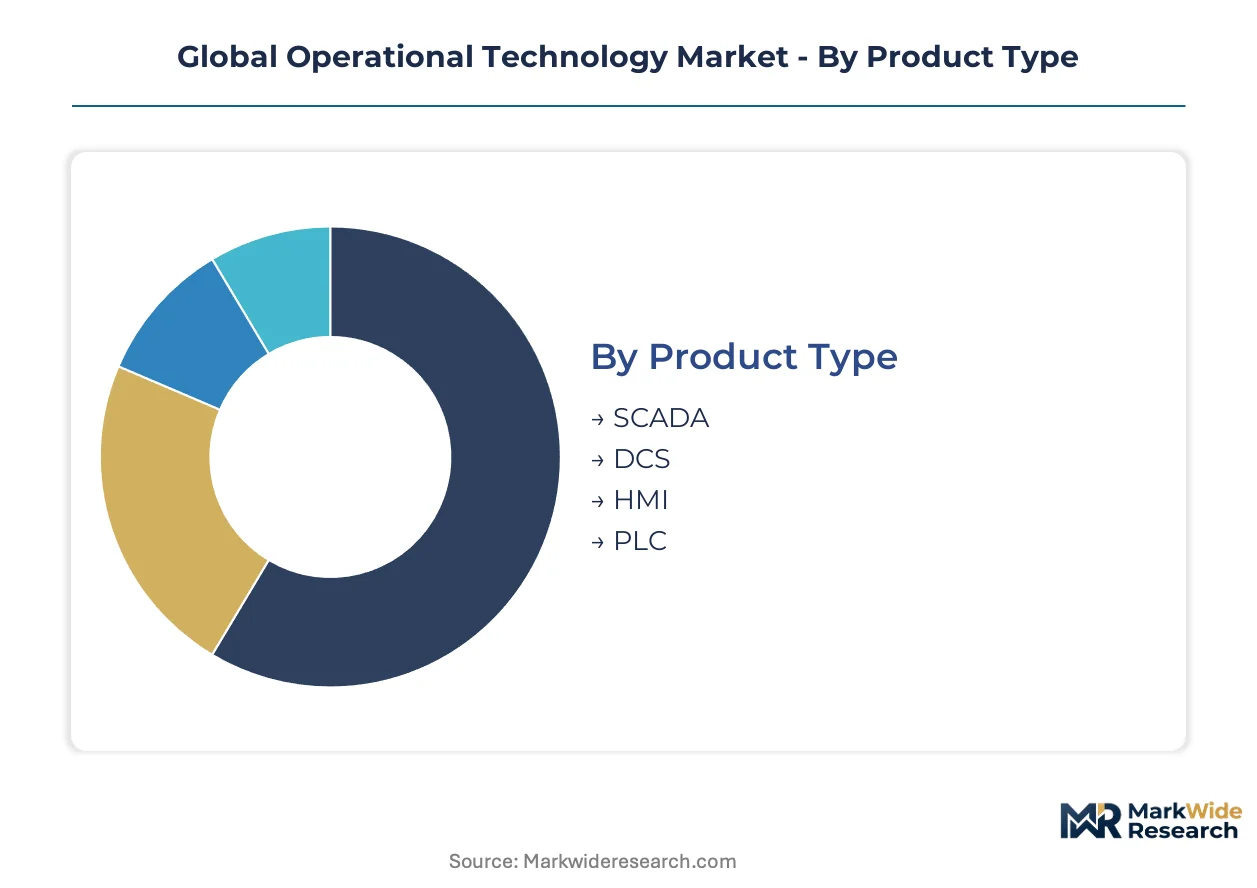
Segmentation in operational technology reveals how procurement specifications diverge across latency requirements, cybersecurity postures, and legacy integration burdens. Channel strategies vary sharply between direct sales for brownfield retrofits and system integrator partnerships for greenfield edge deployments.
Product Type:
Channel mix varies by deployment complexity: SCADA and DCS flow predominantly through system integrators with long-term service attachments, while HMI and PLC hardware move through distribution partners serving maintenance-replacement demand.
- SCADA:Distributed telemetry architectures aggregate sensor data across geographically dispersed assets such as pipelines and electrical grids. German utilities and US midstream operators are consolidating vendor relationships to reduce integration fragmentation under IEC 62443 mandates.
- DCS:Centralized process control platforms manage continuous manufacturing flows in refineries and chemical plants. Demand concentrates in China's Yangtze River Delta as MEE enforcement drives capacity consolidation toward digitally integrated facilities.
- HMI:Operator interface panels bridge human oversight with machine-level control logic.
- PLC:Programmable controllers execute discrete automation sequences across automotive assembly lines.
By volume, PLC leads through sheer installed base density. By growth pace, SCADA is climbing the fastest as critical infrastructure operators confront cybersecurity retrofit cycles.
Technology:
Cost tier stratification separates mature connectivity layers from emerging compute architectures: IoT sensors and cloud platforms compete on per-device economics, while AI and edge deployments command premium positioning through latency guarantees.
- IoT:Sensor networks enable condition monitoring across rotating equipment and thermal systems. India's Gujarat industrial corridor is absorbing substantial IoT infrastructure investment under PLI scheme incentives for electronics manufacturing.
- Edge Computing:Localized processing nodes execute sub-second control decisions without cloud round-trip latency. German automotive clusters in Baden-Württemberg are standardizing edge platforms to synchronize mixed-vendor production lines.
- Cloud Computing:Centralized data lakes support historical analytics and enterprise resource planning integration.
- AI:Machine learning models optimize process parameters and detect anomaly patterns in real-time streams.
By maturity, IoT commands the largest deployment footprint. By margin expansion, edge computing is gaining share fastest as workload migration accelerates.
End User:
Application intensity varies by capital cycle timing: energy and utilities operate decade-long refresh horizons, while manufacturing and transportation compress procurement cycles to match product launch timelines.
- Manufacturing:Discrete and process production facilities deploy OT layers to synchronize supply chains with demand signals. US automotive producers are unifying OT-IT architectures to support software-defined vehicle manufacturing workflows.
- Energy:Oil refining and power generation prioritize uptime economics through predictive maintenance networks. Chinese steel producers face MEE mandates forcing AI-enabled process optimization to meet dual carbon intensity targets.
- Utilities:Electrical distribution and water treatment operators manage geographically dispersed infrastructure.
- Transportation:Rail signaling and port automation systems demand fail-safe control architectures.
By installed base, manufacturing dominates. By investment intensity per asset, energy is expanding most quickly as commodity volatility drives efficiency imperatives.
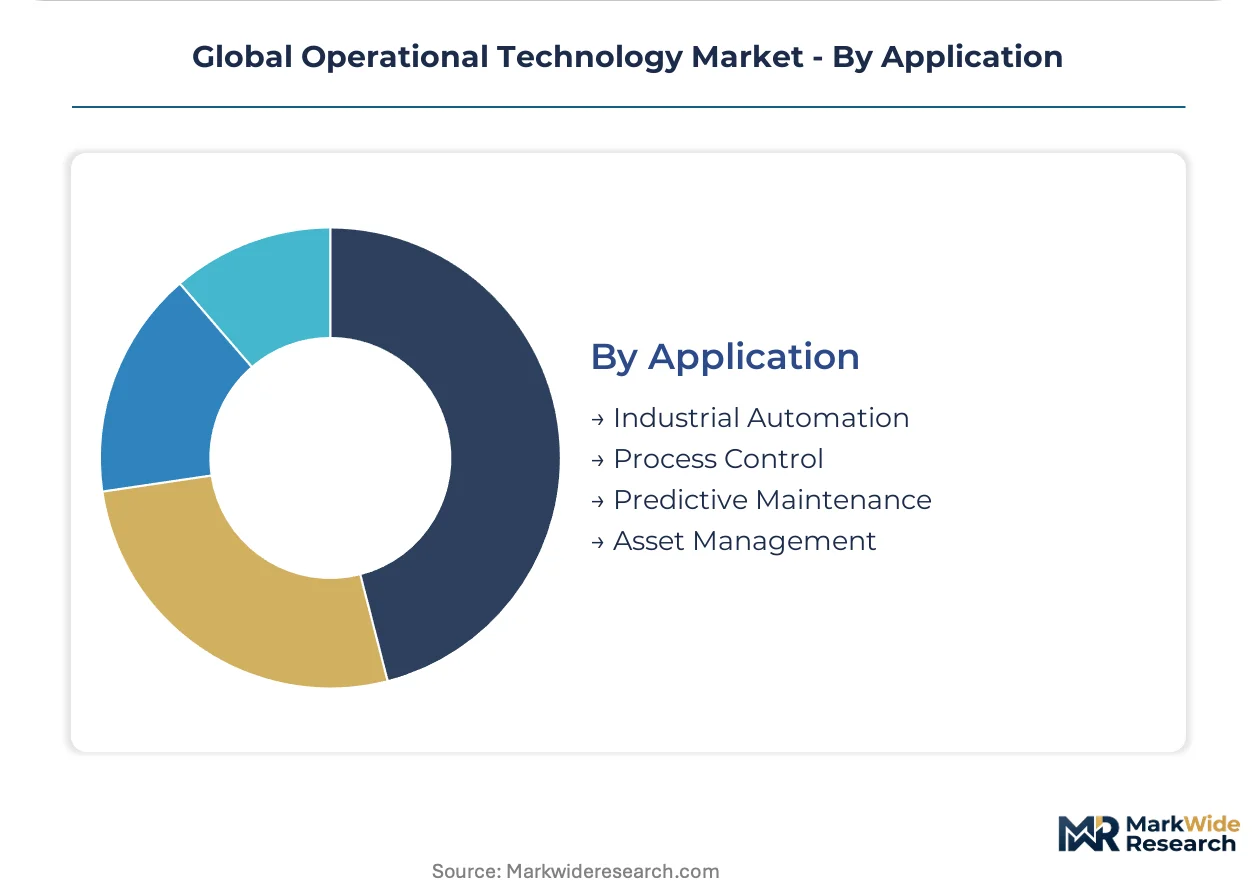
Application:
Customer type segmentation separates capital-equipment purchasers from service-contract adopters: industrial automation and process control remain hardware-weighted, while predictive maintenance and asset management tilt toward subscription and performance-based arrangements.
- Predictive Maintenance:Condition-monitoring systems redirect capital from replacement cycles toward sensor networks and analytics platforms. North American oil and gas midstream operators now procure SCADA functionality as managed services rather than capital equipment.
- Industrial Automation:Fixed and programmable control systems execute repetitive manufacturing sequences. German machinery producers are synchronizing production lines through integrated OT architectures to reduce changeover downtime.
- Process Control:Continuous feedback loops maintain setpoints across temperature, pressure, and flow parameters.
- Asset Management:Lifecycle tracking platforms optimize maintenance scheduling and spare parts inventory.
By contract value concentration, industrial automation leads. By revenue model transformation, predictive maintenance is advancing the fastest as asset owners unbundle long-term service from initial hardware purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed industrial digitization programs are redrawing procurement geographies as manufacturers chase subsidies tied to cybersecurity certification and carbon intensity benchmarks. National regulators are tightening enforcement timelines, compressing vendor qualification windows and favoring pre-certified solution providers.
United States
Midstream oil and gas operators are unbundling SCADA hardware purchases into performance-based managed service contracts. FERC grid reliability directives are accelerating cybersecurity retrofit cycles across electrical distribution infrastructure. Houston-Gulf Coast petrochemical corridors are consolidating vendor relationships under unified IEC 62443-compliant architectures.
Germany
Automotive producers in Baden-Württemberg are synchronizing mixed-vendor production lines through software-defined PLC deployments on containerized edge platforms. EU Cyber Resilience Act security-by-design mandates are hardening procurement specifications toward certified automation vendors. Bavarian heavy machinery clusters are integrating OT-IT architectures to compress changeover downtime.
China
Steel and cement producers face MEE enforcement of dual carbon intensity targets, forcing AI-enabled process optimization platform adoption. Yangtze River Delta chemical plants are consolidating capacity toward digitally integrated facilities with centralized DCS platforms. MIIT industrial internet initiatives are subsidizing edge computing infrastructure across state-owned manufacturing enterprises.
India
PLI scheme incentives for semiconductor and electronics fabrication are channeling OT infrastructure investment into Gujarat and Tamil Nadu industrial corridors. CEA power sector modernization mandates are driving SCADA deployment across state distribution utilities. Gujarat's electronics manufacturing clusters are absorbing substantial IoT sensor network investment under production-linked incentive frameworks.
Japan
Automotive and precision machinery producers are deploying predictive maintenance networks to extend asset life amid capital constraint pressures. METI Society 5.0 industrial transformation guidelines are accelerating digital twin convergence with real-time SCADA data streams. Nagoya-Toyota industrial corridors are piloting physics-based simulation layers merged with operational telemetry for process optimization.
Global Operational Technology Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with captive automation divisions, creating tiered competition between integrated platform providers and specialized control system vendors. Siemens AG, Honeywell International Inc., and Schneider Electric SE anchor the premium tier through certification depth and service attach rates. Mid-scale specialists compete on vertical expertise in process industries or discrete manufacturing. Dominant competitive moves include portfolio diversification into edge computing software and strategic partnerships with hyperscale cloud providers for hybrid OT-IT architectures.
Among European-headquartered industrial conglomerates, Siemens AG and Schneider Electric SE exemplify the integrated platform archetype, leveraging automation-to-software portfolios to capture European manufacturing upgrade cycles. Honeywell International Inc. occupies a parallel position among US-based diversified industrials, representing deep specialization in process control systems for energy and refining applications. Rockwell Automation and ABB Ltd. sit within the mid-scale specialist tier, anchoring competitive positioning through vertical expertise in discrete manufacturing and robotics integration respectively.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International Inc. |
| Schneider Electric SE |
| ABB Ltd. |
| Emerson Electric Co. |
| Rockwell Automation |
| General Electric |
| IBM |
| Hewlett Packard Enterprise Development LP |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for industrial-grade FPGAs and secure microcontrollers concentrate pricing power among Taiwan-based foundry customers, while European automation vendors absorb inventory carrying costs to buffer against IEC 62443 certification delays. This inventory-to-pricing dynamic rewards pre-certified suppliers with margin stability and exposes uncertified entrants to cost compression during compliance gaps.
Pricing Analysis
Certification level creates the primary spread between IEC 62443-compliant system integrators and uncertified component vendors. Three-tier pricing structure across certified premium, transitional standard, and uncertified economy levels reflects audit trail depth and security assurance granularity. Pricing pressure stems from semiconductor foundry concentration in Taiwan, compressing margins for automation hardware vendors dependent on single-source wafer supply. Process industries in energy and refining exhibit lowest price sensitivity due to uptime economics, while discrete manufacturing buyers in automotive assembly prioritize per-unit cost reduction.
Supply Chain Analysis
Strategic stockpiling of industrial processors and secure elements dominates over just-in-time preferences as geopolitical risk reshapes procurement protocols. Supply concentrates in Taiwan for advanced foundry capacity, Germany for precision mechanical components, and China for sensor assembly and edge hardware fabrication. Raw material dependencies span silicon wafers, rare earth magnets for motor drives, and copper for industrial connectivity infrastructure. Single-source vulnerability in Taiwan semiconductor fabrication exposes automation vendors to disruption risk. Distribution runs through authorized system integrators for SCADA and DCS platforms, with direct OEM relationships for PLC and HMI replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Operational Technology Market sits at an inflection where IEC 62443 certification mandates and AI-enabled process control convergence are compressing vendor qualification windows. Procurement specifications hardening around verified cybersecurity postures favor pre-certified solution providers.
For Market Incumbents: Consolidate certification depth as a defensive moat by accelerating IEC 62443 component-level ratings across edge computing portfolios. Capture margin stability through captive silicon sourcing arrangements that buffer Taiwan foundry concentration. Channel control through exclusive system integrator partnerships locks out uncertified competitors from brownfield retrofit cycles in German automotive clusters. For New Entrants and Emerging Players: Managed service gaps in predictive maintenance for North American oil and gas midstream operations offer the most penetrable white-space target. Unbundle hardware from performance-based uptime contracts to transfer cyber liability onto vendor balance sheets. Go-to-market execution should anchor on SCADA-as-a-service pilots with pipeline operators seeking to outsource operational responsibility. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certification friction and multi-year compliance timelines are raising barriers for organic entrant scaling. Target acquisition profiles center on mid-scale specialists with vertical expertise in process control or discrete manufacturing, possessing existing IEC 62443 audit trails. The signal to watch is enforcement timeline acceleration for EU Cyber Resilience Act mandates, which would compress procurement windows toward pre-certified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62443 Certification Acceleration | Pre-certified vendors capture procurement specifications hardening under EU Cyber Resilience Act enforcement timelines. |
| Edge Computing Platform Integration | German automotive clusters standardize containerized edge nodes to synchronize mixed-vendor production lines. |
| Predictive Maintenance Service Unbundling | North American pipeline operators transfer cyber liability to vendors through performance-based SCADA contracts. |
| Strategic Partnership with Hyperscale Cloud Providers | Hybrid OT-IT architectures enable sub-second latency for AI-enabled process optimization workloads. |
| Backward Integration into Secure Silicon Sourcing | Captive supply of industrial-grade processors buffers Taiwan foundry concentration risk for automation hardware vendors. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with automation vendor executives, plant engineers at asset-intensive facilities, system integrators, and cybersecurity certification auditors; and secondary validation against IEC 62443 certification databases, NIST SP 800-82 guidance documents, SEC filings from diversified industrial conglomerates, and trade flow data for industrial semiconductor imports. Bottom-up triangulation across installed base estimates and top-down cross-checks against capital expenditure disclosures anchored volume and value outputs.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, technology layer, end-user industry, and application intensity, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from trend extrapolation of historical capital deployment cycles and forward assessment of compliance-driven procurement acceleration. Forecast inputs incorporated MEE enforcement timelines for Chinese steel and cement producers, PLI scheme absorption rates in Indian industrial corridors, and FERC grid reliability directive implementation pace.
Underlying assumptions cover sustained enforcement of EU Cyber Resilience Act mandates, continued Taiwan semiconductor foundry operational stability, and German automotive cluster investment continuity, with deviation risk concentrated in geopolitical disruption to industrial processor supply and regulatory timeline delays. Revision becomes warranted when IEC 62443 certification backlog crosses eighteen-month thresholds or when Taiwan foundry capacity utilization drops below sustainable allocation levels for industrial-grade silicon.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Motion Control Drive Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
Industrial Robotic Motors Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
Utility Automation Market
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Global Smart Warehousing Market
Industrial Automation
Hardware in the Loop Market
Industrial Automation
SCADA Alarm Management Market
Industrial Automation
US Smart Manufacturing Market