
 Smart and Connected Elevators and Elevators Control Systems Market | 2026-2036
Smart and Connected Elevators and Elevators Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart and Connected Elevators and Elevators Control Systems Market Analytics
Healthcare facility managers are rotating into the fastest-growing buyer archetype for connected elevator platforms, replacing traditional commercial developers as the primary demand engine. OTIS Elevator Company leverages its predictive maintenance portfolio to anchor North American hospital contracts. KONE Corporation sustains R&D intensity across IoT-enabled dispatch systems. ThyssenKrupp AG differentiates through gearless motor integration for high-rise healthcare infrastructure.
Smart and Connected Elevators and Elevators Control Systems comprise electromechanical vertical transport platforms augmented with sensor networks, edge computing nodes, and cloud-connected control panels that enable real-time traffic optimization, fault prediction, and autonomous dispatch algorithms operating at sub-100-millisecond response intervals. These systems serve the primary commercial purpose of eliminating unplanned downtime in buildings where vertical mobility failure incurs operational or life-safety consequences. Smart elevators now lead technology segment value pools as machine learning algorithms displace static traffic programming in premium installations. Maintenance services command the most durable margin structure within service type segmentation due to recurring revenue attachment rates on connected hardware fleets.
The EU Machinery Directive, EN 81-20 standards, and China's GB 7588 safety code collectively mandate redundant braking systems and remote diagnostic capabilities for all new connected elevator installations above specified height thresholds. FDA building infrastructure guidelines for healthcare facilities in the United States further specify elevator response protocols for emergency patient transport scenarios. Stakeholders must monitor regulatory divergence between European CE marking requirements and evolving Chinese GB standard harmonization efforts to avoid compliance fragmentation across multinational deployment portfolios.
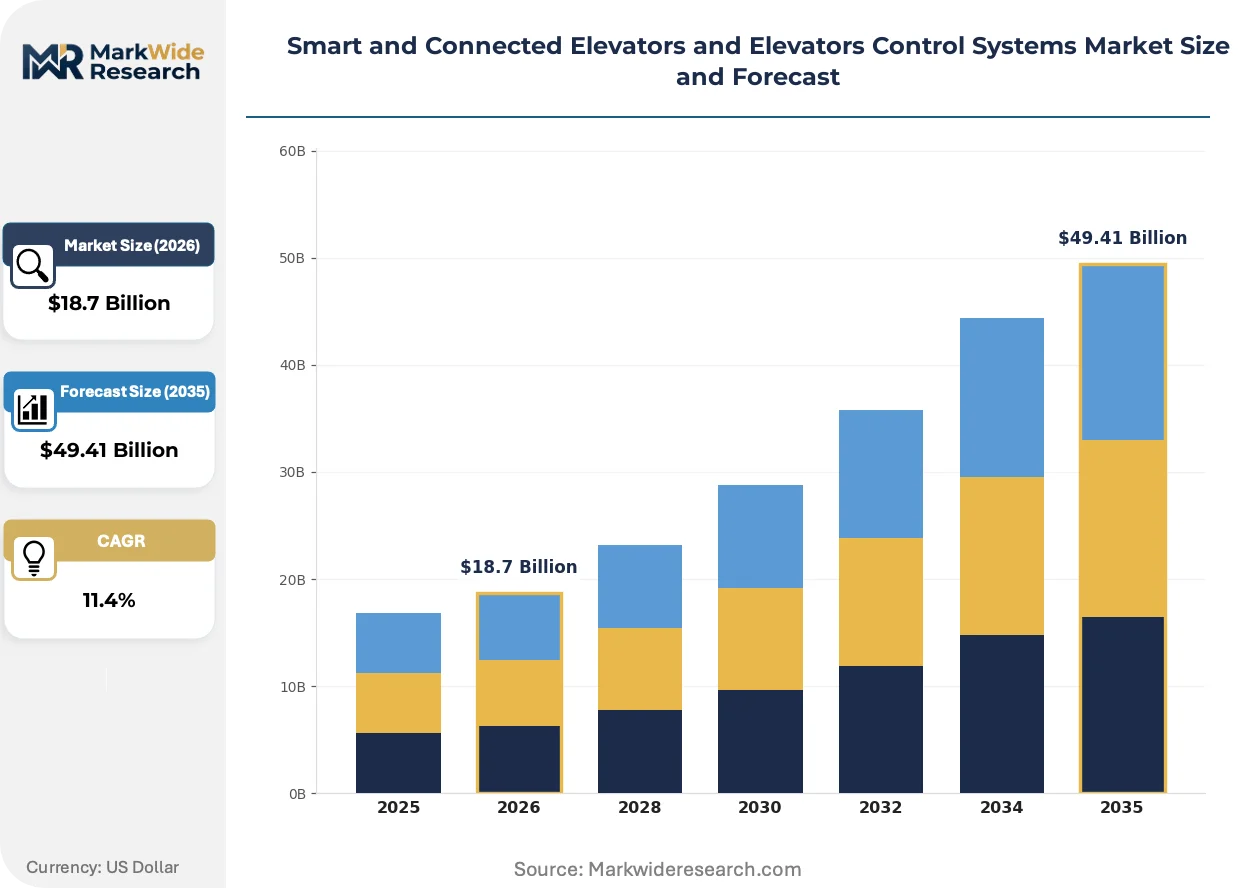
Market Dynamics
Predictive maintenance algorithms are compressing service contract structures across commercial real estate portfolios, forcing incumbent vendors to reprice recurring revenue streams around uptime guarantees rather than scheduled visits.
Growth Catalysts
- EU Machinery Directive mandates:Remote diagnostic capabilities are now compulsory for connected elevator installations above specified height thresholds, creating regulatory pull for sensor-embedded control systems.
- China's tier-one urban verticalization:Shanghai and Beijing municipal planners are mandating smart building certifications for new commercial towers above 150 meters, accelerating specification of IoT-enabled dispatch platforms.
- Machine learning traffic optimization:Edge-deployed neural networks are reducing average passenger wait times by dynamically reallocating car assignments based on real-time lobby queue detection.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motors for gearless elevator systems depend on Chinese-processed neodymium, exposing procurement costs to export quota volatility.
- EN 81-20 compliance timelines:European safety standard recertification cycles extend 18-24 months for retrofitted connected systems, freezing upgrade decisions in aging building stock.
- Escalator substitution in mid-rise:Inclined moving walkways are capturing transport demand in 4-6 story healthcare and retail facilities where elevator capex cannot be justified.
Strategic Opportunities
- India's hospital infrastructure expansion:The country's PLI scheme for medical device manufacturing is funding vertical expansion of tertiary care facilities, opening specification windows for emergency-priority elevator systems.
- Digital twin convergence with BIM:Building information modeling platforms are integrating elevator performance simulations during design phase, enabling predictive specification by architects rather than reactive procurement by contractors.
- F-Gas Regulation phase-down:EU restrictions on hydrofluorocarbon refrigerants are accelerating replacement cycles for hydraulic elevator power units, creating retrofit demand for oil-free electromechanical alternatives.
Industry Challenges
- Field technician skill gaps:Mechatronics competencies combining PLC programming with cloud dashboard interpretation remain scarce in legacy elevator service workforces across North American and European markets.
- Legacy controller integration friction:Pre-2000 electromechanical relay systems in installed base require custom protocol gateways to connect with modern IoT platforms, extending deployment timelines and eroding margin on retrofit contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart and Connected Elevators and Elevators Control Systems Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Elevators, Smart Elevators, Hydraulic Elevators, Gearless Elevators Technology: IoT Integration, Machine Learning, Data Analytics, Remote Monitoring End User: Residential Buildings, Commercial Facilities, Industrial Sites, Hospitals Service Type: Installation Services, Maintenance Services, Modernization Services, Consulting Services |
| Companies Covered | OTIS Elevator Company, KONE Corporation, ThyssenKrupp AG, Schindler Group, Hitachi Ltd., Hyundai Elevator Co., Ltd., Mitsubishi Electric Corporation, Fujitec Co., Ltd., Toshiba Elevator and Building Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart and Connected Elevators and Elevators Control Systems Market Evolving Landscape
Edge computing architectures are redistributing intelligence from cloud data centers to elevator machine room nodes, enabling sub-100-millisecond response intervals for safety-critical fault detection.
Digital twin simulation platforms are decomposing traditional commissioning workflows by enabling virtual stress-testing of dispatch algorithms against building-specific traffic patterns before physical installation. Healthcare facility operators in Germany and Japan are piloting these tools to validate emergency patient transport scenarios. The technology is decomposing the historical separation between equipment procurement and building systems integration, compressing project handoff timelines.
China's GB 7588 safety code revisions are mandating redundant braking verification through independent sensor channels, forcing control system redesigns for all new installations above 75 meters. Domestic manufacturers are accelerating R&D spending to meet 2025 compliance deadlines ahead of multinational competitors. High-rise residential towers in Shenzhen and Guangzhou represent the most affected category, with developers pre-ordering certified systems 18 months ahead of construction completion.
Hospital procurement departments are unbundling elevator service contracts from general facilities management agreements, establishing direct vendor relationships for uptime-critical vertical transport. This behavioral shift displaces the traditional general contractor as the specification gatekeeper in US and UK healthcare construction. The pattern is most visible in acute care facilities where elevator failure directly impacts patient mortality metrics and regulatory accreditation status.
Smart and Connected Elevators and Elevators Control Systems Market Segmentation
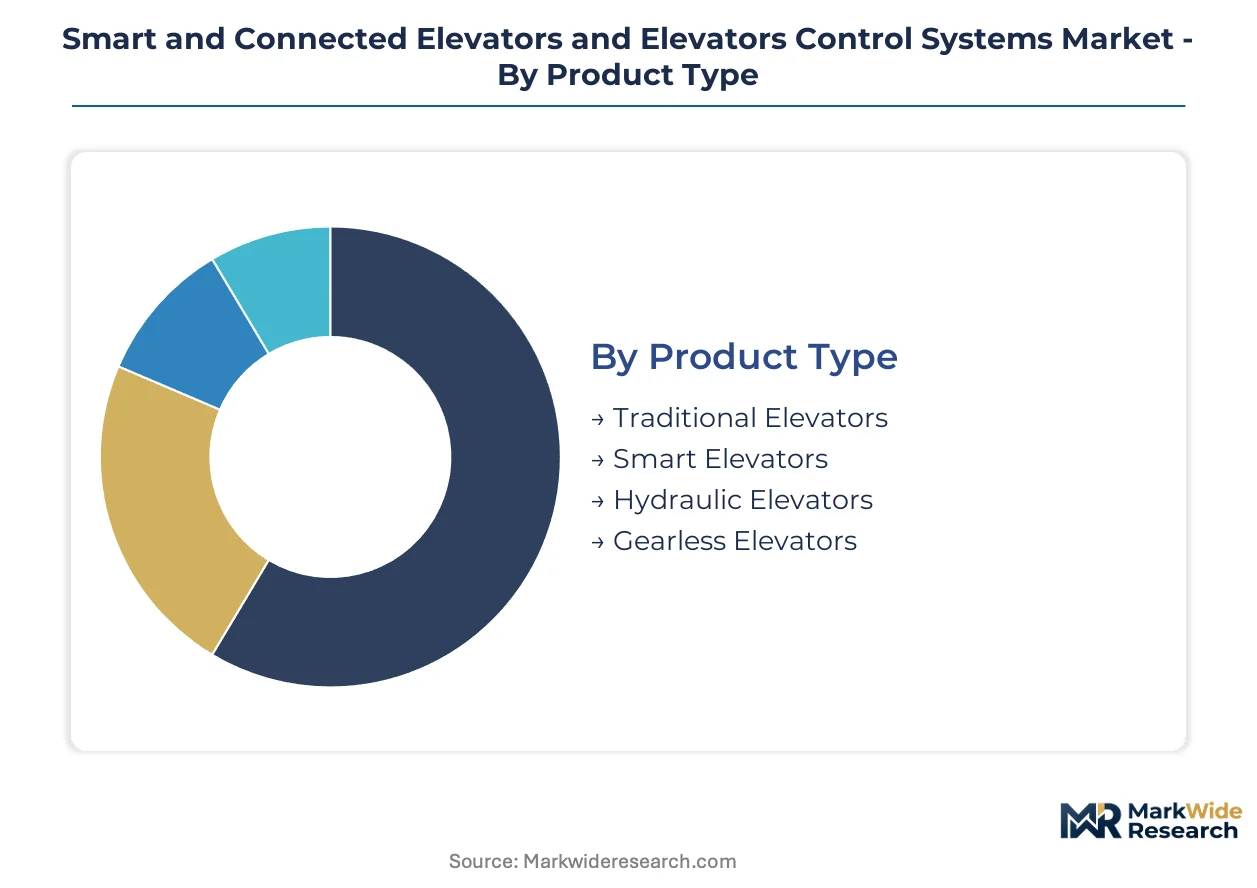
Segmentation reveals how regulatory mandates, technology substitution, and service revenue models reshape competitive positioning across the connected elevator value chain. Procurement patterns diverge sharply between new construction and retrofit contexts, forcing vendors to maintain parallel commercial architectures.
Product Type:
EU Machinery Directive height thresholds and China's GB 7588 revisions create divergent compliance burdens across motor configurations, splitting procurement between certified new builds and legacy retrofits.
- Smart Elevators:Sensor-embedded platforms with edge computing nodes execute autonomous dispatch algorithms at sub-100-millisecond intervals. Demand concentrates in Shanghai and Beijing municipal smart building certifications for towers exceeding 150 meters, where machine learning traffic optimization reduces passenger wait times through real-time lobby queue detection.
- Gearless Elevators:Permanent magnet motor systems eliminate mechanical reduction stages, enabling direct-drive efficiency in high-rise healthcare infrastructure. China's neodymium processing dominance exposes procurement costs to export quota volatility, compressing margin structures for European and North American hospital contracts dependent on rare earth magnet supply chains.
- Traditional Elevators:Static traffic programming and relay-based control systems dominate aging installed base across North American commercial real estate.
- Hydraulic Elevators:Oil-powered piston mechanisms serve low-rise applications where shaft depth constraints prohibit cable drum configurations.
Established volume favors Traditional Elevators; emerging adoption favors Smart Elevators.
Technology:
Response latency requirements separate safety-critical edge deployment from cloud-dependent analytics tiers, creating distinct vendor specialization zones.
- IoT Integration:Cloud-connected control panels and sensor networks enable real-time performance telemetry across distributed elevator fleets. Germany and Japan healthcare facility operators deploy these architectures for emergency patient transport validation, unbundling elevator service contracts from general facilities management agreements.
- Machine Learning:Neural network dispatch algorithms dynamically reallocate car assignments based on predicted traffic patterns rather than static floor programming. Edge-deployed inference engines in Shenzhen and Guangzhou high-rise residential towers satisfy China's GB 7588 redundant braking verification mandates through independent sensor channel architectures.
- Remote Monitoring:Continuous telemetry streams from machine room nodes to vendor operations centers compress mean-time-to-repair intervals.
- Data Analytics:Fleet-level pattern recognition identifies component degradation signatures before fault manifestation.
IoT Integration commands current deployment share; Machine Learning exhibits steepest expansion trajectory as predictive capabilities displace reactive maintenance.
End User:
Life-safety consequences of vertical mobility failure determine specification stringency and service contract pricing power across building typologies.
- Hospitals:Acute care facilities require emergency-priority elevator systems with guaranteed response protocols for patient transport scenarios. FDA building infrastructure guidelines in the United States specify elevator performance standards tied to mortality metrics and regulatory accreditation, establishing direct vendor relationships that displace general contractor gatekeepers.
- Commercial Facilities:Office towers and retail complexes drive predictive maintenance platform adoption as facility managers prioritize uptime guarantees over scheduled visit contracts. EN 81-20 recertification cycles extending 18-24 months freeze upgrade decisions in aging European building stock.
- Residential Buildings:High-rise towers in China's tier-one cities face municipal smart building certification mandates.
- Industrial Sites:Freight-dominant vertical transport prioritizes load capacity over passenger experience metrics.
Commercial Facilities anchor current revenue concentration; Hospitals are gaining share fastest as healthcare infrastructure expansion accelerates specification windows.
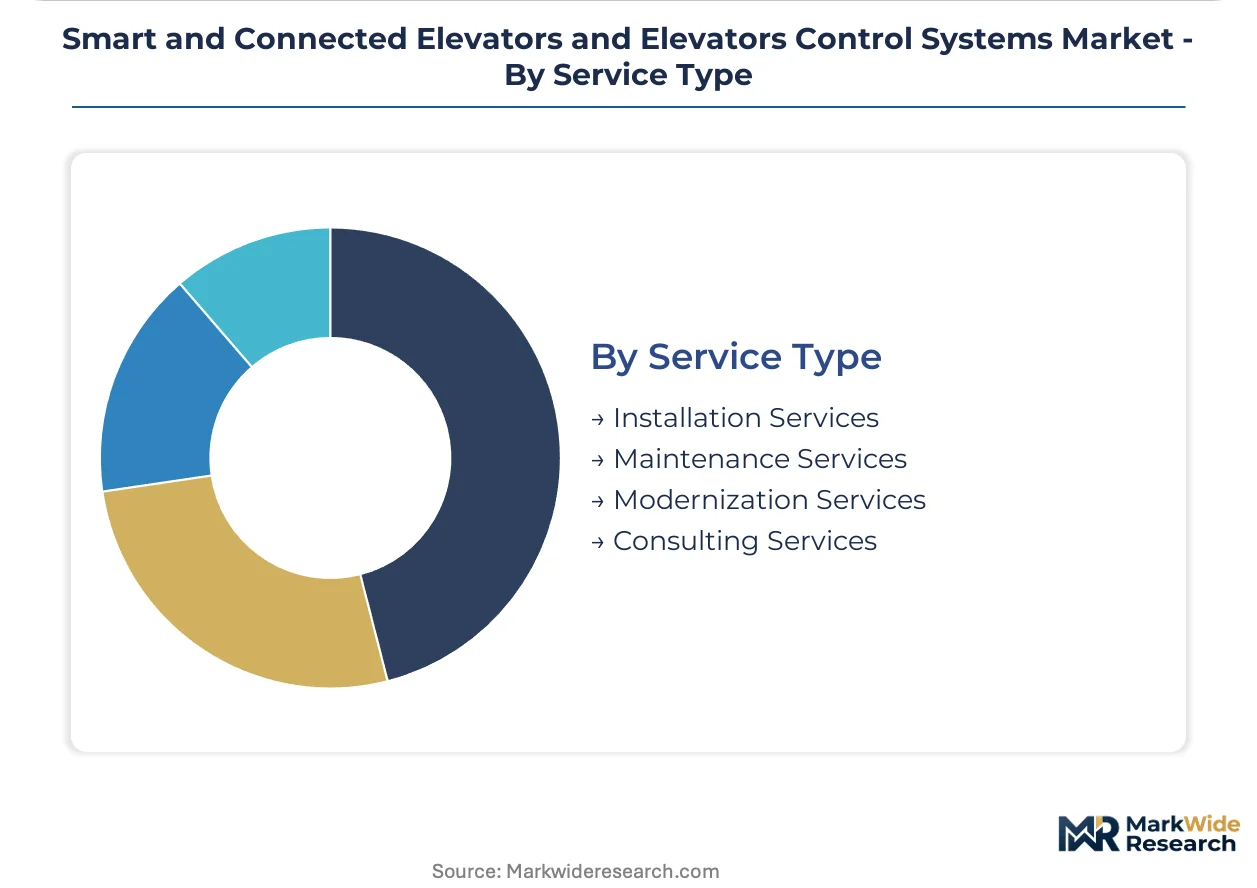
Service Type:
Recurring revenue attachment rates on connected hardware fleets determine margin durability across contract structures.
- Maintenance Services:Predictive maintenance algorithms compress traditional service contract frameworks by substituting uptime guarantees for scheduled technician visits. North American hospital contracts now specify performance-based pricing tied to availability metrics rather than labor-hour billing.
- Modernization Services:Retrofit of pre-2000 electromechanical relay systems with protocol gateways to connect IoT platforms extends deployment timelines. Custom integration requirements erode margin on European contracts where EN 81-20 compliance demands 18-24 month recertification cycles.
- Installation Services:New construction specification concentrates in certified smart building developments.
- Consulting Services:Digital twin convergence with building information modeling enables predictive specification during design phase.
Maintenance Services deliver margin durability; Modernization Services face structural headwinds from legacy controller integration friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German elevator component manufacturers export predictive maintenance platforms to healthcare facility operators across the United States and United Kingdom. This trade corridor reflects Europe's engineering concentration meeting North Atlantic hospital infrastructure renewal cycles.
United States
Acute care hospital construction and FDA building infrastructure guidelines drive specification of emergency-priority elevator systems. The FDA mandates elevator response protocols tied to patient mortality metrics and regulatory accreditation status. Texas Medical Center in Houston anchors the nation's largest hospital elevator procurement cluster, with facility managers unbundling service contracts from general facilities management agreements.
Germany
Digital twin convergence with building information modeling accelerates predictive specification by architects during design phase. The F-Gas Regulation phase-down accelerates replacement cycles for hydraulic elevator power units, creating retrofit demand for oil-free electromechanical alternatives. Healthcare facility operators in Berlin and Munich pilot virtual stress-testing tools for emergency patient transport validation.
China
Shanghai and Beijing municipal smart building certifications mandate IoT-enabled dispatch platforms for commercial towers exceeding 150 meters. GB 7588 safety code revisions mandate redundant braking verification through independent sensor channels for installations above 75 meters. High-rise residential towers in Shenzhen and Guangzhou represent the most affected category, with developers pre-ordering certified systems 18 months ahead of construction completion.
Japan
Healthcare facility operators deploy IoT integration architectures for emergency patient transport scenario validation. METI industrial standards shape edge computing deployment specifications for safety-critical fault detection. Osaka and Nagoya hospital clusters unbundle elevator service contracts to establish direct vendor relationships for uptime-critical vertical transport.
India
The PLI scheme for medical device manufacturing funds vertical expansion of tertiary care facilities, opening specification windows for emergency-priority elevator systems. Central Electricity Authority building codes tighten electrical safety requirements for connected control panels. Maharashtra and Karnataka hospital infrastructure projects concentrate demand for predictive maintenance platform adoption.
Smart and Connected Elevators and Elevators Control Systems Market Competitive Landscape
Listed leaders compete with private specialists across predictive maintenance contract structures and gearless motor integration depth. Market structure concentrates around multinational conglomerates with captive service networks and regional specialists with localized installation expertise. Three archetypes dominate: full-stack vertical transport providers, component specialists focused on control systems and sensors, and maintenance-centric service platforms. Competitive moves center on predictive maintenance algorithm licensing and geographic expansion through hospital infrastructure procurement channels.
Among diversified industrial conglomerates, OTIS Elevator Company and ThyssenKrupp AG occupy positions representing integrated electromechanical and digital service capabilities. KONE Corporation exemplifies the specialist archetype with concentrated exposure to IoT-enabled dispatch systems and Nordic engineering heritage. These three entities anchor the premium tier where predictive maintenance contracts and uptime guarantees displace traditional scheduled visit billing structures.
| Leading Market Players |
|---|
| OTIS Elevator Company |
| KONE Corporation |
| ThyssenKrupp AG |
| Schindler Group |
| Hitachi Ltd. |
| Hyundai Elevator Co., Ltd. |
| Mitsubishi Electric Corporation |
| Fujitec Co., Ltd. |
| Toshiba Elevator and Building Systems Corporation |
| Others |
Value Network & Pricing Analysis
Oil-free electromechanical motor substitution for hydraulic power units simultaneously redistributes procurement toward Chinese permanent magnet suppliers and compresses margin structures for European hospital contracts exposed to neodymium export quota volatility. This input transition forces pricing recalibration across retrofit and new-build segments as vendors absorb rare earth magnet cost uncertainty into long-term service agreements.
Pricing Analysis
Smart elevator systems with edge-deployed neural networks command substantial premiums over relay-based traditional platforms and static-programmed legacy installations, while next-generation digital twin-integrated configurations stratify above both. Pricing stratifies across premium, standard, and economy tiers based on GB 7588 certification grade and predictive maintenance bundling depth. Cost compression in the traditional elevator tier is intensifying because EN 81-20 recertification timelines freeze upgrade decisions and extend sales cycles. Commercial facility managers exhibit highest price sensitivity due to capex constraints, whereas acute care hospital procurement departments prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Eighteen-month pre-order lead times for GB 7588-certified control systems in Shenzhen and Guangzhou signal inventory strain across the sensor-embedded controller tier. Manufacturing concentrates in China, Germany, and Japan, with permanent magnet motors drawing from Chinese-processed neodymium, Japanese precision electronics, and German mechanical engineering. Single-source vulnerability in rare earth magnet processing exposes margin structures to export quota volatility. Distribution runs through captive service networks of multinational conglomerates and regional installation specialists with localized maintenance expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected elevator platforms are crossing a platform-economics inflection where digital twin convergence with building information modeling ecosystems redefines specification authority from general contractors to architect-led predictive procurement.
For Market Incumbents: Fortify predictive maintenance algorithm portfolios through backward integration into sensor hardware production, defending against component specialists capturing margin in the edge computing node tier. Deepen certification investment ahead of China's 2025 GB 7588 compliance deadlines to lock out multinational competitors in high-rise residential tower procurement. Prioritize direct hospital contracting relationships that displace general contractor gatekeepers in US and UK acute care facility construction. For New Entrants and Emerging Players: Lead with digital twin simulation tools for emergency patient transport validation, targeting Germany and Japan healthcare facility operators piloting virtual commissioning workflows. India's PLI-funded tertiary care hospital expansion represents the most penetrable geography, with specification windows opening for emergency-priority elevator systems. Pursue architect-direct go-to-market channels that intercept procurement during building information modeling design phases rather than reactive contractor bidding. For Investors and Strategic Acquirers: The market sits at a regulatory-compliance acceleration phase that favors component specialists with captive sensor channel expertise and protocol gateway integration capabilities. Long-term viability over the coming decade hinges on recurring revenue attachment rates for predictive maintenance contracts displacing scheduled visit billing. Monitor GB 7588 certification completion rates among domestic Chinese manufacturers as the inflection signal for competitive positioning shifts in tier-one city high-rise construction.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | OTIS leverages uptime guarantees to anchor North American hospital contracts against scheduled-visit competitors. |
| Backward Integration into Sensor Hardware | KONE secures margin control over IoT-enabled dispatch system edge computing nodes. |
| Digital Twin Convergence Partnership | ThyssenKrupp integrates gearless motor simulations with architect BIM platforms during German healthcare design phases. |
| GB 7588 Certification Acceleration | Domestic Chinese manufacturers pre-position certified systems 18 months ahead of Shenzhen high-rise completion. |
| Direct Hospital Contracting Channel | Texas Medical Center facility managers unbundle elevator procurement from general facilities management agreements. |
Research Methodology
A spread of perspectives from elevator OEM procurement directors, hospital facilities managers, architect specification leads, and predictive maintenance software engineers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against EU Machinery Directive implementation timelines, FDA building infrastructure guidelines, China's GB 7588 revision drafts, and SEC filings from listed vertical transport conglomerates. Bottom-up triangulation across installed base estimates and top-down cross-checks against municipal smart building certification mandates anchored volume assumptions.
Segmentation dimensions modeled span product type, technology tier, end-user building typology, and service contract structure across the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory mandate acceleration effects and technology substitution dynamics. Forecast inputs included Shanghai and Beijing municipal certification timelines, EN 81-20 recertification cycle durations, and rare earth magnet export quota volatility assumptions.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement, FDA building infrastructure guidelines, and China's GB 7588 implementation; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Electric Gripper Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Middle East Programmable Logic Controller (PLC) Market
Industrial Automation
Industrial Data Loggers Market
Industrial Automation
Port Equipment Automation Market
Industrial Automation
Intelligent Conveyor System Market
Industrial Automation
North America Automated Rotary Indexing Table Market
Industrial Automation
HMI Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
United States SCADA Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Asia-Pacific Medical Automation Market
Industrial Automation
Europe Process Automation Market