
 Global Food Texturants Market | 2026-2036
Global Food Texturants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Texturants Market Foresight
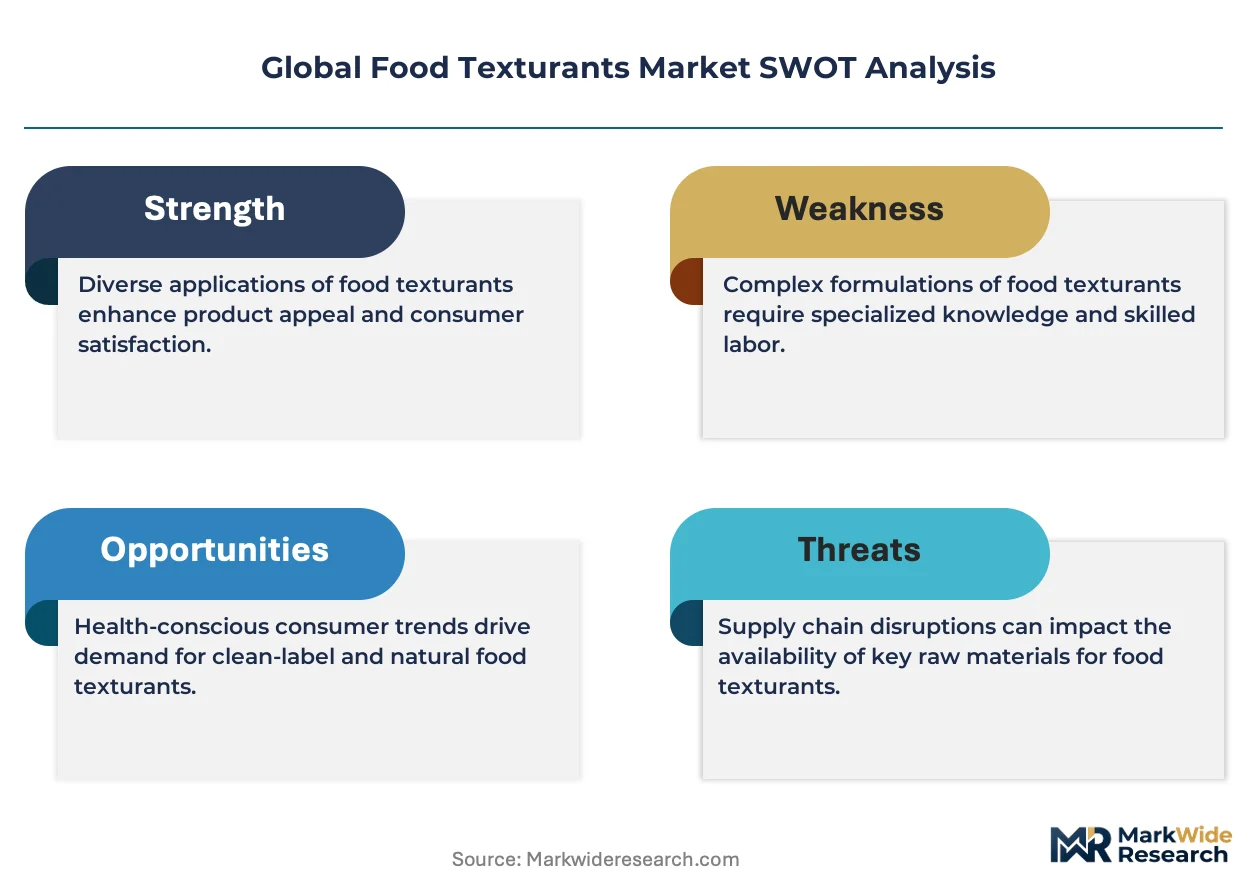
Clean-label specification tiers is unwinding conventional additive portfolios as food manufacturers face reformulation mandates across developed markets. Cargill leverages its plant-protein extraction infrastructure to dominate European bakery and dairy texturant supply. Ingredion sustains R&D intensity in waxy maize and tapioca-derived starch systems for clean-label gelling applications. Kerry Group specializes in microbial fermentation of hydrocolloids, positioning its portfolio for EFSA-compliant label claims.
Food texturants comprise functional ingredients that modify rheological properties, viscosity, and mouthfeel through molecular interactions with water, fat, and protein matrices; hydrocolloids such as xanthan gum and carrageenan achieve viscosities ranging from 500 to 5,000 centipoise at concentrations below 1% by weight, serving primarily to stabilize emulsions and control moisture migration in processed foods. Hydrocolloids lead product type revenue due to their ubiquity in dairy and beverage stabilization, while plant-based source materials are expanding fastest as manufacturers replace animal-derived gelatin with pectin and locust bean gum systems. Functional application segments show margin concentration in gelling and emulsifying, where technical complexity creates formulation lock-in with beverage producers and confectionery makers.
EFSA maintains stringent purity specifications for food additives under EU Regulation 1333/2008, while the EU Green Deal drives substitution toward sustainably sourced texturants with verified carbon footprints. FDA GRAS self-affirmation and FSMA preventive controls shape US market access requirements for imported hydrocolloid and starch ingredients. Stakeholders must monitor evolving EFSA re-evaluations of carrageenan and titanium dioxide alongside emerging ISO standards for carbon-labeled texturants to anticipate portfolio restructuring requirements.
Market Dynamics
Clean-label mandates from EFSA and the EU Green Deal are forcing wholesale reformulation of hydrocolloid portfolios, compressing demand for synthetic additives while expanding plant-derived alternatives across European bakery and dairy processing.
Growth Catalysts
- EFSA Clean-Label Guidance:Reformulation deadlines for processed foods are accelerating substitution of carrageenan with pectin and locust bean gum systems in French and German dairy manufacturing.
- Plant-Protein Extraction Infrastructure:Investment in enzymatic processing capacity for pea and fava bean proteins is expanding texturant yield and functional performance in meat analog applications.
- Carbon Footprint Verification:ISO standards for carbon-labeled texturants are creating procurement preferences among Nordic and Benelux retailers seeking scope-three emissions reductions.
Market Restraints
- Seaweed Supply Concentration:Carrageenan and agar production clusters in the Philippines and Indonesia expose processors to climate-driven harvest volatility and price spikes.
- Clean-Label Cost Premium:Plant-derived hydrocolloids command 15-40% higher input costs versus modified starches, squeezing margins in private-label bakery segments.
- Functional Performance Gaps:Pectin gelling systems require precise calcium concentration control that industrial bakeries struggle to replicate at gelatin's operational simplicity.
Strategic Opportunities
- Fermentation-Derived Hydrocolloids:Precision fermentation of microbial cellulose and xanthan gum variants offers EFSA-compliant label claims without agricultural land use.
- Japanese Functional Foods:FOSHU and Foods with Function Claims regulatory pathways favor texture-modified products targeting elderly swallowing difficulties and satiety management.
- Direct-to-Manufacturer Platforms:Digital ingredient marketplaces are compressing distribution layers between hydrocolloid producers and mid-sized European confectionery specialists.
Industry Challenges
- Reformulation Expertise Scarcity:Food technologists with hydrocolloid synergy modeling capabilities are concentrated among legacy ingredient houses, limiting mid-tier manufacturer access.
- Dual Certification Burden:Simultaneous EFSA Novel Food approvals and FDA GRAS self-affirmations extend product launch timelines for cross-Atlantic texturant introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Texturants Market |
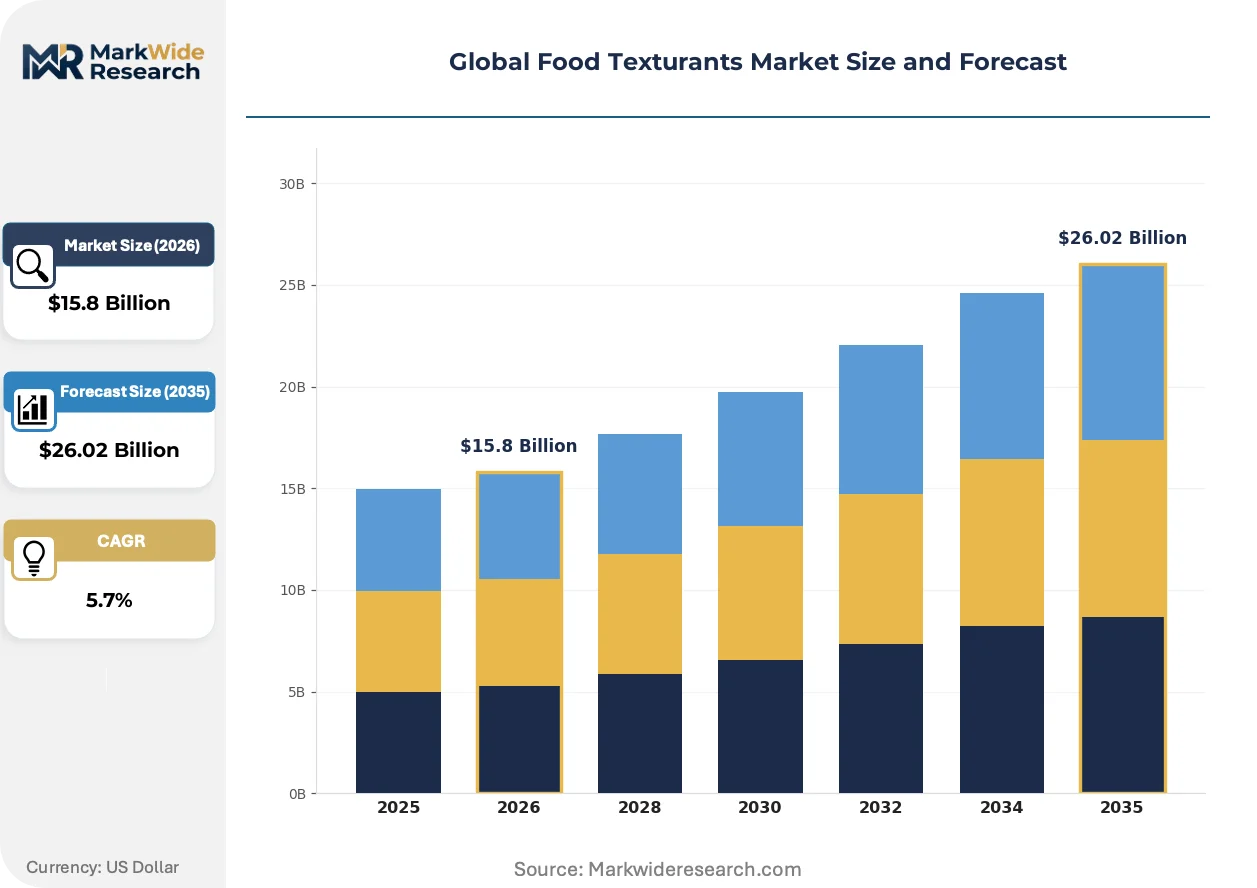
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $26.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloids, Proteins, Starches, Emulsifiers, Lipids, Enzymes Functional Application: Thickening, Stabilizing, Gelling, Emulsifying, Foaming, Binding Source Material: Plant-based, Animal-derived, Microbial, Algal, Synthetic End Use Customer: Food Processing Manufacturers, Beverage Producers, Confectionery Makers, Dairy Product Developers, Snack Food Creators |
| Companies Covered | Cargill, Archer Daniels Midland, Ingredion, Tate & Lyle, DuPont, Kerry Group, International Flavors & Fragrances, CP Kelco, DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Texturants Market Shifts & Advancements
Enzymatic texturant processing and microbial fermentation platforms are displacing conventional extraction methods, while regulatory carbon accounting and clean-label specifications reshape competitive requirements across developed markets.
Precision fermentation of microbial hydrocolloids is decomposing the traditional agricultural supply chain for texturant raw materials. Biotech specialists in Denmark and the Netherlands are scaling xanthan gum and bacterial cellulose production in controlled bioreactor environments. This technology is decomposing price volatility linked to seaweed harvests and tropical weather patterns while enabling batch-to-batch functional consistency that plant extraction cannot match.
EU Green Deal carbon border adjustment mechanisms and EFSA sustainability disclosure requirements are tightening scrutiny of imported hydrocolloid supply chains. Processors must now document deforestation-free sourcing for tropical gums and energy intensity for modified starches. German and French dairy conglomerates are responding by qualifying European-sourced pectin and locally processed waxy maize starches to preempt compliance exposure.
Ingredient buyers are consolidating supplier relationships around full-service texture solution providers rather than commodity hydrocolloid merchants. Mid-sized European bakery and plant-based meat manufacturers now demand integrated formulation support, application testing, and regulatory documentation bundled with raw material supply. This preference shift is most pronounced in the United Kingdom and Netherlands, where technical service capabilities determine contract awards ahead of unit pricing.
Global Food Texturants Market Segmentation
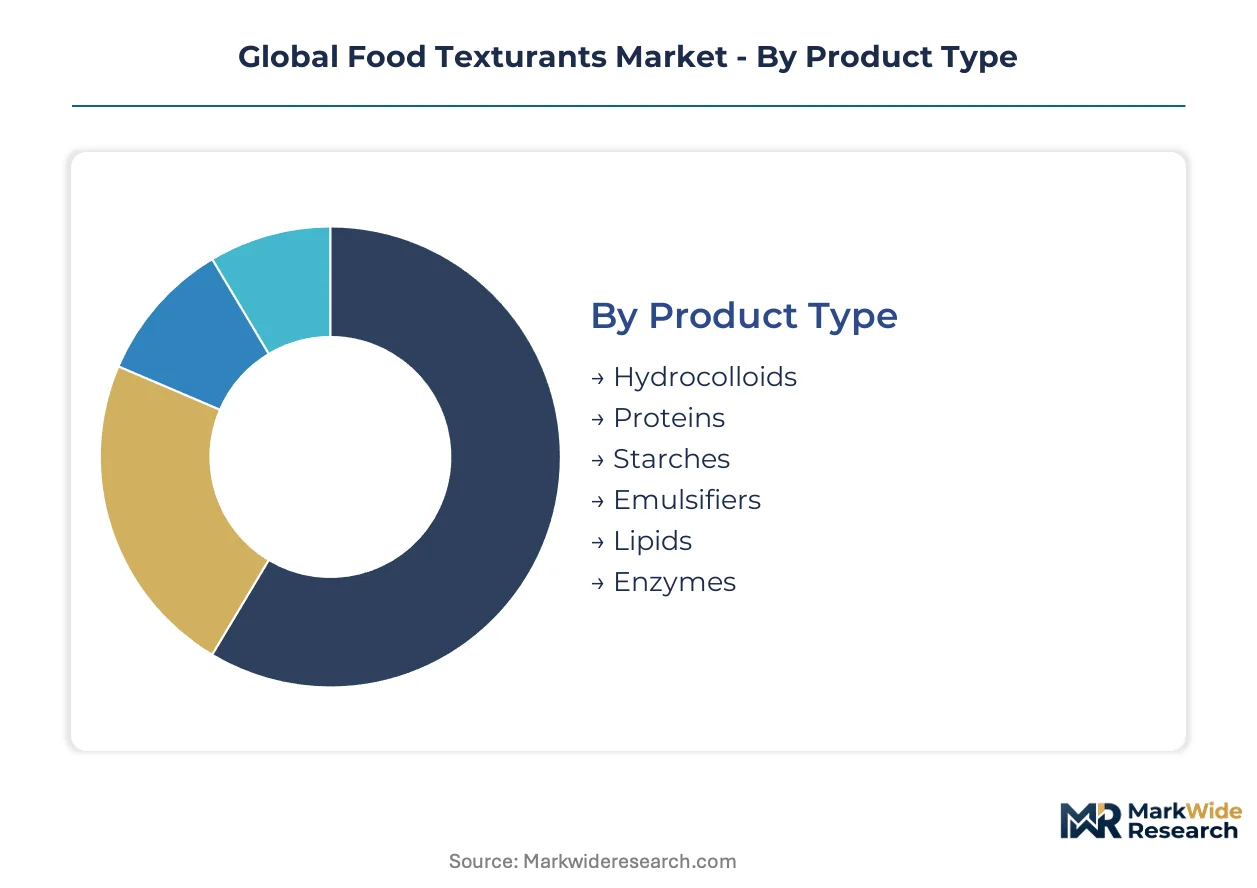
Food texturants operate across divergent technical specifications and regulatory environments that reshape procurement priorities by geography. Manufacturers segment portfolios by molecular function, raw material provenance, and end-use processing requirements to align with EFSA clean-label mandates and carbon accounting pressures.
Product Type:
Hydrocolloids and starches concentrate supply in European domestic markets, while protein-based texturants and specialized emulsifiers flow through export-oriented trade corridors into Asia-Pacific processing hubs.
- Hydrocolloids:Xanthan gum, carrageenan, and pectin modify rheological properties at concentrations below 1% by weight, achieving viscosities between 500 and 5,000 centipoise. German and French dairy manufacturers drive substitution toward pectin and locust bean gum systems as EFSA reformulation deadlines compress carrageenan demand.
- Proteins:Pea, fava bean, and wheat gluten isolates build elastic networks in meat analog and bakery applications through controlled hydration and thermal gelation. Investment in enzymatic extraction capacity across the Netherlands and Denmark is expanding functional yield for plant-based meat developers.
- Starches:Waxy maize and tapioca-derived native starches serve clean-label gelling without chemical modification.
- Emulsifiers:Lecithin and mono-diglycerides stabilize oil-water interfaces in confectionery and beverage systems.
- Lipids:Fractionated fats and crystalline shortenings contribute mouthfeel and structure in baked goods.
- Enzymes:Amylases and transglutaminases modify protein cross-linking and starch breakdown for texture control.
Hydrocolloids hold the largest share; momentum sits with proteins as enzymatic processing infrastructure scales across Northern Europe.
Functional Application:
Margin concentration varies sharply by technical complexity, with multi-functional systems commanding premium positioning against single-attribute commodity additives.
- Thickening:Hydrocolloid hydration builds viscosity in sauces, dressings, and dairy alternatives through water-binding capacity. German beverage producers prioritize xanthan gum for suspension stability in functional drinks.
- Gelling:Calcium-reactive pectin and thermo-reversible gelatin create solid matrices with controlled melt profiles. French industrial bakeries struggle to replicate gelatin's operational simplicity with pectin systems requiring precise calcium concentration control.
- Stabilizing:Prevents phase separation in emulsions and suspensions over shelf life.
- Emulsifying:Reduces interfacial tension between immiscible phases in processed foods.
- Foaming:Protein and surfactant systems entrap air for aerated confectionery and desserts.
- Binding:Protein and starch adhesion holds moisture and particulates in restructured meat and bakery matrices.
Gelling commands the highest technical margins; thickening is expanding most quickly as beverage developers reformulate for clean-label suspension stability.
Source Material:
Carbon footprint verification requirements under EU Green Deal mechanisms are restructuring procurement toward traceable, low-emission supply chains.
- Plant-based:Pectin from citrus peel, locust bean gum from Mediterranean carob, and guar from Indian subcontinent cultivation dominate clean-label portfolios. Benelux and Nordic retailers now require scope-three emissions documentation for tropical gum sourcing.
- Microbial:Precision fermentation of xanthan gum and bacterial cellulose in controlled bioreactor environments eliminates agricultural land use and harvest volatility. Danish and Dutch biotech specialists are scaling production to bypass Philippines and Indonesia seaweed supply concentration risks.
- Animal-derived:Porcine and bovine gelatin retain cost advantages in confectionery gelling.
- Algal:Carrageenan and agar extraction from red seaweed faces climate-driven harvest instability.
- Synthetic:Chemically modified cellulose derivatives serve cost-sensitive private-label segments.
Plant-based sources retain volume leadership; microbial platforms are gaining share fastest as fermentation infrastructure achieves commercial scale.
End Use Customer:
Customer technical capabilities determine service intensity, with mid-sized manufacturers demanding bundled formulation support that commodity suppliers cannot deliver.
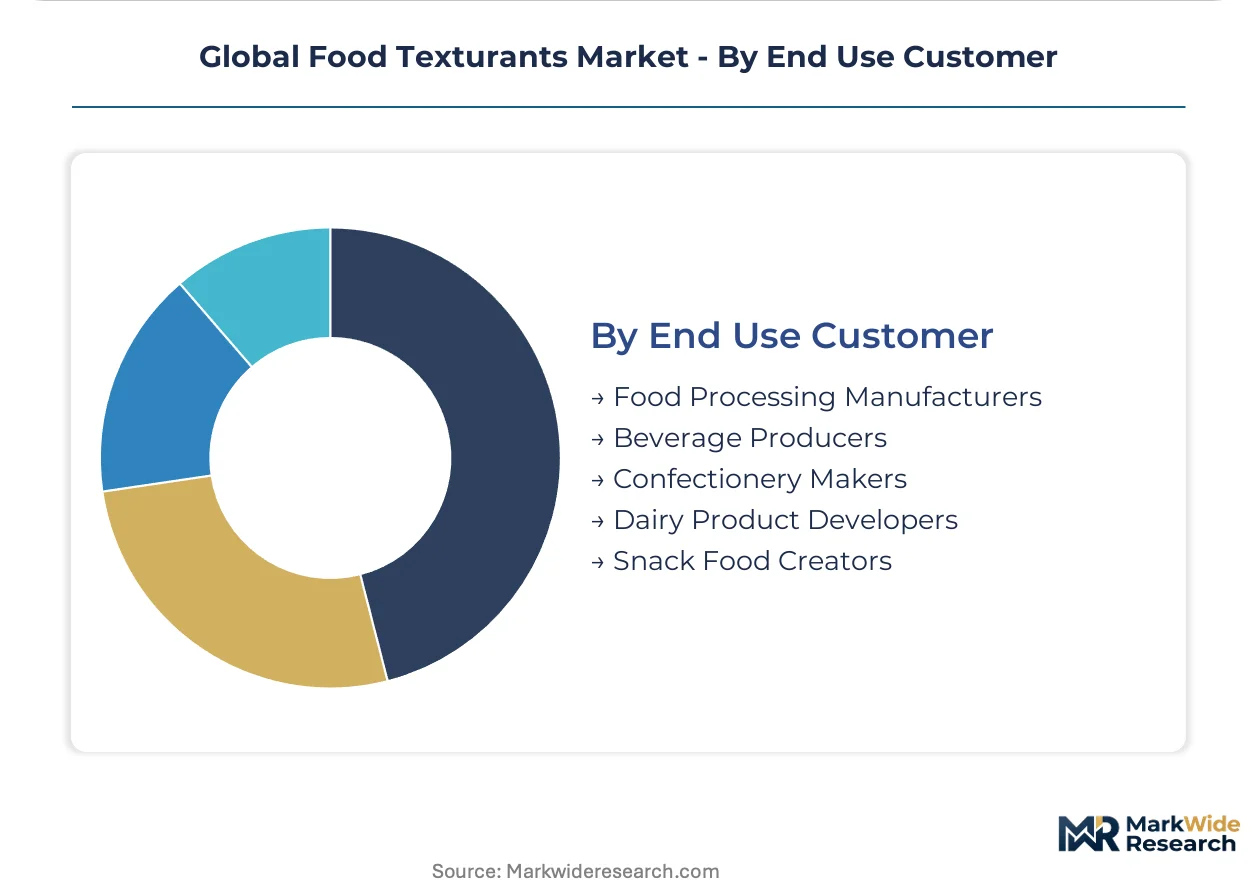
- Food Processing Manufacturers:Meat, bakery, and prepared meal developers require multi-hydrocolloid synergy modeling for moisture control and freeze-thaw stability. United Kingdom and Netherlands-based mid-tier processors now prioritize full-service texture solution providers over commodity merchants.
- Beverage Producers:Suspension stability and mouthfeel modulation in functional drinks and plant-based milks drives hydrocolloid specification. German dairy conglomerates qualify European-sourced pectin to preempt EU Green Deal compliance exposure on imported tropical gums.
- Confectionery Makers:Gelling and crystallization control in gummies and jellies.
- Dairy Product Developers:Yogurt texture, creaminess, and stability in fermented systems.
- Snack Food Creators:Expansion control and oil retention in extruded and fried products.
Food processing manufacturers represent the largest customer base; beverage producers are climbing the fastest as plant-based milk and functional drink development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade imbalances in hydrocolloid raw materials shape regional competitiveness, with Asia-Pacific supplying seaweed-derived inputs while European processors dominate value-added formulation. Import dependency for carrageenan and agar concentrates supply risk in Western markets.
Germany
Bakery and dairy reformulation drives pectin qualification at scale. EFSA clean-label deadlines under EU Regulation 1333/2008 compress carrageenan demand in Bavarian yogurt processing. Hamburg harbors specialized hydrocolloid blending operations serving Nordic export markets.
United States
Plant-based meat developers source enzymatically extracted pea proteins for texture replication. FDA GRAS self-affirmation and FSMA preventive controls structure import requirements for tropical gum suppliers. Chicago-area food technologists concentrate on multi-hydrocolloid synergy modeling for meat analog applications.
China
Domestic starch processing capacity expands for waxy maize derivatives targeting clean-label export markets. SAMR food additive standards and GB quality specifications govern hydrocolloid purity for domestic consumption. Yangtze River Delta clusters concentrate modified starch production for Japanese and South Korean confectionery buyers.
Brazil
Citrus peel pectin extraction scales to capture European clean-label procurement shifts. ANVISA food additive regulations align with Mercosur technical standards for regional trade integration. São Paulo state processors develop tropical gum alternatives to reduce import dependency from Asian suppliers.
Netherlands
Precision fermentation infrastructure for microbial hydrocolloids attracts biotech investment. EU Green Deal carbon border adjustments incentivize local sourcing verification for Benelux retailers. Rotterdam logistics hubs coordinate carbon-labeled texturant distribution across Northern European markets.
Global Food Texturants Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and R&D scale. The market structures around three tiers: multinational ingredient houses with integrated extraction infrastructure, regional specialists with fermentation or enzymatic capabilities, and commodity traders with limited technical service. Dominant competitive moves include backward integration into agricultural raw material sourcing and strategic partnerships with plant-based meat developers requiring bundled formulation support.
Within the multinational tier, Cargill, Ingredion, and Kerry Group exemplify divergent strategic positioning. Cargill leverages its plant-protein extraction infrastructure across European supply chains. Ingredion concentrates R&D intensity in waxy maize and tapioca starch systems. Kerry Group anchors microbial fermentation capabilities for EFSA-compliant hydrocolloid production. These three occupy positions representing extraction-based, starch-specialist, and fermentation-driven archetypes respectively.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Ingredion |
| Tate & Lyle |
| DuPont |
| Kerry Group |
| International Flavors & Fragrances |
| CP Kelco |
| DSM |
| Others |
Supply & Pricing Matrix
Capacity utilization at enzymatic processing facilities in the Netherlands and Denmark sets price floors for plant-derived hydrocolloids, compressing margins for smaller extractors while concentrating procurement leverage among Cargill, Ingredion, and Kerry Group. Scale economies in microbial fermentation infrastructure simultaneously reduce unit costs for xanthan gum variants and elevate technical service bundling as the primary price discriminator.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with three-tier pricing stratification across premium fermentation-derived, standard plant-extracted, and economy modified-starch tiers. Price differentiation rests on EFSA compliance certification and carbon footprint verification grade, with Nordic retailers paying premiums for scope-three documented supply. Cost compression in the economy tier is intensifying because Brazilian citrus peel pectin extraction scales to capture European clean-label procurement shifts. Private-label bakery segments exhibit highest price sensitivity; pharmaceutical-grade microbial hydrocolloid buyers show least.
Supply Chain Analysis
Inventory buffers for tropical seaweed-derived inputs stretch to six-month coverage as Philippine and Indonesian harvest volatility escalates. Raw material sourcing draws from Indian subcontinent guar cultivation, Mediterranean carob orchards for locust bean gum, and Yangtze River Delta waxy maize processing. Single-source vulnerability concentrates in red seaweed supply for carrageenan and agar extraction. Distribution runs through Rotterdam logistics hubs coordinating carbon-labeled texturant allocation to Benelux and Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Food Texturants Market sits in cyclical recovery as EFSA reformulation deadlines force portfolio replacement waves across European dairy and bakery processing. Substitution cycles for carrageenan-to-pectin systems create recurring demand spikes every regulatory re-evaluation period.
For Market Incumbents: Compound technical service capabilities into captive formulation partnerships with mid-sized United Kingdom and Netherlands food processors facing reformulation expertise scarcity. Deepen backward integration into enzymatic pea protein extraction capacity to defend against fermentation-derived hydrocolloid substitution. Prioritize EFSA Novel Food approval pipelines for microbial cellulose variants to preempt regulatory displacement of seaweed-derived portfolios. For New Entrants and Emerging Players: Differentiate on precision fermentation platforms producing EFSA-compliant label claims without agricultural land use exposure. White-space targets include Japanese FOSHU-functional texture-modified products for elderly swallowing difficulties and direct-to-manufacturer digital marketplaces compressing distribution layers for European confectionery specialists. The most penetrable segment sits in carbon-verified hydrocolloid supply for Nordic retailer procurement mandates; pursue go-to-market through sustainability certification partnerships with scope-three accounting platforms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation infrastructure specialists over extraction-dependent legacy operators. Long-term viability over the next decade hinges on regulatory compliance adaptability and carbon accounting integration. Target acquisition archetypes include Dutch and Danish microbial hydrocolloid biotechs with commercial-scale bioreactor operations. The signal to watch is EFSA re-evaluation timing for carrageenan safety classifications, which would accelerate substitution capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Danish biotech specialists bypass Philippine seaweed supply concentration through controlled bioreactor production. |
| EFSA Novel Food Approval Pipeline | Regulatory clearance for microbial cellulose variants secures label-compliant positioning against carrageenan displacement. |
| Backward Integration into Pea Protein | Cargill's enzymatic extraction infrastructure captures plant-based meat texturant demand across European supply chains. |
| Carbon Footprint Verification Program | ISO standards compliance unlocks procurement preferences from Nordic retailers targeting scope-three emissions reductions. |
| Direct-to-Manufacturer Platform Launch | Digital marketplaces compress distribution layers between hydrocolloid producers and mid-sized Netherlands confectionery specialists. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA additive re-evaluation databases, EU Green Deal implementation tracking, and trade flow documentation from customs authorities. Input gathered from food technologists at German dairy conglomerates, procurement leads at United Kingdom bakery manufacturers, regulatory affairs directors at ingredient houses, and sustainability officers at Nordic retail chains. Validation combined bottom-up capacity assessments at fermentation facilities with top-down market sizing from hydrocolloid trade volumes.
Segmentation dimensions modeled span product type, functional application, source material provenance, and end-use customer technical capability across the projection horizon. CAGRs derived from elasticity analysis linking reformulation deadline schedules to substitution rate assumptions, with specific incorporation of enzymatic processing yield improvements and carbon border adjustment mechanism implementation timelines.
The analysis sits within stated boundaries; outcomes outside EFSA regulatory timeline adherence or sustained EU Green Deal enforcement would require recalibration. Forecasts reflect documented assumptions on clean-label mandate penetration and fermentation technology cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Wine Fining Agent Market
Food Additives and Ingredients
Titanium-Free Food Color Alternatives Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market
Food Additives and Ingredients
Europe Food Enzymes Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
South America Brewing Enzymes Market