
 China Food Additives Market | 2026-2036
China Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
China Food Additives Market Outlook
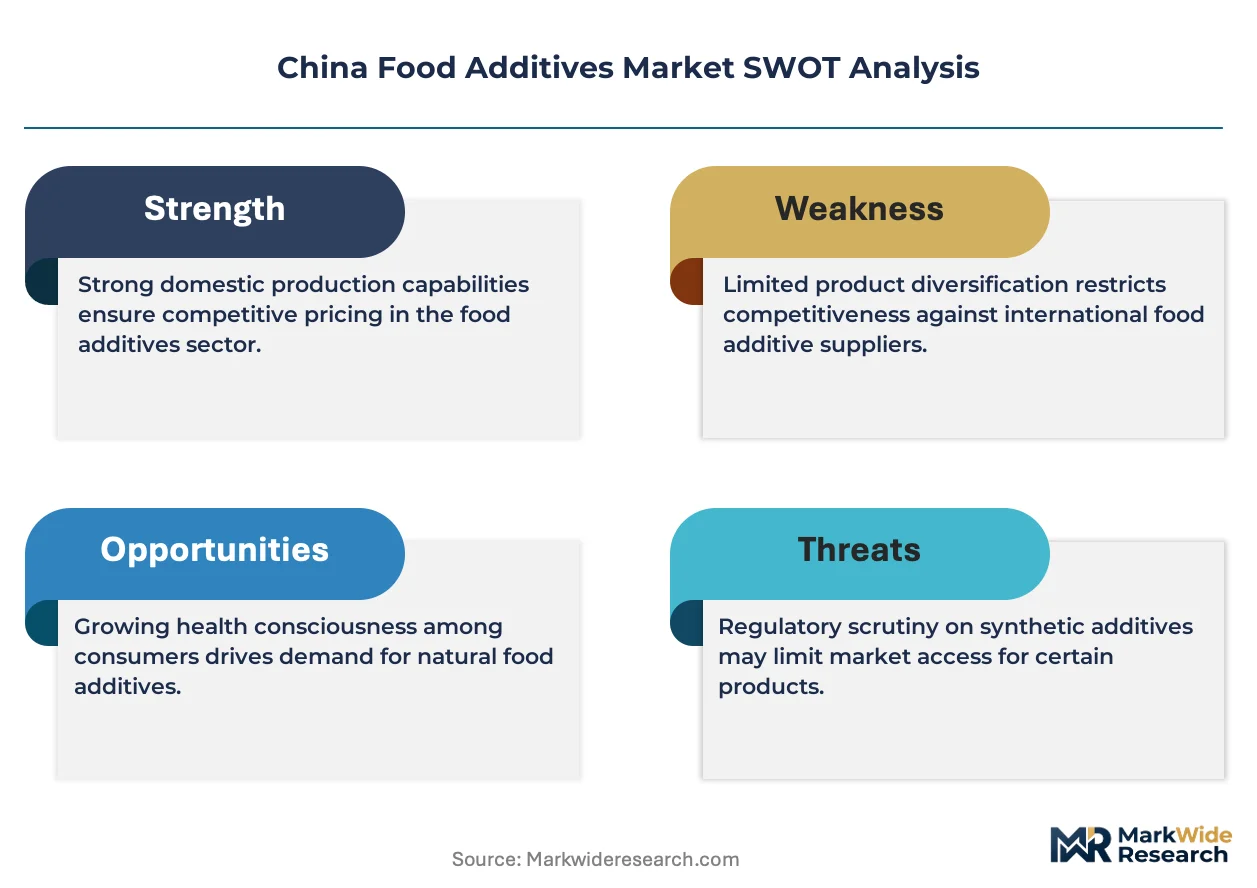
The gap between premium natural extracts and commodity synthetic additives is realigning procurement patterns across China's food sector. DSM-Firmenich AG leverages its integrated biotechnology platforms to dominate high-value flavoring agents for dairy applications. Angel Yeast Co., Ltd. anchors the domestic market through captive fermentation capacity and specialized yeast extract production. Zhejiang NHU Co., Ltd. differentiates via backward integration into vitamin and carotenoid precursors, controlling cost structures that commodity players cannot match.
Food additives encompass substances added to food products to enhance flavor, preserve freshness, improve texture, or modify color, typically used at concentrations below one percent by weight and governed by maximum permitted levels under national food safety standards. Their primary commercial purpose centers on extending shelf stability, standardizing sensory profiles, and enabling industrial-scale production consistency across dispersed manufacturing networks. Preservatives and sweeteners command the deepest margin pools as bakery and beverage applications scale, while natural colorants draw fastest growth from clean-label reformulations. Powder and liquid forms split along processing equipment compatibility, with granular formats gaining share in automated snack seasoning lines.
SAMR enforces GB standards compliance through batch testing protocols that determine market access for both domestic producers and imported additive portfolios. NMPA alignment with evolving food-drug interface definitions shapes how functional additives position between conventional ingredients and health claims. MEE discharge regulations raise wastewater treatment costs for chemical synthesis routes, advantaging biotech-based producers. Stakeholders must monitor GB standard revision cycles and dual carbon enforcement intensity to calibrate capital allocation between synthetic and fermentation-derived capacity expansions.
Market Dynamics
GB standards revision cycles and dual carbon enforcement are compressing synthetic additive margins while biotech fermentation capacity captures preferential licensing in coastal manufacturing clusters.
Growth Catalysts
- Clean-label reformulation mandates:Dairy and beverage manufacturers in Shanghai and Guangdong are accelerating natural extract procurement to meet retailer specification sheets.
- MEE wastewater discharge rules:Stricter chemical synthesis effluent standards are advantaging fermentation-based producers with lower environmental compliance burdens.
- Processed food export certification:SAMR batch testing alignment with destination market standards is unlocking cross-border revenue streams for compliant additive suppliers.
Market Restraints
- Feedstock cost volatility:Corn and molasses price swings directly squeeze yeast extract and fermentation-derived vitamin margins.
- Coastal manufacturing concentration:Over 70% of high-purity additive capacity sits within 200 kilometers of Shanghai, creating single-point vulnerability to port logistics disruptions.
- Synthetic-to-natural substitution ceiling:Bakery applications face technical barriers replacing sorbates with clean-label alternatives at equivalent shelf-life performance.
Strategic Opportunities
- Inland province penetration:Sichuan and Henan processed food clusters remain underserved by premium natural additive distribution networks.
- Precision fermentation scale-up:Integration of CRISPR strain optimization with continuous bioprocessing is collapsing unit economics for rare natural colorants.
- Carbon credit monetization:Dual carbon policy implementation allows biotech producers to trade emission reduction certificates alongside additive sales.
Industry Challenges
- Fermentation specialist talent scarcity:Industrial microbiology and downstream processing expertise commands premium compensation in the Yangtze River Delta.
- GB standards compliance timeline compression:SAMR batch testing protocols require 90-day certification windows that mismatch with just-in-time procurement cycles.
- Legacy synthetic asset stranded risk:Chemical synthesis facilities face accelerated depreciation as MEE enforcement intensifies in the Pearl River Delta.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Food Additives Market |
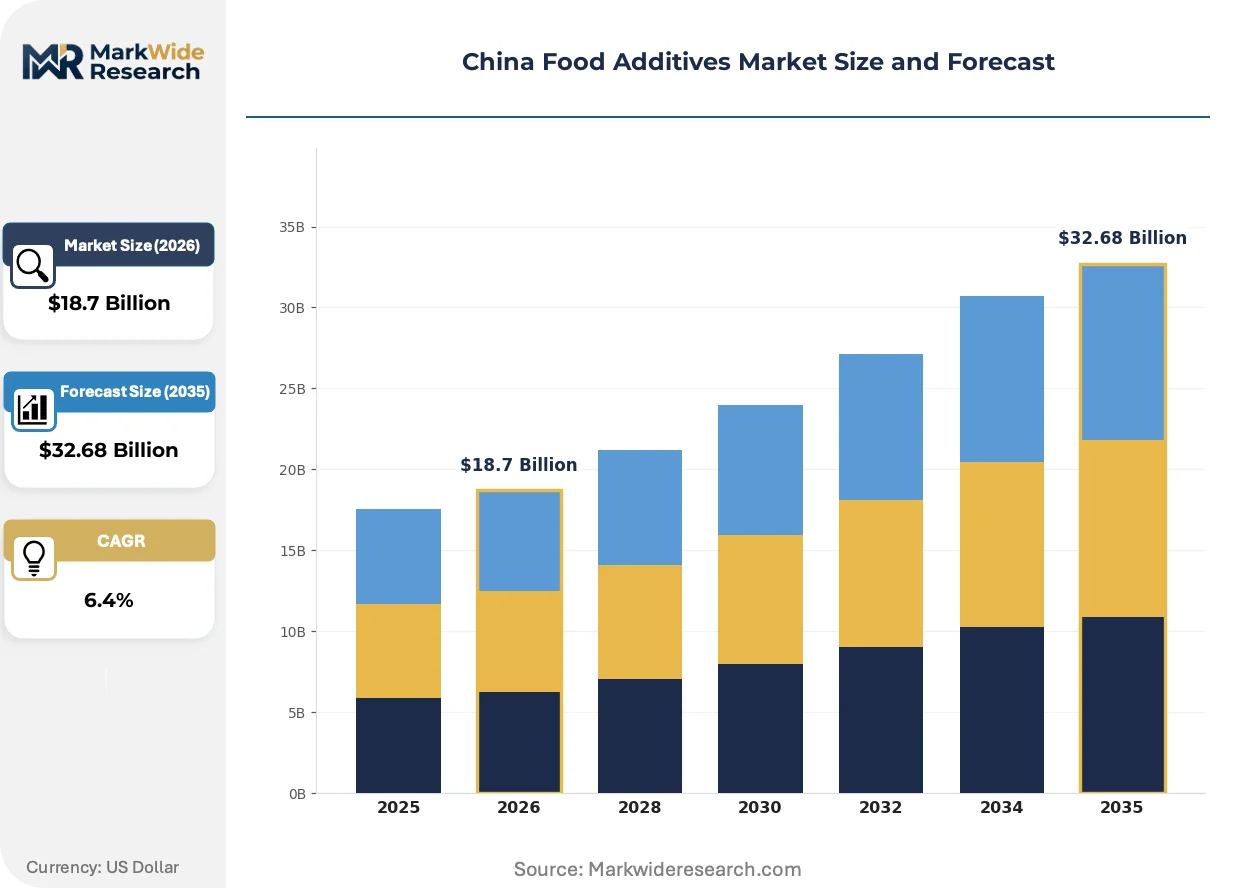
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavoring Agents, Preservatives, Sweeteners, Colorants Application: Dairy Products, Bakery, Beverages, Snacks Form: Liquid, Powder, Granular, Paste End User: Food Manufacturers, Restaurants, Retail Chains, Catering Services |
| Companies Covered | DSM-Firmenich AG, Angel Yeast Co., Ltd., Cargill, Incorporated, Ajinomoto Co., Inc., Zhejiang NHU Co., Ltd., Archer Daniels Midland Company, Kerry Group plc, International Flavors & Fragrances Inc., BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Food Additives Market Strategic Shifts
Biotechnology platforms are displacing petrochemical routes across high-value additive categories while regulatory pressure and procurement rationalization reshape competitive positioning.
Precision fermentation for natural colorants is expanding into carotenoid and anthocyanin production at industrial scale. Beverage manufacturers in Guangdong are adopting these extracts for clean-label reformulations ahead of retailer deadline pressures. The technology is expanding into cost structures that commodity synthetic producers cannot match, compressing mid-tier supplier margins.
SAMR's tightened GB standards for heavy metal residues and purity thresholds are forcing additive suppliers to upgrade analytical testing infrastructure. Domestic producers must demonstrate batch-level compliance through third-party laboratory certification before market release. Dairy applications face the steepest testing burden as infant formula adjacency triggers NMPA-aligned scrutiny.
Direct procurement contracts between additive manufacturers and processed food brands are displacing traditional distributor intermediaries in coastal clusters. Large dairy and beverage processors in Shanghai are negotiating multi-year supply agreements with fermentation specialists to lock in volume and specification stability. This concentration is most visible in yeast extract and natural flavoring categories where supply security dominates price sensitivity.
China Food Additives Market Segmentation
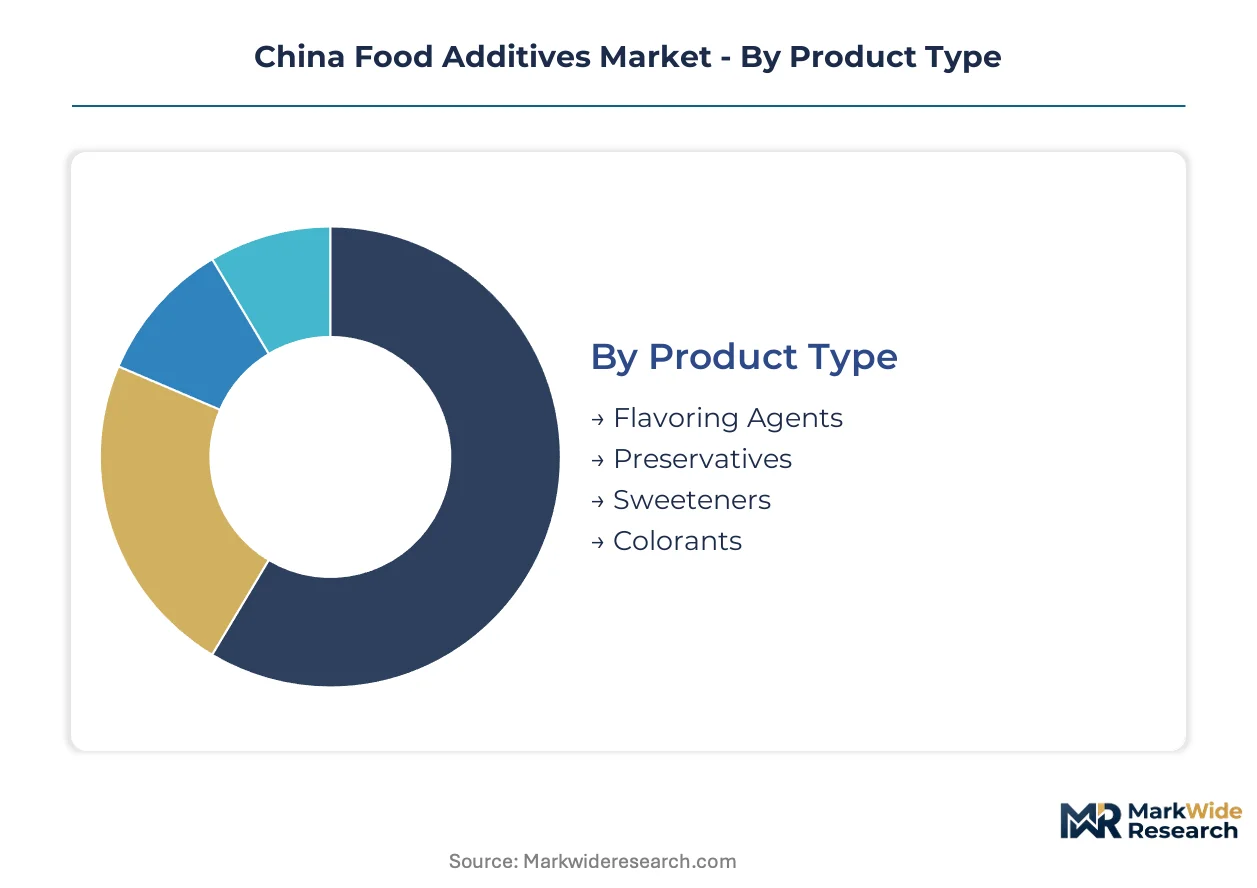
Segmentation in China's food additives market reveals how procurement patterns diverge between coastal manufacturing clusters and inland processing hubs. Each dimension—product chemistry, application requirements, physical form, and buyer type—carries distinct margin profiles and regulatory compliance burdens that reshape supplier strategies.
Product Type:
Supply concentration in fermentation-derived categories is compressing margins for petrochemical-based alternatives as MEE discharge rules tighten around Shanghai and Guangdong facilities.
- Flavoring Agents:These encompass natural extracts, reaction flavors, and compounded seasonings that standardize sensory profiles across dispersed production networks. Dairy processors in Guangdong are locking in multi-year contracts with yeast extract specialists to secure volume stability ahead of clean-label reformulation deadlines.
- Preservatives:Sorbates, benzoates, and natural antimicrobial systems extend shelf stability in ambient-distribution supply chains. Bakery applications face technical barriers substituting synthetic sorbates with clean-label alternatives at equivalent shelf-life performance, preserving demand concentration in coastal chemical synthesis clusters.
- Sweeteners:High-intensity and bulk sweetening systems enable sugar reduction in beverage formulations.
- Colorants:Synthetic dyes and natural extracts from carotenoid and anthocyanin fermentation modify visual appeal.
Flavoring agents absorb the bulk of installed capacity; colorants are expanding most quickly as precision fermentation collapses unit economics for rare natural pigments.
Application:
Cost tier stratification separates premium natural-additive formulations from commodity synthetic applications based on end-use price sensitivity and certification requirements.
- Dairy Products:Infant formula adjacency triggers the steepest SAMR batch testing burden under NMPA-aligned scrutiny, forcing additive suppliers to upgrade analytical infrastructure. Processed dairy manufacturers in Shanghai are accelerating natural extract procurement to meet retailer specification sheets.
- Bakery:Emulsifiers, preservatives, and enzyme systems standardize texture and extend distribution reach in ambient channels. Technical barriers to synthetic-to-natural substitution preserve sorbate demand despite clean-label pressures.
- Beverages:Acidulants, sweeteners, and colorants enable flavor consistency at industrial scale.
- Snacks:Seasoning blends and texture modifiers support automated production lines.
Dairy absorbs the bulk of testing infrastructure investment; beverages are climbing the fastest as Guangdong processors adopt fermentation-derived colorants ahead of retailer deadlines.
Form:
Volume concentration in powder formats reflects compatibility with legacy blending equipment across inland processing clusters.
- Liquid:Pumpable concentrates integrate with continuous beverage processing lines and automated dosing systems. Guangdong beverage manufacturers favor liquid colorants and flavor systems for clean-label reformulations requiring precise dispersion control.
- Powder:Spray-dried and agglomerated formats dominate dry-mix applications in bakery and snack seasoning. Automated snack seasoning lines in Shanghai manufacturing clusters are driving granular format adoption despite powder's legacy installed base.
- Granular:Free-flowing particles reduce dust generation in high-speed packaging operations.
- Paste:High-viscosity concentrates suit artisanal and small-batch production requirements.
Powder commands the bulk of legacy equipment compatibility; granular is gaining share fastest in automated coastal facilities.
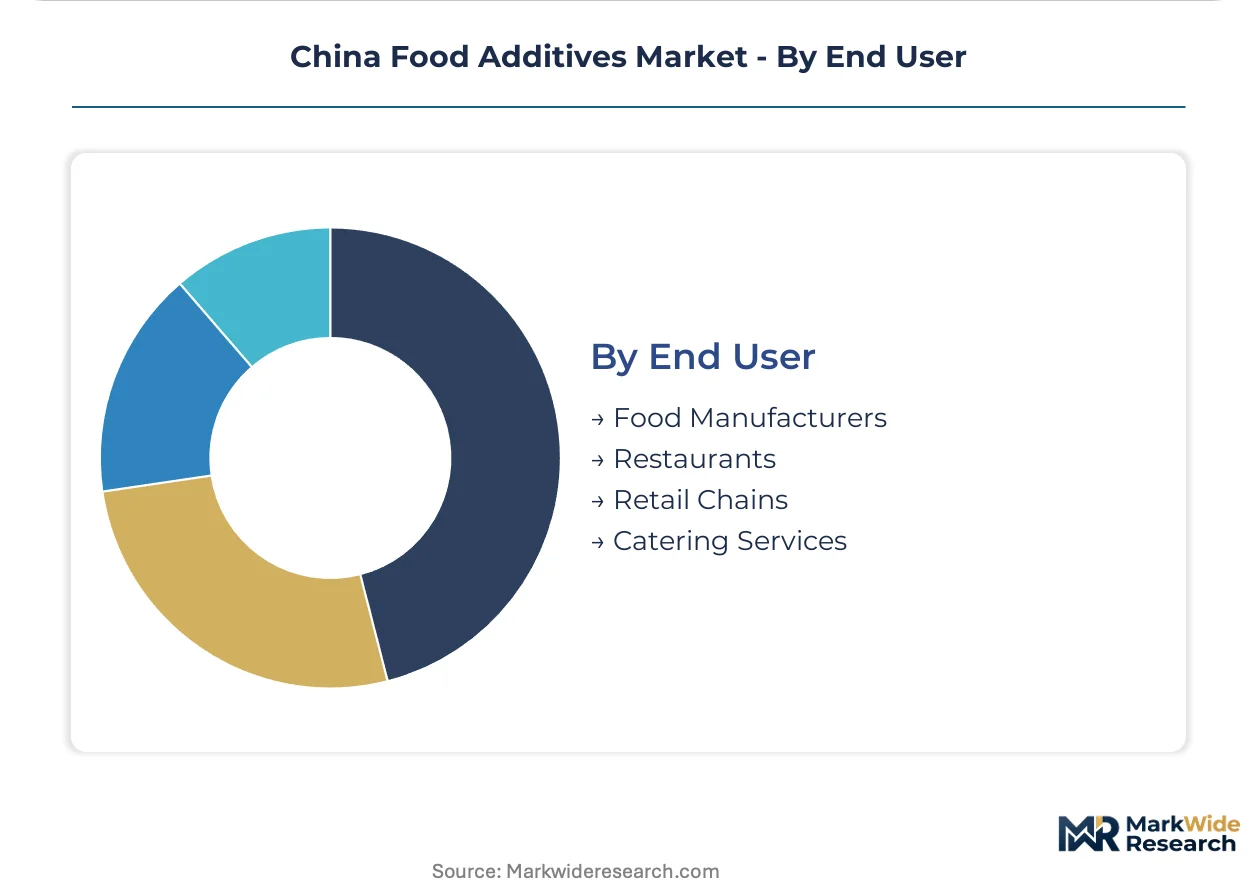
End User:
Customer type determines procurement sophistication, with large food manufacturers bypassing distributor intermediaries for direct fermentation specialist contracts.
- Food Manufacturers:Industrial processors negotiate multi-year supply agreements with additive producers to lock in specification stability and volume security. Direct procurement concentration is most visible in yeast extract and natural flavoring categories where supply security dominates price sensitivity.
- Restaurants:Commercial kitchens source blended seasoning systems through regional distribution networks.
- Retail Chains:Private-label specifications drive clean-label additive demand in coastal markets.
- Catering Services:Centralized production facilities require shelf-stable ingredient systems for mass meal distribution.
Food manufacturers absorb the bulk of direct procurement volume; retail chains are expanding specification requirements fastest as clean-label mandates propagate downstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors China's food additive demand through its dense concentration of dairy and beverage manufacturing campuses. Coastal manufacturing clusters absorb over 70% of high-purity additive capacity within 200 kilometers of this metro. SAMR enforcement intensity tightens fastest in these jurisdictions.
Yangtze River Delta
Processed dairy manufacturers in Shanghai and surrounding Jiangsu province are locking in multi-year natural extract contracts ahead of clean-label reformulation deadlines. SAMR batch testing protocols here impose 90-day certification windows that mismatch with just-in-time procurement cycles. Zhejiang province hosts backward-integrated vitamin producers controlling precursor supply chains.
Pearl River Delta
Guangdong beverage processors are adopting fermentation-derived colorants for clean-label product lines ahead of retailer specification mandates. MEE wastewater discharge rules are compressing synthetic additive margins while biotech fermentation capacity captures preferential licensing. Shenzhen and Guangzhou manufacturing zones concentrate liquid flavor system demand for automated dosing compatibility.
Beijing-Tianjin-Hebei
Infant formula adjacency in this northern corridor triggers the steepest NMPA-aligned scrutiny for additive purity thresholds. SAMR's tightened GB standards for heavy metal residues force suppliers to upgrade analytical testing infrastructure. Tianjin port logistics serve as the primary entry node for imported additive portfolios seeking domestic distribution.
Sichuan-Chongqing
Processed food clusters in this western hub remain underserved by premium natural additive distribution networks relative to coastal saturation. Local manufacturers source commodity preservatives through regional intermediaries rather than direct fermentation specialist contracts. Chongqing's snack seasoning lines are driving granular format adoption despite powder's legacy equipment dominance.
Shandong Peninsula
Bakery applications here face technical barriers substituting synthetic sorbates with clean-label alternatives at equivalent shelf-life performance. Corn and molasses feedstock volatility directly squeezes yeast extract margins for regional fermentation facilities. Qingdao port infrastructure offers alternative import channels reducing single-point vulnerability to Shanghai logistics disruptions.
China Food Additives Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology-platform differentiation in China's food additive sector. DSM-Firmenich AG leverages integrated biotechnology platforms to dominate high-value flavoring agents for dairy applications. Three strategic archetypes define competitive positioning: multinational fermentation specialists with captive strain libraries, domestic backward-integrated vitamin producers, and commodity chemical synthesis operators facing stranded asset risk. Dominant competitive moves include direct procurement contract concentration between additive manufacturers and processed food brands, plus precision fermentation scale-up for rare natural colorants.
Within the fermentation-specialist tier, DSM-Firmenich AG and Angel Yeast Co., Ltd. exemplify divergent geographic anchoring strategies. DSM-Firmenich AG represents multinational platform integration spanning flavor and nutrition applications. Angel Yeast Co., Ltd. occupies a position as the domestic market anchor through specialized yeast extract production. Zhejiang NHU Co., Ltd. sits within the backward-integrated archetype, controlling vitamin and carotenoid precursor supply chains that commodity players cannot replicate. These three companies illustrate how technology-platform depth separates premium-margin positioning from commodity-margin compression.
| Leading Market Players |
|---|
| DSM-Firmenich AG |
| Angel Yeast Co., Ltd. |
| Cargill, Incorporated |
| Ajinomoto Co., Inc. |
| Zhejiang NHU Co., Ltd. |
| Archer Daniels Midland Company |
| Kerry Group plc |
| International Flavors & Fragrances Inc. |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Family-owned fermentation specialists in Zhejiang and Jiangsu provinces anchor supply discipline through multi-generational control of yeast strain libraries and captive precursor production, translating operational continuity into pricing power that resists commodity volatility. Their long capital horizons enable patient capacity expansion that synthetic competitors cannot replicate, tightening spreads between biotech-derived and petrochemical additive tiers as MEE enforcement intensifies.
Pricing Analysis
Yield-anchored pricing dominates fermentation-derived categories, with contracts indexing to downstream shelf-life extension performance rather than input tonnage. Price differentiation rests on GB standard certification tier and backward integration depth into vitamin precursors, separating premium strain-optimized suppliers from commodity chemical operators. Cost compression in synthetic sorbates is intensifying because MEE wastewater rules are raising compliance burdens for Pearl River Delta facilities. Large dairy processors in Shanghai show least price sensitivity, prioritizing specification stability over per-kilogram negotiation.
Supply Chain Analysis
Domestic-content mandates under China's dual carbon policy are reshaping sourcing patterns, advantaging fermentation facilities with verified renewable energy procurement over import-dependent synthetic routes. Supply concentrates in China, with South Korea and Japan contributing specialized enzyme and culture technologies. Corn and molasses feedstock dependencies tether margins to agricultural commodity swings, while port logistics concentration within 200 kilometers of Shanghai creates single-point vulnerability to customs clearance delays. Distribution runs through direct procurement contracts between additive manufacturers and processed food brands, displacing traditional distributor intermediaries in coastal clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAMR's compressed 90-day GB certification windows erect a compliance moat that rewards incumbent investment in analytical infrastructure while straining capital-light entrants. This regulatory barrier-to-entry dynamic concentrates margin capture among players with pre-positioned testing capabilities.
For Market Incumbents: Deepen backward integration into carotenoid and vitamin precursors to defend margin position against precision fermentation scale-ups threatening mid-tier colorant categories. Expand analytical testing capacity ahead of SAMR's next GB standards revision cycle to capture certification bottleneck premiums. Lock multi-year supply agreements with Guangdong beverage processors before clean-label reformulation deadlines consolidate procurement relationships. For New Entrants and Emerging Players: Launch via precision fermentation partnerships targeting underserved Sichuan and Henan processed food clusters where natural additive distribution networks remain thin. Prioritize rare anthocyanin and carotenoid categories where CRISPR strain optimization is collapsing unit economics faster than incumbent capacity can adapt. Position around carbon credit monetization as a differentiated value proposition under dual carbon enforcement. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation-specialist mid-caps in the Yangtze River Delta with stranded synthetic competitors accelerating depreciation in adjacent chemical synthesis facilities. Long-term viability across a decade horizon hinges on biotech platform depth rather than commodity scale. Watch MEE enforcement intensity in the Pearl River Delta as the signal for synthetic asset impairment velocity and biotech licensing preference inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | CRISPR-optimized strains collapse unit economics for rare natural colorants ahead of retailer clean-label deadlines. |
| Backward Integration into Precursors | Zhejiang vitamin producers control cost structures that commodity chemical synthesis operators cannot replicate. |
| Direct Procurement Contract Concentration | Shanghai dairy processors bypass distributors to lock volume security with yeast extract specialists. |
| Analytical Testing Infrastructure Expansion | SAMR batch testing protocols force third-party laboratory certification ahead of market release. |
| Carbon Credit Monetization Program | Dual carbon policy allows biotech producers to trade emission reduction certificates alongside additive sales. |
Study Parameters
Multi-period observation of GB standards revision cycles, MEE enforcement intensity, and dual carbon policy implementation anchored the trend analysis, supplemented by interviews with fermentation plant managers, SAMR regulatory affairs specialists, dairy procurement directors, and yeast extract R&D leads. Secondary validation drew from customs and trade data, SAMR batch testing disclosure records, MEE wastewater discharge filings, and NMPA food-drug interface guidance documents. Bottom-up capacity assessments across coastal manufacturing clusters triangulated against top-down demand projections from processed food production databases.
Input-output matrices mapped additive consumption coefficients to downstream dairy, beverage, bakery, and snack production volumes across the projection horizon. Segmentation dimensions modeled included product chemistry tier, application requirements, physical form compatibility, and end-user procurement sophistication. CAGRs derived from trend extrapolation of clean-label reformulation adoption curves and precision fermentation cost decline trajectories. Industry-specific forecast inputs incorporated corn and molasses price volatility assumptions and SAMR certification timeline compression effects.
The model assumes a particular technology adoption path; alternative pathways for synthetic-to-natural substitution in bakery preservatives would alter the outlook if technical barriers yield to enzymatic or cultured-meat-derived antimicrobial breakthroughs. Forecasts reflect assumptions around MEE enforcement consistency and dual carbon credit market liquidity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
Food Grade Calcium Phosphate Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Food Grade Sodium Hydroxide Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Food Processing Ingredients Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
Japan Anti-Caking Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Canada Food Colorants Market