
 Puffer Machines Market | 2026-2036
Puffer Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Puffer Machines Market Analytics
The EU Green Deal is decoupling legacy detection methods from new procurement cycles across European industrial facilities. Honeywell International Inc leverages its sensing portfolio to anchor positions in automated perimeter monitoring, while ABB competes through integrated control architectures that link puffer arrays to plant-wide safety networks. Pepperl+Fuchs specializes in intrinsically safe designs that sustain demand from hazardous environment operators.
A puffer machine is an aerosol-based trace detection apparatus that releases controlled bursts of inert gas to dislodge particulate residues from surfaces, enabling spectroscopic or ion-mobility analysis of concealed substances at parts-per-billion sensitivity levels. Automated Puffers command the largest installed base due to throughput advantages in high-volume screening environments, while Battery-operated systems represent the fastest-expanding technology segment as remote deployment requirements multiply. The Agriculture vertical retains mature demand patterns, whereas Environmental Agencies concentrate margin pools through specification-intensive tender processes.
EMA emissions guidelines, EU AI Act classification protocols for automated decision systems, and REACH substance restrictions collectively shape product compliance burdens and R&D allocation across manufacturers. FDA clearance pathways govern puffer-based pharmaceutical contamination controls for US-exporting firms, adding a secondary regulatory layer. Stakeholders must weigh standardization investments against the fragmentation risk of divergent national certification timelines.
Market Dynamics
EU Green Deal emissions mandates are decoupling legacy detection methods from new procurement cycles, forcing industrial operators to replace static monitoring with automated puffer arrays that deliver parts-per-billion sensitivity for perimeter security and contamination screening.
Growth Catalysts
- EU AI Act classification protocols:Automated decision systems in puffer arrays gain procurement preference as member states mandate algorithmic transparency for critical infrastructure screening.
- Environmental Agencies:Contamination detection tenders from France, Germany, and the Netherlands concentrate margin pools through specification-intensive processes that favor integrated system suppliers.
- Battery-operated puffer systems:Remote deployment requirements multiply demand for portable trace detection in agricultural perimeter monitoring and mobile security checkpoints.
Market Restraints
- REACH substance restrictions:Compliance burdens limit material choices for ion-mobility spectrometry components, extending R&D timelines for spectroscopic sensor arrays.
- Specialized noble gas supply:Concentration of inert gas purification capacity in select industrial clusters creates input cost volatility for aerosol burst generation systems.
- Ion-mobility resolution limits:Technical constraints in distinguishing complex molecular signatures at high throughput reduce detection confidence in mixed-contaminant environments.
Strategic Opportunities
- EMA emissions guidelines:Pharmaceutical manufacturers face new contamination control mandates that open specification-driven procurement for puffer-based cleanroom monitoring.
- Lidar-puffer sensor fusion:Convergence of optical ranging with aerosol dislodgement enables three-dimensional residue mapping for automated perimeter systems.
- Industrial facility retrofit cycles:Aging security infrastructure across European chemical plants creates replacement demand for networked puffer arrays with plant-wide safety integration.
Industry Challenges
- Ion-mobility spectrometry calibration:Talent scarcity in trace-level sensor tuning extends commissioning timelines and raises service dependency for end-users.
- FDA clearance pathways:Dual certification requirements for US-exporting firms add compliance layers that compress margin structures on pharmaceutical contamination controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Puffer Machines Market |
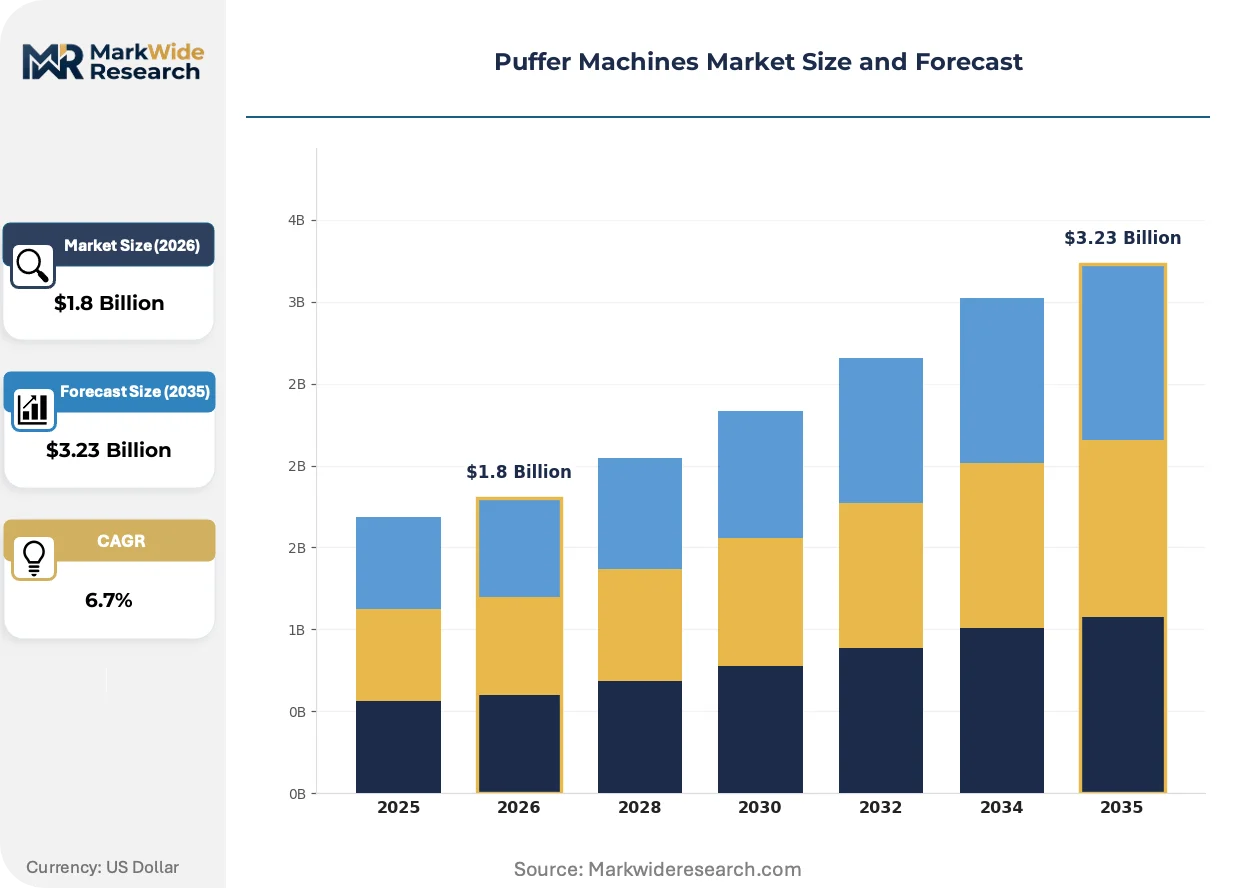
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Puffers, Manual Puffers, Pneumatic Puffers, Automated Puffers Industry Vertical: Agriculture, Construction, Mining, Waste Management End User: Farmers, Contractors, Environmental Agencies, Industrial Operators Technology: Hybrid Technology, Smart Automation, Gas-powered, Battery-operated |
| Companies Covered | Syagen Technology, Sandia National Laboratories, Emerson Electric Co, R. STAHL AG, Extronics, Honeywell International Inc, ABB, BARTEC Top Holding GmbH, Pepperl+Fuchs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Puffer Machines Market Evolving Landscape
Spectroscopic detection architectures are actively displacing legacy ion-mobility systems as the dominant analytical engine, while regulatory frameworks on both sides of the Atlantic harden certification requirements for automated screening equipment.
Multi-sensor fusion architectures are converging with edge computing platforms to enable real-time particulate analysis without centralized laboratory processing. Port operators in Rotterdam and chemical manufacturers along the Rhine corridor are adopting these integrated systems at accelerating pace. The technology is converging with distributed control networks, compressing the traditional separation between detection hardware and plant safety management systems.
REACH substance restrictions and F-Gas Regulation phase-down schedules are forcing reformulation of carrier gases used in aerosol burst generation. Industrial gas suppliers face reformulation investments to maintain supply contracts with puffer system manufacturers. Hazardous environment operators in German chemical clusters are most affected, responding with accelerated qualification programs for alternative inert gas formulations.
Specification-intensive tender processes from environmental regulators are consolidating vendor selection around integrated system suppliers capable of delivering turnkey perimeter security. Traditional component distributors lose position to direct manufacturer relationships in French and Dutch procurement channels. This pattern concentrates most visibly in agricultural screening applications, where national food safety agencies bundle detection equipment with multi-year service obligations.
Puffer Machines Market Segmentation
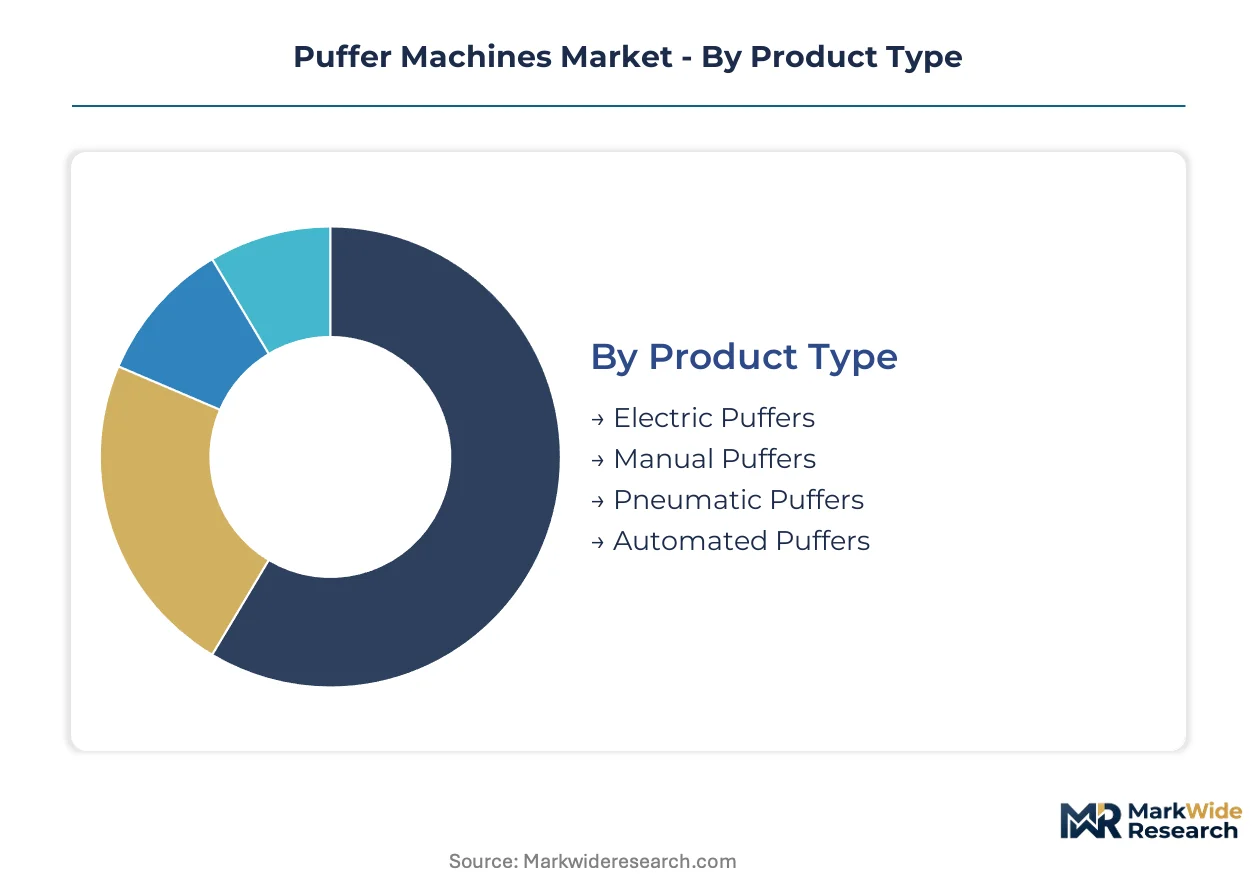
Puffer machine procurement patterns diverge sharply between high-throughput industrial screening environments and mobile field deployments. Understanding these segment boundaries clarifies where specification intensity concentrates margin pools versus where standardization drives cost competition.
Product Type:
Buyers in this category separate between facilities requiring continuous automated throughput and operators needing portable or human-directed deployment flexibility.
- Automated Puffers:These systems integrate aerosol burst generation with spectroscopic or ion-mobility analysis in enclosed architectures designed for unattended operation. Demand concentrates in French and Dutch chemical cluster perimeter security, where EU Green Deal emissions mandates force replacement of static monitoring with parts-per-billion sensitivity arrays.
- Battery-operated Puffers:Portable trace detection units leverage rechargeable power architectures for remote deployment without tethered infrastructure. Agricultural perimeter monitoring across German farming cooperatives and mobile security checkpoints in the Netherlands are expanding procurement fastest as field mobility requirements multiply.
- Electric Puffers:Grid-connected systems deliver consistent burst pressure for fixed-site contamination screening with lower operating cost profiles.
- Manual Puffers:Hand-triggered devices serve calibration, training, and low-volume spot-check applications where capital minimization outweighs throughput needs.
- Pneumatic Puffers:Compressed-air-driven units operate in environments where electrical ignition risks restrict powered alternatives.
Volume sits with Automated Puffers; growth tilts toward Battery-operated systems.
Industry Vertical:
Regulatory enforcement intensity and asset criticality determine specification depth and service contract duration across these demand pools.
- Environmental Agencies:National contamination detection programs in France, Germany, and the Netherlands drive tender processes bundling equipment with multi-year analytical service obligations. REACH substance restrictions and F-Gas Regulation phase-down schedules force continuous recertification of carrier gas formulations, extending vendor relationships.
- Agriculture:Food safety screening retains mature demand patterns with standardized procurement cycles, though national agencies are consolidating vendor selection around integrated system suppliers capable of turnkey perimeter deployment.
- Construction:Dust suppression and residue detection at demolition sites creates intermittent demand for portable puffer verification of hazardous material containment.
- Mining:Explosive residue screening and perimeter monitoring in extractive operations favors intrinsically safe designs for hazardous atmosphere certification.
- Waste Management:Landfill emissions monitoring and leachate contamination detection apply aerosol dislodgement for spectroscopic analysis of volatile compound signatures.
Margin concentrates with Environmental Agencies; standardization pressure weighs heaviest on Agriculture.
End User:
Technical sophistication and in-house calibration capability split this category between self-sufficient operators and service-dependent buyers.
- Industrial Operators:Chemical manufacturers along the Rhine corridor and port facilities in Rotterdam deploy networked puffer arrays with plant-wide safety integration, compressing the traditional separation between detection hardware and distributed control systems.
- Environmental Agencies:National regulators in France and the Netherlands specification-intensive tender processes favor integrated system suppliers over component distributors, consolidating procurement around direct manufacturer relationships.
- Farmers:Agricultural cooperatives in Germany prioritize battery-operated portability for perimeter monitoring with minimal technical staffing requirements.
- Contractors:Construction and demolition firms rent or lease portable units for project-duration compliance verification without capital commitment.
Service dependency runs deepest with Environmental Agencies; capital efficiency drives Contractor procurement patterns.
Technology:
Power architecture and analytical integration depth distinguish competitive positioning in this category.
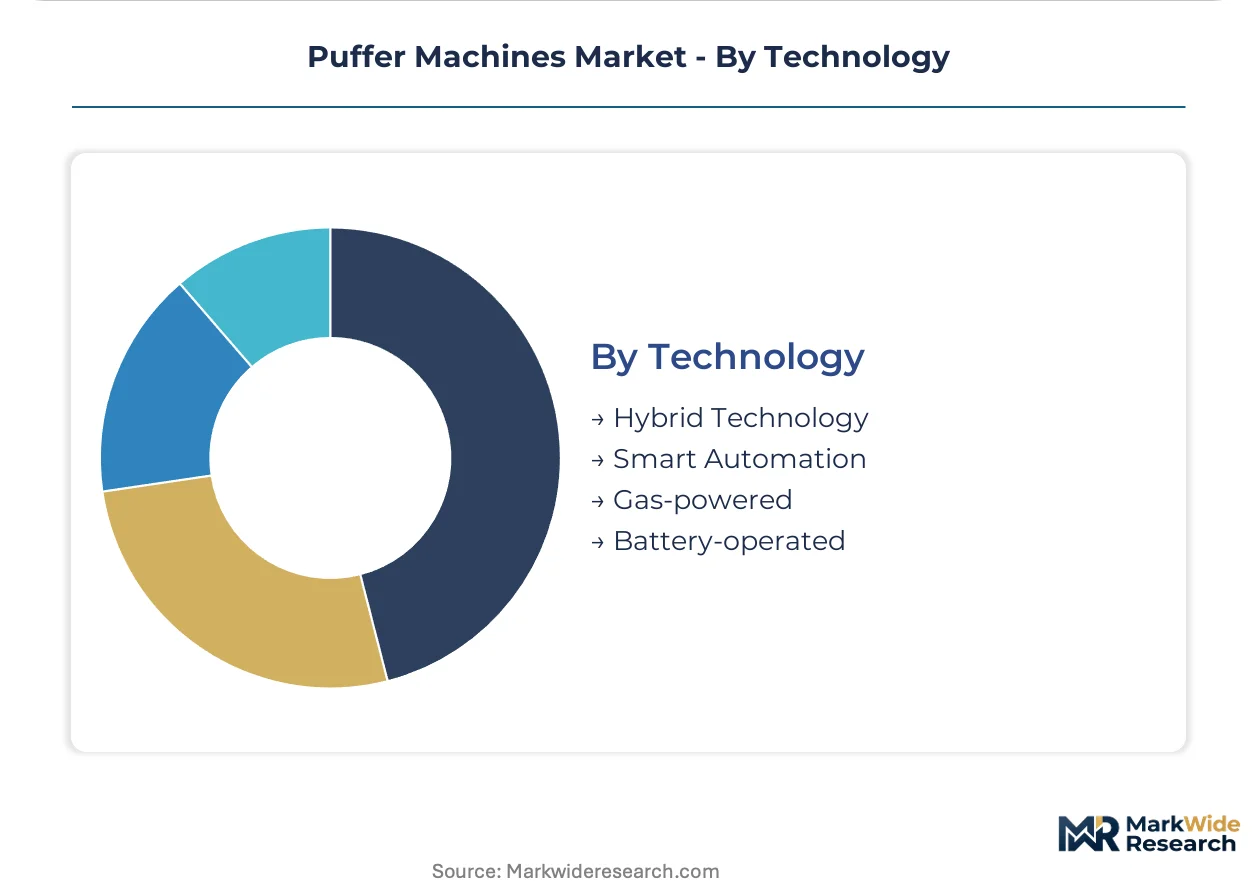
- Smart Automation:Edge computing platforms enable real-time particulate analysis without centralized laboratory processing, converging multi-sensor fusion with distributed control networks. Port operators in Rotterdam and chemical manufacturers in German clusters are adopting these integrated systems at accelerating pace.
- Hybrid Technology:Dual-power architectures combining battery portability with grid-connected operation for extended deployment flexibility serve mixed-use environments.
- Gas-powered:Internal combustion-driven burst generation persists in remote field applications beyond electrical infrastructure reach.
- Battery-operated:Lithium-ion and emerging solid-state power architectures deliver the fastest-expanding technology segment as remote deployment requirements multiply across agricultural and mobile security applications.
Integration depth peaks with Smart Automation; deployment flexibility expands fastest through Battery-operated architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of puffer machines concentrates in German and Swiss industrial clusters, while consumption pulls strongest from French environmental agencies and Dutch port authorities seeking EU Green Deal compliance.
Germany
Rhine corridor chemical manufacturers deploy networked puffer arrays for perimeter emissions monitoring. The EU AI Act classification protocols mandate algorithmic transparency for automated screening systems in critical infrastructure. Baden-Württemberg and North Rhine-Westphalia host the densest concentration of intrinsically safe system fabricators serving hazardous environment operators.
France
ANSM and national food safety agencies drive specification-intensive tender processes for contamination detection equipment. REACH substance restrictions force continuous recertification of carrier gas formulations used in aerosol burst generation. The Île-de-France region anchors procurement for agricultural perimeter security systems bundled with multi-year service obligations.
Netherlands
Port of Rotterdam operators adopt multi-sensor fusion architectures with edge computing for real-time particulate analysis. F-Gas Regulation phase-down schedules accelerate qualification programs for alternative inert gas formulations. Randstad industrial zones concentrate demand for battery-operated portable units in mobile security checkpoints.
United States
FDA clearance pathways govern puffer-based pharmaceutical contamination controls for domestic and export markets. EPA emissions guidelines shape procurement specifications for industrial perimeter monitoring systems. Gulf Coast petrochemical clusters and Pacific Northwest semiconductor fabs represent divergent demand profiles for fixed-site versus cleanroom deployment.
United Kingdom
Health and Safety Executive mandates drive replacement cycles for aging security infrastructure at North Sea chemical terminals. Post-Brexit regulatory divergence from EU REACH creates dual certification burdens for equipment suppliers. The Midlands and Scotland host emerging testbed facilities for lidar-puffer sensor fusion in automated perimeter applications.
Puffer Machines Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with sensing portfolios rather than pure-play specialists. Honeywell and ABB anchor positions through integrated control architectures that compress the separation between detection hardware and plant safety networks. Three archetypes dominate: sensing-integrated conglomerates, hazardous environment specialists with intrinsically safe certifications, and national laboratory technology spinouts. Capacity expansion in noble gas purification and strategic partnerships for edge computing integration represent the dominant competitive moves.
Among Germany-based specialists, R. STAHL AG and BARTEC Top Holding GmbH exemplify the hazardous environment certification archetype, while Pepperl+Fuchs anchors the intrinsically safe design tier. Honeywell International Inc represents the diversified sensing conglomerate model with positions across automated perimeter monitoring. These three occupy positions that reflect divergent bets on regulatory complexity versus standardization pressure across European and North American procurement channels.
| Leading Market Players |
|---|
| Syagen Technology |
| Sandia National Laboratories |
| Emerson Electric Co |
| R. STAHL AG |
| Extronics |
| Honeywell International Inc |
| ABB |
| BARTEC Top Holding GmbH |
| Pepperl+Fuchs |
| Others |
Value Network & Pricing Analysis
Spectroscopic sensor calibration specialists in Baden-Württemberg command wage premiums that compress margin structures at the premium tier while forcing mid-market suppliers toward standardized ion-mobility configurations. Labor-cost differentials between German engineering clusters and Eastern European assembly operations widen pricing spreads across certification-grade tiers.
Pricing Analysis
Price erosion across battery-operated portable units traces to lithium-ion cell commoditization and aggressive Asian component sourcing. Three-tier pricing structure across EMA-compliant pharmaceutical grade, industrial perimeter standard, and agricultural economy levels separates buyers by certification burden and service bundling intensity. REACH substance recertification costs accelerate pricing pressure on inert gas formulations. Environmental agencies exhibit lowest price sensitivity due to multi-year analytical service obligations, while agricultural cooperatives drive hardest bargaining on hardware-only procurement.
Supply Chain Analysis
Dual-sourcing mandates from Dutch port authorities and German chemical operators force qualification of alternative noble gas suppliers beyond traditional Linde-Air Liquide duopoly. Component fabrication concentrates in Germany, Switzerland, and the United States for intrinsically safe enclosures and spectroscopic sensor arrays. Supply chains draw from specialized argon and helium purification facilities, ceramic substrate foundries, and edge computing module suppliers. Single-source vulnerability sits with semiconductor-grade noble gas purification clusters. Distribution runs through direct manufacturer relationships for environmental agency tenders and specialized industrial distributors for agricultural and contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance costs and REACH recertification burdens are forcing sub-scale component distributors toward exit or acquisition, consolidating procurement influence around integrated system suppliers.
For Market Incumbents: Anchor market position through captive production of spectroscopic sensor arrays and backward integration into noble gas formulation qualification. Defend against emerging lidar-puffer fusion specialists by accelerating edge computing platform partnerships. Priority lever: multi-year service contract bundling with environmental agencies to lock out challenger pricing. For New Entrants and Emerging Players: Begin with battery-operated portable units in German agricultural cooperatives where incumbent service infrastructure remains underdeveloped. White-space opportunity exists in cleanroom monitoring for pharmaceutical manufacturers facing EMA emissions guideline compliance deadlines. Go-to-market angle: subscription-based hardware-plus-analytics models that shift capital burden to operating expenditure budgets. For Investors and Strategic Acquirers: The window for entry favors hazardous environment specialists with intrinsically safe certifications and established relationships with German chemical clusters. Long-term viability hinges on regulatory complexity deepening rather than standardization pressure prevailing. Acquisition target archetype: mid-tier spectroscopic sensor technology firms lacking distribution scale. Signal to watch: F-Gas Regulation phase-down acceleration triggering reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Noble Gas Purification | Captive argon supply secures margin against Linde-Air Liquide pricing power in EMA-compliant formulations. |
| Edge Computing Platform Partnership | Real-time particulate analysis without laboratory processing compresses detection latency for Rotterdam port operators. |
| Multi-Year Service Contract Bundling | Analytical service obligations with French environmental agencies lock procurement relationships beyond hardware replacement cycles. |
| Intrinsically Safe Certification Expansion | ATEX/IECEx qualification opens German chemical cluster perimeter security tenders to new supplier qualification. |
| Lidar-Puffer Sensor Fusion Development | Three-dimensional residue mapping capability differentiates automated perimeter systems in Dutch infrastructure screening. |
Research Methodology
Independent corroboration across regulatory filings, customs trade records, and industrial gas supply contracts underwrites the qualitative findings in this study. Primary interviews with plant safety managers at Rhine corridor chemical facilities, procurement leads at Dutch port authorities, spectroscopic sensor R&D directors, and aftermarket service heads at German agricultural cooperatives combined with secondary validation from EMA emissions guideline documentation, EU AI Act classification protocols, REACH substance restriction databases, and F-Gas Regulation implementation schedules. Bottom-up unit economics and top-down industrial expenditure triangulation cross-verify segment sizing.
Rate-of-change decomposition across the projection horizon separates volume growth from price-mix effects and regulatory-driven replacement cycles. Segmentation dimensions modeled include product type automation level, industry vertical regulatory intensity, end-user technical sophistication, and technology integration depth. CAGRs derive from historical procurement pattern analysis and forward-looking tender pipeline assessment. Industry-specific forecast inputs incorporate EU Green Deal implementation timelines and pharmaceutical cleanroom monitoring mandate acceleration.
Underlying measurement precision varies by segment; Environmental Agency tender volumes carry tighter precision than agricultural spot procurement estimates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and noble gas supply continuity. Deviation in F-Gas Regulation phase-down acceleration or REACH substance restriction expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Pet Stretch Blow Molding Machines Market
Packaging Machinery
Emboss Coding Machine Market
Packaging Machinery
Medicine Decoction and Packing Machines Market
Packaging Machinery
Paper Slitting Machine Market
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Tray Packing Machine Market
Packaging Machinery
Injection Blow Molding Machine Market
Packaging Machinery
Pallet Drum Filler Capper Market
Packaging Machinery
Filling Machinery Market
Packaging Machinery
Pallet Stretch Wrapping Machines Market
Packaging Machinery
Cosmetic Filling Machines Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Tablet Packing Machine Market