
 CRO Mass Spectroscopy Services Market | 2026-2036
CRO Mass Spectroscopy Services Market Size, Share, and Industry Trends Forecast 2026-2036
CRO Mass Spectroscopy Services Market Analysis
Buyer concentration in the biopharmaceutical sector is shifting as mid-sized drug developers fragment the sponsor base while top-tier pharmaceutical companies consolidate outsourcing budgets. Thermo Fisher Scientific leverages its integrated instrument-to-service platform to capture recurring method development contracts. Charles River Laboratories anchors North American demand through its captive toxicology and DMPK testing footprint. WuXi AppTec competes on geographic reach, operating multi-site laboratories that reduce sample logistics friction for Asia-based sponsors.
CRO mass spectroscopy services encompass outsourced analytical testing using ionization-based detection systems, typically operating at mass ranges from 50 to 10,000 daltons and resolution thresholds spanning unit-mass to high-resolution exact-mass platforms, to quantify molecular identity and abundance in complex biological matrices. These services primarily support regulatory submission packages for pharmacokinetic characterization, biomarker verification, and impurity profiling across drug development pipelines. Triple quadrupole systems dominate routine bioanalysis for their selectivity-speed balance in regulated GLP environments, while Orbitrap technology leads growth in untargeted metabolomics where exact-mass resolution unlocks novel biomarker discovery. Method development services command premium pricing due to proprietary intellectual property and regulatory defensibility, whereas sample preparation remains a volume-driven, margin-compressed segment.
FDA bioanalytical method validation guidelines and EMA ICH Q14 quality-by-design frameworks shape service scope, forcing CROs to document analytical target profiles and robustness studies prior to regulatory submission. EPA and OECD test guideline compliance extends addressable demand into environmental and agrochemical residue testing. Stakeholders must monitor how FDA's advancing guidance on complex generic peptide bioequivalence reshapes method development priorities and capital allocation across platform technologies.
Market Dynamics
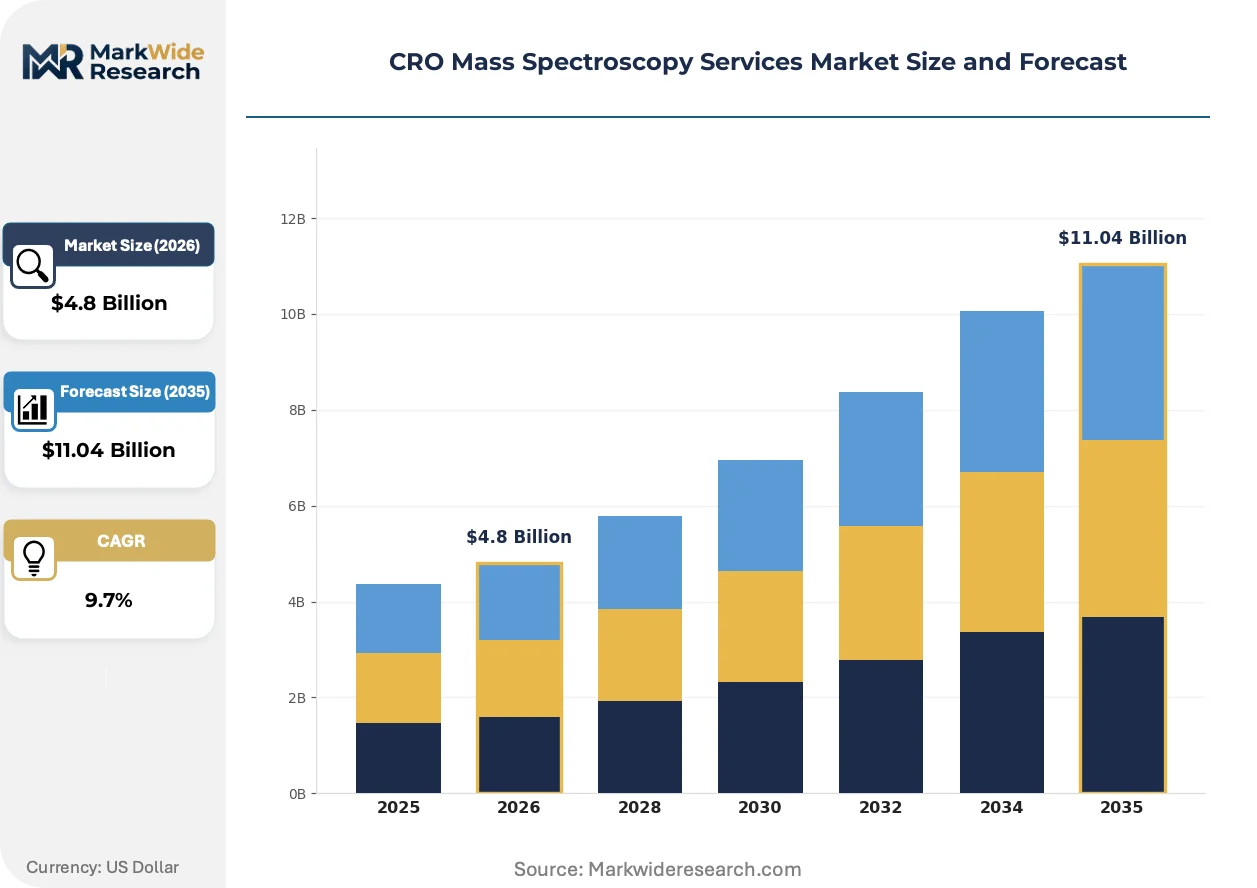
The CRO mass spectroscopy services market is being reshaped by tightening FDA bioequivalence guidelines for complex generics, which force contract laboratories to retool method development capabilities and expand exact-mass platform investments to maintain regulatory defensibility.
Growth Catalysts
- ICH Q14 Methodology Standards:The EMA-adopted quality-by-design framework mandates analytical target profile documentation, creating recurring revenue streams for CROs that build proprietary method libraries.
- Peptide Therapeutics Pipeline:Biopharma sponsors developing GLP-1 analogs and other peptide drugs require specialized bioanalytical assays that triple quadrupole systems cannot validate, pulling demand toward high-resolution platforms.
- United States Sponsor Density:Boston-Cambridge and San Diego biotech clusters concentrate outsourcing budgets, enabling CROs to achieve instrument utilization rates above regional benchmarks.
Market Restraints
- Helium Supply Volatility:Mass spectrometer cryogenic cooling depends on helium extraction concentrated in Qatar and the United States, with price spikes compressing CRO margins on fixed-price contracts.
- Platform Obsolescence Risk:Orbitrap technology cycles compress to 4-5 years, forcing capital redeployment before depreciation schedules complete.
- GLP Certification Barriers:OECD test guideline compliance requires 18-24 month facility qualification timelines that freeze new entrants out of regulated bioanalysis segments.
Strategic Opportunities
- Cell and Gene Therapy Bioanalysis:Viral vector biodistribution studies require novel sample preparation workflows that incumbent CROs have not standardized, creating white space for specialized entrants.
- India CDSCO Alignment:The country's national pharmaceutical regulator is harmonizing bioanalytical guidelines with ICH standards, enabling export-quality CRO capacity to serve Western sponsors at cost-advantaged rates.
- AI-Assisted Peak Integration:Machine learning algorithms trained on historical chromatograms are reducing method development timelines, allowing CROs to compress proposal-to-delivery cycles.
Industry Challenges
- Mass Spectrometrist Talent Scarcity:PhD-level analytical chemists with GLP environment experience command premium compensation, inflating labor costs faster than pricing power allows.
- Cross-Platform Method Transfer:Validated assays frequently fail equivalence testing when transferred between triple quadrupole vendors, triggering sponsor disputes and timeline delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CRO Mass Spectroscopy Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quantitative Analysis, Qualitative Analysis, Method Development, Sample Preparation End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Laboratories Application: Drug Development, Metabolomics, Proteomics, Environmental Testing Technology: Triple Quadrupole, Time of Flight, Ion Trap, Orbitrap |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, SCIEX, Bruker Corporation, Waters Corporation, Charles River Laboratories, Eurofins Scientific, WuXi AppTec, Labcorp Drug Development, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CRO Mass Spectroscopy Services Market Emerging Trajectories
Technological convergence between high-resolution mass spectrometry and automated sample handling is compressing analytical timelines while regulatory pressure on complex generic bioequivalence is forcing capability upgrades across the contract laboratory base.
High-resolution accurate-mass spectrometry is expanding into routine regulated bioanalysis as sponsors demand exact-mass confirmation for peptide and oligonucleotide therapeutics. Mid-sized biopharma developers lacking in-house Orbitrap capacity are outsourcing method development at accelerated rates. This platform shift is expanding into segments previously dominated by triple quadrupole systems, compressing pricing for unit-mass resolution services.
FDA's advancing guidance on complex generic peptide bioequivalence is mandating additional pharmacokinetic endpoints and immunogenicity assessments. The industrial consequence is expanded scope for CRO method development contracts and extended validation protocols. United States-based sponsors are responding by consolidating outsourcing budgets with CROs that maintain captive high-resolution platforms and documented regulatory interaction histories.
Biopharma procurement teams are unbundling method development from sample analysis, awarding intellectual property ownership to sponsors while CROs retain only execution rights. This pattern disrupts traditional full-service contracts and compresses recurring revenue visibility. The shift is most visible among venture-backed biotech sponsors in Massachusetts and California, where cash conservation priorities override historical vendor loyalty.
CRO Mass Spectroscopy Services Market Segmentation
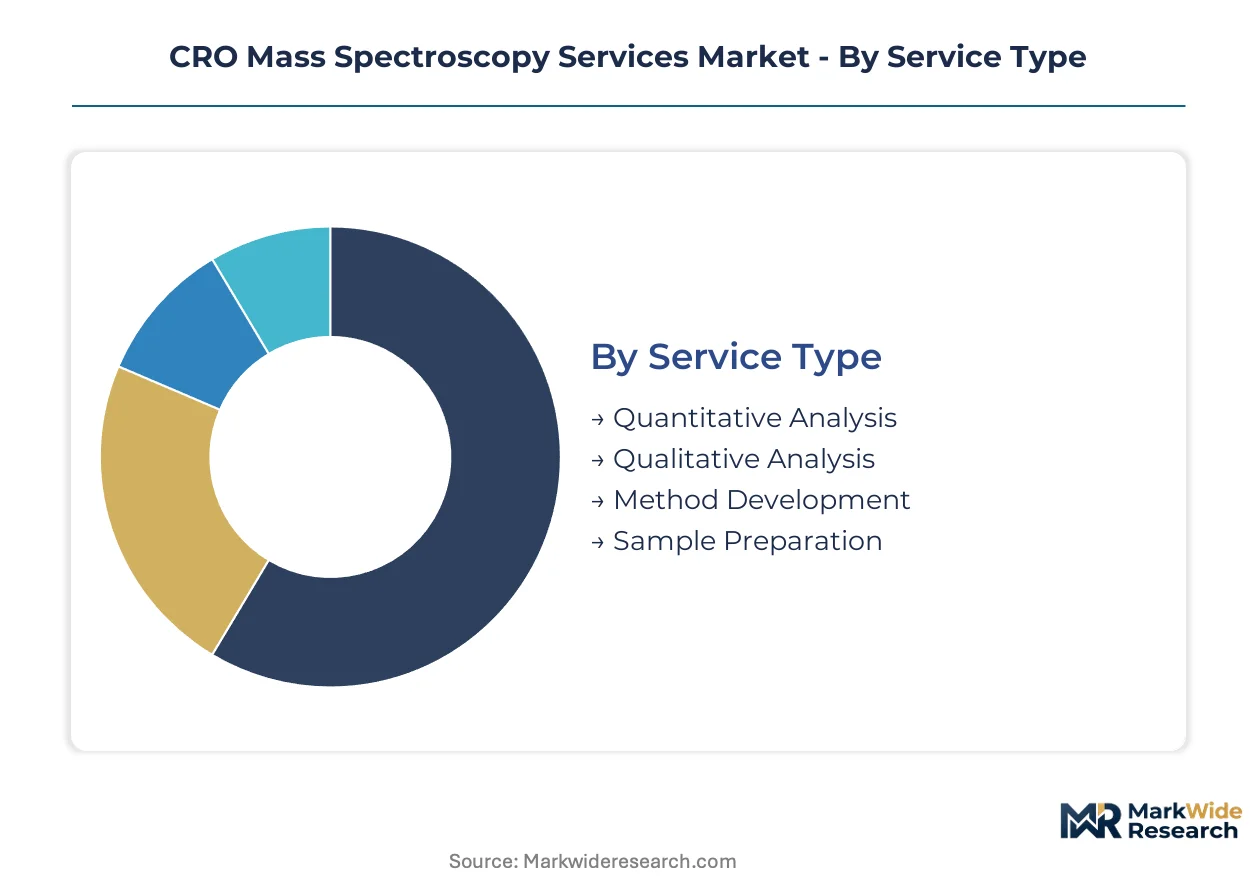
Segmentation in CRO mass spectroscopy services reveals how regulatory burden, technical complexity, and sponsor procurement patterns concentrate value across distinct service tiers. Understanding these divisions exposes where capital deployment and certification investments yield defensible margins.
Service Type:
GLP certification requirements vary sharply across service types, with regulated bioanalysis demanding OECD-compliant quality systems while exploratory work operates under less stringent research-use frameworks.
- Method Development:Proprietary assay design and validation protocols create intellectual property assets that sponsors increasingly demand to own outright. United States-based biopharma sponsors in Boston-Cambridge and San Diego clusters drive premium pricing for regulatory-defensible documentation packages.
- Quantitative Analysis:Routine bioanalytical testing for pharmacokinetic studies operates under fixed-price contracts with thin margins. FDA bioequivalence guideline tightening for complex generics is forcing CROs to upgrade exact-mass platform capabilities to maintain contract eligibility.
- Qualitative Analysis:Structural elucidation and impurity identification services support regulatory submission packages with lower volume but higher per-sample economics.
- Sample Preparation:Automated extraction and matrix cleanup workflows represent a volume-driven segment where robotics investments compress labor costs but limit differentiation.
Quantitative analysis sits at the top of the volume ranking, with method development climbing the fastest.
End User:
Procurement sophistication and contract scale diverge dramatically across sponsor categories, dictating pricing architecture and relationship economics.
- Pharmaceutical Companies:Top-tier sponsors consolidate outsourcing budgets with CROs maintaining captive high-resolution platforms and documented FDA interaction histories. These relationships span multi-year master service agreements with volume commitments.
- Biotechnology Firms:Venture-backed developers in Massachusetts and California unbundle method development from sample analysis to conserve cash, disrupting traditional full-service contracts and compressing recurring revenue visibility for CROs.
- Academic Institutions:Grant-funded research operates outside GLP requirements, enabling price-sensitive purchasing of exploratory mass spectrometry services.
- Research Laboratories:Government and nonprofit facilities contribute steady but lower-margin demand for untargeted metabolomics and proteomics workflows.
Pharmaceutical companies command the largest contract values, though biotechnology firms are expanding their share of method development spend most rapidly.
Application:
Regulatory pathway complexity and clinical trial phase requirements segment the addressable market by analytical rigor and documentation burden.
- Drug Development:Pharmacokinetic characterization and toxicokinetic studies for IND and NDA submissions require validated assays under FDA bioanalytical method validation guidelines. This application concentrates revenue in United States-based CROs with established regulatory inspection records.
- Proteomics:Biomarker discovery and protein quantification workflows increasingly demand Orbitrap exact-mass resolution for post-translational modification analysis.
- Metabolomics:Untargeted metabolic profiling for patient stratification and mechanism-of-action studies pulls demand toward high-resolution platforms as sponsors seek novel biomarker intellectual property.
- Environmental Testing:EPA and OECD test guideline compliance extends addressable demand into agrochemical residue and contaminant screening with distinct certification requirements from pharmaceutical GLP environments.
Drug development dominates current revenue, while metabolomics applications are gaining share fastest among emerging therapeutic platforms.
Technology:
Capital intensity and depreciation schedules segment the installed base, with platform selection determining which CROs can bid on regulated versus exploratory workstreams.
- Orbitrap:High-resolution exact-mass systems command premium pricing for peptide and oligonucleotide bioanalysis where triple quadrupole selectivity proves insufficient. Platform obsolescence cycles compress to 4-5 years, forcing capital redeployment before depreciation schedules complete.
- Triple Quadrupole:Unit-mass resolution systems dominate routine bioanalysis for their selectivity-speed balance in regulated GLP environments, though pricing pressure mounts as high-resolution platforms encroach.
- Time of Flight:TOF systems serve mid-resolution applications in metabolomics and proteomics with lower capital barriers than Orbitrap platforms.
- Ion Trap:Fragmentation-capable systems support structural elucidation workflows with niche positioning between quadrupole and high-resolution platforms.
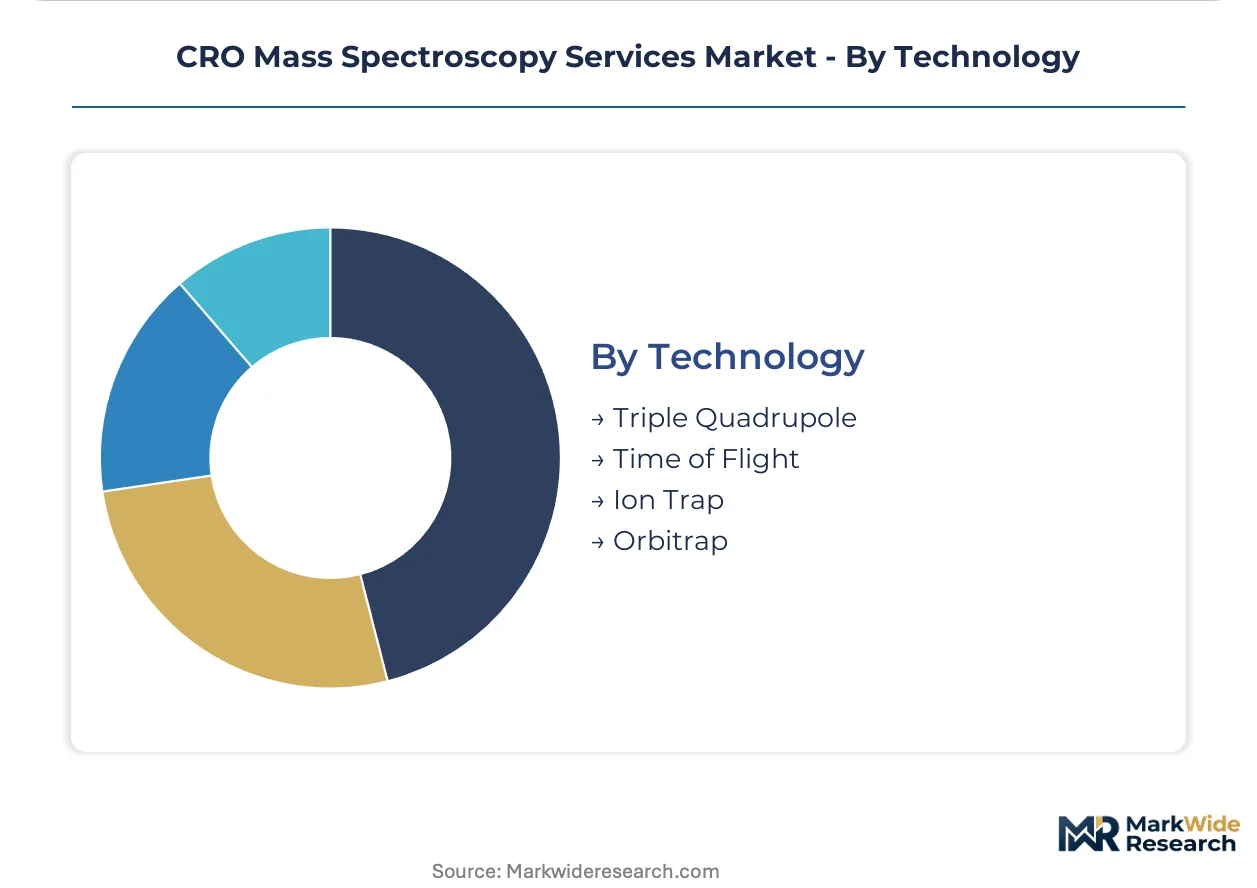
Triple quadrupole platforms retain the largest installed base, with Orbitrap technology expanding most quickly as peptide therapeutic pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States CROs command premium pricing for GLP-certified bioanalysis, while Indian laboratories undercut Western rates by 40-60% on method development contracts. This divergence concentrates high-margin regulated work in North American facilities and commoditized discovery services in South Asian operations.
United States
FDA bioequivalence guideline tightening for complex generics drives exact-mass platform investments across Boston-Cambridge and San Diego biotech clusters. The agency's advancing guidance on peptide bioequivalence mandates additional pharmacokinetic endpoints, extending validation protocols. Massachusetts and California venture-backed sponsors unbundle method development from sample analysis to conserve cash, disrupting traditional full-service contracts.
Germany
EMA ICH Q14 quality-by-design adoption creates recurring revenue for CROs building proprietary method libraries serving mid-sized European pharma. The country's national pharmaceutical regulator enforces analytical target profile documentation requirements that mirror FDA standards. Baden-Württemberg and Bavaria host dense pharmaceutical manufacturing footprints, pulling contract laboratory demand toward centralized European logistics hubs.
India
CDSCO alignment with ICH bioanalytical standards enables export-quality CRO capacity to serve Western sponsors at cost-advantaged rates. The national pharmaceutical regulator's harmonization efforts are accelerating facility qualification timelines previously frozen by regulatory divergence. Hyderabad and Bangalore clusters concentrate method development talent pools that undercut US pricing on non-GLP discovery workflows.
China
NMPA bioanalytical method validation convergence with ICH frameworks expands domestic CRO eligibility for multinational sponsor contracts. The national medical products administration's evolving peptide therapeutic guidelines mirror FDA complexity thresholds. Shanghai and Suzhou biotech parks anchor multi-site laboratory networks that reduce sample logistics friction for Asia-based drug developers.
Switzerland
Swissmedic regulatory inspection reciprocity with FDA and EMA qualifies domestic CROs for simultaneous US-EU submission support. The national regulatory agency's exacting GLP enforcement maintains premium positioning for Basel-Zurich corridor laboratories. Roche and Novartis proximity concentrates specialized bioanalytical demand for large-molecule pharmacokinetic characterization.
CRO Mass Spectroscopy Services Market Vendor Landscape
United States-based integrated platforms anchor the premium tier; Asia-Pacific specialists hold cost-advantaged positions on method development commoditization. Market structure consolidates around three archetypes: full-service instrument-to-service integrators, geographic reach specialists with multi-site networks, and toxicology-anchored North American incumbents. Dominant competitive moves include captive high-resolution platform deployment and documented regulatory interaction histories that secure multi-year master service agreements.
Within the integrated platform tier, Thermo Fisher Scientific exemplifies instrument-to-service vertical control. Charles River Laboratories occupies a position as the toxicology-anchored North American incumbent. WuXi AppTec represents geographic reach specialization through multi-site laboratory networks. These three archetypes illustrate how competitive positioning separates premium-regulated eligibility from cost-driven discovery outsourcing.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| SCIEX |
| Bruker Corporation |
| Waters Corporation |
| Charles River Laboratories |
| Eurofins Scientific |
| WuXi AppTec |
| Labcorp Drug Development |
| Others |
Supply Flow & Price Mechanics
GLP certification tiering separates premium-regulated bioanalysis from commoditized discovery workflows, with United States-based CROs commanding substantial markups for FDA-inspected facilities while Indian laboratories undercut Western rates on non-regulated method development. This bifurcation concentrates high-margin pharmacokinetic studies in North American captive platforms and pushes exploratory metabolomics toward cost-optimized South Asian operations.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for non-GLP method development, compressing margins on fixed-price discovery contracts. Project-based pricing dominates regulated bioanalysis, with FDA certification tier and sponsor audit history driving substantial price differentiation. Pricing pressure intensifies in triple quadrupole bioanalysis as high-resolution Orbitrap platforms encroach on routine applications. Venture-backed biotechnology sponsors in Massachusetts and California exhibit highest price sensitivity, unbundling services to conserve cash.
Supply Chain Analysis
Domestic-content mandates in China's NMPA framework are reshaping sourcing patterns for multinational sponsors seeking local trial support. Instrument manufacturing concentrates in Germany, the United States, and Japan, with mass spectrometer cryogenic cooling drawing from helium extraction concentrated in Qatar and the United States. Single-source vulnerability in noble gas supply chains threatens margin stability on long-term service contracts. Distribution runs through multi-site laboratory networks that reduce sample logistics friction for geographically dispersed sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
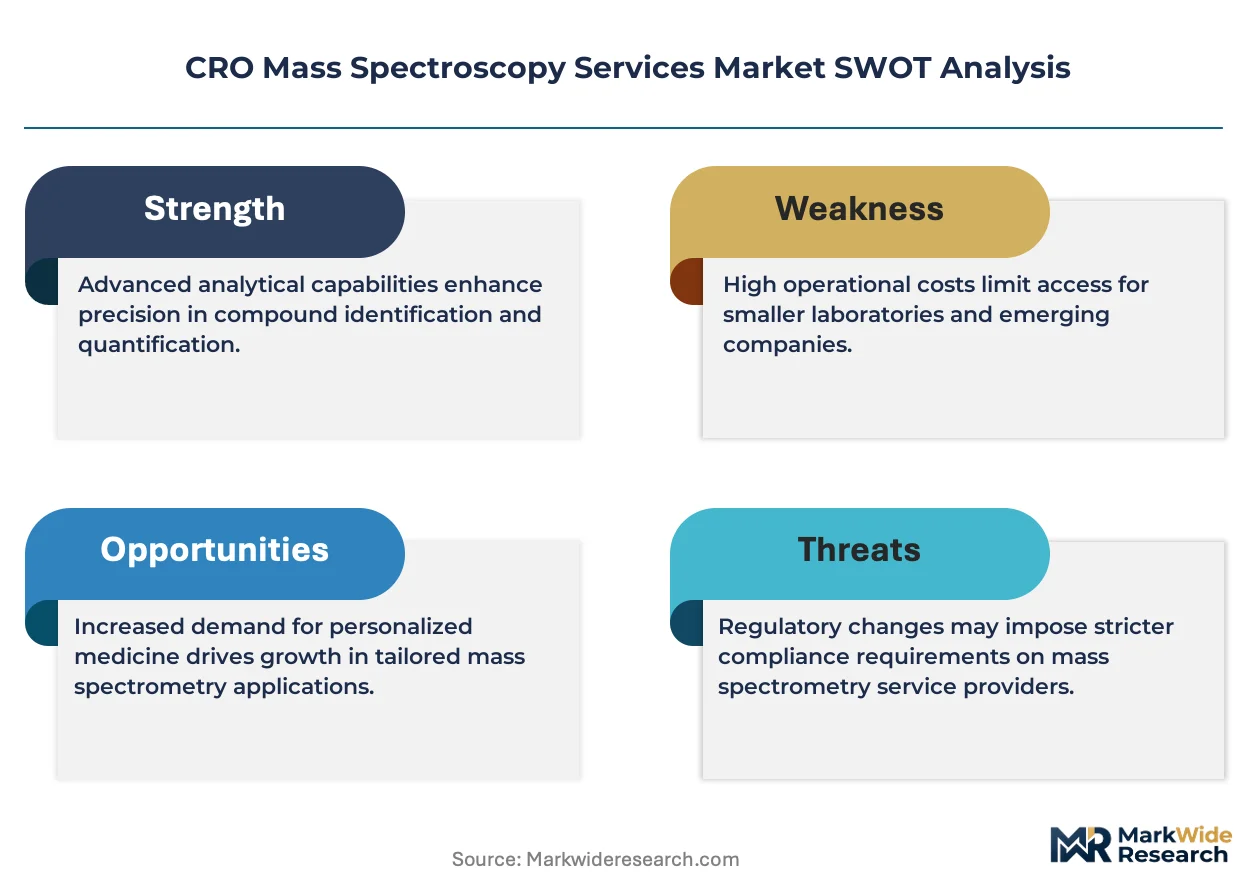
The CRO mass spectroscopy services market functions as a regulatory compounder, with FDA's advancing peptide bioequivalence guidance mandating expanded pharmacokinetic endpoints and exact-mass platform investments that deepen sponsor dependence on certified providers.
For Market Incumbents: Anticipate margin compression in routine triple quadrupole bioanalysis as high-resolution platforms commoditize unit-mass applications, and respond by consolidating method development intellectual property through exclusive licensing arrangements with mid-sized biotechnology sponsors. Captive Orbitrap deployment in Boston-Cambridge and San Diego clusters defends pricing power against emerging Indian competitors. For New Entrants and Emerging Players: Launch via specialized cell and gene therapy bioanalysis workflows that incumbent CROs have not standardized, targeting viral vector biodistribution studies for emerging therapeutic platforms. White space concentrates in novel sample preparation protocols for gene therapy pharmacokinetics, with regulatory inspection reciprocity between Swissmedic and FDA enabling simultaneous US-EU submission support from Basel-Zurich corridor positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where GLP certification barriers freeze new entrants out of regulated segments, creating acquisition opportunities for toxicology-anchored North American laboratories with documented FDA interaction histories. Long-term viability favors platforms with backward integration into instrument supply chains. The signal to watch is CDSCO alignment progress with ICH standards, which would validate Indian capacity for Western sponsor contracts at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Captive High-Resolution Platform Deployment | Orbitrap exact-mass systems unlock peptide therapeutic bioanalysis contracts requiring FDA bioequivalence compliance. |
| Proprietary Method Library Development | ICH Q14 analytical target profile documentation creates recurring revenue streams from validated assay portfolios. |
| Multi-Site Laboratory Network Expansion | Geographic reach specialists reduce sample logistics friction for Asia-based sponsors in Shanghai and Suzhou biotech parks. |
| AI-Assisted Peak Integration Investment | Machine learning algorithms trained on historical chromatograms compress method development timelines and proposal-to-delivery cycles. |
| Regulatory Inspection Reciprocity Qualification | Swissmedic-FDA-EMA alignment enables simultaneous US-EU submission support from centralized European logistics hubs. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with bioanalytical laboratory directors, regulatory affairs leads at pharmaceutical sponsors, CRO procurement officers, and mass spectrometry platform engineers with secondary validation against FDA bioanalytical method validation guidelines, EMA ICH Q14 documentation, ClinicalTrials.gov protocol registrations, and OECD GLP inspection records. Bottom-up service-line builds and top-down market sizing triangulated volume estimates across the analysis window.
Comparable-period anchoring tied projection assumptions to historical instrument deployment cycles and regulatory guidance issuance patterns across the modeling period. Segmentation dimensions modeled include service type, end user category, therapeutic application, and technology platform tier, with CAGRs derived from sponsor outsourcing budget trajectories and capital expenditure patterns for exact-mass system installations. Forecast inputs incorporated peptide therapeutic pipeline maturation rates and CDSCO regulatory harmonization milestones.
Several conditions sit outside the modeled scope, including unforeseen helium supply disruptions, accelerated platform obsolescence cycles below four-year thresholds, and radical shifts in FDA complex generic bioequivalence requirements. Forecasts reflect documented assumptions about sponsor consolidation behavior and regulatory inspection capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
South America Endotoxin and Pyrogen Testing Market
Testing Services
United States Testing, Inspection, and Certification (TIC) Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Mono Rapid Testing Market
Testing Services
Nicotine Testing Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Cholesterol Test Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
Ovulation Test Kit Market
Testing Services
United States Esoteric Testing Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Germany Testing, Inspection and Certification Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Global Sleep Testing Services Market
Testing Services
Global HPV Testing and Pap Test Market