
 Blood Pressure Test Market | 2026-2036
Blood Pressure Test Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Pressure Test Market Outlook
Market Context with Strategic Players
ISO 81060-2 validation for automated non-invasive blood pressure monitors is collapsing the competitive field to manufacturers with dedicated clinical-trial infrastructure. Omron Healthcare, Inc. leverages decades of oscillometric algorithm refinement to sustain leadership across retail pharmacy channels. GE Healthcare anchors hospital procurement decisions through integrated vital-signs platforms embedded in enterprise EMR workflows. Koninklijke Philips N.V. competes by extending wearable blood-pressure sensing into consumer health ecosystems.
Technical Definition and Structural Segments
A blood pressure test measures systolic and diastolic arterial pressure, typically expressed in millimeters of mercury (mmHg), using either cuff-based occlusion with pressure transducers or pulse transit time estimation through optical sensors. The primary commercial purpose spans hypertension diagnosis, medication titration, and longitudinal cardiovascular risk management across clinical and ambulatory settings. Digital monitors dominate unit volume due to one-touch operation and memory logging, while Bluetooth-enabled devices capture the fastest expansion as remote patient monitoring contracts with accountable care organizations proliferate. Mobile devices occupy a narrow but high-margin niche serving pharmaceutical trial sponsors requiring decentralized data collection.
Regulatory Frame and Forward-Looking Close
FDA premarket notification requirements under 21 CFR 870.1130, CE marking under the EU Medical Device Regulation, and Japan's PMDA approval for home-use claims collectively determine which manufacturers access reimbursed channels. These frameworks compel firms to maintain parallel clinical-validation programs across three distinct regulatory architectures, raising fixed costs for new entrants. Stakeholders must monitor whether CMS expands remote therapeutic monitoring reimbursement codes to include automated blood-pressure feedback loops, as this policy shift would reallocate margin pools toward software-integrated device vendors.
Market Dynamics
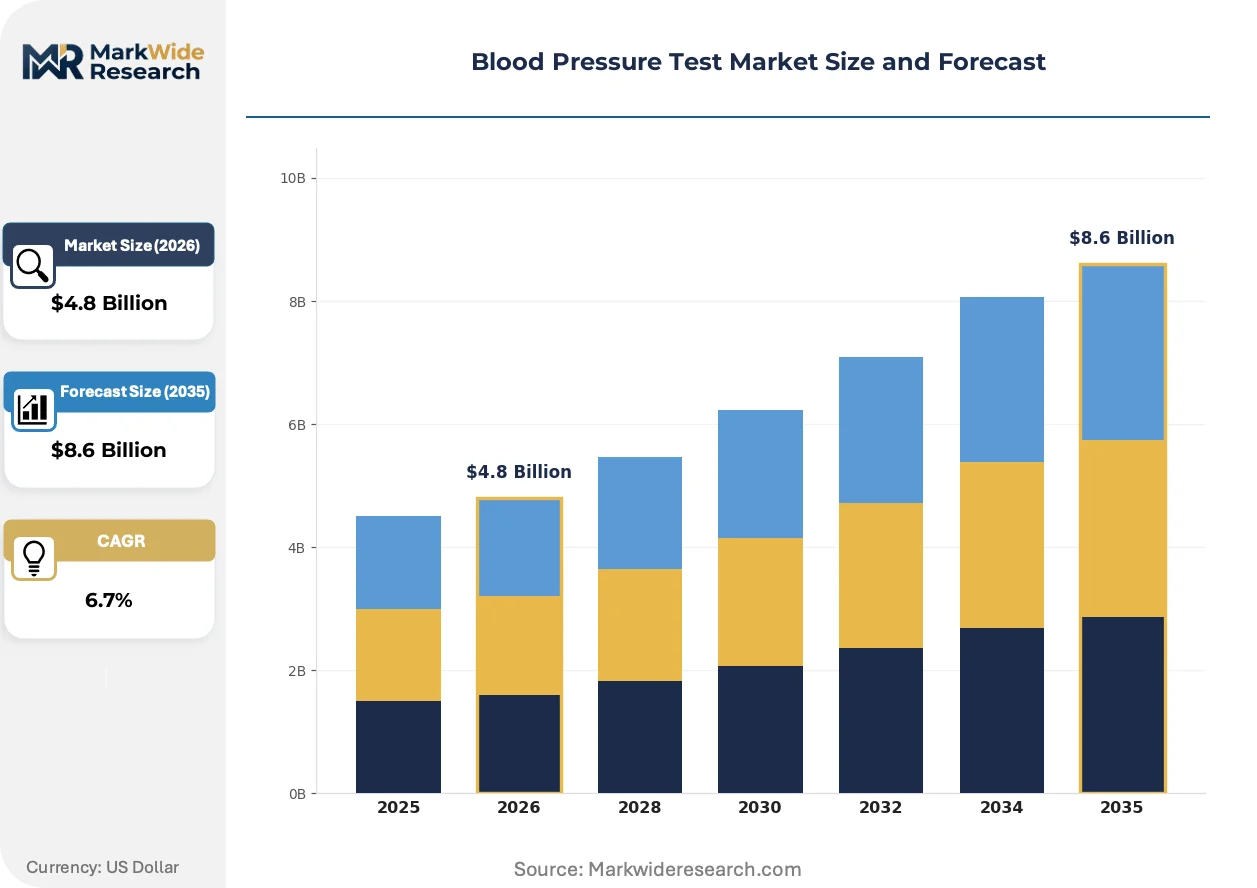
Remote patient monitoring reimbursement codes from CMS are compressing hospital procurement cycles while expanding home-use device volumes, forcing manufacturers to revalidate oscillometric algorithms for ambulatory conditions.
Growth Catalysts
- CMS Remote Therapeutic Monitoring:Reimbursement expansion for automated blood-pressure feedback loops pulls device procurement into accountable care organization contracts.
- Optical Sensor Convergence:Pulse transit time estimation through photoplethysmography enables cuffless wearables for longitudinal cardiovascular tracking.
- Japan's Super-Aged Society:PMDA streamlined approval for home-use claims accelerates preventive hypertension screening among adults over 75.
Market Restraints
- ISO 81060-2 Validation Costs:Clinical-trial infrastructure requirements for automated non-invasive monitors eliminate mid-tier manufacturers without dedicated testing facilities.
- Pressure Transducer Supply Concentration:MEMS sensor fabrication concentrates in Taiwan and South Korea, exposing cuff-based device assembly to single-source vulnerability.
- Algorithm Liability Exposure:Oscillometric interpretation errors in arrhythmic patients create product liability exposure exceeding hardware failure risks.
Strategic Opportunities
- Pharmaceutical Trial Decentralization:Mobile blood-pressure monitors capture high-margin demand from contract research organizations running hybrid clinical studies.
- EU MDR Software Classification:Blood-pressure apps with diagnostic claims face reclassification as Class IIa medical devices, creating first-mover advantage for pre-certified vendors.
- Bluetooth-Enabled RPM Contracts:Integration with Epic and Cerner EMR workflows opens enterprise procurement channels beyond retail pharmacy.
Industry Challenges
- Cross-Platform Algorithm Harmonization:Maintaining consistent oscillometric accuracy across iOS and Android sensor stacks demands specialized firmware engineering talent.
- Parallel Validation Burden:Simultaneous FDA 510(k), CE MDR, and PMDA clinical studies stretch regulatory affairs teams at sub-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Pressure Test Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Monitors, Aneroid Monitors, Wrist Monitors, Mobile Devices End User: Hospitals, Home Care, Clinics, Diagnostics Centers Technology: Oscillometric, Auscultatory, Bluetooth-Enabled, Smartphone Apps Application: Hypertension Management, Health Monitoring, Research Studies, Fitness Tracking |
| Companies Covered | Omron Healthcare, Inc., GE Healthcare, Koninklijke Philips N.V., Hill-Rom Holdings, Inc., A&D Company, Limited, Nihon Kohden Corporation, American Diagnostic Corporation, SunTech Medical, Inc., Masimo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Pressure Test Market Strategic Shifts
Algorithmic interpretation of vascular signals is displacing hardware differentiation as the primary competitive battleground, compressing margins on cuff-based devices while expanding software and data-service revenue pools.
Cuffless blood-pressure estimation through pulse wave velocity analysis is fragmenting the traditional monitor category. Consumer electronics firms are embedding optical sensors into smartwatches and earbuds, capturing intermittent measurements without occlusive cuffs. This technology is fragmenting the boundary between wellness devices and clinical-grade diagnostics, forcing established manufacturers to license third-party algorithms or acquire photonics capabilities.
EU MDR Annex VIII reclassification rules are tightening clinical-evidence requirements for software-driven blood-pressure monitors. Manufacturers must now submit prospective validation studies for algorithm updates, not just initial device approval. Home-use monitor vendors with legacy CE marks under the Medical Device Directive face compressed timelines to resubmit technical documentation.
Patients are consolidating measurement data into Apple Health and Google Fit ecosystems, unbundling device hardware from longitudinal record-keeping. This behavior shifts purchasing influence from physicians to direct-to-consumer channels. Germany and Japan show the strongest platform adoption, where statutory health insurers already reimburse connected prevention programs.
Blood Pressure Test Market Segmentation
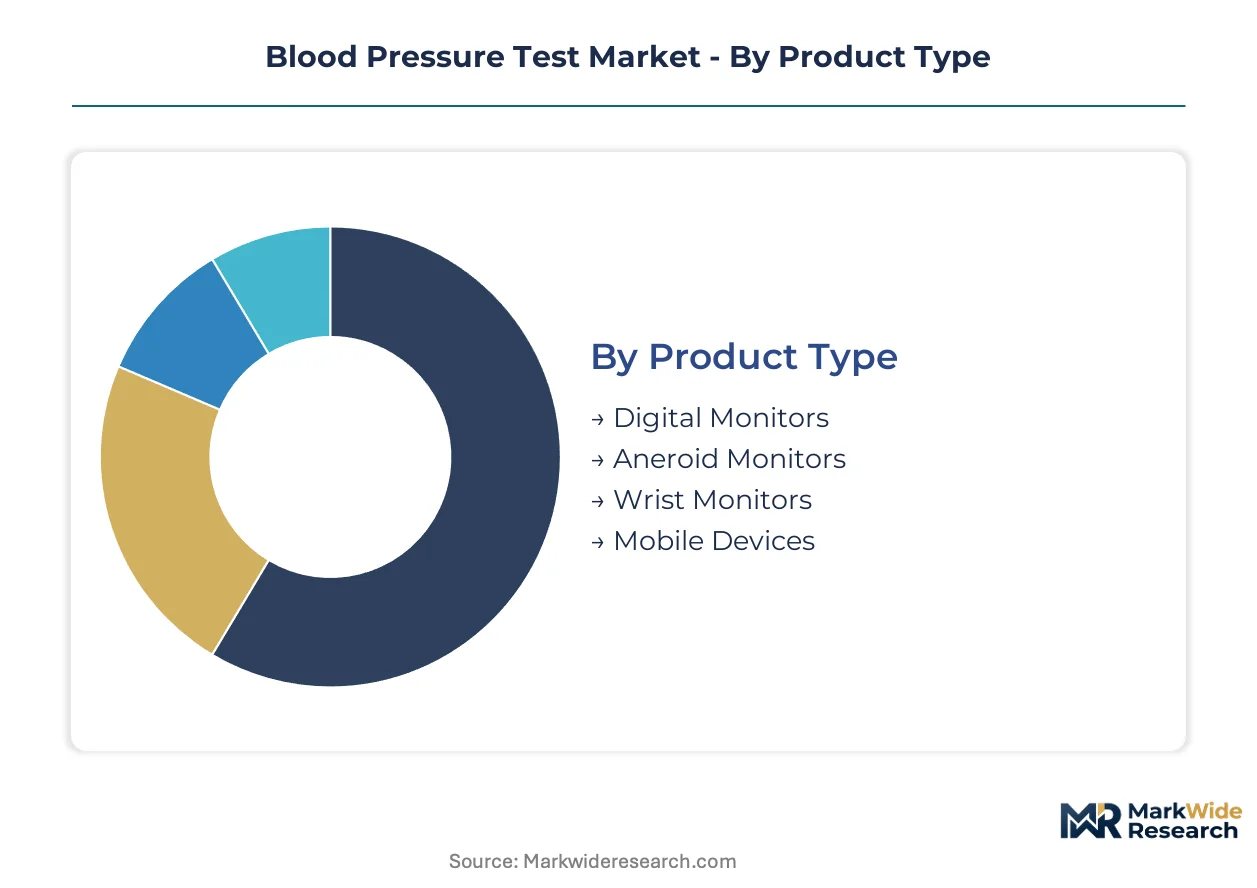
Segmentation in blood pressure testing reveals how reimbursement pathways and sensor convergence reshape competitive boundaries. Device manufacturers must align product architectures with distinct validation requirements across clinical, ambulatory, and consumer channels.
Product Type:
Cuffless optical alternatives threaten traditional monitor categories with substitution pressure concentrated in wrist-worn and smartphone-integrated formats.
- Digital Monitors:Oscillometric devices with pressure transducers and onboard memory dominate retail pharmacy and hospital procurement. CMS remote therapeutic monitoring reimbursement sustains volume leadership in United States accountable care organization contracts.
- Wrist Monitors:Compact oscillometric units with position-sensing algorithms address patient preference for discretion. Demand concentrates in Japan's super-aged society where PMDA streamlined home-use approvals accelerate preventive screening among adults over 75.
- Aneroid Monitors:Manual sphygmomanometers requiring stethoscope auscultation persist in low-resource clinical training environments.
- Mobile Devices:Smartphone-connected cuffs and tablet-integrated sensors serve decentralized clinical trials and pharmaceutical research sponsors.
Digital monitors retain volume leadership; mobile devices hold the steepest expansion curve.
End User:
Procurement authority is migrating from hospital materials management to home-use retail channels as reimbursement shifts toward preventive ambulatory care.
- Home Care:Patients self-manage hypertension through Bluetooth-enabled devices feeding longitudinal data to Epic and Cerner EMR workflows. Germany's statutory health insurers reimburse connected prevention programs, accelerating platform adoption.
- Hospitals:Integrated vital-signs platforms embedded in enterprise systems anchor GE Healthcare and Philips procurement decisions. FDA 510(k) validation under 21 CFR 870.1130 determines vendor qualification for acute care contracts.
- Clinics:Physician offices balance diagnostic accuracy against capital constraints, favoring mid-tier digital monitors with basic memory logging.
- Diagnostics Centers:High-throughput screening facilities require ISO 81060-2 validated automated units for standardized hypertension detection protocols.
Home care captures the fastest volume migration; hospitals maintain the highest per-unit procurement values.
Technology:
Algorithmic interpretation of vascular signals is displacing hardware differentiation as the primary margin determinant.
- Bluetooth-Enabled:Wireless data transmission to remote patient monitoring platforms satisfies CMS reimbursement requirements for automated feedback loops. United States accountable care organizations contract directly with device vendors for population hypertension management.
- Oscillometric:Pressure transducer arrays with proprietary algorithm refinement sustain Omron's retail channel dominance. MEMS sensor fabrication concentration in Taiwan and South Korea exposes assembly to single-source supply vulnerability.
- Auscultatory:Korotkoff sound detection through manual inflation persists in clinical training and low-electronics environments.
- Smartphone Apps:Photoplethysmography-based pulse transit time estimation enables cuffless measurement through camera or accessory sensors. EU MDR Annex VIII reclassification as Class IIa medical devices raises clinical-evidence barriers for diagnostic claims.
Oscillometric technology retains installed-base dominance; Bluetooth-enabled formats climb the fastest on reimbursement tailwinds.
Application:
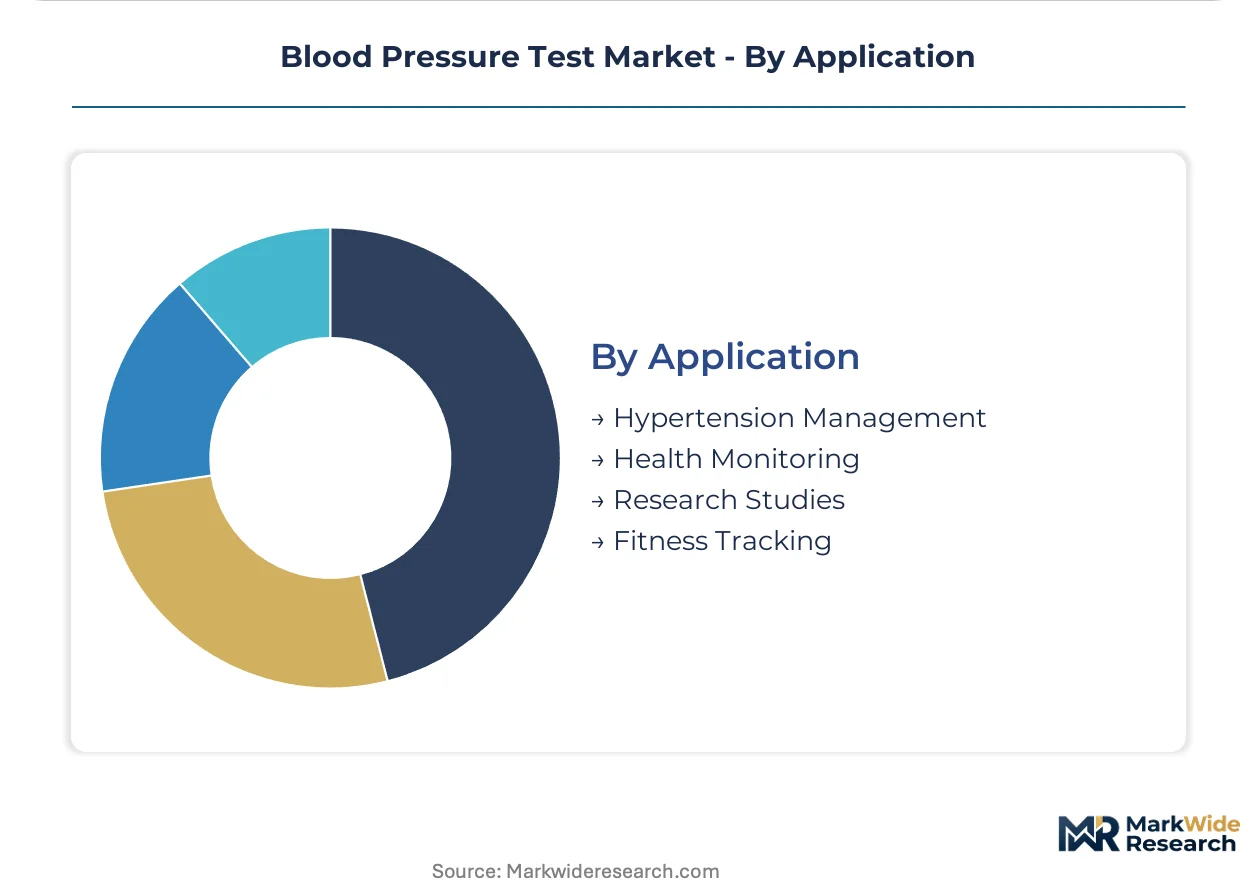
Clinical diagnostic use faces margin compression while wellness-adjacent tracking opens direct-to-consumer pricing power.
- Hypertension Management:Medication titration and cardiovascular risk stratification demand ISO 81060-2 validated accuracy. Japan PMDA and FDA premarket notification requirements restrict vendor participation in reimbursed channels.
- Health Monitoring:Preventive longitudinal tracking integrates Apple Health and Google Fit ecosystems, shifting purchasing influence from physicians to direct-to-consumer channels. Germany shows strongest platform adoption among statutory insurance populations.
- Research Studies:Contract research organizations running hybrid decentralized trials capture high-margin demand for mobile blood-pressure monitors with audit-grade data logging.
- Fitness Tracking:Consumer electronics firms embed optical sensors into smartwatches, fragmenting the boundary between wellness devices and clinical-grade diagnostics.
Hypertension management retains reimbursement anchoring; health monitoring gains share fastest on platform ecosystem expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS remote therapeutic monitoring reimbursement codes are pulling United States procurement toward accountable care organization contracts. Germany's statutory health insurers reimburse connected prevention programs. Japan's PMDA streamlined home-use approvals accelerate preventive screening among adults over 75.
United States
FDA 510(k) premarket notifications under 21 CFR 870.1130 determine vendor qualification for acute care contracts. CMS reimbursement expansion for automated blood-pressure feedback loops compresses hospital procurement cycles while expanding home-use volumes. The Minneapolis medical device corridor concentrates oscillometric algorithm development and clinical-trial infrastructure.
Germany
EU MDR Annex VIII reclassification rules tighten clinical-evidence requirements for software-driven monitors. Statutory health insurers reimburse connected prevention programs, accelerating platform adoption of Bluetooth-enabled devices feeding longitudinal data to EMR workflows. The Baden-Württemberg industrial cluster anchors precision MEMS sensor fabrication for pressure transducer arrays.
Japan
PMDA streamlined approval pathways for home-use claims target the super-aged society demographic over 75. METI preventive cardiovascular screening programs integrate remote monitoring into community health initiatives. The Tokyo-Osaka corridor concentrates wearable blood-pressure sensing development and consumer health ecosystem integration.
China
NMPA medical device registration requirements for home-use blood pressure monitors are converging with international ISO 81060-2 validation standards. The country's national health commission promotes preventive screening in tier-1 cities as hypertension prevalence rises. The Yangtze River Delta manufacturing belt dominates cuff-based device assembly and MEMS sensor integration.
South Korea
MFDS approval frameworks for connected health devices align with FDA and CE marking protocols to enable export-oriented manufacturing. The national health insurance service pilots remote patient monitoring for chronic disease management in Seoul metropolitan hospitals. The Gyeonggi-do semiconductor corridor supplies pressure transducer components to global device assemblers.
Blood Pressure Test Market Competitive Environment
Player mix skews toward diversified health technology conglomerates with dedicated clinical-trial infrastructure. Market structure concentrates around oscillometric algorithm refinement capabilities and regulatory validation expertise across FDA, CE MDR, and PMDA architectures. Two strategic archetypes dominate: integrated vital-signs platform vendors anchoring hospital procurement, and consumer health specialists capturing retail pharmacy and direct-to-consumer channels. Competitive moves center on algorithm licensing partnerships and EMR workflow integration capabilities.
Within the diversified health technology tier, Omron Healthcare, Inc. and GE Healthcare occupy positions reflecting distinct channel strategies. Omron exemplifies the retail pharmacy and home-use specialist archetype through decades of oscillometric algorithm presence in consumer channels. GE Healthcare anchors the hospital procurement vector through integrated vital-signs platforms embedded in enterprise systems. Koninklijke Philips N.V. sits within the wearable sensing expansion archetype, extending blood-pressure monitoring into consumer health ecosystems. These three entities collectively represent the regulatory validation, channel access, and technology convergence vectors shaping competitive positioning.
| Leading Market Players |
|---|
| Omron Healthcare, Inc. |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Hill-Rom Holdings, Inc. |
| A&D Company, Limited |
| Nihon Kohden Corporation |
| American Diagnostic Corporation |
| SunTech Medical, Inc. |
| Masimo |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day MEMS sensor lead times from Taiwan and South Korea concentrate pricing power with oscillometric device assemblers holding strategic inventory positions, while Bluetooth-enabled monitor vendors face component allocation volatility that compresses margin buffers on mid-tier units.
Pricing Analysis
Certification level creates the primary spread between ISO 81060-2 validated clinical units and consumer-grade wellness devices. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, algorithm accuracy claims, and EMR integration depth. Pricing pressure stems from optical sensor convergence enabling smartphone-based cuffless alternatives that undercut traditional monitor price points. Hospital procurement committees demonstrate lowest price sensitivity given reimbursement pass-through structures, while direct-to-consumer retail channels exhibit acute elasticity to promotional discounting.
Supply Chain Analysis
Strategic stockpile preferences dominate among oscillometric device manufacturers buffering against MEMS pressure transducer allocation constraints, whereas just-in-time inventory strategies prevail for software-integrated vendors assembling Bluetooth-enabled units from modular subsystems. Component sourcing concentrates in Taiwan, South Korea, and China's Yangtze River Delta manufacturing belt. Raw material dependencies span MEMS silicon wafers, medical-grade polymers for cuff bladders, and lithium-ion cells for portable power. Single-source vulnerability in Taiwanese MEMS fabrication exposes assembly schedules to geopolitical disruption. Distribution runs through medical device distributors, retail pharmacy chains, and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent oscillometric device manufacturers face substitution defense against photoplethysmography-based cuffless wearables that fragment the boundary between wellness tracking and clinical-grade diagnostics.
For Market Incumbents: Compound algorithmic differentiation through proprietary oscillometric refinement and EMR workflow integration depth to sustain hospital procurement anchoring. Deepen backward integration into MEMS pressure transducer sourcing to mitigate Taiwan supply concentration risk. Accelerate FDA 510(k) pathway investments for connected device platforms ahead of CMS reimbursement expansion for automated feedback loops. For New Entrants and Emerging Players: Differentiate on decentralized clinical trial data capture capabilities serving contract research organizations with audit-grade mobile monitoring solutions. Target pharmaceutical trial sponsors as the most penetrable buyer segment given high-margin willingness-to-pay for validated ambulatory measurement. Pursue EU MDR pre-certification for blood-pressure apps with diagnostic claims to capture first-mover advantage under Class IIa reclassification rules. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified health technology conglomerates seeking to divest non-core consumer monitoring divisions amid strategic portfolio rebalancing. Long-term viability hinges on software-integrated device architectures capturing recurring data-service revenue streams beyond hardware transaction economics. Monitor CMS remote therapeutic monitoring code expansion as the critical inflection signal for reallocating capital toward RPM-contracted vendors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Premarket notification clearance unlocks acute care procurement channels under 21 CFR 870.1130. |
| CE Marking Pathway | EU MDR Annex VIII compliance enables access to German statutory insurance reimbursement frameworks. |
| Hospital System Partnership | Epic and Cerner EMR integration contracts anchor enterprise vital-signs platform decisions. |
| Software Companion Development | Bluetooth-enabled data services capture recurring revenue from accountable care organization hypertension management contracts. |
| Reimbursement Strategy | CMS remote therapeutic monitoring code alignment pulls device procurement into population health contracts. |
Study Parameters
A standing panel of hospital biomedical engineers, GPO contracts managers, retail pharmacy category buyers, and regulatory affairs specialists at device manufacturers provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation through FDA 510(k) premarket notification databases, CMS Medicare reimbursement code filings, EU MDR technical documentation registries, and hospital procurement contract awards. Bottom-up unit volume estimates triangulated against top-down expenditure flows from national health accounts.
Consistency checks validated volume and value outputs against external benchmarks including medical device trade association shipments data and regulatory approval timelines across the analysis window. Segmentation modeling spanned product architecture, end-use setting, connectivity technology, and regional reimbursement framework. CAGRs derived from curve-fitting approaches applied to validated baseline estimates and scenario-weighted growth assumptions. Industry-specific forecast inputs incorporated ISO 81060-2 validation pipeline visibility and CMS remote monitoring policy evolution signals.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement expansion for connected prevention programs or accelerated cuffless technology clinical validation would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway timelines and MEMS supply chain stability. Revision becomes warranted when optical sensor accuracy claims achieve FDA diagnostic-grade clearance thresholds or when Taiwan semiconductor export controls disrupt pressure transducer availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Creatinine Testing Market
Testing Services
North America Drug Screening Market
Testing Services
Arbovirus Testing Market
Testing Services
Asia-Pacific Newborn Screening Market
Testing Services
Cholesterol Test Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Viral Vector Integrity and Potency Analytics Test Instruments Market
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Home Menopause Testing Market