
 Global Mycoplasma Testing Market | 2026-2036
Global Mycoplasma Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mycoplasma Testing Market Foresight
The capability gap between automated high-throughput platforms and manual culture-based methods is unwinding as capital requirements diverge sharply across the competitive landscape. Lonza Group leverages its integrated bioscience manufacturing infrastructure to sustain pricing power in contract testing services. Sartorius AG anchors European supply chains through precision filtration and cell-culture analytics integration. Thermo Fisher Scientific dominates North American instrument placements with applied biosystems PCR workflows that extend into bioproduction quality control.
Mycoplasma testing encompasses nucleic acid amplification, culture isolation, and biochemical detection methods applied to identify cell-culture contaminants lacking rigid cell walls, with detection sensitivity thresholds typically reaching 10–100 colony-forming units per milliliter in validated PCR protocols. The primary commercial purpose centers on safeguarding biologics manufacturing, gene therapy vector production, and vaccine seed-lot purity from economically devastating contamination events. Real-time PCR kits command premium positioning due to accelerated turnaround requirements in biopharmaceutical production, while culture media maintains volume leadership across research institutes with lower throughput demands. ATP bioluminescence competes for in-process monitoring applications where rapid qualitative screening reduces batch-release risk.
FDA biologics guidance, EMA GMP Annex 1 revisions, and ISO 17025 accreditation frameworks collectively mandate validated mycoplasma detection across clinical-grade cell-banking and commercial manufacturing workflows. These standards shape procurement criteria by disqualifying non-validated methods from regulated submissions and driving replacement cycles toward instrument-based platforms. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP chapters as divergence in acceptance criteria threatens cross-border product registration timelines and testing protocol standardization investments.
Market Dynamics
Real-time PCR instrumentation is compressing detection timelines from weeks to hours, forcing biopharmaceutical manufacturers to retire legacy culture-based workflows or risk batch-release delays against tightening FDA and EMA compliance windows.
Growth Catalysts
- EMA GMP Annex 1 revisions:The 2022 update mandates continuous environmental monitoring in aseptic processing, driving replacement demand for automated mycoplasma detection platforms across European cell therapy facilities.
- Cell therapy manufacturing scale-up:CAR-T and gene therapy production in China, the United States, and Germany requires validated contamination control at every cell-banking stage, expanding contract testing volumes.
- ATP bioluminescence:In-process monitoring applications in vaccine seed-lot production are accelerating adoption of rapid qualitative screening to reduce batch-failure risk before final PCR confirmation.
Market Restraints
- Capital intensity of qPCR platforms:Instrument acquisition costs and annual service contracts strain research institute budgets, preserving manual culture methods in academic settings with lower throughput.
- Reagent supply concentration:Master mix and probe chemistries depend on specialized polymerase suppliers concentrated in Germany and the United States, exposing procurement to geopolitical friction and customs delays.
- Pharmacopeial divergence:Differences in acceptance criteria between USP, EP, and JP chapters force manufacturers to maintain multiple validation protocols, increasing compliance overhead for cross-border product registration.
Strategic Opportunities
- India biologics manufacturing:CDSCO's tightening GMP enforcement and the PLI scheme for pharmaceuticals create first-mover advantage for instrument vendors establishing local service infrastructure.
- Point-of-need testing:Portable nucleic acid amplification devices for at-line bioreactor monitoring address the gap between central lab turnaround and real-time process control decisions.
- ISO 17025 accreditation expansion:Third-party testing laboratories pursuing international accreditation standards unlock contract opportunities with multinational biopharmaceutical sponsors requiring harmonized quality systems.
Industry Challenges
- Multidisciplinary skill gaps:Operators must combine molecular biology expertise with GMP documentation discipline and statistical process control, a profile scarce in regional manufacturing clusters outside established biotech hubs.
- Legacy system integration:Automated PCR platforms must interface with existing manufacturing execution systems and laboratory information management systems, requiring custom validation protocols that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mycoplasma Testing Market |
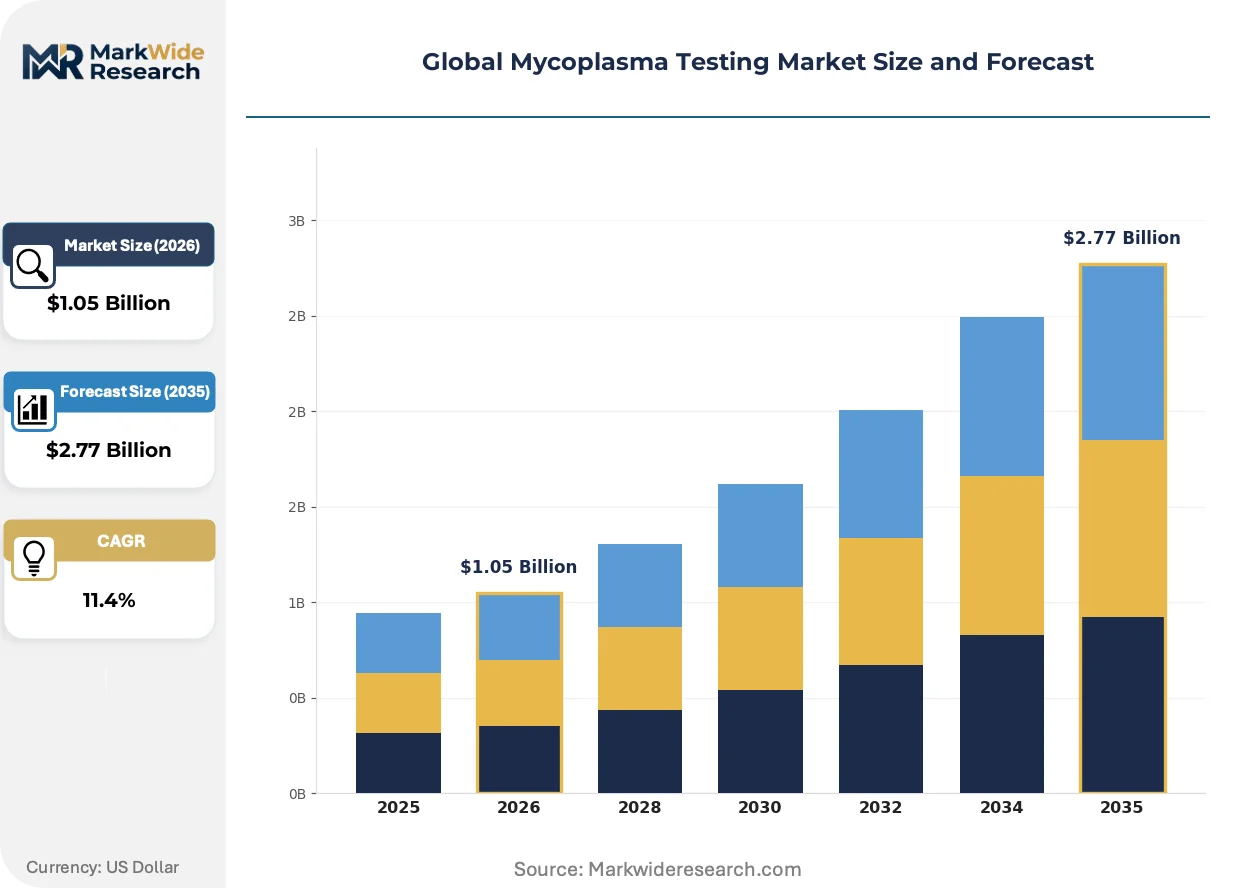
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymerase Chain Reaction Kits, Culture Media, Enzyme-Linked Immunosorbent Assay Kits, Biosensors Application: Pharmaceutical Quality Control, Biopharmaceutical Production, Cell Culture Monitoring, Vaccine Manufacturing Testing Technology: DNA Staining, Real-Time PCR, Immunofluorescence Assay, ATP Bioluminescence End User: Contract Research Organizations, Diagnostic Laboratories, Research Institutes, Bio-Manufacturing Companies |
| Companies Covered | Lonza Group, Sartorius AG, Thermo Fisher Scientific, SGS, Roche Diagnostics, Charles River Laboratories International, Eurofins Scientific, ATCC, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mycoplasma Testing Market Shifts & Advancements
Detection technology is bifurcating between high-throughput automation for commercial manufacturing and simplified point-of-need formats for distributed cell therapy production, reshaping vendor R&D priorities and service model architecture.
Digital PCR is fragmenting the sensitivity hierarchy in mycoplasma detection by enabling absolute quantification without standard curves, a capability cell therapy developers in the United States are adopting ahead of regulatory mandate to preempt FDA scrutiny of low-titer contamination events. The technology compresses validation burden for novel vector platforms where reference materials remain scarce. Platform consolidation is accelerating as biopharmaceutical quality control departments prioritize vendor ecosystems that span sample prep through data integrity.
REACH restrictions on fluorophore chemistries are forcing reagent manufacturers to reformulate probe-based detection kits, with ECHA's 2023 substance evaluation timeline compressing product lifecycle planning for European kit suppliers. The regulatory pressure is amplifying investment in alternative signal amplification chemistries. Biopharmaceutical sponsors are demanding supply chain documentation that traces fluorophore provenance to preempt registration delays.
Service unbundling is penetrating the mycoplasma testing market as biopharmaceutical procurement teams separate instrument acquisition from validation support and ongoing reagent supply, pressuring bundled pricing models that dominated early PCR platform adoption. Contract testing organizations are capturing disaggregated validation service contracts that manufacturers previously self-performed. This pattern is most pronounced in Germany, where mid-sized gene therapy developers lack internal quality infrastructure.
Global Mycoplasma Testing Market Segmentation
Mycoplasma testing segmentation reflects divergent regulatory acceptance criteria across FDA, EMA, and pharmacopeial jurisdictions. Technology choices cascade through validation requirements, capital deployment patterns, and service outsourcing decisions in biopharmaceutical quality control.
Product Type:
FDA and EMA guidance documents differentiate acceptable detection methods by sensitivity thresholds and validation burden, creating tiered procurement patterns across regulated manufacturing environments.
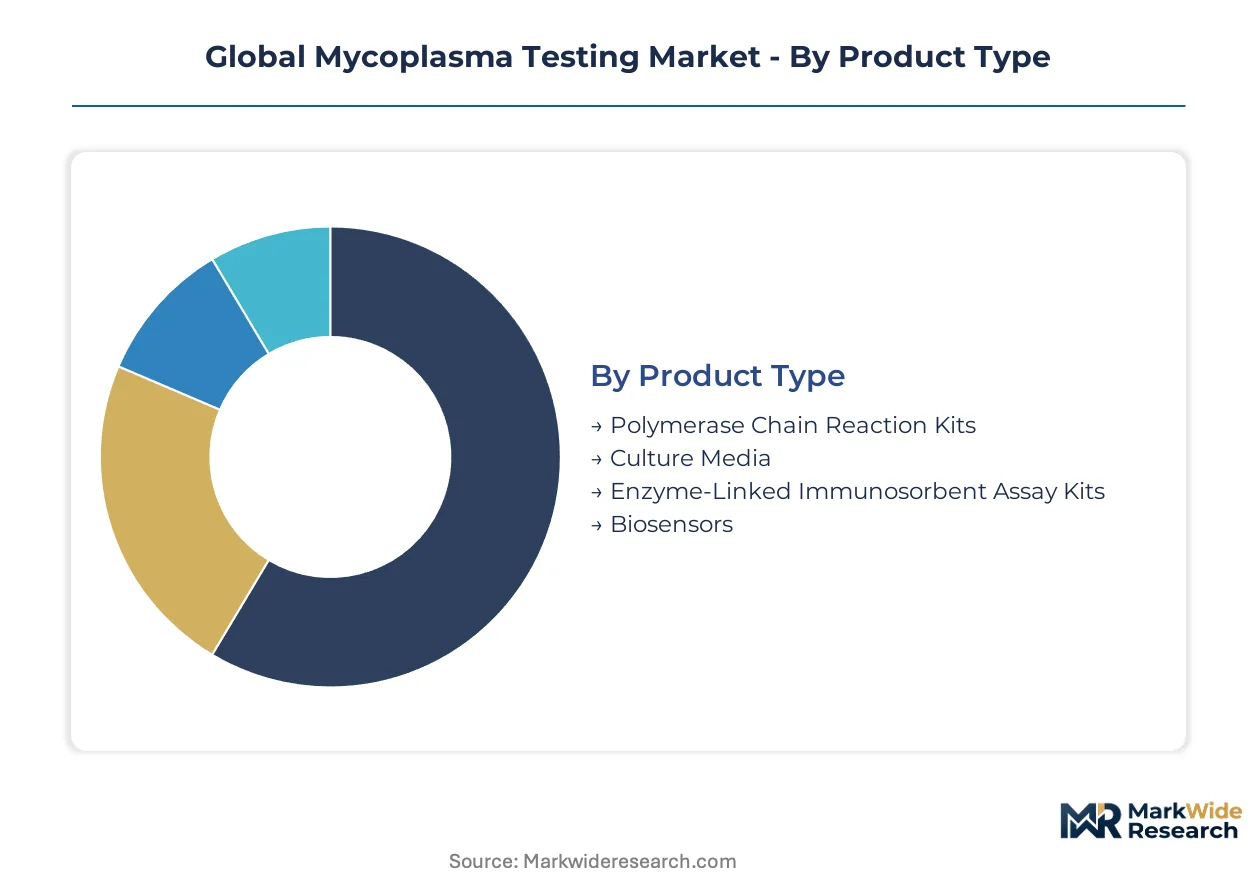
- Polymerase Chain Reaction Kits:Nucleic acid amplification platforms deliver 10–100 CFU/mL detection limits with turnaround compressed to hours. Biopharmaceutical manufacturers in Germany and the United States prioritize these kits for batch-release decisions under tightening compliance windows.
- Culture Media:Traditional agar and broth formulations remain pharmacopeially mandated as reference methods despite multi-week incubation periods. Research institutes with lower throughput and limited capital budgets sustain volume demand for manual culture workflows.
- Enzyme-Linked Immunosorbent Assay Kits:Antibody-based detection offers intermediate sensitivity for screening applications where PCR infrastructure is unavailable.
- Biosensors:Emerging electrochemical and optical platforms target point-of-need deployment in distributed cell therapy manufacturing.
Polymerase Chain Reaction Kits handles the majority of throughput; Biosensors is expanding most quickly on share.
Application:
Cost tier differentiation separates high-stakes commercial manufacturing from research-stage monitoring with divergent failure consequences.
- Biopharmaceutical Production:CAR-T and gene therapy vector manufacturing commands the most stringent contamination control with validated real-time PCR at every cell-banking stage. Chinese and American facilities scale automated platforms to match production volume expansion.
- Pharmaceutical Quality Control:Small-molecule biologics and biosimilars require mycoplasma clearance for master cell banks and working cell banks under ICH Q5D guidelines. European manufacturers face accelerated replacement cycles following EMA GMP Annex 1 revisions.
- Vaccine Manufacturing:Seed-lot purity testing combines ATP bioluminescence screening with confirmatory PCR to reduce batch-failure risk in pandemic response scenarios.
- Cell Culture Monitoring:Academic and contract research environments employ lower-cost methods with reduced documentation requirements.
Biopharmaceutical Production captures the highest validation spend per test; Vaccine Manufacturing is climbing the fastest as pandemic preparedness infrastructure expands.
Testing Technology:
Volume concentration favors established platforms with pharmacopeial recognition, while margin expansion concentrates in emerging methods preempting regulatory mandate.
- Real-Time PCR:Quantitative amplification with fluorogenic probe detection dominates commercial manufacturing for sensitivity, specificity, and automation compatibility. Thermo Fisher and Roche platforms anchor North American and European instrument bases.
- ATP Bioluminescence:Rapid enzymatic detection of metabolic activity enables in-process screening with results in minutes. Vaccine seed-lot producers adopt this for at-line monitoring before final PCR confirmation.
- DNA Staining:Fluorescent dye methods like Hoechst 33258 retain niche applications for academic research despite lower sensitivity and subjective interpretation.
- Immunofluorescence Assay:Antibody-based visualization persists in legacy protocols though largely superseded by nucleic acid methods for regulatory submissions.
Real-Time PCR commands the installed base; ATP Bioluminescence is gaining share fastest in process analytical technology integration.
End User:
Customer type determines capital intensity tolerance and outsourcing propensity, fragmenting vendor go-to-market strategies between instrument sales and service contracts.
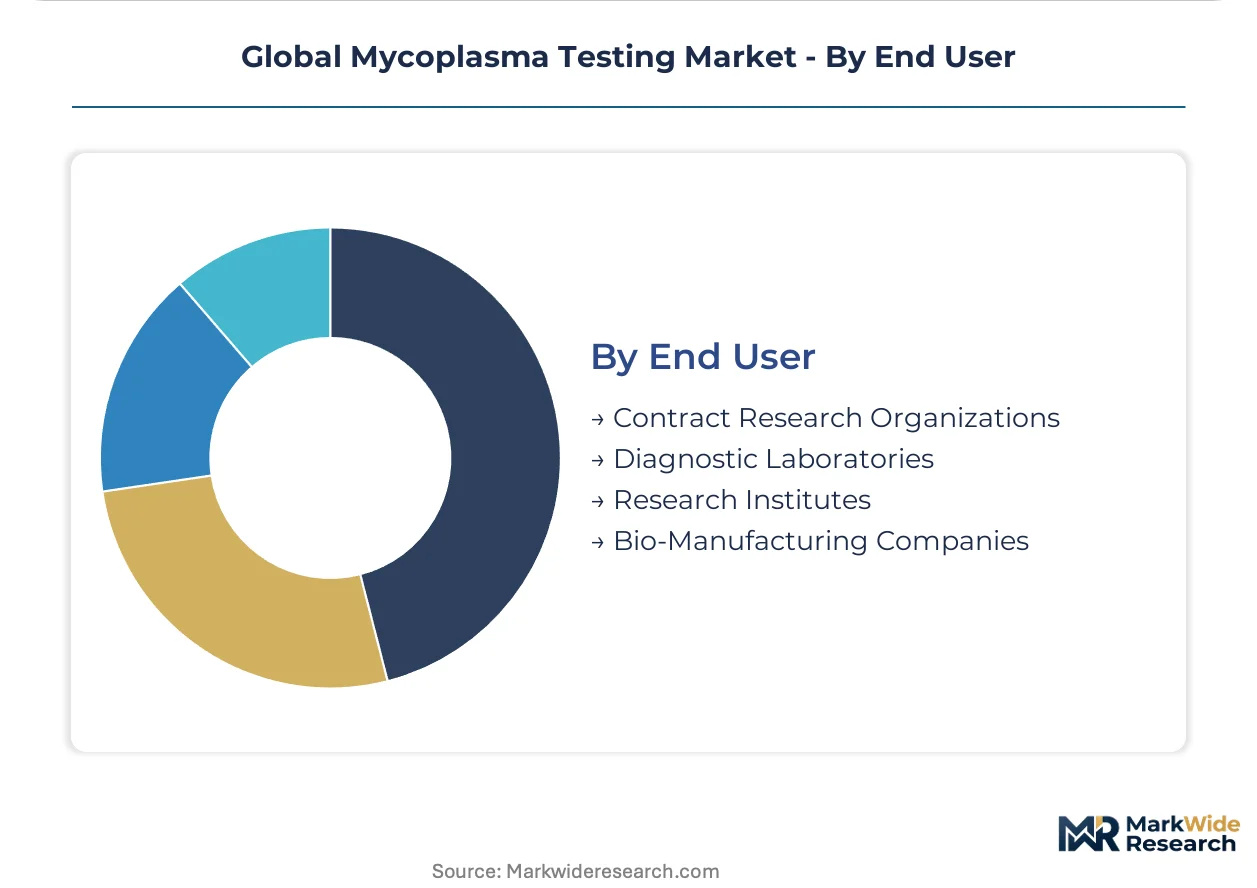
- Bio-Manufacturing Companies:Integrated biopharmaceutical sponsors invest in captive PCR platforms and specialized operators to protect proprietary cell lines. Internal quality control departments prioritize vendor ecosystems spanning sample prep through data integrity.
- Contract Research Organizations:Testing service providers aggregate demand across multiple sponsors, achieving instrument utilization rates that justify high-throughput automation. ISO 17025 accreditation unlocks multinational sponsor contracts requiring harmonized quality systems.
- Diagnostic Laboratories:Clinical reference labs extend into cell therapy release testing as manufacturing decentralizes toward patient proximity.
- Research Institutes:Academic budgets preserve manual culture methods despite regulatory pressure toward validated alternatives.
Bio-Manufacturing Companies deploy the most capital per site; Contract Research Organizations are scaling fastest as biopharmaceutical sponsors disaggregate validation services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research institutes in India and Brazil operate under severe capital constraints, stretching manual culture methods far beyond their economic replacement point, while biopharmaceutical manufacturers in Germany and the United States absorb qPCR platform costs without procurement friction.
United States
CAR-T cell therapy manufacturing in Greater Boston and the San Francisco Bay Area demands validated real-time PCR at every cell-banking stage. FDA biologics guidance mandates contamination control documentation that accelerates instrument replacement cycles. The National Institutes of Health campus in Bethesda sustains substantial contract testing volumes for academic cell-line repositories.
Germany
EMA GMP Annex 1 revisions force mid-sized gene therapy developers toward outsourced validation services. Heidelberg and Munich biotech clusters concentrate demand for automated detection platforms. The country's specialized polymerase suppliers anchor reagent supply chains serving European kit manufacturers.
China
NMPA tightening of cell therapy GMP enforcement drives replacement of legacy culture workflows in Shanghai and Suzhou biomanufacturing zones. The dual carbon goals pressure energy-intensive incubation facilities toward faster molecular methods. CDSCO-style regulatory convergence is anticipated as domestic sponsors pursue international registration.
India
CDSCO's intensified GMP enforcement and the PLI scheme for pharmaceuticals create procurement windows for instrument vendors establishing local service infrastructure. Hyderabad and Bengaluru vaccine manufacturers adopt ATP bioluminescence screening to reduce batch-failure risk. Academic budgets in Pune and Delhi preserve manual culture methods despite regulatory pressure.
Switzerland
Swissmedic's alignment with EMA standards positions Basel and Zurich as contract testing hubs for multinational sponsors. Precision filtration integration with cell-culture analytics supports high-value biologics manufacturing. The country's quality infrastructure attracts ISO 17025 accreditation investments from third-party testing laboratories.
Global Mycoplasma Testing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting vendor positioning across the capability spectrum. Integrated life science conglomerates with bioscience manufacturing infrastructure sustain pricing power in premium contract testing services. Specialized filtration and analytics providers anchor regional supply chains through precision instrumentation. Independent testing laboratories and reagent specialists occupy distinct tiers based on accreditation depth and geographic coverage. Competitive moves concentrate on platform consolidation spanning sample prep through data integrity, and service unbundling that separates instrument acquisition from validation support.
Among diversified life science conglomerates, Lonza Group and Thermo Fisher Scientific exemplify archetypes that integrate manufacturing infrastructure with quality control instrumentation. Sartorius AG represents the precision filtration and analytics specialist tier that anchors European supply chains. These three entities occupy positions that span the value chain from reagent supply through automated platform deployment, reflecting the market's bifurcation between high-throughput commercial manufacturing and distributed cell therapy production.
| Leading Market Players |
|---|
| Lonza Group |
| Sartorius AG |
| Thermo Fisher Scientific |
| SGS |
| Roche Diagnostics |
| Charles River Laboratories International |
| Eurofins Scientific |
| ATCC |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Fluorophore substitution under REACH restrictions is redrawing European reagent manufacturing geography while compressing margins for kit suppliers dependent on legacy chemistries. This input transition simultaneously elevates pricing power for polymerase producers in Germany and the United States who control validated alternative formulations.
Pricing Analysis
Annual service contracts and reagent subscriptions generate lifetime value exceeding instrument hardware margins by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels separates validated PCR platforms for GMP environments from research-grade kits and manual culture media. Cost compression in economy-tier consumables is intensifying because academic buyers face frozen budgets. Contract research organizations exhibit lowest price sensitivity due to sponsor pass-through arrangements, while Indian vaccine manufacturers negotiate aggressively on instrument packages.
Supply Chain Analysis
Extended lead times for thermostable polymerase formulations have normalized at six to eight months since regional inventory buffers depleted. Germany, the United States, and China concentrate master mix production capacity, with specialized probe chemistries drawing from Bavarian and Massachusetts chemical clusters. Single-source vulnerability concentrates in fluorophore precursors subject to ECHA substance evaluation. Distribution runs through authorized distributors with GMP documentation capabilities rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time PCR displacement of culture methods constitutes a high-growth disruption justified by FDA and EMA compliance windows compressing from weeks to hours. This technological inflection rewards early platform consolidation and punishes legacy method dependency.
For Market Incumbents: Consolidate validation service capabilities around automated platforms to capture disaggregated contracts from mid-sized gene therapy developers lacking internal quality infrastructure. Backward integration into polymerase production secures margin protection against reagent supply concentration. Prioritize ISO 17025 accreditation depth to disqualify non-accredited competitors from multinational sponsor procurement. For New Entrants and Emerging Players: ISO 17025 fast-track accreditation unlocks contract testing opportunities with biopharmaceutical sponsors requiring harmonized quality systems for cross-border submissions. Target India's CDSCO-enforced GMP upgrade cycle where local service infrastructure gaps persist. Deploy portable nucleic acid amplification devices for at-line bioreactor monitoring as a beachhead into distributed cell therapy manufacturing. For Investors and Strategic Acquirers: EMA GMP Annex 1 revisions reshape the acquisition landscape toward automated platform vendors with European service footprints. Five-to-ten year viability favors contract testing organizations achieving instrument utilization rates across multiple sponsors. Monitor pharmacopeial harmonization progress between USP, EP, and JP chapters as the signal indicating compliance overhead reduction or sustained fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Consolidation | Thermo Fisher extends Applied Biosystems workflows from sample prep through data integrity certification. |
| Service Unbundling | Validation support contracts separate from instrument acquisition, pressuring bundled pricing models. |
| ISO 17025 Accreditation | Third-party laboratories unlock multinational sponsor contracts requiring harmonized quality systems. |
| Point-of-Need Development | Portable amplification devices address gaps between central lab turnaround and real-time process control. |
| Alternative Chemistry Investment | Reagent manufacturers reformulate probe-based kits preempting REACH fluorophore restrictions. |
Research Methodology
Cross-validation between regulatory filing analysis and procurement pattern assessment anchors the qualitative findings. Primary interviews with biopharmaceutical quality control directors, CRO laboratory managers, regulatory affairs leads, and reagent procurement officers combined with secondary validation against FDA guidance documents, EMA GMP Annex 1 revisions, pharmacopeial chapter comparisons, and ISO 17025 accreditation databases. Bottom-up instrument placement tracking and top-down market sizing triangulate volume estimates.
Sensitivity analysis around polymerase supply disruption scenarios and regulatory harmonization timelines tests forecast robustness. Segmentation across product type, application, testing technology, and end user combines with regional regulatory cluster differentiation across the projection horizon. CAGRs derive from instrument replacement cycle analysis, cell therapy manufacturing capacity expansion, and contract testing volume aggregation. Industry-specific inputs include biologics manufacturing capital expenditure patterns and pharmacopeial acceptance criteria divergence.
The analysis sits within stated boundaries; outcomes outside sustained EMA and FDA enforcement intensity or accelerated pharmacopeial convergence would require recalibration. Forecasts reflect documented assumptions regarding cell therapy manufacturing scale-up and reagent supply stability. Pandemic preparedness infrastructure investment and geopolitical friction in polymerase trade represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Hbsag Testing Market
Testing Services
In-Vitro Diagnostic Services Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Drug Testing Equipment Market
Testing Services
United States Hospital Acquired Disease Testing Market
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
Drug Testing Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Vials Leak Testing Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Diagnostic Shipper Market
Testing Services
Tuberculosis Testing Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Global Legionella Testing Market
Testing Services
Global HPV Testing and Pap Test Market