
 Cabin Interior Composites Market | 2026-2036
Cabin Interior Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Cabin Interior Composites Market Analysis
The aerospace OEM supply channel is narrowing as Tier-1 integrators consolidate direct material sourcing. Collins Aerospace leverages long-term contracts with major airframers to sustain dominant positions in thermoplastic seating solutions. Hexcel Corporation anchors North American carbon fiber supply through captive prepreg operations serving cabin panel programs. Safran SA competes across European narrow-body retrofit campaigns with specialized thermoplastic processing expertise.
Cabin interior composites encompass engineered fiber-reinforced polymer systems designed for flame resistance, acoustic dampening, and weight reduction in commercial aircraft passenger compartments, typically formulated with phenolic or thermoplastic matrices meeting strict smoke-toxicity specifications. These materials replace traditional aluminum and thermoset components to achieve fuel efficiency targets mandated by airline operators. Carbon fiber paneling leads application value due to mature qualification pathways and established repair protocols, while thermoplastic segments represent the fastest-growing material category as out-of-autoclave processing reduces cycle times. Seating applications concentrate margin pools where FAA-certified fire-blocking layers command premium positioning over standard trim and flooring segments.
FAA Part 25.853 flammability standards and EASA CS-25 certification requirements shape material selection by mandating 12-second vertical burn test compliance and heat release thresholds that exclude conventional thermoset alternatives. REACH chemical restrictions in Europe further filter resin formulations, limiting halogenated flame retardants in favor of phosphorus-based systems. OEM procurement teams must monitor evolving MEE environmental standards in China and dual carbon policy timelines that will condition access to the country's expanding narrow-body final assembly lines.
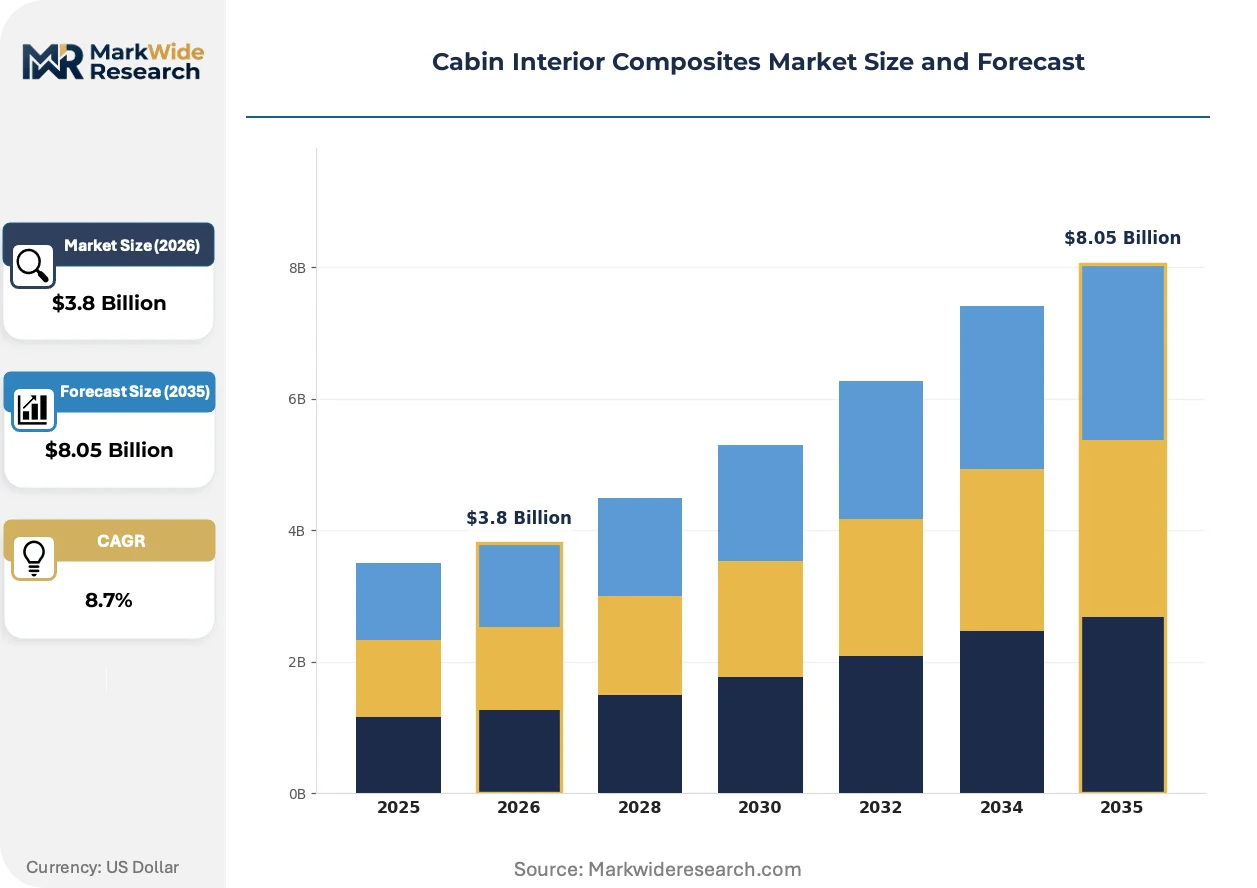
Market Dynamics
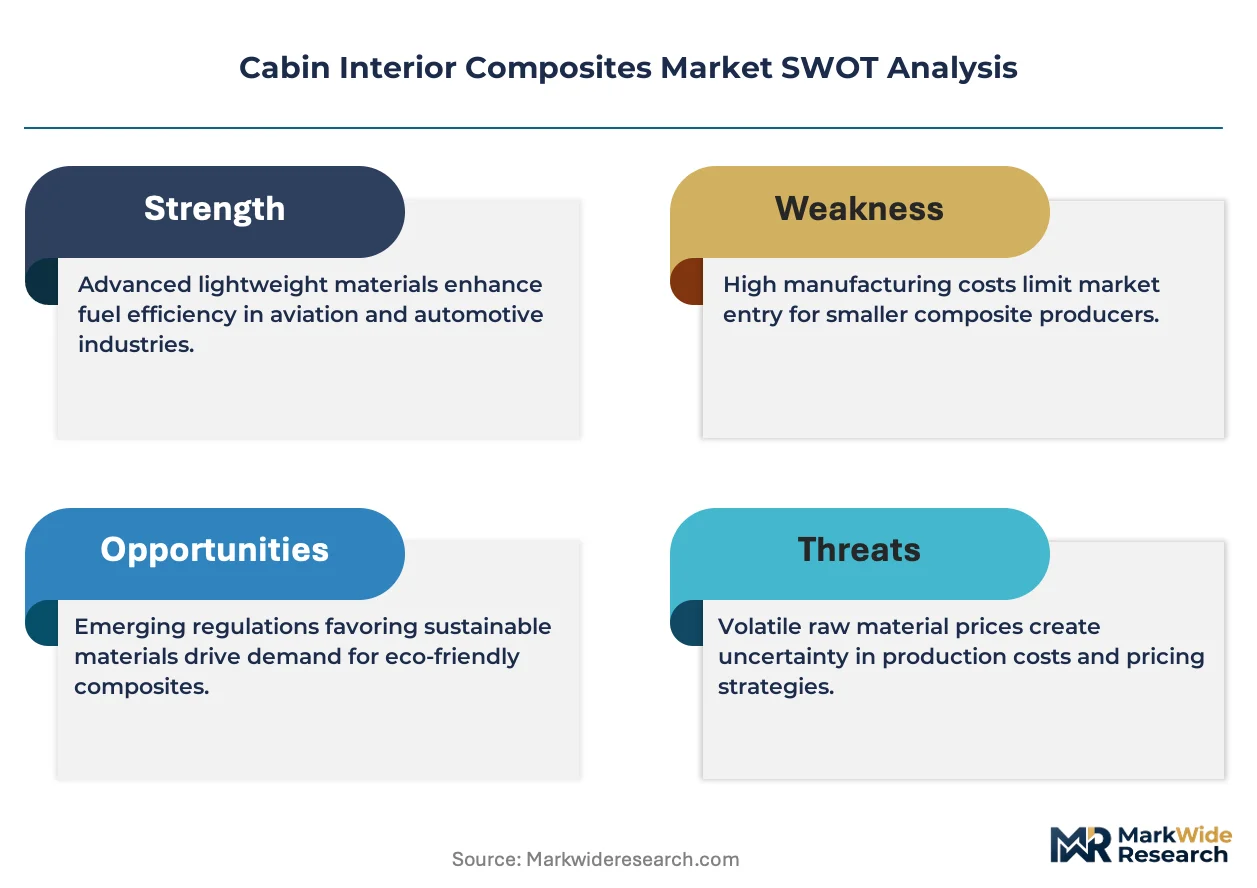
Narrow-body aircraft retrofit mandates across North America and Europe are compressing qualification timelines for thermoplastic cabin panels, forcing Tier-1 integrators to consolidate direct material sourcing around certified prepreg suppliers.
Growth Catalysts
- FAA Part 25.853 flame-retardant mandates:Airworthiness directives tighten vertical burn test compliance, excluding conventional thermoset alternatives from new cabin programs.
- Out-of-autoclave thermoplastic processing:Reduced cycle times enable faster panel fabrication, accelerating adoption in narrow-body seating structures.
- Germany:Airbus supply clusters and Tier-1 interiors engineering centers anchor composite fabrication capacity for European retrofit demand.
Market Restraints
- Phenolic resin input volatility:Raw material cost fluctuations constrain margin stability for flame-retardant matrix suppliers.
- REACH chemical restrictions:ECHA limitations on halogenated flame retardants force costly reformulation toward phosphorus-based systems.
- Carbon fiber panel repair protocols:Established qualification pathways create switching costs that lock operators into incumbent supply relationships.
Strategic Opportunities
- China narrow-body final assembly expansion:MEE environmental standards and dual carbon policy timelines condition access for certified prepreg suppliers.
- Acoustic dampening composites:Emerging application in next-generation cabin architectures separates premium interior offerings.
- Long-term direct contracting:Airlines bypass traditional distribution tiers to secure volume commitments on thermoplastic seating solutions.
Industry Challenges
- Certified fire-blocking layer qualification:FAA smoke-toxicity specifications extend development timelines for seating applications.
- Thermoplastic welding technician scarcity:Specialized joining expertise lags behind out-of-autoclave capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cabin Interior Composites Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbon Fiber, Glass Fiber, Natural Fiber, Thermoplastic End User: Aerospace Manufacturers, Automotive OEMs, Rail Operators, Marine Suppliers Application: Paneling, Seating, Trim, Flooring Manufacturing Process: Injection Molding, Compression Molding, Hand Lay-up, Filament Winding |
| Companies Covered | Diehl Stiftung & Co. KG, Collins Aerospace, RTX Corporation, Aim Altitude, Hexcel Corporation, Safran SA, JAMCO Corporation, The Gill Corporation, FACC AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cabin Interior Composites Market Emerging Trajectories
Thermoplastic matrix systems are compressing traditional manufacturing economics while regulatory chemistry restrictions reshape formulation strategies. These shifts recalibrate competitive advantage toward processing expertise rather than raw material access.
Continuous fiber-reinforced thermoplastic (CFRTP) panels combine melt-processable PEEK and PPS matrices with unidirectional carbon fiber layups. Major narrow-body retrofit programs in Germany and the United States adopt these systems for sidewall and ceiling applications. Conventional phenolic thermoset laminates is rendering obsolete in new aircraft programs as OEMs prioritize repairability and end-of-life recyclability.
EASA CS-25 certification requirements now mandate heat release rate thresholds that thermoplastic systems satisfy more readily than legacy alternatives. European OEM procurement teams filter supplier pools based on REACH-compliant phosphorus-based flame retardant formulations. Seating integrators face compressed requalification schedules as EASA tightens interpretation of 12-second vertical burn test protocols.
Airline technical procurement teams consolidate vendor relationships around single-source certified prepreg agreements. Traditional Tier-2 distributors lose position as direct contracts between airframers and material suppliers displace multi-tier purchasing. This concentration is most visible in North American narrow-body retrofit campaigns where maintenance, repair, and overhaul facilities now source panels through OEM-approved supplier lists rather than independent channels.
Cabin Interior Composites Market Segmentation
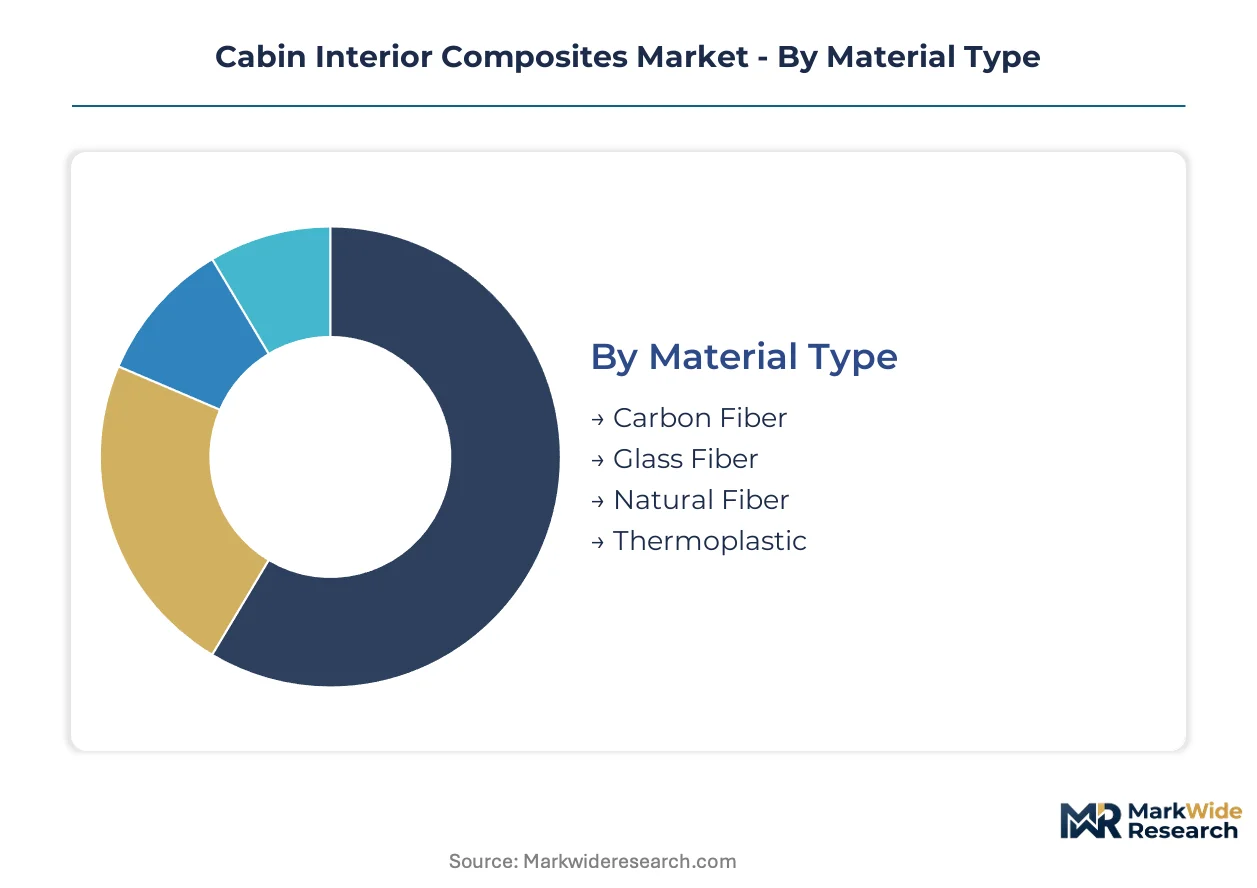
Cabin interior composites serve distinct performance tiers across aircraft architectures, with material selection and manufacturing method directly conditioning flame-retardant certification pathways and repair economics. Segmentation reveals where procurement consolidation concentrates margin pools and which processing technologies compress fabrication timelines for retrofit programs.
Material Type:
Material selection spans structural load-bearing requirements through aesthetic surface finishes, with certification complexity varying sharply by fiber chemistry and matrix formulation.
- Carbon Fiber:High-modulus PAN-based and pitch-based reinforcements in phenolic or thermoplastic matrices deliver the stiffness-to-weight ratios required for overhead bin structures and galley monuments. Demand concentrates in Germany where Airbus supply clusters and Tier-1 interiors engineering centers anchor qualification pathways for narrow-body retrofit panels.
- Thermoplastic:Melt-processable PEEK and PPS matrices with unidirectional carbon fiber layups enable out-of-autoclave fabrication cycles. North American narrow-body retrofit programs adopt these systems most aggressively as FAA Part 25.853 flame-retardant mandates compress requalification timelines.
- Glass Fiber:E-glass and S-glass reinforcements in cost-sensitive secondary structures where electromagnetic transparency or dielectric properties matter.
- Natural Fiber:Flax and hemp fiber composites emerging in non-structural trim applications with reduced end-of-life environmental footprint.
Established volume favors carbon fiber; emerging adoption favors thermoplastic.
End User:
Customer procurement sophistication varies by sector certification burden and fleet replacement cycles.
- Aerospace Manufacturers:Airframers and Tier-1 integrators sourcing FAA-certified and EASA CS-25-compliant panels for production line-fit and retrofit campaigns. German engineering centers and U.S. maintenance facilities drive specification authority.
- Rail Operators:EN 45545-2 fire safety standards govern composite selection for high-speed train interiors, with lighter weight targets than legacy metal constructions.
- Automotive OEMs:Premium electric vehicle programs specify carbon fiber trim for battery enclosure thermal management and cabin aesthetic differentiation.
- Marine Suppliers:IMO fire safety codes and moisture resistance requirements filter material selection for yacht and commercial vessel interiors.
Procurement scale concentrates with aerospace manufacturers; regulatory complexity steers specification authority toward rail and marine certification specialists.
Application:
Functional location within the passenger compartment determines fire-blocking layer requirements and acoustic performance targets.
- Seating:Structural frames and fire-blocking layers commanding premium positioning due to FAA smoke-toxicity specifications and 16g dynamic test requirements. Thermoplastic welding expertise lags behind demand for out-of-autoclave seating structures.
- Paneling:Sidewall, ceiling, and monument panels where carbon fiber laminates dominate due to mature repair protocols and established qualification pathways.
- Trim:Non-structural decorative surfaces with lower certification burden and greater material substitution flexibility.
- Flooring:Honeycomb-core sandwich panels meeting strict stiffness and wear resistance specifications.
Margin pools concentrate in seating; paneling captures volume scale.
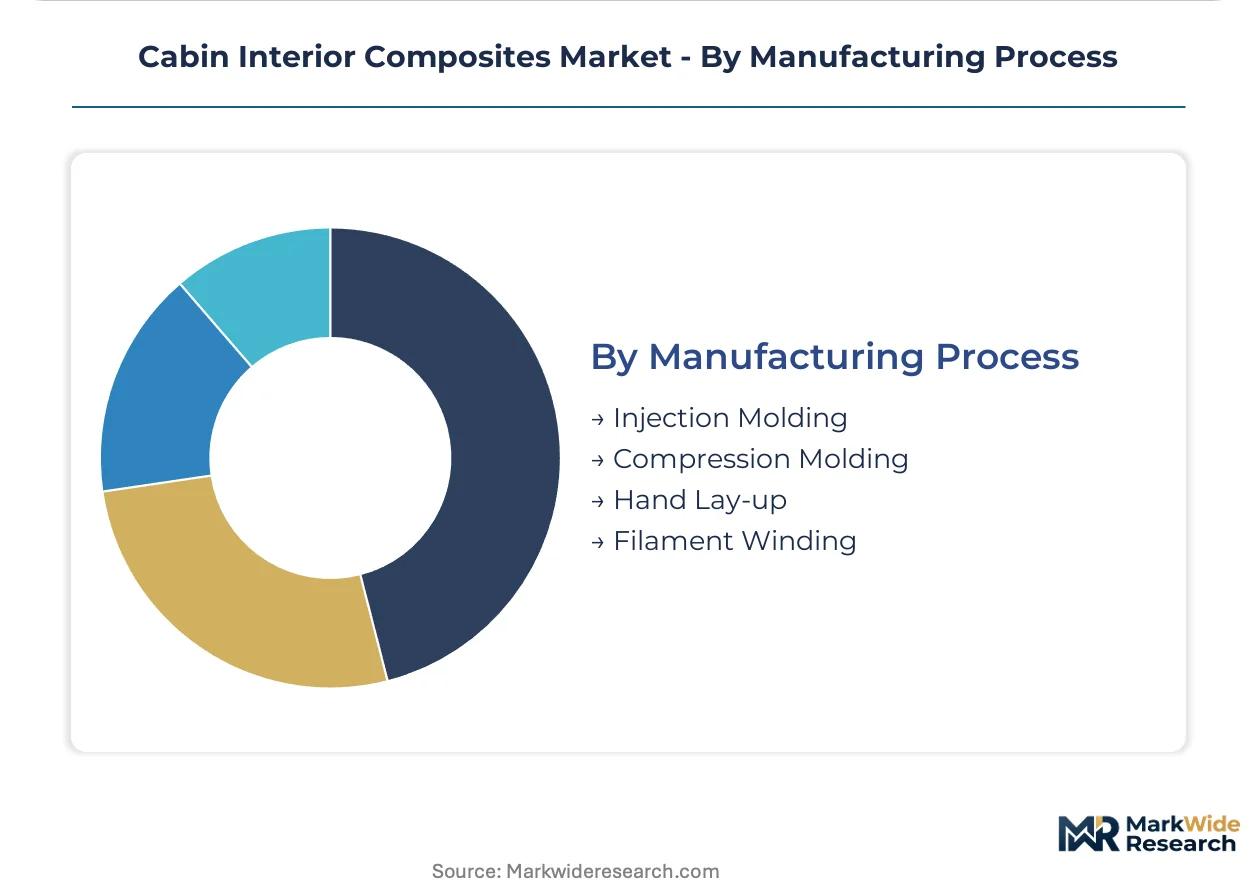
Manufacturing Process:
Process selection trades capital intensity against cycle time compression and geometric complexity.
- Compression Molding:Matched-die forming of thermoplastic prepregs enabling rapid cycle times for high-volume narrow-body seating components. German Tier-1 integrators anchor European capacity.
- Injection Molding:Short-fiber thermoplastic compounds for complex geometric trim pieces with integrated fastening features.
- Hand Lay-up:Labor-intensive wet lay-up of phenolic prepregs for low-volume galley and monument structures.
- Filament Winding:Automated fiber placement for cylindrical or axisymmetric structural elements in lavatory modules.
Compression molding gains share fastest; hand lay-up retreats to legacy program maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's composite logistics corridor, channeling carbon fiber prepregs and thermoplastic resins to Airbus assembly lines and Tier-1 interiors engineering centers across Northern Europe.
United States
FAA Part 25.853 flame-retardant mandates compress requalification timelines for narrow-body retrofit programs. The Federal Aviation Administration tightens vertical burn test protocols, excluding conventional thermoset alternatives. Dallas-Fort Worth maintenance facilities and Seattle-area Boeing supply clusters drive procurement consolidation around certified prepreg suppliers.
Germany
REACH chemical restrictions force reformulation toward phosphorus-based flame retardants in cabin panel matrices. The European Chemicals Agency limits halogenated compounds, raising compliance costs for legacy suppliers. Hamburg and Bremen engineering centers anchor Airbus supply clusters for thermoplastic seating structures and sidewall panel fabrication.
China
MEE environmental standards and dual carbon policy timelines condition market access for foreign prepreg suppliers. The Ministry of Ecology and Environment tightens emissions controls on composite manufacturing. Tianjin and Shanghai final assembly lines for narrow-body programs drive specification authority toward certified domestic and joint-venture fabricators.
France
EASA CS-25 certification requirements mandate heat release rate thresholds favoring thermoplastic systems. The European Union Aviation Safety Agency tightens interpretation of smoke-toxicity specifications for seating applications. Toulouse aerospace clusters concentrate fire-blocking layer qualification expertise and Tier-1 integrator engineering capacity.
United Kingdom
Post-Brexit regulatory divergence creates parallel certification pathways for cabin materials. The UK Civil Aviation Authority maintains flame-retardant standards aligned with EASA baselines while developing independent approval processes. Southwest England composites manufacturing zones supply narrow-body retrofit panels to European and transatlantic maintenance networks.
Cabin Interior Composites Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply hierarchy. Tier-1 interiors integrators consolidate direct material sourcing, displacing traditional distribution channels. Three archetypes dominate: aerospace conglomerates with captive composite operations, independent prepreg specialists with certified fire-blocking expertise, and regional fabricators serving maintenance-repair-overhaul facilities. Consolidation accelerates through long-term direct contracting and strategic capacity expansion near final assembly lines.
Among European-based platform integrators, Diehl Stiftung & Co. KG and Safran SA exemplify the conglomerate archetype with integrated interiors engineering. Collins Aerospace anchors the North American system-tier position. Hexcel Corporation represents the independent prepreg specialist model with captive carbon fiber supply operations.
| Leading Market Players |
|---|
| Diehl Stiftung & Co. KG |
| Collins Aerospace |
| RTX Corporation |
| Aim Altitude |
| Hexcel Corporation |
| Safran SA |
| JAMCO Corporation |
| The Gill Corporation |
| FACC AG |
| Others |
Supply Flow & Price Mechanics
German carbon fiber prepreg concentration around Hamburg and Bremen engineering clusters channels pricing power toward certified fire-blocking layer suppliers serving narrow-body retrofit programs. Tier-1 integrators capture margin pools through long-term direct contracts that compress distributor intermediation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified fire-blocking seating solutions from uncertified trim and generic panel alternatives. Price differentiation rests on certification grade and volume scale, with airlines commanding steepest discounts on multi-year thermoplastic seating commitments. Cost compression in standard-grade phenolic panels is intensifying because REACH-compliant phosphorus-based reformulations raise input costs. Maintenance-repair-overhaul facilities exhibit highest price sensitivity; Airbus and Boeing procurement teams show lowest.
Supply Chain Analysis
Carbon fiber feedstock draws from US, Japanese, and German precursor manufacturers, with PAN-based tow supply tightening around Hexcel Corporation's captive operations and Toray Industries' global network. Phenolic resin and PEEK thermoplastic pellets represent critical input dependencies alongside certified fire-blocking fabric layers. Single-source vulnerability concentrates in qualified prepreg suppliers holding FAA Part 25.853 and EASA CS-25 certification records. Distribution runs through OEM-approved supplier lists rather than independent Tier-2 channels, reflecting procurement consolidation in North American and European narrow-body retrofit campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from continuous fiber-reinforced thermoplastic systems displacing legacy phenolic thermosets in new aircraft programs. Defense requires preemptive positioning against out-of-autoclave processing expertise gaps.
For Market Incumbents: Pre-empt thermoplastic welding technician scarcity by anchoring training partnerships with German engineering centers and US maintenance facilities. Lock in backward integration into PEEK and PPS resin supply through long-term offtake agreements with European chemical producers. Certification investment in EASA CS-25 heat release rate compliance represents the critical defensive lever against emerging CFRTP specialists.
For New Entrants and Emerging Players: Acoustic dampening composites for next-generation cabin architectures represent the most penetrable entry point, with premium positioning available to suppliers demonstrating flame-retardant and sound-attenuation dual certification. China's MEE environmental standards and dual carbon policy timelines create white-space for domestic-joint-venture fabricators serving Tianjin and Shanghai final assembly lines. Go-to-market execution should prioritize direct airline technical procurement relationships bypassing traditional OEM distribution tiers.
For Investors and Strategic Acquirers: Capital is best deployed toward independent prepreg specialists with captive carbon fiber operations and certified fire-blocking expertise, positioned across the 5-10 year narrow-body retrofit cycle. Target acquisition archetypes include mid-cap European fabricators with EASA qualification pathways and underutilized out-of-autoclave capacity. The signal to watch is EASA tightening interpretation of 12-second vertical burn test protocols, which would accelerate thermoplastic substitution and revalue qualified supplier assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Out-of-Autoclave Capacity Expansion | Compression molding lines near Airbus Hamburg and Boeing Seattle reduce cycle times for narrow-body seating structures. |
| Phosphorus-Based Flame Retardant Reformulation | REACH-compliant resin systems unlock European retrofit program access while excluding halogenated competitors. |
| Direct Airline Contracting Bypass | Long-term volume commitments with Delta and Lufthansa Technical Procurement displace traditional distribution tiers. |
| Thermoplastic Welding Technician Training | Specialized joining expertise partnerships with German Tier-1 engineering centers close capacity-constraint gaps. |
| China Joint-Venture Localization | Domestic MEE-certified fabrication capacity near Tianjin final assembly lines secures COMAC program access. |
Methodological Framework
Cross-validation between primary interviews with Tier-1 interiors procurement managers, FAA certification engineers, and airline technical directors anchors the qualitative findings. Secondary validation draws from EASA CS-25 certification databases, FAA airworthiness directive filings, and customs records tracking carbon fiber prepreg imports into Germany and the United States. Bottom-up segment sizing triangulates against top-down aerospace OEM procurement spend estimates across material type, application, and manufacturing process dimensions.
Calibration against historical narrow-body retrofit program timelines and thermoplastic adoption curves shapes the projection framework. Segmentation modeling spans material chemistry, end-user certification burden, application fire-blocking requirements, and regional regulatory clusters. CAGRs derive from fitted adoption curves reflecting out-of-autoclave processing penetration and REACH chemical restriction compliance costs. Industry-specific inputs include EASA heat release rate threshold evolution and MEE environmental standard implementation pacing.
Stress conditions across phenolic resin input volatility, carbon fiber precursor supply constraints, and EASA certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding thermoplastic welding technician pipeline expansion and airline fleet replacement cycles. Cross-checking against FAA Part 25.853 amendment histories and Airbus procurement disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Cabin Interiors Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Galley Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Floor Panels Market