
 Aerospace Interior Adhesive Market | 2026-2036
Aerospace Interior Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Interior Adhesive Market Intelligence
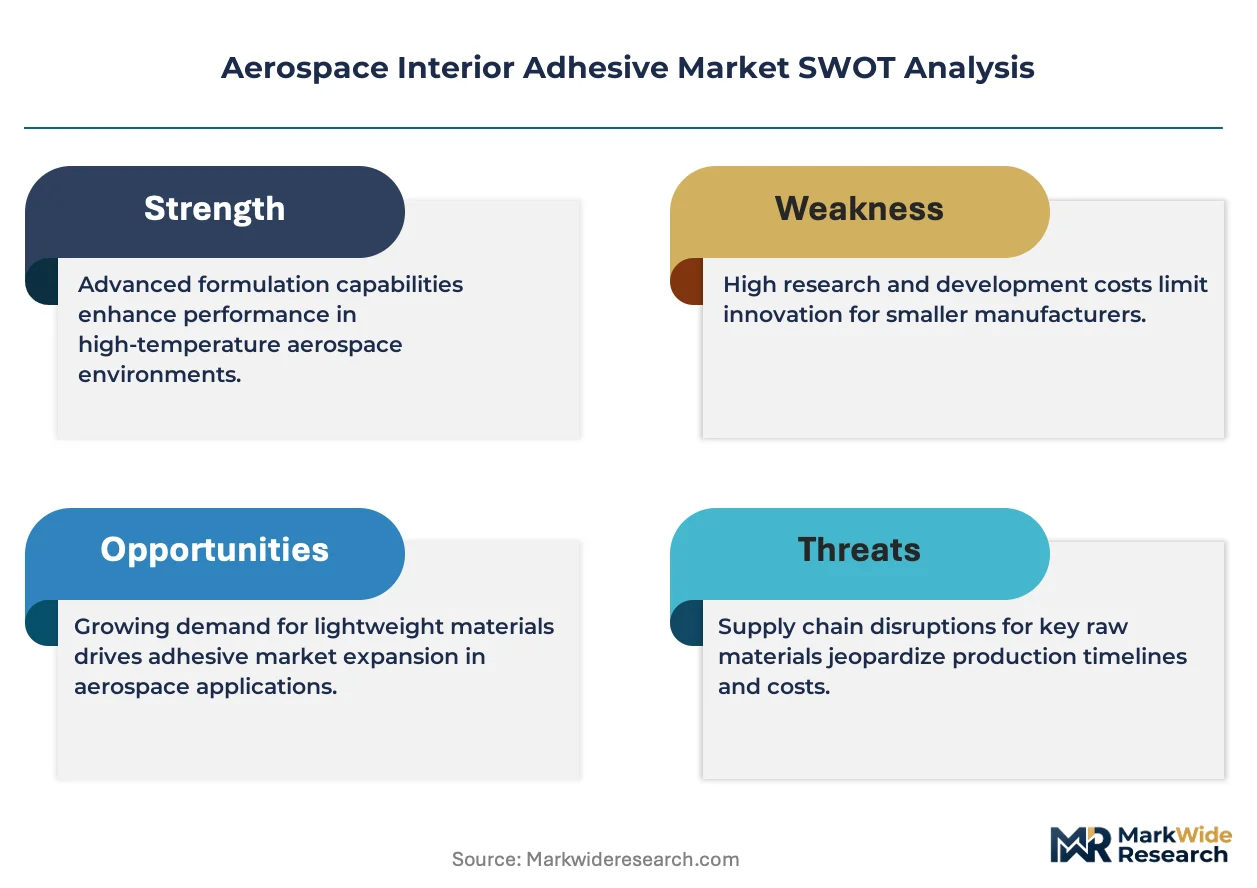
The replacement of traditional mechanical fasteners with high-performance adhesives is pivoting product economics toward lightweighting and accelerated assembly times. This shift favors suppliers with robust testing and certification capabilities. Henkel AG & Co. KGaA leverages its broad chemical portfolio to serve diverse aircraft platforms. Hexcel Corporation specializes in structural adhesives that complement its core composite materials business, while 3M differentiates through its extensive range of film and spray-form adhesives.
Aerospace interior adhesives are specialized bonding agents formulated for non-structural and semi-structural applications within an aircraft cabin. These formulations, often based on epoxy or polyurethane chemistry, must exhibit low outgassing and meet stringent flame, smoke, and toxicity (FST) standards. Epoxy-based products lead the market due to superior strength and thermal resistance. Application demand from OEMs for bonding cabin walls and overhead bins represents a significant portion of the market, with MROs driving aftermarket volume.
Product qualification is governed by stringent standards from bodies like the US Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency. Chemical composition is also subject to regulations such as the EU's REACH framework, which impacts material selection and supply chains. Additionally, compliance with specific OEM material specifications is mandatory for market access. Future material choices will be determined by evolving FST requirements and the push for sustainable adhesive formulations.
Market Dynamics
The fundamental dynamic shaping the aerospace interior adhesive market is the substitution of chemical bonding for mechanical fasteners. This materials science shift is driven by OEM and airline demands for lighter aircraft cabins, which directly translates to fuel savings and reduced emissions over an aircraft's operational life.
Growth Catalysts
- Fleet Modernization:Airline fleet expansion and accelerated cabin refurbishment cycles, particularly within the commercial aviation sector in China and the United States, create consistent demand for interior adhesives for panels, bins, and seating.
- Advanced Formulations:The development of fast-curing and flame-retardant epoxy and polyurethane adhesives enables faster assembly at OEM facilities and quicker turnaround times for MROs, improving operational economics.
- Lightweighting Mandates:Regulatory pressure to improve aircraft fuel efficiency and lower carbon emissions encourages the adoption of lightweight composite panels and components, which rely on adhesives for assembly instead of heavier metal fasteners.
Market Restraints
- Raw Material Volatility:The price and availability of specialized chemical precursors used in high-performance epoxy and polyurethane formulations are subject to fluctuations in the broader petrochemicals market, impacting manufacturer cost structures.
- Regulatory Compliance Burden:Stringent regulations like the EU's REACH framework restrict the use of certain chemicals, forcing costly and time-consuming reformulation and requalification of established adhesive products.
- Stringent Qualification Cycles:The extensive and expensive testing required to meet FAA and EASA flame, smoke, and toxicity standards, in addition to specific OEM material specifications, creates a high barrier to entry for new products.
Strategic Opportunities
- Sustainable Adhesives:Developing bio-based or recyclable adhesive formulations presents a significant opportunity, aligning with airline and OEM corporate sustainability goals and addressing future regulatory pressures on material lifecycle management.
- Smart Cabin Integration:Adhesives formulated for bonding flexible electronics, sensors, and embedded lighting into cabin panels and monuments represent a new application frontier as aircraft interiors become more technologically advanced.
- MRO Market in Emerging Hubs:Expanding aftermarket sales and service support for MRO providers in growing aviation hubs, such as those in the United Arab Emirates and Singapore, offers a path to capture recurring revenue streams.
Industry Challenges
- Certification Timelines:The protracted timeline for qualifying new adhesive systems with airframers like Airbus and Boeing can delay the market entry of innovative materials, slowing the pace of technology adoption.
- Application Skill Gap:Ensuring consistent and correct surface preparation and application by technicians at OEM and MRO facilities is critical for bond performance and requires specialized training beyond traditional mechanical skills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Interior Adhesive Market |
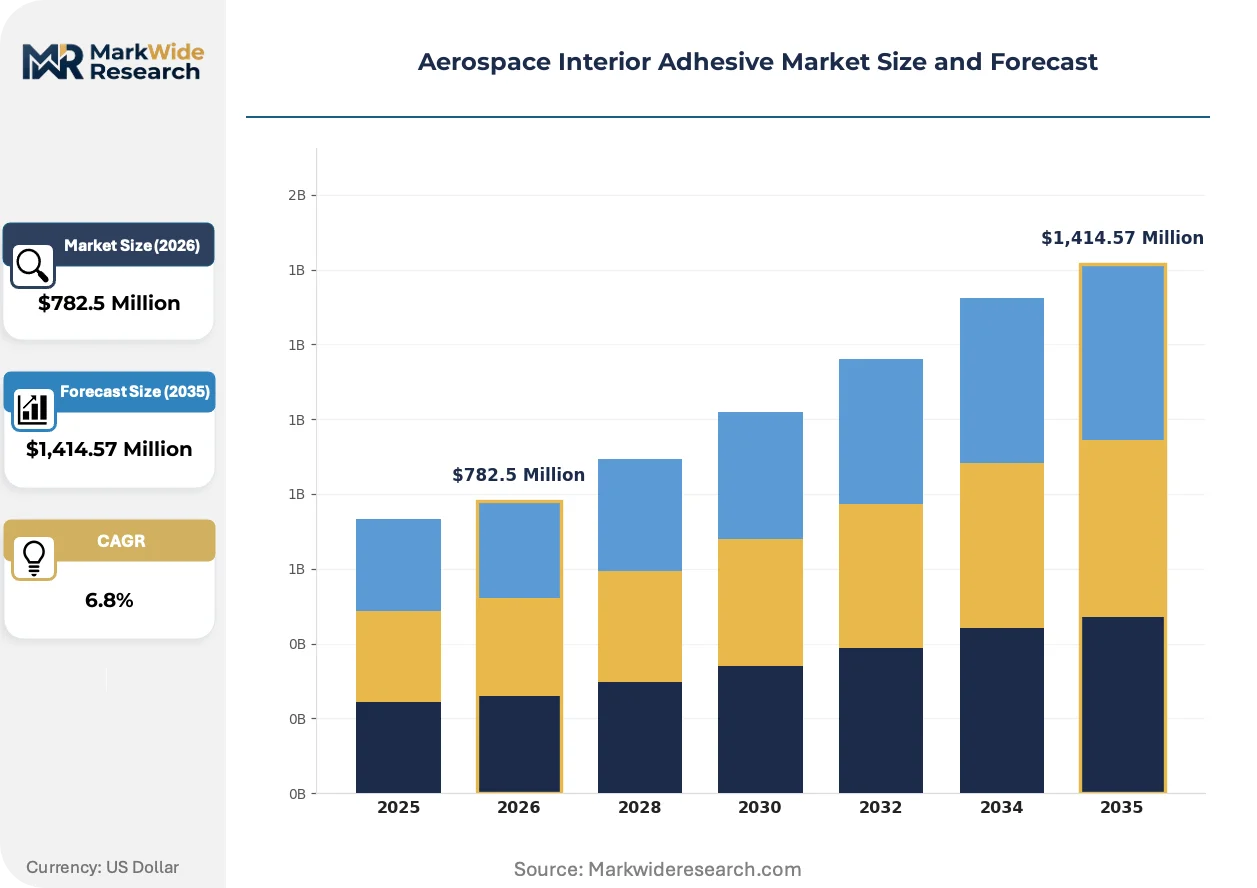
| Market Size in 2026 | $782.5 Million |
| Market Size in 2035 | $1,414.57 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Seating, Cabin Walls, Overhead Bins, Lavatories Product Type: Epoxy, Polyurethane, Cyanoacrylate, Silicone End User: Commercial Aviation, Military Aviation, MRO, OEMs Form: Liquid, Paste, Film, Spray |
| Companies Covered | Arkema, Avery Dennison Corporation, 3M, DELO Industrie Klebstoffe GmbH & Co. KGaA, Hexcel Corporation, Henkel AG & Co. KGaA, Huntsman International LLC, H.B. Fuller Company, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Interior Adhesive Market Strategic Shifts & Innovations
Innovation in the aerospace interior adhesive market is guided by the dual objectives of enhancing cabin safety through superior flame retardancy and reducing environmental impact via sustainable chemistry. These forces are compelling suppliers to move beyond incremental performance gains and invest in next-generation material science platforms.
Multi-functional adhesives are gaining traction for their ability to provide structural bonding while also delivering secondary properties such as acoustic damping or thermal insulation. Major aircraft OEMs and their cabin interior suppliers are adopting these materials to reduce the total number of components and simplify assembly processes. The development of these integrated material solutions is converging with the wider aerospace objective of achieving significant part consolidation and system-level weight reduction.
The European Union's REACH regulation is a significant force driving product reformulation across the chemical industry. Its primary industrial consequence is the restriction of certain substances, which compels adhesive manufacturers to find and qualify compliant alternatives for their formulations. Epoxy and polyurethane producers that supply the European OEM and MRO markets are the most affected segment, accelerating their research into greener and more sustainable chemical building blocks.
A notable shift is occurring in how MROs and airlines specify cabin materials, moving beyond initial unit price to a total cost of ownership model. This calculation incorporates factors like cure speed, which impacts aircraft downtime, and long-term durability, which affects refurbishment cycles. This trend is most prominent within the high-volume commercial aircraft cabin refurbishment sector in North America and Europe, favoring suppliers with certified, fast-curing systems.
Aerospace Interior Adhesive Market Segmentation
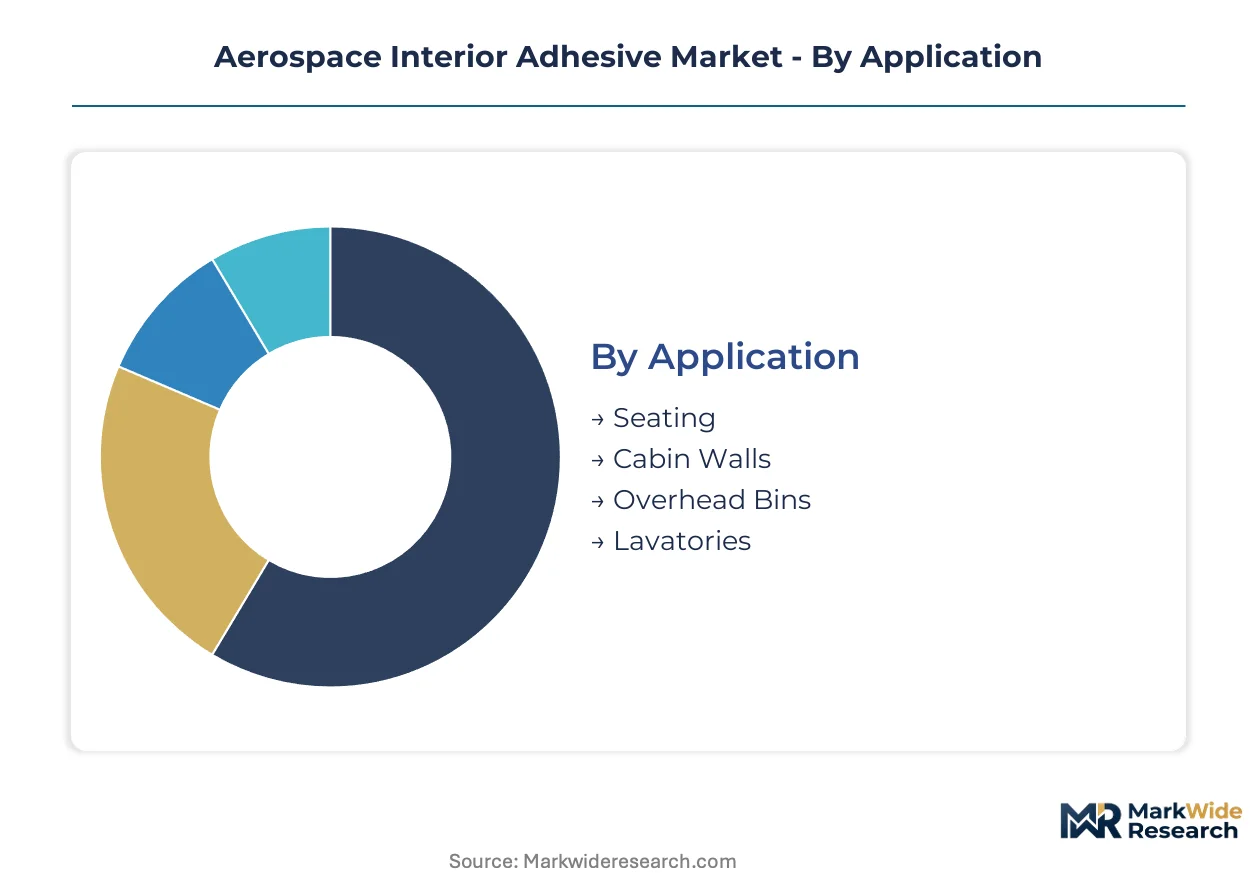
Understanding the distinct segments within the aerospace interior adhesive market provides clarity on specialized product requirements and demand drivers. Each category reflects unique material properties, application methodologies, or end-user needs that shape market competition.
Product Type:
The chemical composition and performance characteristics define adhesive product types within aircraft interiors.
- Epoxy:Epoxy formulations deliver superior bond strength and thermal resistance, making them suitable for demanding semi-structural applications. Demand for epoxy products concentrates in OEM cabin assembly for robust panel and component bonding.
- Polyurethane:Polyurethane adhesives offer flexibility and good adhesion to diverse substrates, often preferred for sealing and vibration damping applications. The commercial aviation MRO sector drives significant polyurethane demand for cabin refurbishment projects requiring durable, flexible bonds.
- Cyanoacrylate:Cyanoacrylate adhesives provide rapid curing for quick fixes and small component bonding, valued for their fast turnaround times in MRO operations.
- Silicone:Silicone-based adhesives offer excellent temperature resistance and flexibility, finding use in specialized sealing applications within lavatories and galleys.
Mature deployment sits with Epoxy formulations. Newer deployment is concentrated in Polyurethane adhesives.
Application:
Application areas delineate functional requirements and performance demands for interior adhesives.
- Cabin Walls:Adhesives for cabin walls support large composite panels, requiring formulations with high strength and FST compliance. OEM production lines in the United States and China generate substantial demand for these specialized bonding agents.
- Seating:Adhesives bond seat components, upholstery, and structural elements, prioritizing flexibility and rapid curing for assembly efficiency. Commercial aviation refurbishment cycles in Europe consistently drive demand for seating adhesive volumes.
- Overhead Bins:Overhead bins utilize adhesives for lightweight panel assembly and structural reinforcement, contributing to overall cabin weight reduction.
- Lavatories:Lavatory modules demand adhesives resistant to moisture and cleaning chemicals, ensuring long-term durability and hygiene standards.
Cabin walls represent the fastest-growing trajectory for adhesive use. Seating applications maintain consistent demand.
End User:
End-user segments define procurement patterns and certification pathways for interior adhesive products.
- Commercial Aviation:Commercial aviation encompasses passenger aircraft, driving high-volume demand for adhesives in new builds and extensive cabin refurbishments. Fleet expansion and modernization initiatives in China fuel significant adhesive consumption.
- OEMs:Original Equipment Manufacturers integrate adhesives into aircraft during initial production, requiring strict adherence to material specifications and rapid cure times. Airbus and Boeing facilities in France and the United States are primary demand centers.
- Military Aviation:Military aviation applications demand adhesives with extreme durability and specialized performance characteristics for mission-critical interiors.
- MRO:Maintenance, Repair, and Overhaul providers utilize adhesives for cabin repairs and upgrades, prioritizing quick-drying and certified replacement materials.
Commercial aviation drives the largest volume of adhesive procurement. Military aviation maintains stable, specialized demand.
Form:
The physical presentation of adhesives dictates application methods and suitability for various manufacturing processes.
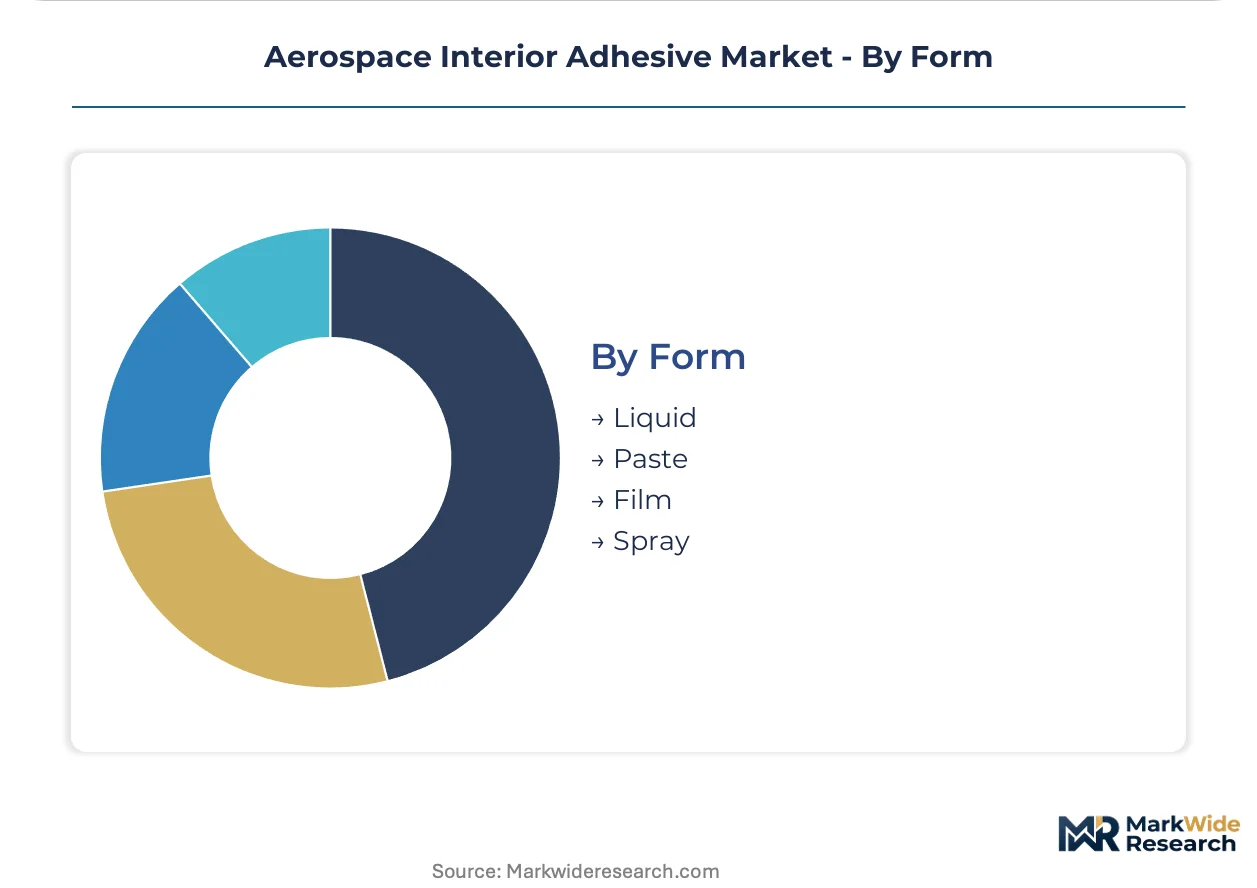
- Liquid:Liquid adhesives offer versatility for various bonding tasks, allowing for precise dispensing and good substrate wetting. Commercial aviation MRO operations in Europe frequently use liquid formulations for interior repairs.
- Film:Film adhesives provide consistent bond line thickness and clean application, ideal for automated processes and structural panel bonding. OEMs increasingly adopt film formats for high-volume cabin component assembly.
- Paste:Paste adhesives offer gap-filling capabilities and controlled application, suitable for irregular surfaces and localized repairs.
- Spray:Spray-applied adhesives facilitate fast and even coverage over large areas, commonly used for bonding insulation and fabrics within aircraft interiors.
Liquid and paste forms are widely adopted across the industry. Film adhesives are gaining share for precision applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for aerospace interior adhesives is pronounced in key aviation manufacturing and MRO hubs. These regions drive significant consumption due to robust OEM production and extensive aftermarket activities. The market's growth trajectory is closely tied to fleet expansion and cabin refurbishment cycles in these strategic locations.
United States
The United States experiences strong demand for aerospace interior adhesives from its extensive commercial aviation sector. FAA regulations mandate rigorous flame, smoke, and toxicity standards for all cabin materials. Major aerospace clusters in Seattle and Wichita drive significant OEM adhesive procurement for new aircraft assembly.
France
France represents a core demand center, largely driven by Airbus's significant OEM production capabilities. EASA certification and the EU's REACH framework heavily influence material selection for interior adhesives. The Toulouse aerospace cluster, centered around Airbus, consumes substantial volumes for cabin wall and overhead bin assembly.
China
China's aerospace interior adhesive market is expanding rapidly, fueled by its aggressive commercial aviation fleet expansion programs. Chinese civil aviation authorities (CAAC) enforce strict safety standards for aircraft interior components. Aerospace manufacturing hubs in Xi'an and Shanghai are increasingly adopting advanced adhesive formulations for local aircraft production.
United Arab Emirates
The United Arab Emirates is emerging as a significant MRO hub, creating consistent demand for aftermarket interior adhesives. The General Civil Aviation Authority (GCAA) oversees all aviation safety and material compliance within the country. Major MRO facilities in Dubai and Abu Dhabi prioritize fast-curing adhesives for efficient cabin repairs and upgrades.
Singapore
Singapore serves as a crucial aerospace MRO and manufacturing center within Southeast Asia, generating steady adhesive demand. The Civil Aviation Authority of Singapore (CAAS) ensures compliance with international and local aviation safety regulations. Seletar Aerospace Park hosts numerous MRO providers and component manufacturers requiring specialized interior bonding solutions.
Aerospace Interior Adhesive Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the aerospace interior adhesive market. The market exhibits a tiered structure, with large chemical conglomerates competing alongside specialized adhesive manufacturers. These players can be categorized into diversified chemical giants, niche structural adhesive providers, and broad-portfolio film and spray adhesive specialists. Companies primarily engage in strategic partnerships for product qualification and continuous innovation in flame-retardant formulations.
Among the diversified chemical giants, Henkel AG & Co. KGaA exemplifies a broad portfolio approach, serving multiple aerospace platforms. Hexcel Corporation, with its focus on structural adhesives, occupies a position complementary to its core composite materials business. Meanwhile, 3M Company anchors the market for extensive film and spray-form adhesive solutions. These companies represent distinct strategic archetypes, from comprehensive material science providers to specialized bonding solution developers. Their presence highlights the varied demands for performance and application methods across the aerospace interior market.
| Leading Market Players |
|---|
| Arkema |
| Avery Dennison Corporation |
| 3M |
| DELO Industrie Klebstoffe GmbH & Co. KGaA |
| Hexcel Corporation |
| Henkel AG & Co. KGaA |
| Huntsman International LLC |
| H.B. Fuller Company |
| Solvay |
| Others |
Cost & Logistics Intelligence
Skilled adhesive application technicians, concentrated in established aerospace manufacturing hubs, influence pricing-tier spreads. Labor-cost differentials impact the final cost of specialized bonding solutions for OEMs and MROs.
Pricing Analysis
Volume-based purchasing drives transactional pricing for standard adhesive formulations. Price differentiation stems from product qualification levels and specific OEM material specifications. Pricing pressure stems from raw material volatility within the petrochemicals market. Commercial aviation MROs exhibit higher price sensitivity compared to OEM procurement teams for new aircraft builds.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand for structural adhesives, ensuring strict adherence to specifications. Geographic supply concentration for key chemical precursors exists in Germany, the United States, and China. The supply chain draws from specialized chemical producers for epoxy and polyurethane resins. Regulatory restrictions, such as the EU's REACH framework, represent a structural risk for material availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerospace interior adhesive market operates as a cost-of-compliance story. Stringent FAA and EASA flame, smoke, and toxicity standards create a significant barrier-to-entry moat for compliant material suppliers.
For Market Incumbents: Acquire advanced material science startups specializing in sustainable adhesive formulations. This move addresses future regulatory pressures on material lifecycle management and emerging OEM demands for greener solutions. Certification investment in new fast-curing systems counters the threat of extended aircraft downtime for MROs. Focus on expanding application training programs for technicians to maintain bond performance standards.
For New Entrants and Emerging Players: Online technical support platforms for MROs offer a direct channel for product specification and rapid problem-solving. Target the commercial aviation MRO segment in emerging hubs like the United Arab Emirates. Develop specialized, rapid-cure cyanoacrylate or silicone formulations for quick fixes in cabin refurbishment. A value-added service model focusing on application training can differentiate offerings.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized adhesive manufacturers given the push for lightweighting and advanced material integration. Long-term viability rests on suppliers with robust R&D pipelines for multi-functional and sustainable adhesives. Target acquisition archetypes include niche players with proprietary flame-retardant or bio-based chemistries. Practitioners should monitor evolving FST requirements as an inflection indicator for material innovation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-based Formulations | Aligns with airline sustainability goals and preempts future environmental regulations. |
| Expand MRO Technical Support | Enhances aftermarket presence and captures recurring revenue streams from maintenance operations. |
| Acquire FST Certification Expertise | Strengthens market access by meeting stringent safety standards from aviation authorities. |
| Develop Multi-functional Adhesives | Reduces component count for OEMs and simplifies aircraft cabin assembly processes. |
| Global Application Training Programs | Ensures consistent bond performance and mitigates skill gaps among installation technicians. |
Research Approach
Industry reports, regulatory filings from FAA and EASA, and academic research formed the secondary backbone for market sizing. Primary interviews with R&D directors, procurement leads at Airbus and Boeing, MRO facility managers, and airline cabin design specialists provided critical market insights. This approach integrated bottom-up data from company-level disclosures with top-down market validation. Data triangulation ensured the accuracy of market trends and growth projections.
Historical trendline analysis across the analysis window established foundational growth patterns for the aerospace interior adhesive market. The analytical framework modeled segmentation dimensions including product type, application area, end-user, and geographic demand centers. Compound annual growth rates were derived from a multi-factor regression analysis integrating fleet expansion and refurbishment cycles. Aircraft order backlogs and MRO spending forecasts served as key industry-specific forecast inputs.
The model holds under current regulatory frameworks and projected economic conditions; deviation in global airline traffic or raw material supply disruptions would shift market dynamics. Forecasts reflect assumptions regarding technological advancements and OEM adoption rates. Practitioners should monitor geopolitical stability and evolving FST compliance requirements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Curtains Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Aircraft Galley Market
Aircraft Cabin Interior
Aerospace Galley Trolley Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Interior Market