
 Asia-Pacific Commercial Aircraft Cabin Lighting Market | 2026-2036
Asia-Pacific Commercial Aircraft Cabin Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Commercial Aircraft Cabin Lighting Market Outlook
Aftermarket service revenue is tilting toward LED retrofit and modular replacement cycles as airlines extend airframe life. Collins Aerospace leverages its integrated avionics-to-lighting pipeline to capture recurring overhaul contracts across Australian and Indonesian carrier fleets. Diehl Aerospace GmbH anchors European-Asian joint ventures that sustain long-term supply agreements with China's COMAC assembly lines. Safran Cabin competes on narrowbody platform specialization, dominating A320-family cabin reconfiguration programs throughout the region.
Asia-Pacific commercial aircraft cabin lighting encompasses electroluminescent and solid-state illumination systems engineered to FAA/EASA photometric standards for passenger safety, mood modulation, and emergency egress visibility, typically operating at 28V DC with color temperatures spanning 2700K to 6500K. LED product types now lead installed base transitions given their 50,000-hour operational lifespan and weight reductions against legacy fluorescent tubes. Smart Lighting technology segments are drawing disproportionate R&D allocation as carriers specify circadian-rhythm programming and zone-controllable intensity for long-haul routes. Retrofit Services end users represent the fastest-growing demand pool as secondhand aircraft acquisitions accelerate across Vietnam, Philippines, and Malaysia.
India's DGCA enforces compliance with ICAO Annex 6 cabin illumination minima, while Australia's Civil Aviation Safety Administration mandates photometric testing under MOS Part 21 certification pathways. Japan's METI coordinates industry alignment with JIS C 8105-1 luminaire safety standards for domestically assembled regional jets. Stakeholders must monitor evolving CAAC airworthiness directives on LED flicker thresholds and harmonic interference as China's aviation regulator tighthens electromagnetic compatibility requirements for indigenous narrowbody programs.
Market Dynamics
Fleet modernization cycles across Southeast Asian full-service carriers are compressing replacement timelines for cabin lighting systems, while India's DGCA mandates force simultaneous compliance upgrades that reshape supplier prioritization.
Growth Catalysts
- LED Retrofit Mandates:China's CAAC airworthiness directives on electromagnetic compatibility are accelerating solid-state lighting transitions across COMAC assembly lines and retrofit programs.
- Long-Haul Circadian Programming:Australian and Indonesian carriers specify zone-controllable smart lighting for passenger experience differentiation on transpacific routes.
- Secondhand Aircraft Acquisitions:Vietnamese, Philippine, and Malaysian operators acquire aging narrowbodies that require complete cabin reconfiguration, driving modular lighting replacement demand.
Market Restraints
- Aviation-Grade LED Component Concentration:Specialized photodiodes and thermal management substrates concentrate among Japanese and South Korean component suppliers, creating input bottlenecks.
- Harmonic Interference Testing Costs:China's tightened electromagnetic compatibility requirements for indigenous narrowbody programs impose extended certification timelines and capital-intensive pre-qualification.
- Fluorescent Tube Aftermarket Persistence:Legacy 28V DC fluorescent systems retain installed base in regional turboprop fleets where LED conversion economics remain unfavorable.
Strategic Opportunities
- Indonesian Archipelago Connectivity Expansion:Garuda Indonesia and Lion Air fleet expansion for secondary city routes creates demand for lightweight, modular cabin lighting systems.
- Japan METI Regional Jet Standards Alignment:JIS C 8105-1 luminaire safety coordination for Mitsubishi SpaceJet derivatives opens specification pathways for domestic suppliers.
- Predictive Maintenance Integration:IoT-enabled lighting health monitoring converges with airline digital operations platforms, enabling subscription-based service revenue models.
Industry Challenges
- Photometric Calibration Specialist Shortage:FAA/EASA-certified testing engineers for 2700K-6500K color temperature validation remain concentrated in Shanghai and Tianjin clusters, constraining regional expansion.
- Legacy Airframe Electrical Architecture Compatibility:Pre-2010 narrowbody designs require substantial harness modification to support smart lighting zone control, complicating retrofit execution.
- Cross-Border Certification Parallel Processing:Simultaneous CAAC, DGCA, and CASA approval pathways for LED retrofit kits extend time-to-revenue for aftermarket suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Commercial Aircraft Cabin Lighting Market |
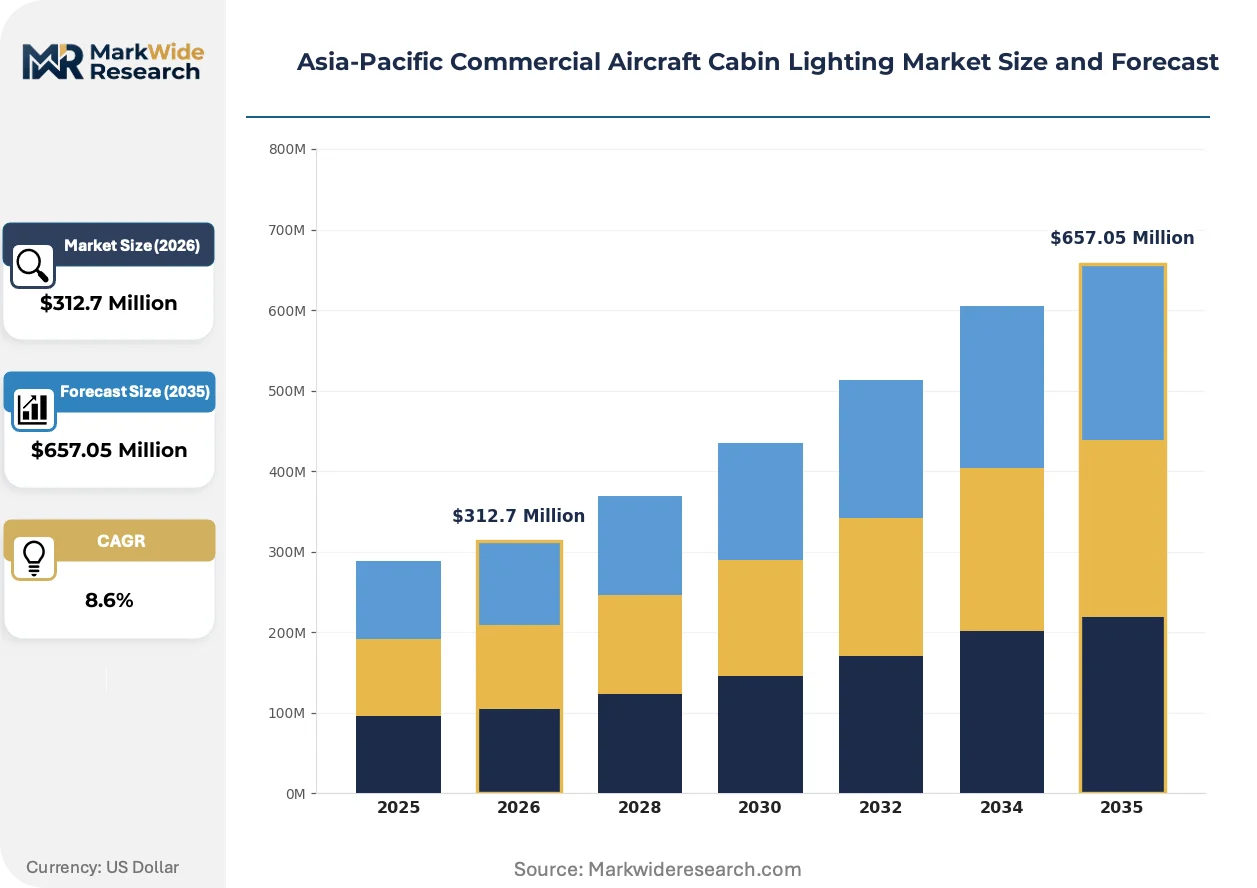
| Market Size in 2026 | $312.7 Million |
| Market Size in 2035 | $657.05 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Fluorescent, Incandescent Technology: Smart Lighting, Dynamic Lighting, Conventional Lighting, Control Systems End User: Commercial Airlines, Private Jets, Cargo Aircraft, Retrofit Services Installation: OEM Installations, Aftermarket Installations, Modular Installations, Custom Installations |
| Companies Covered | Collins Aerospace, Astronics Corporation, Diehl Aerospace GmbH, Luminator Technology Group, STG Aerospace, Safran Cabin, Honeywell Aerospace, SCHOTT Technical Glass Solutions GmbH, Oxley Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Commercial Aircraft Cabin Lighting Market Strategic Shifts
Digital twin integration is virtualizing how lighting systems are specified, tested, and sustained through airframe life cycles. Three interconnected developments are compressing traditional development timelines and reshaping competitive positioning.
Smart Lighting control architectures are virtualizing the traditional hardware-defined cabin illumination stack. Full-service carriers across Thailand and Singapore now specify software-defined mood programming that overrides fixed hardware configurations. This virtualization is collapsing the boundary between avionics and cabin systems, forcing lighting suppliers to develop API-compatible platforms.
Australia's Civil Aviation Safety Administration now mandates photometric testing under MOS Part 21 certification pathways that mirror evolving EASA CS-25 amendments. This regulatory convergence is harmonizing test protocols across the Asia-Pacific, reducing duplicate qualification costs for suppliers serving multiple jurisdictions. Narrowbody retrofit specialists are consolidating testing infrastructure in Melbourne to capture cross-border certification efficiency.
Airline technical procurement teams now unbundle lighting system acquisition from long-term service agreements, reversing prior bundled sourcing patterns. Low-cost carriers in Vietnam and the Philippines separately negotiate hardware supply, installation labor, and post-warranty maintenance, fragmenting vendor relationships. This unbundling is most visible in secondary aircraft leasing transactions where lessors retain component-level service flexibility.
Asia-Pacific Commercial Aircraft Cabin Lighting Market Segmentation
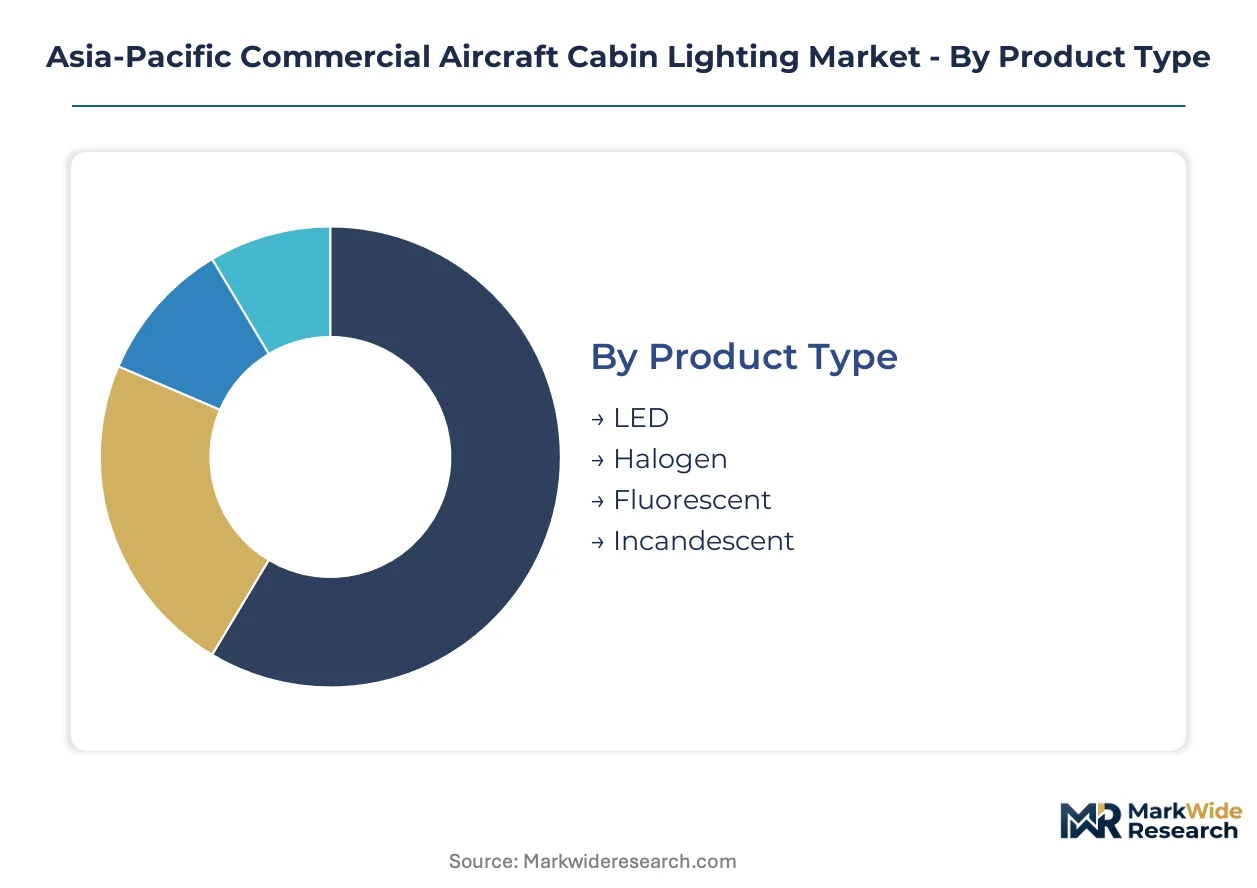
Cabin lighting procurement across Asia-Pacific fragments across four structural dimensions that determine supplier engagement models and margin profiles. Each segmentation axis reveals distinct competitive dynamics between legacy incumbents and emerging technology specialists.
Product Type:
Mature fluorescent and incandescent technologies now compete against emerging solid-state alternatives as airworthiness directives accelerate obsolescence timelines.
- LED:Solid-state electroluminescent systems operating at 28V DC with 50,000-hour operational lifespan and 40% weight reduction versus legacy tubes. Demand concentrates in Chinese COMAC assembly lines and Australian carrier retrofit programs as CAAC electromagnetic compatibility mandates tighten.
- Fluorescent:Legacy 28V DC gas-discharge tubes retain installed base in regional turboprop fleets where conversion economics remain unfavorable. Vietnamese and Philippine operators of aging narrowbodies sustain residual demand for compatible replacement stock.
- Halogen:Tungsten-halogen incandescent systems persist in emergency egress and reading light applications requiring instantaneous full-output illumination without warm-up latency.
- Incandescent:Conventional filament-based sources dominate cost-sensitive cargo aircraft configurations where photometric performance requirements remain minimal.
LED retains volume leadership; Fluorescent holds the steepest contraction trajectory as regulatory pressure mounts.
Technology:
Cost tier stratification separates premium programmable systems from commodity fixed-output alternatives.
- Smart Lighting:Zone-controllable, software-defined architectures enabling circadian-rhythm programming and API integration with airline digital operations platforms. Thai and Singapore full-service carriers specify these systems for transpacific route differentiation.
- Dynamic Lighting:Scene-capable systems with pre-programmed mood transitions but without full software-defined configurability. Indonesian archipelago carriers deploy these for secondary city route passenger experience upgrades.
- Conventional Lighting:Fixed-output, hardware-defined illumination without programmable capabilities. Low-cost operators in Malaysia and Philippines specify these for acquisition-cost minimization on short-haul narrowbodies.
- Control Systems:Distributed dimming modules, power management units, and cabin management system interfaces that enable centralized lighting command. Demand clusters around Shanghai and Tianjin manufacturing clusters for indigenous narrowbody programs.
Conventional Lighting retains volume leadership; Smart Lighting commands the steepest expansion curve.
End User:
Customer type determines procurement complexity, with unbundled sourcing patterns fragmenting vendor relationships across secondary transactions.
- Commercial Airlines:Full-service and low-cost carriers operating scheduled passenger services with fleet-wide standardization requirements. Fleet modernization programs across Southeast Asia compress replacement timelines for cabin lighting systems.
- Retrofit Services:Third-party maintenance, repair, and overhaul providers executing cabin reconfigurations on secondhand aircraft acquisitions. Vietnamese, Philippine, and Malaysian operators drive fastest demand acceleration as aging narrowbody imports surge.
- Private Jets:Business aviation operators specifying custom illumination configurations for VIP cabin interiors. Demand concentrates in Australian and Singapore-based completion centers serving ultra-high-net-worth clientele.
- Cargo Aircraft:Freighter operators with minimal photometric requirements prioritizing reliability and acquisition cost over passenger experience features. Regional express carriers in Indonesia and Thailand sustain this segment.
Commercial Airlines retain volume leadership; Retrofit Services represent the fastest-expanding demand pool.
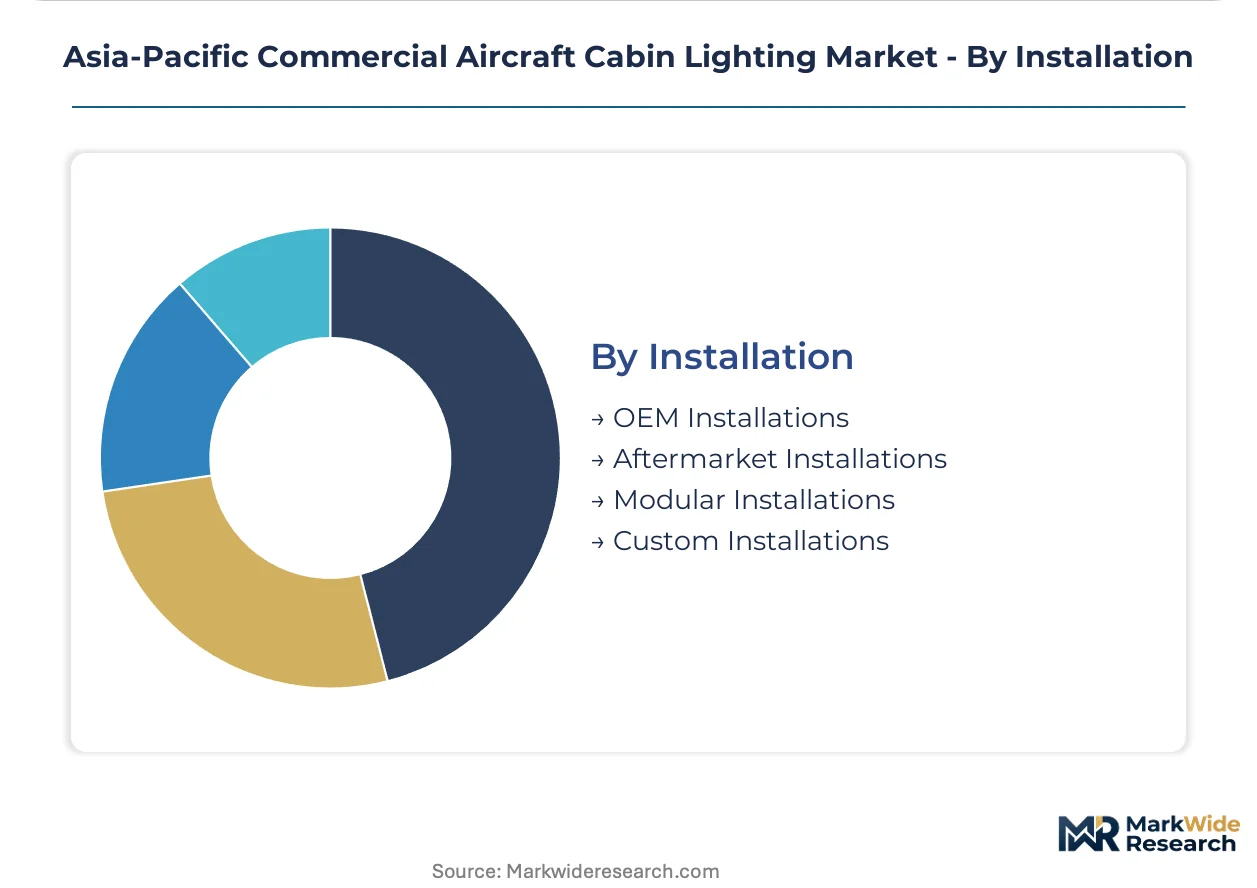
Installation:
Supply concentration in tier-one aviation manufacturing clusters shapes geographic deployment patterns for each installation mode.
- OEM Installations:Factory-integrated lighting systems specified during original airframe assembly. COMAC's Shanghai and Tianjin production lines anchor regional demand as indigenous narrowbody programs scale.
- Aftermarket Installations:Post-delivery replacement and upgrade services executed during heavy maintenance checks. Australian and Indonesian carrier fleets generate recurring overhaul contract opportunities.
- Modular Installations:Line-replaceable unit configurations enabling rapid swap-out without airframe modification. Secondary city operators across the Indonesian archipelago prioritize these for fleet flexibility.
- Custom Installations:Bespoke engineering for unique cabin configurations, VIP interiors, or special mission aircraft. Singapore-based completion centers specialize in these high-margin, low-volume engagements.
OEM Installations retain volume leadership; Modular Installations gain share fastest as fleet flexibility priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and Tianjin anchor regional supply chains for indigenous narrowbody programs, while Australian and Southeast Asian carrier fleets generate concentrated aftermarket demand. Procurement patterns diverge sharply between OEM-integrated systems and modular retrofit configurations.
China
CAAC electromagnetic compatibility directives accelerate LED transitions across COMAC assembly lines in Shanghai and Tianjin. The regulator's tightened airworthiness requirements for indigenous narrowbody programs compress supplier qualification timelines. Tier-one aviation manufacturing clusters concentrate specification authority for factory-integrated lighting systems.
Australia
CASA mandates photometric testing under MOS Part 21 certification pathways that mirror evolving EASA CS-25 amendments. Melbourne testing infrastructure consolidates to capture cross-border certification efficiency for narrowbody retrofit specialists. Australian carrier fleets generate recurring overhaul contract opportunities for LED retrofit providers.
India
DGCA enforces stricter cabin safety inspections under revised civil aviation requirements that reshape supplier prioritization. Fleet modernization programs across full-service carriers compress replacement timelines for cabin lighting systems. Technical procurement teams unbundle lighting acquisition from long-term service agreements.
Indonesia
Garuda Indonesia and Lion Air fleet expansion for secondary city routes creates demand for lightweight, modular cabin lighting systems. Archipelago connectivity expansion prioritizes line-replaceable unit configurations enabling rapid swap-out without airframe modification. Zone-controllable smart lighting specifications differentiate transpacific route passenger experience.
Vietnam
Secondhand aircraft acquisitions accelerate across Vietnamese operators, driving complete cabin reconfiguration and modular lighting replacement demand. Aging narrowbody imports surge as low-cost carriers separately negotiate hardware supply, installation labor, and post-warranty maintenance. Retrofit service providers capture fastest demand acceleration in the regional aftermarket.
Asia-Pacific Commercial Aircraft Cabin Lighting Market Competitive Environment
Integrated avionics-to-lighting pipeline specialists and narrowbody platform specialists split the market across OEM and aftermarket vectors. Collins Aerospace leverages recurring overhaul contracts across Australian and Indonesian carrier fleets, while Safran Cabin dominates A320-family cabin reconfiguration programs. Diehl Aerospace GmbH anchors European-Asian joint ventures sustaining long-term supply agreements. Competitive moves concentrate on strategic partnerships for certification harmonization and portfolio diversification into predictive maintenance integration.
Among integrated systems architects, Collins Aerospace and Honeywell Aerospace occupy positions spanning avionics-to-cabin illumination pipelines. Diehl Aerospace GmbH exemplifies the European-Asian joint venture archetype, anchoring supply relationships with indigenous narrowbody programs. Safran Cabin represents narrowbody platform specialization, sitting within the aftermarket reconfiguration tier serving A320-family operators throughout Southeast Asia.
| Leading Market Players |
|---|
| Collins Aerospace |
| Astronics Corporation |
| Diehl Aerospace GmbH |
| Luminator Technology Group |
| STG Aerospace |
| Safran Cabin |
| Honeywell Aerospace |
| SCHOTT Technical Glass Solutions GmbH |
| Oxley Group |
| Others |
Value Chain & Pricing Dynamics
Shanghai and Tianjin tier-one aviation manufacturing clusters concentrate specification authority for factory-integrated lighting systems, compressing supplier margins for aftermarket providers while elevating pricing power for OEM-anchored incumbents serving COMAC assembly lines.
Pricing Analysis
CAAC electromagnetic compatibility directives dictate the pricing tier structure across LED retrofit and OEM-integrated segments. Three-tier pricing stratifies across FAA/EASA dual-certified premium systems, single-certification standard configurations, and economy-grade fluorescent replacements for regional turboprop fleets. Price differentiation centers on certification grade and after-sales service bundling. Cost compression in economy-tier fluorescent replacement is intensifying as Vietnamese and Philippine operators unbundle hardware from installation labor. Low-cost carriers in Malaysia and Philippines exhibit highest price sensitivity; VIP completion centers in Singapore show least sensitivity.
Supply Chain Analysis
Tariff exposure between Japan and South Korea for specialized photodiodes and thermal management substrates dominates supply chain risk planning. Component manufacturing concentrates in Japan, South Korea, and China. Raw material dependencies include gallium nitride wafers, aluminum nitride substrates, and aviation-grade silicone encapsulants. Single-source vulnerability persists for FAA-certified photometric calibration equipment. Distribution runs through Shanghai and Tianjin for OEM channels, with modular replacement stock flowing through Melbourne and Singapore for aftermarket retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as procurement unbundling fragments vendor relationships and creates specialist niches in predictive maintenance integration and cross-border certification services.
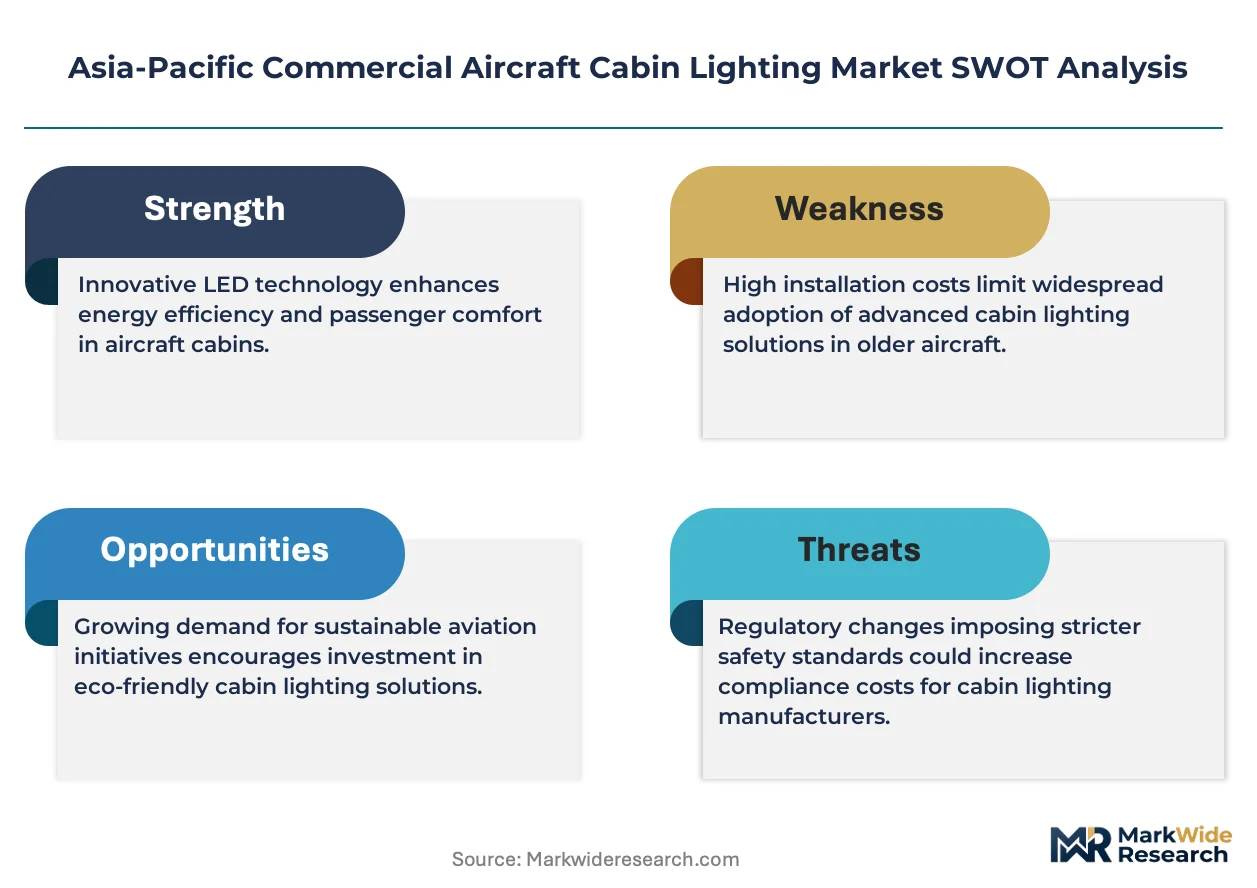
For Market Incumbents: Insulate recurring overhaul contract positions by deepening backward integration into LED component supply and establishing captive photometric calibration capacity in Melbourne to offset specialist engineer shortages. Threat from emerging modular lighting specialists in Indonesia requires preemptive certification investment under CASA MOS Part 21 pathways. For New Entrants and Emerging Players: Pursue white-space opportunity in IoT-enabled lighting health monitoring platforms for Australian and Indonesian carrier fleets. Most penetrable segment: subscription-based predictive maintenance for secondhand narrowbody acquisitions in Vietnam and Philippines. Go-to-market angle: API-compatible smart lighting control architectures that bypass legacy avionics integration barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors narrowbody platform specialists with established CAAC qualification and modular installation capabilities. Long-term viability hinges on LED transition completion across regional turboprop fleets. Signal to watch: CAAC airworthiness directive expansion beyond electromagnetic compatibility into harmonic interference thresholds for indigenous programs.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Border Certification Harmonization | Consolidated Melbourne testing infrastructure captures simultaneous CAAC, DGCA, and CASA approval efficiency for retrofit specialists. |
| Predictive Maintenance Platform Development | IoT-enabled lighting health monitoring converges with Garuda Indonesia and Lion Air digital operations platforms. |
| Backward Integration into LED Components | Captive supply of aviation-grade photodiodes reduces dependency on Japanese and South Korean substrate suppliers. |
| Modular Installation Capability Expansion | Line-replaceable unit configurations serve Indonesian archipelago secondary city route fleet flexibility requirements. |
| Smart Lighting API Standardization | Software-defined control architectures enable Thai and Singapore full-service carrier circadian-rhythm programming specifications. |
Study Parameters
Initial hypotheses were tested against primary input from airline technical procurement directors, MRO retrofit service managers, avionics integration engineers, and CAAC certification specialists and refined through secondary validation against FAA airworthiness directives, EASA CS-25 amendments, COMAC supplier disclosure filings, and customs trade data for aviation-grade LED components. Bottom-up fleet analysis triangulated with top-down market sizing across OEM and aftermarket channels.
Demand-supply balance modeling anchored projections across the analysis window. Segmentation dimensions included product type, technology tier, end-user category, and installation mode. CAGRs derived from fitted growth curves calibrated to fleet modernization cycle timing and regulatory mandate implementation schedules. Industry-specific inputs encompassed COMAC delivery schedules, secondhand narrowbody import volumes, and CAAC electromagnetic compatibility directive scope expansion.
Macroeconomic conditions sit as an overlay; deviation in aviation fuel costs, aircraft lease rates, or regional currency volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation timing and fleet retirement patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aircraft Seat Upholstery Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
Aircraft Curtains Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aerospace Lavatory System Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market