
 Commercial Aircraft Interior Lighting Market | 2026-2036
Commercial Aircraft Interior Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Interior Lighting Market Analysis
Multi-source procurement for cabin electronics is decoupling from traditional single-source airframe agreements. Collins Aerospace leverages its integrated avionics heritage to sustain long-term OEM relationships. Diehl Stiftung & Co. KG anchors European supply chains through specialized lighting manufacturing. Safran competes on aerospace propulsion adjacencies that extend into cabin systems integration.
Commercial aircraft interior lighting encompasses engineered illumination systems designed for passenger and crew environments, typically operating on 28V DC aircraft power with color temperatures ranging from 2700K to 6500K for circadian rhythm management. These systems reduce power draw versus legacy incandescent units while supporting mood-lighting protocols that airlines deploy to manage jet lag on long-haul routes. LED product types now dominate retrofit decisions as carriers phase out fluorescent tubes to cut maintenance intervals and fuel burn. Ambient technology applications command premium positioning in wide-body cabin redesigns where carriers differentiate passenger experience. OEM end users increasingly specify factory-installed programmable systems rather than airline-furnished equipment to streamline certification.
FAA airworthiness standards and EASA CS-25 certification requirements govern photometric performance, fire resistance, and electromagnetic compatibility for installed cabin lighting. The EU Green Deal framework pressures European operators toward lower-energy LED configurations through emissions-linked operating cost structures. Stakeholders must monitor evolving DO-160G environmental test criteria alongside airline sustainability reporting mandates that tie fleet interior decisions to carbon disclosure obligations.
Market Dynamics
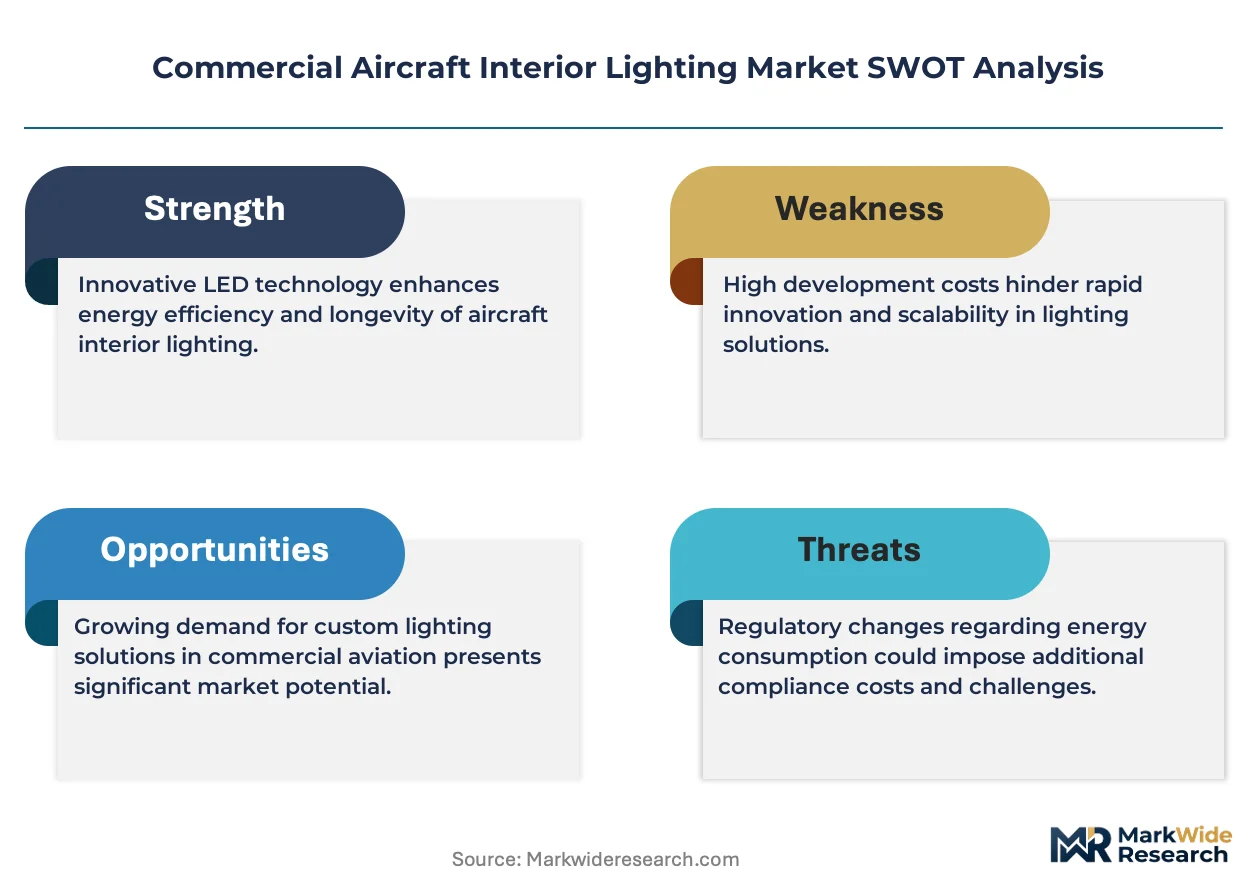
Airlines retrofitting narrow-body fleets for passenger experience upgrades are expanding LED adoption while FAA airworthiness directives tighten compliance requirements around reliability standards.
Growth Catalysts
- Retrofit cycles:Narrow-body fleet modernization programs drive replacement demand for legacy fluorescent tubes with programmable LED arrays.
- EU Green Deal:European operators face emissions-linked operating cost structures that pressure adoption of lower-energy cabin configurations.
- Circadian protocols:Long-haul carriers deploy color-tunable systems ranging from 2700K to 6500K to manage jet lag on transoceanic routes.
Market Restraints
- DO-160G testing costs:Electromagnetic compatibility and environmental test criteria impose capital-intensive certification timelines on new entrants.
- Single-source legacy contracts:Traditional airframe agreements lock airlines into incumbent supplier relationships that resist component substitution.
- Fluorescent residual stock:Maintenance organizations retain inventory of legacy tube formats that delay full fleet conversion economics.
Strategic Opportunities
- Wide-body premium cabins:Ambient technology applications command positioning in cabin redesigns where carriers differentiate passenger experience.
- OEM factory-install shift:Airframers increasingly specify programmable systems at production rather than accepting airline-furnished equipment.
- CSRD disclosure mandates:European sustainability reporting requirements tie fleet interior decisions to carbon disclosure obligations that favor LED retrofits.
Industry Challenges
- Aerospace electronics talent scarcity:Specialized firmware engineers for avionics-grade lighting control systems command premium compensation.
- 28V DC integration complexity:Legacy aircraft electrical architectures require power conditioning units that add weight and certification burden.
- EASA CS-25 fire resistance:Photometric performance and material flammability standards extend development cycles for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Interior Lighting Market |
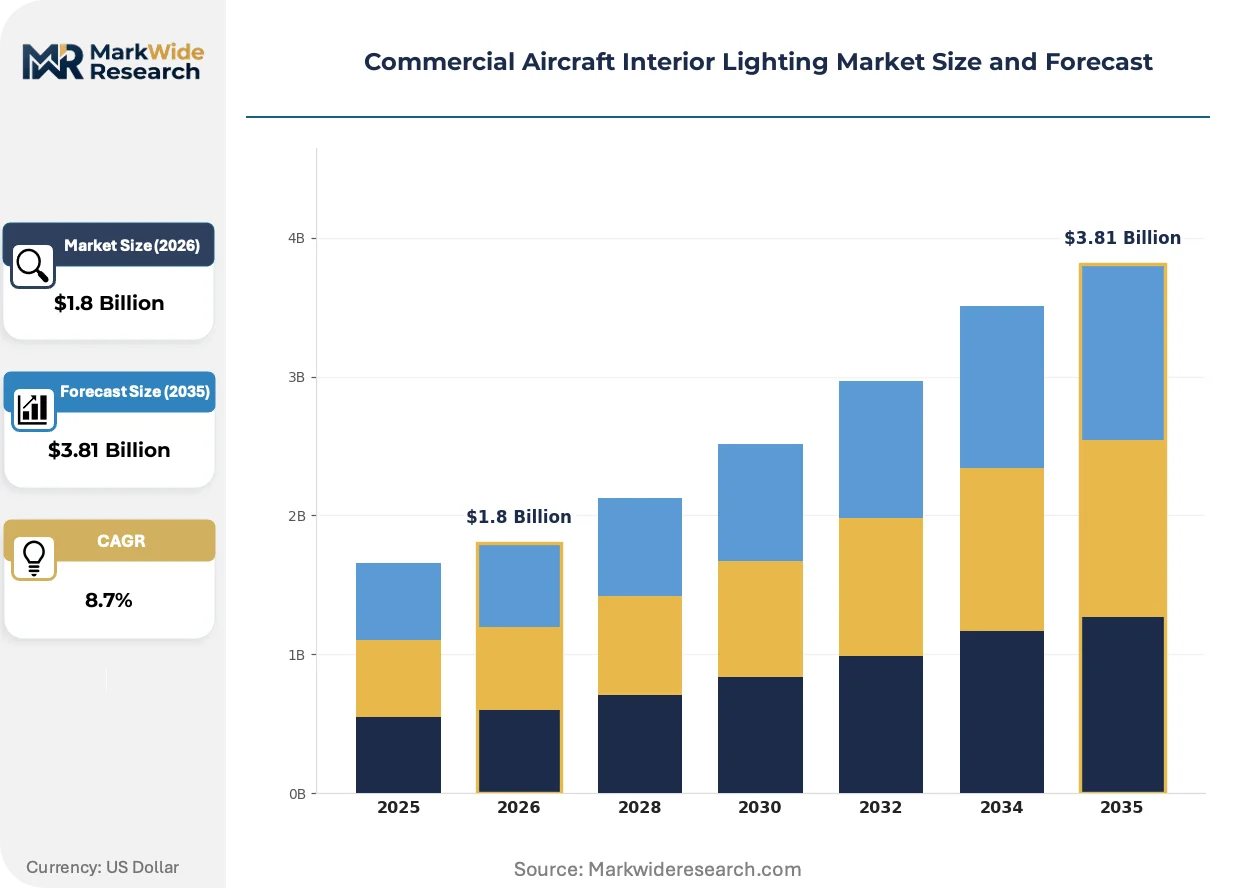
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, Fluorescent, Incandescent Application: Cockpit, Cabin, Lavatory, Galley End User: Commercial Airlines, Charter Services, Cargo Carriers, OEMs Technology: Directional, Ambient, Task, Accent |
| Companies Covered | Astronics Corporation, Luminator Technology Group, Collins Aerospace, Schott AG, SELA, STG Aerospace, Diehl Stiftung & Co. KG, Cobalt Aerospace Group, Safran, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Interior Lighting Market Emerging Trajectories
Programmable LED architectures are displacing fixed-output systems as airlines prioritize configurable cabin environments over static illumination.
Addressable RGBW LED engines are automating scene management across boarding, cruise, and sleep phases without crew manual intervention. Full-service carriers in the Middle East and Asia-Pacific deploy these systems fastest. The technology is automating labor-intensive cabin preparation workflows while compressing retrofit installation windows.
EASA CS-25 certification amendments now mandate predictive failure monitoring for critical illumination paths in extended-range twin-engine operations. This forces suppliers to embed diagnostic circuitry that reports degradation before catastrophic failure. Wide-body programs in European jurisdictions face the steepest compliance ramps.
Airlines now bundle lighting specifications into airframe purchase agreements rather than sourcing separately as buyer-furnished equipment. This concentrates procurement leverage with OEM engineering teams. The shift is most visible in United States narrow-body orders where factory-install rates exceed prior-generation programs.
Commercial Aircraft Interior Lighting Market Segmentation
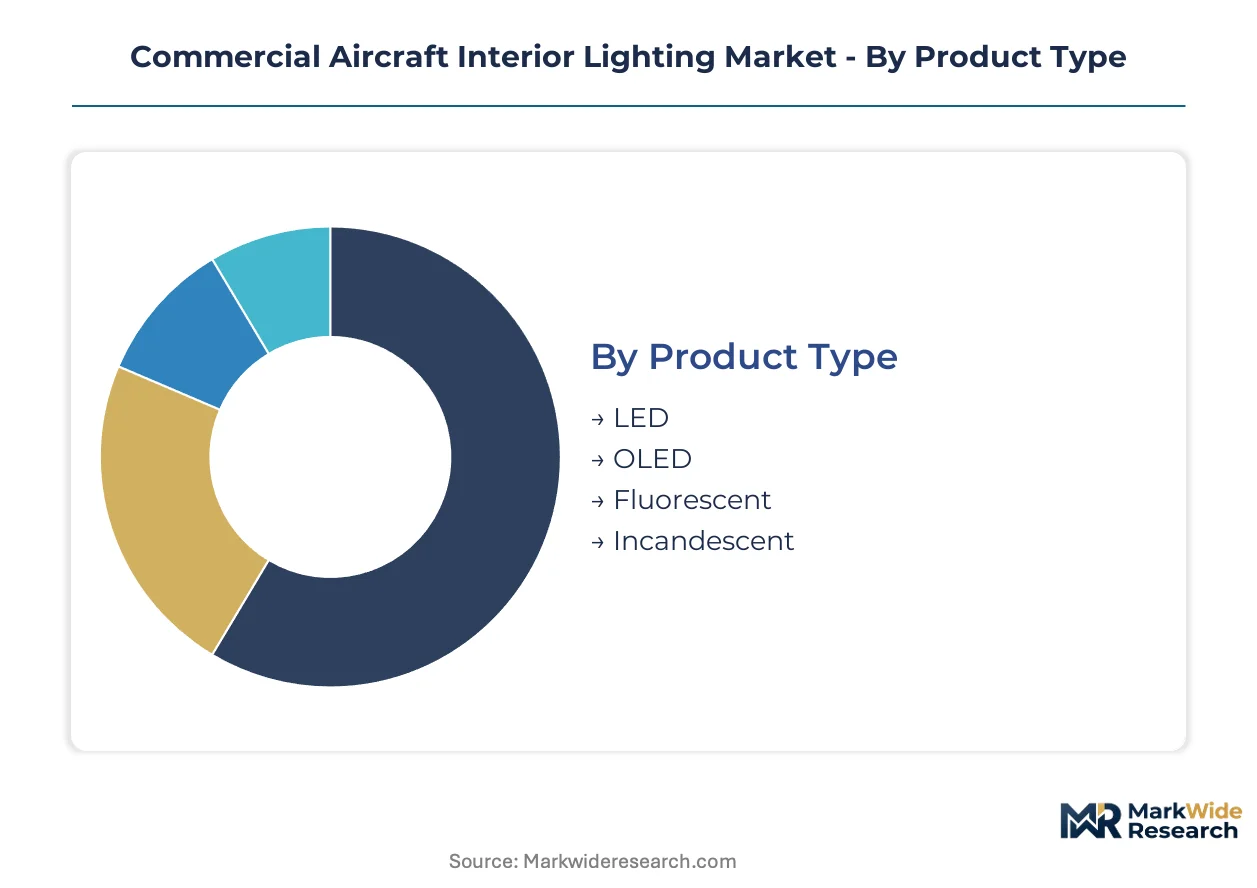
Interior lighting procurement splits across technical specifications, installation timing, and operator business models. Each dimension carries distinct certification burdens and supplier qualification requirements that reshape competitive access.
Product Type:
Retrofit economics and factory-install specifications diverge sharply across illumination technologies, with energy recovery timelines and airworthiness compliance framing buyer calculations.
- LED:Solid-state arrays operating on 28V DC aircraft power deliver 50,000-hour service life with programmable color temperature from 2700K to 6500K. Narrow-body fleet retrofits in the United States concentrate demand as carriers chase fuel burn reductions and extended maintenance intervals.
- OLED:Thin-film organic electroluminescent panels enable curved surface integration and uniform luminance without secondary optics. Premium wide-body cabin redesigns in the Middle East and Asia-Pacific adopt these for architectural lighting features that differentiate passenger experience.
- Fluorescent:Legacy tube formats persist in maintenance inventories where fleet conversion economics lag replacement cycles.
- Incandescent:Residual demand concentrates in non-critical indicator applications and aging regional aircraft with minimal retrofit justification.
LED leads volumes today; OLED is gaining share fastest.
Application:
Regulatory stringency and passenger exposure hours determine specification tiers across aircraft zones.
- Cabin:Mood-lighting protocols for jet lag management require addressable RGBW engines with automated scene transitions. Long-haul carriers deploy these systems most aggressively on transoceanic routes where circadian rhythm intervention commands premium pricing power.
- Cockpit:FAA and EASA impose predictive failure monitoring mandates for critical illumination paths in extended-range operations. European-registered wide-bodies face the steepest compliance ramps under amended CS-25 certification requirements.
- Lavatory:Compact fixture designs prioritize fire resistance and electromagnetic compatibility over programmability.
- Galley:Task-optimized output dominates crew workspace illumination with minimal color-tunability requirements.
Cabin applications command the largest revenue pool; cockpit specifications carry the highest certification barriers.
End User:
Procurement authority and equipment ownership models fragment demand across operator types.
- Commercial Airlines:Full-service and low-cost carriers drive narrow-body retrofit volumes with passenger experience upgrade programs. United States major carriers operate the largest active fleet modification pipelines, bundling lighting specifications into airframe purchase agreements rather than sourcing separately.
- OEMs:Boeing and Airbus engineering teams increasingly specify factory-installed programmable systems to streamline certification and compress delivery timelines. This shift concentrates procurement leverage with airframer supply chain organizations.
- Charter Services:Fractional ownership and business jet operators prioritize rapid installation windows over custom programming capabilities.
- Cargo Carriers:Minimal crew and passenger exposure reduce specification complexity to basic functional illumination.
Commercial airlines dominate current procurement; OEM factory-install channels are expanding most quickly.
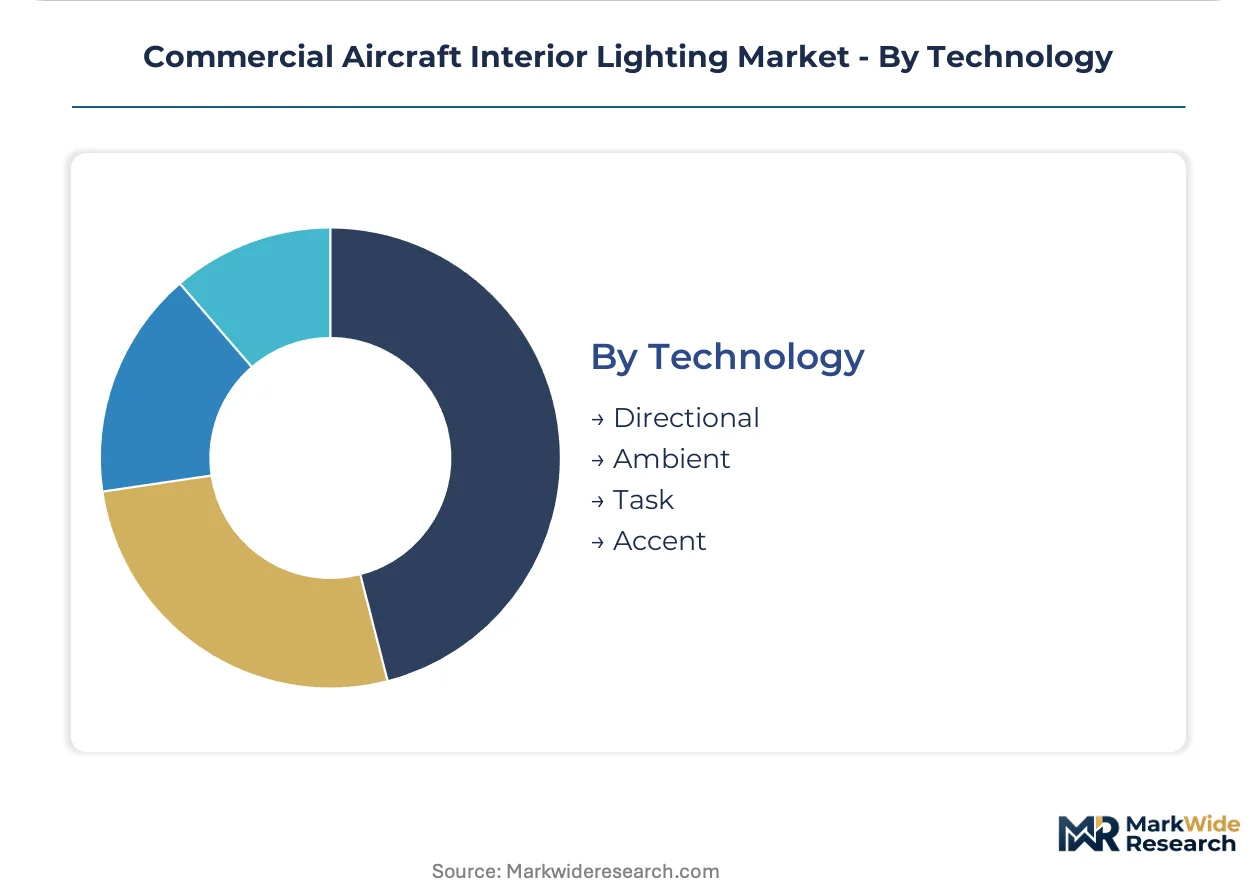
Technology:
Light distribution architecture determines integration complexity and software control requirements.
- Ambient:Indirect wash lighting for ceiling and sidewall surfaces enables continuous color gradient programming across flight phases. Wide-body premium cabins in Asia-Pacific deploy these systems for competitive differentiation on long-haul routes.
- Directional:Focused beam control for reading and work surfaces relies on precision optics rather than addressable electronics. Narrow-body economy cabins standardize on these for cost-controlled retrofit programs.
- Task:High-output localized illumination serves crew workstations and safety-critical zones with minimal network integration.
- Accent:Decorative highlight fixtures for branding and architectural features carry limited functional certification burden.
Directional technology anchors installed base volumes; ambient systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production toward jurisdictions where FAA and EASA certification reciprocity reduces duplicate testing costs. Manufacturers now site final assembly in countries with bilateral aviation safety agreements to compress program timelines.
United States
Major carriers including Delta and United operate the world's largest narrow-body retrofit pipelines. FAA airworthiness directives on LED reliability standards tighten compliance timelines for suppliers serving domestic fleets. Wichita's aviation manufacturing cluster anchors lighting system integration work for Boeing programs.
Germany
Lufthansa Group's fleet standardization programs drive demand for programmable cabin environments across A320 and A350 fleets. EASA CS-25 certification amendments mandate predictive failure monitoring that extends development cycles for suppliers. Hamburg's aerospace corridor concentrates cabin system engineering and integration facilities.
China
COMAC's C919 production ramp and airline fleet expansion create factory-install demand for programmable LED architectures. The Civil Aviation Administration of China aligns certification requirements with FAA and EASA standards to accelerate supplier qualification. Shanghai's Pudong aerospace zone hosts cabin electronics manufacturing for both domestic and export programs.
France
Airbus engineering teams in Toulouse specify factory-installed lighting systems to streamline delivery timelines for A320neo and A350 programs. The EU Green Deal pressures Air France-KLM toward lower-energy cabin configurations through emissions-linked operating structures. Toulouse-Blagnac's aerospace cluster integrates lighting specifications into airframe purchase agreements.
United Arab Emirates
Emirates and Etihad deploy ambient lighting systems fastest among full-service carriers to differentiate premium cabins on long-haul routes. The General Civil Aviation Authority harmonizes certification with EASA standards to attract supplier investment. Dubai's aviation services hub concentrates retrofit installation capacity for Middle East and Asia-Pacific operators.
Commercial Aircraft Interior Lighting Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue OLED specialization and addressable RGBW automation. The market consolidates around three to five integrated suppliers with airframe OEM relationships, while specialized lighting fabricators serve retrofit channels. Tier-one archetypes include diversified aerospace conglomerates with avionics heritage, European family-owned engineering groups with cabin system focus, and mid-scale specialists with narrow-body retrofit expertise. Dominant competitive moves include backward integration into LED engine manufacturing and strategic partnerships with airframers to secure factory-install positions.
Among the named suppliers, Collins Aerospace represents the diversified conglomerate archetype with integrated avionics heritage, Diehl Stiftung & Co. KG occupies the European engineering specialist position, and Safran exemplifies propulsion-adjacent diversification into cabin systems. These three anchors demonstrate how supplier positioning traces to parent-company capability origins rather than lighting-specific scale advantages.
| Leading Market Players |
|---|
| Astronics Corporation |
| Luminator Technology Group |
| Collins Aerospace |
| Schott AG |
| SELA |
| STG Aerospace |
| Diehl Stiftung & Co. KG |
| Cobalt Aerospace Group |
| Safran |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between factory-install OEM systems and aftermarket retrofit kits manifests in divergent margin structures and supply chain footprints. FAA DO-160G environmental testing requirements concentrate premium pricing power with incumbent suppliers holding airframe partnerships, while price-sensitive narrow-body retrofit channels draw from distributed component sourcing across multiple jurisdictions.
Pricing Analysis
Distributor margins for aftermarket retrofit channels compress as airlines consolidate procurement through direct airframe agreements. Three-tier pricing structure across premium programmable arrays, standard LED replacements, and residual fluorescent formats tracks certification burden and software complexity. Pricing pressure stems from OEM factory-install shifts that eliminate intermediary markups. Low-cost carriers exhibit highest price sensitivity; full-service Middle Eastern operators prioritize feature depth over unit cost.
Supply Chain Analysis
Regional distribution centers in Wichita, Hamburg, and Shanghai anchor hub-and-spoke patterns for finished lighting assemblies. LED engine fabrication concentrates in China, South Korea, and Taiwan; optical component finishing occurs in Germany and France. Raw material dependencies include gallium nitride substrates, aluminum heat sinks, and aerospace-grade polycarbonate lenses. Single-source vulnerability around specialized firmware engineering creates chokepoint risk. Distribution runs through airframer-certified logistics networks rather than open-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA predictive failure monitoring mandates function as a regulatory compounder, accelerating supplier consolidation as compliance costs outpace smaller competitors' capital access.
For Market Incumbents: Cement factory-install positions at Boeing and Airbus through exclusive engineering partnerships that embed lighting specifications into airframe purchase agreements. Deepen backward integration into LED engine manufacturing to capture margin from optical component suppliers. Address emerging OLED specialization threats from Asian entrants by accelerating RGBW automation roadmaps. For New Entrants and Emerging Players: Begin with narrow-body retrofit channels in the United States where airline procurement remains fragmented across maintenance organizations. Target cargo carrier segments where specification complexity lags passenger aviation and certification barriers moderate. Pursue FAA Parts Manufacturer Approval as primary go-to-market credential rather than airframe OEM qualification. For Investors and Strategic Acquirers: Consolidation pressure builds where DO-160G testing costs exceed $2 million per product variant and three-year certification timelines strand development capital. Long-term viability favors suppliers with captive airframe relationships and firmware engineering depth. Target acquisition archetype: mid-scale specialists with narrow-body retrofit expertise and established airline maintenance organization contracts. Monitor EASA CS-25 amendment implementation velocity as inflection indicator for European compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Engine Manufacturing | Captures optical component margins previously flowing to Schott AG and specialized substrate suppliers. |
| FAA Parts Manufacturer Approval Pathway | Unlocks aftermarket retrofit access without airframe OEM qualification dependency. |
| RGBW Automation Platform Launch | Addresses Emirates and Etihad demand for programmable cabin environments on A350 and 787 fleets. |
| Joint Venture with COMAC | Positions for C919 factory-install specifications as Chinese production scales. |
| Predictive Failure Monitoring Certification | Satisfies amended EASA CS-25 requirements for European-registered wide-body operations. |
Methodological Framework
Direct dialogue with avionics engineering directors, airline fleet procurement managers, MRO facility operators, and FAA certification specialists grounded qualitative findings. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 amendment documentation, airframe OEM supplier qualification records, and airline sustainability disclosure reports. Bottom-up and top-down triangulation cross-checked segment volumes against fleet retrofit pipeline data.
Bottom-up modeling aggregated individual aircraft retrofit economics and factory-install contract values across the projection horizon. Segmentation dimensions included product type, application zone, end-user procurement model, and technology architecture. CAGRs derived from fitted growth curves against historical narrow-body fleet modification cycles. Industry-specific inputs incorporated fuel burn reduction valuations and maintenance interval extension calculations.
Several conditions sit outside the modeled scope, including military aircraft applications, business aviation below super-mid cabin class, and speculative next-generation airframe programs without firm delivery commitments. Forecasts reflect documented assumptions regarding certification timeline stability and airline capital expenditure continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Seat Upholstery Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Cabin Management System Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Aerospace Lavatory System Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market