

Aircraft High-Lift Device Aerodynamic Modification Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft High-Lift Device Aerodynamic Modification Systems Market Insights
Commercial aviation's shift toward fleet modernization is repositioning demand within the aircraft high-lift device modification landscape. Aviation Partners Boeing leverages its blended winglet heritage to extend aerodynamic efficiency solutions into high-lift domains. GKN Aerospace anchors European supply chains through composite flap track fairing expertise and advanced manufacturing scale. Safran dominates electromechanical actuation integration, competing on flight control system architecture depth.
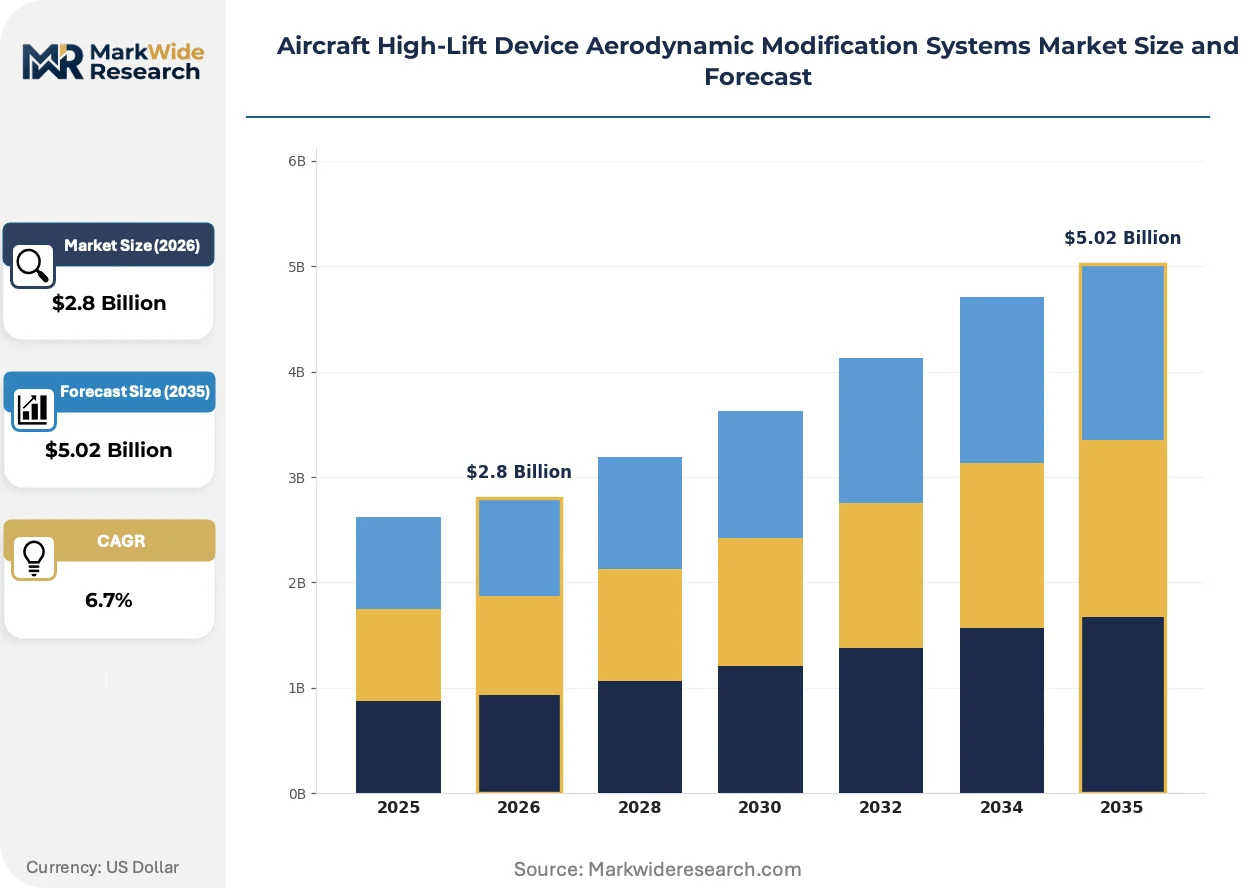
Aircraft high-lift device aerodynamic modification systems encompass engineered alterations to flaps, slats, and leading or trailing edge surfaces that expand wing camber and area during low-speed flight phases, typically employing composite skins, precision-actuated linkages, and computational fluid dynamics-optimized profiles to reduce stall speeds and improve climb performance. Trailing edge devices capture the largest retrofit volume as airlines prioritize takeoff and landing field performance gains on narrow-body workhorses. Electro-mechanical systems displace hydraulic architectures fastest, concentrating margin pools among suppliers certifying fault-tolerant architectures under amended type certificates. Hydraulic actuation sustains relevance in military applications where battle damage tolerance and thermal extremes resist full electrification.
FAA airworthiness directives and EASA certification memoranda shape modification pathways by mandating fatigue life analysis and flutter clearance for altered high-lift geometries. The EU Green Deal's aviation emissions benchmarks and ICAO's Carbon Offsetting and Reduction Scheme for International Aviation tighten operational efficiency requirements that modification programs must substantiate. Stakeholders must monitor evolving electromechanical certification standards and decide whether to pursue supplemental type certificate strategies or anchor on OEM-integrated forward-fit positions.
Market Dynamics
Electromechanical actuation architectures are forcing a wholesale redesign of high-lift control systems, compressing certification timelines and redistributing engineering value toward fault-tolerant electronics suppliers.
Growth Catalysts
- ICAO CORSIA compliance deadlines:Airlines retrofit narrow-body fleets with aerodynamic modifications to document verified emissions reductions and avoid offset purchase obligations.
- Composite skin adoption:Carbon fiber-reinforced polymer trailing edge assemblies reduce weight and extend fatigue life, accelerating replacement of aluminum heritage structures.
- United States MRO hub concentration:Major modification centers in Miami, Dallas-Fort Worth, and Los Angeles aggregate demand and standardize specification packages for global fleet operators.
Market Restraints
- Titanium and nickel alloy input volatility:Precision-actuated hinge fittings and flap track hardware face cost pressure from aerospace-grade metal supply constraints.
- European supplier concentration:Specialized composite manufacturing for high-lift surfaces clusters in France, Germany, and the United Kingdom, creating single-source exposure for amendment programs.
- Hydraulic legacy lock-in:Wide-body platforms certified before 2010 retain centralized hydraulic architectures that resist electromechanical retrofits without supplemental type certificate complexity.
Strategic Opportunities
- India domestic fleet expansion:Low-cost carriers operating Airbus A320neo and Boeing 737 MAX aircraft create forward-fit demand for OEM-integrated high-lift optimization.
- EU Green Deal aviation benchmarks:Modification subsidies and emissions-linked financing accelerate payback periods for aerodynamic retrofit investments.
- Digital twin convergence with CFD:Real-time flight data feeds back into computational fluid dynamics models, enabling continuous profile refinement without hardware changes.
Industry Challenges
- Electromechanical systems engineering talent scarcity:Fault-tolerant architecture design and DO-178C software certification expertise concentrates among defense-aerospace crossover engineers.
- Amended type certificate timeline compression:FAA and EASA flutter clearance and fatigue life extension analyses extend program schedules beyond airline fleet planning cycles.
- Heritage hydraulic-electromechanical integration:Mixed-architecture aircraft require custom control law development and pilot retraining protocols.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft High-Lift Device Aerodynamic Modification Systems Market Trends and Innovations
Computational methods and material science are converging to redefine how high-lift surfaces are designed, certified, and maintained across commercial aviation.
Shape memory alloy actuators are absorbing discrete hinge and linkage functions in next-generation trailing edge systems. Regional jet operators in North America pilot these mechanisms for reduced part count and simplified rigging protocols. The technology is absorbing maintenance budget allocations previously directed toward hydraulic line inspection and seal replacement.
EASA certification memoranda on electromechanical flight control integrity are mandating redundant channel architectures and failure probability thresholds. Amendment programs must now demonstrate 10^-9 catastrophic failure rates per flight hour through hardware-software co-verification. Narrow-body retrofit providers face the steepest compliance burden as they adapt civil derivatives of military actuator designs.
Airline engineering departments are unbundling modification specification from airframe OEM service bulletins. Low-cost carriers in Southeast Asia now contract directly with specialized aerodynamic firms for slat and flap profile optimization, bypassing traditional channel structures. This pattern concentrates most visibly in Indonesia and Vietnam where rapid fleet growth outpaces OEM field engineering capacity.
Aircraft High-Lift Device Aerodynamic Modification Systems Market Segmentation
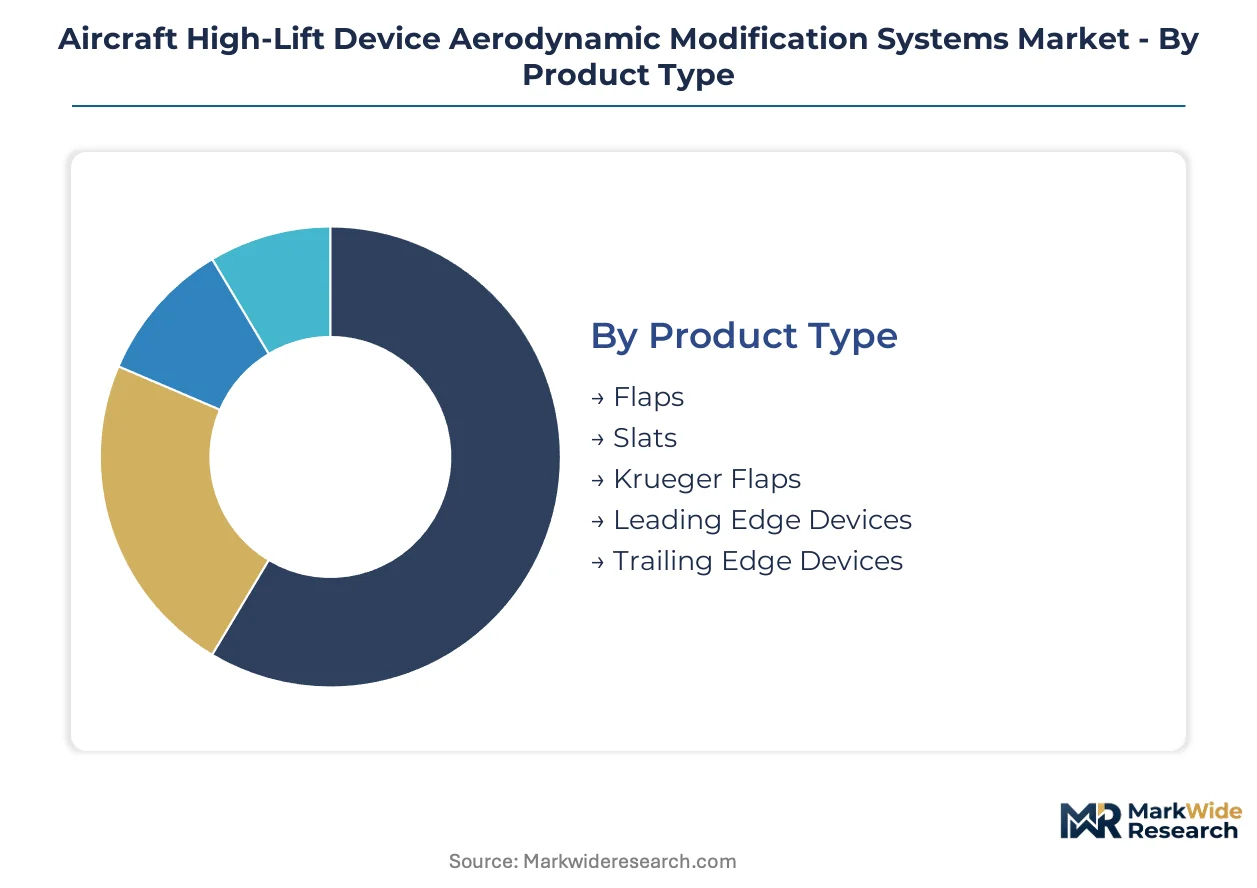
Aircraft high-lift device aerodynamic modification systems fragment across four structural dimensions. Each category channels engineering investment toward distinct certification pathways and margin pools. Understanding these partitions clarifies where specification power concentrates and where retrofit demand concentrates.
Product Type:
Supply concentration in trailing edge manufacturing has concentrated tier-one supplier relationships around Miami, Dallas-Fort Worth, and Los Angeles modification hubs.
- Flaps:Multi-segmented trailing edge surfaces deploy during takeoff and landing phases to expand wing camber and area. Airlines operating narrow-body Boeing 737 and Airbus A320 fleets in the United States prioritize flap retrofits for documented fuel burn reductions under FAA airworthiness directives.
- Slats:Extendable leading edge devices increase wing chord and delay stall onset at high angles of attack. European low-cost carriers retrofit slat systems to meet EU Green Deal aviation emissions benchmarks and secure emissions-linked financing.
- Krueger Flaps:Hinged leading edge panels that pivot forward and downward to increase camber on inboard wing sections.
- Leading Edge Devices:Encompass fixed and variable geometry surfaces that manage boundary layer behavior during low-speed flight.
- Trailing Edge Devices:Capture the largest retrofit volume as modification centers standardize specification packages for global fleet operators seeking takeoff and landing field performance gains.
Today's leader: Trailing Edge Devices. Tomorrow's challenger: Slats.
Technology:
Cost tier stratification separates military-grade hydraulic resilience from commercial electric efficiency mandates.
- Hydraulic Actuation:Centralized fluid power systems deliver high force density and battle damage tolerance. Military applications in the United States sustain hydraulic relevance where thermal extremes and combat survivability resist full electrification.
- Electric Actuation:Distributed motor-driven architectures eliminate hydraulic fluid lines and reduce maintenance burden. Commercial airlines retrofit narrow-body fleets with electric systems to document verified emissions reductions for ICAO CORSIA compliance.
- Pneumatic Actuation:Compressed air systems historically employed for de-icing and auxiliary functions.
- Mechanical Linkage:Cable and rod systems retain certification simplicity for legacy aircraft amendments.
- Electro-Mechanical Systems:Integrated motor-gearbox units with fault-tolerant electronics displace hydraulic architectures fastest, concentrating margin pools among suppliers certifying redundant channel architectures under amended type certificates.
Volume concentrates in Electro-Mechanical Systems. Certification complexity favors Electric Actuation for next-generation narrow-body platforms.
Application:
Customer type differentiation separates OEM forward-fit engineering from airline retrofit procurement cycles.
- Commercial Aircraft:Narrow-body and wide-body platforms dominate modification demand. United States-based MRO hubs aggregate specification development for global fleet operators seeking ICAO emissions compliance.
- Business Jets:Corporate operators prioritize discrete profile optimization without fleet-wide standardization.
- Military Aircraft:Battle damage tolerance requirements and thermal extremes sustain hydraulic architecture relevance.
- Cargo Planes:Freighter conversion programs integrate high-lift modifications for payload-range performance.
- Unmanned Aerial Vehicles:Emerging demand for automated deployment mechanisms in surveillance and logistics platforms.
Margin pools concentrate in Commercial Aircraft. Military Aircraft sustains hydraulic supplier relevance.
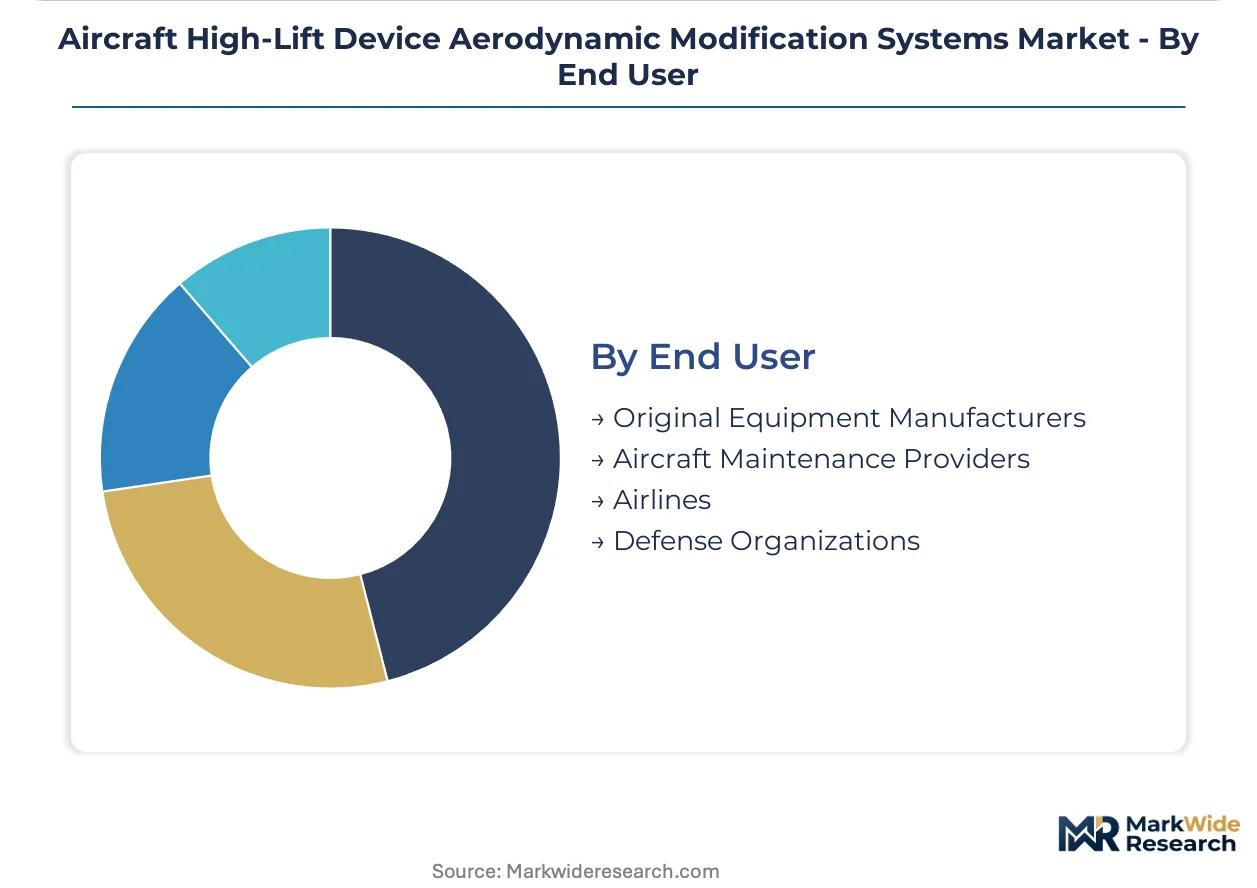
End User:
Procurement authority is shifting from OEM service bulletins toward direct airline engineering engagement.
- Original Equipment Manufacturers:Boeing and Airbus anchor forward-fit specification development. Their engineering centers in the United States and France drive certification standards that amendment programs must reference.
- Aircraft Maintenance Providers:Miami, Dallas-Fort Worth, and Los Angeles modification centers standardize retrofit packages.
- Airlines:Low-cost carriers in Southeast Asia now contract directly with specialized aerodynamic firms, bypassing traditional channel structures.
- Defense Organizations:Military procurement sustains hydraulic system demand through battle damage tolerance specifications.
Specification power rests with Original Equipment Manufacturers. Procurement volume is shifting toward Airlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing modification program engineering between jurisdictions with divergent certification cost structures. The FAA's amended type certificate pathways in the United States attract retrofit volume through streamlined flutter clearance protocols. European suppliers face margin compression from EASA's electromechanical integrity mandates while Asian MRO centers capture assembly work.
United States
Commercial airlines operating narrow-body fleets drive retrofit demand through Miami, Dallas-Fort Worth, and Los Angeles modification hubs. The FAA's continuous airworthiness directives reshape specification requirements for altered high-lift geometries. Engineering centers in Seattle and Wichita anchor OEM-integrated forward-fit development for Boeing platforms.
France
Safran's electromechanical actuation expertise concentrates design authority for Airbus-integrated systems in Toulouse and Paris-Saclay clusters. EASA certification memoranda on flight control integrity mandate redundant channel architectures that extend engineering timelines. The EU Green Deal's aviation emissions benchmarks tighten operational efficiency requirements for modification programs.
Germany
Lufthansa Technik anchors European MRO capacity for high-lift device overhaul and amendment in Hamburg. The country's national aviation regulator enforces fatigue life analysis standards that shape retrofit certification pathways. Composite manufacturing for flap track fairings clusters in Bavaria and Baden-Württemberg aerospace supplier networks.
United Kingdom
GKN Aerospace's composite flap track fairing production sustains British supply chain relevance despite post-Brexit regulatory divergence. The Civil Aviation Authority maintains bilateral recognition agreements with the FAA and EASA for modified type certificates. Bristol and Portsmouth engineering centers specialize in precision-actuated linkage manufacturing.
India
Low-cost carriers operating Airbus A320neo and Boeing 737 MAX aircraft create forward-fit demand for OEM-integrated high-lift optimization. The Directorate General of Civil Aviation aligns certification standards with ICAO emissions compliance frameworks. Bangalore and Hyderabad emerging as MRO assembly nodes for regional fleet modification programs.
Aircraft High-Lift Device Aerodynamic Modification Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-one suppliers anchoring electromechanical certification value while MRO integrators capture retrofit installation margin. The vendor base concentrates around three strategic archetypes: OEM-embedded engineering divisions, independent aerodynamic specialists, and composite structure fabricators. Consolidation pressure is intensifying as amended type certificate complexity forces smaller players toward partnership structures. Dominant competitive moves include vertical integration into fault-tolerant electronics supply and geographic expansion toward Asian MRO hubs.
Among OEM-embedded engineering divisions, Aviation Partners Boeing exemplifies the aerodynamic efficiency heritage archetype, extending blended winglet expertise into high-lift domains. GKN Aerospace and Safran occupy positions on opposite sides of the actuation technology divide, with the former anchoring composite structure supply chains and the latter representing electromechanical system integration depth. These three entities illustrate how certification authority and manufacturing scale separate premium-tier suppliers from retrofit-focused competitors.
| Leading Market Players |
|---|
| Aviation Partners Boeing |
| Lufthansa Technik |
| BASF Coatings |
| SACS Aerospace |
| MicroTau |
| GKN Aerospace |
| Spirit AeroSystems |
| Safran |
| Liebherr-Aerospace |
| Others |
Pricing and Supply Chain Analysis
Captive supply of titanium and nickel alloy hinge fittings anchors pricing power among United States-based electromechanical actuator suppliers serving FAA-certified amendment programs. This backward integration into precision aerospace metals buffers margin pools against raw material volatility while concentrating specification authority with tier-one vendors.
Pricing Analysis
Distributor margin compression runs through European composite flap track fairing supply chains as EASA electromechanical integrity mandates extend engineering timelines. Three-tier pricing structure separates fault-tolerant certified architectures from standard electric actuation and legacy hydraulic systems. Cost compression in standard-tier electric actuation is intensifying because low-cost Asian MRO centers aggregate volume for narrow-body retrofit programs. Low-cost carriers in Southeast Asia exhibit highest price sensitivity; defense organizations sustain lowest sensitivity due to battle damage tolerance specifications.
Supply Chain Analysis
Single-source vulnerability sits with French and German composite manufacturing clusters specialized in carbon fiber-reinforced polymer trailing edge assemblies. Raw material dependencies center on aerospace-grade titanium, nickel superalloys, and carbon fiber prepreg from Japan and the United States. Tariff exposure on precision-actuated components imported into India threatens regional fleet expansion timelines. Distribution runs through Miami, Dallas-Fort Worth, and Los Angeles modification hubs that standardize specification packages for global operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States streamlined flutter clearance protocols and European EASA electromechanical integrity timelines that compress supplier margins.
For Market Incumbents: Hedge against emerging entrant disruption in electromechanical fault-tolerant architecture supply by deepening backward integration into aerospace-grade titanium processing. Channel control through direct airline engineering engagement in Southeast Asia counters OEM service bulletin unbundling. Certification investment in DO-178C software expertise anchors amended type certificate authority. For New Entrants and Emerging Players: Regional jet operators in North America piloting shape memory alloy actuators represent the most penetrable buyer archetype for simplified rigging protocols. White-space targets include unmanned aerial vehicle automated deployment mechanisms and cargo plane freighter conversion programs. A direct-to-airline specification development model bypasses congested OEM field engineering capacity in Indonesia and Vietnam. For Investors and Strategic Acquirers: Roll-up economics work for specialized aerodynamic firms with amended type certificate portfolios because FAA-EASA regulatory divergence fragments certification authority across jurisdictions. Acquisition target archetypes include composite structure fabricators with captive supply of carbon fiber prepreg and electromechanical specialists with defense-aerospace crossover engineering talent. The signal to watch is airline engineering department unbundling acceleration from OEM service bulletins.| Strategic Initiative | Industry Significance |
|---|---|
| Fault-Tolerant Electronics Certification | DO-178C software verification anchors amended type certificate authority for narrow-body retrofits. |
| Backward Integration into Aerospace Metals | In-house titanium processing buffers margin pools against nickel alloy input volatility. |
| Direct Airline Engineering Engagement | Bypassing OEM service bulletins captures procurement volume shifting toward low-cost carriers. |
| Shape Memory Alloy Actuator Pilot Programs | Regional jet operators absorb maintenance budgets previously directed toward hydraulic line inspection. |
| Asian MRO Hub Geographic Expansion | Bangalore and Hyderabad assembly nodes capture forward-fit demand from India domestic fleet expansion. |
Research Methodology
Coverage spans the United States, France, Germany, the United Kingdom, and India, with primary inputs from each jurisdiction's regulatory and manufacturing clusters. Primary interviews with electromechanical systems engineers, FAA certification specialists, airline fleet planning directors, MRO procurement managers, and composite manufacturing executives combined with secondary validation from FAA airworthiness directives, EASA certification memoranda, ICAO CORSIA compliance frameworks, and SEC filings from tier-one suppliers. Bottom-up retrofit volume estimates triangulated against top-down OEM forward-fit projections.
Segmentation dimensions were modeled at product type, technology architecture, application platform, and end-user procurement authority levels across the projection horizon. CAGRs derived from fitted growth curves on documented emissions reduction requirements and fleet modernization cycles. Industry-specific forecast inputs include amended type certificate timeline distributions and electromechanical certification standard evolution trajectories.
Underlying measurement precision varies by segment; trailing edge device retrofit volume carries tighter precision than unmanned aerial vehicle emerging demand. Forecasts reflect assumptions on regulatory timeline adherence and material supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.