
 Battery Terminal Brushes Market | 2026-2036
Battery Terminal Brushes Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Terminal Brushes Market Insights
Fleet maintenance divisions are redrawing procurement patterns for battery terminal brushes as commercial transport operators prioritize preventive electrical maintenance over reactive replacement cycles. Lisle Corporation leverages its established distribution through automotive aftermarket channels to sustain visibility among professional mechanics. BrushTech USA specializes in coated brush configurations that address sulfation buildup without terminal abrasion. East Penn Manufacturing anchors supply relationships with battery OEMs, extending its reach into bundled maintenance kits.
Battery terminal brushes are handheld or powered implements designed to remove lead oxide corrosion, sulfation deposits, and electrolyte residue from lead-acid battery posts and cable clamps, typically employing brass or steel filaments with specified wire gauges to balance conductivity restoration against base metal damage. Manual brushes retain dominant volume share across price-sensitive automotive service bays, while powered brushes capture margin concentration in industrial forklift and heavy-equipment maintenance operations where labor cost reduction justifies equipment investment. Nylon variants are displacing metal filaments in marine applications where saltwater corrosion resistance determines tool longevity.
OSHA workplace safety standards and EPA hazardous waste handling rules directly shape product design requirements for insulated handles and debris containment in professional battery service environments. The EU REACH framework restricts certain plating chemistries in brush ferrules exported to European member states, compelling material specification adjustments for multinational suppliers. Stakeholders must monitor evolving right-to-repair legislation and battery recycling mandates, as these frameworks will determine whether terminal maintenance tools become standardized components of extended producer responsibility programs or remain discretionary aftermarket purchases.
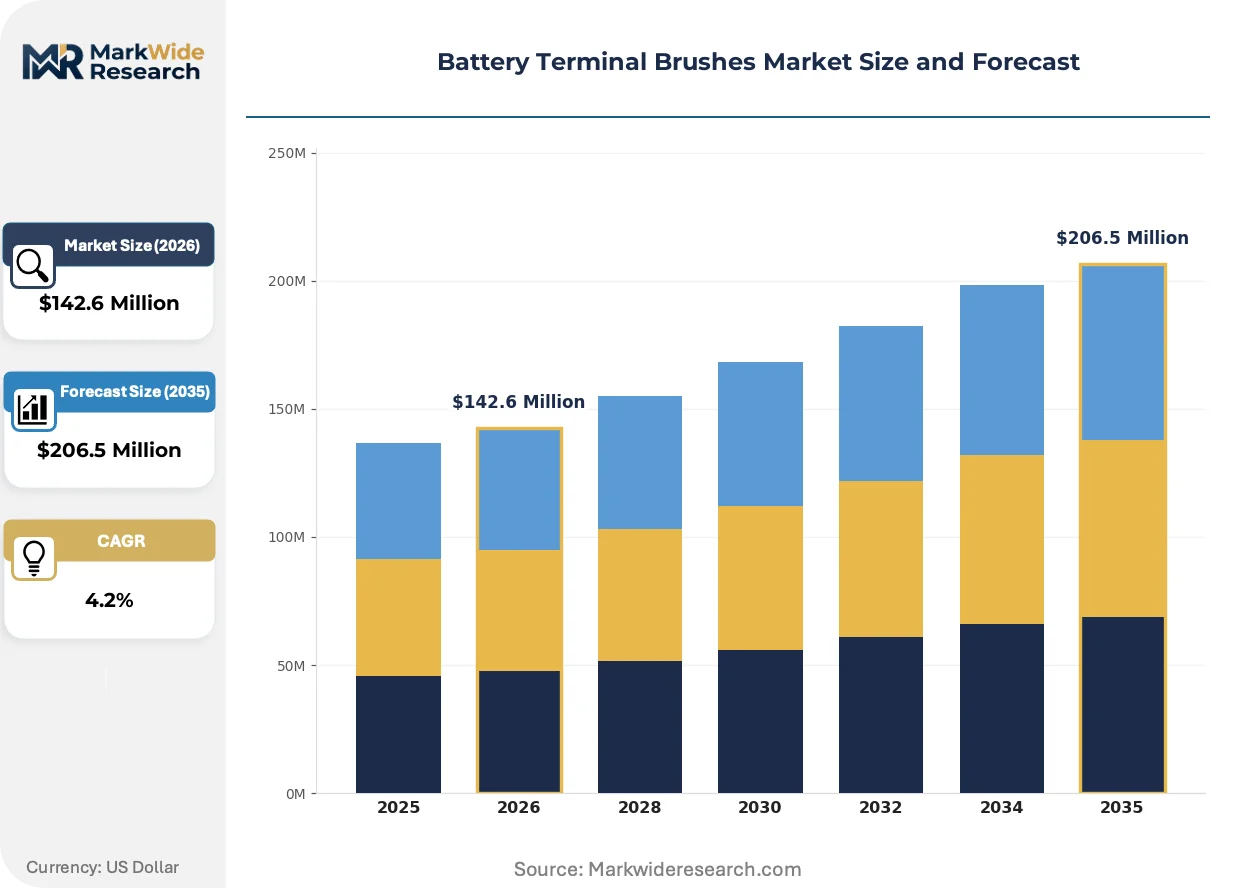
Market Dynamics
Fleet electrification timelines and tightening EPA corrosion-prevention mandates are compressing maintenance intervals across commercial transport, forcing tool procurement cycles to accelerate from reactive replacement toward preventive scheduling systems.
Growth Catalysts
- EPA Hazardous Waste Handling Rules:Professional battery service environments must deploy insulated-handle brushes with debris containment, expanding specification requirements for industrial-grade terminal cleaning tools.
- Marine Saltwater Corrosion Resistance:Nylon filament variants are capturing share in Gulf Coast and coastal Northeast servicing hubs where metal brush longevity collapses under electrolytic degradation.
- Powered System Adoption:Forklift fleet operators are converting manual brush inventories to powered terminal cleaning systems that compress labor hours per maintenance event.
Market Restraints
- Brass Filament Cost Volatility:Copper alloy input prices swing with commodity cycles, squeezing margin on professional-grade wire brush configurations.
- REACH Plating Chemistry Restrictions:EU ferrule plating specifications force material re-engineering for exports, fragmenting production runs.
- Disposable Wipe Substitution:Pre-saturated terminal cleaning pads threaten low-end manual brush volume in consumer automotive channels.
Strategic Opportunities
- Right-to-Repair Mandates:Pending state-level legislation in Minnesota and New York positions terminal brushes as standardized EPR kit components rather than discretionary aftermarket items.
- EV Battery Maintenance Protocols:High-voltage system safety training programs are creating demand for specialized insulated brush configurations in technician certification curricula.
- Direct Fleet Procurement Platforms:Commercial transport operators are bypassing traditional distributor networks through integrated maintenance software procurement modules.
Industry Challenges
- Technician Certification Timelines:OSHA electrical safety training requirements extend onboarding periods for battery service personnel, constraining field deployment velocity.
- Legacy Inventory Integration:Fleet maintenance software platforms require SKU rationalization that conflicts with existing multi-supplier brush specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Terminal Brushes Market |
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $206.5 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Brushes, Powered Brushes, Specialty Brushes, Coated Brushes Material: Metal, Nylon, Brass, Steel End User: Automotive, Industrial, Marine, Residential Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Lisle Corporation, K-D Tools, BrushTech USA, EZ Red, East Penn Manufacturing, PLP Battery Supply, Deagia, JB Tools, CRC Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Terminal Brushes Market Trends and Innovations
Terminal brush design is pivoting toward conductivity restoration without base metal abrasion, driven by thinner battery post specifications in start-stop automotive systems and lithium-lead hybrid architectures.
Coated filament technology is miniaturizing. Micro-layered polymer coatings on brass cores remove sulfation without scoring lead terminals, preserving post integrity across extended charge cycles. Tier-1 automotive service chains are specifying these configurations for warranty-sensitive battery replacements. The technology is miniaturizing brush head geometries for confined-space engine compartments while maintaining debris extraction efficiency.
OSHA workplace safety standards are tightening handle insulation and spark-resistance specifications for professional battery service environments. Tool manufacturers must certify to updated electrical protection categories, adding testing overhead but creating specification barriers against unqualified imports. Industrial forklift maintenance divisions are absorbing these compliance costs faster than independent automotive service bays.
Buyer concentration among national fleet operators is consolidating procurement authority away from regional distributors. Large commercial transport groups now specify terminal brushes through centralized maintenance software that ties inventory to vehicle telematics-triggered service intervals. This pattern concentrates most visibly across Midwest automotive manufacturing corridors where integrated fleet management platforms have achieved deepest penetration.
Battery Terminal Brushes Market Segmentation
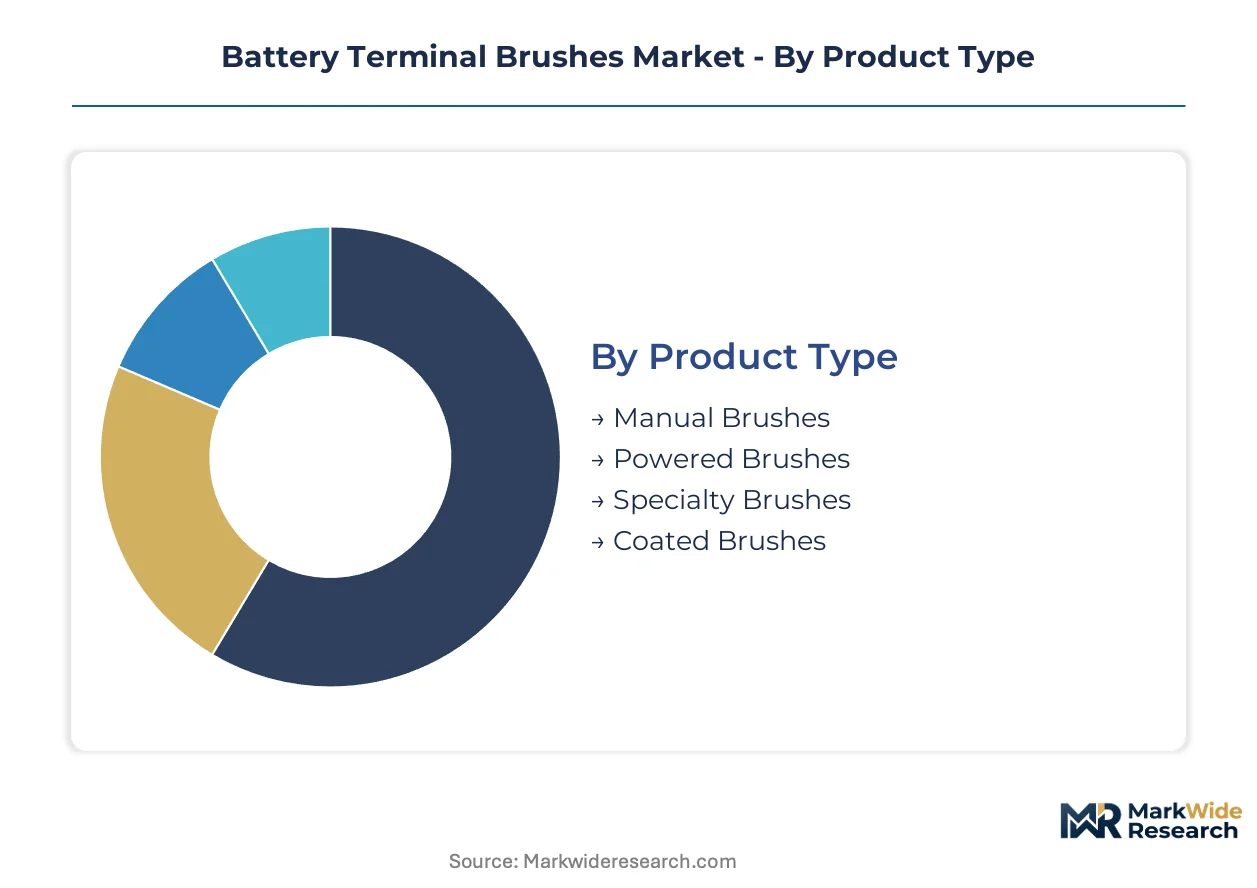
Battery terminal brush procurement patterns diverge sharply across product configurations and end-use environments. Understanding these divides clarifies where substitute threats concentrate and where specification requirements create defensive moats.
Product Type:
Disposable wipe substitution pressures vary dramatically by product category, with low-complexity manual formats facing the most acute threat from pre-saturated terminal cleaning pads.
- Manual Brushes:Handheld implements with brass or steel filaments dominate automotive service bays where price sensitivity overrides labor efficiency concerns. Fleet maintenance divisions across Midwest automotive manufacturing corridors sustain volume through bulk procurement, though consumer channels face accelerating wipe substitution.
- Powered Brushes:Motorized terminal cleaning systems compress maintenance intervals for forklift fleets and heavy-equipment operators. Gulf Coast marine servicing hubs are piloting battery-powered variants that reduce technician exposure to corrosive residue in confined engine compartments.
- Specialty Brushes:Configurations for lithium-lead hybrid architectures and high-voltage EV systems require insulated handle specifications under OSHA electrical safety standards.
- Coated Brushes:Micro-layered polymer coatings on brass cores address sulfation without terminal abrasion, capturing specification mandates from Tier-1 automotive service chains.
Manual brushes retain volume leadership; powered brushes hold the steepest expansion curve.
Material:
Material selection tracks directly against corrosion environment severity, with saltwater exposure driving the most pronounced specification shifts.
- Metal:Traditional brass and steel filaments deliver conductivity restoration for standard lead-acid terminals. EPA hazardous waste handling rules now mandate debris containment accessories for professional service environments using metal configurations.
- Nylon:Synthetic filaments resist electrolytic degradation in coastal Northeast servicing hubs where saltwater corrosion collapses metal brush longevity. Marine applications are consolidating procurement around nylon variants despite higher unit costs.
- Brass:Copper alloy filaments balance conductivity against base metal damage, though commodity price volatility squeezes margin on professional-grade configurations.
- Steel:Higher-gauge steel wire addresses heavy sulfation buildup in industrial forklift maintenance, where terminal replacement costs justify aggressive cleaning protocols.
Metal configurations dominate current procurement volumes; nylon is climbing the fastest as marine specification standards tighten.
End User:
End-user concentration reflects divergent maintenance interval pressures, with commercial transport fleets compressing schedules most aggressively.
- Automotive:Start-stop system proliferation is thinning battery post specifications, driving demand for coated filament configurations that preserve terminal integrity. Service chains specify these for warranty-sensitive replacements.
- Industrial:Forklift fleet operators are converting manual brush inventories to powered systems that reduce labor hours per maintenance event. OSHA electrical safety training requirements extend technician onboarding periods.
- Marine:Saltwater corrosion resistance determines tool longevity in Gulf Coast hubs, where nylon variants are displacing metal filaments despite premium pricing.
- Residential:Consumer automotive channels face the strongest pre-saturated wipe substitution, constraining manual brush volume in price-sensitive DIY segments.
Automotive retains volume leadership; marine holds the steepest expansion curve.
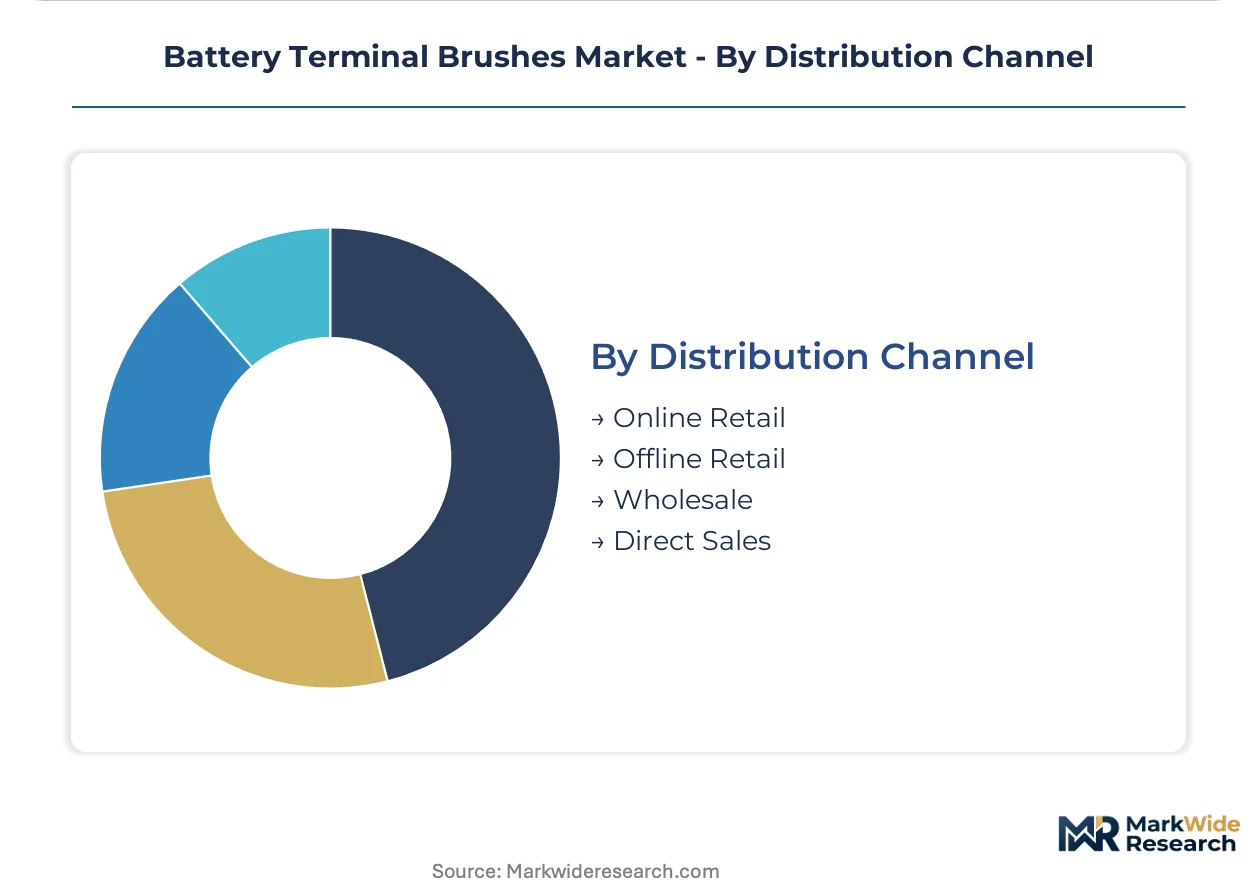
Distribution Channel:
Channel configuration is shifting as fleet procurement authority consolidates away from regional distributor networks.
- Online Retail:E-commerce platforms capture residential and small independent service bay demand, particularly for standardized manual brush specifications with visible customer ratings.
- Offline Retail:Brick-and-mortar automotive parts stores sustain visibility for emergency replacement purchases, though shelf space is contracting as wipes expand.
- Wholesale:Regional distributors retain fragmented automotive service bay relationships, facing pressure from direct fleet procurement platforms.
- Direct Sales:National fleet operators now specify terminal brushes through centralized maintenance software tying inventory to vehicle telematics-triggered service intervals.
Wholesale retains volume leadership; direct sales holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet maintenance divisions at commercial transport operators concentrate procurement authority in the United States, particularly across Midwest automotive manufacturing corridors and Gulf Coast marine servicing hubs, while regulatory divergence shapes specification requirements across major economies.
United States
Midwest automotive manufacturing corridors anchor domestic demand as fleet operators convert manual brush inventories to powered terminal cleaning systems. EPA hazardous waste handling rules mandate insulated-handle configurations with debris containment for professional battery service environments. Gulf Coast marine servicing hubs pilot nylon filament variants that resist saltwater electrolytic degradation in confined engine compartments.
Germany
Industrial forklift maintenance operations drive specification standards for coated filament technology that removes sulfation without scoring lead terminals. EU REACH framework restrictions on brush ferrule plating chemistries compel material re-engineering for domestic production runs. Baden-Württemberg automotive service chains specify micro-layered polymer configurations for warranty-sensitive battery replacement protocols.
China
Domestic battery OEM supply relationships extend into bundled maintenance kit configurations for aftermarket distribution. GB standards and MIIT industrial safety protocols shape insulated handle specifications for high-voltage system maintenance training programs. Yangtze River Delta manufacturing clusters concentrate export-oriented production of brass and steel filament configurations.
Japan
Start-stop automotive system proliferation drives demand for terminal brushes that preserve thinned battery post integrity across extended charge cycles. METI energy efficiency directives and JIS standards influence professional-grade tool certification requirements. Kansai region automotive service networks specify coated brush geometries for confined-space engine compartment access.
India
Commercial transport fleet expansion accelerates preventive maintenance scheduling systems over reactive replacement cycles. BIS quality certification requirements and state-level right-to-repair legislative developments position terminal brushes as standardized extended producer responsibility components. Maharashtra automotive manufacturing corridors concentrate procurement relationships with battery OEM maintenance kit bundling.
Battery Terminal Brushes Market Competitive Landscape
Player mix skews toward specialized tool fabricators with established automotive aftermarket distribution relationships rather than diversified industrial conglomerates. The vendor base organizes around three strategic archetypes: legacy automotive tool specialists with generational brand recognition, battery OEM-integrated suppliers leveraging bundled kit relationships, and regional fabricators serving price-sensitive service bay segments. Competitive positioning depends on M&A activity consolidating regional distributor networks and strategic partnerships embedding terminal brushes into fleet maintenance software procurement modules.
Within the legacy automotive tool tier, Lisle Corporation exemplifies distribution-centric positioning through professional mechanic channels, while BrushTech USA occupies a specialization niche around coated brush configurations. East Penn Manufacturing anchors the battery OEM-integrated archetype through bundled maintenance kit relationships. These three entities collectively represent the competitive structure: distribution scale, technical specialization, and vertical integration into battery manufacturer supply chains.
| Leading Market Players |
|---|
| Lisle Corporation |
| K-D Tools |
| BrushTech USA |
| EZ Red |
| East Penn Manufacturing |
| PLP Battery Supply |
| Deagia |
| JB Tools |
| CRC Industries |
| Others |
Pricing and Supply Chain Analysis
Nylon filament substitution for brass and steel cores is redrawing procurement geography toward coastal Southeast Asian manufacturing clusters while simultaneously compressing margin structures on legacy metal configurations. This material transition simultaneously elevates unit economics for corrosion-resistant variants and erodes pricing power for commodity-grade brushes in price-sensitive automotive service channels.
Pricing Analysis
Current-generation coated filament brushes command premium positioning against prior-generation uncoated metal configurations, while next-generation battery-powered systems occupy the top tier. Three-tier pricing structure across premium, standard, and economy levels separates OSHA-certified insulated-handle systems from professional-grade manual brushes and consumer disposable formats. Cost compression in economy-tier manual brushes is intensifying because pre-saturated wipe substitution accelerates in DIY channels. Fleet procurement divisions exhibit lowest price sensitivity due to telematics-integrated maintenance scheduling, while independent automotive service bays retain acute cost consciousness.
Supply Chain Analysis
Inventory cycles for brass filament stock extend lead times during copper commodity volatility periods, forcing manufacturers to hold buffer positions. Manufacturing concentration centers on China for brass and steel filament production, Vietnam for nylon synthetic extrusion, and the United States for final assembly of OSHA-certified insulated-handle configurations. Raw material sourcing draws from Chilean copper concentrates, Saudi petrochemical feedstocks for nylon polymers, and domestic steel wire from Midwest mills. Single-source vulnerability concentrates in coated filament polymer chemistry suppliers. Distribution runs through integrated fleet maintenance software platforms that disintermediate traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among national fleet operators deploying centralized procurement platforms, fragmenting negotiating leverage for regional distributors and independent service channels.
For Market Incumbents: Secure specification mandates from Tier-1 automotive service chains before coated filament technology commoditizes, and anchor supply relationships with battery OEM maintenance kit bundling to defend against direct fleet procurement bypass. Brass filament cost volatility threatens margin stability; backward integration into captive wire drawing capacity insulates against commodity swings. For New Entrants and Emerging Players: OSHA electrical safety certification fast-tracks market access for insulated-handle configurations targeting forklift fleet operators converting from manual systems. Marine servicing hubs along the Gulf Coast present the most penetrable white-space segment, as saltwater corrosion resistance specifications displace incumbent metal suppliers. Direct sales through fleet maintenance software procurement modules offers the clearest go-to-market path. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized tool fabricators with established automotive aftermarket distribution relationships over diversified industrial conglomerates. Five-to-ten year viability hinges on embedded positioning within extended producer responsibility frameworks and right-to-repair legislative developments. Signal to monitor: state-level EPR mandate adoption rates that would standardize terminal brushes as mandatory kit components rather than discretionary purchases.| Strategic Initiative | Industry Significance |
|---|---|
| Coated Filament Technology Scale-Up | Micro-layered polymer configurations capture Tier-1 automotive warranty-sensitive replacement specifications. |
| Battery OEM Kit Bundling Partnership | Vertical integration into East Penn Manufacturing supply chains locks in recurring aftermarket volume. |
| Fleet Software Procurement Integration | API connectivity with telematics-triggered maintenance platforms concentrates procurement authority. |
| OSHA Certification Investment | Insulated-handle specifications create specification barriers against unqualified import competition. |
| Marine Nylon Variant Production | Saltwater corrosion resistance addresses Gulf Coast hub demand collapse for metal filament longevity. |
Research Methodology
Desk research of customs trade databases, SEC equipment supplier filings, and EPA hazardous waste handling guidance preceded structured interviews with fleet maintenance directors, automotive aftermarket distributors, battery OEM procurement managers, and industrial safety compliance officers. Primary fieldwork with forklift fleet operators and marine servicing technicians validated secondary estimates of powered system adoption rates. Bottom-up unit economics modeling triangulated against top-down market sizing from equipment supplier revenue disclosures.
Variance decomposition across product type, material composition, end-use vertical, and distribution channel segments drove analytical framework construction throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against aggregate market trajectory. Industry-specific inputs included fleet electrification timelines, EPA corrosion-prevention mandate compliance deadlines, and right-to-repair legislative tracking across Minnesota and New York statehouses.
Underlying assumptions cover fleet maintenance software platform penetration rates and coated filament technology cost curves, with deviation risk concentrated in brass commodity price volatility and REACH plating chemistry restriction expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Residential Battery Market
Batteries
Lithium Pouch Cell Market
Batteries
Sweden Rechargeable Battery Market
Batteries
Home Inverter Battery Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
Micro Battery Market
Batteries
Seawater Battery Market
Batteries
Taiwan Battery Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Secondary Battery Market
Batteries
Sodium-Air Battery Market
Batteries
Floor Scrubber Battery Market
Batteries
USA Forklift Battery Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Bio Based Battery Market