
 Global Infertility Drugs Market | 2026-2036
Global Infertility Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Infertility Drugs Market Foresight
ISO 13485 certification for medical device and pharmaceutical quality management is collapsing the supplier base for active pharmaceutical ingredient manufacturers serving fertility drug formulators. Merck KGaA leverages its integrated gonadotropin production network from recombinant DNA fermentation through finished vial packaging. Ferring Pharmaceuticals anchors its position through specialized peptide hormone synthesis capabilities in Europe. Pfizer Inc. competes via broad distribution infrastructure that reaches hospital pharmacies and specialty distributors across multiple continents.
Infertility drugs comprise synthetic and recombinant hormonal agents that modulate the hypothalamic-pituitary-gonadal axis to induce ovulation, support luteal function, or enhance spermatogenesis, with formulations typically requiring cold-chain storage between 2°C and 8°C to preserve protein bioactivity. Gonadotropins command the largest revenue share among product types due to their essential role in controlled ovarian hyperstimulation protocols for in vitro fertilization cycles. Fertility clinics represent the fastest-expanding end-user channel as these centers vertically integrate dispensing functions to capture margin and ensure protocol adherence. Online pharmacies are displacing retail pharmacy volume for maintenance prescriptions of oral agents such as clomiphene citrate and letrozole.
FDA oversight of reproductive toxicology studies and EMA's centralized marketing authorization procedure govern clinical development pathways, while the EU MDR imposes strengthened post-market surveillance obligations on combination drug-device fertility products. The NMPA's accelerated review pathway for biologics is reshaping where sponsors initiate first-in-human gonadotropin trials. Stakeholders must monitor evolving payer policies for pharmacological infertility treatment as public and private reimbursement decisions increasingly mandate documented failure of drug therapy before covering assisted reproductive technology procedures.
Market Dynamics
Controlled ovarian hyperstimulation protocols are reshaping pharmaceutical procurement patterns as fertility clinics consolidate dispensing functions to capture margin and enforce protocol adherence. The shift toward clinic-based medication management is compressing traditional pharmacy channels and altering how gonadotropin manufacturers structure their distribution contracts.
Growth Catalysts
- Reimbursement mandates:United States private payers increasingly require documented pharmacological failure before authorizing assisted reproductive technology coverage, extending drug therapy duration and prescription volumes.
- EMA-FDA-NMPA harmonization:Reciprocal clinical trial data acceptance is collapsing multi-regional study timelines and accelerating ovulation-inducing agent approvals across jurisdictions.
- Fertility clinic verticalization:Reproductive endocrinology networks are integrating in-house pharmacies to ensure cold-chain integrity and protocol compliance, creating captive demand channels.
Market Restraints
- Recombinant protein input concentration:Active pharmaceutical ingredient production for gonadotropins concentrates among ISO 13485-certified fermentation facilities in Germany and Switzerland, creating supply vulnerability.
- Cold-chain infrastructure gaps:Temperature-controlled distribution between 2°C and 8°C remains underdeveloped across Sub-Saharan Africa and parts of Southeast Asia, limiting market access.
- Oral agent substitution:Generic letrozole and clomiphene citrate formulations are capturing first-line ovulation induction cases that previously advanced directly to injectable gonadotropins.
Strategic Opportunities
- Brazil regulatory acceleration:ANVISA's streamlined biologics pathway offers sponsors an alternative first-in-human trial jurisdiction outside traditional FDA-EMA sequences.
- Online pharmacy channel expansion:Maintenance prescriptions for oral fertility agents are migrating to telehealth-integrated dispensers, bypassing traditional retail pharmacy networks.
- Peptide synthesis convergence:Specialized hormone manufacturing capabilities in European contract development organizations are enabling novel luteal support formulations.
Industry Challenges
- Reproductive toxicology specialist scarcity:FDA-mandated preclinical fertility studies require qualified investigators experienced in embryofetal development assessment, constraining trial initiation capacity.
- EU MDR compliance timeline:Combination drug-device fertility products face strengthened post-market surveillance obligations and notified body re-certification backlogs.
- Legacy ERP integration:Fertility clinic networks acquiring independent practices encounter incompatible inventory management systems for temperature-sensitive biologics tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Infertility Drugs Market |
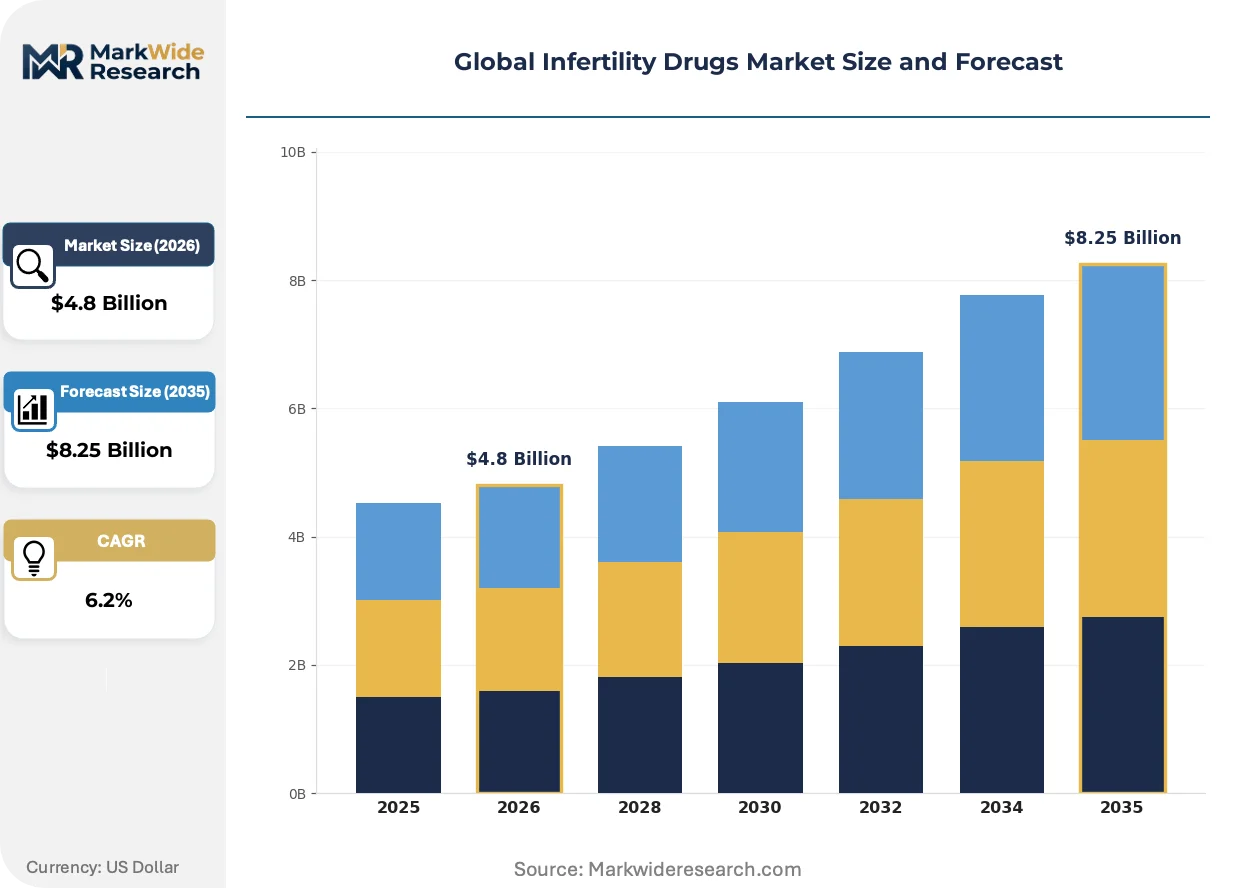
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clomiphene Citrate, Gonadotropins, Letrozole, Metformin, Bromocriptine Therapy Area: Ovulation Induction, Controlled Ovarian Hyperstimulation, Luteal Phase Support, Male Infertility, Endometriosis Management End User: Fertility Clinics, Gynecology Centers, Reproductive Endocrinologists, Assisted Reproductive Technology Labs Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Specialty Distributors |
| Companies Covered | Merck KGaA, Ferring Pharmaceuticals, Bayer AG, Pfizer Inc., Organon & Co., Novartis AG, Abbott Laboratories, Teva Pharmaceutical Industries Ltd., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Infertility Drugs Market Shifts & Advancements
Biosimilar gonadotropin development, regulatory data reciprocity expansion, and channel consolidation are restructuring competitive positioning across the infertility therapeutics landscape. These forces are compressing pricing power for originator molecules while elevating manufacturing quality standards.
Recombinant follicle-stimulating hormone biosimilars are supplanting originator gonadotropins in European tenders and United States group purchasing organization contracts. Fertility clinics in Germany and the Netherlands are adopting these alternatives to manage pharmacy budgets without protocol modification. The substitution is compressing revenue per stimulation cycle for established recombinant manufacturers while expanding addressable patient volumes.
EMA's centralized marketing authorization procedure now accepts FDA reproductive toxicology study packages without redundant European animal testing, collapsing parallel submission timelines by twelve to eighteen months. Sponsors are restructuring clinical development strategies to sequence United States filings before European applications. This regulatory convergence most benefits mid-cap peptide hormone developers lacking legacy multi-regional infrastructure.
Specialty distributors are losing fertility drug volume to clinic-integrated dispensing as reproductive endocrinology networks consolidate procurement under single pharmacy licenses. Hospital-affiliated fertility centers in Spain and Australia are capturing margin previously allocated to wholesale channels. The channel compression is most advanced in metropolitan markets with concentrated clinic networks and favorable self-dispensing regulations.
Global Infertility Drugs Market Segmentation
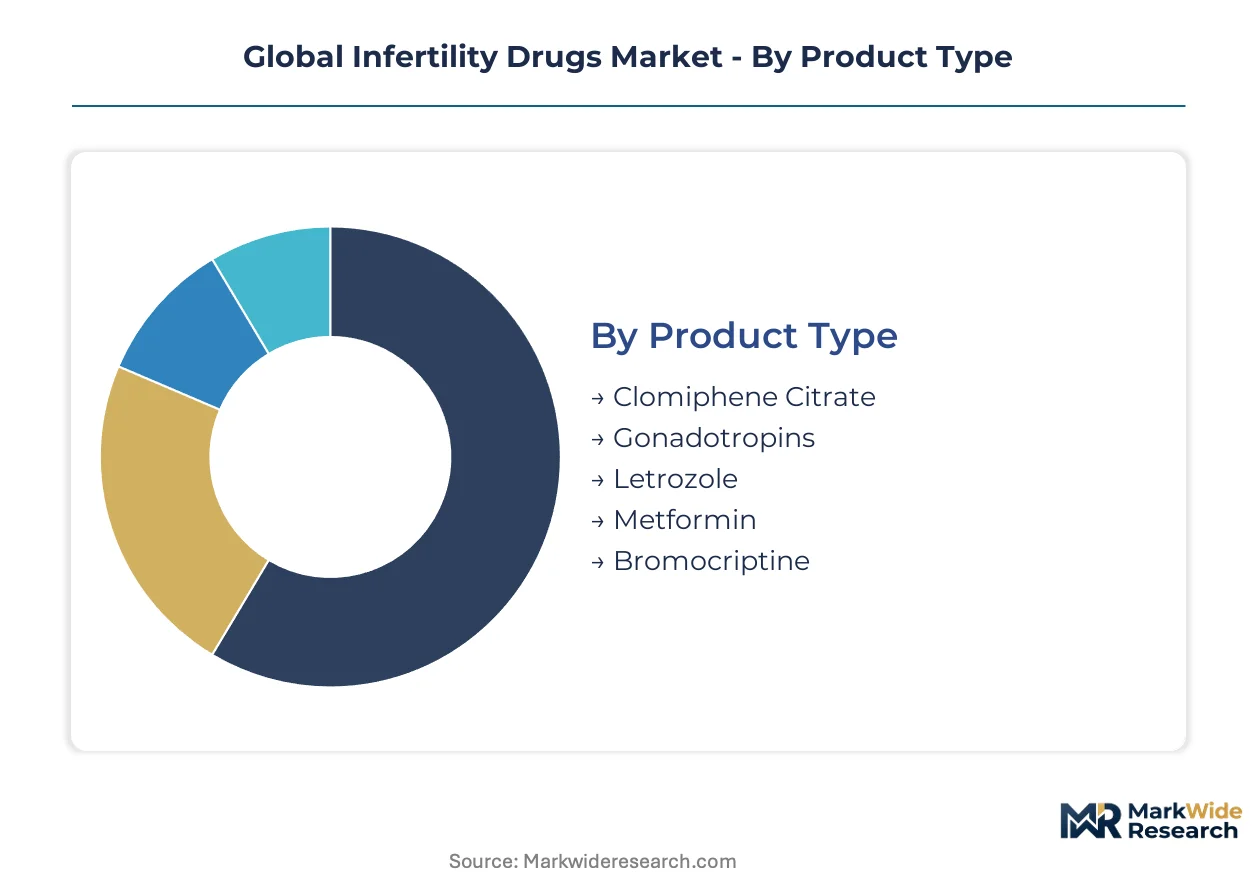
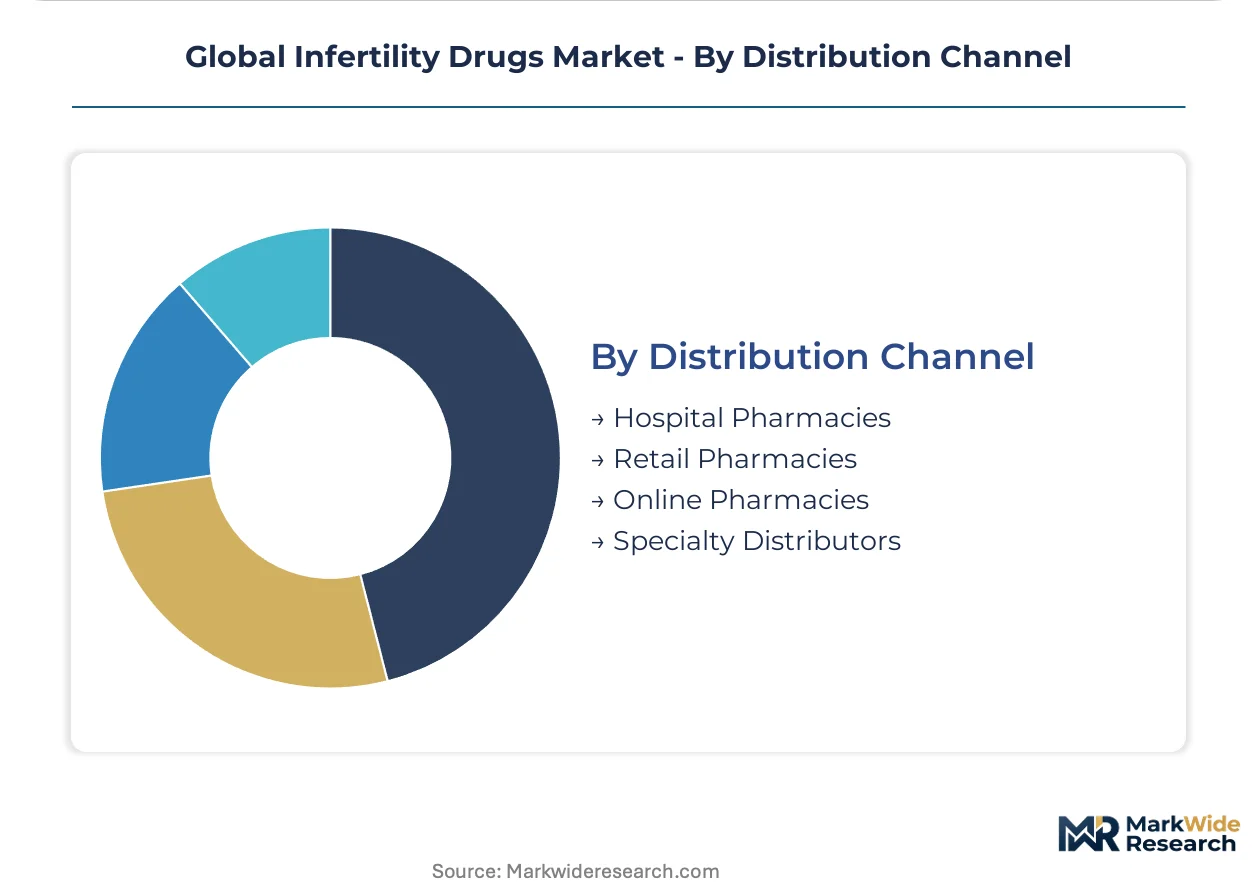
Infertility drugs span hormonal mechanisms, therapeutic protocols, and dispensing channels that each concentrate value differently across geographies. Understanding where demand clusters by product chemistry versus where procurement consolidates by channel reveals how manufacturers must align formulation investments with distribution reach.
Product Type:
Domestic formulation dominates oral agents with localized generic manufacturing, while recombinant biologics concentrate production in ISO-certified European fermentation facilities for worldwide export.
- Gonadotropins:Recombinant follicle-stimulating hormone and luteinizing hormone formulations derived from DNA fermentation require cold-chain distribution between 2°C and 8°C. Demand concentrates in fertility clinics across the United States and Germany where controlled ovarian hyperstimulation protocols are standard before assisted reproductive technology procedures.
- Clomiphene Citrate:Oral selective estrogen receptor modulator tablets manufactured through synthetic organic chemistry routes. Prescription volume clusters in India and Brazil where first-line ovulation induction therapy is accessed through retail pharmacy networks before specialist referral.
- Letrozole:Aromatase inhibitor tablets increasingly prescribed off-label for ovulation induction in polycystic ovary syndrome patients.
- Metformin:Biguanide oral agent addressing insulin resistance in infertility associated with metabolic syndrome.
- Bromocriptine:Dopamine agonist tablets suppressing prolactin secretion in hyperprolactinemic amenorrhea cases.
Gonadiprotropins command the established base. The steepest expansion runs through letrozole as off-label prescribing protocols widen.
Therapy Area:
Cost tier stratification separates high-expense injectable protocols from maintenance oral therapies, with reimbursement thresholds determining patient progression between stages.
- Controlled Ovarian Hyperstimulation:Injectable gonadotropin protocols stimulating multiple follicular development for in vitro fertilization retrieval cycles. United States fertility clinic networks drive volume where private payer mandates require documented pharmacological failure before assisted reproductive technology authorization.
- Ovulation Induction:Oral or low-dose injectable regimens restoring monofollicular ovulation in anovulatory disorders. Demand spreads across India's gynecology centers and Spain's public hospital fertility units where clomiphene citrate remains first-line before gonadotropin escalation.
- Luteal Phase Support:Progesterone supplementation protocols maintaining endometrial receptivity after ovulation or embryo transfer.
- Male Infertility:Hormonal and antioxidant therapies addressing spermatogenic dysfunction or hypogonadotropic hypogonadism.
- Endometriosis Management:Gonadotropin-releasing hormone agonists and antagonists suppressing estrogen-driven disease progression.
Controlled ovarian hyperstimulation captures the revenue concentration. Ovulation induction is climbing the fastest as diagnostic access expands in middle-income markets.
End User:
Customer type fragmentation splits between integrated dispensing networks capturing margin and independent practices reliant on external pharmacy fulfillment.
- Fertility Clinics:Specialized reproductive medicine centers vertically integrating in-house pharmacies to ensure cold-chain integrity and protocol adherence. Volume concentrates in United States metropolitan networks and Australian capital city chains where self-dispensing regulations permit margin capture.
- Reproductive Endocrinologists:Individual specialist practices referring patients to external pharmacies for medication fulfillment. These providers dominate Japan's fragmented fertility care structure where clinic-based dispensing faces regulatory constraints.
- Gynecology Centers:General obstetrics practices providing initial infertility evaluation and oral agent prescription before specialist referral.
- Assisted Reproductive Technology Labs:Embryology facilities coordinating medication timing with oocyte retrieval and embryo transfer schedules.
Fertility clinics command the established base. Reproductive endocrinologists in regulated markets show the steepest expansion trajectory as telehealth integration extends their reach.
Distribution Channel:
Supply concentration in specialty cold-chain distributors is fragmenting as clinic networks internalize fulfillment and online platforms capture oral maintenance prescriptions.
- Specialty Distributors:Temperature-controlled logistics providers handling gonadotropin shipments from manufacturer to fertility clinic. McKesson and Alliance Healthcare maintain dominance in United States and United Kingdom markets where 2°C to 8°C chain validation is mandatory.
- Online Pharmacies:Telehealth-integrated dispensers shipping oral agents directly to patients for maintenance therapy. Expansion concentrates in Germany and the Netherlands where electronic prescription systems enable seamless fulfillment.
- Hospital Pharmacies:Institutional dispensers serving academic medical center fertility units with formulary-controlled procurement.
- Retail Pharmacies:Community dispensers handling initial clomiphene citrate and letrozole prescriptions before specialist referral.
Specialty distributors command the established base for biologics. Online pharmacies are gaining share fastest for oral agent maintenance therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement mandates in the United States now require documented pharmacological failure before assisted reproductive technology coverage, extending prescription durations for ovulation-inducing agents. Germany's EMA-aligned centralized marketing authorization accelerates gonadotropin approvals across the European Union. India's CDSCO is streamlining biologics pathways to expand domestic access to recombinant fertility hormones.
United States
Private payer pre-authorization protocols now mandate sequential drug therapy before in vitro fertilization coverage, driving extended clomiphene citrate and letrozole prescription cycles. FDA reproductive toxicology guidelines govern all preclinical gonadotropin development, with investigators concentrated in Boston and San Diego research clusters. Fertility clinic networks in New York and Los Angeles have vertically integrated in-house pharmacies to capture dispensing margins and ensure cold-chain protocol adherence.
Germany
EMA centralized marketing authorization enables simultaneous EU-wide gonadotropin launches, collapsing parallel national approval timelines. The country's national pharmaceutical regulator maintains ISO 13485 certification requirements for all recombinant hormone fermentation facilities. Manufacturing clusters in Bavaria and Baden-Württemberg host specialized peptide synthesis contract development organizations serving European fertility drug formulators.
China
NMPA's accelerated biologics review pathway is attracting sponsors to initiate first-in-human gonadotropin trials domestically rather than sequencing through FDA-EMA sequences first. The national medical products administration mandates cold-chain validation for all temperature-sensitive fertility drug shipments. Reproductive medicine centers in Shanghai and Beijing are expanding pharmacological treatment protocols as first-line interventions before assisted reproductive technology procedures.
India
CDSCO streamlined approval processes for recombinant hormones are expanding domestic manufacturing capacity for export to Southeast Asian and African markets. The central drugs standard control organization requires local clinical trial data for gonadotropin registrations despite increasing data reciprocity negotiations. Gynecology centers in Maharashtra and Karnataka drive clomiphene citrate volume through retail pharmacy networks before specialist referral for injectable protocols.
Brazil
ANVISA's streamlined biologics pathway offers sponsors an alternative first-in-human trial jurisdiction outside traditional FDA-EMA regulatory sequences. The national health surveillance agency mandates temperature-controlled distribution documentation for all imported fertility medications. Fertility clinics in São Paulo and Rio de Janeiro are consolidating procurement under single pharmacy licenses to capture margin previously allocated to wholesale distribution channels.
Global Infertility Drugs Market Competitive Landscape
Player mix skews toward integrated biopharmaceutical conglomerates with recombinant protein manufacturing capabilities and specialized peptide hormone developers with European synthesis expertise. Market structure concentrates among ISO 13485-certified fermentation facilities in Germany and Switzerland, with secondary formulation capabilities distributed across North American and Asian contract manufacturers. Three strategic archetypes dominate: vertically integrated gonadotropin producers controlling recombinant DNA fermentation through finished vial packaging, specialized peptide hormone synthesis houses with luteal support formulation expertise, and broad-distribution pharmaceutical conglomerates leveraging hospital pharmacy and specialty distributor reach. Competitive dynamics center on regulatory data reciprocity exploitation and fertility clinic dispensing channel capture.
Within the integrated biopharmaceutical tier, Merck KGaA exemplifies the archetype of recombinant gonadotropin production spanning DNA fermentation through finished packaging. Ferring Pharmaceuticals occupies a position among specialized European peptide hormone synthesis houses with concentrated luteal support capabilities. Pfizer Inc. represents the broad-distribution conglomerate archetype, leveraging continental hospital pharmacy and specialty distributor infrastructure across multiple therapeutic areas including fertility. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Merck KGaA |
| Ferring Pharmaceuticals |
| Bayer AG |
| Pfizer Inc. |
| Organon & Co. |
| Novartis AG |
| Abbott Laboratories |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi |
| Others |
Supply & Pricing Matrix
Fermentation capacity utilization above 85 percent in Bavarian and Baden-Württemberg facilities creates natural supply concentration that protects price floors for recombinant gonadotropins while compressing margins for oral generics manufactured at sub-scale Indian and Chinese tablet plants. This scale asymmetry rewards ISO 13485-certified biologics producers with pricing power tied to cold-chain validation, while forcing commodity oral manufacturers into volume-based competition without quality differentiation.
Pricing Analysis
Certification level creates the primary spread between premium recombinant biologics and economy oral agents, with FDA-grade gonadotropins commanding substantial premiums over CE-marked biosimilars and unbranded clomiphene citrate. Three-tier pricing structure across premium, standard, and economy levels reflects cold-chain compliance investment, with fertility clinic networks least price-sensitive due to captive margin capture and retail pharmacy channels most sensitive due to generic substitution. Cost compression in oral segments is intensifying because Indian CDSCO accelerated approvals flooded markets with letrozole and clomiphene citrate alternatives.
Supply Chain Analysis
Inventory lead times for recombinant hormones stretch 12-16 weeks due to multi-stage fermentation and purification cycles, creating working capital intensity that bars sub-scale entrants. Supply concentrates in Germany, Switzerland, and Denmark for active pharmaceutical ingredients, with formulation finishing distributed across the United States, India, and China. Raw material dependencies include recombinant DNA cell banks, specialized peptide synthesis reagents, and pharmaceutical-grade excipients. Single-source vulnerability runs through the limited qualified fermentation facilities capable of GMP gonadotropin production. Distribution runs through specialty cold-chain logistics providers with 2°C to 8°C validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified reproductive toxicology investigators and ISO 13485-certified fermentation capacity represent the binding constraints that determine competitive survival, with scarcity concentrated in Boston-San Diego research clusters and Bavarian manufacturing zones respectively. Market position therefore hinges on securing these assets before competitors lock in exclusive arrangements.
For Market Incumbents: Shield formulation margins by backward integration into peptide synthesis capabilities or captive supply of recombinant cell banks, while accelerating clinic dispensing channel capture before fertility networks consolidate procurement under single pharmacy licenses. Biosimilar substitution from European tender processes and United States group purchasing organizations threatens originator pricing power most severely in standard-tier gonadotropins. For New Entrants and Emerging Players: Anchor in Brazil's ANVISA streamlined pathway for first-in-human gonadotropin trials, bypassing FDA-EMA sequencing delays that consume 18-24 months for established competitors. Online pharmacy integration for oral agent maintenance prescriptions offers the most penetrable channel, with telehealth-integrated dispensers in Germany and the Netherlands showing rapid prescription migration away from retail networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fertility clinic networks with captive dispensing functions, making these assets preferable to standalone pharmaceutical manufacturing. Long-term viability over a multi-year horizon rests on regulatory data reciprocity exploitation and cold-chain infrastructure control. Acquisition targets should display ISO 13485 certification with available fermentation capacity. The signal to monitor is NMPA approval velocity for biologics, which would indicate shifting trial initiation geography.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA-FDA-NMPA harmonization collapses multi-regional study timelines by accepting reciprocal toxicology packages. |
| Manufacturing Scale-Up | Fermentation capacity expansion in ISO 13485-certified facilities addresses supply vulnerability for gonadotropin APIs. |
| Regulatory Approval Pathway | ANVISA's streamlined biologics route offers sponsors alternative first-in-human jurisdictions outside traditional sequences. |
| Distribution Channel Expansion | Fertility clinic vertical integration captures margin previously allocated to specialty wholesale distributors. |
| Pipeline Diversification | Novel luteal support formulations from European peptide synthesis contract development organizations extend protocol capture. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA reproductive toxicology filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov gonadotropin protocols, and formulary database coverage policies. Primary interviews engaged drug development executives at recombinant biologics manufacturers, regulatory affairs leads navigating EMA-FDA-NMPA harmonization, fertility clinic pharmacy directors managing cold-chain protocols, and payer access specialists overseeing pre-authorization mandates. Bottom-up prescription volume modeling triangulates against top-down market sizing from manufacturer shipment data and distributor channel audits.
Segmentation dimensions modeled span product type (gonadotropins, oral ovulation inductors, luteal support agents), therapy area (controlled ovarian hyperstimulation, ovulation induction, male infertility), end user (fertility clinics, reproductive endocrinologists, gynecology centers), and distribution channel (specialty cold-chain distributors, online pharmacies, hospital pharmacies) across the analysis window. CAGRs derive from patient population projections, treatment protocol penetration curves, and reimbursement policy elasticity estimates. Forecast inputs include fertility clinic network expansion rates and biosimilar substitution coefficients from European tender data.
Decision-makers should treat outputs as directional under assumptions of sustained EMA-FDA-NMPA regulatory convergence and stable private payer pre-authorization protocols; material deviation in harmonization timelines or reimbursement stringency would warrant model refresh. Specific risks include cold-chain infrastructure gaps in Sub-Saharan Africa and Southeast Asia limiting addressable market expansion, and reproductive toxicology investigator scarcity constraining trial initiation capacity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Drug-Induced Immune Hemolytic Anemia Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Bio-Identical Hormones Replacement Therapy Market
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Isocitrate Dehydrogenase (IDH) Inhibitors Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Glycosylated Peptide Market