
 6-Azauracil Market | 2026-2036
6-Azauracil Market Size, Share, and Industry Trends Forecast 2026-2036
6-Azauracil Market Analytics
ISO 9001 and GMP certification cycles is rotating the competitive landscape, filtering out contract manufacturers lacking documented quality systems. Merck KGaA leverages its European production footprint to supply reference-grade material to European pharmacopeia users. Hunan Huateng Pharmaceutical anchors the Chinese supply base with backward integration into pyrimidine precursor chemistry. Sigma-Aldrich competes through its global distribution network and electronic ordering systems that reduce procurement friction for research buyers.
6-Azauracil is a synthetic pyrimidine analog with a modified uracil ring structure where carbon at the six position replaces nitrogen, functioning primarily as an antimetabolite that disrupts nucleic acid synthesis in rapidly dividing cells. Injectable formulations dominate current revenue due to hospital-based oncology administration protocols, while intranasal delivery represents the fastest-growing segment as researchers explore CNS-targeting applications for glioma protocols. Pharmaceutical companies occupy the largest end-user share, though research institutions are expanding procurement volumes for CRISPR-based genetic disorder studies.
FDA oversees IND-enabling toxicology requirements for 6-Azauracil candidates, while EMA's REACH framework governs chemical registration for European import and synthesis operations. China's NMPA and SAMR enforce dual carbon goals that constrain energy-intensive pyrimidine production, tightening supply for non-compliant manufacturers. Stakeholders should monitor evolving pharmacopeia monograph standards and regional carbon compliance deadlines to secure uninterrupted manufacturing access.
Market Dynamics
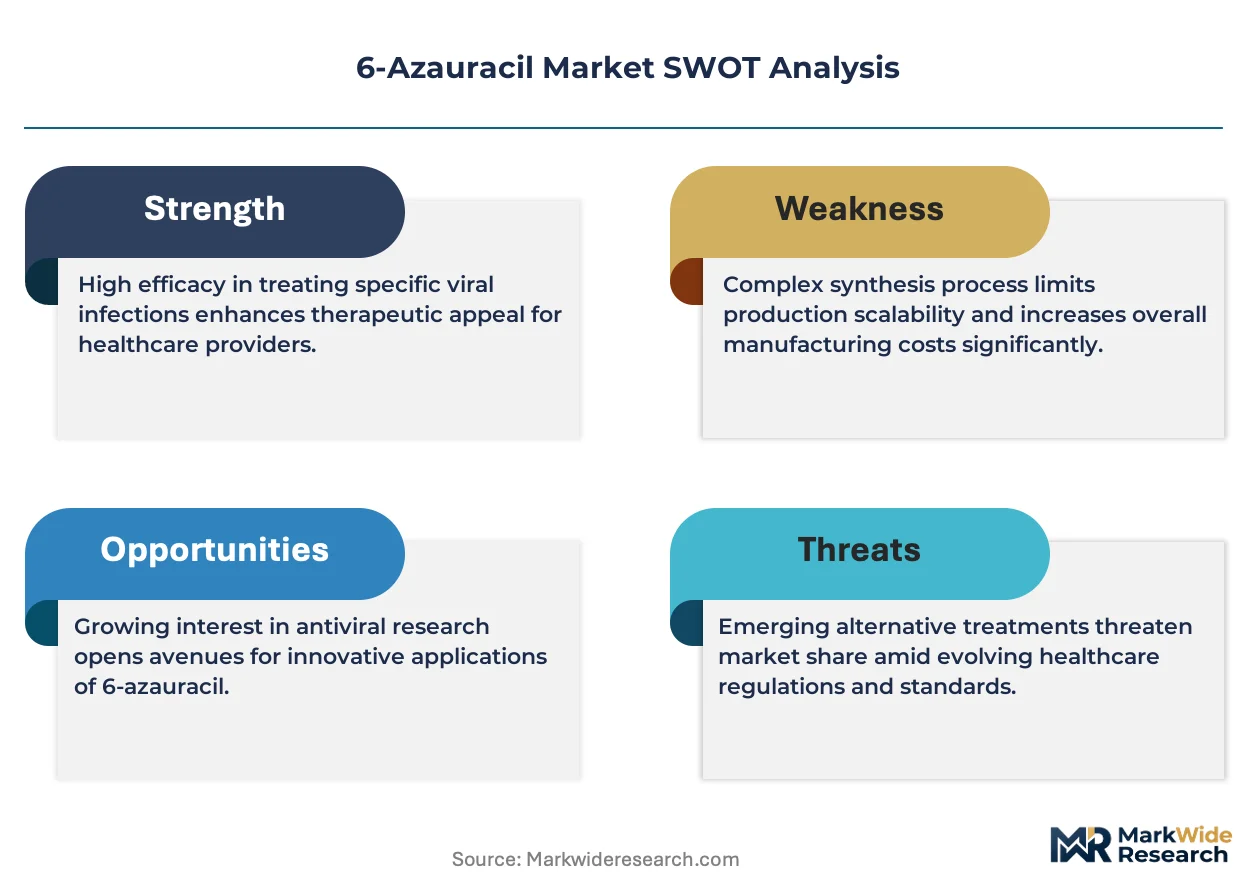
ISO 9001 and GMP certification cycles are filtering contract manufacturers, concentrating supply among documented quality system holders while orphan drug pathways accelerate clinical development timelines for pyrimidine analog candidates.
Growth Catalysts
- Orphan drug designation pathways:FDA and EMA streamlined frameworks reduce clinical development timelines for rare oncology indications, accelerating sponsor investment in 6-Azauracil programs.
- Academic medical center expansion:Rising oncology research investment at university-affiliated hospitals expands procurement volumes for reference-grade pyrimidine analogs.
- CRISPR-based genetic studies:Research institutions are expanding compound procurement for gene-editing protocols targeting nucleic acid synthesis pathways.
Market Restraints
- Pyrimidine precursor cost volatility:Energy-intensive synthesis of azole intermediates exposes margins to feedstock price swings and carbon compliance costs.
- Chinese supply concentration:Backward-integrated domestic manufacturers control critical precursor chemistry, creating geographic single-point vulnerability.
- Injectable administration limitations:Hospital-based oncology protocols restrict patient access outside tertiary care settings, compressing addressable populations.
Strategic Opportunities
- Intranasal CNS delivery:Glioma researchers are exploring non-invasive administration routes that bypass blood-brain barriers, opening new protocol designs.
- Carbon compliance incentives:China's dual carbon goals reward low-emission pyrimidine producers with preferential licensing under NMPA and SAMR frameworks.
- Electronic procurement platforms:Research buyers are migrating to integrated ordering systems that reduce friction for small-batch reference material acquisition.
Industry Challenges
- GMP certification timeline compression:Contract manufacturers face 18-24 month validation cycles that delay market entry for new production entrants.
- Pharmacopeia monograph alignment:Diverging European, USP, and ChP standards require multi-jurisdiction testing protocols that inflate quality assurance overhead.
- Cross-border chemical registration:ECHA REACH dossier requirements for European import operations create documentation burdens for non-EU synthesis facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 6-Azauracil Market |
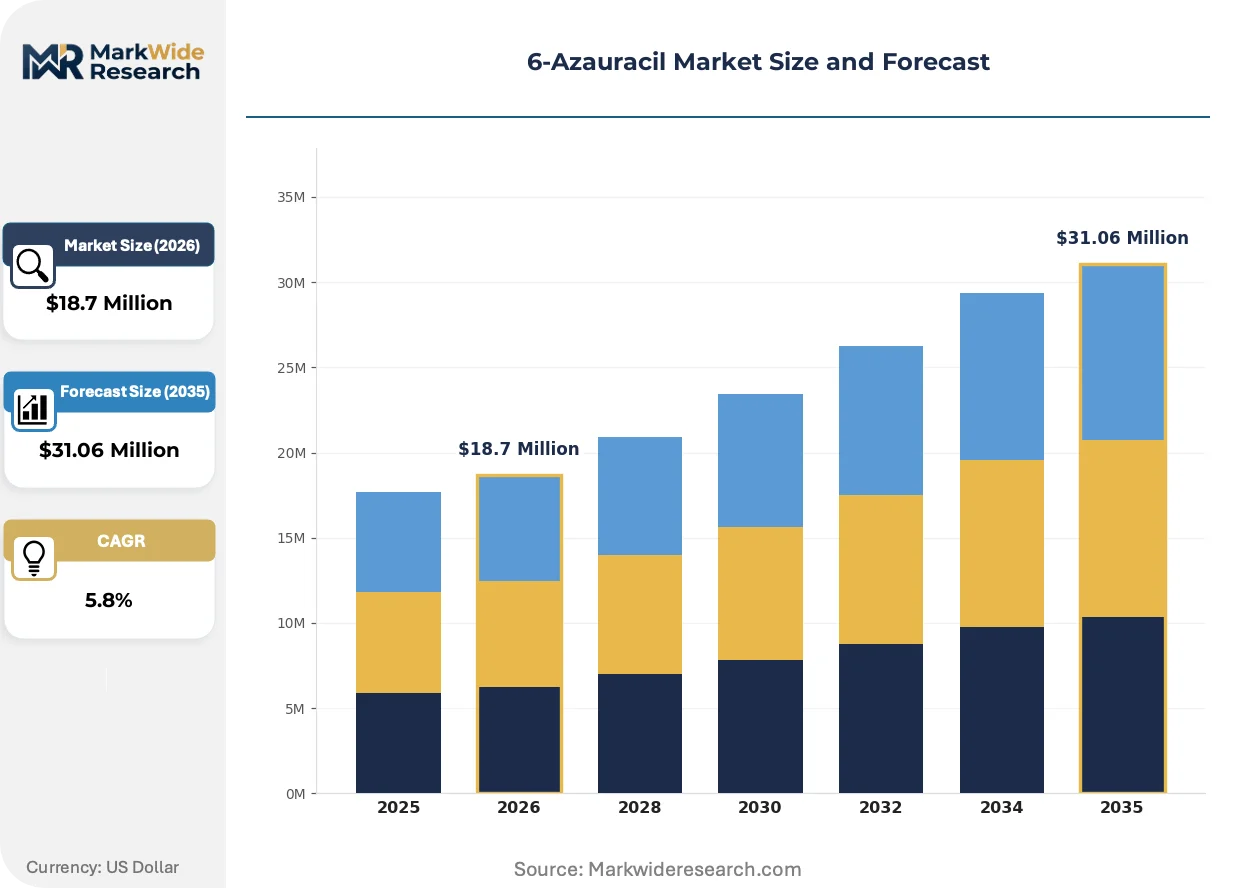
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $31.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Topical, Intranasal Application: Oncology, Antiviral, Genetic Disorders, Immunotherapy End User: Pharmaceutical Companies, Research Institutions, Hospitals, Clinics Delivery Mode: IV Infusion, Oral Administration, Subcutaneous Injection, Transdermal System |
| Companies Covered | Merck KGaA, Hunan Huateng Pharmaceutical, Hangzhou Hairui Chemical, Sichuan Hainuowei, Liaoyang Jiulong Pharmaceutical Chemical, Shijiazhuang Jing Kang Technology, Sigma-Aldrich, Tocris Bioscience, Santa Cruz Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
6-Azauracil Market Evolving Landscape
Delivery technology divergence and regulatory pathway specialization are fragmenting competitive positioning, with formulation innovation outpacing synthesis commoditization.
Intranasal administration technology is bifurcating the oncology administration landscape. Glioma research protocols at academic medical centers are piloting CNS-targeting delivery systems that circumvent invasive surgical requirements. This bifurcation is compressing hospital-only revenue models while opening outpatient protocol possibilities.
REACH framework amendments are tightening chemical registration requirements for pyrimidine imports into European synthesis operations. ECHA dossier standards now mandate extended environmental fate testing for azole-class compounds. European pharmacopeia users are responding by consolidating supplier audits around pre-registered reference material providers.
Research procurement patterns are fragmenting across institutional buyer tiers. Large pharmaceutical sponsors are centralizing compound sourcing through preferred vendor agreements, while independent investigators rely on distributor networks with electronic reordering capabilities. Japan and Germany exhibit the strongest concentration of consolidated procurement, reflecting cluster density of active clinical trials.
6-Azauracil Market Segmentation
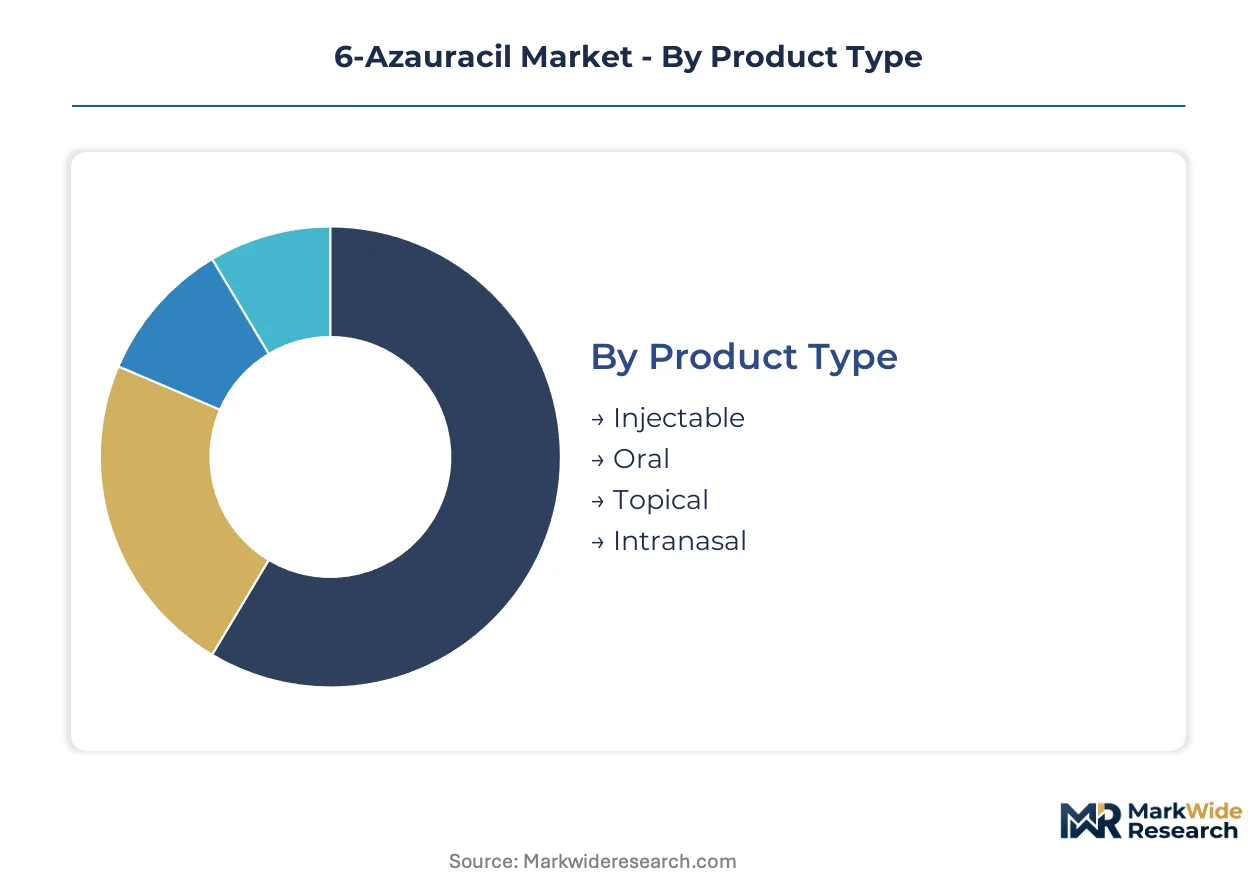
Segmentation in the 6-Azauracil market reflects divergent regulatory pathways and administration protocols that shape procurement patterns. FDA and EMA orphan drug designations favor certain delivery modes over others, while hospital-based oncology administration concentrates demand in specific product categories.
Product Type:
FDA IND requirements and EMA pharmacopeia standards create tiered compliance burdens across administration formats, filtering contract manufacturers by validation capability.
- Injectable:Sterile parenteral formulations meeting USP and EP monograph standards dominate hospital-based oncology procurement. United States academic medical centers drive the majority of volume through centralized pharmacy protocols that mandate documented cold-chain integrity.
- Intranasal:CNS-targeting delivery systems for glioma protocols are expanding fastest as researchers bypass blood-brain barriers without surgical intervention. Germany hosts the most active pilot programs at university-affiliated hospitals exploring outpatient administration models.
- Oral:Solid dosage forms face compressed margins due to simpler GMP requirements and broader generic competition in antiviral applications.
- Topical:Transdermal preparations remain niche, limited by poor bioavailability of pyrimidine analogs through skin permeation barriers.
Injectable handles the majority of throughput; Intranasal is the fastest mover on share.
Application:
Cost tier differentiation separates reference-grade material for clinical trials from commercial-scale API production, with pricing stratifying across premium, standard, and economy levels.
- Oncology:Antimetabolite mechanisms targeting nucleic acid synthesis in rapidly dividing cells command premium pricing for IND-enabling toxicology batches. Japan's PMDA orphan drug framework accelerates sponsor investment in rare indication protocols.
- Genetic Disorders:CRISPR-based studies at research institutions are expanding procurement volumes for gene-editing applications targeting pyrimidine synthesis pathways.
- Antiviral:Standard-grade material for broad-spectrum RNA virus inhibition faces price pressure from older pyrimidine analog substitutes.
- Immunotherapy:Combination protocols with checkpoint inhibitors remain exploratory, with demand concentrated in United States NCI-designated cancer centers.
Oncology captures the highest value per kilogram; Genetic Disorders is expanding most quickly as research procurement scales.
End User:
Customer type determines order frequency and batch size, with pharmaceutical sponsors consolidating through preferred vendor agreements while independent investigators rely on distributor networks.
- Pharmaceutical Companies:Large sponsors centralize compound sourcing through multi-year supply agreements that lock in reference-grade purity specifications and audit rights.
- Research Institutions:Academic medical centers in Germany and Japan exhibit the strongest procurement concentration, reflecting cluster density of active clinical trials and CRISPR-based genetic studies.
- Hospitals:Tertiary care oncology centers require GMP-certified injectable formulations with documented pharmacopeia compliance for inpatient administration protocols.
- Clinics:Outpatient settings face restricted access due to injectable administration limitations and specialized handling requirements.
Pharmaceutical Companies anchor volume commitment; Research Institutions are climbing the fastest as academic procurement expands.
Delivery Mode:
Supply concentration in backward-integrated pyrimidine chemistry shapes availability across administration routes, with IV infusion formats benefiting from established hospital infrastructure.
- IV Infusion:Hospital-based oncology protocols in the United States and Japan rely on centralized pharmacy compounding with documented sterility assurance and extended stability data.
- Subcutaneous Injection:Self-administration potential for outpatient immunotherapy protocols is gaining traction at European academic medical centers exploring patient convenience models.
- Oral Administration:Simplified logistics and reduced handling costs appeal to antiviral applications, though bioavailability challenges limit oncology uptake.
- Transdermal System:Patch-based delivery remains developmental, constrained by molecular weight limitations and skin penetration requirements for pyrimidine analogs.
IV Infusion maintains dominant throughput; Subcutaneous Injection is gaining share fastest as outpatient protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives and EMA accelerated assessment pathways are concentrating clinical trial investment in jurisdictions with streamlined regulatory frameworks. Germany, Japan, and the United States host the majority of active 6-Azauracil protocols, while China's dual carbon policies reshape precursor chemical availability.
United States
NCI-designated cancer centers in Boston and Houston drive reference-grade procurement for IND-enabling toxicology studies. FDA's orphan drug designation framework reduces clinical development timelines for rare oncology indications. Academic medical centers in the Research Triangle and San Diego clusters are expanding CRISPR-based genetic disorder research requiring pyrimidine analog supply.
Germany
University-affiliated hospitals in Heidelberg and Munich pilot intranasal CNS delivery protocols for glioma applications. EMA's REACH framework governs chemical registration for European import and synthesis operations. The Rhine-Main biotech corridor concentrates pharmacopeia-compliant reference material demand from European sponsors.
Japan
PMDA's orphan drug framework accelerates sponsor investment in rare indication protocols targeting nucleic acid synthesis disruption. METI funding for precision oncology research expands procurement at Tokyo and Osaka academic medical centers. The Kanto region hosts the densest cluster of active clinical trials for antimetabolite candidates.
China
NMPA and SAMR enforcement of dual carbon goals constrains energy-intensive pyrimidine production, tightening supply for non-compliant manufacturers. Hunan and Sichuan provinces anchor backward-integrated domestic production of azole intermediates. Yangtze River Delta chemical parks face carbon compliance deadlines that favor low-emission producers with preferential licensing.
Switzerland
Swissmedic's streamlined clinical trial authorization attracts sponsor headquarters seeking European market access. Basel and Zurich host contract research organizations managing multi-site oncology protocols requiring GMP-certified injectable formulations. The country's pharmacopeia alignment with EP standards reduces quality assurance overhead for reference-grade material sourcing.
6-Azauracil Market Competitive Landscape
Player mix skews toward European and Chinese chemical manufacturers with documented quality systems. Supply concentrates among ISO 9001 and GMP-certified contract manufacturers capable of pharmacopeia-grade production. Three archetypes dominate: backward-integrated pyrimidine specialists, global distributor-chemists with electronic procurement platforms, and research-grade reference material providers. Competitive moves center on carbon compliance certification and preferred vendor agreements with large pharmaceutical sponsors.
Among European-based suppliers, Merck KGaA occupies a position exemplifying the integrated quality-system archetype. Hunan Huateng Pharmaceutical anchors the Chinese supply base representing backward-integrated pyrimidine chemistry. Sigma-Aldrich sits within the distributor-chemist tier, connecting research buyers to reference-grade material through electronic ordering infrastructure. These three entities collectively illustrate the geographic and functional segmentation shaping procurement patterns across institutional buyer tiers.
| Leading Market Players |
|---|
| Merck KGaA |
| Hunan Huateng Pharmaceutical |
| Hangzhou Hairui Chemical |
| Sichuan Hainuowei |
| Liaoyang Jiulong Pharmaceutical Chemical |
| Shijiazhuang Jing Kang Technology |
| Sigma-Aldrich |
| Tocris Bioscience |
| Santa Cruz Biotechnology |
| Others |
Value Network & Pricing Analysis
Azole intermediate substitution for traditional pyrimidine precursors is redrawing procurement geography while compressing margin structures across reference-grade and standard-tier supply tiers. This feedstock shift favors Hunan and Sichuan producers with captive synthesis capabilities, forcing European contract manufacturers to absorb carbon compliance premiums or exit pharmacopeia-grade segments.
Pricing Analysis
Certification level creates the primary spread between USP-grade injectable batches and research-grade material. Three-tier pricing structure across premium, standard, and economy levels stratifies by GMP validation depth and pharmacopeia alignment. Cost compression in standard-grade oral formulations is intensifying because of generic pyrimidine analog substitution. Research institutions exhibit highest price sensitivity due to grant-funded procurement constraints, while pharmaceutical sponsors lock in long-term offtake with audit rights.
Supply Chain Analysis
Yangtze River Delta carbon compliance deadlines constitute a chokepoint constraining non-compliant azole intermediate output. Supply concentrates in China, Germany, and Switzerland for backward-integrated pyrimidine chemistry. Synthesis draws from energy-intensive precursor streams including urea derivatives and malic acid derivatives. Single-source vulnerability runs through Hunan province's dominant azole production cluster. Distribution runs through electronic procurement platforms for research buyers and direct vendor agreements for pharmaceutical sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intranasal CNS delivery technology is disrupting hospital-centric oncology administration, creating white-space for outpatient protocol developers and specialized formulation providers.
For Market Incumbents: Compound GMP certification depth with preferred vendor agreement structures to lock in pharmaceutical sponsor volume. Threat from REACH framework amendments intensifies documentation burdens for non-EU synthesis facilities. Prioritize carbon compliance certification under NMPA dual carbon goals to defend Chinese supply access. For New Entrants and Emerging Players: Electronic procurement platform under-service at mid-tier research institutions opens direct-channel opportunities. Most penetrable segment: independent academic investigators in Germany and Japan requiring small-batch reference material with rapid reorder capability. Go-to-market angle: integrated ordering systems with documented pharmacopeia compliance and extended stability data. For Investors and Strategic Acquirers: Capital is best deployed toward ISO 9001-certified contract manufacturers with documented European pharmacopeia alignment and existing orphan drug program supply relationships. Long-term viability centers on formulation innovation capabilities rather than synthesis commoditization. Signal to watch: intranasal delivery technology adoption rates in glioma protocol designs at NCI-designated cancer centers.| Strategic Initiative | Industry Significance |
|---|---|
| Intranasal Formulation Development | Enables CNS-targeting glioma protocols bypassing invasive surgical requirements at academic medical centers. |
| Carbon Compliance Certification | Secures preferential NMPA licensing for low-emission pyrimidine producers in Yangtze River Delta chemical parks. |
| Preferred Vendor Agreement Expansion | Locks multi-year supply commitments from pharmaceutical sponsors requiring audit rights and reference-grade purity. |
| Electronic Procurement Platform Integration | Reduces friction for research buyers migrating from distributor networks to direct ordering systems. |
| REACH Dossier Pre-Registration | Streamlines European import operations for azole-class compounds under tightening ECHA environmental fate standards. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads, hospital procurement managers, and GMP compliance officers at contract manufacturers; and secondary validation through FDA IND filings, EMA orphan drug designations, ClinicalTrials.gov protocol registries, and customs trade data for pyrimidine precursor movements. Bottom-up volume estimates from synthesis facility capacity and top-down triangulation against academic medical center procurement budgets cross-checked segment outputs.
Across the projection horizon, the analytical framework modeled segmentation by administration route, application indication, end-user archetype, and regional regulatory cluster. CAGRs derived from compound annual growth rate fitting against historical orphan drug program investment patterns and CRISPR research funding trajectories. Forecast inputs incorporated energy cost assumptions for azole intermediate synthesis and carbon compliance deadline schedules under NMPA frameworks.
Underlying assumptions cover stable orphan drug incentive structures and REACH framework enforcement continuity, with deviation risk concentrated in Chinese dual carbon policy implementation pace and intranasal delivery technology clinical validation timelines. Practitioners should keep alternative scenarios live as glioma protocol enrollment rates and carbon compliance certification adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Human Insulin Drugs Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Sezary Syndrome Market
Biopharmaceuticals
Heparin API Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
North America Vaccines Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
Global Biopharma Buffer Market