
 Hungary Third Party Logistics (3PL) Market | 2026-2036
Hungary Third Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Hungary Third Party Logistics (3PL) Market Foresight
Market Context
EU Green Deal emissions mandates are recalibrating fleet investment requirements for Hungarian road transport operators. DSV Hungaria leverages its integrated European network to sustain cross-border capacity advantages. Waberers International anchors domestic full-truckload operations through extensive owned fleet assets. Raben Trans European Hungary differentiates via temperature-controlled specialization serving pharmaceutical and food verticals.
Technical Definition and Structural Segments
Third Party Logistics encompasses outsourced supply chain functions including transportation execution, warehousing operations, inventory optimization, and freight forwarding coordination, typically governed by service-level agreements specifying delivery windows, damage rates, and inventory accuracy thresholds. Transportation services occupy the largest revenue pool within Hungary's 3PL structure, while warehousing commands premium margins in Budapest's constrained industrial real estate zone. E-Commerce end users represent the fastest-expanding demand segment, with Robotics technology deployment accelerating among large-scale operators seeking labor cost containment.
Regulatory Framework
EU F-Gas Regulation and REACH compliance requirements shape cold-chain equipment standards and warehouse material handling specifications across Hungarian 3PL operations. Hungary's national transport authority and the EU Mobility Package enforce driver rest rules and cabotage restrictions that constrain fleet utilization models. Stakeholders must monitor evolving EU AI Act provisions affecting automated warehouse decision systems and route optimization algorithms.
Market Dynamics
The EU Green Deal's tightening emission standards for commercial transport fleets are forcing Hungarian road operators into accelerated fleet renewal cycles, reshaping capital allocation across the 3PL sector.
Growth Catalysts
- EU Green Deal mandates:Stricter CO2 thresholds for heavy-duty vehicles are accelerating demand for electric and alternative-fuel fleet investments among Hungarian operators serving automotive manufacturers.
- E-Commerce fulfillment density:Budapest's concentrated consumer base is driving warehousing absorption and last-mile infrastructure buildout along the M0 logistics corridor.
- Robotics deployment:Automated storage and retrieval systems are compressing labor cost structures in large-scale distribution centers serving pharmaceutical and food verticals.
Market Restraints
- Diesel price volatility:Fuel cost swings directly erode margins in full-truckload operations where fuel surcharges lag spot market movements.
- EU Mobility Package cabotage limits:Restricted cross-border driver utilization within Hungary constrains fleet productivity for international operators.
- Industrial land scarcity:Budapest's constrained warehouse supply inflames rental costs and extends facility development timelines.
Strategic Opportunities
- Debrecen logistics cluster:BMW's manufacturing presence is creating unmet demand for specialized automotive parts warehousing and sequencing services in eastern Hungary.
- EU AI Act compliance services:Automated warehouse decision systems require algorithmic audit capabilities that Hungarian operators can package as premium advisory offerings.
- Temperature-controlled pharma growth:EMA serialization requirements and cold-chain integrity mandates are opening specialized 2-8°C distribution lanes.
Industry Challenges
- Certified driver scarcity:ADR hazardous materials and temperature-controlled transport qualifications face acute supply gaps, constraining specialized service expansion.
- WMS-TMS integration complexity:Legacy enterprise resource planning systems at Hungarian manufacturing clients resist seamless API connectivity with modern 3PL platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hungary Third Party Logistics (3PL) Market |
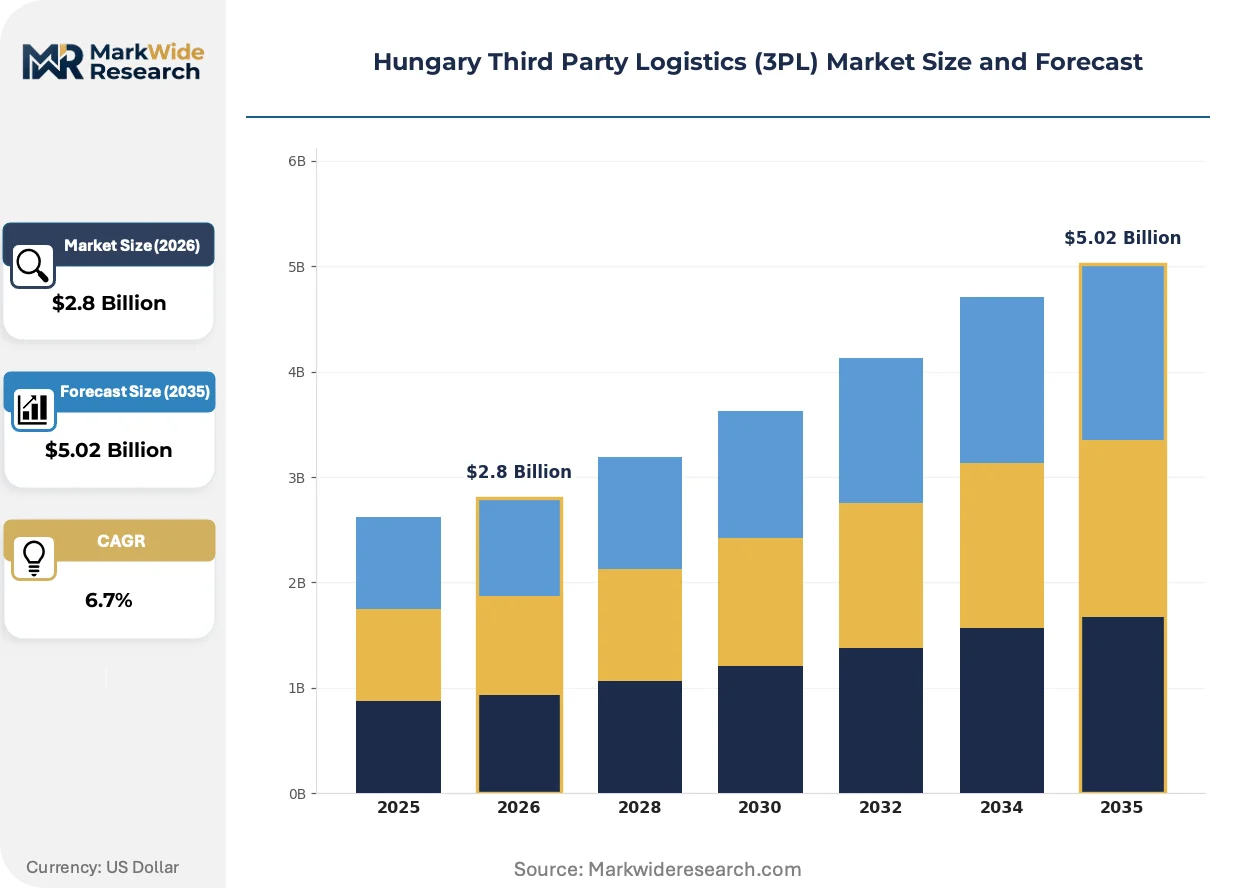
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Freight Forwarding End User: Manufacturing, Retail, E-Commerce, Automotive Technology: Warehouse Management System, Transportation Management System, Robotics, IoT Capacity: Small Scale, Medium Scale, Large Scale, Enterprise |
| Companies Covered | DSV Hungaria, DB Schenker, Gartner Intertrans Hungaria, Waberers International, TNT Express Hungary Kft., Duvenbeck Logisztikai, DHL Global, Raben Trans European Hungary, UPS Healthcare Hungary Zrt., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hungary Third Party Logistics (3PL) Market Shifts & Advancements
Digital freight matching platforms and warehouse automation are compressing traditional intermediation layers, while regulatory compliance requirements are becoming competitive differentiators rather than cost centers.
Autonomous mobile robots are rewriting fulfillment economics in Hungarian distribution centers. Pharmaceutical wholesalers and grocery retailers are deploying AMR fleets at accelerating pace. Labor cost containment targets that previously justified five-year payback periods now clear eighteen-month hurdles.
EU F-Gas Regulation phase-down schedules are forcing cold-chain operators into refrigeration system retrofits. Industrial consequence includes accelerated capital obsolescence for conventional warehouse equipment. Temperature-controlled 3PL providers serving food and pharma verticals are responding with CO2-based refrigeration investments and equipment leasing structures.
Shippers are unbundling transportation management from warehousing contracts, compressing contract durations and accelerating vendor rotation. Traditional multi-year integrated agreements fragment into modular, shorter-term engagements. Automotive parts suppliers in the Győr corridor exhibit the most aggressive contract restructuring behavior.
Hungary Third Party Logistics (3PL) Market Segmentation
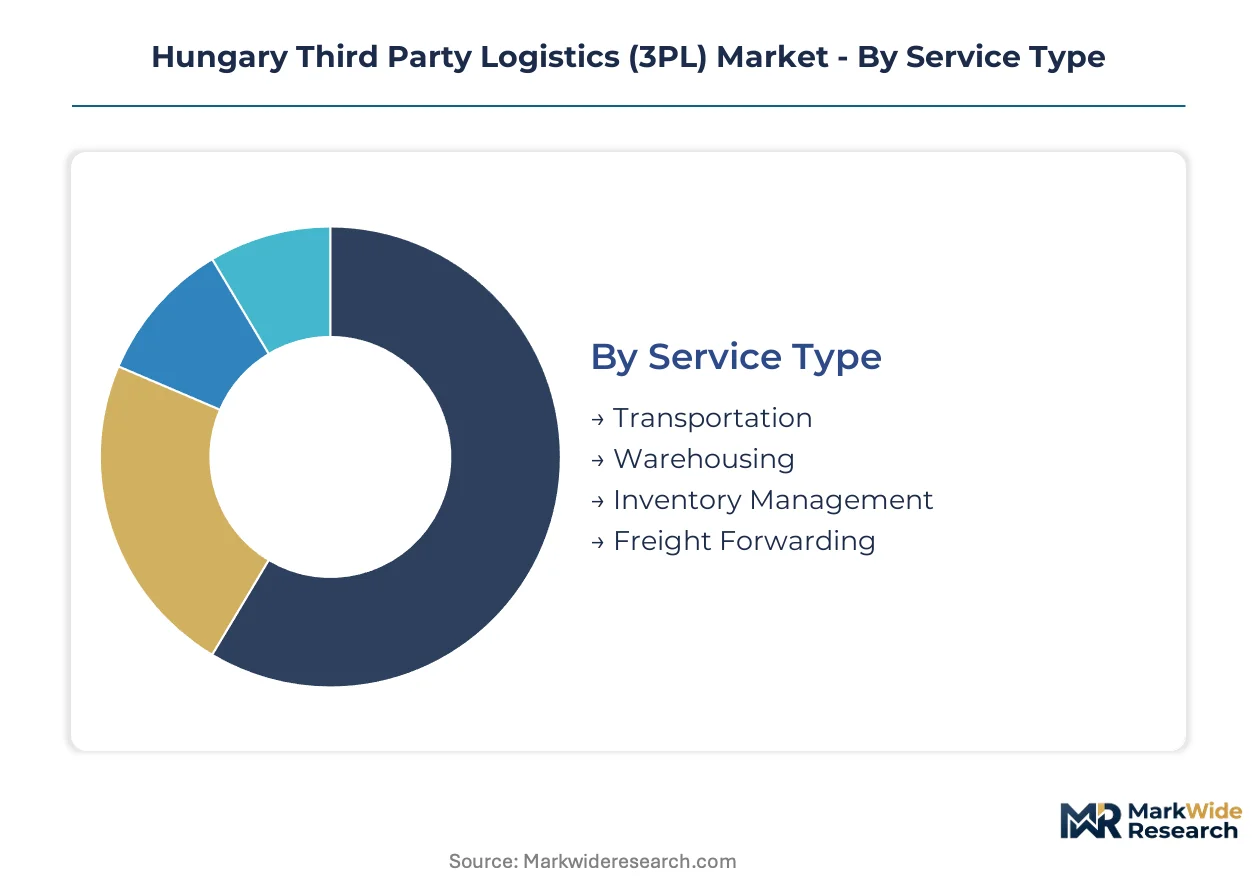
Service configuration in Hungary's 3PL sector varies sharply by regulatory burden and capital intensity. Segment selection determines which EU directives apply, from F-Gas refrigeration mandates to AI Act algorithmic governance.
Service Type:
Certification requirements diverge sharply across service lines, with temperature-controlled transport demanding ADR hazardous materials licensing and EU F-Gas refrigeration compliance that ambient operations avoid entirely.
- Transportation:Full-truckload and less-than-truckload execution dominates revenue pools, with fleet operators navigating EU Mobility Package cabotage restrictions and driver rest mandates. Demand concentrates along the Budapest-Győr corridor serving Audi and Mercedes-Benz assembly plants, where just-in-sequence delivery windows compress turnaround times.
- Warehousing:Temperature-controlled facilities serving pharmaceutical verticals require EMA serialization compliance and GDP certification that ambient storage avoids. Budapest's M0 logistics ring hosts the densest concentration, though land scarcity inflames rental costs and extends development timelines.
- Inventory Management:Stock optimization and demand forecasting services leverage WMS-TMS integration, though legacy ERP systems at Hungarian manufacturing clients resist seamless API connectivity.
- Freight Forwarding:Cross-border customs brokerage and multimodal coordination depend on AEO authorized economic operator status for expedited EU frontier clearance.
Transportation sits at the top of the volume ranking, with Warehousing climbing the fastest as e-Commerce fulfillment density reshapes Budapest's industrial real estate absorption.
End User:
Customer scale and contract structure vary dramatically, from automotive tier-one suppliers demanding multi-year integrated agreements to e-Commerce platforms driving modular, shorter-term engagements.
- Manufacturing:Industrial clients require vendor-managed inventory and production sequencing capabilities. Győr-based automotive parts suppliers exhibit aggressive contract unbundling behavior, separating transportation management from warehousing agreements.
- Retail:Grocery and consumer goods distributors prioritize temperature-controlled last-mile density and store replenishment frequency.
- E-Commerce:Pure-play and omnichannel retailers are expanding fastest, with Budapest's concentrated consumer base driving robotics deployment for labor cost containment in fulfillment centers.
- Automotive:OEM and tier-one suppliers demand specialized sequencing, milk-run collection, and cross-dock consolidation. BMW's Debrecen manufacturing presence is creating unmet demand for dedicated parts warehousing in eastern Hungary.
Manufacturing retains the largest contract value base, with E-Commerce expanding most quickly as platform economics reshape fulfillment infrastructure requirements.
Technology:
Capital deployment and compliance obligations stratify by automation level, with EU AI Act provisions beginning to govern algorithmic warehouse decision systems and route optimization tools.
- Warehouse Management System:Software platforms govern inventory location, picking optimization, and labor allocation. Pharmaceutical wholesalers require serialization track-and-trace modules that food distributors often omit.
- Transportation Management System:Route optimization and carrier selection tools face emerging EU AI Act audit requirements for automated decision systems.
- Robotics:Autonomous mobile robots and automated storage and retrieval systems are compressing fulfillment economics, with payback periods shortening from five years to eighteen months in large-scale distribution centers.
- IoT:Sensor networks for cold-chain monitoring and fleet telematics require cybersecurity compliance under EU NIS2 directives.
Warehouse Management System commands the deepest installed base, with Robotics gaining share fastest as labor cost containment targets intensify across Hungarian distribution operations.
Capacity:
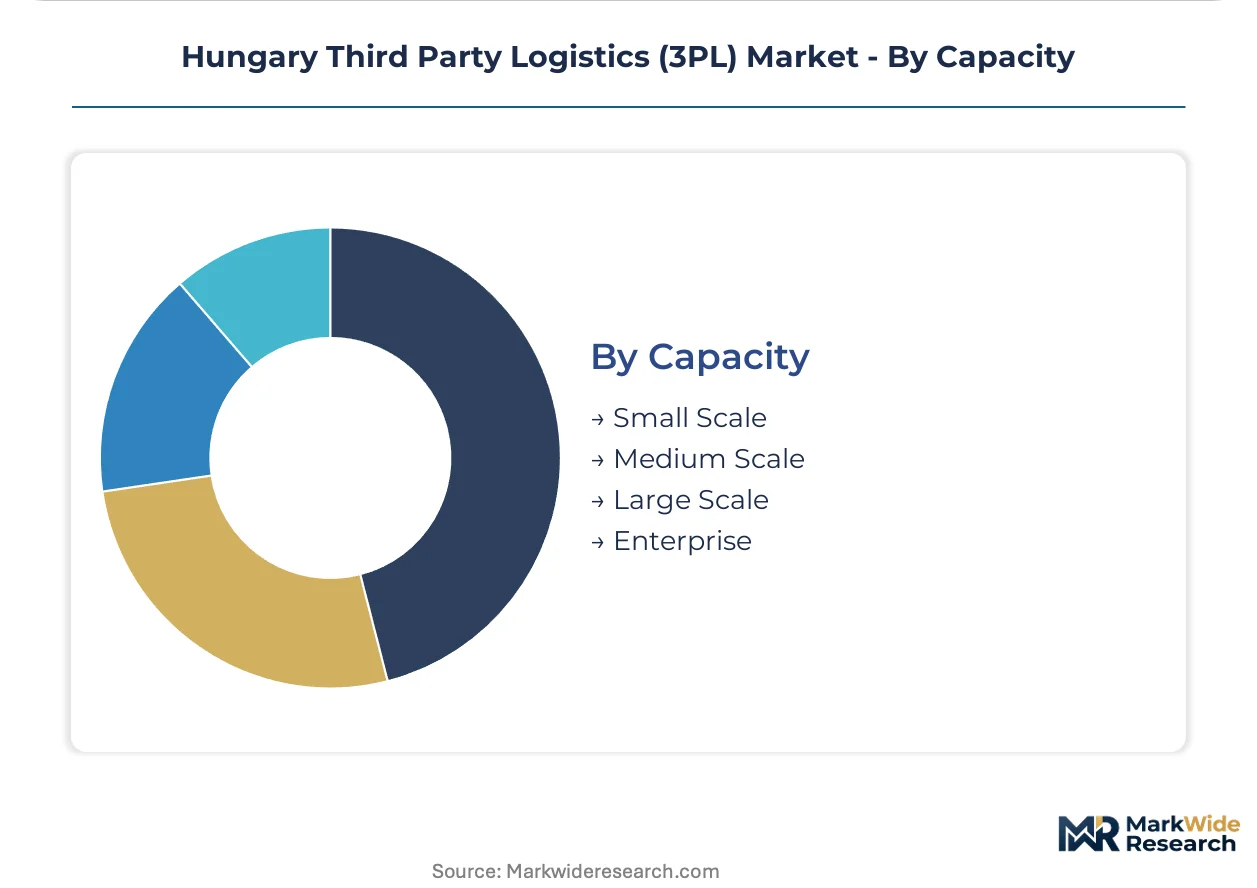
Facility scale determines which regulatory thresholds apply, from REACH chemical handling volumes to mandatory energy audit obligations for large industrial sites.
- Small Scale:Local operators with limited fleet assets serve niche routes and specialized cargo. These players face acute pressure from digital freight matching platforms that compress traditional intermediation margins.
- Medium Scale:Regional networks with owned warehousing and contracted carrier relationships dominate fragmented verticals like temperature-controlled food distribution.
- Large Scale:National operators with integrated road networks and multi-site warehousing leverage scale economies in procurement and technology deployment.
- Enterprise:International 3PLs with pan-European networks, including DSV and Raben, sustain cross-border capacity advantages through integrated systems and regulatory compliance scale.
Large Scale operators anchor the revenue core, with Enterprise segment climbing fastest as automotive manufacturers consolidate vendor relationships toward integrated European networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Central European logistics infrastructure traces its modern lineage to post-communist industrial restructuring, when Hungary positioned itself as a manufacturing supply corridor connecting Western European markets with Eastern production bases.
Budapest and the M0 Logistics Corridor
Audi and Mercedes-Benz assembly plants in Győr drive just-in-sequence freight volumes along the Budapest-Győr industrial axis. EU Mobility Package cabotage restrictions constrain cross-border driver utilization for operators based here. The M0 ring hosts Hungary's densest warehousing concentration, where land scarcity inflames rental costs and extends development timelines.
Debrecen and Eastern Hungary
BMW's manufacturing investment is creating unmet demand for specialized automotive parts warehousing and sequencing services. EU Green Deal emission mandates are accelerating electric fleet procurement among operators serving this emerging cluster. The Debrecen logistics zone remains undersupplied relative to Western Hungary's infrastructure density.
Győr-Moson-Sopron County
Tier-one automotive suppliers concentrate production sequencing and vendor-managed inventory operations near Audi's engine plant. REACH compliance requirements shape chemical handling protocols for paint and coating logistics. The county's industrial parks absorb the highest per-capita warehousing investment outside Budapest.
Szeged and Southern Hungary
Food processing and agricultural distribution anchor temperature-controlled transport demand toward Romanian and Serbian border corridors. F-Gas Regulation phase-down schedules are forcing refrigeration system retrofits among cold-chain operators. The Szeged logistics sub-market remains fragmented compared to Budapest-centric networks.
Hungary Third Party Logistics (3PL) Market Competitive Landscape
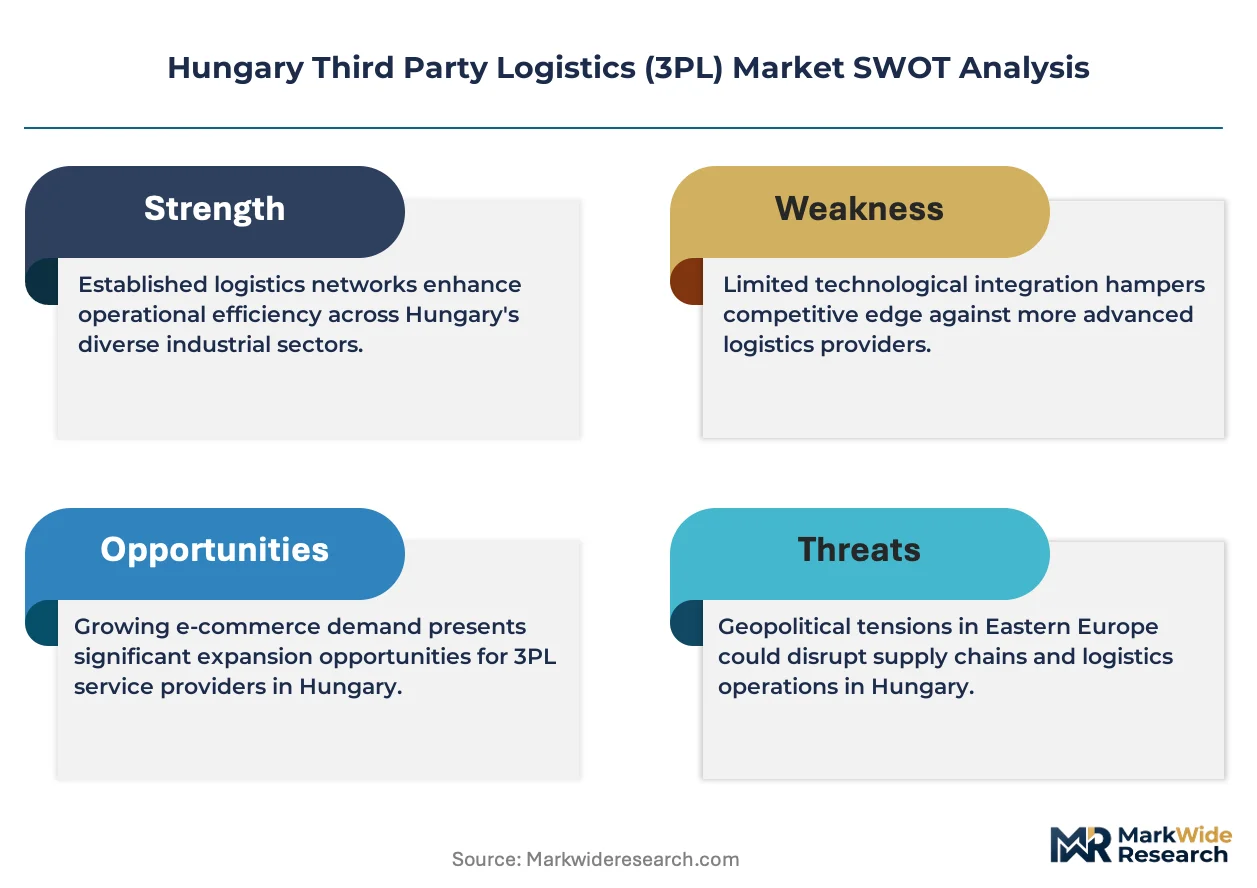
The competitive structure tilts toward integrated European networks with domestic fleet ownership. International operators leverage cross-border capacity advantages through pan-European systems, while Hungarian-owned players anchor full-truckload density through extensive asset bases. Three archetypes dominate: integrated European networks, domestic fleet-heavy operators, and temperature-controlled specialists. M&A activity concentrates on technology-enabled last-mile capabilities, while strategic partnerships target electric fleet procurement consortiums.
Within the integrated network tier, DSV Hungaria and DB Schenker represent the European scale archetype, leveraging cross-border regulatory compliance scale. Domestic fleet-heavy operators include Waberers International, which exemplifies asset-based full-truckload positioning through owned vehicle concentration. Raben Trans European Hungary occupies the temperature-controlled specialization vector, serving pharmaceutical and food verticals where GDP certification and cold-chain integrity create service differentiation.
| Leading Market Players |
|---|
| DSV Hungaria |
| DB Schenker |
| Gartner Intertrans Hungaria |
| Waberers International |
| TNT Express Hungary Kft. |
| Duvenbeck Logisztikai |
| DHL Global |
| Raben Trans European Hungary |
| UPS Healthcare Hungary Zrt. |
| Others |
Supply & Pricing Matrix
Autonomous mobile robot deployment across Budapest's fulfillment centers is compressing labor cost structures while simultaneously concentrating operational scale among capital-rich operators capable of eighteen-month payback cycles. This technology transition rewards large-scale 3PLs with pricing power in premium warehousing tiers while squeezing margin structures for smaller fleet operators unable to automate.
Pricing Analysis
Bundled transportation-warehousing contracts are fragmenting into modular service components as automotive shippers unbundle multi-year agreements. Three-tier pricing structure across premium GDP-certified cold chain, standard ambient warehousing, and economy spot-truckload tiers reflects certification investment and capacity scarcity. Pricing pressure stems from diesel volatility eroding full-truckload margins where fuel surcharges lag spot movements. E-Commerce platforms exhibit highest price sensitivity, while pharmaceutical manufacturers accept premium rates for EMA serialization compliance.
Supply Chain Analysis
Certified driver scarcity across the Budapest-Győr corridor and Debrecen manufacturing zone is constraining specialized service expansion and inflaming wage costs for ADR hazardous materials and temperature-controlled qualifications. Fleet assets and warehousing infrastructure draw most heavily from Germany, Poland, and domestic Hungarian manufacturing. Refrigeration equipment and telematics hardware rest on single-source vulnerability from concentrated European component suppliers. Distribution runs through hub-and-spoke road networks radiating from the M0 logistics ring, with multimodal rail connections to Rotterdam and Koper providing Balkan corridor alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hungary's 3PL sector functions as a stable compounder anchored by automotive manufacturing expansion and EU regulatory compliance mandates that perpetually renew outsourcing demand. Structural drivers include emission standard tightening, e-Commerce fulfillment density, and pharmaceutical cold-chain growth.
For Market Incumbents: To counter contract unbundling by automotive tier-one suppliers, deepen captive warehousing relationships through vendor-managed inventory capabilities in the Győr corridor and Debrecen cluster. Prioritize electric fleet procurement consortiums to deflect EU Green Deal capital pressure while securing long-term automotive sequencing contracts. For New Entrants and Emerging Players: Enter via temperature-controlled pharmaceutical distribution in eastern Hungary, where BMW's Debrecen presence has created unmet demand for specialized parts warehousing and GDP-certified cold chain. Target modular last-mile robotics deployment for mid-market e-Commerce platforms underserved by enterprise-scale operators. For Investors and Strategic Acquirers: Valuations sit cheapest among medium-scale regional operators with owned fleet assets but limited technology integration. Long-term viability favors consolidators capable of pan-European compliance scale. Monitor EU AI Act implementation timelines as inflection signal for algorithmic audit service premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Procurement Consortium | Pools capital requirements for EU Green Deal compliance across operators serving Audi and BMW plants. |
| WMS-TMS Platform Integration | Resolves API connectivity failures with legacy ERP systems at Hungarian manufacturing clients. |
| Debrecen Logistics Hub Development | Captures unmet automotive parts warehousing demand from BMW's eastern Hungary manufacturing base. |
| CO2 Refrigeration Retrofit Program | Addresses F-Gas Regulation phase-down while securing pharmaceutical GDP certification advantages. |
| EU AI Act Compliance Services | Packages algorithmic audit capabilities as premium advisory offerings for automated warehouse systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, warehouse facility managers, automotive procurement leads, pharmaceutical supply chain heads, and customs brokerage specialists with secondary validation. Trade flow databases, EU regulatory filings, Hungarian transport authority statistics, and automotive production schedules anchored bottom-up volume estimates against top-down macroeconomic triangulation.
Segment-weighting approaches distributed value across service type, end-user vertical, technology deployment, and capacity tier dimensions throughout the forecast period. CAGRs derived from historical trajectory analysis, regulatory implementation timelines, and capital investment cycle modeling incorporated automotive manufacturing expansion curves and e-Commerce penetration rates as sector-specific inputs.
The model holds under stable EU regulatory implementation and continued automotive foreign direct investment; deviation in diesel price volatility extremes, driver qualification supply shocks, or industrial land release delays would shift trajectory. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Latin America Container Terminal Operations Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
Poland Third Party Logistics (3PL) Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
First and Last Mile Delivery Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Digital Logistics Market
Logistics and Shipping
Autonomous Last Mile Delivery Market