
 Microdermabrasion Market | 2026-2036
Microdermabrasion Market Size, Share, and Industry Trends Forecast 2026-2036
Microdermabrasion Market Outlook
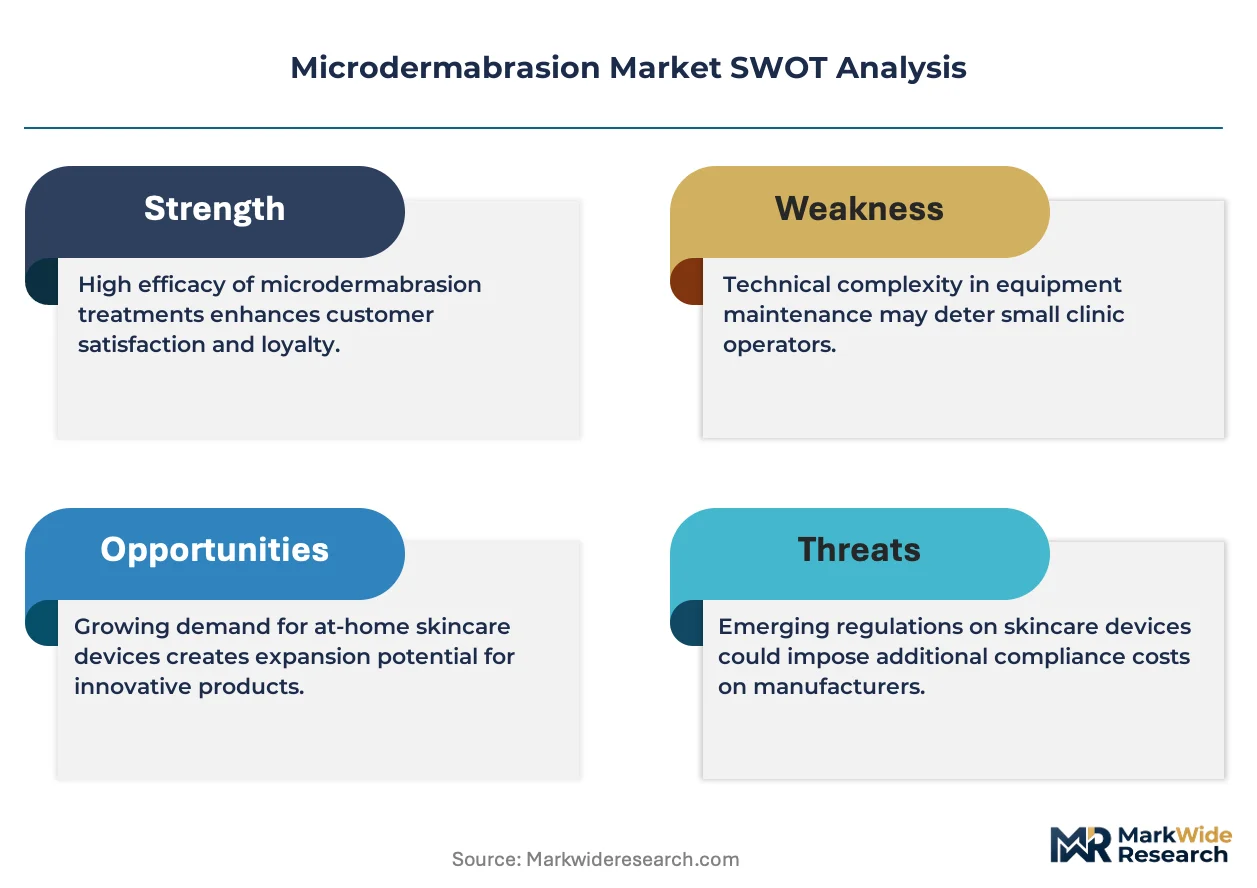
Equipment leasing and pay-per-procedure financing is narrowing the capital barrier for mid-size dermatology practices and independent medspas seeking professional-grade systems. Johnson & Johnson leverages its institutional relationships with hospital outpatient departments to sustain placement volumes for capital equipment. Koninklijke Philips N.V. anchors its position through dual-channel distribution that serves both clinical settings and authorized retail partners. HydraFacial LLC differentiates by controlling proprietary consumable streams tied to its device ecosystem.
Microdermabrasion employs mechanical exfoliation through either diamond-tipped wands or pressurized crystal streams to remove the stratum corneum, typically operating at vacuum pressures between 60-90 mmHg to stimulate dermal fibroblast activity and enhance topical product penetration. Professional devices command the dominant revenue position given higher price points and recurring consumable attachment sales, while home use devices represent the fastest-expanding volume segment as consumers seek clinic-grade results between professional visits. Diamond microdermabrasion systems lead technology preferences in clinical settings due to reduced particle dispersion and lower consumable dependency compared to crystal-based alternatives.
FDA 510(k) clearance requirements govern device safety and efficacy claims for microdermabrasion systems marketed in the United States, while the EU Medical Device Regulation (MDR) reclassifies many aesthetic devices and intensifies clinical evidence obligations for market access. ISO 13485 quality management standards shape manufacturing protocols for device OEMs targeting multi-jurisdiction distribution. Stakeholders must monitor evolving classification boundaries between cosmetic and medical devices, as regulatory reclassification would trigger substantial compliance investments and channel restructuring.
Market Dynamics
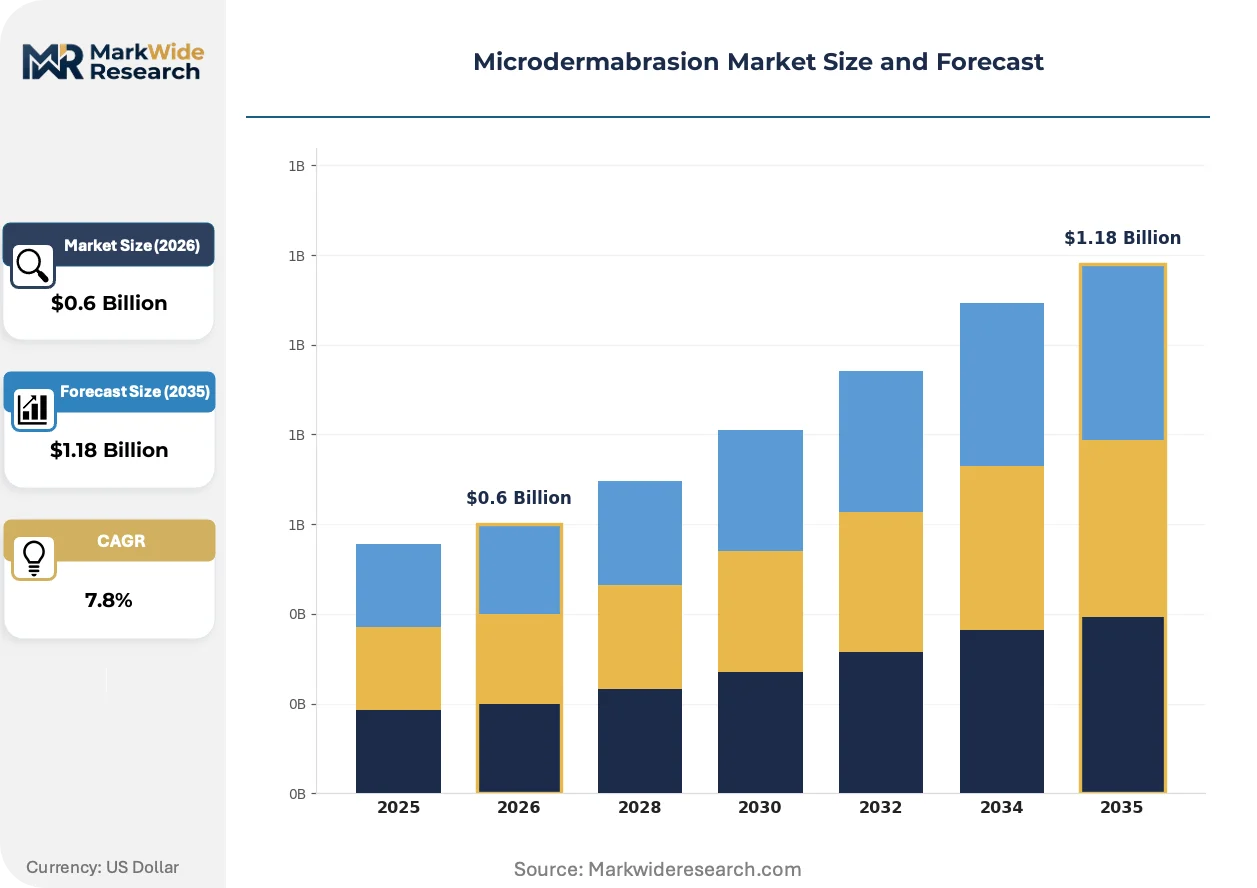
Equipment financing structures and tightening FDA 510(k) pathways are compressing development timelines while expanding addressable practice segments through reduced capital barriers.
Growth Catalysts
- EU Medical Device Regulation:Reclassification of aesthetic devices under MDR intensifies clinical evidence requirements, filtering substandard competitors and elevating compliant OEM margins.
- Dermatology clinic expansion:Physician-owned practices and medspa chains drive professional device procurement as patient volumes rise for non-invasive facial rejuvenation procedures.
- Diamond-tip systems:Reduced particle dispersion and lower consumable dependency compared to crystal-based alternatives accelerate technology preference shifts in clinical settings.
Market Restraints
- Consumable attachment economics:Recurring revenue dependency on proprietary tips and serums creates margin pressure when supply chains face input volatility.
- FDA clearance timelines:Material and efficacy requirement tightening extends development cycles for new entrants, compressing competitive response windows.
- Home-use device substitution:Clinic-grade result expectations from consumer devices threaten professional treatment frequency among price-sensitive segments.
Strategic Opportunities
- Pay-per-procedure financing:Mid-size dermatology practices and independent medspas access professional-grade systems without capital expenditure concentration.
- ISO 13485 multi-jurisdiction manufacturing:Quality management standardization enables OEMs to serve distributed clinical and retail channels from unified production bases.
- Dual-channel distribution:Simultaneous clinical setting and authorized retail partner servicing captures professional and maintenance-use demand within unified brand ecosystems.
Industry Challenges
- Cosmetic-medical classification boundaries:Regulatory reclassification triggers substantial compliance investments and channel restructuring for device portfolios spanning both categories.
- Consumable stream integration:Proprietary attachment ecosystems require continuous R&D coordination between hardware engineering and topical formulation chemistry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microdermabrasion Market |
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.18 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diamond Microdermabrasion, Crystal Microdermabrasion, Home Use Devices, Professional Devices Application: Facial Treatment, Body Treatment, Scar Reduction, Anti-Aging End User: Dermatology Clinics, Beauty Salons, Home Users, Hospitals Technology: Dual Action, LED Technology, Vacuum Technology, Manual Technique |
| Companies Covered | Lumenis Ltd, Johnson & Johnson, Koninklijke Philips N.V., Altair Instruments, Skin for Life, HydraFacial LLC, PMD Beauty, Envy Medical, Inc., Silhouet-Tone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microdermabrasion Market Strategic Shifts
Mechanical exfoliation technology is converging with vacuum-assisted delivery systems and topical infusion protocols, reshaping treatment protocols and device architecture requirements.
Microdermabrasion is hybridizing with hydradermabrasion and serum infusion capabilities, enabling simultaneous exfoliation and active ingredient delivery. Medspa chains and physician-owned dermatology practices are adopting these integrated platforms to compress treatment times and elevate per-session revenue. The technology is hybridizing previously separate procedure categories, forcing standalone device manufacturers to expand platform functionality or cede placement volume to ecosystem providers.
EU MDR clinical evidence obligations are intensifying post-market surveillance requirements for aesthetic device manufacturers. The regulation mandates sustained safety documentation and periodic performance reviews, elevating compliance infrastructure costs. Class IIa and IIb device reclassifications most heavily impact crystal-based system OEMs, which must now generate clinical data previously unnecessary for market access.
Subscription-based consumable replenishment is displacing traditional bulk purchasing among high-volume dermatology practices. The model locks practices into proprietary tip and serum ecosystems while smoothing manufacturer revenue predictability. California and Texas medspa concentrations exhibit the fastest behavioral transition, with chains negotiating enterprise-level replenishment contracts tied to device placement commitments.
Microdermabrasion Market Segmentation
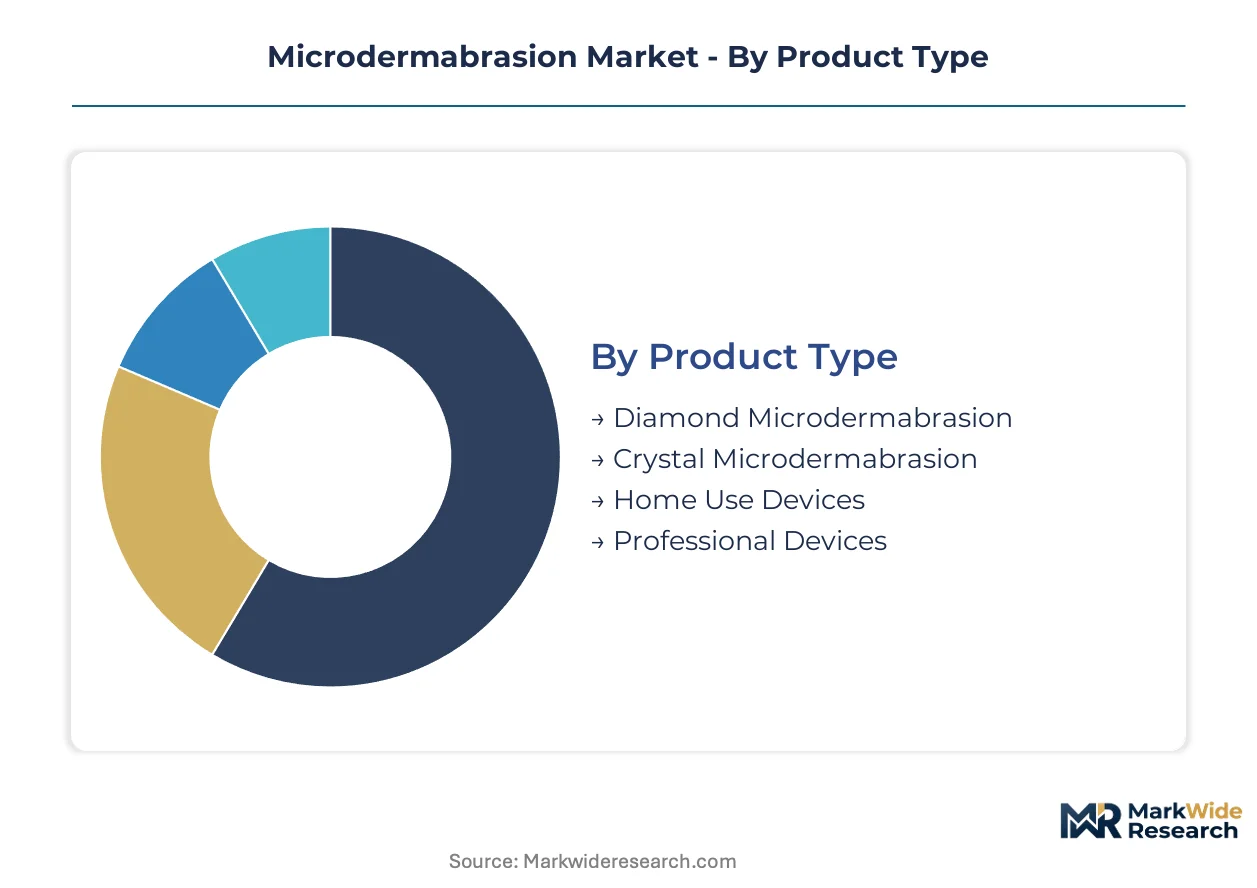
Technology heterogeneity in microdermabrasion creates distinct procurement patterns across clinical and consumer channels. Device architecture choices directly determine consumable economics, regulatory pathway complexity, and end-user training requirements.
Product Type:
Cost tier stratification separates capital-intensive professional systems from accessible consumer alternatives, with technology modality driving lifetime ownership economics.
- Diamond Microdermabrasion:Diamond-tipped wands abrade the stratum corneum through direct mechanical contact, eliminating crystal dispersion and reducing consumable dependency. Demand concentrates in physician-owned dermatology practices and medspa chains across the United States, where particle-free operation simplifies OSHA compliance and facility hygiene protocols.
- Crystal Microdermabrasion:Pressurized aluminum oxide or sodium bicarbonate crystals strike the skin surface at controlled velocities, requiring dedicated filtration systems and particle containment infrastructure. Beauty salons and lower-tier clinical settings in price-sensitive European markets retain preference for lower upfront equipment costs despite higher ongoing consumable expenditure.
- Home Use Devices:Compact, battery-operated or plug-in units deliver reduced vacuum pressure and simplified exfoliation for consumer maintenance between professional treatments.
- Professional Devices:Clinical-grade systems integrate adjustable vacuum pressures, multiple handpiece configurations, and sterilization-compatible construction for high-throughput environments.
Professional devices hold installed capacity. Home use devices are rotating up the share rankings.
Application:
Volume concentration varies by procedure reimbursement status and consumer willingness to pay for aesthetic outcomes.
- Facial Treatment:Full-face exfoliation protocols dominate procedure volume, addressing photodamage, fine lines, and texture irregularities through standardized treatment zones. Medspa chains in California and Texas drive demand concentration, bundling microdermabrasion with hydradermabrasion and serum infusion to elevate per-session revenue.
- Scar Reduction:Targeted application to acne scarring, surgical scars, and striae distensae requires modified treatment parameters and extended session protocols. Dermatology clinics in Germany and France prioritize scar-focused devices for patient populations seeking medical-grade outcomes from aesthetic procedures.
- Body Treatment:Extended treatment areas including décolletage, hands, and back require larger handpiece surfaces and enhanced vacuum capacity.
- Anti-Aging:Preventive and corrective protocols targeting collagen stimulation and epidermal turnover for mature skin demographics.
Facial treatment commands procedure volume leadership. Scar reduction is climbing the fastest as clinical evidence accumulates.
End User:
Customer type determines purchasing authority, financing preference, and device specification requirements.
- Dermatology Clinics:Physician-supervised practices demand FDA 510(k)-cleared or EU MDR-compliant systems with documented clinical efficacy, prioritizing liability protection and reimbursement documentation. These settings exhibit the steepest expansion trajectory as patient volumes rise for non-invasive facial rejuvenation procedures.
- Beauty Salons:Non-medical aesthetic providers operate under lighter regulatory burdens in most jurisdictions, selecting lower-cost systems without medical device classification.
- Home Users:Individual consumers purchasing through authorized retail partners or direct-to-consumer channels seek clinic-grade results with simplified operation.
- Hospitals:Outpatient departments and ambulatory surgery centers integrate microdermabrasion into broader dermatologic service lines, requiring enterprise procurement compatibility.
Dermatology clinics hold installed capacity. Beauty salons are rotating up the share rankings.
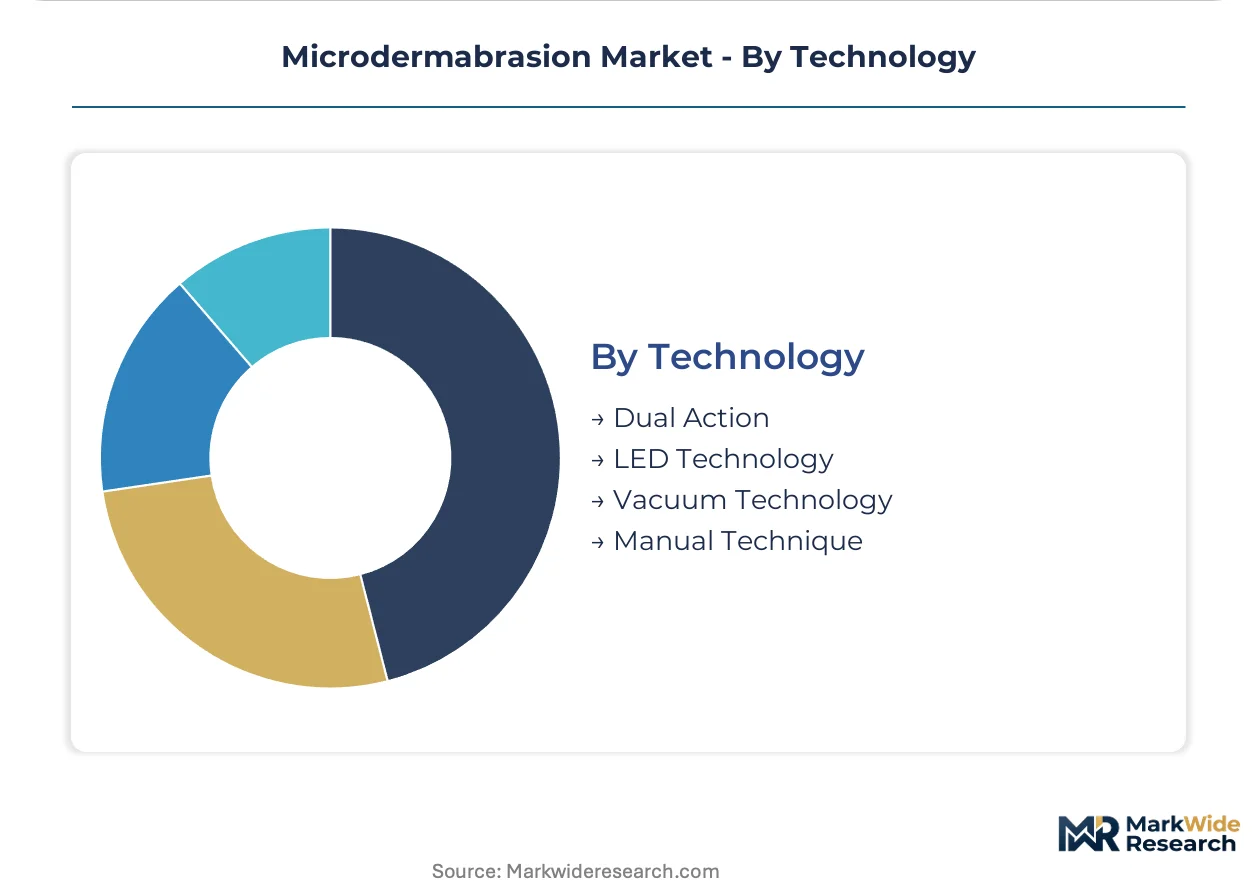
Technology:
Maturity differentiation separates established vacuum-assisted systems from emerging hybrid modalities.
- Vacuum Technology:Negative pressure systems operating at 60-90 mmHg enable controlled exfoliation depth and simultaneous debris removal, forming the foundational architecture for clinical-grade devices. Diamond and crystal modalities both deploy vacuum assistance, with pressure adjustability distinguishing professional from consumer implementations.
- Dual Action:Integrated platforms combining mechanical exfoliation with simultaneous serum infusion or hydradermabrasion capabilities compress treatment times and expand addressable indications.
- LED Technology:Photobiomodulation adjuncts targeting collagen synthesis and inflammation reduction following exfoliation.
- Manual Technique:Non-mechanized exfoliation methods requiring practitioner skill without powered assistance.
Vacuum technology holds installed capacity. Dual action systems are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR reclassification and FDA 510(k) pathway tightening are reshaping competitive access across major markets, while equipment financing innovation expands addressable practice segments. Dermatology clinic expansion and medspa chain consolidation concentrate procurement authority in specific metropolitan clusters.
United States
Medspa chains and physician-owned dermatology practices in California and Texas drive professional device procurement as patient volumes surge for non-invasive facial rejuvenation. FDA 510(k) clearance requirements govern safety and efficacy claims, extending development timelines for new entrants. Los Angeles and Dallas-Fort Worth anchor the fastest-growing practice concentrations, with enterprise-level replenishment contracts locking chains into proprietary consumable ecosystems.
Germany
Dermatology clinics in Berlin and Munich prioritize scar-focused devices for patient populations seeking medical-grade outcomes from aesthetic procedures. EU MDR intensifies clinical evidence obligations for Class IIa and IIb device reclassifications, filtering substandard competitors. The Rhine-Ruhr corridor hosts the densest concentration of compliance-focused OEMs serving distributed clinical channels.
United Kingdom
Beauty salons and lower-tier clinical settings retain preference for crystal-based systems despite higher ongoing consumable expenditure, though diamond-tip adoption accelerates in London medical aesthetics practices. MHRA alignment with EU MDR post-Brexit maintains stringent quality management expectations. Harley Street and Manchester city center clusters exhibit steepest technology preference shifts toward particle-free operation.
France
ANSM oversight of aesthetic device classification creates regulatory clarity for manufacturers navigating cosmetic-medical boundaries. Paris and Lyon dermatology practices lead adoption of hybrid platforms combining mechanical exfoliation with serum infusion capabilities. The Île-de-France region concentrates pay-per-procedure financing uptake among independent medspas seeking professional-grade systems without capital expenditure concentration.
Japan
PMDA medical device registration requirements shape market access for foreign OEMs targeting high-value aesthetic practices. Tokyo and Osaka metropolitan areas drive demand for compact professional systems suited to space-constrained clinic environments. Kansai region medspa chains pioneer subscription-based consumable replenishment models smoothing manufacturer revenue predictability.
Microdermabrasion Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tiers where no single vendor commands dominant share. The vendor base spans diversified healthcare conglomerates, dedicated aesthetic device manufacturers, and emerging consumer-facing brands. Three archetypes predominate: ecosystem providers locking practices into proprietary consumable streams, dual-channel distributors serving clinical and retail segments simultaneously, and financing-integrated lessors reducing capital barriers for mid-size practices. Competitive moves concentrate on strategic partnerships with medspa chains and portfolio diversification into hybrid treatment platforms.
Among diversified healthcare conglomerates, Johnson & Johnson and Koninklijke Philips N.V. occupy positions anchored by institutional relationships and multi-jurisdiction distribution infrastructure. HydraFacial LLC exemplifies the ecosystem provider archetype, representing vendors that control proprietary consumable streams tied to device placement. These three entities illustrate the strategic divergence between scale-driven channel access and vertical integration into recurring revenue models.
| Leading Market Players |
|---|
| Lumenis Ltd |
| Johnson & Johnson |
| Koninklijke Philips N.V. |
| Altair Instruments |
| Skin for Life |
| HydraFacial LLC |
| PMD Beauty |
| Envy Medical, Inc. |
| Silhouet-Tone |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Ruhr corridor anchors OEM manufacturing capacity for diamond-tipped wands and vacuum pump assemblies, concentrating component sourcing leverage that filters downstream into professional device pricing power across European and North American distribution channels.
Pricing Analysis
Certification level creates the primary spread between FDA 510(k)-cleared professional systems and unclassified beauty salon alternatives. Three-tier pricing structure across premium clinical-grade, standard professional, and economy consumer levels reflects ISO 13485 compliance investment and clinical evidence burden. Cost compression in the standard tier is intensifying because EU MDR reclassification demands elevate quality management overhead. Independent medspas exhibit highest price sensitivity due to capital constraint, while hospital outpatient departments prioritize liability protection over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for aluminum oxide crystal feedstock and miniature vacuum pump motors. Component sourcing concentrates in Germany, China, and Japan for precision-machined diamond tips, medical-grade filtration membranes, and control electronics. Raw material dependency on synthetic diamond substrates, biocompatible plastics, and specialized aluminum oxide powders creates input volatility when commodity markets fluctuate. Distribution runs through authorized clinical distributors for professional systems and direct-to-consumer channels for home-use devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as HydraFacial's consumable-tied ecosystem demonstrates how proprietary attachment streams capture lifetime customer value and compress standalone device margins.
For Market Incumbents: Entrench placement volume through pay-per-procedure financing partnerships with medspa chains, locking practices into proprietary tip replenishment contracts. Deepen backward integration into diamond substrate manufacturing to defend margin position against crystal-based substitute technologies. Prioritize ISO 13485 multi-jurisdiction certification investment to filter substandard competitors under EU MDR intensification. For New Entrants and Emerging Players: Pursue scar-reduction application specialization where clinical evidence accumulation creates differentiation headroom against facial-treatment incumbents. Target beauty salon channels in price-sensitive European markets with lower-cost crystal systems that bypass FDA 510(k) burden. Deploy direct-to-consumer home-use positioning with clinic-grade vacuum pressure claims as the go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ecosystem providers with captive consumable revenue streams over hardware-only manufacturers facing substitution pressure. Five-to-ten year viability concentrates on dual-channel distribution capability spanning clinical procurement and authorized retail. Watch subscription-based replenishment contract penetration rates as the signal for platform economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Pathway | Clinical evidence investment filters substandard competitors and elevates compliant OEM margins. |
| Pay-per-Procedure Financing Launch | Equipment leasing reduces capital barriers for mid-size dermatology practices and independent medspas. |
| Proprietary Consumable Ecosystem | Locked-in tip and serum replenishment contracts smooth manufacturer revenue predictability. |
| Dual-Channel Distribution Buildout | Simultaneous clinical and retail servicing captures professional and maintenance-use demand. |
| Hybrid Platform Integration | Hydradermabrasion and serum infusion capabilities compress treatment times and elevate per-session revenue. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic owners, medspa chain procurement directors, biomedical equipment engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data for aesthetic device imports. Bottom-up installed base estimates triangulated against top-down market sizing from equipment financing disclosure patterns.
Calibration against historical placement volumes and consumable attachment shipment data anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology modality, certification tier, end-user channel, and application focus. CAGRs were derived from regression analysis of procedure volume growth against device replacement cycles and consumable replenishment frequency. Industry-specific forecast inputs incorporated EU MDR implementation timelines and medspa chain consolidation patterns.
Sensitivities concentrate around regulatory reclassification boundaries between cosmetic and medical devices, consumable supply chain disruption, and home-use device substitution rates. Forecasts reflect documented assumptions regarding patient volume growth, financing penetration, and competitive response windows. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Hirsutism Market
Dermatology
Dermal Facial Fillers Market
Dermatology
Folliculitis Treatment Market
Dermatology
Derma Rollers Market
Dermatology
Lentigo Maligna Melanoma Therapeutic Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
Japan Scar Treatment Market
Dermatology
Scar Treatment Oils Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Keratoacanthoma Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Erythema Treatment Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Global Rosacea Market