
 Rafting Equipment Market | 2026-2036
Rafting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Rafting Equipment Market Analytics
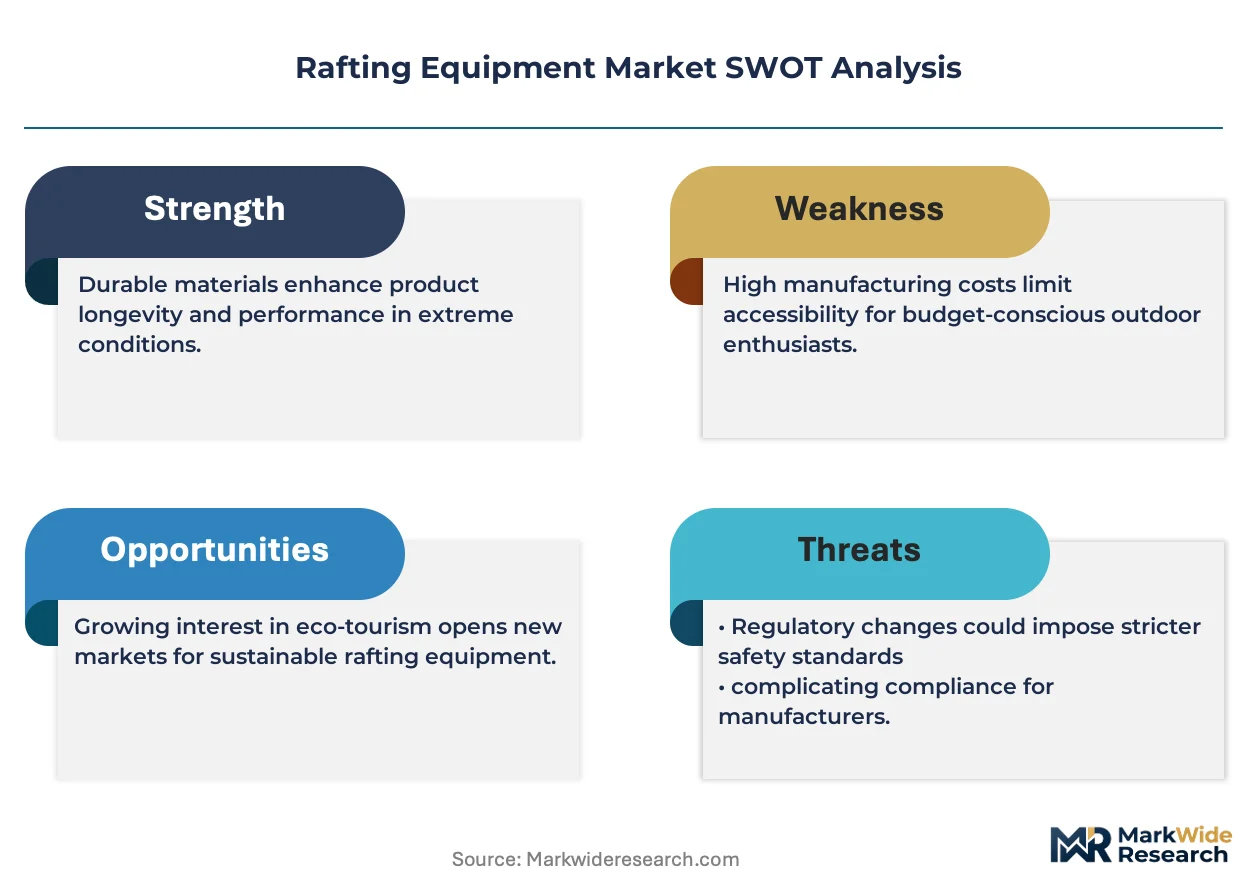
ISO 6185 inflatable boat certification is bifurcating the competitive landscape into qualified suppliers and marginal entrants. NRS leverages its vertically integrated manufacturing campus in Moscow, Idaho to control raft fabric supply from weaving through RF welding. HYSIDE Inflatables anchors its position through proprietary Hypalon-compatible coating chemistry developed for high-UV desert river environments. AIRE sustains market presence by operating a full-time river testing program on Idaho's Payette and Salmon watersheds, feeding design iteration directly from guide feedback loops.
Rafting equipment encompasses purpose-built inflatable and rigid-hull watercraft plus associated protective and propulsion gear designed for navigating turbulent river environments. Modern expedition rafts employ multi-chamber air retention with pressure-rated Boston valves, 4000+ denier bottom fabrics, and internally laced self-bailing floors rated for repeated rock impact at flows exceeding 5,000 cubic feet per second. Inflatable Rafts and Safety Equipment command the dominant value share, as commercial liability insurers mandate helmet, PFD, and throw bag replacement cycles that recur regardless of macro conditions. Kayaks within the rafting equipment category represent the fastest-growing product type, driven by packraft crossover adoption among backcountry fishing and hunting segments seeking sub-ten-pound portage solutions. The Application dimension shows Adventure Sports and Competition segments carrying premium pricing power, while Recreational Use volume concentrates through big-box retail channels with compressed margin structures.
US Coast Guard flotation device standards, EU CE marking under the Recreational Craft Directive, and New Zealand Maritime Rule Part 40 collectively govern product market access and liability exposure across major demand clusters. These frameworks impose testing protocols that favor manufacturers with in-house certification engineering rather than outsourced compliance documentation. Stakeholders must monitor evolving river access permit systems and watershed-level capacity restrictions, as regulatory scarcity of commercial launch slots directly constrains fleet expansion decisions irrespective of equipment demand signals.
Market Dynamics
Polyurethane-coated fabric welding and drop-stitch floor construction are compressing replacement cycles while extending vessel service life, fundamentally altering how commercial outfitters calculate fleet economics and capital deployment timelines.
Growth Catalysts
- Permit scarcity mechanics:Tightening Class III-IV allocations under US Forest Service and Bureau of Land Management frameworks force commercial operators to maximize utilization per vessel, driving premium equipment upgrades rather than fleet expansion.
- Drop-stitch floor technology:This construction method enables rigid-hull performance in inflatable platforms, opening packraft crossover demand from backcountry hunting and fishing segments seeking sub-ten-pound portage solutions.
- Liability insurance mandates:Commercial liability carriers enforce helmet, PFD, and throw bag replacement cycles that recur regardless of macroeconomic conditions, creating resilient recurring revenue streams for safety equipment suppliers.
Market Restraints
- Petrochemical input volatility:Polyurethane and PVC resin prices fluctuate with crude oil indices, compressing margin predictability for fabric manufacturers dependent on petroleum-derived coating chemistry.
- Fabric supply concentration:Weaving and RF welding capabilities cluster in specific manufacturing corridors, creating single-source vulnerability for raft builders lacking captive textile production.
- Hypalon material obsolescence:Environmental regulations restricting chlorosulfonated polyethylene production are forcing reformulation investments for high-UV desert river applications previously dependent on this compound.
Strategic Opportunities
- Slovenia's Soca Valley expansion:Commercial outfitter density remains below saturation thresholds in this Alpine corridor, presenting fleet penetration potential for expedition-grade vessel suppliers.
- ISO 6185 certification arbitrage:Qualified suppliers can capture share from marginal entrants unable to meet inflatable boat testing protocols, consolidating position in commercial procurement channels.
- RF welding equipment leasing:In-house fabrication capabilities allow mid-size operators to bypass traditional supplier relationships, creating equipment financing and technical training service revenue streams.
Industry Challenges
- River access permit acquisition timelines:US Forest Service and Bureau of Land Management lottery systems create multi-year uncertainty for fleet expansion planning, complicating capital commitment decisions.
- Certification engineering talent scarcity:In-house compliance documentation capabilities require specialized expertise in flotation device standards and CE marking under the Recreational Craft Directive, constraining manufacturer scaling velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rafting Equipment Market |
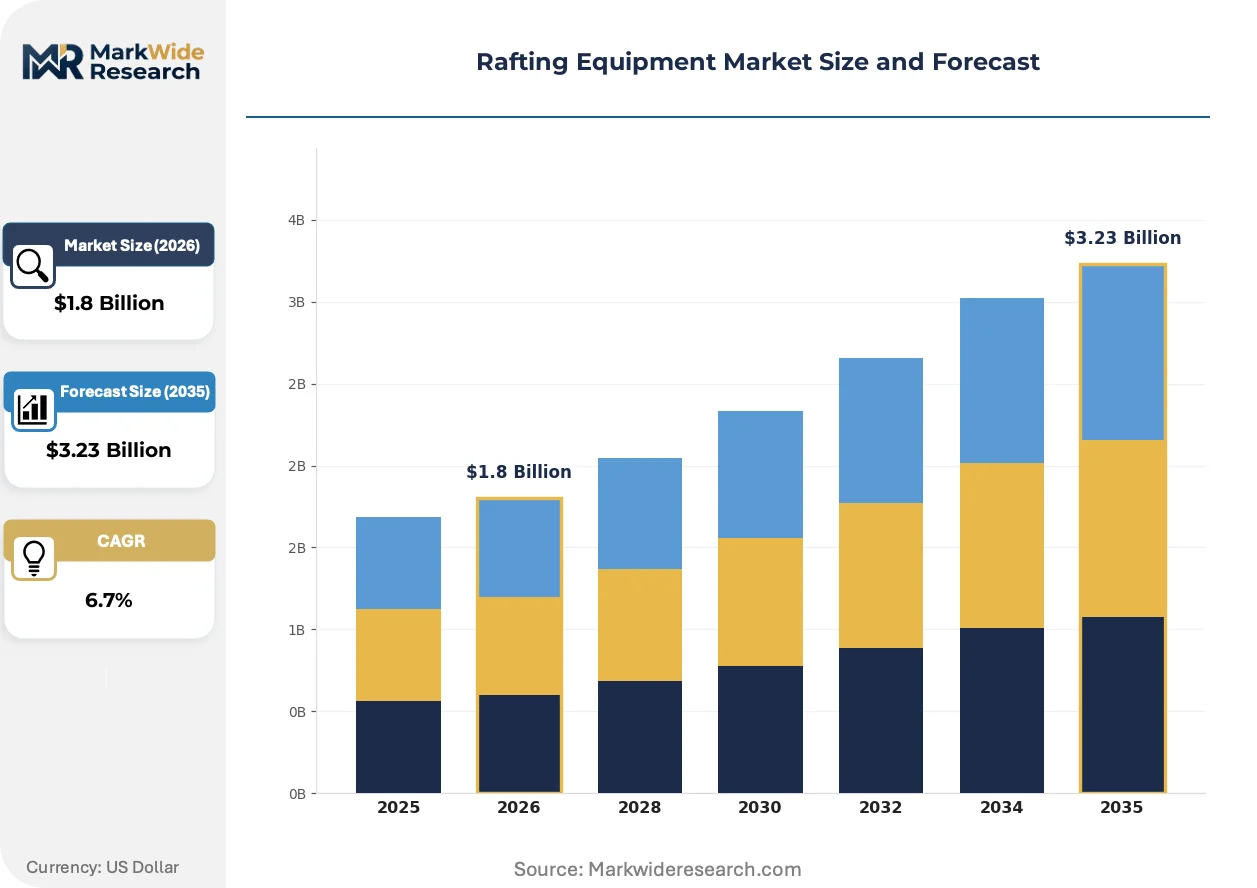
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Rafts, Kayaks, Rafting Gear, Safety Equipment Application: Adventure Sports, Recreational Use, Competition, Training End User: Outdoor Enthusiasts, Tour Operators, Sports Teams, Schools Distribution Channel: Retail Stores, E-Commerce, Specialty Shops, Rental Services |
| Companies Covered | AIRE, HYSIDE Inflatables, Maravia, NRS, SOTAR, Rogue Rafts, Aqua Marina, Rave Sports, Advanced Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rafting Equipment Market Evolving Landscape
Equipment fabrication methods and procurement patterns are diverging between commercial tour operators and recreational buyers, with technology adoption rates splitting along liability exposure and utilization intensity lines.
Drop-stitch floor construction is supplanting traditional glued PVC assemblies in expedition raft manufacturing. Commercial operators running Idaho's Payette and Salmon watersheds at flows exceeding 5,000 cubic feet per second are adopting these platforms for repeated rock impact resistance. This shift is compressing replacement demand for conventional multi-chamber designs while elevating price floors for premium-tier vessels.
EU CE marking under the Recreational Craft Directive is tightening market access requirements for inflatable boat imports. Manufacturers lacking in-house certification engineering face documentation bottlenecks that favor established suppliers with dedicated compliance teams. The commercial tour segment across New Zealand's South Island is responding by consolidating procurement around qualified vendors rather than testing marginal entrants.
Commercial liability insurers are unbundling safety equipment from vessel procurement packages. Outfitters across the Pacific Northwest and Colorado River basin are now sourcing helmets, PFDs, and throw bags through specialized channels with compressed replacement cycles. This pattern is most visible in the United States, where mandated refresh schedules operate independently of macro demand signals.
Rafting Equipment Market Segmentation
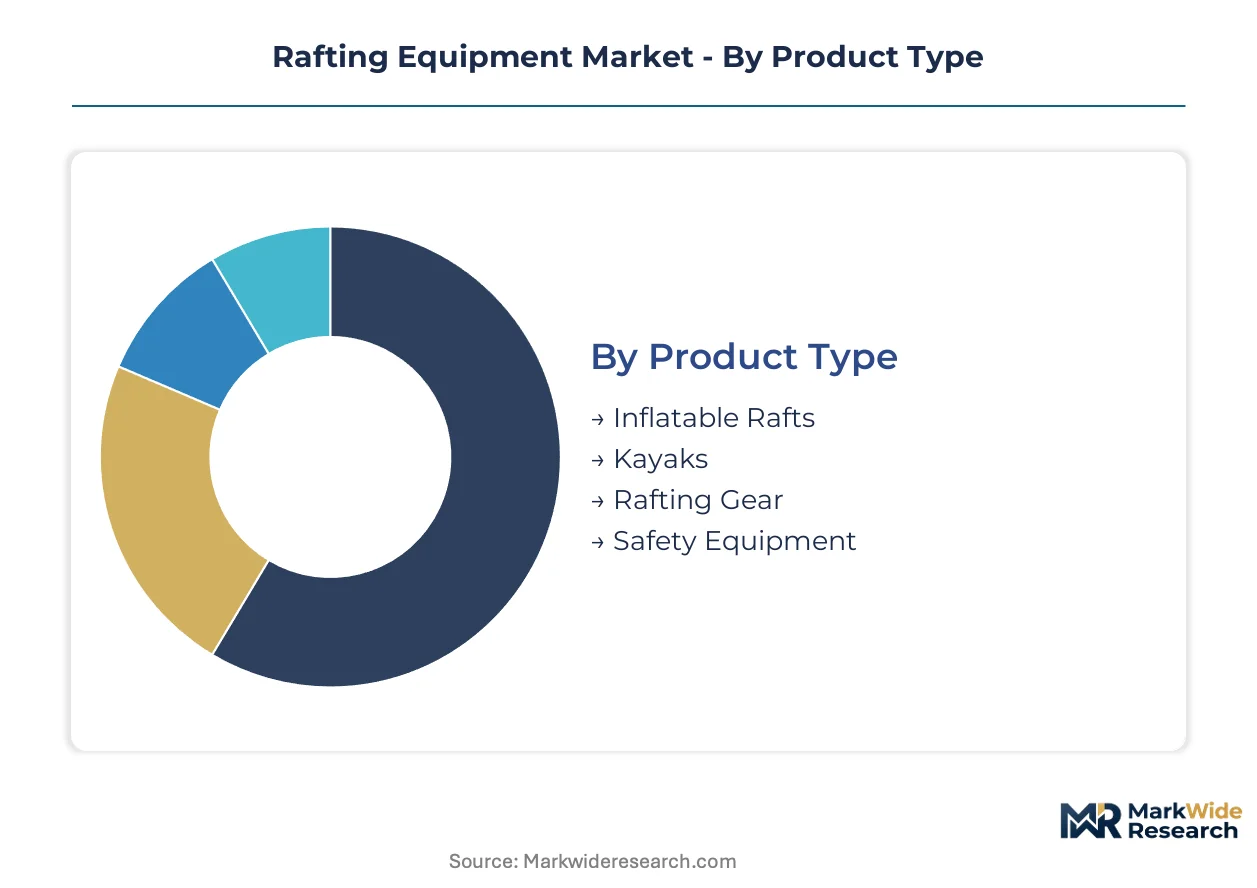
Rafting equipment segmentation reflects divergent compliance burdens across product categories. US Coast Guard flotation standards, EU CE marking under the Recreational Craft Directive, and ISO 6185 inflatable boat certification create tiered market access that fragments procurement channels and margin structures.
Product Type:
Regulatory differentiation separates certified commercial-grade equipment from recreational consumer goods, with certification engineering capabilities determining supplier viability in institutional channels.
- Inflatable Rafts:Multi-chamber air retention systems with pressure-rated Boston valves and 4000+ denier bottom fabrics withstand repeated rock impact at flows exceeding 5,000 cubic feet per second. Demand concentrates among commercial tour operators across the Pacific Northwest and Colorado River basin, where Class III-IV permit scarcity forces premium fleet upgrades rather than volume expansion.
- Safety Equipment:Helmets, PFDs, and throw bags carry mandatory replacement cycles enforced by commercial liability insurers regardless of macroeconomic conditions. This segment commands resilient recurring revenue as US Forest Service and Bureau of Land Management permit holders must maintain compliant gear inventories to retain operating licenses.
- Kayaks:Packraft crossover designs with drop-stitch floor construction enable sub-ten-pound portage solutions for backcountry hunting and fishing segments.
- Rafting Gear:Paddles, dry bags, and repair kits complete expedition outfitting with lower certification barriers than flotation devices.
Established volume favors Inflatable Rafts; emerging adoption favors Kayaks.
Application:
Cost tier differentiation separates premium-priced commercial operations from compressed-margin consumer retail, with liability exposure driving equipment specification divergence.
- Adventure Sports:Commercial guided trips on Class III-IV whitewater require expedition-grade vessels with welded polyurethane-coated fabric construction. Slovenia's Soca Valley and New Zealand's South Island outfitters prioritize durability over upfront cost given utilization intensity.
- Competition:Slalom and downriver racing circuits demand lightweight, high-performance hull designs with specialized geometry for gate navigation and sprint speed.
- Recreational Use:Big-box retail channels dominate with price-sensitive consumers seeking entry-level PVC constructions for occasional flatwater and mild whitewater exposure.
- Training:Schools and certification programs require standardized fleet configurations to ensure consistent instruction across cohorts.
Premium pricing power concentrates in Adventure Sports; volume scale concentrates in Recreational Use.
End User:
Customer type determines procurement sophistication, with institutional buyers leveraging technical specifications against fragmented consumer decision-making.
- Tour Operators:Commercial permit holders across the US Forest Service and Bureau of Land Management systems calculate fleet economics around extended service life from drop-stitch floor technology.
- Outdoor Enthusiasts:Individual buyers researching packraft solutions for backcountry access represent the fastest-climbing adoption trajectory within the category.
- Sports Teams:Competitive programs require standardized equipment for fair event participation and team logistics coordination.
- Schools:Educational institutions prioritize bulk procurement with simplified maintenance protocols and standardized training curricula.
Procurement concentration favors Tour Operators; fragmentation favors Outdoor Enthusiasts.
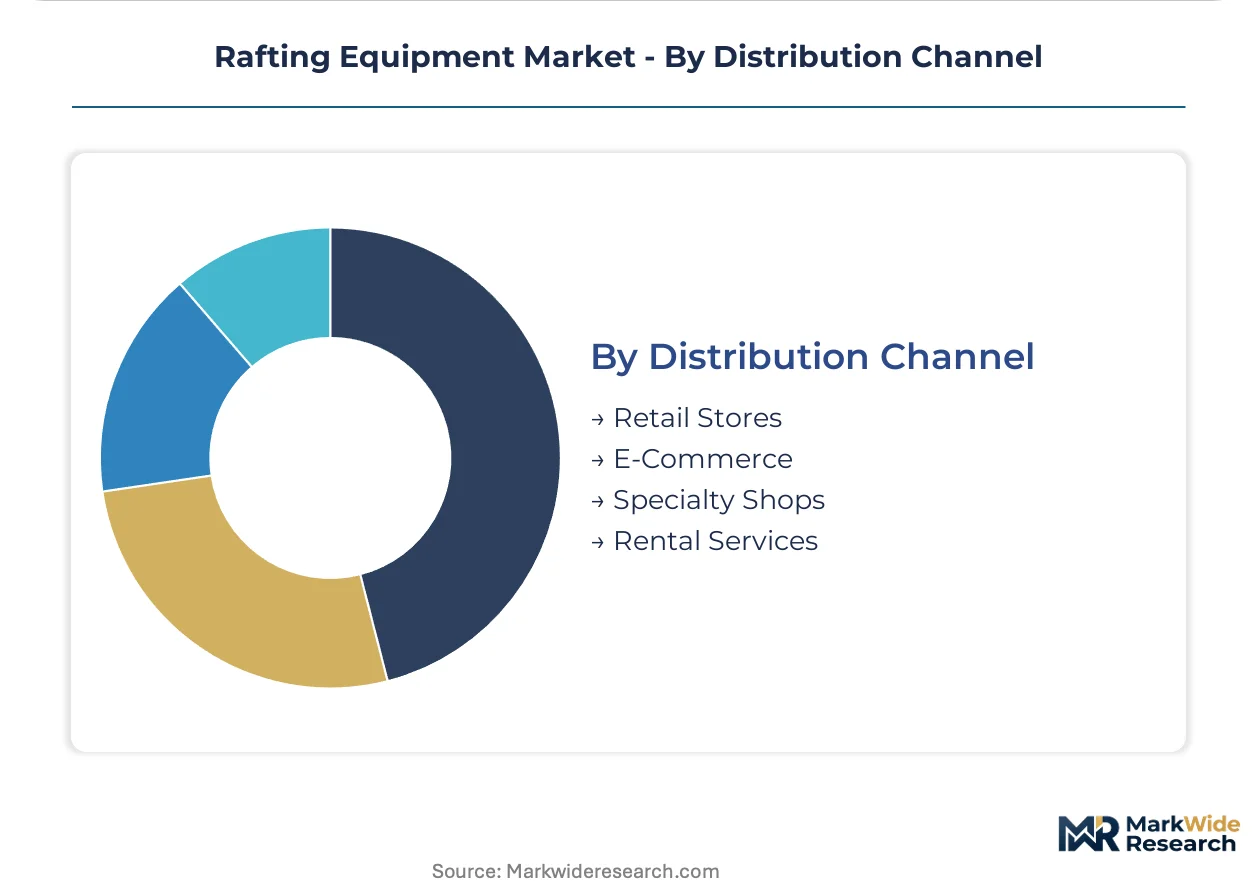
Distribution Channel:
Supply concentration in fabric weaving and RF welding corridors shapes channel economics, with proximity to manufacturing determining inventory velocity and technical support availability.
- Specialty Shops:Moscow, Idaho and comparable manufacturing-adjacent locations offer direct technical consultation on Hypalon-compatible coating chemistry and custom fabrication options.
- Rental Services:Fleet operators in permit-constrained watersheds generate secondary revenue through equipment leasing to unlicensed recreational users.
- E-Commerce:Direct-to-consumer platforms capture packraft demand from dispersed backcountry hunting and fishing segments lacking local specialty access.
- Retail Stores:Big-box channels move high-volume recreational inventory with compressed margin structures and limited technical service capabilities.
Technical integration favors Specialty Shops; reach expansion favors E-Commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial tour operators concentrate procurement decisions in watersheds with active permit allocation systems, while recreational demand disperses across regions with accessible whitewater resources.
United States
Class III-IV permit scarcity under US Forest Service and Bureau of Land Management frameworks forces commercial operators toward premium fleet upgrades rather than volume expansion. US Coast Guard flotation device standards govern safety equipment compliance across all navigable waters. The Pacific Northwest and Colorado River basin anchor commercial outfitter density, with Moscow, Idaho hosting vertically integrated manufacturing corridors.
New Zealand
Guided rafting sectors on the South Island drive expedition-grade vessel procurement for high-utilization commercial operations. Maritime Rule Part 40 imposes certification requirements that favor qualified suppliers over marginal entrants. Queenstown and Canterbury regional clusters concentrate outfitter activity around accessible Alpine whitewater corridors.
Slovenia
The Soca Valley commercial outfitter market remains below saturation thresholds, presenting fleet penetration opportunities for expedition-grade suppliers. EU CE marking under the Recreational Craft Directive restricts market access for non-compliant imports. Bovec and Kobarid sub-regions anchor commercial rafting infrastructure along the emerald Alpine river system.
Canada
Western province outfitters on the Kicking Horse and Ottawa Rivers source equipment through cross-border procurement channels tied to US manufacturing corridors. Transport Canada flotation device regulations align closely with USCG standards, simplifying supplier qualification processes. British Columbia and Ontario concentrate commercial permit allocations under Parks Canada and provincial park frameworks.
Australia
Tasmanian and Queensland commercial operators on the Franklin and Tully Rivers operate under state-level environmental licensing that constrains fleet expansion timelines. The Australian Maritime Safety Authority governs commercial vessel certification with standards comparable to ISO 6185 protocols. Cairns and Hobart metropolitan areas anchor regional outfitter procurement decisions.
Rafting Equipment Market Competitive Landscape
Player mix skews toward specialized fabricators with captive textile production or proprietary coating chemistry rather than diversified recreational marine conglomerates. The vendor base separates into three strategic archetypes: vertically integrated manufacturers controlling fabric supply from weaving through RF welding, coating chemistry specialists with proprietary formulations for high-UV environments, and design-forward operators with embedded river testing programs. Dominant competitive moves include backward integration into fabric weaving capabilities and certification engineering investments that bypass outsourced compliance documentation bottlenecks.
Within the vertically integrated tier, NRS anchors manufacturing concentration in the Moscow, Idaho corridor through captive control of fabric supply chains. HYSIDE Inflatables occupies a position defined by proprietary coating chemistry specialization. AIRE exemplifies the river-testing archetype with embedded design iteration programs feeding directly from commercial guide feedback loops on Idaho watersheds.
| Leading Market Players |
|---|
| AIRE |
| HYSIDE Inflatables |
| Maravia |
| NRS |
| SOTAR |
| Rogue Rafts |
| Aqua Marina |
| Rave Sports |
| Advanced Elements |
| Others |
Value Network & Pricing Analysis
Ninety-day fabric procurement lead times for 4000+ denier polyurethane-coated textiles concentrate pricing power with Moscow, Idaho-based weavers possessing RF welding capabilities, while commercial outfitters facing permit scarcity absorb premium vessel costs through extended utilization schedules rather than fleet expansion economics.
Pricing Analysis
Cost-plus contracts with crude oil indexation dominate raw material procurement for PVC and polyurethane resin inputs, compressing margin predictability for fabric manufacturers lacking captive petrochemical supply. Three-tier pricing structure across expedition-grade, commercial-standard, and entry-level recreational tiers separates ISO 6185-certified vessels from uncertified imports. Pricing pressure stems from petrochemical input volatility, with resin costs fluctuating in tandem with energy indices. Recreational buyers through big-box channels exhibit highest price sensitivity, while commercial tour operators prioritize service life and warranty terms over upfront vessel expenditure.
Supply Chain Analysis
Strategic stockpiling of Hypalon-compatible coating precursors prevails among high-UV desert river specialists anticipating environmental regulation-driven supply interruptions, contrasting with just-in-time fabric procurement among standard PVC assemblers. Manufacturing gravity centers on the United States, China, and Slovenia for expedition-grade vessel production. Raw material dependencies encompass petroleum-derived polyurethane resins, synthetic textile fibers, and proprietary coating chemistries. Single-source vulnerability concentrates in RF welding equipment and specialized fabric weaving corridors. Distribution runs through specialty shops adjacent to manufacturing clusters, direct-to-consumer e-commerce for packraft segments, and rental services in permit-constrained watersheds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from hard-shell kayak manufacturers and inflatable SUP platforms encroaching on recreational whitewater participation, as packraft crossover adoption reshapes entry-point equipment preferences.
For Market Incumbents: Consolidate backward integration into fabric weaving and RF welding capabilities to bypass supplier concentration risk in polyurethane-coated textile corridors. Deepen ISO 6185 certification engineering investments to capture procurement share from commercial operators abandoning marginal entrants facing documentation bottlenecks under EU CE marking requirements. For New Entrants and Emerging Players: Anchor in Slovenia's Soca Valley commercial outfitter market, where expedition-grade vessel penetration remains below saturation thresholds and EU regulatory barriers filter established competitors. Target packraft crossover demand from backcountry hunting and fishing segments through sub-ten-pound portage solutions with drop-stitch floor construction, leveraging direct-to-consumer e-commerce channels to bypass specialty shop distribution concentration. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because ISO 6185 certification requirements and US Forest Service permit scarcity create structural barriers protecting qualified suppliers from price-erosion cycles typical of unconstrained recreational equipment categories. Monitor river access permit allocation volumes under Bureau of Land Management frameworks as the inflection signal; permit expansion would unlock fleet growth demand, while continued tightening forces utilization-maximization equipment upgrades with divergent margin profiles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fabric Weaving | Captive supply of 4000+ denier polyurethane-coated textiles insulates against petrochemical price volatility and single-source vulnerability. |
| ISO 6185 Certification Investment | In-house compliance engineering unlocks commercial procurement channels that marginal entrants cannot access under EU and USCG frameworks. |
| Drop-Stitch Floor Technology Licensing | Proprietary rigid-hull inflatable construction commands premium pricing from commercial operators seeking extended service life. |
| Slovenia Market Entry | First-mover positioning in the Soca Valley captures outfitter fleet expansion before saturation thresholds trigger consolidation. |
| RF Welding Equipment Leasing Program | Technical training and financing services create recurring revenue from mid-size operators seeking in-house fabrication capabilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of US Forest Service permit allocation databases, Bureau of Land Management river management frameworks, and commercial liability insurance underwriting guidelines, combining interviews with commercial outfitter fleet managers, rafting equipment procurement directors, and polyurethane fabric manufacturing engineers with validation against ISO 6185 certification records and EU Recreational Craft Directive compliance filings, employing bottom-up vessel shipment tallies and top-down adventure tourism expenditure estimates for triangulation.
Segmentation dimensions modeled encompass product type, application, end user, and distribution channel across the projection horizon, with CAGRs derived from permit allocation trajectory analysis and commercial fleet replacement cycle patterns. Forecast inputs incorporate Class III-IV whitewater participation rates, packraft crossover adoption curves from backcountry recreation segments, and regulatory scarcity mechanics affecting commercial launch slot availability.
Material uncertainties — permit lottery outcome volatility, petrochemical input price swings, and environmental regulation-driven Hypalon phase-out timelines — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained commercial operator utilization intensity and recreational packraft penetration trajectories. Revision becomes warranted when US Forest Service permit allocation volumes or EU coating chemistry restrictions cross thresholds that alter fleet expansion or material substitution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Spain Sports Tourism Market
Outdoor and Adventure Activities
North America Spectator Sports Market
Outdoor and Adventure Activities
Kayak Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
Global Hydration Backpack Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Leisure Centers Market
Outdoor and Adventure Activities
Global Climbing Shoes Market
Outdoor and Adventure Activities
Speed Chute Market
Outdoor and Adventure Activities
Global Ski Poles Market
Outdoor and Adventure Activities
Ski Gear and Equipment Market
Outdoor and Adventure Activities
Recreation Services Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Global Personal Watercraft Market
Outdoor and Adventure Activities
Skiing Equipment Market