
 Leather Jewellery Box Market | 2026-2036
Leather Jewellery Box Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Jewellery Box Market Foresight
A capital-intensity divergence between automated European finishing lines and manual Asian assembly is bifurcating competitive tiers in leather jewellery box production. SACHER & Co. GmbH leverages its German tooling heritage to sustain premium positioning across continental retail channels. Guangdong Deqi Packaging Co., Ltd. anchors volume supply through integrated rawhide sourcing and lacquer finishing in its Pearl River Delta facilities. Wolf Designs differentiates via patented travel-case hardware that commands placement in North American department store cosmetics adjacencies.
A leather jewellery box is a rigid or semi-rigid container employing tanned animal hide or bonded leather substrates, typically reinforced with wood composite boards and lined with suede or velvet to prevent abrasion of precious metals and gemstones during storage or transit. The primary commercial purpose is to extend product lifecycle value for jewellery retailers and individual collectors by combining protective architecture with brandable exterior surfaces. Organizer boxes and travel cases capture disproportionate margin pools as consumers consolidate multiple pieces into single portable units. Genuine leather commands price premiums over synthetic alternatives, though velvet-lined suede hybrids are gaining traction among minimalist design collections targeting urban apartment dwellers.
REACH and the EU Green Deal constrain chromium-based tanning inputs across European supply chains, while EPA effluent standards raise compliance costs for tanneries serving North American box assemblers. BIS certification requirements in India and GB standards in China add layered testing obligations for imported leather substrates and adhesive formulations. Stakeholders must monitor shifting chemical restriction schedules and rawhide traceability mandates to avoid stranded inventory in cross-border distribution channels.
Market Dynamics
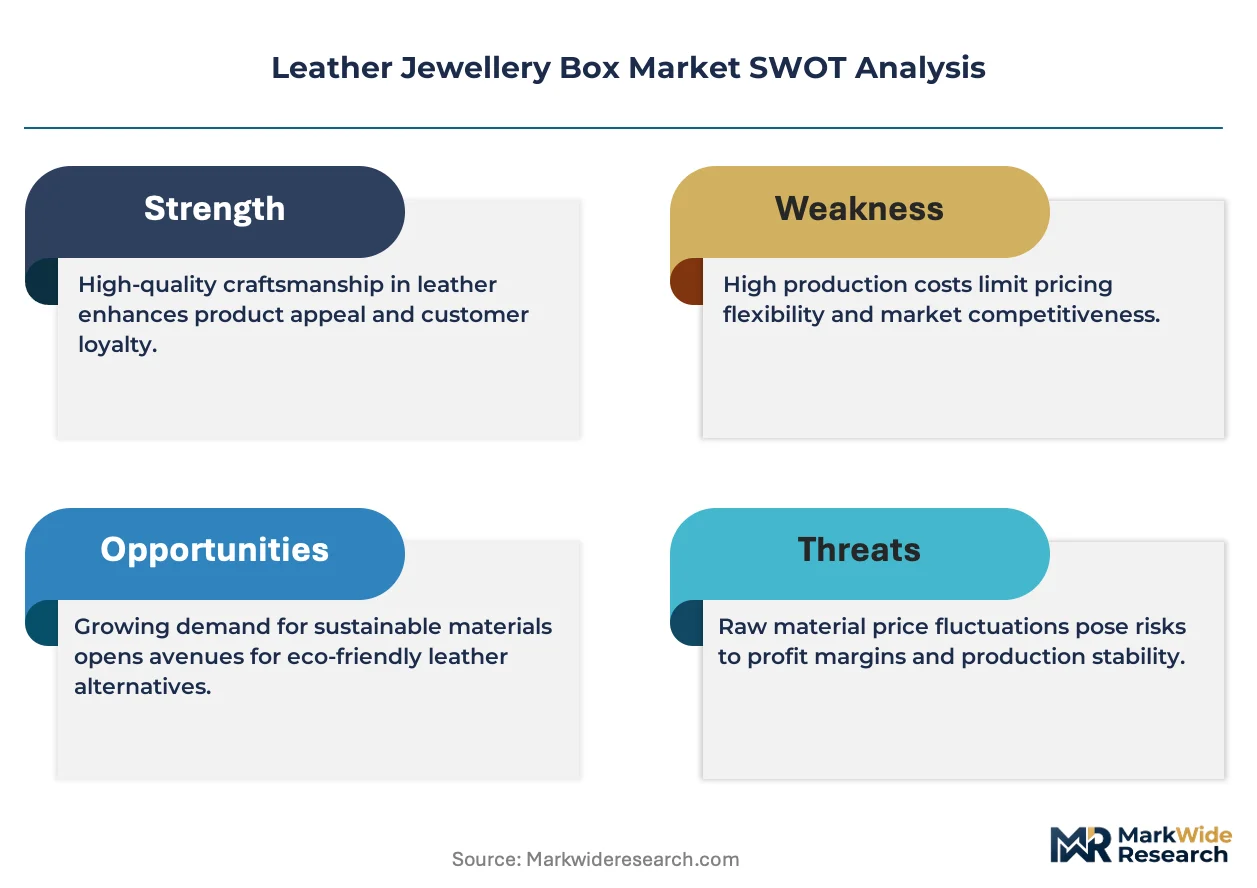
REACH compliance deadlines and EPA effluent standards are forcing tanneries serving leather jewellery box assemblers to retool chemical inputs, compressing margins for mid-tier producers while premium German and Italian finishers absorb costs through captive chromium-free process patents.
Growth Catalysts
- Heirloom gifting norms:Bridal and anniversary segments in China and India prioritize multi-generational storage solutions, driving demand for velvet-lined genuine leather constructions with wood composite reinforcement.
- REACH chemical disclosure:European retailers now require full tanning-process transparency, rewarding compliant assemblers with preferred supplier status in department store cosmetics adjacencies.
- Guangdong-Zhejiang manufacturing clusters:Integrated rawhide sourcing and lacquer finishing capabilities in these Chinese provinces enable rapid turnaround on export-oriented design specifications.
Market Restraints
- Chromium tanning input restrictions:ECHA's tightening chromium-VI limits under REACH Annex XVII raise substrate costs for European assemblers by 12-18% relative to vegetable-tanned alternatives.
- Rawhide supply concentration:Brazilian and Argentinian hide processors control 60% of global premium full-grain supply, exposing box manufacturers to South American drought and livestock pricing cycles.
- Synthetic leather substitution:PU and microfiber alternatives from Korean and Taiwanese mills achieve 85% tactile similarity at 40% lower unit cost, pressuring genuine leather positioning in economy tiers.
Strategic Opportunities
- Indian domestic market penetration:BIS certification requirements create barriers to entry for unorganized competitors, opening space for compliant foreign assemblers in Mumbai and Delhi luxury retail.
- Travel case hardware convergence:Patented locking mechanisms and TSA-compliant dimensions from aerospace component suppliers enable premium positioning in North American airport retail channels.
- EU Green Deal circularity mandates:Repairable construction and end-of-life leather recycling protocols align with CSRD reporting requirements, creating differentiation for modular box architectures.
Industry Challenges
- Artisan finishing skill scarcity:Traditional hand-burnishing and edge-painting techniques require 8-12 year training cycles, constraining capacity expansion for European heritage brands.
- Cross-border certification latency:GB standard testing in China, BIS approval in India, and EPA registration in the United States create 14-22 month product launch timelines for multi-market SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Jewellery Box Market |
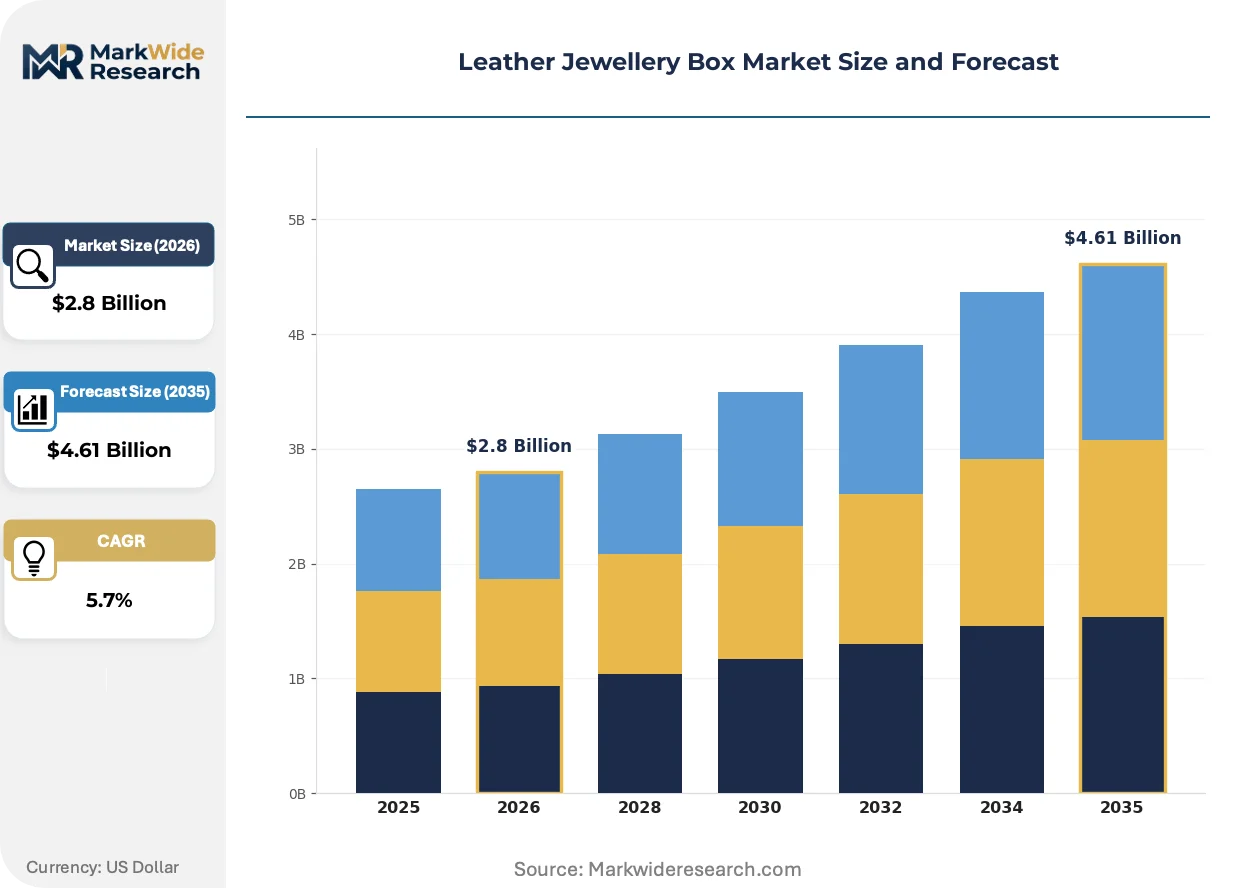
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Travel Cases, Organizer Boxes, Ring Boxes, Necklace Holders Material: Genuine Leather, synthetic Leather, Suede, Velvet Design Style: Classic, Modern, Vintage, Minimalist Target Customer: Women, Gift Buyers, Collectors, Retailers |
| Companies Covered | SACHER & Co. GmbH, Guangdong Deqi Packaging Co., Ltd., Keep Promise Packaging Industrial Co., Ltd., THE JEWELLER'S BOX COMPANY, Floriani astucci srl, Dahlinger GmbH and Co KG, Westpack A/S, LEATHER TALKS, Wolf Designs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Jewellery Box Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry mandates are compressing traditional tanning timelines while digital fabrication enables mass-customization of interior configurations previously reserved for bespoke ateliers.
Vegetable-tanned leather substrates with bio-based fatliquoring agents are miniaturizing the environmental footprint of luxury box production. Italian tanneries in Tuscany's Santa Croce cluster have adopted these processes to maintain CE-marked export eligibility. The technology is miniaturizing water and chemical inputs by 60% relative to conventional chromium methods, enabling smaller-batch production economics for independent design studios.
EPA effluent guidelines under the Clean Water Act are compelling North American tanneries to install closed-loop wastewater systems. The regulatory burden falls heaviest on mid-volume processors serving box assemblers in the US Northeast, where discharge permits now require real-time heavy metal monitoring. These facilities are consolidating or outsourcing finishing to Mexican maquiladoras with newer treatment infrastructure.
Direct-to-consumer configurators now allow buyers to specify compartment dimensions, lining colors, and monogram placement without minimum order quantities. This model disrupts traditional wholesale relationships between Guangdong manufacturers and European department store buyers. The shift is most visible in urban Chinese markets, where Alibaba's Tmall Luxury Pavilion hosts virtual ateliers from Shenzhen-based box specialists.
Leather Jewellery Box Market Segmentation
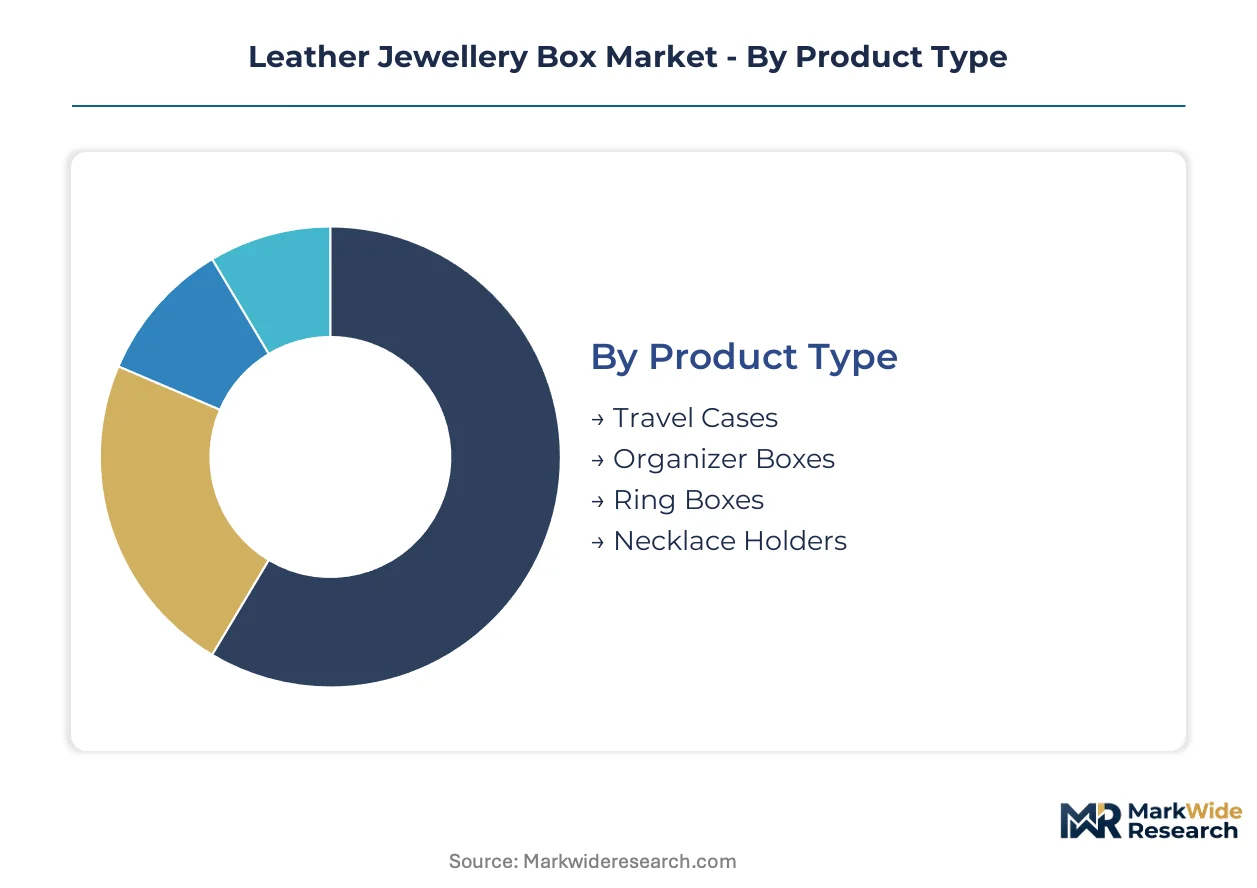
Segmentation in leather jewellery boxes reveals how procurement patterns split between domestic heirloom purchases and export-oriented gifting corridors. Each dimension—product format, substrate, aesthetic, and buyer type—carries distinct margin profiles and compliance burdens that reshape supplier priorities across manufacturing clusters.
Product Type:
Domestic markets favor stationary storage formats, while export demand concentrates on portable solutions for travel retail and cross-border e-commerce.
- Travel Cases:Compact constructions with TSA-compliant dimensions and patented locking hardware. Demand clusters in North American airport retail and Chinese cross-border e-commerce, driven by business traveler consolidation of multiple pieces into single portable units.
- Organizer Boxes:Multi-compartment architectures with wood composite reinforcement and suede-lined drawers. Gift buyers in Indian bridal registries and Chinese anniversary segments prioritize these for multi-generational storage.
- Ring Boxes:Small-format hinged designs for single-piece presentation, prevalent in European jewellery retail adjacencies.
- Necklace Holders:Vertical or suspended configurations preventing chain tangling, favored by collectors in Japanese and South Korean urban markets.
Organizer Boxes holds the largest share; momentum sits with Travel Cases.
Material:
Cost tiers separate chromium-tanned European substrates from vegetable-processed alternatives, with synthetic substitutes pressuring mid-market positioning.
- Genuine Leather:Full-grain and top-grain hides from Brazilian and Argentinian processors, chromium-tanned for durability or vegetable-tanned for REACH compliance. REACH chemical disclosure requirements reward transparent European tanneries with preferred supplier status in department store channels.
- Synthetic Leather:PU and microfiber substrates from Korean and Taiwanese mills achieving tactile similarity at lower unit cost. Economy-tier box assemblers in Guangdong adopt these for price-sensitive export orders to Southeast Asian markets.
- Suede:Split-hide napped finishes, often paired with velvet hybrids in minimalist design collections targeting urban apartment dwellers in Chinese and Indian metropolitan areas.
- Velvet:Synthetic or cotton-pile linings, standard in entry-level constructions where substrate cost minimization outweighs exterior prestige signaling.
Genuine Leather commands the premium tier; Synthetic Leather is climbing the fastest.
Design Style:
Volume concentrates in heritage aesthetics for gifting occasions, while emerging demand shifts toward space-efficient formats for dense urban housing.
- Classic:Traditional hand-burnished finishes with edge-painted seams and brass hardware. European heritage brands in Germany and Italy sustain capacity constraints due to 8-12 year artisan training cycles.
- Minimalist:Clean lines, concealed closures, and neutral palettes. Shenzhen-based design studios target Chinese urban apartment dwellers through Alibaba's Tmall Luxury Pavilion configurators.
- Vintage:Distressed patina effects and antique-style fittings, popular in North American bridal gifting segments seeking heirloom resonance.
- Modern:Geometric profiles with magnetic closures and modular interior inserts, gaining traction in South Korean and Japanese collector markets.
Classic retains the gifting core; Minimalist shows the steepest expansion trajectory.
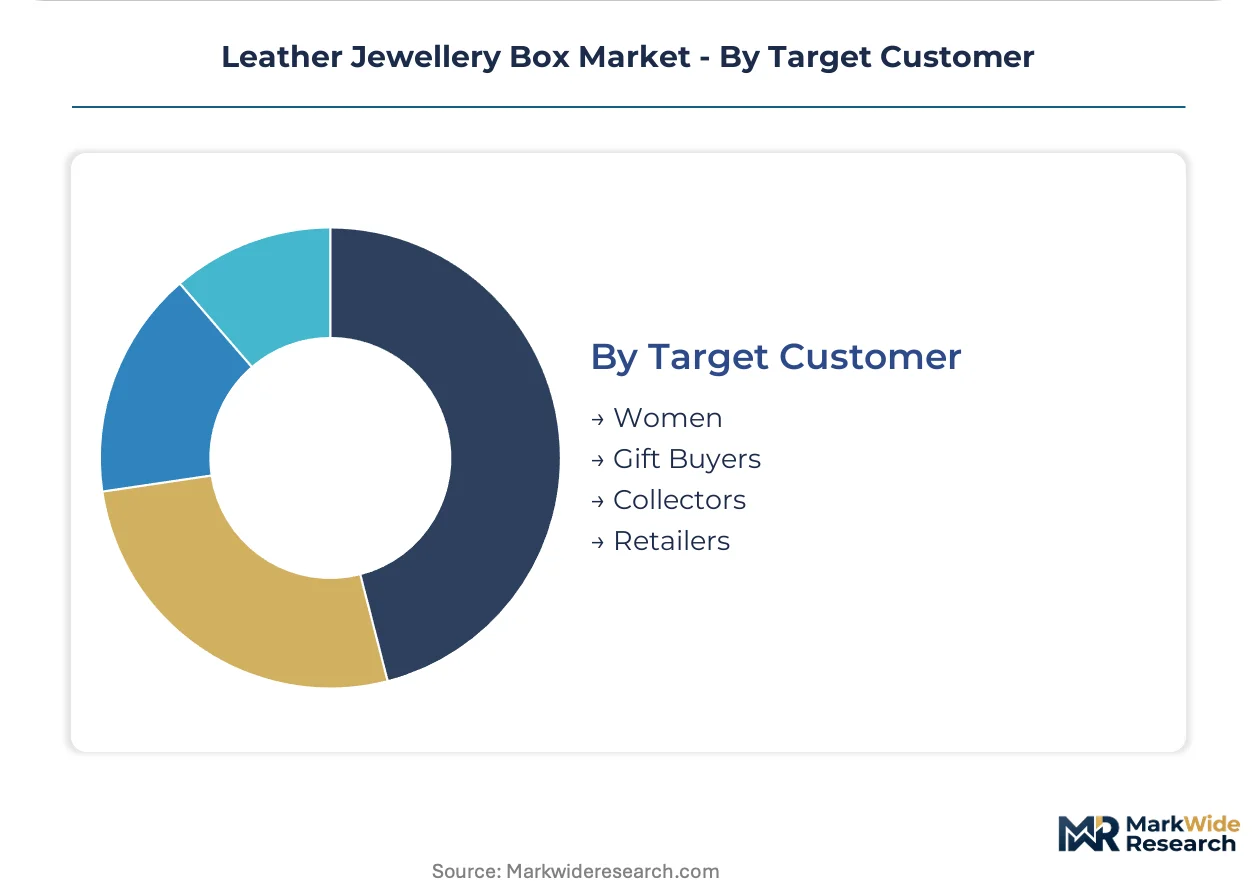
Target Customer:
Customer type determines channel strategy, with direct-to-consumer configurators disrupting traditional wholesale relationships in Chinese markets.
- Gift Buyers:Seasonal and occasion-driven purchasers prioritizing presentation packaging and monogram services. Chinese bridal and Indian anniversary segments drive peak demand cycles.
- Collectors:High-value repeat purchasers seeking modular expansion systems and conservation-grade linings. Japanese and South Korean urban markets show concentration of this segment.
- Women:Primary end-users across all geographies, with self-purchase rising in Chinese and Indian professional demographics.
- Retailers:Jewellery brands and department stores sourcing private-label boxes, subject to BIS certification in India and GB standard testing in China.
Gift Buyers represent the volume anchor; Collectors offer the highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese manufacturing clusters dominate global leather jewellery box trade, while European demand absorbs premium-tier finished goods through specialized retail channels. Import dependency for full-grain hides concentrates sourcing leverage in South American processors, reshaping regional competitive positioning.
China
Guangdong and Zhejiang provinces anchor production volume through integrated rawhide sourcing and lacquer finishing capabilities. GB standards testing requirements under SAMR oversight add compliance layers for adhesive formulations and substrate imports. Shenzhen-based design studios leverage Alibaba's Tmall Luxury Pavilion to deploy direct-to-consumer configurators, disrupting traditional wholesale relationships with European department store buyers.
Germany
Heritage tooling expertise sustains premium positioning across continental retail channels, with REACH chemical disclosure requirements rewarding transparent tanning process documentation. ECHA's tightening chromium-VI limits under REACH Annex XVII raise substrate costs relative to vegetable-tanned alternatives. Artisan finishing skills in traditional hand-burnishing and edge-painting constrain capacity expansion due to extended training cycles.
United States
EPA effluent standards under the Clean Water Act compel tanneries serving box assemblers to install closed-loop wastewater systems. Real-time heavy metal monitoring requirements in discharge permits drive consolidation among mid-volume processors in the Northeast. Patented travel-case hardware commands placement in department store cosmetics adjacencies and airport retail channels.
India
BIS certification requirements create barriers to entry for unorganized competitors in Mumbai and Delhi luxury retail corridors. Bridal registry and anniversary gifting segments prioritize multi-generational storage solutions with velvet-lined genuine leather constructions. Domestic demand clusters in metropolitan professional demographics where self-purchase patterns are expanding.
Italy
Tuscan tanneries in the Santa Croce cluster have adopted vegetable-tanned substrates with bio-based fatliquoring agents to maintain CE-marked export eligibility. These processes miniaturize water and chemical inputs relative to conventional chromium methods, enabling smaller-batch production economics for independent design studios. Classic hand-burnished finishes with brass hardware sustain capacity constraints due to artisan skill scarcity.
Leather Jewellery Box Market Competitive Landscape
Concentration sits with heritage European finishers and volume-oriented Chinese manufacturers, creating a bifurcated structure where premium and economy tiers operate with limited mid-market overlap. German and Italian specialists anchor the upper tier through patented process technologies and artisan positioning, while Guangdong-based fabricators dominate export volume through integrated supply chains. Strategic moves center on compliance-driven supplier consolidation and direct-to-consumer channel bypass of traditional wholesale intermediaries.
Among German heritage specialists, SACHER & Co. GmbH and Dahlinger GmbH and Co KG exemplify the premium-tier archetype through tooling lineage and continental retail channel penetration. Guangdong Deqi Packaging Co., Ltd. occupies a position within the volume-driven export segment, leveraging Pearl River Delta manufacturing density for rapid design turnaround. Wolf Designs represents the hardware-differentiated travel case specialization, with patented locking mechanisms enabling placement in North American airport retail and department store adjacencies.
| Leading Market Players |
|---|
| SACHER & Co. GmbH |
| Guangdong Deqi Packaging Co., Ltd. |
| Keep Promise Packaging Industrial Co., Ltd. |
| THE JEWELLER'S BOX COMPANY |
| Floriani astucci srl |
| Dahlinger GmbH and Co KG |
| Westpack A/S |
| LEATHER TALKS |
| Wolf Designs |
| Others |
Supply & Pricing Matrix
Capacity utilization gaps between automated European finishing lines and manual Asian assembly plants concentrate pricing power with Guangdong-based volume manufacturers while compressing margins for mid-tier European producers. REACH compliance costs and artisan skill scarcity in German heritage workshops sustain premium price floors for vegetable-tanned heirloom constructions, whereas Pearl River Delta fabricators exploit rawhide integration to undercut on standard-grade export orders.
Pricing Analysis
Gift buyers anchor the three-tier pricing structure across premium, standard, and economy levels in the leather jewellery box market. Price differentiation rests on certification grade—REACH-compliant vegetable-tanned substrates command substantial premiums over chromium-tanned alternatives—and customization depth for monogram services. Pricing pressure stems from Korean and Taiwanese synthetic leather mills achieving tactile parity at lower unit costs, eroding genuine leather positioning in economy tiers. Retail procurement teams show highest price sensitivity, while collectors seeking modular conservation-grade systems demonstrate lowest elasticity.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes intermittently disrupt just-in-time delivery schedules for Guangdong exporters serving department store buyers. Geographic supply concentrates in China, Brazil, and Italy, with full-grain hide processing anchored in South American facilities and finishing craftsmanship clustered in Tuscan tanneries. Raw material dependencies center on Brazilian and Argentinian hide processors, chromium and vegetable tanning agents, and wood composite board substrates. Single-source vulnerability runs through South American drought-exposed livestock cycles. Distribution runs through Alibaba's Tmall Luxury Pavilion direct-to-consumer configurators and European department store wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales monogram services and repairable construction protocols expand faster than hardware unit sales, converting one-time gift purchases into recurring brand relationships. This service-attach dynamic reshapes margin architecture away from transactional box manufacturing toward lifetime customer value capture.
For Market Incumbents: Secure captive chromium-free tanning capacity through backward integration into Italian vegetable-tanned substrate suppliers, insulating margin structures from ECHA's tightening REACH Annex XVII limits. Consolidate artisan finishing skills through structured apprenticeship pipelines in Germany and Italy, countering the eight-to-twelve-year training cycle bottleneck that constrains heritage brand expansion. For New Entrants and Emerging Players: After-sales repair networks and end-of-life leather recycling protocols represent underserved white-space where incumbents lack CSRD-aligned service infrastructure. Target Indian metropolitan professional demographics through BIS-certified direct-to-consumer platforms, exploiting certification barriers that exclude unorganized competitors from Mumbai and Delhi luxury retail. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among design studios offering modular interior expansion systems and subscription-based conservation services. Long-term viability favors acquisition targets with established TSA-compliant travel case hardware patents and airport retail placement. Watch for inflection in EU Green Deal circularity mandate enforcement timelines, which will accelerate compliance-driven supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vegetable-Tanned Substrates | Captive REACH-compliant supply secures premium-tier pricing power against ECHA regulatory tightening. |
| Direct-to-Consumer Configurator Launch | Alibaba's Tmall Luxury Pavilion placement bypasses wholesale intermediaries and captures gift-buyer data. |
| Artisan Apprenticeship Pipeline Investment | Structured training programs in Santa Croce tanneries alleviate eight-to-twelve-year skill scarcity constraints. |
| Repairable Construction Protocol Development | Modular architectures align with CSRD reporting requirements and extend customer lifetime value. |
| BIS Certification Acquisition | Indian regulatory compliance opens Mumbai and Delhi luxury retail corridors to foreign assemblers. |
Research Methodology
Operator-level perspectives from tannery production managers, jewellery brand procurement directors, Guangdong export manufacturers, Italian artisan workshop owners, and Indian luxury retail buyers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs trade databases, SAMR GB standard filings, ECHA REACH registration dossiers, and BIS certification records. Bottom-up demand modeling across bridal registry segments and collector demographics triangulated against top-down manufacturing capacity assessments in Guangdong and Zhejiang clusters.
Sensitivity analysis tested forecast robustness across chromium-tanning restriction scenarios, South American hide supply disruptions, and synthetic leather substitution rates. Segmentation dimensions spanned product format, substrate type, design aesthetic, and buyer archetype, with additional granularity on regional regulatory compliance tiers. CAGRs derived from installed base depreciation curves and gifting occasion frequency modeling, incorporating REACH implementation timelines and EPA effluent standard phase-in schedules as structural breakpoints.
Underlying assumptions cover stable Brazilian and Argentinian hide supply, gradual REACH Annex XVII enforcement acceleration, and sustained Chinese cross-border e-commerce growth, with deviation risk concentrated in South American drought cycles and EU Green Deal circularity mandate timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Artificial Jewellery Market
Jewelry
Italy Luxury Jewelry Market
Jewelry
Brazil Jewelry Market
Jewelry
Wedding Rings Market
Jewelry
Jewelry Repair Market
Jewelry
Global Jewelry Market
Jewelry
China Jewellery Market
Jewelry
Qatar Jewelry Market
Jewelry
Luxury Fine Jewellery Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Quartz Ring Market
Jewelry
Global Costume Jewelry Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Colorful Gold Jewelry Market
Jewelry
Latin America Jewelry Market
Jewelry
3D Printing for Jewelry Market