
 Luxury Fine Jewellery Market | 2026-2036
Luxury Fine Jewellery Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Fine Jewellery Market Foresight
White-glove after-sales care and lifetime maintenance contracts is shifting how value gets captured beyond the initial transaction. Cartier leverages its global service ateliers to sustain repeat engagement across generations of collectors. Harry Winston competes through direct control of rough diamond procurement, anchoring rarity claims with documented provenance. Van Cleef & Arpels differentiates via patented setting techniques that extend repair dependency back to house-certified craftsmen.
Luxury fine jewellery denotes wearable objets d'art fabricated from precious metals and gemstones, typically achieving minimum fineness thresholds of 18-karat gold or 950 platinum, with diamond grading assessed under standardized cut, color, clarity, and carat protocols. These pieces function simultaneously as personal adornment, portable wealth storage, and intergenerational transfer vehicles within family estates. Rings occupy the deepest margin pools due to bridal and commemorative occasion anchoring, while necklaces lead absolute value contribution through high-jewellery one-of-a-kind commissions. Gold dominates material volume across accessible luxury tiers, yet platinum and rare natural pearls command outsized price-per-gram premiums in collector circles.
REACH in Europe mandates full supply chain disclosure for conflict minerals and mercury traces in gold refining, compelling houses to restructure supplier qualification or risk market exclusion. The CSRD extends these obligations to Scope 3 emissions reporting, embedding carbon intensity into luxury valuation frameworks. In the US, FTC jewellery guides enforce strict alloy purity and gemstone treatment disclosures, with enforcement actions shaping advertising compliance budgets. Stakeholders must now weigh traceability investment against brand positioning trade-offs as younger collectors treat provenance transparency as a non-negotiable purchase criterion.
Market Dynamics
Ultra-wealthy collectors now treat provenance documentation as a purchase prerequisite, forcing houses to restructure supplier qualification around blockchain traceability and third-party assay verification. This shift compresses margins for mid-tier players lacking captive mining relationships or archival authentication capabilities.
Growth Catalysts
- EU Green Deal supply chain mandates:REACH disclosure requirements for conflict minerals and mercury traces in gold refining create competitive separation between compliant houses and laggards. First-generation Chinese ultra-wealthy buyers prioritize houses with documented ethical sourcing.
- Bridal and commemorative occasion anchoring:Rings retain the deepest margin pools across accessible luxury tiers, sustaining house profitability through lifecycle gifting rituals and anniversary upgrade cycles.
- Heritage house archival authentication:Patented setting techniques and house-certified craftsmen create repair dependency that locks collectors into multi-generational service relationships.
Market Restraints
- Rough diamond procurement concentration:Direct control of rough supply sits with a handful of vertically integrated operators, squeezing independent houses on rarity claims and documented provenance.
- Platinum and natural pearl scarcity:Rare material inputs command outsized price-per-gram premiums that compress accessible tier margins and limit volume scaling.
- CSRD Scope 3 emissions reporting:Carbon intensity disclosure requirements embed new compliance costs into luxury valuation frameworks, disadvantaging smaller maisons.
Strategic Opportunities
- First-generation Chinese wealth:Domestic maisons compete with heritage houses for share among buyers seeking cultural resonance alongside investment-grade portability.
- Lifetime maintenance contracts:White-glove after-sales care shifts value capture beyond initial transaction, creating recurring revenue streams through global service atelier networks.
- Blockchain provenance convergence with AI authentication:Technology pairing enables real-time gemstone tracing and forgery detection, reducing insurance costs for high-value pieces.
Industry Challenges
- Master craftsman skill scarcity:Patented setting techniques require house-certified repair networks that cannot scale quickly, creating service bottlenecks during demand surges.
- FTC alloy purity enforcement:Strict gemstone treatment disclosure requirements shape advertising compliance budgets and limit marketing flexibility for treated stone tiers.
- Supplier reconfiguration friction:REACH-mandated supply chain restructuring forces multi-year qualification timelines that disrupt existing procurement relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Fine Jewellery Market |
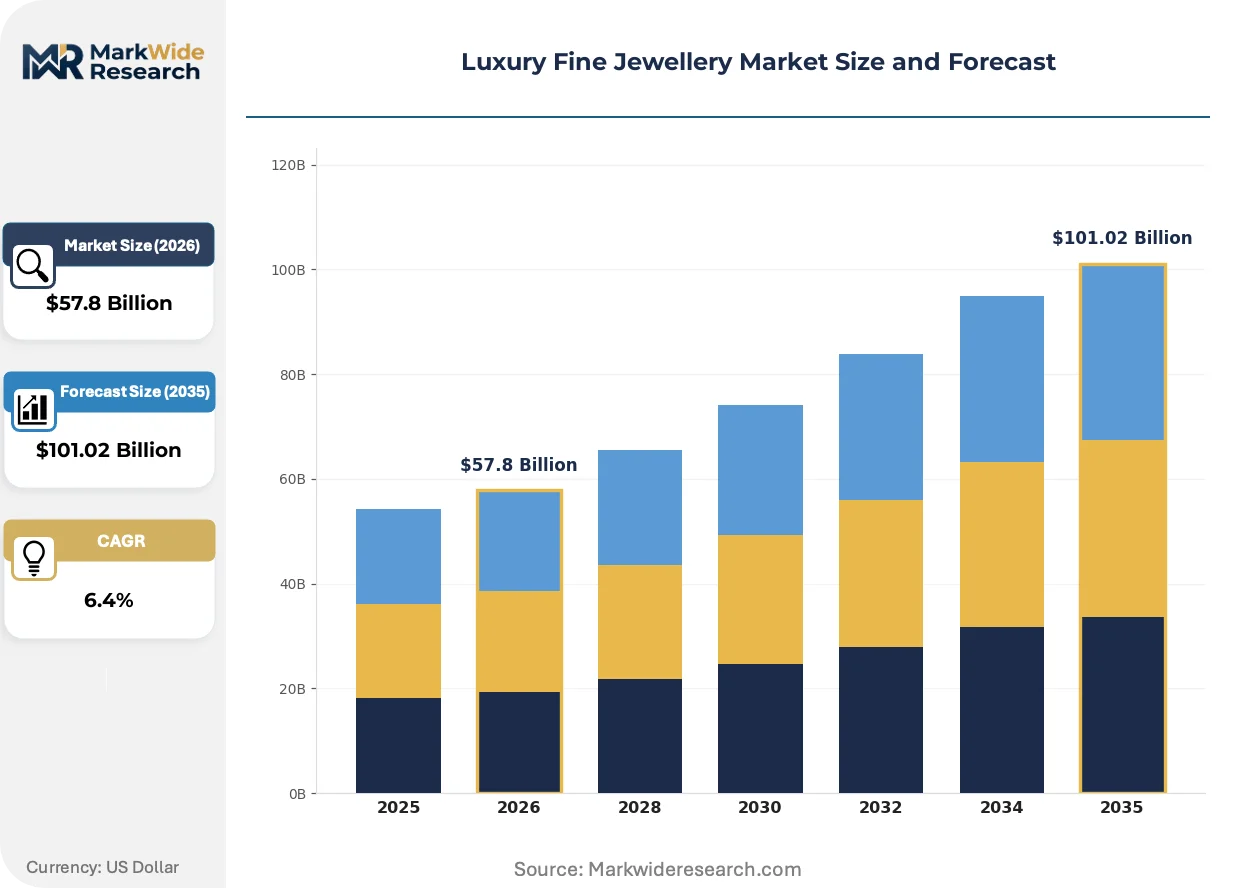
| Market Size in 2026 | $57.8 Billion |
| Market Size in 2035 | $101.02 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Necklaces, Rings, Bracelets, Earrings Material: Gold, Platinum, Diamond, Pearl End User: Women, Men, Children, Couples Distribution Channel: Luxury Boutiques, Online Retailers, Department Stores, Auction Houses |
| Companies Covered | Bulgari, Boucheron, Cartier, Chopard, Graff, Tiffany & Co., Harry Winston, Buccellati, Van Cleef & Arpels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Fine Jewellery Market Shifts & Advancements
Digital traceability infrastructure is absorbing capital and attention across the value chain, reshaping how rarity gets certified and how collectors verify authenticity before acquisition.
Blockchain-based provenance platforms are absorbing verification costs previously borne by insurers and auction houses. High-net-worth collectors in Switzerland and the UAE now demand immutable ownership records for pieces above seven-figure thresholds. This technology is absorbing margin from traditional authentication intermediaries while compressing transaction friction in secondary markets.
CSRD extends carbon disclosure obligations to Scope 3 emissions, embedding supply chain intensity into luxury valuation frameworks. Houses must now document energy consumption across mining, cutting, and retail operations. High-jewellery one-of-a-kind commissions face the steepest compliance burden due to bespoke material sourcing.
Collector procurement patterns favor direct house relationships over multi-brand retail intermediaries. First-generation ultra-wealthy buyers in China and Saudi Arabia increasingly commission pieces through private salons rather than auction channels. This rotation concentrates margin capture with houses possessing established clienteling infrastructure and archival design capabilities.
Luxury Fine Jewellery Market Segmentation
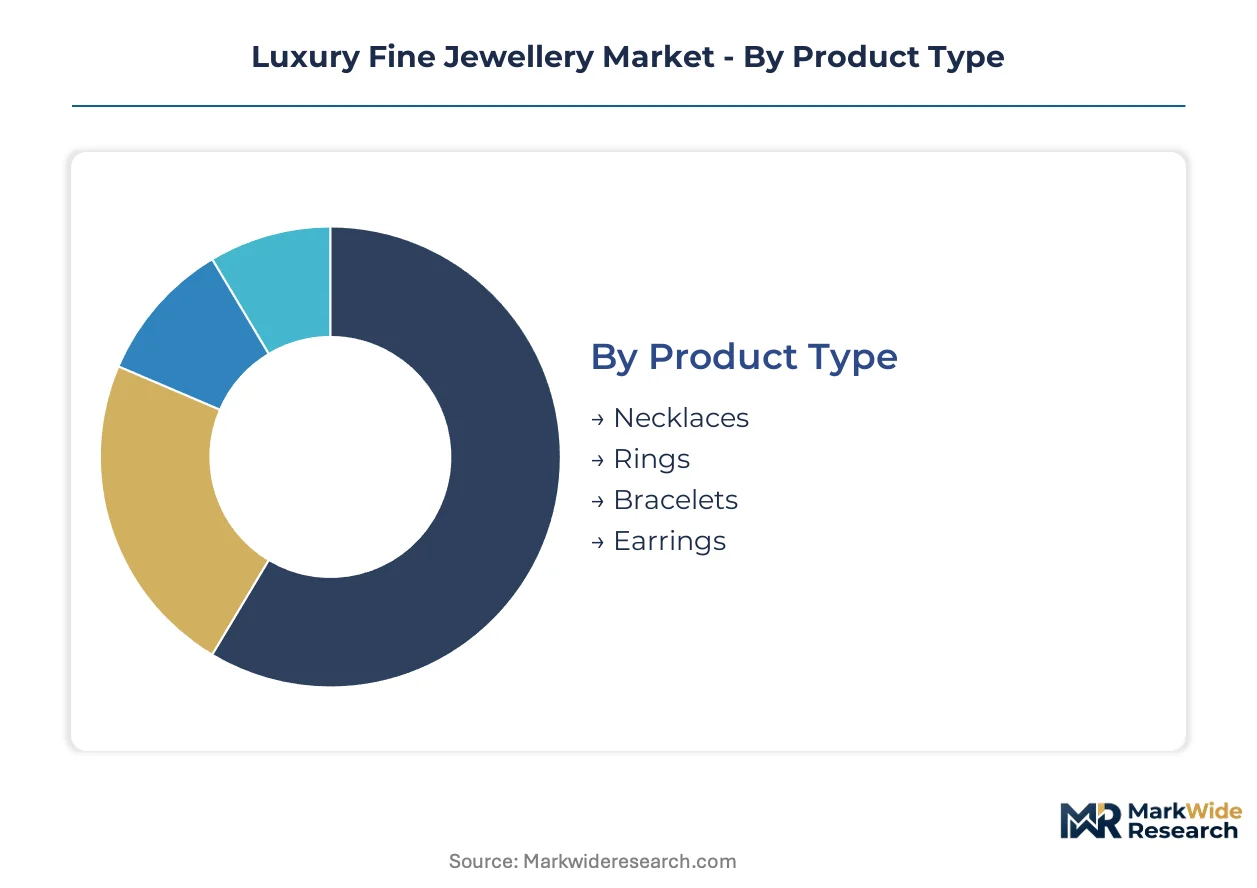
Segmentation in luxury fine jewellery reveals how purchasing logic diverges across collector archetypes, material preferences, and acquisition channels. Houses calibrate inventory depth and service infrastructure around these fracture lines to defend margin pools and lock in lifetime value.
Product Type:
Product type segmentation exposes how occasion anchoring and margin architecture vary across wearable categories, with some formats commanding deeper profitability through ritualized repurchase cycles.
- Necklaces:High-jewellery one-of-a-kind commissions drive absolute value contribution through statement pieces designed for red-carpet visibility and intergenerational transfer. Demand concentrates among first-generation ultra-wealthy buyers in China and Saudi Arabia who commission through private salons rather than auction channels, with archival design capabilities determining house selection.
- Rings:Bridal and commemorative occasion anchoring creates the deepest margin pools across accessible luxury tiers, sustaining profitability through lifecycle gifting rituals and anniversary upgrade cycles. Gold and platinum bands dominate volume, though rare natural pearl and colored gemstone centerstones command outsized price-per-gram premiums in collector circles.
- Bracelets:Stackable designs and charm-based systems encourage repeat acquisition and mix-and-match personalization across accessible tiers.
- Earrings:Day-to-evening versatility supports higher purchase frequency, though per-unit values trail necklace and ring categories.
Necklaces lead volumes today; rings are gaining share fastest through bridal market expansion.
Material:
Material segmentation tracks how fineness thresholds and scarcity dynamics reshape procurement strategy and price-per-gram positioning across the value chain.
- Gold:Dominates material volume across accessible luxury tiers with 18-karat fineness serving as the minimum threshold for fine jewellery classification. REACH compliance on mercury traces in refining and EU Green Deal supply chain mandates are forcing houses to restructure supplier qualification around documented ethical sourcing, compressing margins for mid-tier players lacking captive mining relationships.
- Diamond:Grading under standardized cut, color, clarity, and carat protocols enables investment-grade portability and secondary market liquidity. Direct control of rough supply sits with vertically integrated operators, squeezing independent houses on rarity claims and documented provenance as ultra-wealthy collectors treat blockchain traceability as a purchase prerequisite.
- Platinum:950 fineness commands outsized price-per-gram premiums in collector circles due to scarcity and density advantages for intricate settings.
- Pearl:Rare natural specimens face supply constraints that limit volume scaling and compress accessible tier margins.
Gold leads volumes today; diamond is climbing the fastest through blockchain provenance convergence.
End User:
End user segmentation maps how gendered purchasing rituals and demographic life stages dictate marketing investment and clienteling infrastructure deployment.
- Women:Core demand concentration across all product categories, with self-purchase and gift-receipt occasions requiring differentiated service protocols. First-generation ultra-wealthy buyers in China prioritize houses with documented ethical sourcing alongside cultural resonance, driving competition between domestic maisons and heritage houses for share.
- Men:Cufflinks, signet rings, and chain necklaces anchor entry points, with expansion into high-jewellery bracelets and brooches accelerating. White-glove after-sales care and lifetime maintenance contracts shift value capture beyond initial transaction, creating recurring revenue streams through global service atelier networks targeting male collectors.
- Children:Heirloom commissioning and coming-of-age gifting sustain lower-volume, higher-margin custom work.
- Couples:Bridal registry and anniversary upgrade cycles lock in multi-decade house relationships through coordinated purchasing.
Women lead volumes today; men are expanding most quickly through category diversification.
Distribution Channel:
Channel segmentation captures the rotation away from multi-brand retail intermediaries toward direct house relationships and digital infrastructure.
- Luxury Boutiques:Private salons and flagship ateliers concentrate margin capture with houses possessing established clienteling infrastructure and archival authentication capabilities. Collector procurement patterns favor direct relationships over intermediaries, with CSRD Scope 3 emissions reporting embedding carbon intensity into luxury valuation frameworks that disadvantage smaller maisons lacking compliance scale.
- Online Retailers:Digital traceability infrastructure absorbs verification costs previously borne by insurers, with blockchain-based provenance platforms compressing transaction friction in secondary markets. High-net-worth collectors in Switzerland and the UAE now demand immutable ownership records for pieces above seven-figure thresholds.
- Department Stores:Accessible tier volume concentration faces margin pressure from inventory carrying costs and space productivity metrics.
- Auction Houses:Secondary market liquidity provision absorbs authentication burden, though primary commission pieces increasingly bypass this channel.
Luxury boutiques lead volumes today; online retailers are gaining share fastest through blockchain authentication adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's first-generation ultra-wealthy collectors drive faster value growth than US bridal market expansion, while European heritage houses face steeper compliance costs under EU Green Deal mandates.
United States
Bridal registry and anniversary upgrade cycles sustain multi-decade house relationships through coordinated purchasing rituals. FTC jewellery guides enforce strict alloy purity and gemstone treatment disclosures, with enforcement actions shaping advertising compliance budgets. New York and Los Angeles anchor flagship atelier networks where private salons concentrate margin capture with established clienteling infrastructure.
China
Domestic maisons compete with heritage houses for share among buyers seeking cultural resonance alongside investment-grade portability. SAMR and dual carbon goals tighten supply chain disclosure requirements for precious metal sourcing. Shanghai and Beijing host the densest concentration of private salons where collectors commission high-jewellery one-of-a-kind pieces directly.
France
Heritage archival authentication capabilities and patented setting techniques lock collectors into multi-generational service relationships. REACH mandates full supply chain disclosure for conflict minerals and mercury traces in gold refining. Paris concentrates the highest density of house-certified craftsmen and global service ateliers.
Switzerland
High-net-worth collectors demand immutable ownership records for pieces above seven-figure thresholds, absorbing verification costs through blockchain-based provenance platforms. Swissmedic and national banking secrecy frameworks shape wealth storage preferences for portable assets. Geneva and Zurich anchor secondary market liquidity provision and authentication infrastructure.
United Arab Emirates
Dubai and Abu Dhabi host private salons where collector procurement patterns favor direct house relationships over auction channels. MOHAP oversees product safety standards while free zone frameworks enable rapid inventory positioning for regional ultra-wealthy buyers. The emirates serve as logistics hubs for Gulf Cooperation Council wealth concentration.
Luxury Fine Jewellery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage houses commanding premium positioning through archival authentication while mid-tier players face margin compression from traceability investments. The vendor base concentrates around vertically integrated operators with captive rough diamond procurement and those with established global service atelier networks. Three archetypes dominate: heritage maisons with multi-century archival depth, vertically integrated rough-to-retail operators, and domestic challengers leveraging cultural resonance in emerging wealth markets. Competitive moves center on blockchain provenance infrastructure deployment and lifetime maintenance contract expansion to capture recurring revenue beyond initial transactions.
Among heritage French maisans, Cartier and Van Cleef & Arpels exemplify the archival-authentication archetype through house-certified craftsman networks that create repair dependency. Harry Winston occupies a position within the vertically integrated tier through direct rough diamond procurement control. Tiffany & Co. represents the American heritage specialist model with bridal market anchoring and anniversary upgrade cycle capture. These three names illustrate how geographic origin and structural positioning shape competitive strategy without dictating specific market share claims.
| Leading Market Players |
|---|
| Bulgari |
| Boucheron |
| Cartier |
| Chopard |
| Graff |
| Tiffany & Co. |
| Harry Winston |
| Buccellati |
| Van Cleef & Arpels |
| Others |
Supply & Pricing Matrix
First-generation ultra-wealthy collectors in China anchor the dominant pricing model around provenance premiums and archival authentication, compressing margins for houses lacking blockchain traceability infrastructure while rewarding vertically integrated operators with captive rough supply.
Pricing Analysis
Capacity additions in India and Vietnam are reshaping price floors for accessible-tier gold fabrication, yet heritage houses maintain premium positioning through three-tier pricing structure across high-jewellery, fine-jewellery, and accessible-luxury levels. Price differentiation hinges on house-certified craftsman networks and documented ethical sourcing under REACH compliance. Pricing pressure stems from CSRD-mandated carbon disclosure costs embedding into luxury valuation frameworks. Mid-tier maisons face acute price sensitivity as younger collectors treat provenance transparency as non-negotiable.
Supply Chain Analysis
Master craftsman scarcity in France and Italy constrains output scaling for patented setting techniques requiring house-certified repair networks. Rough diamond supply draws from Botswana, Russia, and Canada, while refined gold feeds from Swiss and UAE bullion hubs. Single-source vulnerability concentrates in De Beers-sightholder relationships for rare gem-quality stones. Distribution runs through Paris, Geneva, and Dubai flagship ateliers where private salons capture margin from direct collector relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal compliance costs pressuring European heritage houses and SAMR disclosure requirements creating entry barriers for unqualified foreign entrants in China.
For Market Incumbents: Lock in multi-generational collector relationships through lifetime maintenance contracts and global service atelier expansion. Counter domestic Chinese maisons by deepening archival authentication capabilities that create repair dependency. Prioritize blockchain provenance infrastructure deployment to defend against emerging technology-enabled challengers. For New Entrants and Emerging Players: Begin with white-glove private salon formats in Saudi Arabia and UAE free zones where collector procurement favors direct house relationships. Target male high-jewellery expansion as the least penetrable incumbent stronghold. Deploy AI-authentication partnerships as the primary go-to-market differentiator against heritage archival depth. For Investors and Strategic Acquirers: Vertically integrated luxury conglomerates are the most active acquirer in this space, seeking archival-authentication capabilities and captive rough supply. Long-term viability over the coming decade rests on houses with established clienteling infrastructure in first-generation wealth markets. Watch blockchain-traceability adoption rates among ultra-wealthy collectors under forty as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Infrastructure | Immutable ownership records reduce insurance costs for seven-figure pieces in Switzerland and UAE. |
| Lifetime Maintenance Contract Expansion | White-glove after-sales care shifts value capture beyond initial transaction across generations. |
| Private Salon Network Buildout | Direct collector relationships in Shanghai and Beijing bypass auction channel margin leakage. |
| REACH-Compliant Supplier Reconfiguration | Full supply chain disclosure for conflict minerals creates competitive separation from laggards. |
| Master Craftsman Apprenticeship Programs | House-certified repair networks address skill scarcity bottlenecks during demand surges. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with heritage house archivists, master craftsmen, private clienteling directors, and auction house specialists alongside secondary validation from customs records, SAMR filings, and Swiss bullion trade data. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Comparable-period anchoring linked forward projections to historical bridal registry cycles, anniversary upgrade patterns, and high-jewellery commission frequencies across the analysis window. The analytical framework modeled product type, material fineness, end-user gender, and distribution channel depth, with CAGRs derived from collector wealth formation rates and compliance cost trajectories. Rough diamond procurement concentration and archival authentication capacity served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including sudden geopolitical disruptions to rough supply, accelerated lab-grown diamond substitution, and unilateral tariff escalations affecting bullion flows. Forecasts reflect assumptions around sustained ultra-wealthy wealth formation in China and progressive EU regulatory enforcement. Material deviation in blockchain-traceability adoption or REACH compliance timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Europe Luxury Jewelry Market
Jewelry
Global Body Piercing Jewelry Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Global Jewelry Market
Jewelry
Jewelry Repair Market
Jewelry
Diamond Jewelry Market
Jewelry
Artificial Jewellery Market
Jewelry
Saudi Arabia Luxury Jewelry Market
Jewelry
Japan Jewellery Market
Jewelry
Quartz Ring Market
Jewelry
Global Gems and Jewelry Market
Jewelry
Pearl Jewelry Market
Jewelry
Imitation Jewelry Market
Jewelry
China Luxury Jewelry Market
Jewelry
China Jewellery Market
Jewelry
South Africa Luxury Jewelry Market