
 Qatar Jewelry Market | 2026-2036
Qatar Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Jewelry Market Analytics
Investment-grade 22-karat gold specifications is unwinding traditional retail dynamics as Qatari buyers prioritize wealth-preserving purity benchmarks over decorative lower-karat alternatives. Malabar Gold and Diamonds leverages its Kerala-origin supply chain to dominate mass-market bridal segments with competitive making-charge structures. Alfardan Jewellery sustains heritage positioning through multi-generational pearl trading relationships and exclusive Gulf-inspired designs. Amiri Gems competes on certified diamond traceability, occupying the upper echelon of Doha's engagement ring market.
Qatar jewelry encompasses ornamental and investment articles crafted from precious metals and gemstones, typically alloyed to specific karat ratings such as 18-karat or 22-karat gold for durability and luster, serving ceremonial, status-display, and wealth-storage functions across Gulf consumer cultures. Gold material segments anchor the value structure, absorbing the majority of fabrication volume due to cultural affinity and central bank exchangeability. Diamond material categories differentiate margin pools, with certified solitaire demand expanding fastest among younger professional buyers. Rings product types lead unit sales through wedding and engagement traditions, while necklaces command higher average ticket values in luxury price tiers.
The Qatar Central Bank's precious metals licensing framework and the Ministry of Commerce and Industry's consumer protection standards jointly enforce hallmarking accuracy and retail transparency, shaping vendor compliance investments and buyer trust thresholds. Qatar's customs authority coordinates with the GCC standardization organization to regulate import tariffs and origin documentation, directly affecting landed costs for Indian and Turkish manufacturing sources. Stakeholders must monitor evolving central bank reserve policies and potential VAT adjustments that could alter the relative attractiveness of physical gold holdings versus jewelry consumption.
Market Dynamics
The Qatar Central Bank's gold trade licensing reforms are compressing retail margins while elevating compliance thresholds, forcing distributors to consolidate sourcing relationships and absorb higher provenance documentation costs.
Growth Catalysts
- Central bank reserve accumulation:The Qatar Central Bank's sustained gold purchases are reinforcing cultural confidence in precious metals as wealth storage, stimulating retail investment-grade jewelry demand.
- Wedding expenditure escalation:Affluent Qatari families are expanding ceremonial jewelry budgets, with 22-karat bridal sets commanding priority allocation in flagship retail corridors.
- GCC standardization harmonization:Unified hallmarking protocols across Gulf Cooperation Council jurisdictions are reducing cross-border certification friction for Doha-based retailers.
Market Restraints
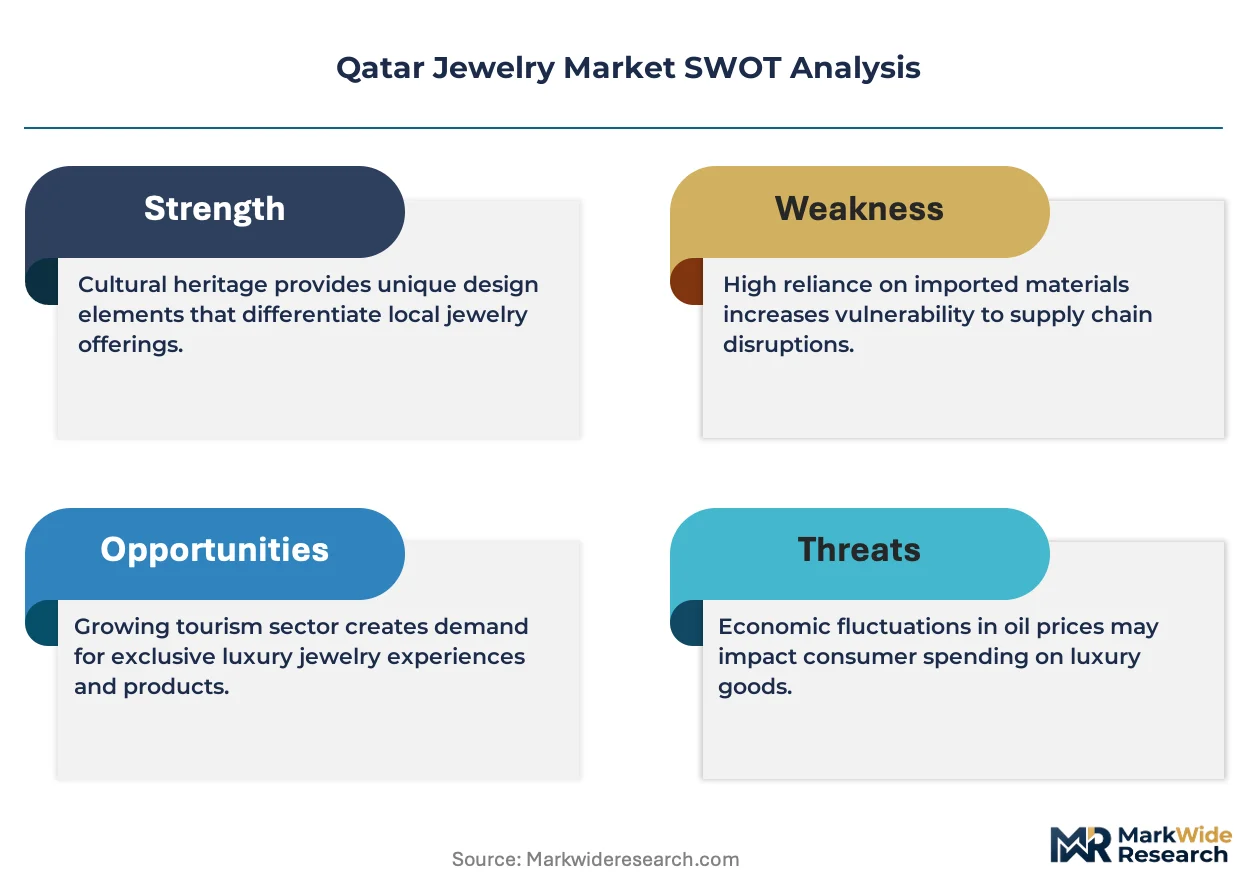
- Indian supply chain concentration:Fabrication dependence on Kerala and Mumbai manufacturing clusters exposes Qatari importers to rupee volatility and shipping disruptions through Strait of Hormuz chokepoints.
- Laboratory-grown diamond substitution:Synthetic solitaire availability at 40-60% price discounts is fragmenting engagement ring demand away from natural certified stones.
- Central bank compliance costs:Enhanced Qatar Central Bank licensing requirements for gold traders are elevating working capital intensity and squeezing smaller independent retailers.
Strategic Opportunities
- Pearl-Qatar tourism integration:Luxury hospitality developments on the artificial island are creating captive high-net-worth visitor traffic for flagship jewelry boutiques.
- Blockchain traceability convergence:Integration of distributed ledger technology with Gulf Cooperation Council customs documentation is enabling premium pricing for fully documented ethical gold.
- West Bay professional segment:Younger expatriate executives in Doha's financial district represent underpenetrated demand for contemporary diamond jewelry with transferable international warranties.
Industry Challenges
- Artisanal goldsmith scarcity:Traditional filigree and Arabic calligraphy engraving skills are diminishing as younger workers migrate to technology sectors, compressing heritage design capacity.
- Multi-jurisdictional hallmarking reconciliation:Indian BIS marks, Turkish assay certificates, and Qatar Central Bank stamps require complex documentation alignment, elongating import clearance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Jewelry Market |
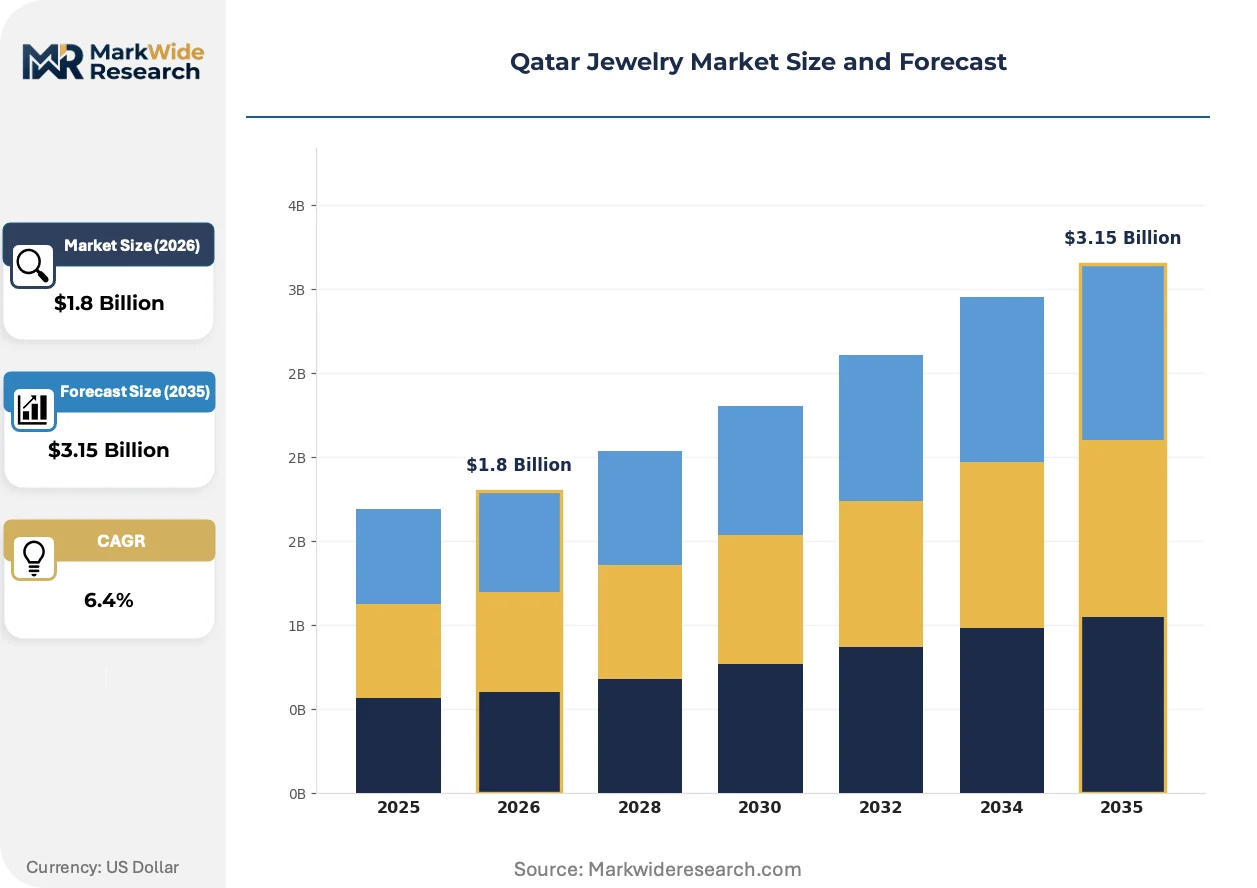
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Earrings, Bracelets Material: Gold, Silver, Platinum, Diamonds Customer Type: Individual Buyers, Retailers, Wholesalers, Online Shoppers Price Tier: Luxury, Premium, Mid-range, Budget |
| Companies Covered | Malabar Gold and Diamonds, Al Sulaiman Jewellers, Sky Jewellery, Amiri Gems, Alfardan Jewellery, Cheval Qatar, AL MAJED GROUP HOLDING, Ever Fashion Luxury, The World of Gemstones, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Jewelry Market Evolving Landscape
Digital authentication tools and shifting generational preferences are restructuring how Qatari consumers evaluate provenance, purity, and resale liquidity in jewelry acquisition decisions.
Laser-inscribed diamond certification is displacing paper-based grading reports as the trust mechanism in Doha's engagement ring segment. Younger professional buyers at West Bay boutiques are demanding GIA and IGI blockchain-registered stones with scannable QR verification. This authentication shift is compressing margins for retailers holding legacy inventory without digital traceability.
The Qatar Central Bank's precious metals licensing framework is mandating enhanced retail transparency through serialized transaction reporting. Jewelry vendors must now integrate point-of-sale systems with central bank monitoring infrastructure, elevating technology investment requirements. Smaller traditional souk operators are responding through cooperative compliance pooling arrangements.
Generational wealth transfer patterns are fragmenting ceremonial jewelry procurement across nuclear family units rather than patriarchal集中采购. Adult daughters in Qatari households are increasingly selecting their own bridal sets during pre-wedding consultations at Pearl-Qatar flagships. This decision-making diffusion is elevating brand recognition importance over traditional family jeweler relationships.
Qatar Jewelry Market Segmentation
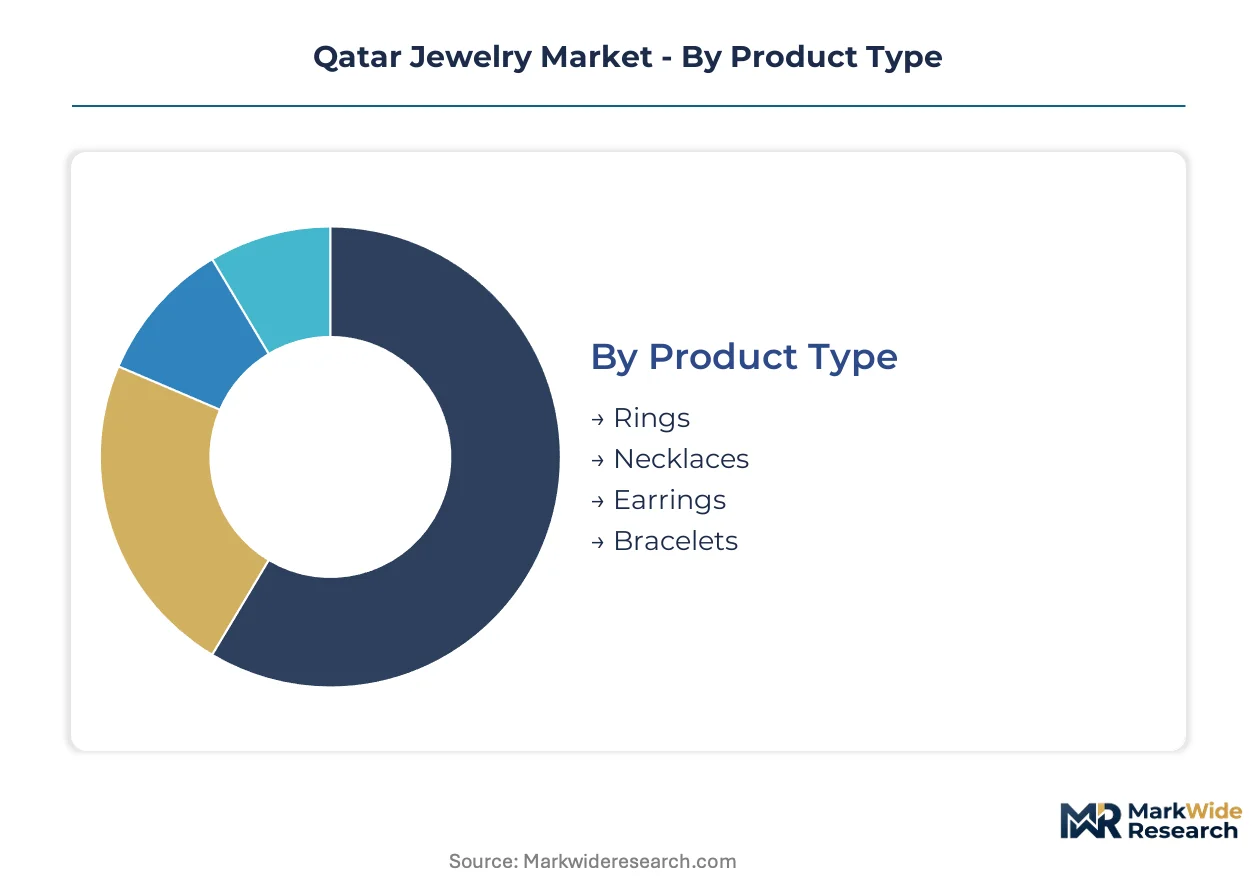
Segmentation in Qatar's jewelry market reveals how ceremonial traditions, investment motives, and retail channel evolution create distinct profit pools. Understanding these divides allows vendors to align inventory depth with buyer willingness to pay across Doha's concentrated luxury corridors.
Product Type:
Margin concentration follows ceremonial significance, with bridal-adjacent categories commanding premium making-charge multiples over discretionary fashion pieces.
- Rings:Engagement and wedding bands dominate unit velocity, with 22-karat gold solitaires and diamond-set platinum bands absorbing the majority of ceremonial budgets. Demand clusters at Pearl-Qatar flagships where multi-generational family consultations precede high-value purchases.
- Necklaces:Bridal sets and heritage-inspired collar designs generate the highest average transaction values, particularly multi-strand pearl arrangements leveraging Qatar's historical trading relationships. Alfardan Jewellery's exclusive Gulf motifs capture premium positioning here.
- Earrings:Diamond studs and chandelier designs serve both daily wear and occasion markets, with younger professionals at West Bay driving demand for contemporary, transferable-warranty pieces.
- Bracelets:Bangle sets remain central to dowry traditions, though charm bracelets and tennis bracelets are gaining traction among expatriate segments seeking versatile investment-wear hybrids.
The dominant share belongs to Rings, while Necklaces is closing the gap fastest as bridal expenditure escalation elevates statement-piece demand.
Material:
Volume flows track cultural wealth-storage preferences, with purity benchmarks and central bank exchangeability shaping procurement priorities.
- Gold:22-karat specifications anchor the market, with investment-grade purity preferences reinforced by Qatar Central Bank reserve accumulation. Kerala-origin supply chains through Malabar Gold and Diamonds dominate mass-market fabrication.
- Diamonds:Certified solitaires with GIA and IGI blockchain registration are displacing legacy inventory, particularly in West Bay engagement ring consultations where younger buyers demand scannable provenance verification.
- Silver:Lower-karat alternatives and silver-gold hybrids serve budget-conscious segments and younger first-time buyers, though margins compress against gold's investment appeal.
- Platinum:White-metal preferences in contemporary bridal sets and men's wedding bands drive niche demand, with limited local fabrication requiring import dependency.
Gold retains volume leadership by a wide margin, though Diamonds is climbing the fastest as authentication technology reshapes trust mechanisms.
Customer Type:
Purchase scale and decision-making authority fragment across channel types, with institutional buyers demanding price transparency that individual ceremonial purchasers accept less readily.
- Individual Buyers:Affluent Qatari families and expatriate professionals drive ceremonial and investment demand, with generational wealth transfer patterns diffusing procurement authority across nuclear family units.
- Retailers:Doha-based boutique operators and franchise flagships at Pearl-Qatar and West Bay manage inventory depth against Qatar Central Bank licensing compliance costs and serialized transaction reporting requirements.
- Wholesalers:Import-dependent distributors navigate multi-jurisdictional hallmarking reconciliation between Indian BIS marks, Turkish assay certificates, and Qatar Central Bank stamps.
- Online Shoppers:Digital-native segments, particularly younger expatriates, are expanding despite jewelry's tactile purchase traditions, with blockchain-registered diamonds enabling remote confidence.
Individual Buyers command the largest revenue pool, while Online Shoppers is gaining share fastest as digital authentication tools reduce perceived purchase risk.
Price Tier:
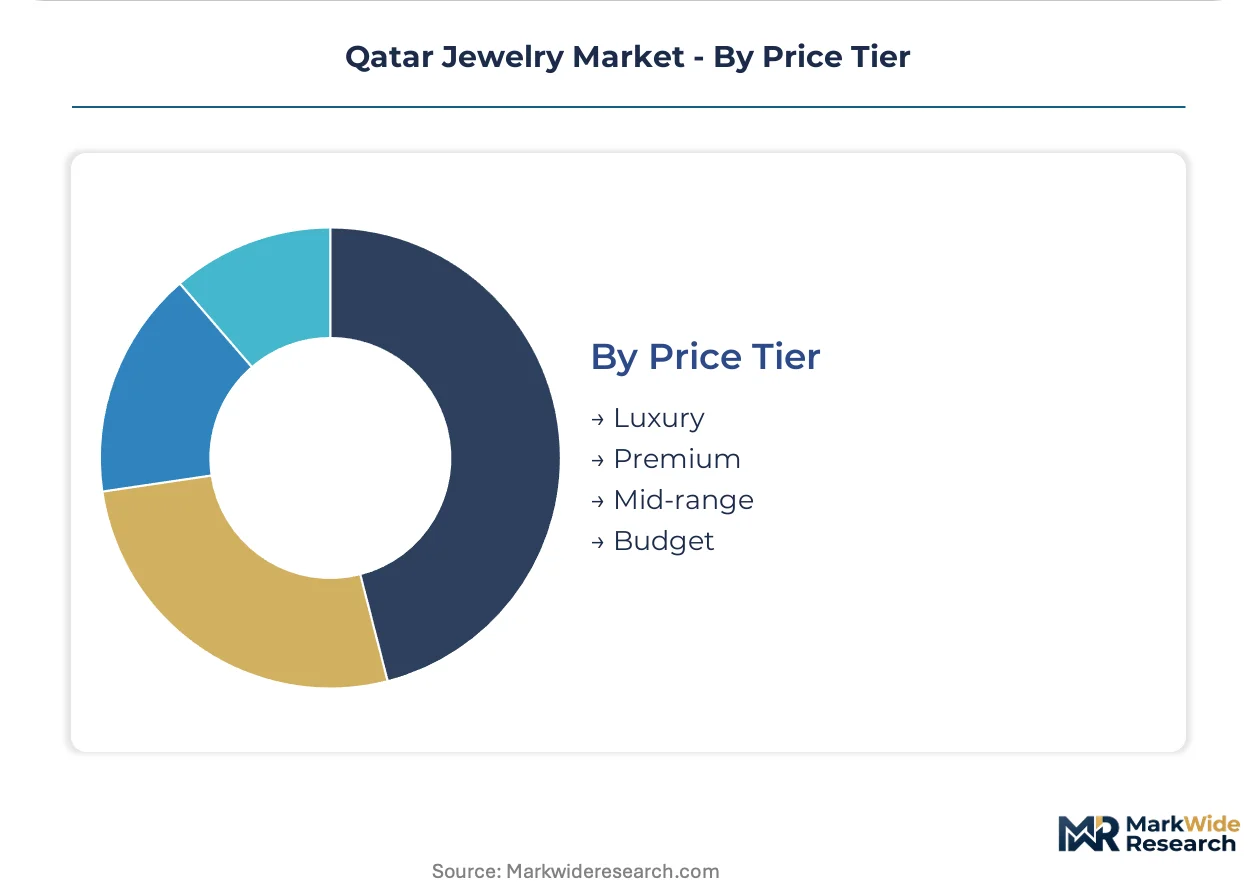
Three-tier pricing structure across luxury, premium, and accessible levels mirrors certification grade and provenance documentation intensity.
- Luxury:Heritage pearl arrangements, large-carat certified diamonds, and bespoke filigree command the highest margins, with Alfardan Jewellery's multi-generational relationships and Amiri Gems' traceability guarantees sustaining positioning.
- Premium:Standard-certified diamonds and 22-karat bridal sets with documented Kerala or Turkish origin serve affluent but price-conscious ceremonial buyers.
- Mid-range:Smaller solitaires, 18-karat alternatives, and silver-gold hybrids target younger professionals and first-time buyers in West Bay's financial district.
- Budget:Laboratory-grown diamond substitution and minimal-making-charge plain gold pieces compete on accessibility, with synthetic solitaires at 40-60% discounts fragmenting natural stone demand.
Luxury captures the highest margin per transaction, though Premium is expanding most quickly as compliance costs and provenance documentation elevate baseline price floors across the market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kerala-origin fabrication clusters and Dubai's re-export hubs concentrate supply-side leverage for Qatar's jewelry imports, with Indian BIS hallmarking and UAE customs documentation shaping landed cost structures across Doha's retail corridors.
Doha Metropolitan Area
Wedding expenditure escalation and generational wealth transfer patterns drive ceremonial jewelry demand across West Bay and Pearl-Qatar districts. The Qatar Central Bank's precious metals licensing framework mandates serialized transaction reporting for all retail vendors. Luxury flagship boutiques cluster along the Pearl-Qatar's marina promenade, where multi-generational family consultations precede high-value bridal purchases.
Al Wakrah Industrial Zone
Import-dependent distributors navigate multi-jurisdictional hallmarking reconciliation for Indian and Turkish manufacturing sources. The Ministry of Commerce and Industry's consumer protection standards enforce retail transparency and provenance documentation. Wholesale operations concentrate near Hamad International Airport logistics corridors, reducing clearance timelines for Kerala-origin gold shipments.
Lusail Development Corridor
Younger expatriate professionals in emerging financial districts represent underpenetrated demand for contemporary diamond jewelry with transferable international warranties. Qatar Central Bank reserve accumulation reinforces cultural confidence in 22-karat investment-grade specifications. Retail pre-leasing activity targets blockchain-traceable certified solitaires for West Bay-adjacent professional segments.
Al Khor and Northern Municipalities
Budget-conscious segments and first-time buyers seek accessible 18-karat alternatives and silver-gold hybrids outside Doha's luxury core. Laboratory-grown diamond substitution at 40-60% price discounts fragments natural stone demand in peripheral retail zones. Traditional souk operators respond to compliance cost pressures through cooperative technology pooling arrangements.
Qatar Jewelry Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Qatar's jewelry market, with heritage pearl traders and Kerala-origin supply chain specialists occupying distinct competitive tiers. Market structure concentrates around established family-owned houses with multi-generational relationships and Indian subcontinent franchise operators with scale fabrication advantages. Three archetypes dominate: heritage-positioned luxury houses, mass-market bridal specialists with competitive making-charge structures, and certified diamond traceability leaders. Dominant competitive moves include backward integration into Kerala manufacturing clusters and exclusive Gulf-inspired design differentiation.
Within the heritage-positioned tier, Alfardan Jewellery and Amiri Gems exemplify distinct competitive vectors, with the former anchoring multi-generational pearl trading relationships and the latter occupying certified diamond traceability positioning in Doha's engagement ring segment. Malabar Gold and Diamonds represents the mass-market bridal specialist archetype, leveraging its Kerala-origin supply chain for competitive making-charge structures. These three companies illustrate how geographic origin and supply chain configuration translate into differentiated retail positioning across Pearl-Qatar and West Bay corridors.
| Leading Market Players |
|---|
| Malabar Gold and Diamonds |
| Al Sulaiman Jewellers |
| Sky Jewellery |
| Amiri Gems |
| Alfardan Jewellery |
| Cheval Qatar |
| AL MAJED GROUP HOLDING |
| Ever Fashion Luxury |
| The World of Gemstones |
| Others |
Value Network & Pricing Analysis
Laboratory-grown diamond substitution is simultaneously shifting supply geography away from traditional Antwerp and Mumbai cutting centers toward Chinese synthesis clusters while compressing natural solitaire pricing premiums by forty to sixty percent across Doha's engagement ring segment. This displacement dynamic is forcing Kerala-origin gold fabricators to absorb higher compliance documentation costs without commensurate price recovery mechanisms.
Pricing Analysis
The Qatar Central Bank's precious metals licensing framework dictates the pricing tier structure across Doha's retail corridors, with serialized transaction reporting requirements elevating baseline compliance investments that compress independent souk operator margins. Three-tier pricing structure across heritage luxury, certified premium, and accessible economy levels separates Alfardan's pearl arrangements from Malabar's bridal sets from laboratory-grown diamond substitutes. Cost compression in the budget tier is intensifying because synthetic solitaire availability fragments natural stone demand without proportional overhead reduction. Expatriate professionals in West Bay exhibit highest price sensitivity due to transferable-warranty requirements, while multi-generational Qatari families demonstrate lowest sensitivity during ceremonial consultations at Pearl-Qatar flagships.
Supply Chain Analysis
Inventory lead times elongate during multi-jurisdictional hallmarking reconciliation between Indian BIS marks, Turkish assay certificates, and Qatar Central Bank stamps, compressing working capital velocity for import-dependent distributors. Geographic concentration centers on Kerala and Mumbai fabrication clusters for gold, Antwerp and Surat for diamond cutting, and Shenzhen for laboratory-grown synthesis. Raw material dependencies encompass 22-karat gold bullion, GIA-certified rough diamonds, and platinum group metals for white-metal bridal sets. Single-source vulnerability runs through Strait of Hormuz shipping chokepoints exposing Kerala-origin shipments to disruption. Distribution feeds through Pearl-Qatar and West Bay flagship boutiques with wholesale consolidation near Hamad International Airport logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled provenance verification services attach faster than core jewelry hardware sales, with digital authentication subscriptions and transferable international warranty programs expanding revenue per customer relationship across younger professional segments.
For Market Incumbents: Consolidate sourcing relationships into Kerala manufacturing clusters to defend against compliance cost escalation and capture scale efficiencies in 22-karat fabrication. Acquire or partner with blockchain traceability platforms to preempt laboratory-grown diamond substitution threats through differentiated ethical gold documentation. Channel control through exclusive Pearl-Qatar flagship positioning remains the priority lever against mass-market bridal specialists. For New Entrants and Emerging Players: Digital-native authentication service gaps where incumbents under-serve present immediate white-space opportunity, particularly blockchain-registered diamond certification for West Bay expatriate professionals. Target Lusail Development Corridor retail pre-leasing for contemporary design positioning with transferable warranty bundling. Go-to-market angle should emphasize scannable provenance verification and remote purchase confidence tools. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Kerala-origin franchise operators seeking capital for compliance technology upgrades and backward integration into fabrication capacity. Long-term viability over a five-to-ten year horizon favors vertically integrated players with captive supply chains and digital authentication capabilities. Watch Qatar Central Bank reserve accumulation velocity as inflection indicator for retail investment-grade demand sentiment.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | Enables premium pricing for fully documented ethical gold through GCC customs documentation convergence. |
| Kerala Fabrication Backward Integration | Captures competitive making-charge structures and reduces rupee volatility exposure for mass-market bridal segments. |
| Pearl-Qatar Flagship Expansion | Captures high-net-worth visitor traffic from luxury hospitality developments on the artificial island. |
| Laboratory-Grown Diamond Portfolio Entry | Addresses price-sensitive younger professionals while maintaining natural stone positioning at heritage tier. |
| West Bay Professional Segment Targeting | Penetrates underdeveloped expatriate executive demand for contemporary designs with international warranties. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Qatar Central Bank regulatory filings, GCC standardization organization documentation, and Indian BIS hallmarking protocols through bottom-up and top-down triangulation. Primary interviews engaged jewelry retail operations directors, Kerala-origin supply chain managers, pearl trading relationship specialists, and digital authentication platform developers. Secondary sources encompassed customs and trade data, Ministry of Commerce and Industry consumer protection standards, and precious metals licensing framework disclosures.
Segmentation dimensions modeled include product type across rings, necklaces, earrings, and bracelets; material composition spanning gold, diamond, silver, and platinum specifications; customer archetype differentiation between individual ceremonial buyers, retail boutique operators, wholesale distributors, and digital-native online shoppers; and price tier stratification across luxury, premium, mid-range, and budget levels. CAGRs were derived through demand elasticity analysis against central bank reserve accumulation patterns and wedding expenditure escalation trajectories across the projection horizon. Industry-specific inputs incorporated hallmarking compliance cost trajectories and laboratory-grown diamond substitution elasticity coefficients.
Underlying assumptions cover sustained GCC standardization harmonization and stable Strait of Hormuz logistics corridors, with deviation risk concentrated in Qatar Central Bank licensing regime intensification and rupee volatility spikes affecting Kerala fabrication economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Leather Jewellery Box Market
Jewelry
Diamond Jewelry Market
Jewelry
Pearl Jewelry Market
Jewelry
Italy Luxury Jewelry Market
Jewelry
Colorful Gold Jewelry Market
Jewelry
Global Jewelry Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Global Gems and Jewelry Market
Jewelry
China Luxury Jewelry Market
Jewelry
Global Costume Jewelry Market
Jewelry
Germany Luxury Jewelry Market
Jewelry
Quartz Ring Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
Jewelry Repair Market
Jewelry
3D Printed Jewelry Market