
 Jewellery Box Market | 2026-2036
Jewellery Box Market Size, Share, and Industry Trends Forecast 2026-2036
Jewellery Box Market Foresight
Buyer concentration across online retail platforms is restructuring how jewellery box suppliers allocate production capacity and negotiate terms. WOLF leverages its heritage positioning to sustain premium pricing in specialty stores. Westpack competes through manufacturing scale across European distribution networks. Reed & Barton anchors its presence in the North American gift segment through established retail partnerships.
A jewellery box is a rigid or semi-rigid container engineered to store, organize, and protect rings, necklaces, watches, and other precious items, typically incorporating velvet-lined compartments, hinged lids with magnetic or mechanical closures, and moisture-resistant interior finishes. Wooden construction dominates the product type category due to perceived durability and customization potential for luxury gifting, while leather variants command margin pools in the professional demographic where portability and executive aesthetics drive replacement cycles. The modern design style is displacing classic formats among teens and young adults purchasing through online retail channels.
The EPA regulates volatile organic compound emissions from lacquers and adhesives used in wooden box manufacturing, while REACH restricts hazardous substances in metal alloys and synthetic leather treatments across European supply chains. California's Proposition 65 adds disclosure requirements for jewellery box sellers distributing into the United States. Stakeholders must monitor evolving chemical compliance thresholds and channel migration toward direct-to-consumer platforms to calibrate inventory and certification investments.
Market Dynamics
REACH compliance in Europe is tightening material standards for synthetic leather and metal finishes, forcing manufacturers to requalify suppliers and redesign product lines while affluent professionals in China drive premium demand through luxury gift-giving channels.
Growth Catalysts
- REACH substance restrictions:European ECHA enforcement against hazardous metal alloys and synthetic leather treatments is accelerating adoption of certified sustainable materials among premium manufacturers seeking market access.
- China domestic jewellery consumption:Rising affluence among urban professionals is expanding procurement of premium storage solutions through e-commerce platforms with high penetration rates.
- Wooden construction customization:Laser engraving and CNC routing technologies are enabling mass personalization for luxury gifting segments without sacrificing production velocity.
Market Restraints
- Input cost volatility:Rosewood and mahogany prices fluctuate with CITES export restrictions from Southeast Asian source countries, compressing margin pools for solid-wood product lines.
- Supply concentration risk:Velvet lining production clusters in Zhejiang province create single-point vulnerability for European and North American assemblers dependent on just-in-time delivery.
- Substitution threat:Digital jewellery authentication platforms and blockchain-based provenance tracking reduce perceived need for physical storage display among younger collectors.
Strategic Opportunities
- India emerging middle class:Gold jewellery ownership traditions combined with organized retail expansion create underpenetrated demand for premium wooden and leather storage solutions.
- EU Green Deal circularity mandates:Extended producer responsibility frameworks for furniture and homewares will reward modular repairable box designs with preferential procurement status.
- Smart inventory integration:RFID-enabled jewellery boxes converging with home automation systems offer white space for technology licensors and traditional manufacturers to collaborate.
Industry Challenges
- Finishing certification timelines:California Proposition 65 disclosure requirements and EPA VOC testing for lacquers create 90-120 day delays for new product launches in North American distribution.
- Artisan skill scarcity:Hand-applied French polishing and marquetry techniques face generational attrition, forcing premium brands to automate or accept quality inconsistency.
- Multi-channel inventory fragmentation:Direct-to-consumer fulfillment expectations clash with specialty retailer minimum order quantities, complicating demand forecasting and working capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jewellery Box Market |
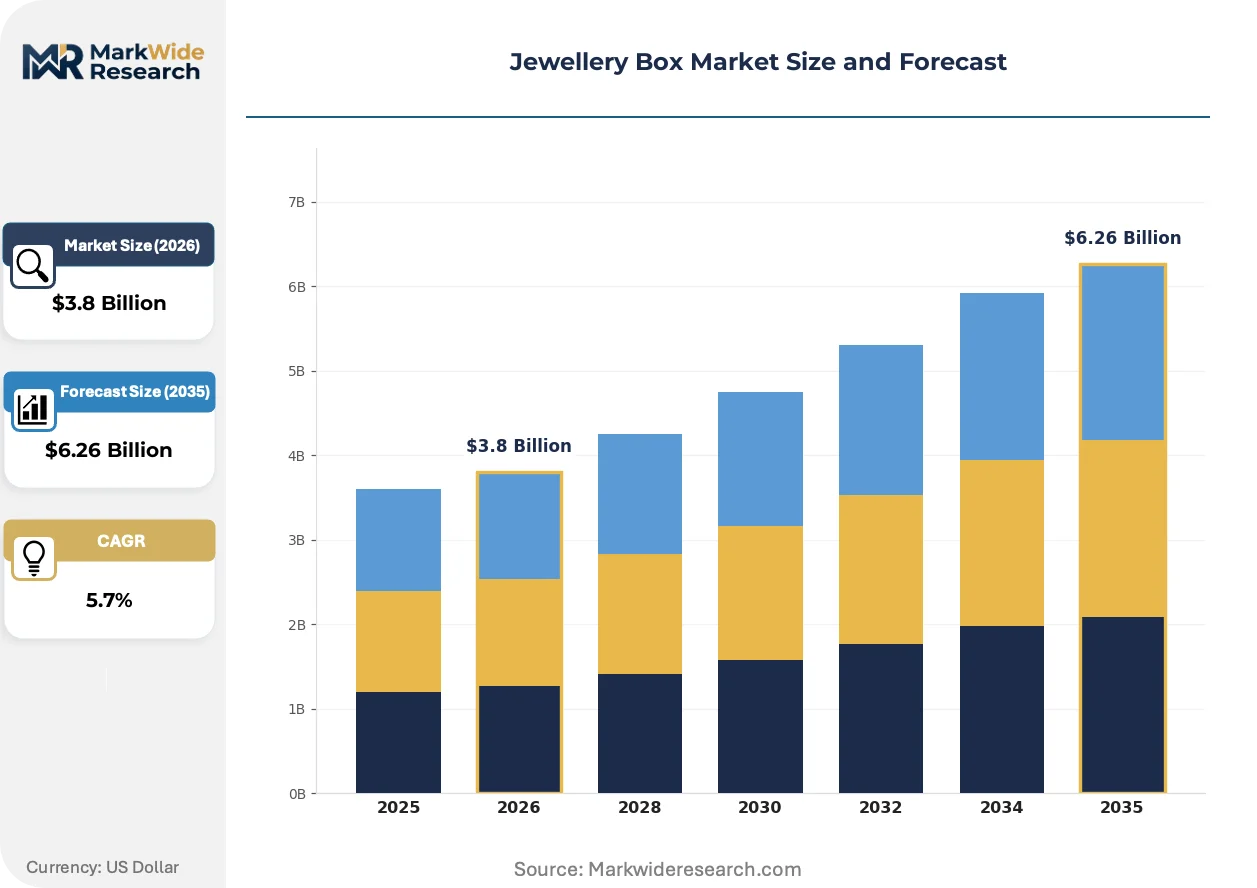
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
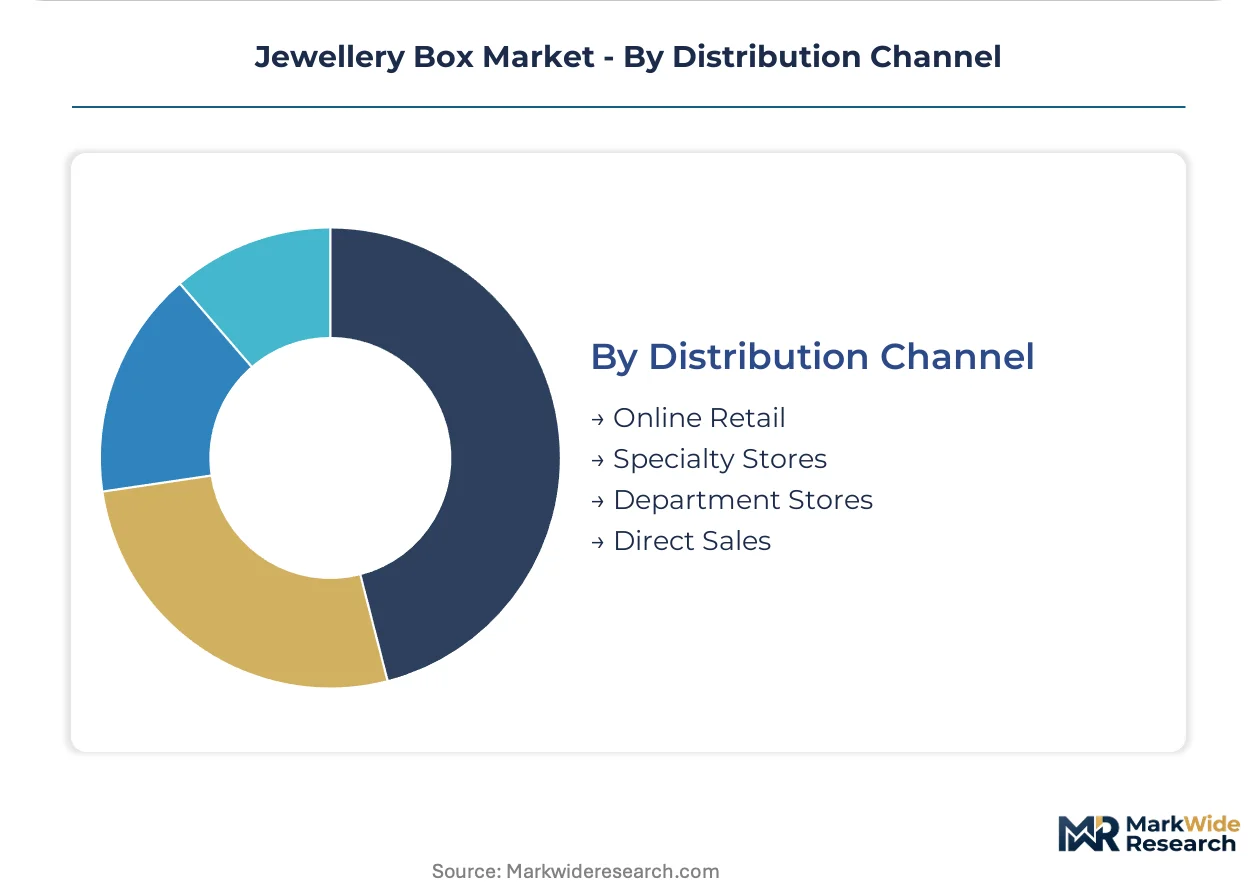
| Segmentation | Product Type: Wooden, Leather, Metal, Fabric Design Style: Classic, Modern, Vintage, Minimalist Target Demographic: Adults, Teens, Kids, Professionals Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | WOLF, Westpack, Reed & Barton, Gunther Mele Limited, Taylor Box Company, American Chest Company, Dahlinger GmbH & Co KG, Stockpak, Finer Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jewellery Box Market Shifts & Advancements
Material science advances and regulatory stringency are compressing traditional design cycles while digital commerce infrastructure reshapes how buyers discover and evaluate storage solutions across price tiers.
Magnetic mechanical closure systems incorporating rare-earth neodymium arrays are consolidating position in mid-premium and luxury segments. Urban professionals purchasing through online retail channels favor these mechanisms for their satisfying tactile feedback and reduced mechanical wear compared to traditional brass hinges. The technology is consolidating supplier bases as magnetic component specialists acquire finishing capabilities previously held by discrete hardware manufacturers.
EPA enforcement of volatile organic compound limits under the Clean Air Act is tightening permissible emissions from lacquer spraying operations in wooden box manufacturing. Facilities in North Carolina and Tennessee face capital expenditure requirements for regenerative thermal oxidizers or water-based finish conversions. Small-batch artisan producers are responding by consolidating finishing operations into shared service facilities to amortize compliance costs.
Social commerce discovery via short-form video platforms is displacing traditional search-engine optimization for customer acquisition among teens and young adults. Influencer-curated unboxing content drives impulse purchases of modern-design formats previously unavailable through brick-and-mortar jewellery retailers. This behavioral shift concentrates marketing spend in content production and platform algorithm optimization rather than legacy trade show and print advertising channels.
Jewellery Box Market Segmentation

Jewellery box procurement patterns diverge sharply across material preferences, aesthetic sensibilities, and channel behaviors. Understanding these fault lines enables suppliers to calibrate production mixes, certification investments, and inventory positioning against divergent margin and velocity profiles.
Product Type:
Cost tier drives supplier selection more than any other factor in this category, with raw material exposure and finishing complexity creating distinct margin architectures.
- Wooden:Solid timber construction with CNC-routed compartments and lacquer or oil finishes dominates luxury gifting. Demand concentrates among affluent professionals in China purchasing through e-commerce platforms, where customization and heirloom positioning justify premium pricing.
- Leather:Full-grain or bonded leather exteriors with velvet-lined interiors command portability-focused segments. European REACH compliance costs and synthetic leather reformulation timelines compress margin pools for mid-tier manufacturers serving professional demographic replacement cycles.
- Metal:Aluminum or steel constructions with powder-coated or plated finishes target travel and security applications.
- Fabric:Canvas, linen, or synthetic textile coverings over rigid substrates serve entry-level and promotional segments.
Volume sits with wooden construction; growth tilts toward leather variants as executive gifting expands.
Design Style:
Generational replacement cycles and social commerce discovery patterns are fragmenting aesthetic demand faster than production lead times can accommodate.
- Modern:Clean lines, hidden hardware, and neutral palettes attract teens and young adults purchasing through short-form video platforms. North American and European urban markets show steepest expansion trajectory as influencer-curated unboxing content displaces traditional retail discovery.
- Classic:Ornate detailing, brass fittings, and heritage finishes sustain gift segments among established collectors. Hand-applied techniques face artisan skill scarcity, forcing brands to automate or accept quality variance.
- Vintage:Distressed finishes and period-accurate hardware target nostalgia-driven procurement.
- Minimalist:Reduced component counts and monochrome palettes serve space-constrained urban dwellings.
Classic formats retain volume leadership; modern designs are gaining share fastest among digital-native purchasers.
Target Demographic:
Life-stage jewelry accumulation patterns and storage space constraints create non-overlapping demand profiles requiring distinct product architectures.
- Professionals:Compact, portable designs with security features dominate executive travel and desk-side storage. Leather and metal constructions concentrate here, with replacement cycles driven by career milestone gifting in China and India.
- Adults:Large-capacity wooden armoires and stackable systems serve established collections. Volume concentrates in North American and European suburban households with dedicated dressing areas.
- Teens:Entry-price modern and minimalist formats purchased through social commerce channels.
- Kids:Themed, music-box-integrated designs for initial jewelry ownership occasions.
Adult households anchor volume; professional segments show steepest expansion as executive gifting globalizes.
Distribution Channel:
Channel-specific fulfillment expectations and margin structures are forcing manufacturers into incompatible operating models simultaneously.
- Online Retail:Platform algorithm visibility and review velocity determine survival. Modern and minimalist designs purchased by teens and young adults concentrate here, with social commerce discovery via short-form video displacing search-based acquisition.
- Specialty Stores:Heritage wooden and classic designs sustain premium positioning through tactile evaluation and sales associate guidance. WOLF and comparable brands defend margin through exclusive SKU allocation and co-branded display investments.
- Department Stores:Mid-tier wooden and leather assortments serving gift occasions with seasonal promotional calendars.
- Direct Sales:Custom and corporate gifting programs with extended production timelines and engraving services.
Specialty stores retain margin leadership; online retail is expanding most quickly as platform infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the steepest demand trajectory for premium jewellery storage solutions, with urban professionals driving procurement through e-commerce platforms while regulatory divergence across major economies fragments supplier certification requirements.
United States
Affluent suburban households anchor volume demand for large-capacity wooden armoires, while executive gifting sustains leather variant procurement. EPA enforcement of Clean Air Act VOC limits from lacquer spraying operations forces North Carolina and Tennessee facilities to install regenerative thermal oxidizers or convert to water-based finishes. Small-batch artisans in Asheville consolidate into shared finishing cooperatives to amortize compliance costs.
Germany
Precision-engineered metal constructions for travel and security applications command premium positioning among professional demographics. ECHA REACH substance restrictions on hazardous metal alloys and synthetic leather treatments accelerate supplier requalification timelines. Industrial clusters in Baden-Württemberg specialize in CNC-routed wooden components with oil finishes for heritage gift segments.
China
Domestic jewellery consumption expansion and e-commerce platform penetration reshape procurement patterns for premium storage solutions among urban professionals. SAMR market surveillance and GB standards compliance tighten product safety documentation for cross-border sellers. Manufacturing concentration in Zhejiang province for velvet linings creates single-point vulnerability for European and North American assemblers.
India
Gold jewellery ownership traditions combined with organized retail expansion generate underpenetrated demand for wooden and leather storage solutions among emerging middle-class households. BIS quality certification requirements for imported finished goods extend customs clearance timelines. Industrial corridors in Gujarat and Maharashtra attract contract manufacturers serving European private-label programs.
United Kingdom
Heritage positioning and classic design formats sustain gift segment volume through established department store partnerships. CSRD sustainability disclosure mandates pressure importers to document supply chain environmental footprints. London-based design studios specialize in modern minimalist formats targeting social commerce discovery among young adults.
Jewellery Box Market Competitive Landscape
Chinese producers anchor the manufacturing-intensive tier; European specialists hold the premium heritage positioning. The vendor base stratifies across scale-driven fabricators, design-forward independents, and vertically integrated gift specialists. Three archetypes dominate: volume manufacturers serving private-label programs, heritage brands defending specialty retail margins, and agile specialists pivoting toward direct-to-consumer fulfillment. Competitive moves concentrate on shared finishing facility investments to amortize regulatory compliance costs and exclusive SKU allocation to defend specialty retail positioning.
Among heritage-positioned specialists, WOLF and Reed & Barton exemplify the premium-tier archetype through established retail partnerships and tactile evaluation channels. Westpack occupies a position among European-scale fabricators serving distribution networks across multiple countries. These three companies represent distinct competitive vectors: heritage brand equity, manufacturing scale, and regional distribution density respectively.
| Leading Market Players |
|---|
| WOLF |
| Westpack |
| Reed & Barton |
| Gunther Mele Limited |
| Taylor Box Company |
| American Chest Company |
| Dahlinger GmbH & Co KG |
| Stockpak |
| Finer Packaging |
| Others |
Supply & Pricing Matrix
REACH substance restrictions on synthetic leather and metal alloys are forcing European manufacturers to requalify suppliers and absorb reformulation costs, compressing margin pools for mid-tier producers while premium wooden construction lines retain pricing power through customization velocity and heirloom positioning.
Pricing Analysis
Volume concentrates in entry-level fabric and promotional segments where price sensitivity runs highest among teens purchasing through social commerce channels, while margin pools accrue to solid-wood luxury gifting lines serving affluent professionals in China with CNC-routed personalization capabilities. Three-tier pricing structure across premium, standard, and economy levels stratifies by material certification grade and finishing complexity, with EPA VOC compliance costs and CITES-restricted rosewood scarcity intensifying cost compression in North American solid-wood manufacturing. Specialty retailers command the least price-sensitive buyer base through tactile evaluation and exclusive SKU allocation, whereas online retail platforms concentrate the most price-elastic demand through algorithm-driven comparison shopping.
Supply Chain Analysis
Certification gating through ECHA REACH substance restrictions and California Proposition 65 disclosure requirements is extending supplier qualification timelines and consolidating vendor relationships around pre-qualified material sources. Manufacturing concentration clusters in China for velvet linings and CNC-routed wooden components, Germany for precision metal hardware, and Vietnam for bonded leather exteriors, with raw material dependencies centering on Southeast Asian timber subject to CITES export controls, Zhejiang province textile finishing, and rare-earth neodymium for magnetic closure systems. Single-source vulnerability in velvet lining production creates chokepoint exposure for European and North American assemblers dependent on just-in-time delivery. Distribution runs through direct-to-consumer fulfillment platforms, specialty retail partnerships, and department store seasonal programs with incompatible minimum order quantities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic mechanical closure systems incorporating rare-earth neodymium arrays are displacing traditional brass hinge mechanisms across mid-premium and luxury segments, rendering legacy hardware suppliers structurally disadvantaged unless they acquire magnetic component capabilities or exit the category.
For Market Incumbents: Cement heritage positioning through exclusive SKU allocation to specialty retailers and co-branded display investments that defend margin against direct-to-consumer entrants. Deepen backward integration into CNC routing and laser engraving capabilities to capture customization premiums from Chinese executive gifting demand. Prioritize REACH-compliant material certification to maintain European market access as ECHA enforcement intensifies against hazardous metal alloys. For New Entrants and Emerging Players: Capture white space in RFID-enabled smart inventory integration converging with home automation systems, where technology licensors and traditional manufacturers remain unaligned. Target India's emerging middle-class households with organized retail expansion accelerating gold jewellery ownership and storage solution procurement. Pursue social commerce discovery via short-form video platforms for modern minimalist formats among digital-native teens and young adults in North American and European urban markets. For Investors and Strategic Acquirers: The window for entry favors vertically integrated manufacturers with captive CNC routing, magnetic component sourcing, and certified sustainable material pipelines that can amortize regulatory compliance costs across product lines. Assess targets on modular repairable design capabilities that align with EU Green Deal circularity mandates and extended producer responsibility frameworks. Monitor ECHA substance restriction expansion timelines and SAMR market surveillance intensity in China as inflection indicators for certification investment requirements and cross-border seller compliance burdens.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | ECHA enforcement accelerates sustainable material adoption among premium manufacturers seeking European market access. |
| Shared Finishing Cooperative Formation | Small-batch artisans in North Carolina and Tennessee amortize EPA VOC compliance costs through consolidated lacquer spraying operations. |
| Social Commerce Content Production Investment | Influencer-curated unboxing content displaces traditional search-engine optimization for customer acquisition among digital-native purchasers. |
| Modular Repairable Design Development | EU Green Deal extended producer responsibility frameworks reward circularity-aligned jewellery box architectures with preferential procurement status. |
| RFID-Enabled Smart Inventory Integration | Technology licensors and traditional manufacturers collaborate on home automation convergence for white-space premium positioning. |
Research Methodology
Multi-period observation of e-commerce platform penetration rates, regulatory enforcement timelines, and material substitution patterns anchored the trend analysis, supplemented by interviews with jewellery box brand managers, category buyers at specialty retailers, CNC routing facility operators, and ECHA compliance consultants. Secondary validation drew from customs and trade data, EPA Clean Air Act enforcement records, SAMR market surveillance disclosures, and SEC filings of publicly traded home goods distributors. Bottom-up demand modeling across demographic segments triangulated against top-down market sizing from production capacity assessments and channel inventory velocity.
Segment-weighting approaches applied differential growth assumptions across wooden, leather, metal, and fabric product types, with additional stratification by modern, classic, vintage, and minimalist design styles, and by professionals, adults, teens, and kids demographic targets. CAGRs were derived from regression analysis of historical consumption patterns against projected e-commerce penetration and regulatory compliance cost trajectories. Forecast inputs incorporated CITES timber export restriction probability, velvet lining production concentration risk, and magnetic component supplier consolidation trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance restriction expansion, SAMR enforcement intensity in China, and generational substitution toward digital jewellery authentication platforms. A model refresh is warranted upon material change in REACH compliance thresholds or social commerce platform algorithm modifications affecting customer acquisition economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Diamond Jewelry Market
Jewelry
Luxury Jewelry Market
Jewelry
Body Jewelry Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Colorful Gold Jewelry Market
Jewelry
South Korea Luxury Jewelry Market
Jewelry
Imitation Jewelry Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Jewelry Repair Market
Jewelry
Global Gems and Jewelry Market
Jewelry
3D Printed Jewelry Market
Jewelry
Beaded Jewelry Market
Jewelry
Wedding Rings Market
Jewelry
Japan Jewellery Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
Italy Luxury Jewelry Market