
 3D Printing for Jewelry Market | 2026-2036
3D Printing for Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing for Jewelry Market Insights
ISO 13485 certification for biocompatible implant-grade jewelry alloys is collapsing the barrier between medical-device and luxury-jewelry equipment suppliers. Formlabs Inc. leverages its resin chemistry expertise to dominate designer-focused desktop systems. Materialise NV anchors industrial-scale precious metal printing through its Magics software and build-processor integration. Rapid Shape GmbH specializes in high-speed DLP platforms calibrated for castable wax resins, occupying the European dental-to-jewelry crossover segment.
3D printing for jewelry encompasses additive manufacturing processes that deposit photopolymer resins, metal powders, or wax-based materials in layer thicknesses of 25–100 microns to produce master patterns, direct metal components, or investment casting molds. The technology eliminates hand-carving bottlenecks and enables lattice geometries, interlocking assemblies, and topology-optimized settings impossible through subtractive methods. SLA technology leads in surface finish fidelity for high-detail filigree work, while DLP captures accelerating share in small-batch production due to faster layer exposure times. Rings dominate product type volumes as the most technically forgiving geometry for dimensional accuracy, though bracelets generate premium margin pools due to material intensity and customization complexity.
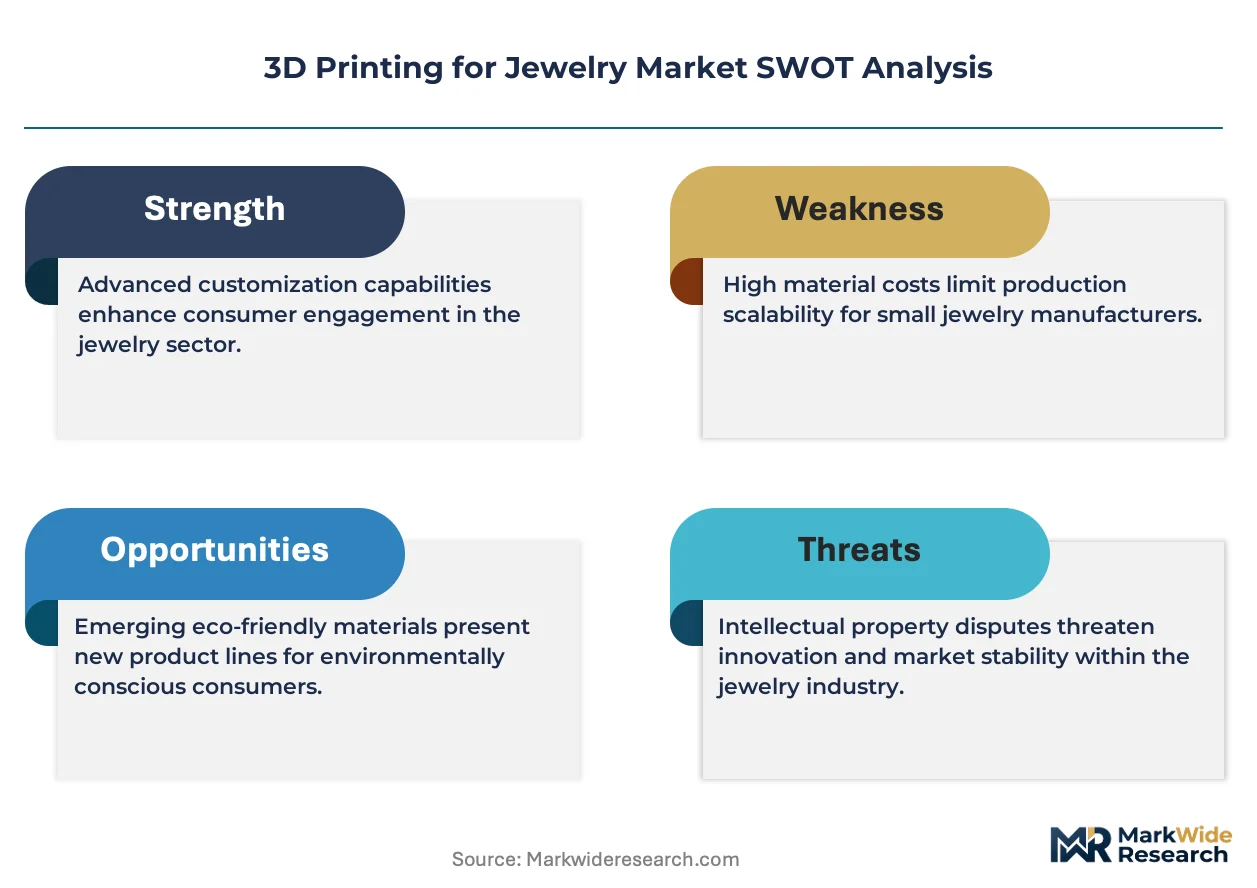
REACH restricts cadmium and nickel release in printed alloys across Europe, forcing material reformulation and third-party assay verification. The EU Green Deal's due diligence requirements for conflict minerals extend to recycled precious metal feedstocks, reshaping supplier qualification protocols. FDA biocompatibility standards for implantable jewelry grades create dual-use certification pathways that advantage established medical-device printers. Stakeholders must monitor whether regional assay hallmarking authorities adapt stamp eligibility rules to recognize laser-sintered density standards versus traditional wrought-metal benchmarks.
Market Dynamics
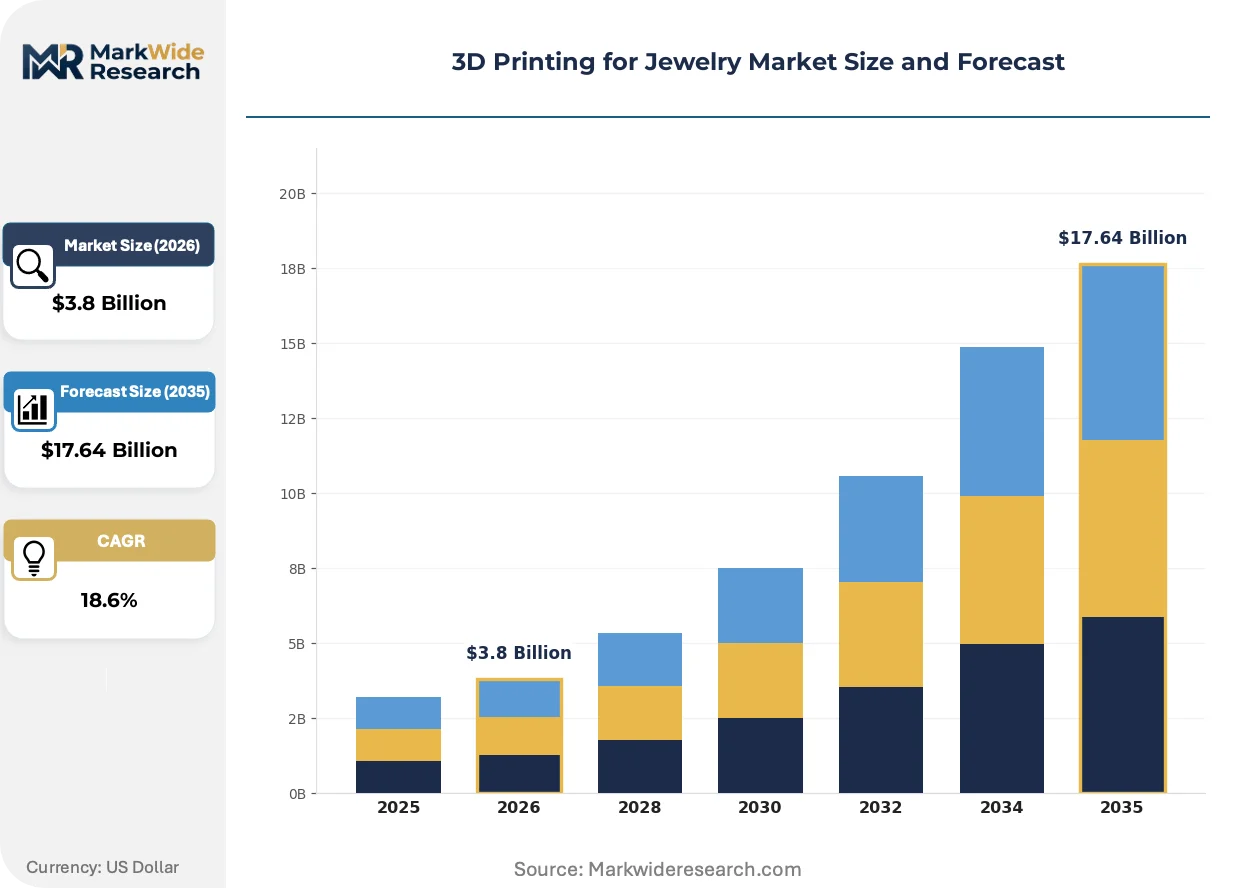
The shift from wax carving to direct precious metal printing is compressing prototype-to-production timelines and collapsing the traditional barrier between artisan workshops and certified manufacturing facilities. This structural force is redrawing supplier qualification protocols and equipment procurement patterns across the value chain.
Growth Catalysts
- REACH alloy reformulation mandates:European restrictions on cadmium and nickel release are forcing material suppliers to develop certified printable precious metal feedstocks, creating first-mover advantages for assay-verified vendors.
- Custom engagement ring demand:Designer studios are abandoning hand-carved wax masters in favor of DLP-printed castable resins, accelerating adoption of desktop systems calibrated for filigree geometries.
- Italy's Vicenza cluster digitization:Generational goldsmithing artisans are integrating SLA and DLP workflows, establishing a regional proof-of-concept for prototype-to-production scaling.
Market Restraints
- Precious metal powder cost volatility:Rhodium and palladium feedstock price swings compress margins for direct metal printing operations, privileging resin-based investment casting workflows.
- Equipment vendor concentration:ISO 13485 certification requirements for biocompatible implant-grade alloys are collapsing the supplier base to a narrow set of medical-device-certified equipment manufacturers.
- Layer thickness limitations:Current DLP systems at 25–50 micron resolution struggle with micro-pavé setting tolerances below 0.3mm, restricting adoption in high-jewelry segments.
Strategic Opportunities
- FDA biocompatibility pathway leverage:Dual-use certification for implantable jewelry grades creates cross-selling opportunities into medical-device channels for established metal printer vendors.
- Recycled precious metal integration:EU Green Deal due diligence requirements for conflict minerals are opening certified recycled feedstock sourcing as a competitive differentiator.
- Topology-optimized lattice geometries:Interlocking assemblies and hollow structures impossible through subtractive methods are unlocking premium positioning in bracelet and statement-piece categories.
Industry Challenges
- Assay hallmarking adaptation delays:Regional authorities have not uniformly recognized laser-sintered density standards versus traditional wrought-metal benchmarks, creating cross-border sales friction.
- Artisan-to-technician skill transfer:Generational wax carvers lack CAD design proficiency, slowing workshop-level adoption despite equipment availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing for Jewelry Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Silver, Gold, Platinum, Resin Technology: SLA, SLS, DLP, FDM Product Type: Rings, Necklaces, Earrings, Bracelets Customer Type: Retailers, Designers, Consumers, Hobbyists |
| Companies Covered | 3D Systems, Inc., Formlabs Inc., Materialise NV, Desktop Metal, Shapeways Holdings Inc., Rapid Shape GmbH, Flashforge, Autodesk Inc., Stratasys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing for Jewelry Market Trends and Innovations
Workflow digitization is dissolving the traditional separation between jewelry design studios and certified production facilities. Three convergent developments are compressing development cycles and redrawing competitive boundaries.
Direct precious metal laser sintering is displacing investment casting for small-batch production runs in high-margin bridal categories. Mid-sized designer ateliers in Germany and the United States are adopting these systems to eliminate outsourcing dependencies. The technology is displacing the traditional foundry middleman, capturing margin previously allocated to casting houses and shortening delivery windows from weeks to days.
REACH enforcement across European member states is mandating third-party assay verification for all printed alloy compositions. ECHA compliance deadlines are forcing reformulation of legacy brass and white-gold alternatives. Italian and French manufacturers are responding by consolidating supplier relationships to vertically integrated material vendors with certified traceability documentation.
Designer-led procurement is fragmenting equipment purchasing away from centralized manufacturing engineering teams. Individual studios now specify desktop systems based on resin chemistry compatibility rather than throughput metrics. This pattern is most visible in the United Kingdom and Netherlands, where independent designers operate as micro-manufacturers with direct customer relationships.
3D Printing for Jewelry Market Segmentation
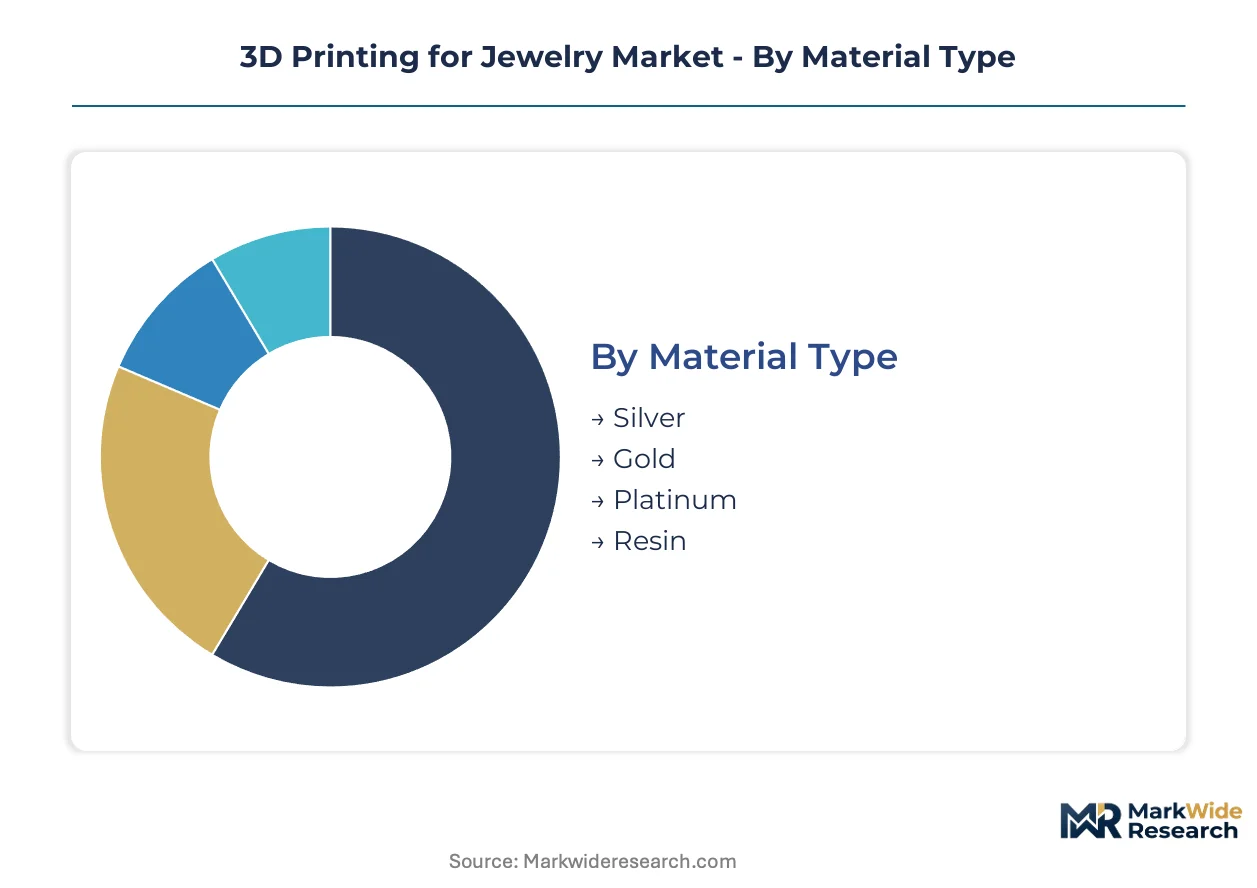
Material specifications determine regulatory compliance pathways for 3D printed jewelry, while technology choices govern surface finish fidelity and production throughput. Customer type segmentation reveals divergent procurement patterns between certified manufacturing facilities and independent design studios.
Material Type:
REACH and FDA biocompatibility standards create divergent certification burdens across precious metal feedstocks, reshaping supplier qualification protocols.
- Silver:Sterling and fine silver alloys dominate prototype-to-production workflows in Italy's Vicenza cluster due to favorable laser-sintering characteristics and established assay hallmarking acceptance. ECHA restrictions on nickel release favor silver formulations for European consumer-direct channels.
- Gold:14K and 18K yellow and white gold variants command premium positioning in bridal categories, though rhodium-plated white gold faces reformulation pressure under REACH cadmium limits. Direct metal printing adoption concentrates in German mid-sized ateliers seeking to eliminate casting house dependencies.
- Platinum:Iridium-hardened platinum feedstocks satisfy FDA implant-grade biocompatibility thresholds for piercing jewelry, creating dual-use certification pathways into medical-device channels.
- Resin:Castable wax-resin formulations enable DLP-based master pattern production for investment casting, preserving traditional foundry relationships while compressing hand-carving timelines.
Established volume favors Gold; emerging adoption favors Resin.
Technology:
Layer exposure mechanisms differentiate capital intensity, throughput speed, and geometric fidelity across jewelry production workflows.
- SLA:Laser-based stereolithography delivers sub-25 micron resolution for high-detail filigree and micro-pavé settings, dominating Italian artisan workshops where surface finish quality determines hallmarking eligibility. The technology's sequential point exposure limits batch throughput, restricting deployment to premium custom work.
- DLP:Digital light projection captures accelerating share in small-batch production through parallel layer curing, with 50 micron platforms now calibrated for castable wax resins in UK and Netherlands designer studios. Faster print speeds offset slightly reduced fidelity for non-pavé geometries.
- SLS:Selective laser sintering of polymer powders serves indirect casting applications and prototype validation, occupying a niche between resin masters and direct metal output.
- FDM:Fused deposition modeling of specialized filaments supports rough form studies and customer visualization, rarely advancing to final production given visible layer lines.
SLA anchors premium positioning; DLP climbs fastest in production scaling.
Product Type:
Geometric complexity and material intensity determine which additive processes achieve dimensional accuracy and economic viability.
- Rings:Cylindrical symmetry and closed-loop structures prove most forgiving for 3D printing tolerances, with direct precious metal sintering displacing investment casting in German and US bridal ateliers. Topology-optimized lattice interiors reduce material consumption while maintaining structural integrity.
- Bracelets:Extended surface area and articulation requirements generate premium margin pools through customization complexity, though link tolerances below 0.3mm strain current DLP resolution limits.
- Necklaces:Chain geometries and pendant mounts leverage resin-based master patterns for casting, preserving precious metal density standards that assay authorities recognize.
- Earrings:Lightweight, paired components suit small-format desktop systems, with French manufacturers integrating DLP workflows for rapid style iteration.
Rings concentrate production volume; bracelets concentrate margin expansion.
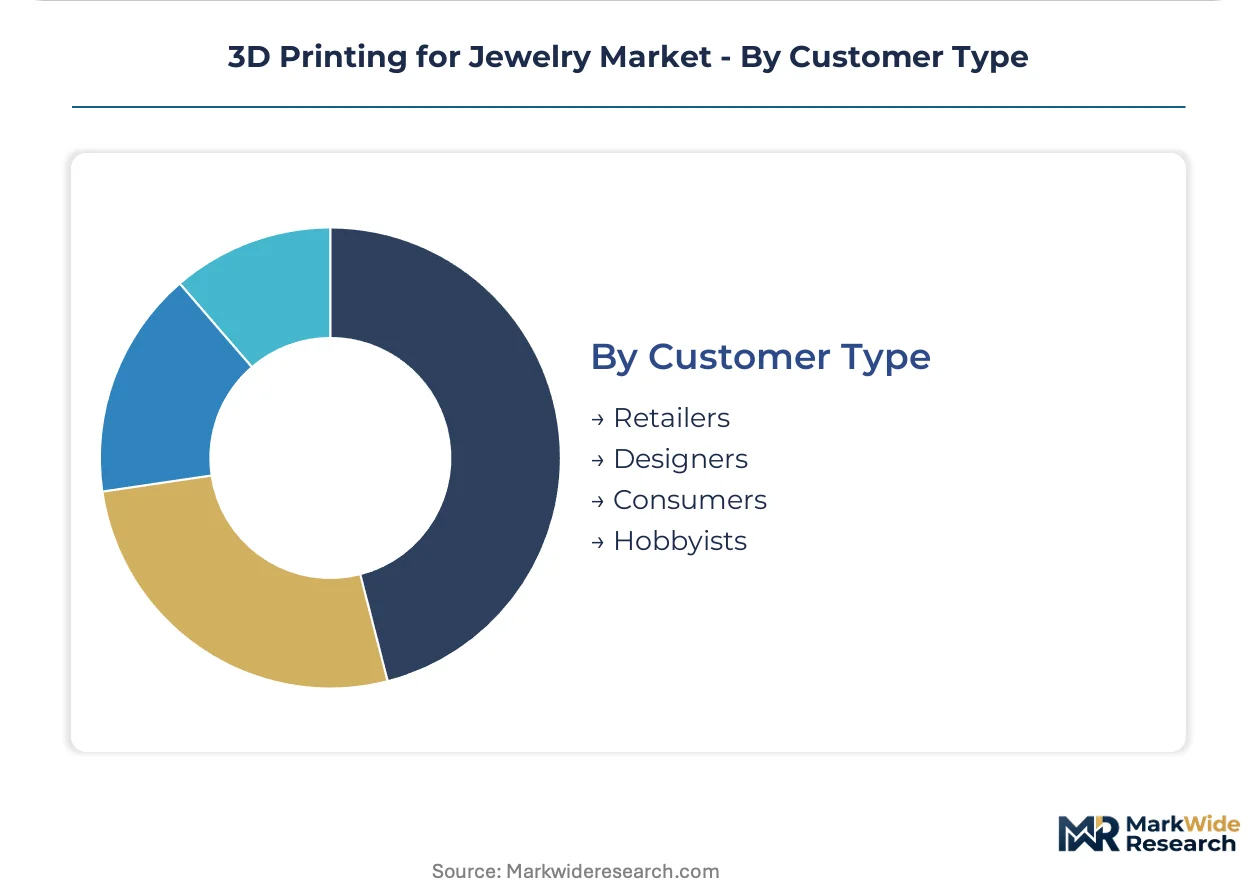
Customer Type:
Procurement authority and technical capability determine equipment specification and material sourcing patterns across the value chain.
- Designers:Independent studios in the United Kingdom and Netherlands operate as micro-manufacturers, specifying desktop systems based on resin chemistry compatibility rather than throughput metrics. These actors fragment equipment purchasing away from centralized engineering teams.
- Retailers:Multi-brand jewelry houses consolidate production through certified manufacturing partners, demanding ISO 13485 traceability for biocompatible alloy lines and ECHA-compliant documentation.
- Consumers:End-user direct purchasing remains limited to polymer-based hobbyist platforms, with precious metal printing restricted to professional channels due to assay verification requirements.
- Hobbyists:Entry-level FDM and resin systems support design experimentation and custom gift production, rarely intersecting with regulated precious metal workflows.
Retailers anchor certified volume; designers drive technology diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Custom engagement ring designers concentrate procurement authority in Italy, Germany, and the United Kingdom, while mid-sized ateliers in the United States accelerate direct metal printing adoption. Regulatory divergence between ECHA alloy mandates and FDA biocompatibility pathways fragments vendor qualification protocols across jurisdictions.
Italy
Vicenza's generational goldsmithing cluster drives European demand for DLP-based prototype-to-production workflows. ECHA REACH restrictions on cadmium and nickel release force reformulation of legacy white-gold alternatives. The Veneto region anchors artisan adoption of SLA systems for high-detail filigree work.
Germany
Mid-sized bridal ateliers in Baden-Württemberg and Bavaria eliminate casting house dependencies through direct precious metal sintering. The country's national materials regulator enforces strict assay verification for printed alloy compositions. Stuttgart-based equipment vendors supply ISO 13485-certified systems for implant-grade biocompatible jewelry.
United Kingdom
Independent designer studios in London and Birmingham operate as micro-manufacturers specifying desktop systems by resin chemistry. The British hallmarking authority adapts stamp eligibility rules to recognize laser-sintered density standards. Hatton Garden's jewelry district fragments equipment purchasing away from centralized engineering teams.
United States
Custom engagement ring demand concentrates in New York and Los Angeles designer ateliers shifting from wax carving to castable resin printing. FDA biocompatibility standards for implantable jewelry grades create dual-use certification pathways. Brooklyn-based studios drive fastest adoption of topology-optimized lattice geometries.
Netherlands
Amsterdam and Rotterdam host independent designers operating direct-to-consumer channels with DLP-calibrated wax resin workflows. The Dutch national environmental agency enforces EU Green Deal due diligence for conflict minerals in recycled precious metal feedstocks. The Randstad region exemplifies designer-led procurement fragmentation.
3D Printing for Jewelry Market Competitive Landscape
Player mix skews toward specialized equipment vendors with resin chemistry expertise and medical-device-certified metal printing systems. Market structure concentrates around three strategic archetypes: desktop system specialists calibrated for castable resins, industrial-scale software-integrated platform providers, and dental-to-jewelry crossover equipment manufacturers. Dominant competitive moves include strategic partnerships with assay-verified material suppliers and portfolio diversification into biocompatible implant-grade alloy certifications.
Within the desktop system tier, Formlabs Inc. and Rapid Shape GmbH exemplify divergent specialization paths. Formlabs occupies a position as a resin chemistry-focused vendor serving designer studios, while Rapid Shape anchors the European dental-to-jewelry crossover segment with high-speed DLP platforms. Materialise NV represents the industrial-scale archetype through its Magics software and build-processor integration for certified manufacturing facilities.
| Leading Market Players |
|---|
| 3D Systems, Inc. |
| Formlabs Inc. |
| Materialise NV |
| Desktop Metal |
| Shapeways Holdings Inc. |
| Rapid Shape GmbH |
| Flashforge |
| Autodesk Inc. |
| Stratasys |
| Others |
Pricing and Supply Chain Analysis
ISO 13485 certification requirements gate both equipment vendor qualification and price differentiation across the 3D printing for jewelry value chain, compressing procurement options while stratifying system costs by medical-device compliance tier. Buyers face asymmetric pricing power as certified metal printing platforms command premiums over resin-based alternatives, yet precious metal powder volatility feeds back into outsourcing decisions that reshape supply chain node selection.
Pricing Analysis
Cost-plus contracts with London Bullion Market Association indexation dominate precious metal powder sourcing, transferring rhodium and palladium volatility risk from suppliers to printer operators. Pricing stratifies across ISO 13485-certified systems, uncertified industrial platforms, and desktop resin units, with certification tier as the primary price differentiation driver. Cost compression in direct metal printing is intensifying because powder feedstock swings erode fixed-price job shop margins. Independent designer studios exhibit highest price sensitivity, while certified manufacturing facilities absorb premiums for assay-verified traceability documentation.
Supply Chain Analysis
Just-in-time resin cartridge replenishment dominates designer studio procurement, whereas certified manufacturing facilities maintain strategic stockpiles of assay-verified precious metal powders to hedge LBMA price volatility. Supply concentrates in Germany for ISO 13485-certified equipment, Italy for castable resin formulations, and Belgium for industrial-scale build-processor software. Raw material dependencies rest on rhodium-plated palladium powders, photopolymer resin monomers, and iridium-hardened platinum feedstocks. Single-source vulnerability pervades medical-device-certified equipment vendors. Distribution runs through vertically integrated material suppliers with ECHA-compliant documentation rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is fragmenting toward independent designer studios, collapsing centralized manufacturing engineering teams' volume leverage and redistributing pricing power across micro-manufacturer networks.
For Market Incumbents: Consolidate resin chemistry IP through exclusive formulation partnerships with Italian and German material suppliers, defending against desktop system commoditization. Deepen backward integration into castable wax resin production to capture margin pools previously allocated to third-party cartridge vendors. Prioritize ISO 13485 certification maintenance as regulatory barriers tighten around biocompatible implant-grade alloy lines. For New Entrants and Emerging Players: Anchor in the United Kingdom and Netherlands designer studio segments, where procurement fragmentation creates white-space for resin-chemistry-specialized desktop platforms. Target uncertified industrial-scale equipment gaps in mid-sized German bridal ateliers seeking to bypass foundry dependencies. Pursue direct-to-designer go-to-market models with resin subscription bundling rather than capital equipment sales. For Investors and Strategic Acquirers: FDA biocompatibility pathway convergence with EU MDR implant-grade standards reshapes the acquisition landscape toward dual-use certified equipment vendors with medical-device channel access. Long-term viability favors platforms spanning jewelry and dental applications with shared resin chemistry expertise. Watch ECHA REACH enforcement acceleration across Southern European member states as the inflection signal for material supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Chemistry Patent Acquisition | Secures exclusive castable wax formulations for DLP platform lock-in across Vicenza artisan clusters. |
| ISO 13485 Certification Investment | Opens dual-use medical-device channels for iridium-hardened platinum piercing jewelry lines. |
| Recycled Precious Metal Feedstock Integration | Meets EU Green Deal due diligence requirements for conflict-mineral-free sourcing documentation. |
| Direct Metal Sintering Capacity Addition | Eliminates casting house dependencies for German bridal ateliers seeking compressed delivery windows. |
| Assay Hallmarking Authority Partnership | Accelerates laser-sintered density standard recognition for cross-border sales friction reduction. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of equipment vendor technical specifications, ECHA regulatory filings, and LBMA precious metal pricing archives. Primary interviews engaged jewelry design studio operators, certified manufacturing facility procurement managers, resin chemistry R&D directors, and assay hallmarking authority technical officers. Secondary validation drew from FDA 510(k) device databases, EU MDR notified body documentation, and SEC filings of publicly traded additive manufacturing equipment suppliers. Bottom-up demand modeling triangulated against top-down market sizing across material, technology, and customer type dimensions.
Segmentation dimensions modeled include material type certification burden, technology layer exposure mechanism, product type geometric complexity, and customer procurement authority concentration. Value projections across the analysis window derive from unit economics of resin cartridge consumption, precious metal powder utilization rates, and equipment depreciation schedules. CAGRs incorporate technology substitution curves for direct metal printing displacement of investment casting, alongside regulatory compliance cost pass-through assumptions.
Material uncertainties — ECHA REACH alloy reformulation timing, FDA biocompatibility pathway harmonization delays, and LBMA precious metal price volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding artisan CAD proficiency adoption curves and assay authority standard recognition timelines. Revision becomes warranted when laser-sintered density benchmark acceptance crosses threshold coverage across major European hallmarking jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Qatar Jewelry Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
Bead Products Market
Jewelry
Jewellery Box Market
Jewelry
Chalcedony Earrings Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
Pearl Jewelry Market
Jewelry
Germany Luxury Jewelry Market
Jewelry
Italy Luxury Jewelry Market
Jewelry
3D Printed Jewelry Market
Jewelry
Diamond Jewelry Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Artificial Jewellery Market
Jewelry
Saudi Arabia Luxury Jewelry Market
Jewelry
Jewelry Cleaners Market
Jewelry
Smart Jewelry Market