
 Jewellery Market | 2026-2036
Jewellery Market Size, Share, and Industry Trends Forecast 2026-2036
Jewellery Market Intelligence
Kimberley Process Certification Scheme compliance for rough diamond sourcing is collapsing the supplier base eligible for premium inventory. Chow Tai Fook Jewellery Company Limited leverages its vertically integrated mining-to-retail pipeline to secure certified rough allocations. Cartier sustains its position through in-house gemological laboratories that verify provenance beyond baseline requirements. Tiffany & Co. differentiates with full chain-of-custody documentation for solitaire diamonds.
Jewellery comprises ornamental pieces crafted from precious metals and gemstones, typically achieving hardness ratings of Mohs 5–10 depending on stone composition, with settings engineered through lost-wax casting, die-striking, or CAD-assisted milling to ensure structural integrity under daily wear. Gold material segments dominate value pools in emerging economies where bullion retains currency-like liquidity, while platinum anchors bridal markets in North America and Japan due to density and hypoallergenic properties. Online platforms represent the fastest-expanding distribution channel, displacing auction houses for first-time luxury purchases among digitally native collectors.
The Kimberley Process, EU Conflict Minerals Regulation, and India's BIS hallmarking mandate collectively reshape procurement by penalizing opaque sourcing and mandating karat verification at point of sale. BIS enforcement in Indian retail corridors has eliminated unhallmarked inventory from organized channels, redirecting consumer trust toward certified sellers. Stakeholders must now decide whether to absorb traceability technology costs or cede volume to competitors with captive mining partnerships and blockchain-enabled audit trails.
Market Dynamics
Traceability mandates from the Kimberley Process and EU Conflict Minerals Regulation are compressing the supplier base eligible for premium inventory, forcing procurement teams to absorb compliance technology costs or cede volume to competitors with captive mining partnerships.
Growth Catalysts
- EU Conflict Minerals Regulation:Mandatory due diligence for 3TG sourcing is redirecting procurement toward certified refiners with blockchain-enabled audit trails, tightening supply chain accountability across European retail corridors.
- India's BIS hallmarking mandate:Enforcement at point of sale has eliminated unhallmarked inventory from organized channels, redirecting consumer trust toward certified sellers and sustaining year-round gold acquisition cycles.
- Lost-wax casting automation:CAD-assisted milling and robotic finishing are compressing production timelines for complex settings, enabling made-to-order bridal collections at scale.
Market Restraints
- Rough diamond supply concentration:Kimberley Process compliance requirements have collapsed the eligible supplier base for certified rough, concentrating premium allocations among vertically integrated mining-to-retail pipelines.
- Platinum price volatility:Density-driven material costs and South African supply interruptions are compressing margins on North American and Japanese bridal inventory.
- Lab-grown diamond substitution:Mohs-hardness-equivalent synthetics at 60-70% price points are capturing share in solitaire and fashion segments among digitally native collectors.
Strategic Opportunities
- Blockchain provenance platforms:Full chain-of-custody documentation is opening premium positioning for mid-market retailers previously excluded from certified rough allocations.
- India's festival-season procurement cycles:Wedding-related purchases and Akshaya Tritiya acquisitions sustain predictable demand windows for bullion-anchored inventory planning.
- Online platform expansion:Digital-native collectors are displacing auction houses for first-time luxury purchases, creating direct-to-consumer channels for certified solitaire diamonds.
Industry Challenges
- Gemological certification backlog:In-house laboratory capacity constraints at major houses are extending verification timelines for provenance documentation beyond baseline Kimberley Process requirements.
- Legacy inventory reconfiguration:Unhallmarked stock elimination under BIS enforcement requires write-downs or recasting for Indian market compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jewellery Market |
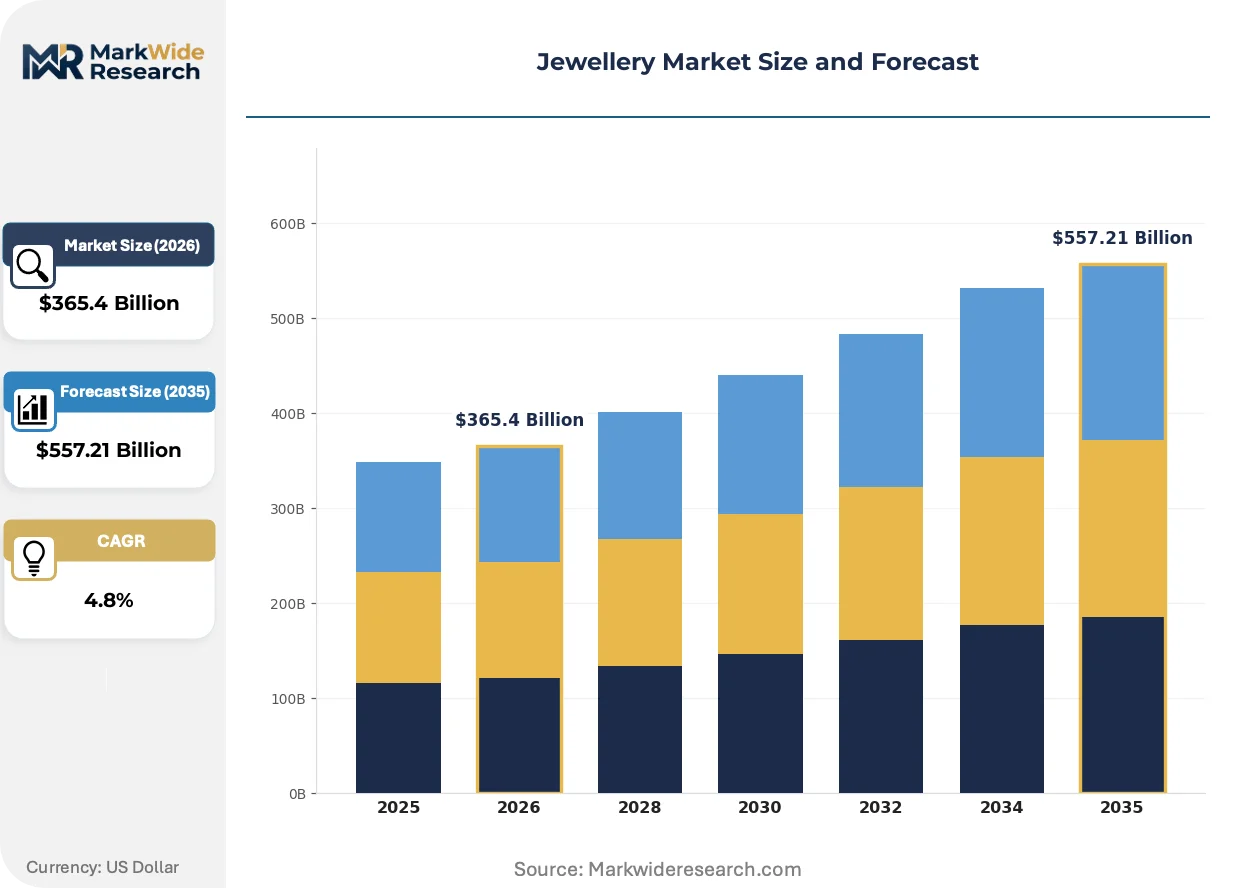
| Market Size in 2026 | $365.4 Billion |
| Market Size in 2035 | $557.21 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Earrings, Bracelets Material: Gold, Silver, Platinum, Diamond End User: Men, Women, Children, Collectors Distribution Channel: Retail Stores, Online Platforms, Auctions, Tradeshows |
| Companies Covered | Chow Tai Fook Jewellery Company Limited, Cartier, Tiffany & Co., Signet Jewelers, Rajesh Exports Ltd., Pandora A/S, Titan Company, Van Cleef & Arpels, Graff, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jewellery Market Strategic Shifts & Innovations
Digital traceability infrastructure and automated production methods are compressing traditional procurement and manufacturing timelines, while regulatory mandates reshape competitive access to certified raw materials.
CAD-assisted milling with robotic finishing is supplanting hand-carved wax modeling for complex bridal settings. Mid-market manufacturers in India and Thailand are adopting these systems to compress made-to-order timelines from weeks to days. The technology is supplanting traditional artisan dependencies and enabling scalable customization previously reserved for heritage maisons.
REACH substance restrictions and EU Conflict Minerals due diligence are extending compliance obligations downstream to finished jewellery importers. European retailers must now document 3TG sourcing back to smelter level or face market exclusion. Bridal and solitaire lines with full chain-of-custody documentation command shelf-space priority in Frankfurt and Paris corridors.
Collector purchasing has rotated from auction-house consignment toward platform-based direct acquisition with embedded certification. First-time luxury buyers in Seoul and Singapore complete high-value transactions through mobile interfaces with third-party escrow verification. This channel compression is most visible among digitally native demographics seeking Mohs-verified gemstones with immediate provenance documentation.
Jewellery Market Segmentation
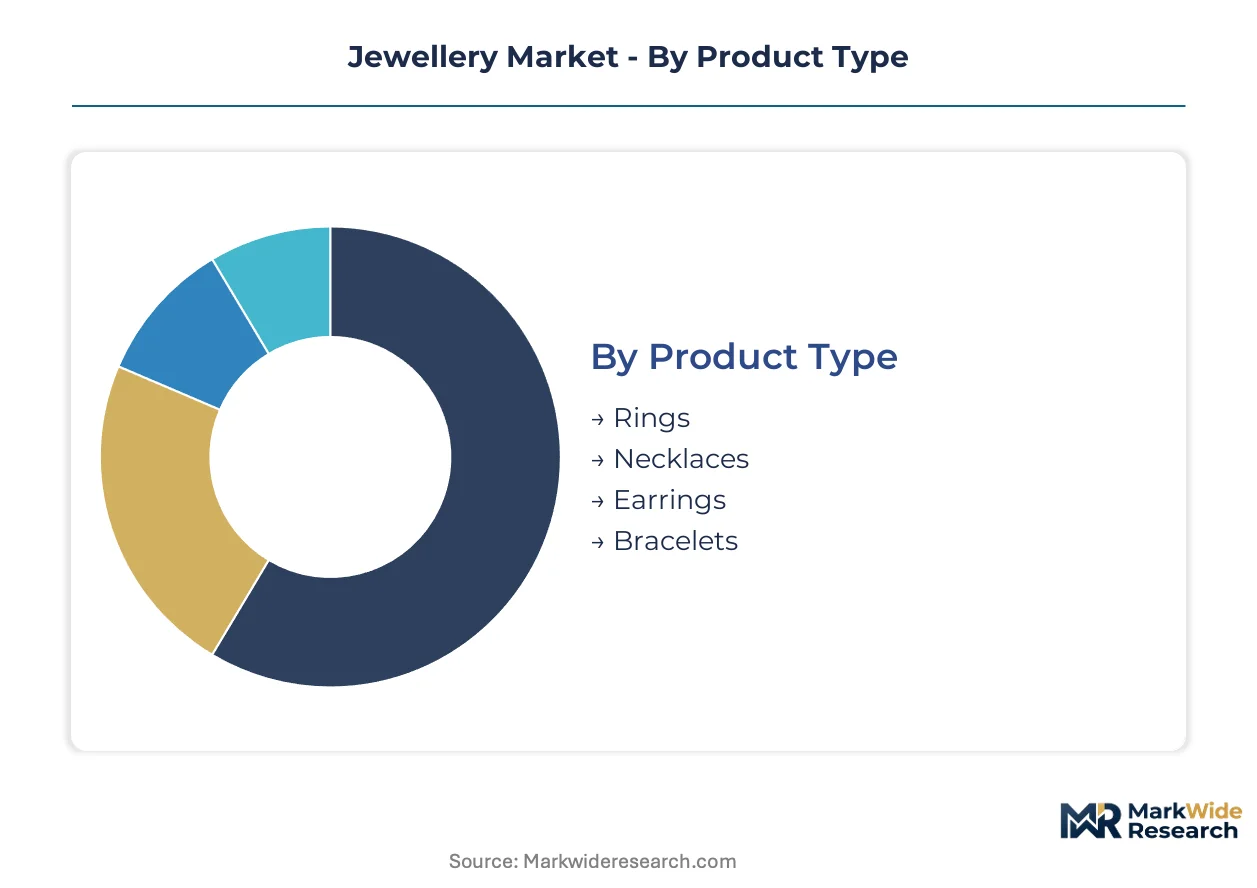
Jewellery segmentation reveals divergent margin profiles across product types and materials, with bridal and investment-grade categories commanding premium positioning while fashion accessories drive volume through digital channels. Channel mix varies sharply by segment, as certified solitaires flow through controlled retail pipelines while silver fashion pieces migrate toward platform-based discovery.
Product Type:
Rings and necklaces dominate bridal and anniversary gifting corridors, with earrings and bracelets capturing fashion-oriented replenishment cycles through differentiated channel strategies.
- Rings:Solitaire and bridal bands anchor certified diamond demand, with lost-wax casting automation compressing made-to-order timelines from weeks to days. Bridal purchases in India and North America sustain year-round procurement cycles for 18-karat and platinum settings.
- Necklaces:Chain and pendant configurations span investment-grade bullion to gemstone statement pieces, with festival-season acquisitions in Indian markets driving predictable gold volume spikes around Akshaya Tritiya and Diwali windows.
- Earrings:Stud and drop formats capture fashion replenishment demand through platform-based discovery, with lab-grown diamond studs gaining traction among digitally native collectors seeking Mohs-hardness equivalence at reduced price points.
- Bracelets:Bangle and chain styles concentrate in Asian bridal traditions, with BIS-hallmarked gold inventory redirecting consumer trust toward certified sellers under India's point-of-sale enforcement mandate.
By volume, earrings lead through platform-based replenishment cycles. By growth pace, rings are climbing the fastest as CAD-assisted milling enables scalable customization.
Material:
Cost tier stratification separates bullion-anchored investment demand from fashion-accessory metals, with density and hypoallergenic properties driving bridal material selection.
- Gold:18-karat and 22-karat compositions dominate emerging-market value pools where bullion retains currency-like liquidity, with BIS hallmarking enforcement eliminating unhallmarked inventory from organized Indian retail channels.
- Silver:Sterling-grade fashion accessories capture platform-based discovery among price-sensitive collectors, with lower material costs enabling trend-responsive replenishment cycles absent from precious-metal bridal segments.
- Platinum:Density-driven hypoallergenic properties anchor North American and Japanese bridal markets, though South African supply interruptions compress margins on finished inventory.
- Diamond:Certified rough allocations concentrate among vertically integrated pipelines, with full chain-of-custody documentation commanding shelf-space priority in European retail corridors under REACH and Conflict Minerals due diligence.
Gold retains the largest revenue footprint across investment and bridal applications. Platinum is gaining share fastest in hypoallergenic bridal positioning.
End User:
Customer type determines certification depth and purchase occasion, with collectors demanding provenance documentation beyond baseline regulatory requirements.
- Women:Bridal and self-purchase segments drive certified solitaire and gold bullion demand, with anniversary gifting sustaining replacement cycles across multi-decade customer relationships.
- Men:Wedding bands and cufflink accessories concentrate in platinum and titanium compositions, with lower replenishment frequency than women's fashion segments.
- Children:Commemorative gifting occasions generate lower price-point demand through silver and 14-karat gold keepsake pieces.
- Collectors:Gemological certification requirements exceed baseline Kimberley Process mandates, with in-house laboratory verification extending timelines for provenance documentation at heritage maisons.
Women's purchases dominate absolute volume across bridal and fashion categories. Collector acquisitions are expanding most quickly as platform-based direct acquisition displaces auction-house consignment.
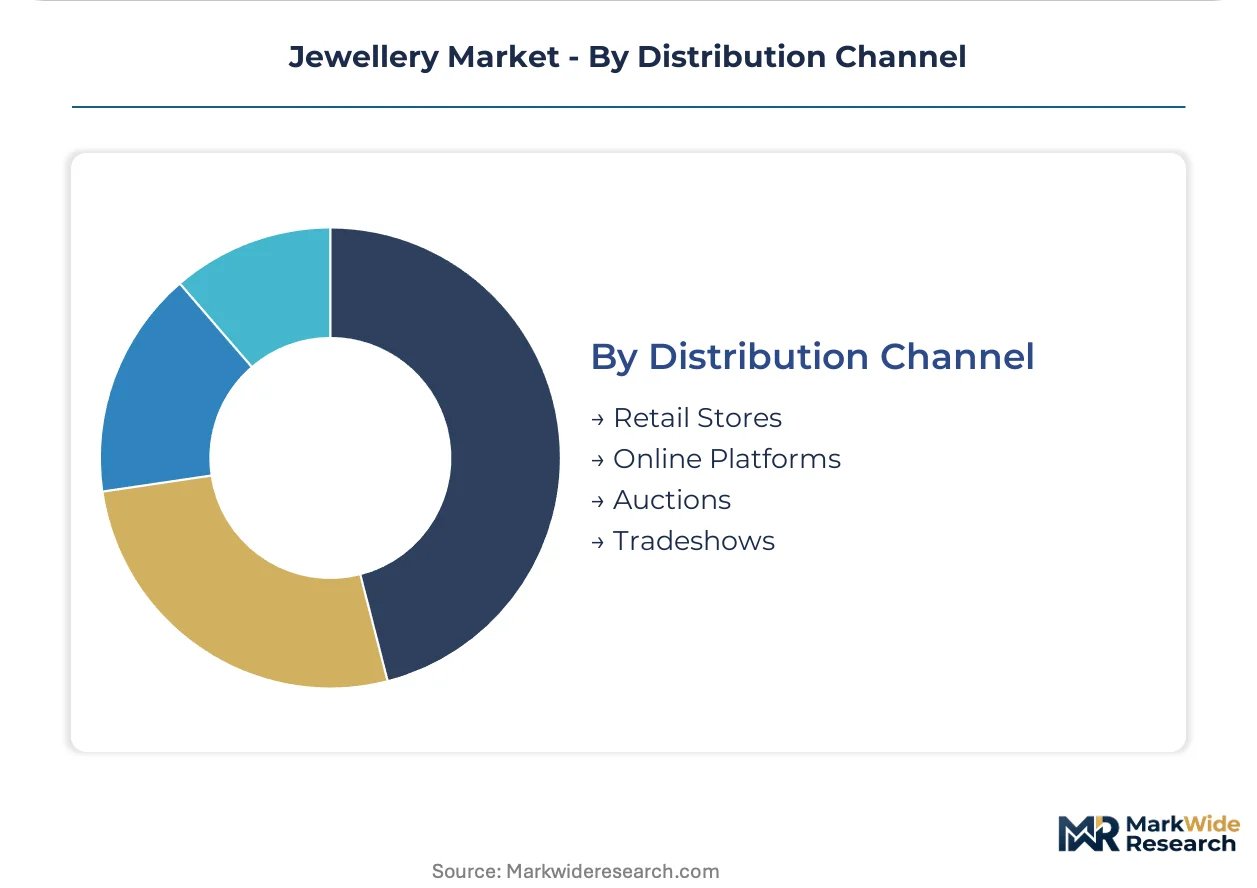
Distribution Channel:
Channel selection reflects certification burden and purchase complexity, with high-value solitaires requiring controlled retail environments while fashion pieces migrate online.
- Retail Stores:Controlled environments for bridal and certified diamond transactions, with BIS enforcement in Indian corridors redirecting consumer trust toward organized sellers with hallmarking compliance.
- Online Platforms:Mobile interfaces with third-party escrow verification capture first-time luxury buyers in Seoul and Singapore, with embedded certification displacing traditional auction-house discovery.
- Auctions:Estate and rare gemstone consignment retains collector concentration, though volume is shifting toward platform-based direct acquisition with immediate provenance documentation.
- Tradeshows:B2B rough and polished diamond sourcing concentrates in Antwerp and Mumbai corridors, with Kimberley Process compliance requirements collapsing eligible supplier bases for premium allocations.
Retail stores retain the largest transaction value through bridal concentration. Online platforms are gaining share fastest as digitally native collectors complete high-value transactions through mobile interfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bridal buyers in India and gift purchasers in China concentrate volume, while collectors in the United States and Japan drive certified diamond premiums. European enforcement of traceability mandates redirects procurement toward compliant channels.
India
Wedding-related gold acquisitions and Akshaya Tritiya festival purchases sustain year-round procurement cycles for 22-karat bullion. BIS hallmarking enforcement at point of sale eliminates unhallmarked inventory from organized retail channels. Mumbai and Surat anchor diamond cutting and jewelry manufacturing clusters where compliant sellers redirect consumer trust.
China
Millennial and Gen Z consumers drive self-purchase and gifting demand for 24-karat gold and gem-set pieces. SAMR quality standards and evolving consumer protection frameworks tighten retail accountability. Shenzhen's jewelry manufacturing district concentrates CAD-assisted production capacity for domestic and export markets.
United States
Anniversary gifting and bridal segments sustain replacement cycles for certified solitaire diamonds. FTC jewelry guides enforce disclosure standards for gemstone treatments and metal content. New York's Diamond District and Los Angeles jewelry corridors concentrate wholesale and retail trading with embedded certification services.
Japan
Platinum bridal bands dominate wedding purchases due to density and hypoallergenic properties. METI consumer safety standards and precious metals marking laws enforce karat verification at retail. Tokyo's Ginza and Osaka's Shinsaibashi districts anchor high-end bridal and collector-oriented boutiques.
Germany
EU Conflict Minerals Regulation mandates due diligence for 3TG sourcing in finished jewelry imports. REACH substance restrictions extend compliance obligations to downstream importers. Frankfurt and Munich retail corridors prioritize bridal and solitaire lines with full chain-of-custody documentation.
Jewellery Market Key Industry Players
Player mix skews toward heritage maisons with captive mining partnerships and vertically integrated Asian conglomerates controlling rough allocation pipelines. Market structure concentrates certified diamond supply among established houses with in-house gemological capacity, while mid-market retailers compete on platform-based discovery and made-to-order automation. Strategic archetypes include vertically integrated mining-to-retail pipelines, heritage houses with proprietary certification laboratories, and digital-native direct-to-consumer platforms. Dominant competitive moves encompass blockchain provenance investments and CAD-assisted production automation.
Within the vertically integrated tier, Chow Tai Fook Jewellery Company Limited represents the archetype of mining-to-retail pipeline control securing certified rough allocations. Heritage maisons with in-house verification capacity include Cartier and Tiffany & Co., occupying positions where gemological certification extends beyond baseline regulatory requirements. These three anchors exemplify how supply chain positioning and documentation capabilities separate premium-tier competitors from compliance-challenged mid-market retailers.
| Leading Market Players |
|---|
| Chow Tai Fook Jewellery Company Limited |
| Cartier |
| Tiffany & Co. |
| Signet Jewelers |
| Rajesh Exports Ltd. |
| Pandora A/S |
| Titan Company |
| Van Cleef & Arpels |
| Graff |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Surat diamond cutting clusters and Shenzhen CAD-assisted manufacturing hubs compresses unit economics for mid-market producers while elevating price floors for certified inventory. This scale concentration simultaneously concentrates procurement leverage among vertically integrated houses and fragments margin pools for non-compliant retailers facing BIS hallmarking enforcement.
Pricing Analysis
Cost-plus contracts with London Bullion Market Association indexation dominate gold procurement for Indian bridal manufacturers, with karat-grade verification adding tiered certification premiums. Price differentiation separates BIS-hallmarked 22-karat inventory from unmarked alternatives, while platinum bridal bands command density-driven premiums in Tokyo and New York corridors. Pricing pressure stems from lab-grown diamond substitution at 60-70% price points, compressing solitaire margins. Digitally native collectors exhibit highest price sensitivity, whereas heritage maisons serving anniversary gifting segments maintain inelastic demand.
Supply Chain Analysis
Inventory lead times for certified rough diamonds extend through Kimberley Process verification queues, compressing available-to-promise windows for bridal collections. Geographic supply concentrates in India, China, and Belgium, with Surat and Mumbai anchoring cutting capacity and Antwerp controlling rough trading corridors. Raw material dependencies include South African platinum, Russian rough diamonds, and Ghanaian gold. Single-source vulnerability runs through South African platinum supply interruptions. Distribution runs through vertically integrated mining-to-retail pipelines and platform-based direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where BIS hallmarking mandates and Kimberley Process compliance create irreversible certification barriers that captive mining partnerships exploit.
For Market Incumbents: Fortify upstream control over certified rough allocations through mining joint ventures in compliant jurisdictions, while extending in-house gemological laboratory capacity to compress provenance verification timelines. Lab-grown diamond substitution threatens natural solitaire margins, requiring differentiation through blockchain-enabled chain-of-custody documentation.
For New Entrants and Emerging Players: BIS fast-track certification for 22-karat gold inventory opens organized retail access in Indian festival-season procurement windows. White-space targets include platform-based direct-to-consumer channels for digitally native collectors in Seoul and Singapore, and CAD-assisted made-to-order bridal automation for compressed delivery timelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heritage maisons with multi-decade anniversary gifting relationships and captive mining partnerships. Long-term viability centers on regulatory compliance infrastructure as a non-replicable asset. Acquisition targets include mid-market retailers with blockchain provenance platforms. The signal to watch is BIS enforcement expansion into tier-two Indian cities.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Investment | Full chain-of-custody documentation commands shelf-space priority under EU Conflict Minerals Regulation enforcement. |
| CAD-Assisted Production Automation | Robotic finishing compresses made-to-order timelines from weeks to days for scalable bridal customization. |
| Captive Mining Partnership | Vertically integrated rough allocation secures Kimberley Process certified inventory ahead of collapsed supplier base. |
| In-House Gemological Laboratory | Proprietary certification capacity extends provenance verification beyond baseline regulatory requirements at Cartier and Tiffany. |
| Platform-Based Direct Acquisition | Mobile interfaces with third-party escrow verification displace auction houses for first-time luxury buyers in Seoul. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bridal procurement directors at heritage maisons, BIS compliance officers at Indian retail chains, CAD-assisted manufacturing engineers in Shenzhen, and rough diamond sourcing managers in Antwerp. Secondary validation drew from Kimberley Process participant statistics, BIS hallmarking enforcement reports, EU Conflict Minerals filings, and LBMA precious metals pricing data. Bottom-up volume estimates triangulated with top-down market sizing across certification tiers.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type, material composition, end-user archetype, and distribution channel complexity. CAGRs derived from trend extrapolation of bridal procurement cycles, festival-season gold acquisition patterns, and platform-based channel migration rates. Industry-specific inputs included BIS enforcement penetration curves and lab-grown diamond substitution elasticities.
Underlying assumptions cover sustained BIS hallmarking enforcement, stable Kimberley Process participation rates, and continued platinum supply from South African operations, with deviation risk concentrated in regulatory enforcement intensity and synthetic diamond technology advancement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Bead Products Market
Jewelry
Artificial Jewellery Market
Jewelry
Jewelry Repair Market
Jewelry
Jewellery Box Market
Jewelry
Wedding Rings Market
Jewelry
Jewelry Cleaners Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Global Body Piercing Jewelry Market
Jewelry
Chalcedony Earrings Market
Jewelry
South Korea Luxury Jewelry Market
Jewelry
Luxury Fine Jewellery Market
Jewelry
Beaded Jewelry Market
Jewelry
Quartz Ring Market
Jewelry
Body Jewelry Market
Jewelry
Demi-Fine Jewelry Market
Jewelry
South Africa Luxury Jewelry Market