
 Brazil Jewelry Market | 2026-2036
Brazil Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Jewelry Market Analysis
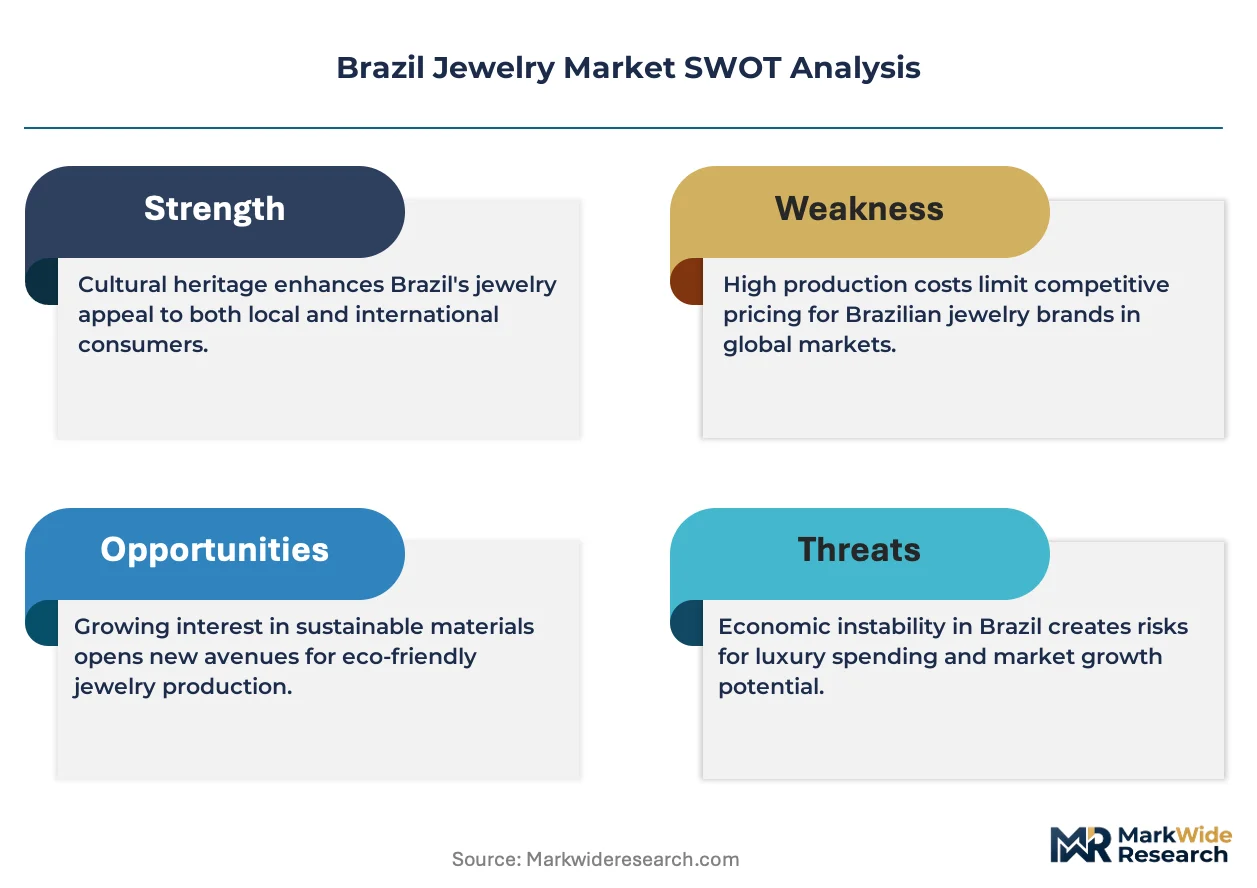
Multi-source gemstone procurement is broadening supply options for Brazilian jewelry houses. H. Stern Jewelers Inc. leverages its vertically integrated cutting and polishing operations in Rio de Janeiro to control rough diamond flows. Jóias Vivara anchors its position through a dense franchise network spanning state capitals. Manoel Bernardes S.A. specializes in handcrafted gold pieces rooted in Minas Gerais artisanal traditions.
Jewelry comprises ornamental objects crafted from precious metals and gemstones, typically involving alloying, casting, stone setting, and surface finishing to achieve specified karat purity and wear resistance. The primary commercial purpose centers on personal adornment, wealth storage, and ceremonial gift exchange across life events. Gold rings and gemstone necklaces occupy the mature volume core, while platinum bracelets capture expanding margin pools among affluent buyers. Silver earrings compete aggressively in mid-tier and budget tiers where price sensitivity shapes purchasing frequency.
ANVISA enforces metal biocompatibility and nickel release limits under Mercosur technical regulations, compelling domestic foundries to certify alloys through accredited laboratories. BIS-equivalent INMETRO conformity assessment applies to jewelry sold through formal retail channels, creating compliance barriers for informal importers. Stakeholders must monitor evolving traceability requirements for gemstone provenance and recycled gold sourcing as consumer scrutiny intensifies.
Market Dynamics
ANVISA's nickel release limits and INMETRO conformity assessments are tightening compliance thresholds for Brazilian foundries, forcing upstream investment in certified alloy testing and accredited laboratory partnerships.
Growth Catalysts
- Bridal segment expansion:Wedding-related purchases are concentrating purchasing power among younger demographic cohorts entering marriage formation years.
- INMETRO certification alignment:Formal retail channels gain competitive separation as informal importers face exclusion from compliant distribution networks.
- São Paulo retail corridor density:Luxury concentration in the state's goldsmithing clusters creates localized economies of scale for production and distribution.
Market Restraints
- Input metal volatility:Gold and platinum price swings compress margin predictability for inventory-heavy operators.
- Gemstone provenance tracing:Recycled gold sourcing documentation demands strain supplier verification systems.
- ANVISA biocompatibility testing:Extended laboratory certification timelines delay new alloy introductions to formal channels.
Strategic Opportunities
- Minas Gerais artisanal positioning:Handcrafted heritage narratives command premium pricing differentiation in domestic and export markets.
- Franchise network penetration:State capital coverage gaps outside São Paulo present white-space expansion for organized retail formats.
- Traceability technology convergence:Blockchain-linked provenance systems intersect with consumer scrutiny to enable certified sourcing premiums.
Industry Challenges
- Master goldsmith succession:Traditional hand-finishing skills face attrition as training pipeline contraction limits artisanal capacity scaling.
- Legacy equipment retrofitting:Casting and polishing machinery upgrades for emissions compliance demand capital deployment with extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Jewelry Market |
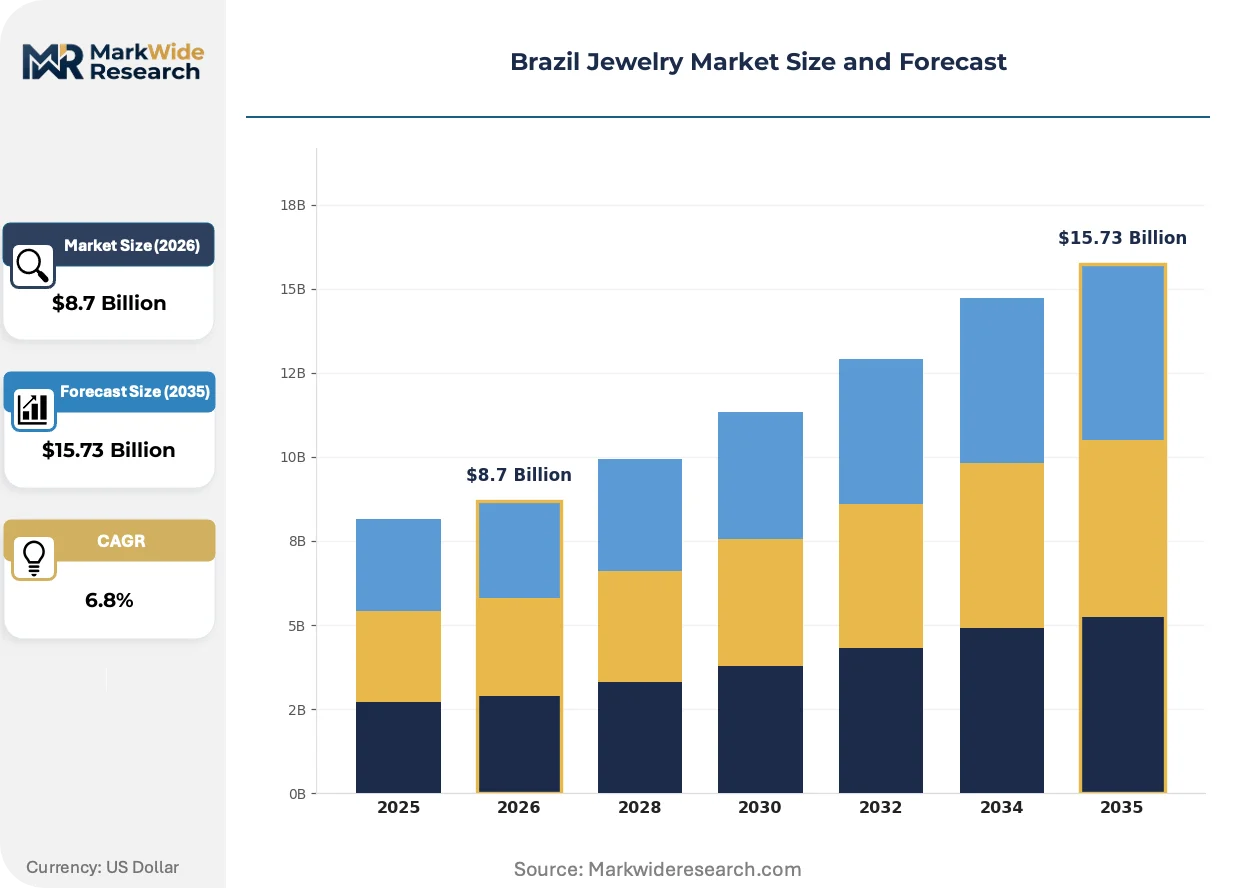
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Bracelets, Earrings Material: Gold, Silver, Platinum, Gemstones End User: Women, Men, Children, Couples Price Tier: Luxury, Mid-tier, Budget, Discount |
| Companies Covered | Tiffany & Co., Manoel Bernardes S.A., Jóias Vivara, Compagnie Financiere Richemont SA, Signet Jewelers Ltd., H. Stern Jewelers Inc., LVMH Moët Hennessy Louis Vuitton SE, Chow Tai Fook Jewellery Group Ltd., Pandora A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Jewelry Market Emerging Trajectories
Digital fabrication and regulatory traceability mandates are compressing traditional production timelines while elevating compliance infrastructure requirements across Brazilian jewelry manufacturing.
Laser-assisted stone setting is automating precision placement in high-volume production lines. Mid-tier manufacturers in São Paulo state are adopting these systems to reduce rework rates on pavé mounting. The technology is automating labor-intensive bench processes that previously constrained output scaling.
ANVISA's updated nickel release thresholds under Mercosur technical regulations are compelling foundry recertification. Domestic alloy suppliers must route batches through INMETRO-accredited laboratories before channel entry. Bridal ring manufacturers face the steepest compliance cost absorption given skin-contact exposure duration.
Direct-to-consumer digital channels are fragmenting traditional wholesale dependency. Younger buyers in southeastern state capitals are bypassing multi-brand retailers for atelier-owned e-commerce storefronts. Rio de Janeiro and Belo Horizonte exhibit the fastest channel-shift velocity as independent designers cultivate social-media-driven discovery.
Brazil Jewelry Market Segmentation
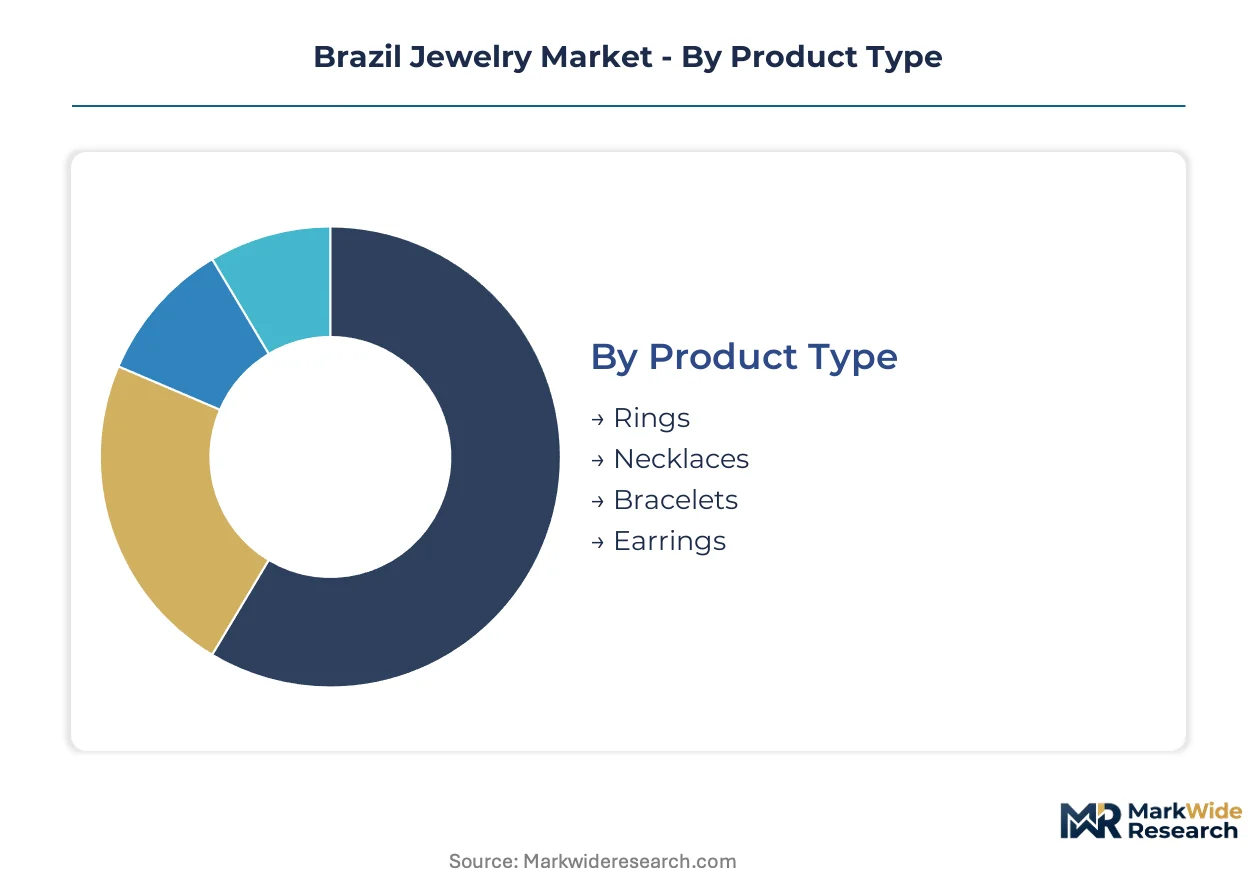
Jewelry purchasing in Brazil fragments across ceremonial occasions, metal preferences, and regional income gradients. Segmentation reveals how São Paulo's luxury corridors diverge from Minas Gerais artisanal demand, while ANVISA compliance costs reshape viable price positioning.
Product Type:
Occasion-based wearing patterns separate daily adornment from ceremonial investment pieces.
- Rings:Bridal and wedding bands dominate volume through karat-gold specifications and skin-contact durability requirements. São Paulo bridal boutiques concentrate purchasing power among younger cohorts entering marriage formation years, though ANVISA nickel testing adds compliance burden to new alloy introductions.
- Necklaces:Chain and pendant configurations span choker to opera lengths with clasp engineering for security. Gemstone-intensive designs from Rio de Janeiro ateliers are gaining share fastest as direct-to-consumer channels fragment traditional wholesale dependency.
- Bracelets:Bangle and link constructions in platinum capture expanding margin pools among affluent buyers in southeastern state capitals.
- Earrings:Silver-based studs and drops compete aggressively in mid-tier tiers where price sensitivity shapes purchasing frequency.
Volume sits with rings; growth tilts toward necklaces.
Material:
Cost structure and regulatory exposure vary sharply by metal type and sourcing complexity.
- Gold:18-karat and 22-karat alloys anchor the mature volume core with INMETRO certification mandatory for formal retail. Minas Gerais foundries face extended laboratory timelines for biocompatibility verification.
- Silver:925 sterling dominates mid-tier and budget positioning with lower purity thresholds reducing compliance overhead.
- Platinum:Dense, hypoallergenic properties command premium positioning in São Paulo luxury corridors where margin pools concentrate.
- Gemstones:Multi-source procurement broadens supply options for Brazilian houses, though provenance documentation demands strain verification systems.
Gold retains the volume base; platinum shows the steepest margin expansion trajectory.
End User:
Demographic targeting aligns with life-stage purchasing triggers and gift-exchange occasions.
- Women:Self-purchase and received-gift occasions drive the majority of transaction volume across all price tiers.
- Men:Wedding band and cufflink demand concentrates purchasing power among professional demographics in urban centers.
- Children:Commemorative gifting for birthdays and religious milestones sustains steady replacement demand.
- Couples:Coordinated bridal sets and anniversary investments command premium positioning with certified sourcing premiums.
Women account for volume concentration; couples represent the expanding premium segment.
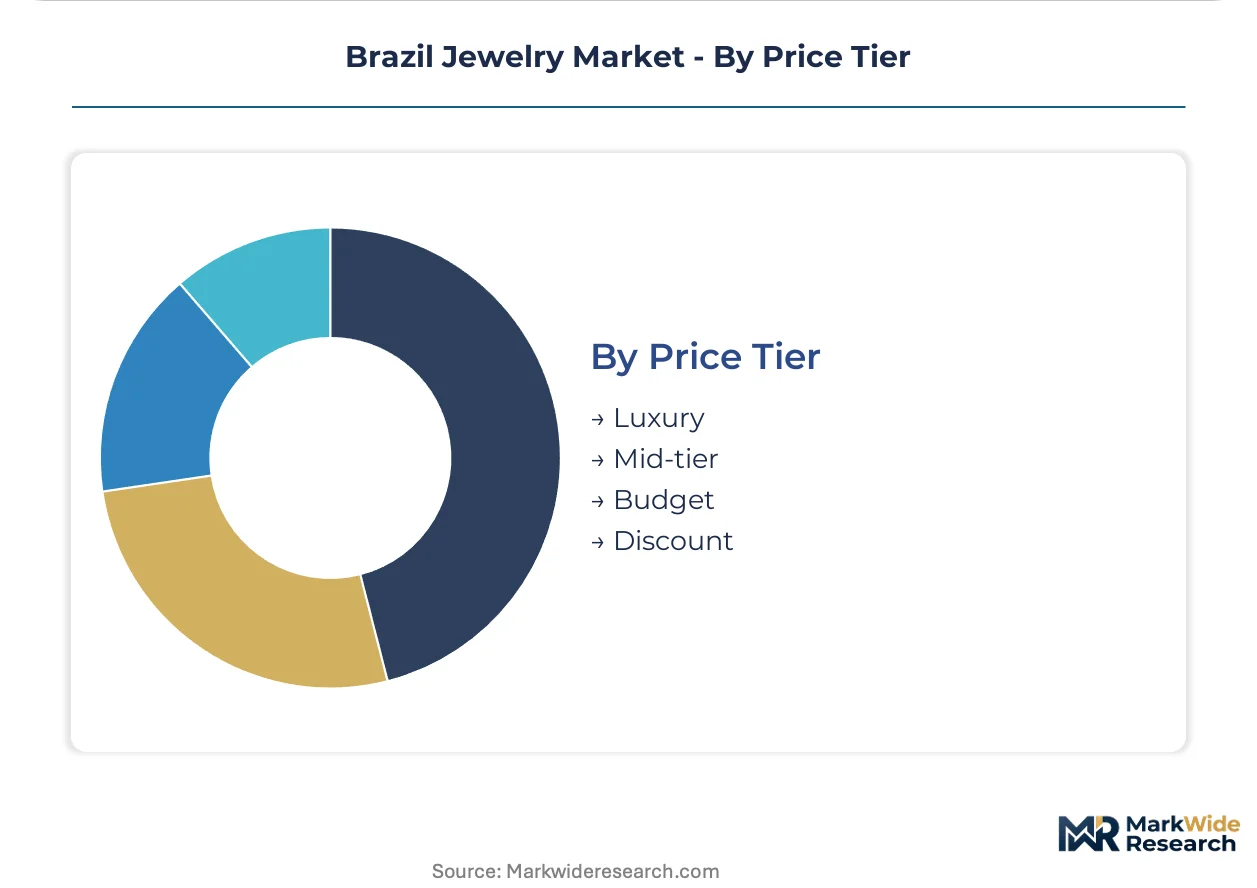
Price Tier:
Distribution channel access and certification compliance create sharp stratification in viable positioning.
- Luxury:H. Stern and comparable houses leverage vertically integrated cutting operations to control rough flows. São Paulo retail corridor density supports localized economies of scale for high-margin pieces.
- Mid-tier:Franchise networks like Jóias Vivara anchor penetration across state capitals outside the southeast core.
- Budget:Silver-dominant assortments compete on price sensitivity with reduced ANVISA testing burdens.
- Discount:Informal importers face exclusion from INMETRO-compliant distribution networks, compressing addressable market scope.
Mid-tier holds volume dominance; luxury captures margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Purchasing power concentrates in southeastern state capitals where bridal demand and luxury retail density intersect. São Paulo anchors volume absorption while Minas Gerais and Rio de Janeiro fragment across artisanal and digital-native positioning. ANVISA enforcement tightens compliance thresholds uniformly across all sub-regions.
São Paulo
Bridal boutiques concentrate marriage-formation demand among younger cohorts entering peak wedding years. INMETRO certification mandates filter informal importers from formal retail channels. The state's goldsmithing clusters in the capital city generate localized economies of scale for production and distribution.
Minas Gerais
Handcrafted heritage narratives command premium pricing differentiation rooted in centuries-old artisanal traditions. Extended ANVISA laboratory timelines for biocompatibility verification delay new alloy introductions. Belo Horizonte ateliers cultivate direct-to-consumer e-commerce storefronts bypassing traditional wholesale dependency.
Rio de Janeiro
Gemstone-intensive designs from independent designers gain share fastest through social-media-driven discovery. ANVISA nickel release thresholds under Mercosur technical regulations compel foundry recertification. The city's vertically integrated cutting operations control rough diamond flows for domestic houses.
Rio Grande do Sul
Mid-tier silver-dominant assortments compete aggressively where price sensitivity shapes purchasing frequency. Lower purity thresholds reduce compliance overhead relative to gold-intensive operators. Porto Alegre retail corridors exhibit slower channel-shift velocity than southeastern counterparts.
Bahia
Informal importers face exclusion from INMETRO-compliant distribution networks compressing addressable market scope. Regional income gradients favor budget-tier positioning over luxury concentration. Salvador's retail infrastructure lags state capital coverage density elsewhere in the northeast.
Brazil Jewelry Market Vendor Landscape
Franchise network expansion dominates the current landscape as organized retail formats penetrate state capitals outside the southeast core. The vendor base stratifies across three tiers: luxury houses with captive gemstone operations, mid-tier franchise networks with geographic breadth, and artisanal specialists with heritage positioning. Strategic archetypes include vertically integrated producers controlling rough flows, franchise operators scaling through capital-light expansion, and atelier-direct designers capturing digital-native demand. Competitive intensity centers on M&A activity among mid-tier operators and capacity expansion in certified alloy testing infrastructure.
Within the heritage-specialist tier, Manoel Bernardes S.A. exemplifies handcrafted gold positioning rooted in Minas Gerais traditions. Among franchise-network operators, Jóias Vivara anchors mid-tier penetration across state capitals through dense retail coverage. At the vertically integrated end, H. Stern Jewelers Inc. represents captive control over cutting and polishing operations.
| Leading Market Players |
|---|
| Tiffany & Co. |
| Manoel Bernardes S.A. |
| Jóias Vivara |
| Compagnie Financiere Richemont SA |
| Signet Jewelers Ltd. |
| H. Stern Jewelers Inc. |
| LVMH Moët Hennessy Louis Vuitton SE |
| Chow Tai Fook Jewellery Group Ltd. |
| Pandora A/S |
| Others |
Supply Flow & Price Mechanics
ANVISA's nickel release mandates under Mercosur technical regulations gate both qualified alloy supply and premium-tier pricing access, forcing bridal ring manufacturers to absorb steeper compliance costs for skin-contact pieces while informal importers face exclusion from INMETRO-certified distribution channels.
Pricing Analysis
The volume-mass split favors gold rings and silver earrings at scale, while platinum bracelets and certified bridal sets capture expanding margin pools. Price differentiation hinges on INMETRO certification tier and karat purity grade, with São Paulo luxury corridors commanding brand premiums. Cost compression in mid-tier silver assortments is intensifying because informal channels face regulatory exclusion. Budget-tier buyers exhibit acute price sensitivity, whereas couples purchasing certified bridal sets demonstrate minimal elasticity.
Supply Chain Analysis
Reverse-logistics flows for bridal ring resizing and heirloom refurbishment create secondary value recovery channels that extend customer lifetime value. Rough diamond sourcing concentrates in South Africa, Botswana, and Russia, while gold refining draws from Swiss and UAE hubs. Domestic foundries rest on certified alloy suppliers and INMETRO-accredited laboratory partnerships. Single-source vulnerability in gemstone cutting equipment strains capacity scaling. Distribution runs through São Paulo goldsmithing clusters and state capital franchise networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as players pursue captive control over rough diamond flows and cutting operations to defend margin pools against regulatory cost absorption.
For Market Incumbents: Anticipate ANVISA timeline extensions for new alloy certification by pre-qualifying laboratory partnerships and buffering inventory cycles. Secure backward integration into gemstone cutting capacity to offset provenance documentation demands. Channel control through owned retail corridors in São Paulo state anchors pricing power against franchise-network erosion. For New Entrants and Emerging Players: The price-point gap between H. Stern's vertically integrated luxury positioning and informal silver importers creates white-space for mid-tier digital-native ateliers. Target Belo Horizonte and Porto Alegre for direct-to-consumer e-commerce penetration where traditional wholesale dependency remains entrenched. Lead with blockchain-linked provenance narratives to capture certified sourcing premiums among younger southeastern buyers. For Investors and Strategic Acquirers: Master goldsmith training pipeline contraction is the leading indicator that artisanal capacity will constrain heritage-positioned players. Long-term viability favors acquisition targets with captive alloy testing infrastructure and Minas Gerais craft credentials. Monitor ANVISA enforcement intensity in informal channels as the signal for formal retail share expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cutting Operations | H. Stern's Rio de Janeiro facilities demonstrate how rough flow control defends margin pools against volatile gemstone procurement. |
| INMETRO Certification Pre-Positioning | Early laboratory partnership investments compress new alloy introduction timelines ahead of ANVISA enforcement waves. |
| Direct-to-Consumer Channel Launch | Belo Horizonte ateliers bypass wholesale dependency through social-media-driven discovery among younger demographic cohorts. |
| Heritage Craft Positioning | Manoel Bernardes leverages Minas Gerais artisanal narratives to command premium pricing differentiation in domestic and export markets. |
| Blockchain Provenance Integration | Traceability technology convergence enables certified sourcing premiums as consumer scrutiny intensifies across bridal segments. |
Methodological Framework
Multi-period observation of bridal purchase velocity, ANVISA certification timelines, and franchise network expansion anchored the trend analysis, supplemented by interviews with goldsmithing cluster operators, INMETRO-accredited laboratory directors, luxury retail procurement heads, and artisanal cooperative managers. Secondary validation drew from ANVISA regulatory filings, INMETRO conformity assessment databases, Mercosur technical regulation updates, and São Paulo state industrial production statistics. Bottom-up channel checks triangulated against top-down metal consumption estimates.
Segment-weighting applied product type, material grade, price tier, and regional purchasing power concentration across the projection horizon. CAGRs were derived from trend extrapolation of bridal formation rates and certified retail channel penetration. Modeled inputs included gold price volatility bands, ANVISA laboratory capacity constraints, and digital channel shift velocity in southeastern state capitals.
Inputs from ANVISA enforcement bulletins and INMETRO certification registries were available through the study window; gaps in informal channel transaction data introduce uncertainty bands around discount-tier estimates. Forecasts reflect assumptions on regulatory enforcement consistency and bridal demographic stability. Practitioners should monitor ANVISA nickel threshold revision announcements and master goldsmith training program enrollment for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Beaded Jewelry Market
Jewelry
Latin America Jewelry Market
Jewelry
Luxury Jewelry Market
Jewelry
Germany Luxury Jewelry Market
Jewelry
Italy Luxury Jewelry Market
Jewelry
Quartz Ring Market
Jewelry
Body Jewelry Market
Jewelry
Pearl Jewelry Market
Jewelry
Crystal Bracelets Market
Jewelry
Luxury Fine Jewellery Market
Jewelry
Jewelry Repair Market
Jewelry
Qatar Jewelry Market
Jewelry
Chalcedony Earrings Market
Jewelry
Mexico Luxury Jewelry Market
Jewelry
Jewellery Market
Jewelry
South Korea Luxury Jewelry Market