
 Jewelry Repair Market | 2026-2036
Jewelry Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Jewelry Repair Market Insights
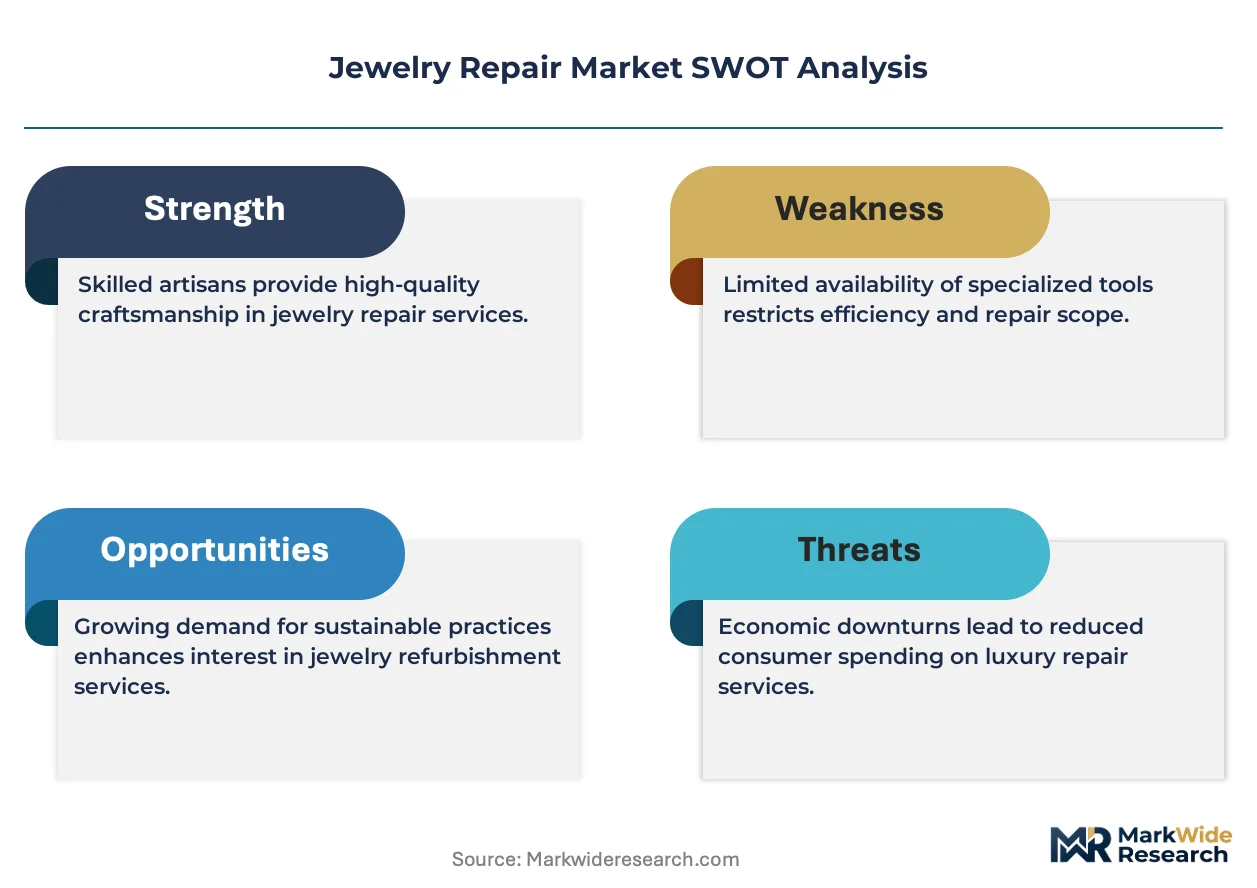
Bench jeweler availability is reorganizing service capacity across the industry. Fast-Fix sustains a nationwide kiosk network that brings repair access to mall and airport retail environments. My Jewelry Repair leverages mail-in logistics to serve customers outside major metropolitan areas. Zales anchors in-house repair operations within its owned retail footprint, competing on turnaround speed and brand trust.
Jewelry repair encompasses the restoration, alteration, and maintenance of precious metal and gemstone items through soldering, stone setting, polishing, and metalwork processes requiring magnification and torch or laser equipment. The practice preserves material value and sentimental worth in pieces that replacement cannot replicate. Ring resizing and stone replacement command the largest share of service revenue due to frequency of wear-related damage. Gold and platinum material types carry higher average repair values than silver, concentrating margin pools in luxury metalwork.
The Federal Trade Commission's Jewelry Guides govern disclosure standards for repair materials and gemstone treatments, while state-level consumer protection laws in California and New York impose warranty and pricing transparency obligations on service providers. ISO 9001 certification and NAJA educational credentials increasingly filter which shops gain access to insurance-funded restoration work and estate jewelry handling. Stakeholders must track how digital authentication tools and blockchain provenance records reshape customer expectations for repair documentation and chain-of-custody verification.
Market Dynamics
Bench jeweler scarcity is decomposing service capacity across the United States, forcing repair networks to reorganize around centralized hubs and mail-in logistics rather than maintaining dense geographic coverage through standalone shops.
Growth Catalysts
- Laser welding adoption:Precision heat control expands repairable damage categories previously deemed irreversible, pulling high-value estate pieces back into serviceable inventory.
- FTC Jewelry Guides enforcement:Disclosure standardization builds consumer confidence in certified repair documentation, reducing information asymmetry between shops and heirloom owners.
- Insurance-funded restoration:Carriers increasingly require NAJA-credentialed handlers for claims processing, directing volume toward credentialed providers.
Market Restraints
- Platinum group metal volatility:Rhodium and palladium price swings compress margin predictability on white gold plating and platinum restoration work.
- Bench jeweler pipeline collapse:Trade school graduation rates lag replacement demand by a widening gap, concentrating skilled labor in coastal metropolitan clusters.
- Silver price ceiling:Low material value relative to labor cost renders many silver repairs economically irrational for consumers, shrinking addressable volume.
Strategic Opportunities
- Blockchain provenance integration:Immutable repair records create defensible differentiation for shops serving auction houses and estate trustees.
- Remote diagnostic imaging:High-resolution photography and video consultation compress initial assessment cycles for mail-in customers outside service corridors.
- ISO 9001 certification gap:Mid-tier independent shops remain uncertified, creating acquisition targets for chains seeking insurance network access.
Industry Challenges
- Apprenticeship timeline compression:Traditional multi-year training paths conflict with immediate labor needs, degrading quality consistency.
- Equipment amortization pressure:Laser welder and CAD/CAM system investments demand volume throughput that fragmented demand cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jewelry Repair Market |
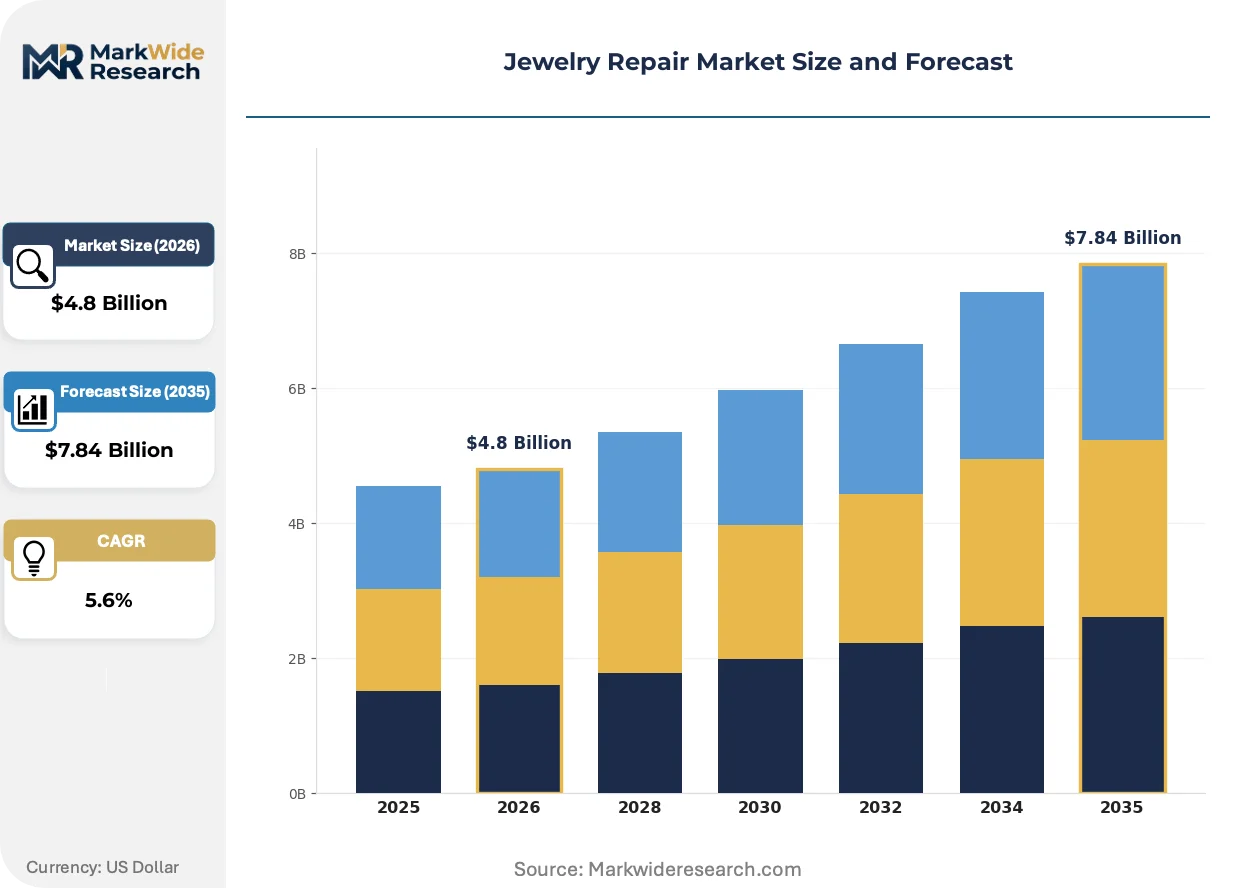
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ring Resizing, Stone Replacement, Cleaning, Engraving Material Type: Gold, Silver, Platinum, Gemstones Customer Type: Retail Customers, Wholesale Clients, Jewelers, Collectors Repair Technique: Soldering, Polishing, Prong Setting, Recasting |
| Companies Covered | My Jewelry Repair, Quick Jewelry Repairs, Jewelry Repair Enterprises, Service Jewelry & Repair, Jewelry Service Center, Fast-Fix, Jared, Zales, REEDS Jewelers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jewelry Repair Market Trends and Innovations
Digital authentication tools are reconfiguring trust mechanisms between repair providers and high-net-worth clients, shifting competitive advantage from geographic proximity toward documented chain-of-custody capabilities.
Laser welding technology is decomposing the traditional heat-damage risk calculus that constrained repairable jewelry categories. Luxury watch service centers and high-end estate specialists are adopting pulsed Nd:YAG systems at accelerating rates. This capability expansion is compressing the boundary between restoration and replacement economics, enabling shops to capture value from previously unrepairable platinum settings and heat-sensitive colored gemstones.
The FTC's updated Jewelry Guides are tightening disclosure obligations for repair materials and gemstone treatments across United States commerce. Shops must now document metal alloy substitutions and synthetic stone replacements with explicit consumer acknowledgment. Estate jewelry handlers and insurance-funded restorers face the steepest compliance burden, with many consolidating documentation workflows into centralized CRM systems.
Collector behavior is shifting toward documentation-driven shop selection rather than convenience-based proximity. High-value heirloom owners now prioritize shops offering photographic repair logs and third-party authentication partnerships over turnaround speed. This preference rotation is most visible in California and New York metropolitan corridors, where estate density and auction house concentration amplify documentation demands.
Jewelry Repair Market Segmentation
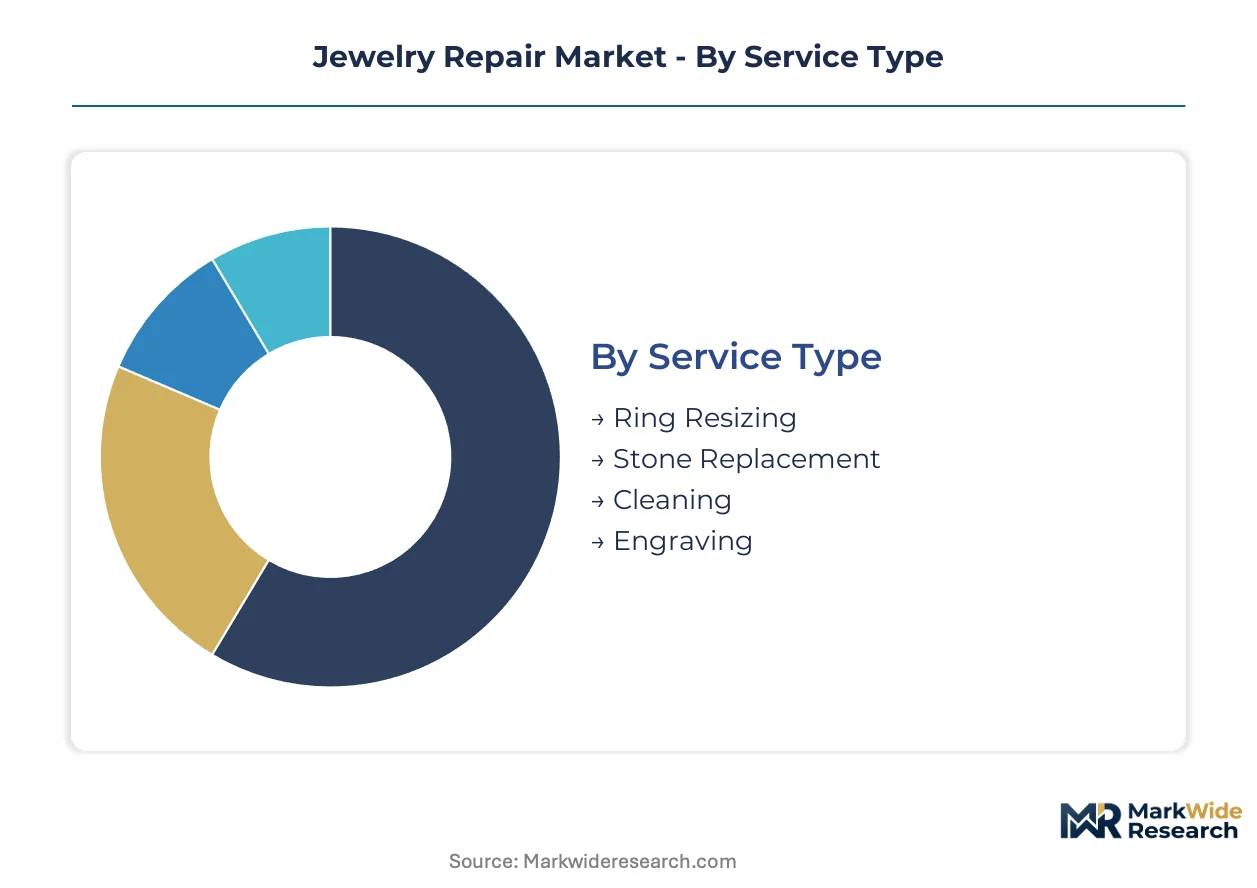
Jewelry repair demand fragments across service modalities, material values, and customer sophistication levels. Margin concentration follows metal type and credential requirements rather than volume throughput. Each segmentation axis reveals distinct competitive dynamics and capability investments.
Service Type:
Revenue pools concentrate in structural alterations and stone work where labor skill premiums exceed material costs.
- Ring Resizing:Shank cutting, metal insertion, and re-soldering accommodate finger measurement changes from weight fluctuation or inheritance transfers. United States demand clusters in metropolitan corridors with aging estate jewelry inventories and high bridal market turnover.
- Stone Replacement:Prong reconstruction, gem sourcing, and secure resetting address loss from wear damage or theft claims. Insurance-funded restorations in California and New York drive credential requirements and documentation standards.
- Cleaning:Ultrasonic and steam removal of accumulated residue restores luster without metal loss. Retail chains bundle this as loss-leader traffic generation.
- Engraving:Rotary or laser inscription adds personalization to gifts and memorial pieces. Seasonal demand spikes concentrate in fourth-quarter gift cycles.
Ring resizing holds installed capacity. Stone replacement is rotating up the share rankings.
Material Type:
Price-to-labor ratios determine repair economics and shop willingness to accept work.
- Gold:Yellow and rose alloys dominate volume due to jewelry stock penetration, though white gold rhodium plating adds recurring service revenue. United States consumers show highest propensity to repair 14K and 18K pieces.
- Platinum:Dense, high-melting-point metal demands laser welding capability and specialized torch gases. Estate piece restoration in high-net-worth coastal markets commands premium labor rates.
- Silver:Low spot price relative to bench jeweler hourly rates renders many repairs economically irrational. Volume concentrates in costume jewelry and artisan craft segments.
- Gemstones:Heat-sensitive colored stones and fracture-filled diamonds require temperature-controlled repair environments. Auction house and collector documentation requirements filter provider access.
Platinum commands margin concentration. Gold maintains volume dominance.
Customer Type:
Procurement patterns split between emotional-value-driven retail and documentation-driven institutional buyers.
- Retail Customers:Individual heirloom owners prioritize sentimental preservation over replacement cost. Turnaround sensitivity varies by occasion proximity.
- Wholesale Clients:Retail jewelers outsource overflow capacity and specialized techniques beyond in-house capability. Relationship duration drives vendor selection.
- Jewelers:Trade-only repair services handle manufacturing defects and warranty claims from original sale. Volume concentration supports dedicated bench allocation.
- Collectors:High-value watch and estate jewelry owners demand photographic logs, third-party authentication, and chain-of-custody documentation. California and New York auction corridor proximity amplifies service expectations.
Collectors are climbing the fastest in service premium capture. Retail customers anchor volume throughput.
Repair Technique:
Equipment intensity and skill certification requirements stratify provider capabilities.
- Soldering:Traditional torch-based metal fusion remains foundational for shank repair and chain mending. Heat damage risk constrains application on temperature-sensitive stone settings.
- Polishing:Buffing wheel and compound restoration removes surface scratches and restores reflectivity. Marginal labor cost supports high-frequency, low-margin service bundling.
- Prong Setting:Stone retention reconstruction prevents loss from worn or bent metal claws. Insurance claim documentation requires NAJA-credentialed handlers.
- Recasting:Complete melting and reformation salvages damaged pieces into new designs. Metal loss and alloy mixing complexities limit provider adoption.
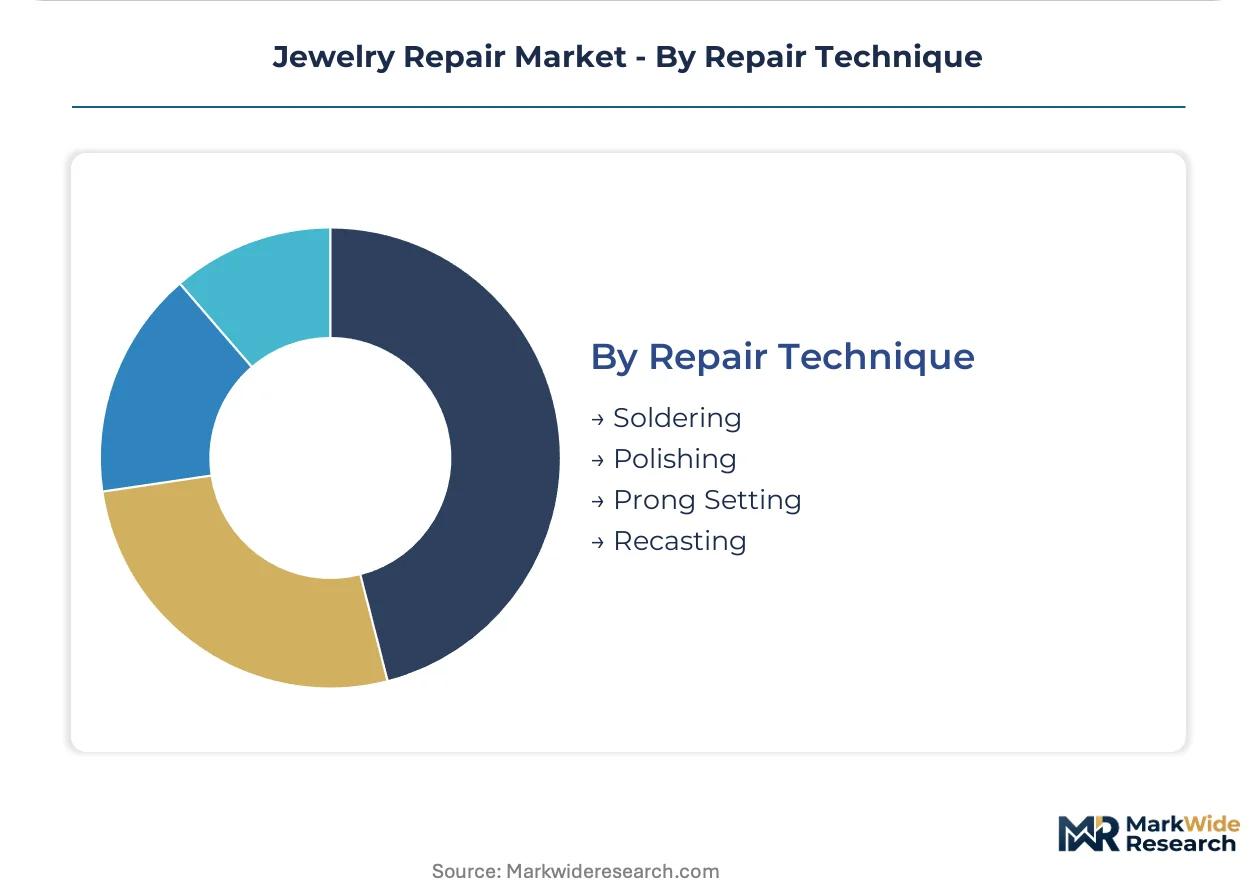
Soldering holds technique ubiquity. Prong setting is gaining share fastest on insurance volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FTC's Jewelry Guides enforcement in the United States anchors regulatory standards that shape disclosure obligations across developed markets, with certified repair documentation requirements filtering into Canada and European Union consumer protection frameworks.
United States
Luxury watch collectors and heirloom jewelry owners in California and New York metropolitan corridors drive demand for NAJA-credentialed handlers and photographic repair logs. The FTC's updated Jewelry Guides mandate explicit consumer acknowledgment for metal alloy substitutions and synthetic stone replacements. Los Angeles and Manhattan host dense concentrations of estate specialists competing on chain-of-custody verification capabilities.
Canada
Toronto and Vancouver anchor service demand for platinum restoration and insurance-funded stone replacement among high-net-worth households. Health Canada consumer protection regulations align with FTC disclosure frameworks for cross-border service providers. The Greater Toronto Area concentrates independent repair shops pursuing ISO 9001 certification for insurance network access.
Germany
Munich and Hamburg support premium estate jewelry restoration demand from generational wealth holders. REACH regulations govern chemical disclosure for cleaning compounds and plating solutions used in repair processes. The Rhine-Ruhr industrial corridor hosts specialized equipment suppliers serving laser welding adoption across Central European shops.
United Kingdom
London's auction house concentration elevates documentation requirements for repair providers serving estate trustees and collector consignors. The UK's Consumer Rights Act imposes warranty transparency obligations on service contracts. Hatton Garden maintains its position as a repair cluster where blockchain provenance integration differentiates premium providers.
France
Parisian luxury heritage sustains demand for artisan metalwork restoration among family-owned jewelry inventories. ANSM chemical safety standards regulate compounds used in ultrasonic cleaning and polishing processes. The Place Vendôme district concentrates high-end repair ateliers serving maison clients with archival documentation requirements.
Jewelry Repair Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the jewelry repair market. National retail chains leverage owned-store footprints for turnaround speed and brand trust, while mail-in specialists capture geographic coverage through logistics networks rather than physical presence. Three archetypes dominate: mall kiosk operators optimizing convenience access, estate specialists commanding premium labor rates through credential density, and hybrid platforms integrating remote diagnostics with centralized bench capacity. Consolidation pressure favors acquisition of ISO 9001-certified independents by chains seeking insurance network access, while equipment amortization demands push mid-tier shops toward hub-and-spoke collaboration models.
Within the national retail tier, Zales and Jared exemplify scale-driven service integration through in-house bench operations, while Fast-Fix occupies a distinct position with mall and airport kiosk density prioritizing convenience over technical complexity. My Jewelry Repair represents the logistics-first archetype, using mail-in infrastructure to serve customers outside metropolitan service corridors.
| Leading Market Players |
|---|
| My Jewelry Repair |
| Quick Jewelry Repairs |
| Jewelry Repair Enterprises |
| Service Jewelry & Repair |
| Jewelry Service Center |
| Fast-Fix |
| Jared |
| Zales |
| REEDS Jewelers |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with certified bench jewelers lock in both repair throughput and labor rate visibility for chains competing on turnaround speed. These agreements concentrate pricing power among ISO 9001-certified hubs in California and New York while forcing independent shops into spot-market labor sourcing that amplifies margin volatility.
Pricing Analysis
Geographic price spreads between Manhattan estate specialists and Midwest mall kiosk operators exceed three-to-one on identical ring resizing procedures. Three-tier pricing structure across NAJA-credentialed estate handlers, ISO-certified mid-tier chains, and uncertified independents stratifies the market. Cost compression in silver repair tiers is intensifying because material value fails to justify bench jeweler hourly rates. Retail customers seeking heirloom preservation show lowest price sensitivity, while silver costume jewelry owners abandon repairs entirely above minimal thresholds.
Supply Chain Analysis
Port congestion on trans-Pacific lanes from Shenzhen and Mumbai delays laser welder and CAD/CAM equipment deliveries to United States service hubs by weeks. Equipment manufacturing concentrates in Germany, Japan, and China, while rhodium and palladium sourcing for white gold plating rests on South African and Russian mine output. Single-source vulnerability in palladium supply chains threatens plating cost predictability. Distribution runs through manufacturer-direct sales to large chains, with independents purchasing through secondary distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among insurance carriers mandating NAJA credentials, fragmenting volume access for uncertified providers. This consolidation among institutional buyers forces repair networks to credential-stack or exit insurance-funded restoration channels entirely.
For Market Incumbents: Compound credential density by acquiring ISO 9001-certified independents in underserved metropolitan corridors before competitors lock in insurance network access. Defend against mail-in logistics specialists by embedding photographic documentation workflows into CRM systems. Laser welding capability expansion represents the priority defensive investment. For New Entrants and Emerging Players: NAJA certification fast-track programs open white-space access in estate jewelry corridors where documentation requirements filter out uncredentialed competitors. Target platinum restoration demand in coastal high-net-worth markets where labor skill premiums exceed equipment amortization concerns. Remote diagnostic imaging partnerships with auction houses provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier independent shops with latent ISO 9001 certification potential and established insurance carrier relationships. Long-term viability over the next decade hinges on blockchain provenance integration capabilities and centralized hub logistics infrastructure. The signal to watch is carrier consolidation around preferred provider networks that freeze out uncredentialed competitors.| Strategic Initiative | Industry Significance |
|---|---|
| NAJA Credential Acquisition | Unlocks insurance-funded restoration volume concentrated in California and New York corridors. |
| Laser Welding Equipment Deployment | Expands repairable damage categories to capture previously unrepairable platinum estate pieces. |
| Blockchain Provenance Integration | Differentiates providers serving auction houses and collector consignors demanding immutable documentation. |
| Mail-in Logistics Network Buildout | Extends geographic coverage beyond metropolitan bench jeweler clusters into underserved inland markets. |
| ISO 9001 Certification Pathway | Qualifies shops for insurance network access and estate trustee procurement requirements. |
Research Methodology
A standing panel of bench jeweler trade school directors, insurance claims adjusters, estate auction house specialists, and laser equipment distributors provided ongoing calibration against field conditions. Primary interviews with Fast-Fix kiosk operators, My Jewelry Repair logistics managers, and Zales service center heads combined with secondary validation from FTC Jewelry Guides enforcement records, NAJA educational program disclosures, and United States trade school graduation databases. Bottom-up service volume estimates triangulated against top-down jewelry stock penetration models.
Consistency checks validated volume and value outputs against external benchmarks including customs data on laser welder imports, insurance carrier restoration claim filings, and estate auction consignment records. The analytical framework segmented demand across service type, material value tier, customer sophistication level, and repair technique intensity throughout the forecast period. CAGRs derived from cohort-based replacement demand modeling and bench jeweler pipeline projections. Industry-specific inputs included rhodium price volatility indices and laser equipment adoption curves.
Underlying assumptions cover stable FTC Jewelry Guides enforcement intensity, NAJA credential maintenance requirements, and palladium supply continuity, with deviation risk concentrated in trade school graduation rate collapses and platinum group metal price spikes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Global Body Piercing Jewelry Market
Jewelry
Bead Products Market
Jewelry
Luxury Jewelry Market
Jewelry
Global Jewelry Market
Jewelry
Crystal Bracelets Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Leather Jewellery Box Market
Jewelry
Germany Luxury Jewelry Market
Jewelry
Pearl Jewelry Market
Jewelry
Mexico Luxury Jewelry Market
Jewelry
Global Costume Jewelry Market
Jewelry
Artificial Jewellery Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
Customized Jewelry Market
Jewelry
Italy Luxury Jewelry Market