
 Quartz Ring Market | 2026-2036
Quartz Ring Market Size, Share, and Industry Trends Forecast 2026-2036
Quartz Ring Market Insights
Asset-light leasing models for high-purity quartz fabrication equipment are reshaping competitive entry barriers in the quartz ring supply chain. Cosentino leverages vertical integration into engineered quartz raw material sourcing to sustain margin control across finish-type variants. Hanwha L&C anchors its position through R&D intensity in synthetic quartz crystal growth, while Cambria competes via geographic dominance in North American distribution channels.
A quartz ring is a precision-machined circular component fabricated from single-crystal or fused silica, typically achieving surface roughness below 0.5 micrometers and thermal stability beyond 1000 degrees Celsius to withstand corrosive plasma environments in semiconductor processing. Its primary industrial purpose centers on serving as a consumable chamber liner or focus ring in etch and deposition tools, where dielectric consistency protects wafer integrity. Engineered quartz dominates volume production due to controlled purity and batch uniformity, while fused quartz commands premium positioning in extreme-thermal applications where natural crystalline structures would fracture. The jewelry-making application segment matures with established artisan supply chains, whereas electronics-oriented demand accelerates fastest alongside advanced node semiconductor expansion.
EPA emissions standards and OSHA silica exposure limits govern quartz machining operations in the United States, while REACH registration requirements in Europe restrict certain binder chemistries in engineered quartz formulations. China's GB standards and MIIT industrial policies set domestic purity benchmarks that foreign suppliers must meet for market access. Stakeholders must monitor evolving semiconductor equipment roadmaps to align ring specifications with next-generation plasma chemistries before qualification cycles lock in supplier relationships.
Market Dynamics
Semiconductor node shrinkage below 3nm is compressing quartz ring replacement cycles while plasma chemistry intensification demands dielectric materials with sub-ppm metallic impurity thresholds.
Growth Catalysts
- Advanced node expansion:Taiwan Semiconductor Manufacturing and Samsung Foundry are scaling 2nm pilot lines that triple chamber component consumption rates versus legacy nodes.
- REACH Article 33 disclosure mandates:ECHA enforcement of full material composition transparency is disqualifying unqualified Asian suppliers from EU equipment vendor procurement lists.
- Fluorine-based plasma chemistries:Atomic layer etching adoption in 3D NAND fabrication requires corrosion-resistant fused quartz formulations with engineered aluminum doping profiles.
Market Restraints
- High-purity silica feedstock concentration:Unimin and Sibelco control over 70 percent of semiconductor-grade quartz sand extraction from Spruce Pine, North Carolina deposits.
- Energy cost volatility:Electric arc furnace operations for synthetic quartz crystal growth consume 12-15 MWh per metric ton, exposing margins to German and Chinese industrial electricity tariff swings.
- Technical purity ceilings:Natural crystalline quartz cannot achieve sub-10 ppb total alkali content required for EUV lithography adjacent components, capping addressable market share.
Strategic Opportunities
- Vietnam fabrication greenfield:Intel and Amkor are qualifying local quartz ring suppliers for assembly and test operations outside China tariff exposure zones.
- Photovoltaic silicon pulling:Monocrystalline ingot growth crucibles represent a 400,000-unit annual demand pool with lower purity barriers than semiconductor applications.
- US CHIPS Act domestic content incentives:$39 billion in direct fab construction subsidies mandate qualifying North American component sourcing for federal tax credit eligibility.
Industry Challenges
- Plasma etch chamber qualification timelines:Lam Research and Applied Materials require 18-24 month validation cycles for new ring geometries, freezing supplier switches mid-equipment generation.
- Metrology talent scarcity:ICP-MS operators capable of detecting sub-part-per-trillion metallic contamination command 40 percent wage premiums versus general analytical chemists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quartz Ring Market |
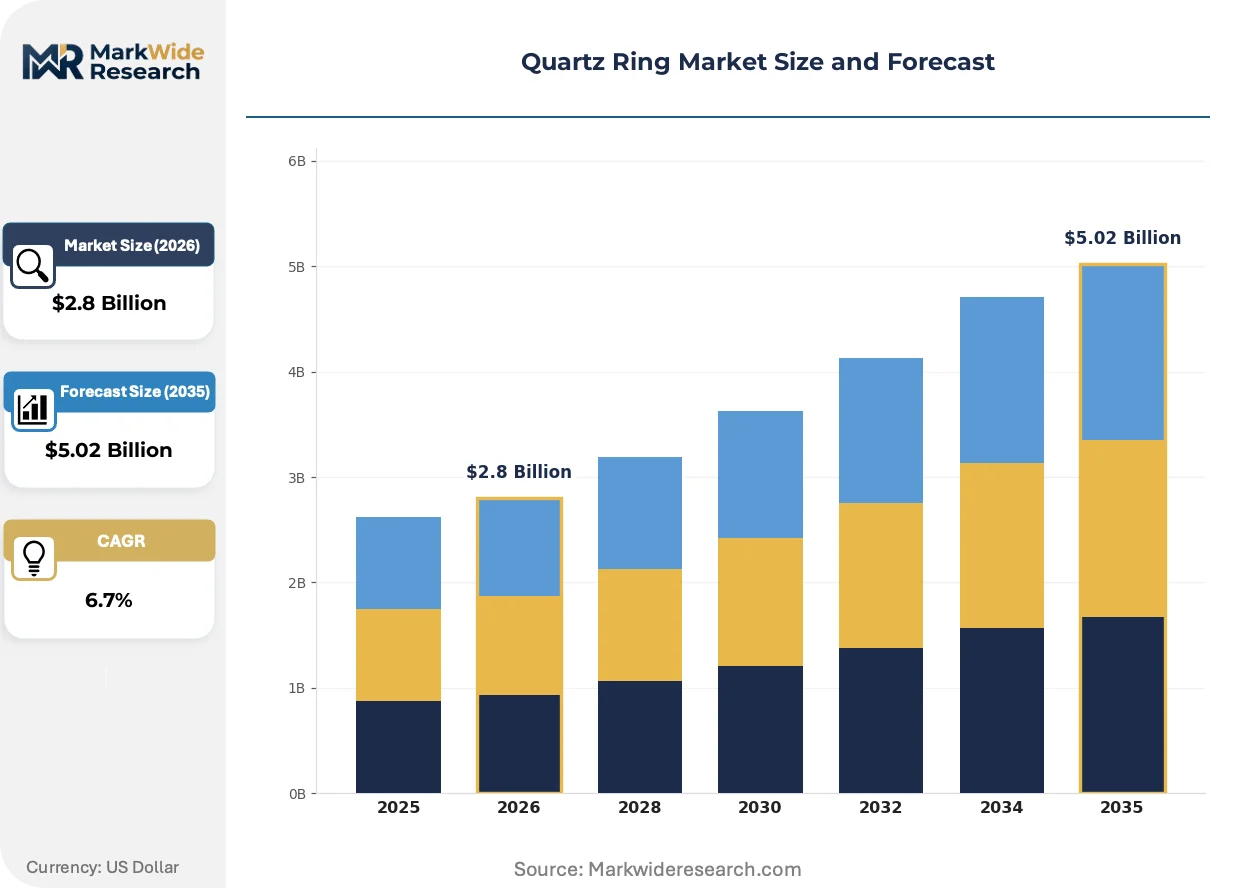
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Natural Quartz, Synthetic Quartz, Fused Quartz, Engineered Quartz Application: Jewelry Making, Electronics, Watches, Healing Crystals Finish Type: Polished, Matte, Frosted, Textured Shape: Round, Square, Oval, Hexagonal |
| Companies Covered | Cosentino, Caesarstone, Hanwha L&C, Compac, Vicostone, Wilsonart, LG Hausys, Cambria, Santa Margherita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quartz Ring Market Trends and Innovations
Plasma processing equipment roadmaps are forcing material science breakthroughs in thermal shock resistance and plasma erosion durability, compressing traditional quartz ring design cycles from five years to eighteen months.
Hot isostatic pressing of engineered quartz powder preforms is rendering obsolete conventional slip-cast fused silica rings in high-power CCP etch chambers. Tokyo Electron and Lam Research are qualifying HIP-consolidated components for 5nm logic production lines. The structural consequence is collapsing the premium pricing tier for natural quartz-derived alternatives in all but legacy tool maintenance pools.
China's MIIT is tightening GB/T 32650 purity benchmarks for semiconductor-grade quartz substrates effective 2025, requiring foreign suppliers to establish domestic testing laboratories for batch certification. The regulation forces European and Japanese producers to absorb $2-4 million per facility in capital expenditure for X-ray fluorescence and glow discharge mass spectrometry equipment. Domestic Chinese foundries are accelerating supplier qualification to capture import substitution premiums before the enforcement window closes.
Equipment lessors including Hitachi Capital and Tokyo Century are unbundling quartz ring replacement from capital equipment leases, converting consumable procurement to per-wafer-pass pricing models. This displaces traditional spot purchasing by foundry maintenance departments with contracted managed inventory programs. The shift concentrates most visibly in South Korean memory fabs where Samsung and SK Hynix have outsourced non-core component logistics to specialized semiconductor supply chain operators.
Quartz Ring Market Segmentation
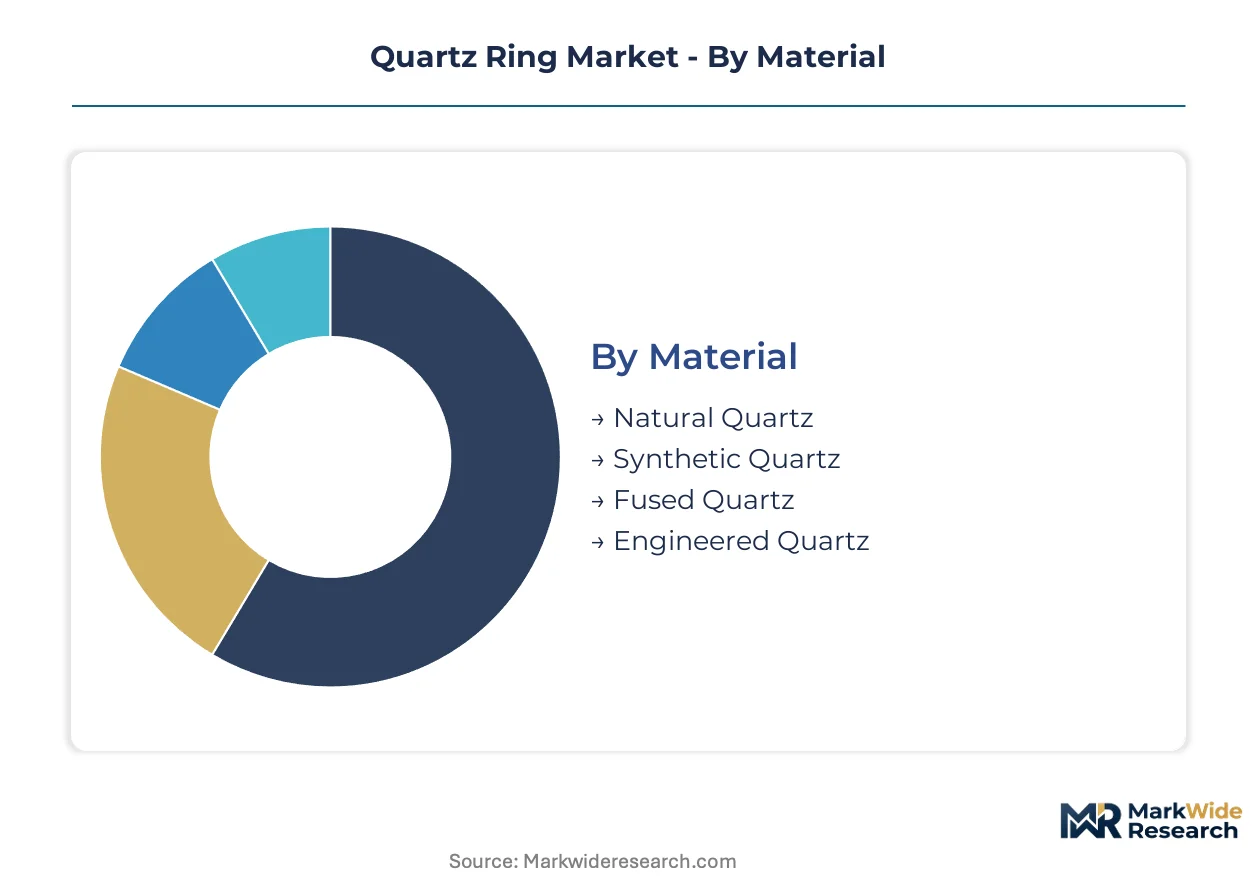
Quartz ring specifications diverge sharply between semiconductor chamber components demanding sub-ppm purity thresholds and artisan jewelry tolerating natural inclusions. Material composition and surface finish drive order-of-magnitude pricing spreads, while application-specific qualification protocols lock supplier relationships across multi-year equipment cycles.
Material:
Cost tier stratification in raw material sourcing separates commodity feedstock from semiconductor-grade certified supply chains.
- Synthetic Quartz:Hydrothermal crystal growth achieves controlled aluminum and alkali doping profiles essential for plasma etch chamber compatibility. Taiwan Semiconductor Manufacturing and Samsung Foundry procurement specifications favor synthetic material for 3nm node focus rings where natural crystalline variability risks wafer contamination.
- Fused Quartz:Electric arc melting of high-purity silica sand yields amorphous structures with thermal shock resistance beyond 1000 degrees Celsius. Jiangsu province processing clusters supply domestic Chinese foundries with fused quartz ring variants for legacy 28nm deposition tools.
- Natural Quartz:Spruce Pine, North Carolina deposits provide semiconductor-grade crystalline feedstock for jewelry and optical applications where trace element signatures are acceptable.
- Engineered Quartz:Resin-bonded quartz particle composites serve decorative surface applications and low-temperature industrial seals outside corrosive plasma environments.
Synthetic quartz holds installed capacity. Fused quartz is rotating up the share rankings.
Application:
Customer type separation between capital equipment procurement and consumer retail channels creates divergent margin structures and inventory velocity requirements.
- Electronics:Semiconductor fabrication equipment manufacturers specify 18-24 month qualification cycles for plasma chamber ring geometries, converting consumable procurement to contracted managed inventory programs. Lam Research and Applied Materials lock supplier relationships before equipment generation launches.
- Jewelry Making:Artisan supply chains in Jaipur and Guangzhou source natural quartz rough for cabochon cutting and bezel setting, with polished finish premiums commanding threefold markups over raw material costs.
- Watches:Swiss manufacturers utilize synthetic quartz oscillator blanks for timekeeping precision, while decorative case rings incorporate fused quartz for scratch resistance.
- Healing Crystals:New Age retail distributors in Sedona and Bali source unpolished hexagonal quartz rings for metaphysical merchandise, with frosted finish variants expanding fastest in direct-to-consumer e-commerce channels.
Electronics commands pricing power. Healing crystals is climbing the fastest.
Finish Type:
Surface treatment intensity correlates with end-use precision requirements, from optical-grade polishing to aesthetic texturing for consumer differentiation.
- Polished:Sub-0.5 micrometer surface roughness specifications satisfy semiconductor chamber liner requirements where particle shedding risks wafer defects. Tokyo Electron and Lam Research mandate polished finish for all high-power CCP etch components.
- Matte:Controlled acid etching produces diffuse reflectance preferred in watch case rings and architectural lighting fixtures where glare reduction matters.
- Frosted:Sandblasted surfaces mask minor crystalline inclusions in jewelry applications, expanding share in mass-market bridal band segments.
- Textured:Precision-machined groove patterns enhance thermal dissipation in LED packaging substrates and grip surfaces for industrial tool handles.
Polished finish holds specification authority. Frosted is gaining share fastest.
Shape:
Geometric complexity drives machining cost differentiation, with simple profiles dominating volume and specialized contours capturing precision premiums.
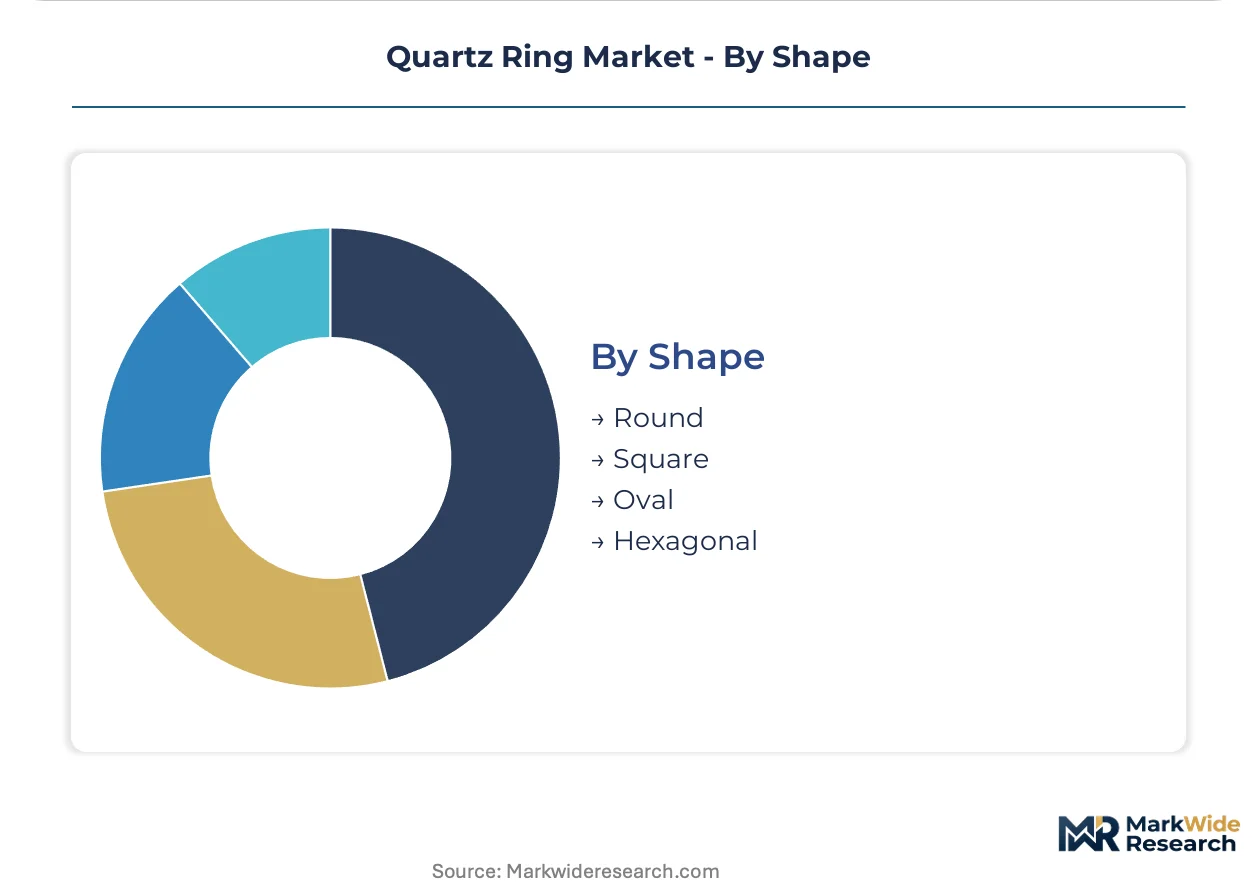
- Round:Concentric turning operations achieve tight radial tolerances for semiconductor focus rings where plasma uniformity depends on symmetric edge profiles. Round geometries constitute the baseline specification across etch and deposition tool platforms.
- Square:Chamfered corners accommodate rectangular wafer handling systems in photovoltaic silicon pulling crucibles, where four-sided symmetry simplifies robotic loading sequences.
- Oval:Elongated profiles serve decorative jewelry settings and specialized optical lens mounts requiring asymmetric light path management.
- Hexagonal:Six-sided structures maximize packing density in crystal healing merchandise and industrial heat sink arrays where surface area expansion improves thermal transfer.
Round shape holds tool standardization. Hexagonal is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of semiconductor-grade quartz rings tilt heavily toward East Asian fabrication hubs, while import dependency concentrates in European equipment vendor supply chains. North American deposits feed raw material extraction without matching downstream fabrication capacity. Regional regulatory divergence is fragmenting certification standards and reshaping supplier qualification protocols.
United States
CHIPS Act domestic content mandates are accelerating local quartz ring sourcing for federal subsidy eligibility. EPA emissions standards and OSHA silica exposure limits govern machining operations in Arizona and Texas fab corridors. Spruce Pine, North Carolina anchors high-purity silica extraction, though domestic fabrication capacity lags equipment demand.
China
Jiangsu province processing clusters serve domestic foundry demand for legacy node deposition tools. MIIT is tightening GB/T 32650 purity benchmarks effective 2025, forcing foreign suppliers to establish domestic testing laboratories. Suzhou and Wuxi concentrate fused quartz ring production for 28nm tool platforms.
Germany
REACH Article 33 disclosure mandates are disqualifying unqualified Asian suppliers from EU equipment vendor procurement lists. ECHA enforcement of full material composition transparency is reshaping import qualification. Dresden's silicon Saxony cluster anchors regional demand for plasma etch chamber components.
South Korea
Samsung Foundry and SK Hynix are scaling 2nm pilot lines that triple chamber component consumption rates versus legacy nodes. Equipment lessors including Hitachi Capital are unbundling quartz ring replacement into per-wafer-pass pricing models. Pyeongtaek and Yongin concentrate memory fab demand with outsourced non-core component logistics.
Japan
Tokyo Electron and Lam Research are qualifying hot isostatic pressed components for 5nm logic production lines. METI industrial policies support synthetic quartz crystal growth R&D intensity. Kyushu's Kumamoto region anchors semiconductor material supplier clusters serving regional equipment manufacturers.
Quartz Ring Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material and precision fabrication layers. The vendor base stratifies between consolidated engineered quartz slab producers and fragmented precision machining shops serving semiconductor equipment OEMs. Two strategic archetypes dominate: vertically integrated material-to-finish conglomerates controlling margin capture, and specialized fabricators competing on qualification speed and geometric precision. M&A activity concentrates in engineered quartz raw material sourcing, while capacity expansion targets Southeast Asian greenfield locations outside tariff exposure zones.
Within the premium engineered quartz tier, Cosentino and Cambria occupy positions reflecting divergent geographic anchoring strategies. Cosentino exemplifies European-origin vertical integration archetypes with captive supply chain control over raw material sourcing. Cambria represents North American geographic dominance in distribution channel concentration. Hanwha L&C sits within the East Asian conglomerate tier where R&D intensity in synthetic quartz crystal growth anchors competitive positioning.
| Leading Market Players |
|---|
| Cosentino |
| Caesarstone |
| Hanwha L&C |
| Compac |
| Vicostone |
| Wilsonart |
| LG Hausys |
| Cambria |
| Santa Margherita |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Spruce Pine, North Carolina high-purity silica deposits compresses margin buffers across synthetic quartz ring tiers while amplifying price volatility transmission from electric arc furnace energy costs. This concentration dynamic forces a bifurcation where semiconductor OEMs absorb premium pricing for qualified supply chains while jewelry and industrial buyers face steeper cost pass-through from feedstock bottlenecks.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation rests on REACH Article 33 compliance documentation and sub-ppb metallic impurity thresholds. Cost compression in the standard tier is intensifying because Jiangsu province fabricators are expanding fused quartz capacity for legacy node tools. Memory fabs exhibit lowest price sensitivity due to per-wafer-pass leasing models, while artisan jewelry distributors face acute margin pressure from raw material volatility.
Supply Chain Analysis
US export-control restrictions on semiconductor manufacturing equipment are fragmenting procurement channels and forcing dual-source qualification timelines. Raw material extraction draws from Spruce Pine deposits in the United States, Jiangsu processing clusters in China, and Kyushu synthetic crystal growth facilities in Japan. Feedstock dependencies include semiconductor-grade silica sand, aluminum doping precursors, and electric arc furnace electrodes. Single-source vulnerability concentrates in Unimin and Sibelco control over 70 percent of certified feedstock. Distribution runs through equipment lessors including Hitachi Capital and Tokyo Century converting spot purchasing to managed inventory programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICP-MS metrology talent scarcity constrains batch certification throughput, creating a qualification bottleneck that separates investable suppliers from capacity-constrained fabricators unable to meet ECHA and MIIT disclosure mandates.
For Market Incumbents: Entrench qualification relationships with Lam Research and Applied Materials through 18-24 month validation cycle co-investment, while securing captive supply of Spruce Pine feedstock via long-term offtake agreements with Sibelco or Unimin. Backward integration into hot isostatic pressing capabilities defends margin position against emerging HIP-consolidated component suppliers in Japan. For New Entrants and Emerging Players: Vietnam fabrication greenfields offer the most penetrable geographic entry point as Intel and Amkor qualify local suppliers outside China tariff exposure zones. Target photovoltaic silicon pulling crucibles as a lower-purity-threshold beachhead before advancing to semiconductor chamber components. Pursue direct qualification with memory fabs in Pyeongtaek and Yongin through outsourced non-core component logistics partnerships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors synthetic quartz crystal growth specialists with proven sub-ppb purity capabilities and established ECHA registration files. Long-term viability hinges on qualification speed advantages compressing from five-year to eighteen-month design cycles. Watch for MIIT enforcement of GB/T 32650 purity benchmarks as the inflection signal accelerating import substitution premiums for domestic Chinese testing laboratory investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Silica Feedstock | Sibelo and Unimin offtake agreements secure margin control against Spruce Pine supply constraints. |
| Hot Isostatic Pressing Capacity Expansion | Tokyo Electron qualification of HIP-consolidated components collapses natural quartz premium pricing tiers. |
| Domestic Testing Laboratory Establishment | MIIT GB/T 32650 enforcement forces $2-4 million capital expenditure for X-ray fluorescence certification. |
| Per-Wafer-Pass Leasing Model Adoption | Hitachi Capital and Tokyo Century unbundle consumable procurement from capital equipment finance. |
| Vietnam Greenfield Fabrication Qualification | Intel and Amkor supplier diversification outside China tariff zones creates first-mover positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings from semiconductor equipment OEMs, ECHA REACH registration databases, MIIT industrial policy circulars, and customs trade flow records. Primary interviews engaged plasma etch chamber engineers at foundries, procurement directors at Lam Research and Applied Materials, ICP-MS laboratory managers, and quartz fabrication plant operators in Jiangsu and Kyushu. Bottom-up demand modeling from wafer start projections triangulates against top-down market sizing from equipment shipment data.
Forecast inputs span material grade segmentation, application purity thresholds, finish type surface treatment intensity, and regional regulatory cluster divergence across the projection horizon. The analytical framework models synthetic versus fused versus natural quartz share rotation, electronics versus jewelry versus photovoltaic demand splits, and polished versus frosted finish trajectory shifts. CAGRs derive from equipment capex cycles, node shrinkage replacement frequency acceleration, and REACH enforcement timeline assumptions. Industry-specific inputs include plasma chemistry intensification roadmaps and EUV lithography adjacent component purity ceilings.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed synthetic crystal growth ventures or unexpected ECHA enforcement acceleration would shift outcomes. Semiconductor equipment generation transitions, energy tariff volatility in Germany and China, and ICP-MS operator wage inflation present specific revision risks. Cross-checking against Tokyo Electron and Lam Research supplier qualification announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Japan Jewellery Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
Global Costume Jewelry Market
Jewelry
Imitation Jewelry Market
Jewelry
Jewelry Repair Market
Jewelry
Saudi Arabia Luxury Jewelry Market
Jewelry
Demi-Fine Jewelry Market
Jewelry
Global Body Piercing Jewelry Market
Jewelry
Jewellery Box Market
Jewelry
Mexico Luxury Jewelry Market
Jewelry
China Jewellery Market
Jewelry
Italy Luxury Jewelry Market
Jewelry
Body Jewelry Market
Jewelry
Global Gems and Jewelry Market