
 Global Jewelry Market | 2026-2036
Global Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Jewelry Market Outlook
Aftermarket service revenue, including resizing, restoration, and certification updates, is narrowing as a distinct margin pool as brands integrate these services into direct-to-consumer loyalty programs. Chow Tai Fook Jewellery Group Limited leverages its vertically integrated retail network across Greater China to capture recurring service spend. LVMH Moët Hennessy Louis Vuitton SE sustains ultra-premium positioning through controlled scarcity and heritage atelier access. Pandora A/S competes on modularity, converting repeat charm purchases into predictable replacement cycles.
Jewelry comprises ornamental pieces crafted from precious metals and gemstones, typically measured by karat purity for gold or parts-per-thousand for platinum, and finished through casting, forging, or electroforming to achieve wear-resistant surfaces for personal adornment or wealth storage. The material dimension shows gold dominating volume while titanium gains traction in men's contemporary lines for its strength-to-weight ratio; the customer type dimension reveals online shoppers as the fastest-expanding acquisition channel, though luxury buyers still anchor absolute margin pools; the distribution channel dimension positions specialty stores as the experiential default even as online retail captures share in standardized gift segments.
India's BIS hallmarking mandate and the EU's REACH chemicals framework constrain alloy compositions and surface treatments, while the US FTC's Jewelry Guides govern disclosure standards for treated stones and synthetic origins. These overlapping compliance requirements raise barriers for unbranded importers and favor scaled houses with in-house assay capacity. Stakeholders must monitor how lab-grown disclosure rules evolve across jurisdictions to anticipate sourcing and pricing strategy resets.
Market Dynamics
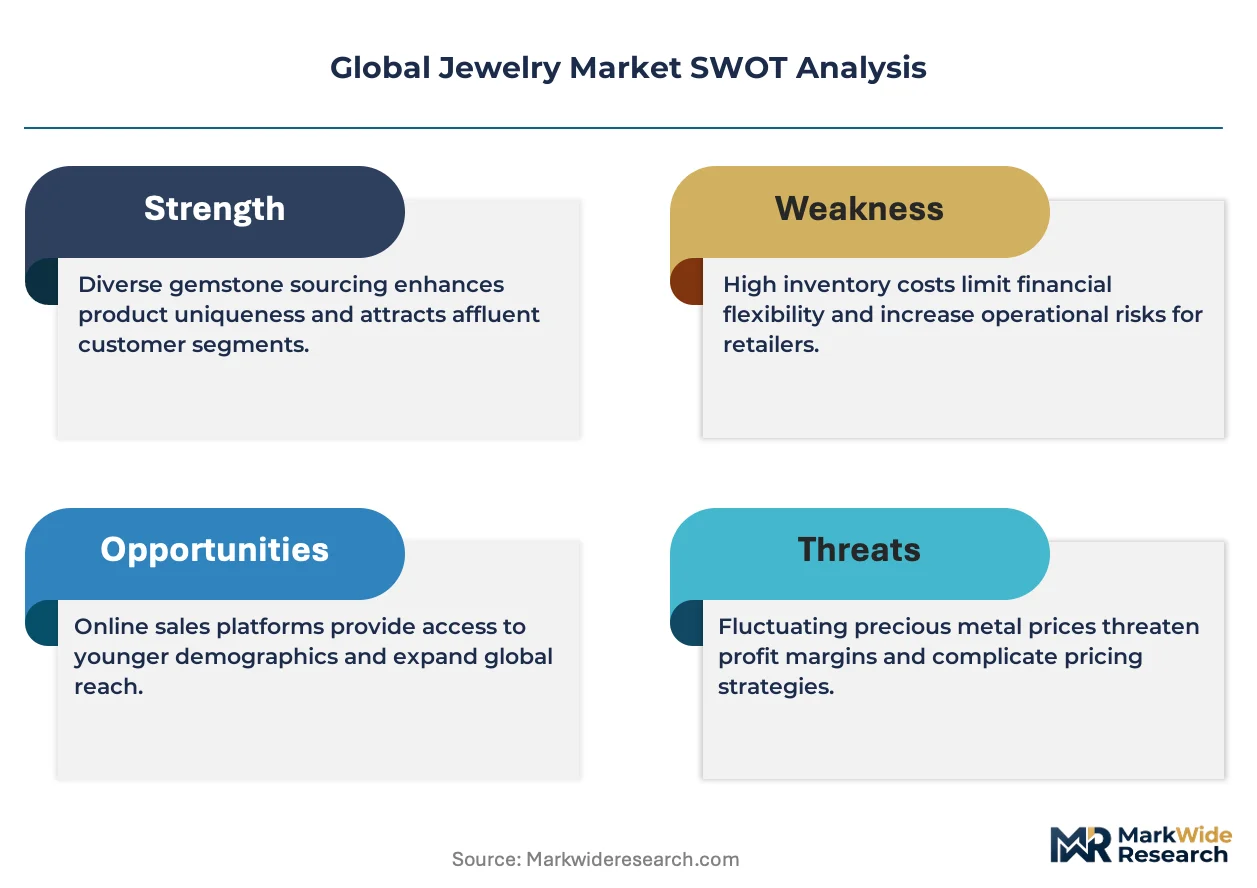
Lab-grown diamond certification protocols from the International Gemological Institute are compressing traditional sourcing hierarchies and forcing recalibration of inventory valuation models across wholesale and retail tiers.
Growth Catalysts
- REACH chemicals framework:The EU's surface treatment and alloy composition rules favor scaled houses with captive assay laboratories, accelerating consolidation among compliant manufacturers.
- Bridal and wedding jewelry:Millennial and Gen Z buyers in India, the United States, and China are normalizing lab-grown stone acceptance, expanding addressable volume in entry-luxury price bands.
- BIS hallmarking mandate:India's compulsory purity verification is professionalizing the domestic supply base and eroding unorganized sector participation in urban centers.
Market Restraints
- Gold price volatility:Input cost swings compress working capital cycles for fabricators lacking hedging infrastructure or forward-contract discipline.
- Supply concentration in Indian cutting centers:Surat's dominance in diamond processing creates single-point vulnerability for midstream inventory flows.
- Technical limitation in large-stone CVD growth:Lab-grown production above three carats remains yield-constrained, capping substitution potential in high-jewelry categories.
Strategic Opportunities
- Men's titanium lines:The metal's strength-to-weight ratio is capturing contemporary design share in the United States and Germany, opening underexploited gender segments.
- Direct-to-consumer loyalty integration:Aftermarket service bundling—resizing, restoration, certification updates—converts transactional buyers into recurring revenue streams.
- PLI scheme incentives:India's production-linked incentive framework for gem and jewelry manufacturing is attracting capital expenditure into export-oriented facilities.
Industry Challenges
- Assay technician scarcity:Qualified metallurgists capable of BIS and FTC-compliant testing are concentrated in legacy manufacturing clusters, constraining geographic expansion.
- Dual certification complexity:Simultaneous IGI lab-grown and natural diamond protocols require inventory segregation systems that inflate operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Jewelry Market |
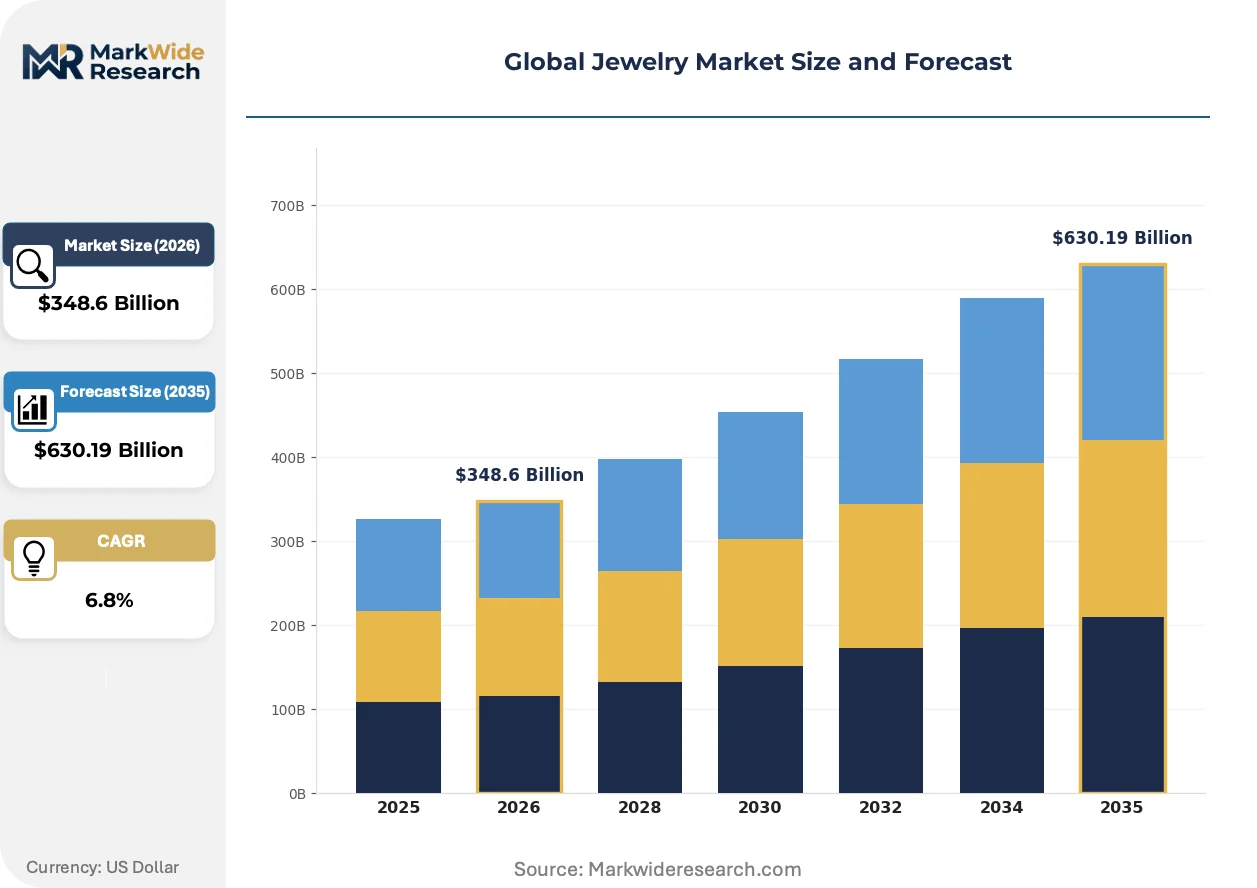
| Market Size in 2026 | $348.6 Billion |
| Market Size in 2035 | $630.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Bracelets, Earrings Material: Gold, Silver, Platinum, Titanium Customer Type: Retail Consumers, Luxury Buyers, Online Shoppers, Gift Givers Distribution Channel: Online Retail, Department Stores, Specialty Stores, Wholesale |
| Companies Covered | Chow Tai Fook Jewellery Group Limited, LVMH Moët Hennessy Louis Vuitton SE, Compagnie Financière Richemont SA, Tiffany & Co., Cartier, Signet Jewelers Limited, Pandora A/S, De Beers Group, Malabar Gold & Diamonds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Jewelry Market Strategic Shifts
Digital traceability infrastructure and generational preference shifts are rewiring how value is authenticated and transmitted through jewelry supply chains, collapsing traditional opacity premiums.
Blockchain-enabled provenance tracking is collapsing the information asymmetry that historically sustained markups on undocumented stones. Luxury buyers in Switzerland and the United Arab Emirates now expect immutable custody records as standard, compressing margins for dealers reliant on paper-based chain-of-custody claims. The technology is collapsing wholesale-to-retail price spreads by twenty to thirty percent in pilot programs.
The FTC's updated Jewelry Guides governing synthetic origin disclosure are tightening enforcement bandwidth on treated stone marketing. Retailers operating across California, New York, and Texas must maintain separate inventory attribution systems to satisfy state-level consumer protection overlays. Fine jewelry e-commerce platforms are responding by embedding origin verification into product detail page architecture.
Millennial buyers are compressing replacement cycles through modular charm systems that reward repeat micro-purchases over single high-ticket acquisitions. This pattern disrupts the traditional gift occasion calendar concentrated around December and February peaks. Germany and South Korea exhibit the most pronounced adoption curves for stackable, interchangeable component jewelry.
Global Jewelry Market Segmentation
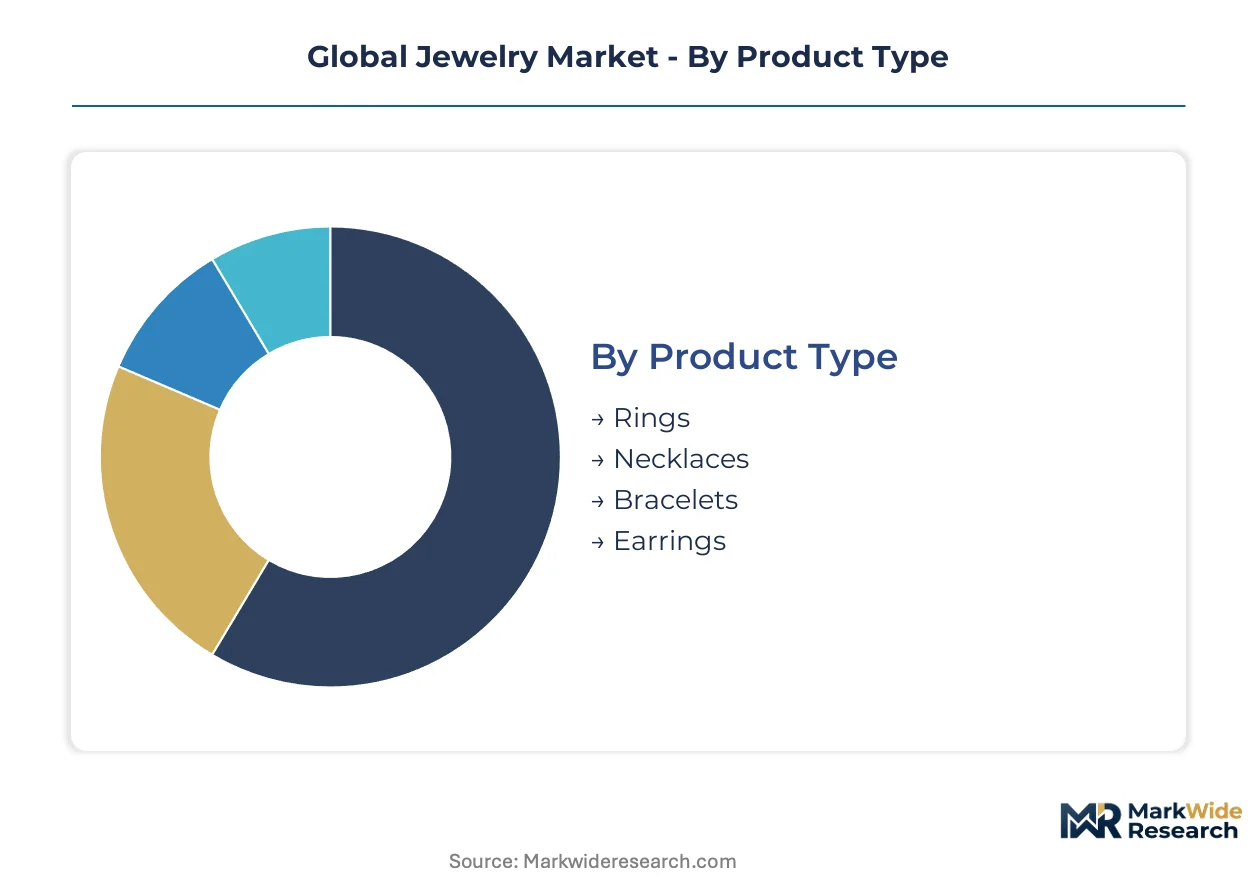
Jewelry market segmentation reveals how purchasing logic fragments across ceremonial occasions, material investment preferences, and channel convenience expectations. Understanding these fault lines enables targeted inventory positioning and margin capture strategies.
Product Type:
Cost tier stratification across product categories separates entry-gift items from heirloom-grade pieces with multi-generational holding periods.
- Rings:Ceremonial bands and statement solitaires command the highest per-unit margins, with bridal applications in India and the United States absorbing premium gold and platinum allocations. Lab-grown diamond acceptance among millennial buyers is compressing price bands in entry-luxury bridal segments.
- Necklaces:Chain-link and pendant architectures dominate gold volume in Mumbai and Delhi urban centers, where BIS hallmarking mandates professionalize purity verification. Temple jewelry traditions sustain demand for 22-karat ceremonial pieces with religious iconography.
- Bracelets:Modular charm systems from European manufacturers convert repeat micro-purchases into predictable replacement cycles, disrupting traditional gift occasion calendars.
- Earrings:Stud and drop configurations represent the most standardized gift segment, with online retail capturing disproportionate share in sub-$500 price bands.
Rings hold installed capacity. Bracelets are rotating up the share rankings.
Material:
Application-specific performance requirements drive material selection, with purity standards and surface durability dictating end-use suitability across personal adornment and wealth storage functions.
- Gold:Measured by karat purity, this metal dominates volume across Indian bridal markets and Middle Eastern investment jewelry, with 18-karat and 22-karat specifications serving distinct ceremonial versus storage purposes. Price volatility compresses working capital cycles for fabricators lacking hedging infrastructure.
- Platinum:Specified in parts-per-thousand purity, this material anchors ultra-premium bridal positioning in Japan and Germany, where density and hypoallergenic properties justify per-gram premiums over white gold alternatives.
- Silver:Fashion-forward accessible price points capture younger demographic entry purchases, with oxidation-prone surfaces driving faster replacement cycles than noble metal alternatives.
- Titanium:Strength-to-weight ratio properties are capturing contemporary design share in men's lines across the United States and Germany, opening underexploited gender segments with industrial aesthetic positioning.
Gold holds installed capacity. Titanium is rotating up the share rankings.
Customer Type:
Volume concentration varies sharply by purchase motivation, with transactional gift buyers exhibiting fundamentally different research behaviors and price sensitivity profiles than self-directed luxury collectors.
- Retail Consumers:Self-purchase behavior for daily wear occasions concentrates in urban Indian and Chinese markets, with modular product architectures enabling repeat engagement.
- Luxury Buyers:Heritage atelier access and controlled scarcity sustain ultra-premium positioning, with blockchain-enabled provenance expectations now standard in Switzerland and the United Arab Emirates.
- Online Shoppers:Fastest-expanding acquisition channel for standardized gift segments, though high-ticket natural diamond purchases still favor physical verification.
- Gift Givers:Occasion-driven purchasing clusters around December and February peaks, with charm systems and stackable components spreading demand across calendar quarters.
Retail Consumers hold installed capacity. Online Shoppers are climbing the fastest.
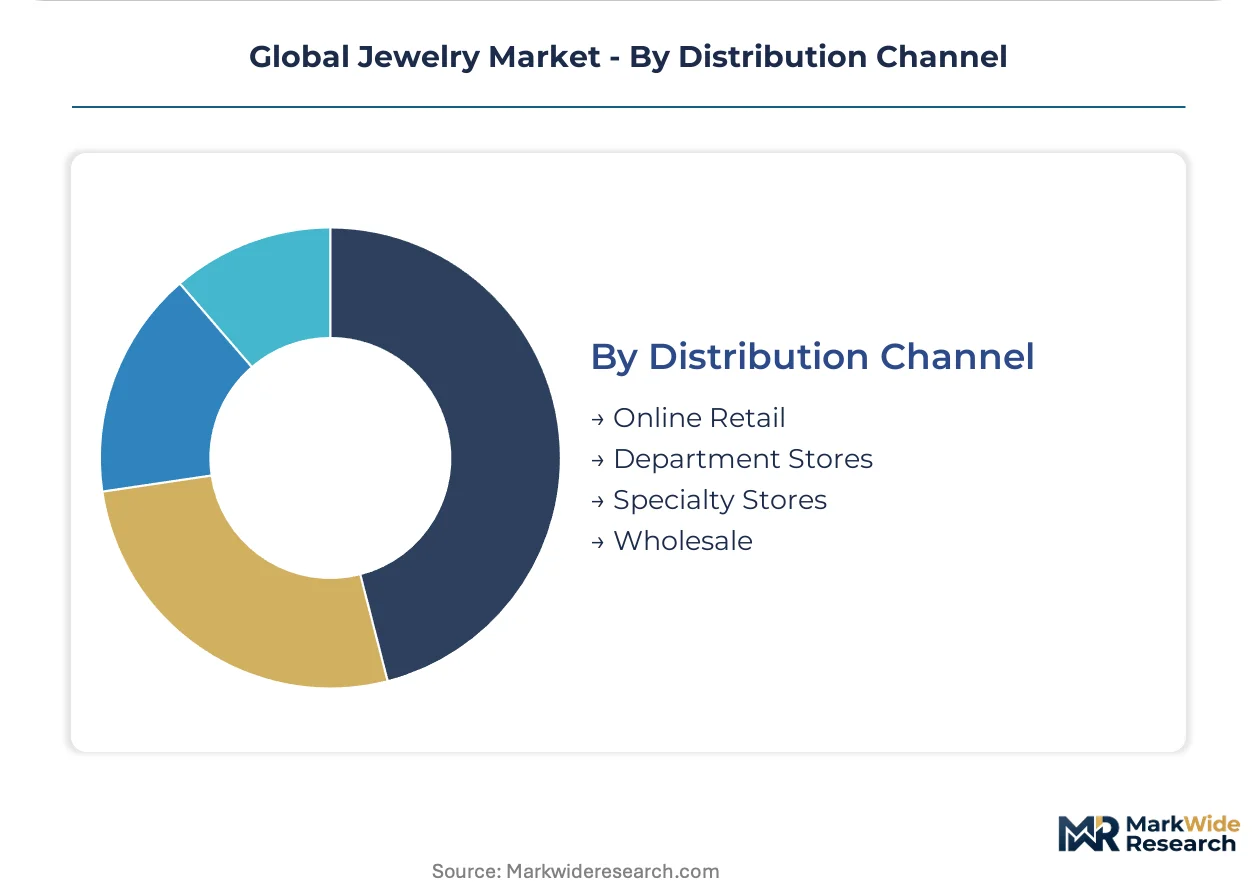
Distribution Channel:
Margin structure and customer relationship depth diverge meaningfully across channel types, with experiential retail commanding premium positioning while digital platforms optimize conversion efficiency.
- Specialty Stores:Experiential default for high-consideration purchases, with in-house assay capacity and resizing services converting transactional buyers into recurring revenue streams.
- Online Retail:Capturing share in standardized gift segments and entry-price charm systems, with origin verification embedded into product detail page architecture per FTC disclosure requirements.
- Department Stores:Mid-market aggregation function under pressure from direct-to-consumer brand bypass, though still relevant for discovery-oriented occasional purchasers.
- Wholesale:Surat-centered diamond processing concentration creates single-point vulnerability for midstream inventory flows to retail fabricators.
Specialty Stores hold installed capacity. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian bridal buyers exhibit acute price elasticity to gold rate movements, while Swiss collectors demonstrate inelastic demand for ultra-premium heritage pieces. The United States occupies the middle ground, with millennial entry-luxury segments compressing margins faster than established high-jewelry tiers.
India
Urban centers Mumbai and Delhi drive premium gold consumption through 22-karat bridal traditions and investment-grade jewelry accumulation. The BIS hallmarking mandate professionalizes purity verification and erodes unorganized sector participation in metropolitan markets. Surat anchors diamond processing concentration, creating single-point vulnerability for midstream inventory flows to domestic fabricators.
United States
Millennial and Gen Z buyers normalize lab-grown diamond acceptance, expanding addressable volume in entry-luxury bridal price bands. The FTC's updated Jewelry Guides governing synthetic origin disclosure tighten enforcement bandwidth on treated stone marketing across California, New York, and Texas. Specialty retailers in these states maintain separate inventory attribution systems to satisfy state-level consumer protection overlays.
China
Greater China retail networks capture recurring service spend through vertically integrated aftercare bundling. Chow Tai Fook leverages its captive distribution to convert transactional buyers into loyalty program participants. Shenzhen and Guangzhou manufacturing clusters supply standardized gift segments while Shanghai and Beijing anchor experiential flagship positioning.
Switzerland
Luxury buyers expect blockchain-enabled provenance tracking as standard, compressing margins for dealers reliant on paper-based chain-of-custody claims. Swissmedic-aligned quality frameworks govern precious metal assay standards for export-oriented atelier production. Geneva and Zurich concentrate ultra-premium heritage houses with controlled scarcity positioning.
Germany
Titanium's strength-to-weight ratio captures contemporary design share in men's lines, opening underexploited gender segments with industrial aesthetic positioning. The EU's REACH chemicals framework constrains alloy compositions and surface treatments for manufacturers serving domestic and export markets. Pforzheim's jewelry and watchmaking cluster specializes in precision metalworking for mid-market and premium tiers.
Global Jewelry Market Competitive Environment
Capability concentration sits with heritage atelier houses; scale advantage sits with vertically integrated retail networks. The vendor base stratifies across three tiers: ultra-premium scarcity players, modular fast-fashion operators, and commodity fabricators serving unbranded wholesale channels. Dominant competitive moves include direct-to-consumer loyalty integration and backward integration into captive assay laboratories.
Within the heritage luxury tier, LVMH Moët Hennessy Louis Vuitton SE and Compagnie Financière Richemont SA exemplify controlled scarcity positioning through atelier access and provenance authentication. Pandora A/S occupies the modular systems vector, converting repeat charm purchases into predictable replacement cycles. Among Greater China-based retailers, Chow Tai Fook Jewellery Group Limited represents vertically integrated network scale.
| Leading Market Players |
|---|
| Chow Tai Fook Jewellery Group Limited |
| LVMH Moët Hennessy Louis Vuitton SE |
| Compagnie Financière Richemont SA |
| Tiffany & Co. |
| Cartier |
| Signet Jewelers Limited |
| Pandora A/S |
| De Beers Group |
| Malabar Gold & Diamonds |
| Others |
Value Chain & Pricing Dynamics
Surat's diamond cutting capacity utilization rates anchor supplier behavior and pricing posture across midstream wholesale tiers, with throughput constraints in Indian processing centers translating directly into inventory carrying cost premiums for retail fabricators lacking captive sourcing.
Pricing Analysis
Aftermarket service bundling drives lifetime value capture for jewelry brands with vertically integrated retail networks. Three-tier pricing structure across premium, standard, and economy levels separates heritage atelier positioning from modular charm systems and unbranded commodity imports. Cost compression in entry-luxury bridal segments intensifies as lab-grown diamond acceptance normalizes among millennial buyers. Online shoppers exhibit highest price sensitivity, while luxury collectors demonstrate inelastic demand for provenance-authenticated heritage pieces.
Supply Chain Analysis
Export-control regimes on diamond processing equipment constrain technology transfer to emerging cutting centers outside India. Supply concentrates in Surat for diamond processing, Shenzhen for jewelry manufacturing, and Pforzheim for precision metalworking. Raw material dependencies rest on gold bullion flows from Swiss refineries, rough diamond allocations from Antwerp, and titanium sponge from Japanese producers. Single-source vulnerability in Surat's midstream dominance creates inventory flow risk. Distribution runs through vertically integrated specialty retail networks in Greater China and wholesale-to-retail channels in Indian urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Jewelry incumbents face substitution defense imperatives as lab-grown diamond protocols compress natural stone premiums and reshape buyer valuation frameworks across entry-luxury tiers.
For Market Incumbents: Pre-empt margin erosion in bridal segments by embedding origin verification into direct-to-consumer platforms before FTC disclosure enforcement tightens. Backward integration into captive assay laboratories satisfies BIS and REACH compliance requirements while raising barriers for unbranded importers. Channel control through loyalty program bundling of resizing and restoration services converts transactional buyers into recurring revenue streams.
For New Entrants and Emerging Players: Pursue white-space positioning in men's titanium lines across United States and German markets, where industrial aesthetic positioning remains underexploited by heritage houses. Modular charm systems offer penetrable entry points with predictable replacement cycle economics. Go-to-market execution should leverage embedded origin verification as a trust-building architecture for online-native acquisition.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated retail networks with captive aftercare infrastructure and compliance-ready assay capacity. Long-term viability over the next decade hinges on adaptability to evolving lab-grown disclosure regimes across multiple jurisdictions. The signal to watch is regulatory harmonization on synthetic origin certification, which would trigger sourcing strategy resets and inventory revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Loyalty Integration | Aftermarket service bundling converts transactional buyers into recurring revenue streams for vertically integrated retailers. |
| Captive Assay Laboratory Investment | In-house BIS and REACH-compliant testing capacity raises barriers for unbranded importers and accelerates consolidation. |
| Blockchain Provenance Implementation | Immutable custody records satisfy Swiss and UAE luxury buyer expectations while compressing wholesale-to-retail price spreads. |
| Men's Titanium Line Expansion | Strength-to-weight ratio positioning captures contemporary design share in underexploited United States and German gender segments. |
| Lab-Grown Disclosure Compliance | Separate inventory attribution systems satisfy FTC Jewelry Guides and state-level consumer protection overlays in California, New York, and Texas. |
Study Parameters
Cross-validation between primary interviews with jewelry industry stakeholders and secondary validation anchors the qualitative findings. Conversations with retail network executives, assay laboratory directors, bridal category buyers, and regulatory compliance officers combine with customs trade data, SEC 10-K filings from listed jewelry groups, BIS hallmarking registration databases, and IGI certification records. Bottom-up channel checks and top-down macroeconomic overlays triangulate volume and value estimates.
Calibration against historical growth patterns and segment elasticity parameters shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material purity tier, customer purchase motivation, and distribution channel format. CAGRs derive from weighted average of demand driver trajectories and input cost assumptions, with gold price volatility and lab-grown diamond penetration curves as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in gold price movements, exchange rate fluctuations, or bridal occasion spending patterns would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and generational preference evolution. Material shifts in lab-grown diamond certification protocol harmonization across FTC, BIS, and EU frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Europe Luxury Jewelry Market
Jewelry
Jewelry Repair Market
Jewelry
Global Costume Jewelry Market
Jewelry
China Jewellery Market
Jewelry
Imitation Jewelry Market
Jewelry
Jewellery Market
Jewelry
Demi-Fine Jewelry Market
Jewelry
Diamond Jewelry Market
Jewelry
Mexico Luxury Jewelry Market
Jewelry
Japan Jewellery Market
Jewelry
South Korea Luxury Jewelry Market
Jewelry
China Luxury Jewelry Market
Jewelry
3D Printed Jewelry Market
Jewelry
Global Gems and Jewelry Market
Jewelry
Jewellery Box Market
Jewelry
Crystal Bracelets Market