
 Global Costume Jewelry Market | 2026-2036
Global Costume Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Costume Jewelry Market Analysis
Market Context
Aftermarket repair and customization revenue is narrowing as brands push replacement cycles over longevity. LVMH Moët Hennessy Louis Vuitton leverages its luxury fashion ecosystem to command premium positioning in designer costume collections. Claire's Stores Inc. dominates mall-based impulse purchases through tight vertical control over tween and teen demographics. BaubleBar Inc. specializes in trend-responsive drops that compress design-to-shelf timelines below traditional seasonal calendars.
Technical Definition and Segment Structure
Costume jewelry denotes non-precious ornamental accessories fabricated from base metals, synthetic resins, glass, wood, or plated alloys, typically employing rhodium, gold-tone, or enamel surface treatments to simulate fine jewelry aesthetics at accessible price points. Earrings and necklaces anchor volume production due to their visibility in social media-driven styling, while rings capture margin expansion through stackable and customizable formats. Plastic and metal materials split the mass-market supply base, with metal-plated pieces commanding higher unit economics in specialty store channels. Online distribution is displacing department store placement as algorithmic discovery and influencer seeding redirect consumer search behavior toward direct purchase pathways.
Regulatory Environment and Outlook
REACH in Europe and California Proposition 65 in the United States enforce strict cadmium, lead, and nickel migration limits that determine market access for imported costume jewelry lots. China's GB standards and India's BIS hallmarking extensions into non-precious categories are tightening conformity assessment burdens for cross-border suppliers. Stakeholders must monitor evolving chemical restriction schedules and certification reciprocity agreements to preempt customs detention and retailer compliance blacklists.
Market Dynamics
Social commerce algorithms and influencer-driven discovery are compressing design-to-purchase cycles while fragmenting brand loyalty across micro-trend cycles.
Growth Catalysts
- REACH nickel migration limits:European ECHA enforcement is accelerating supplier migration to hypoallergenic alloys, creating premium positioning for compliant manufacturers.
- India bridal consumption clusters:Festival and wedding calendar density sustains high-volume demand for plated sets and imitation temple jewelry.
- Direct-to-consumer platform infrastructure:Shopify and TikTok Shop integration is lowering customer acquisition costs for trend-responsive drops.
Market Restraints
- Base metal price volatility:Copper and zinc input swings compress margin buffers for plated alloy producers.
- Guangdong supply concentration:Dongguan and Yiwu clusters concentrate 60% of global costume jewelry fabrication, creating single-point vulnerability.
- California Proposition 65 cadmium thresholds:Strict surface coating migration limits trigger retailer compliance blacklists and lot rejections.
Strategic Opportunities
- Brazil urban middle-class expansion:São Paulo and Rio de Janeiro present underpenetrated demand for accessible fashion jewelry.
- AI-assisted generative design:Midjourney and proprietary tools are compressing concept-to-sample timelines from weeks to days.
- Livestream commerce infrastructure:Shopee and Lazada streaming integrations enable real-time inventory liquidation with lower returns.
Industry Challenges
- CAD-to-CAM translation skills:Shortage of technicians bridging digital design files to CNC mold production creates bottlenecks.
- Multi-jurisdiction certification stacking:Simultaneous REACH, Prop 65, and BIS compliance documentation extends go-to-market timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Costume Jewelry Market |
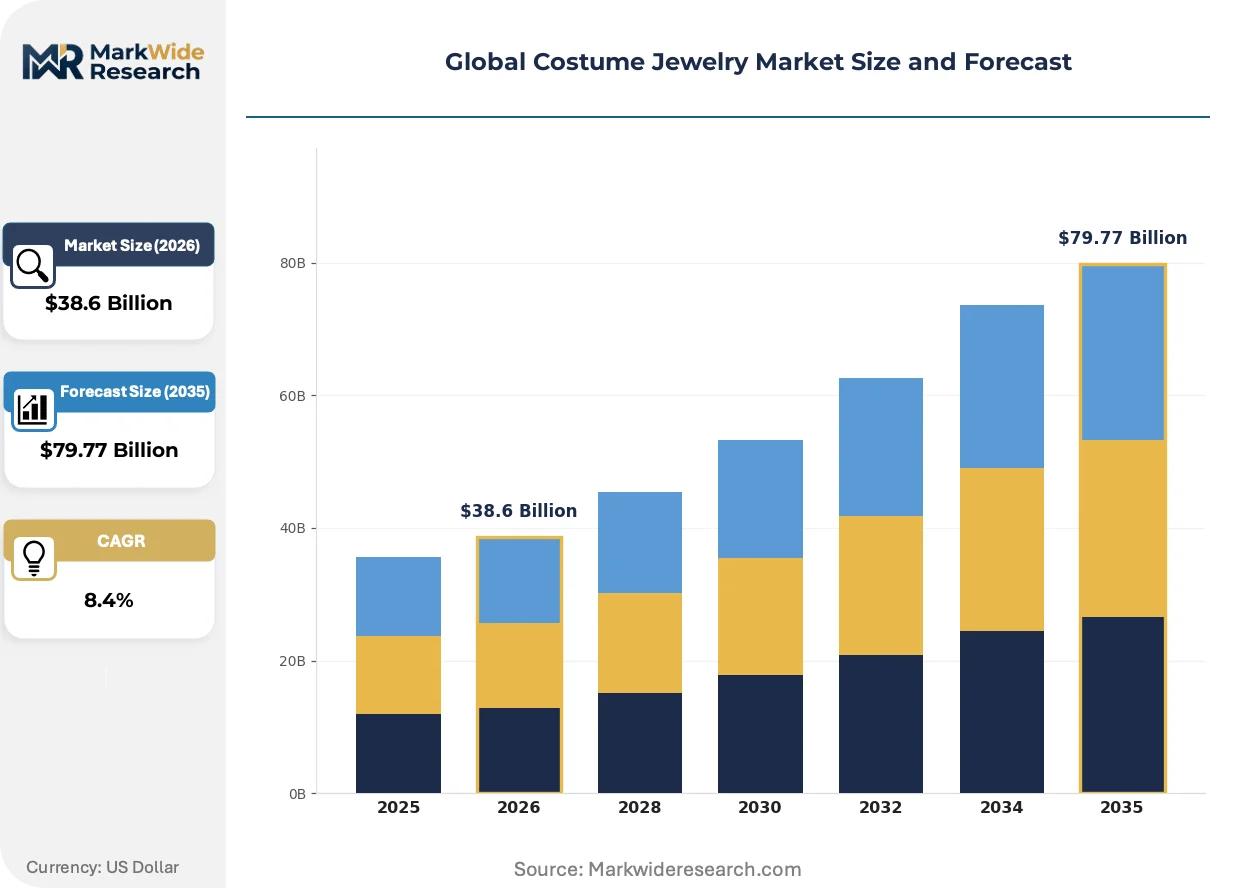
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Necklaces, Bracelets, Earrings, Rings Material: Plastic, Metal, Glass, Wood Distribution Channel: Online, Specialty Stores, Department Stores, Craft Fairs Customer Type: Women, Men, Children, Fashion Enthusiasts |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton, BaubleBar Inc., Avon Products Inc., Randa Accessories, Buckley London, Claire’s Stores Inc., Stuller Inc., DCK Group, Swank Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Costume Jewelry Market Emerging Trajectories
Digital fabrication and material science advances are collapsing traditional barriers between mass production and customization while regulatory chemistry restrictions are forcing alloy reformulation across the supply base.
Bioresin and cellulose acetate compounds are hybridizing with traditional petroleum-based plastics to reduce petroleum dependency in statement pieces. Gen Z-oriented direct brands are adopting these materials at accelerated pace to meet sustainability messaging requirements. This hybridizing approach is enabling price positioning above conventional acrylic while maintaining accessible unit economics.
ECHA REACH Annex XVII nickel release restrictions are tightening enforcement across EU member state market surveillance authorities. Manufacturers must now submit third-party migration test reports for every alloy batch to avoid customs detention. Earrings and body-piercing jewelry face the strictest thresholds, forcing suppliers toward surgical steel and titanium alternatives.
Algorithmic personalization engines are replacing editorial curation in discovery pathways. Instagram and TikTok recommendation systems now surface micro-trend jewelry to users before traditional seasonal retail cycles. This behavioral shift is most visible in US and UK markets where influencer seeding budgets now exceed wholesale trade show participation.
Global Costume Jewelry Market Segmentation
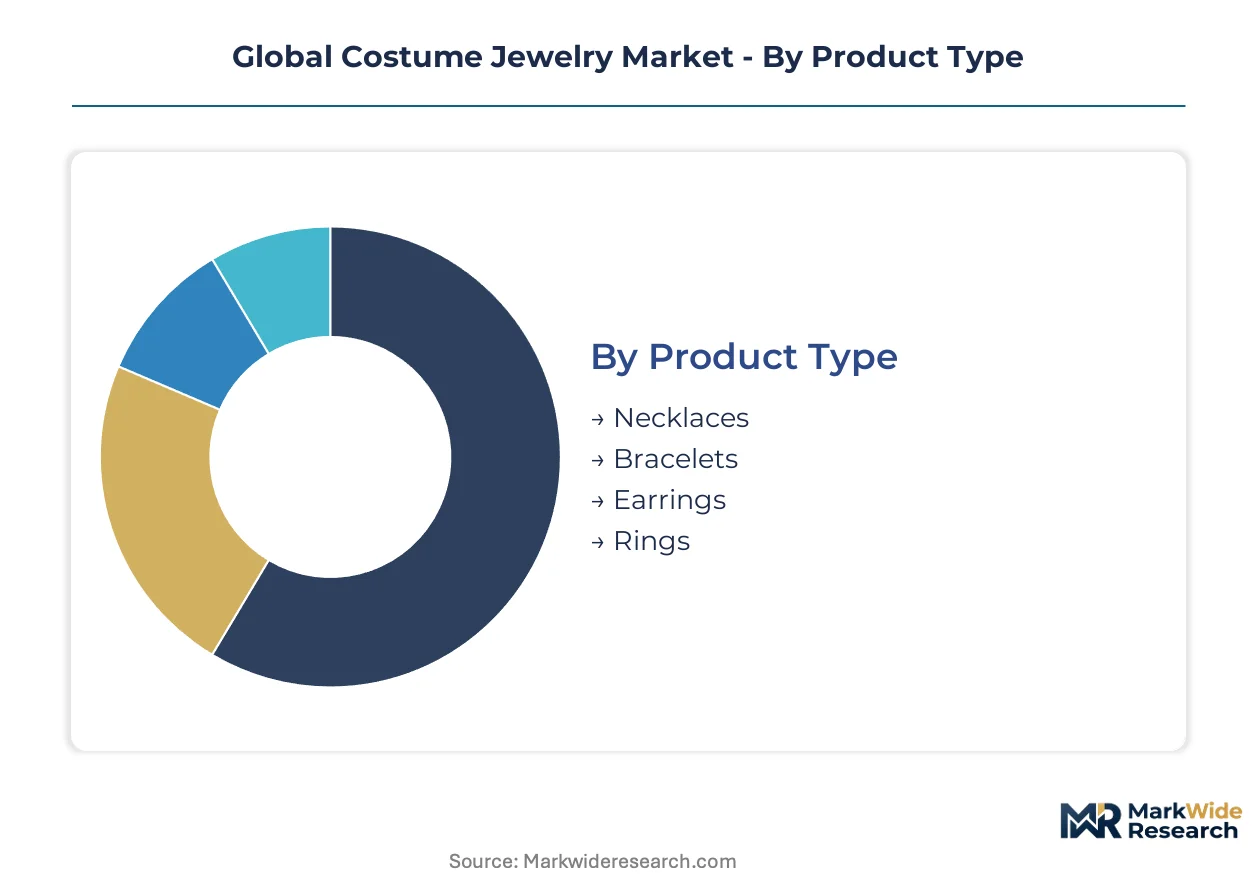
Costume jewelry segmentation reveals divergent service intensity across product categories, with repair frequency and customization attach rates varying dramatically by wear location and material fragility. Understanding these patterns enables manufacturers to allocate warranty reserves and aftermarket support infrastructure efficiently.
Product Type:
After-sales service intensity peaks with items subjected to repeated mechanical stress and skin contact, creating divergent margin profiles across wear locations.
- Necklaces:Chain-link and pendant constructions face clasp fatigue and plating wear at friction points, driving higher return rates for quality defects. Bridal and festival consumption clusters in India sustain volume demand for layered temple-style sets with intensive post-purchase adjustment needs.
- Earrings:Post and hook mechanisms concentrate nickel migration exposure, triggering strict ECHA REACH Annex XVII compliance documentation for every alloy batch. Social media visibility accelerates purchase frequency among fashion-forward millennials and Gen Z consumers in direct-to-consumer channels.
- Bracelets:Hinged and elasticated designs experience stress fractures from daily wear patterns.
- Rings:Stackable formats enable customization attach rates above other categories.
Necklaces hold the largest share; momentum sits with earrings.
Material:
Cost tier stratification separates petroleum-dependent synthetics from metal-plated alloys with divergent regulatory compliance burdens and unit economics.
- Metal:Rhodium, gold-tone, and enamel surface treatments over base copper and zinc alloys command premium positioning in specialty store channels. ECHA enforcement of nickel-free and lead-free standards elevates testing costs while creating differentiation for compliant surgical steel and titanium alternatives.
- Plastic:Petroleum-based acrylics and emerging bioresin compounds hybridize to reduce dependency on fossil feedstocks. Gen Z-oriented direct brands adopt cellulose acetate at accelerated pace to meet sustainability messaging requirements while maintaining accessible price points.
- Glass:Bead and crystal elements concentrate artisan production in Czech and Indian clusters.
- Wood:Lightweight statement pieces serve niche eco-positioning segments with limited scale.
Metal captures the highest margin tier; bioresin hybrids are gaining share fastest.
Distribution Channel:
Customer acquisition cost structures favor algorithmic discovery over physical footprint maintenance, compressing traditional retail economics.
- Online:Shopify and TikTok Shop integration collapses design-to-purchase cycles below seasonal calendars. Influencer seeding budgets now exceed wholesale trade show participation in US and UK markets as Instagram and TikTok recommendation systems surface micro-trends before traditional retail cycles.
- Specialty Stores:Tight vertical control over tween and teen demographics sustains mall-based impulse purchase velocity through curated trend responsiveness.
- Department Stores:Placement displacement accelerates as search behavior redirects toward direct purchase pathways.
- Craft Fairs:Artisan producers leverage localized production narratives for premium positioning.
Online holds the largest share; specialty stores retain the steepest expansion trajectory in experiential retail formats.
Customer Type:
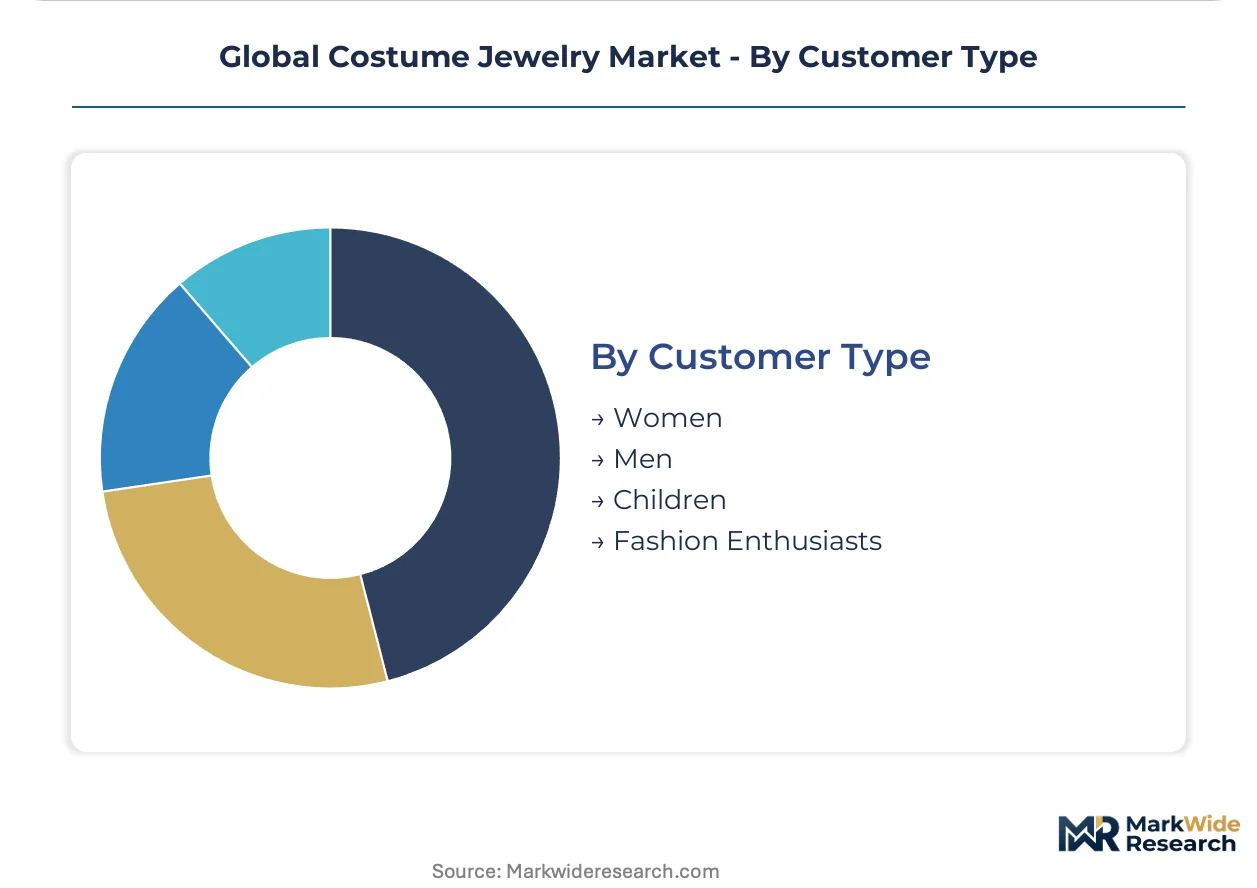
Volume concentration and margin expansion potential split across demographic segments with divergent occasion-based purchase patterns.
- Women:Festival and wedding calendar density in India sustains high-volume consumption of plated sets and imitation temple jewelry across all adult age cohorts. Bridal occasion clustering creates predictable demand spikes requiring flexible production scheduling.
- Fashion Enthusiasts:Trend-responsive drops with compressed design-to-shelf timelines capture margin expansion through stackable and customizable formats. Algorithmic personalization engines replace editorial curation for this segment in discovery pathways.
- Children:Safety compliance burdens restrict material choices to certified hypoallergenic alloys.
- Men:Underpenetrated category with emerging demand for minimalist metal and leather-accented designs.
Women hold the largest share; fashion enthusiasts are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian buyers exhibit the highest price elasticity, accepting plated alloys for festival consumption, while French and Italian consumers pay premiums for designer positioning. Chinese manufacturing clusters serve both extremes through tiered output segmentation.
India
Festival and wedding calendar density sustains high-volume demand for plated temple jewelry sets across Maharashtra and Gujarat. BIS hallmarking extensions into non-precious categories tighten conformity assessment for cross-border suppliers. Surat and Mumbai clusters dominate fabrication of imitation bridal collections with compressed design-to-delivery timelines.
United States
Algorithmic discovery on TikTok Shop and Instagram accelerates purchase frequency among Gen Z consumers. California Proposition 65 cadmium thresholds trigger retailer compliance blacklists for non-conforming imports. Los Angeles-based direct brands leverage influencer seeding budgets that now exceed wholesale trade show participation.
China
Dongguan and Yiwu clusters concentrate sixty percent of global costume jewelry fabrication, creating single-point supply vulnerability. GB standards on surface coating migration limits align with export market requirements. Guangdong province maintains vertical control over mold-making through CNC production corridors serving European and American buyers.
France
Luxury fashion ecosystem integration commands premium positioning for designer costume collections in Paris and Lyon. ECHA REACH Annex XVII nickel release restrictions force surgical steel alternatives for earring posts. Île-de-France houses the headquarters of conglomerates leveraging multi-brand portfolios across price tiers.
Brazil
São Paulo and Rio de Janeiro present underpenetrated demand for accessible fashion jewelry among expanding urban middle-class cohorts. ANVISA cosmetic-adjacent regulations influence material safety expectations for skin-contact accessories. Southeast regional distributors are building direct-to-consumer platform infrastructure to bypass traditional import markups.
Global Costume Jewelry Market Vendor Landscape
Capability concentration sits with luxury fashion conglomerates; scale advantage sits with vertically integrated mass-market specialists. The vendor base stratifies across three tiers: heritage luxury houses with ecosystem leverage, trend-responsive direct brands with compressed design cycles, and commodity fabricators serving private-label retailers. Dominant competitive moves include backward integration into captive alloy production and algorithmic personalization engine deployment.
Within the luxury-tier vector, LVMH Moët Hennessy Louis Vuitton exemplifies ecosystem-driven premium positioning through multi-brand portfolio architecture. Claire's Stores Inc. occupies a position in mall-based impulse purchase channels through tight demographic control over tween and teen segments. BaubleBar Inc. represents the trend-responsive archetype with compressed design-to-shelf timelines below traditional seasonal calendars.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton |
| BaubleBar Inc. |
| Avon Products Inc. |
| Randa Accessories |
| Buckley London |
| Claire's Stores Inc. |
| Stuller Inc. |
| DCK Group |
| Swank Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Dongguan mold-making corridors is elevating alloy batch premiums while compressing margin buffers for plated jewelry producers serving European REACH compliance tiers.
Pricing Analysis
After-sales repair and customization revenue drives lifetime value concentration in necklace and bracelet categories where clasp fatigue and plating wear trigger repeat service encounters. Three-tier pricing structure across designer, specialty store, and mass-market economy levels separates LVMH ecosystem positioning from Claire's impulse velocity and BaubleBar trend-drop accessibility. Cost compression in base metal inputs is intensifying because copper and zinc price volatility erodes unit economics for Guangdong fabricators. Indian bridal buyers exhibit highest price elasticity for plated temple sets, while French consumers pay premiums for designer costume collections with ECHA-compliant surgical steel alternatives.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for costume jewelry importers navigating Section 301 duty schedules. Dongguan and Yiwu clusters in China, Surat and Mumbai fabrication hubs in India, and emerging São Paulo distribution nodes anchor global production geography. Raw material flows draw from Zambian copper concentrates, Peruvian zinc output, and petroleum-based resin feedstocks from Gulf Coast petrochemical corridors. Single-source vulnerability concentrates in Guangdong CNC mold production where 60 percent of global fabrication rests. Distribution runs through direct-to-consumer platform infrastructure with TikTok Shop and Shopify displacing traditional department store wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from AI-assisted generative design tools that compress concept-to-sample timelines from weeks to days, eroding traditional speed-to-market advantages.
For Market Incumbents: Entrench compliance differentiation by building captive alloy production capacity for REACH-certified nickel-free and lead-free batches. Secure backward integration into surgical steel and titanium alternatives for earring posts facing strictest ECHA Annex XVII thresholds. Channel control through mall-based tween demographic lock-in sustains Claire's impulse velocity against direct-brand algorithmic discovery. For New Entrants and Emerging Players: Build out livestream commerce infrastructure on Shopee and Lazada platforms to capture Brazilian urban middle-class expansion with real-time inventory liquidation models. Target São Paulo and Rio de Janeiro metropolitan corridors where accessible fashion jewelry demand outpaces established import distribution. Sustainability messaging through bioresin and cellulose acetate hybrid materials unlocks Gen Z positioning above conventional acrylic price tiers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-assisted design and direct-to-consumer platform segments as software substitution reduces physical tooling requirements. Acquire trend-responsive direct brands with compressed design-to-shelf capabilities below seasonal calendars rather than legacy wholesale-dependent operators. Watch TikTok Shop and Instagram algorithmic personalization engine deployment rates as signal for channel-shift inflection.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification Investment | ECHA nickel migration enforcement elevates testing costs while creating premium positioning for compliant surgical steel alternatives. |
| Direct-to-Consumer Platform Launch | Shopify and TikTok Shop integration collapses customer acquisition costs for trend-responsive drops below traditional wholesale economics. |
| Bioresin Material Transition | Cellulose acetate hybrid compounds reduce petroleum dependency while enabling sustainability messaging for Gen Z-oriented brands. |
| Livestream Commerce Infrastructure Buildout | Shopee and Lazada streaming integrations enable real-time inventory liquidation with lower return rates in Southeast Asian markets. |
| Backward Integration into Captive Alloy Production | In-house control over nickel-free and lead-free batch certification preempts customs detention and retailer compliance blacklists. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade records, BIS conformity assessment filings, and ECHA restriction proposal databases to validate market sizing. Primary interviews engaged category buyers at specialty retailers, alloy procurement managers at Guangdong fabrication clusters, and regulatory compliance officers navigating REACH and California Proposition 65 thresholds. Secondary sources incorporated SEC 10-K disclosures from listed accessories conglomerates, Indian bridal consumption surveys, and algorithmic commerce platform analytics. Bottom-up triangulation across production cluster output estimates and top-down validation through retail channel revenue reconciliation anchored value projections.
Forecast inputs span product type segmentation across necklaces, earrings, bracelets, and rings; material tiers separating metal-plated alloys from petroleum-based and bioresin plastics; and distribution channel splits between online, specialty store, department store, and craft fair pathways. CAGRs were derived through regression analysis against historical volume trajectories adjusted for regulatory enforcement intensity and social commerce penetration rates. Industry-specific inputs include ECHA Annex XVII nickel release restriction implementation schedules and Indian festival calendar density effects on bridal consumption clustering.
Stress conditions across base metal price volatility, REACH compliance documentation burdens, and TikTok Shop algorithmic discovery penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory reciprocity agreements and certification stacking timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Chalcedony Earrings Market
Jewelry
Brazil Jewelry Market
Jewelry
Latin America Jewelry Market
Jewelry
Global Jewelry Market
Jewelry
South Africa Luxury Jewelry Market
Jewelry
3D Printed Jewelry Market
Jewelry
Germany Luxury Jewelry Market
Jewelry
Italy Luxury Jewelry Market
Jewelry
Saudi Arabia Luxury Jewelry Market
Jewelry
Leather Jewellery Box Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
Mexico Luxury Jewelry Market
Jewelry
Global Gems and Jewelry Market
Jewelry
Bead Products Market
Jewelry
Qatar Jewelry Market
Jewelry
South Korea Luxury Jewelry Market