
 Canada Luxury Jewelry Market | 2026-2036
Canada Luxury Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Luxury Jewelry Market Insights
Asset-light leasing models for prime retail space is tilting competitive dynamics toward digitally native brands that avoid capital-heavy flagship commitments. Mejuri leverages direct-to-consumer data analytics to optimize inventory turns across its showrooms. Maison Birks anchors its position through heritage craftsmanship and controlled distribution via owned boutiques. Spence Diamonds differentiates on custom design consultation, converting in-store experiences into higher-margin bespoke orders.
Canada luxury jewelry comprises high-value ornamental pieces crafted from precious metals and certified gemstones, typically exceeding premium price thresholds and emphasizing provenance, artisanal finishing, and resale value preservation. Platinum settings with Canadian-mined diamonds command particular cachet due to traceability protocols and hardness ratings suited to daily wear. Rings and necklaces dominate current revenue, though men's bracelets represent the fastest-growing product type as gendered purchasing norms erode. Gold and platinum capture the deepest margin pools, while silver competes on entry-luxury accessibility and younger demographic recruitment.
Health Canada enforces lead-content thresholds under the Consumer Product Safety Act, compelling reformulation of base-metal alloys and expanded third-party testing. Competition Bureau guidelines on diamond grading disclosures shape pricing transparency and consumer trust in retail transactions. The Canadian Jewellers Association administers voluntary certification programs that filter market access for independent artisans. Stakeholders must monitor evolving ethical-sourcing mandates and provincial sales-tax harmonization debates that could reshape cross-border e-commerce fulfillment economics.
Market Dynamics
Health Canada's tightened lead-content thresholds under the Consumer Product Safety Act are compelling jewelry brands to reformulate base-metal alloys and absorb expanded third-party testing costs, reshaping competitive economics across the value chain.
Growth Catalysts
- Ethical-sourcing mandates:The Canadian Jewellers Association's voluntary certification programs are filtering market access and elevating consumer trust in provenance-verified pieces.
- Millennial wealth concentration:Affluent millennials in Toronto and Vancouver are accelerating demand for traceable gemstone jewelry with documented artisanal craftsmanship.
- Provincial sales-tax harmonization debates:Potential reforms in Ontario and British Columbia could reshape cross-border e-commerce fulfillment economics for digital-native entrants.
Market Restraints
- Input cost volatility:Platinum and gold price fluctuations compress margin buffers for mid-tier collections dependent on precious metal settings.
- Supply concentration risk:Certified Canadian-mined diamonds flow through a limited number of approved cutters, creating bottleneck exposure for traceability-dependent brands.
- Regulatory friction:Competition Bureau diamond-grading disclosure guidelines add compliance overhead to retail transactions, particularly for independent artisans.
Strategic Opportunities
- Men's jewelry underpenetration:Bracelets and signet rings for male buyers in Vancouver and Calgary represent a white space as gendered purchasing norms erode.
- Asset-light showroom expansion:Short-term leasing models in Toronto's Yorkville and Vancouver's Gastown enable digitally native brands to test physical presence without flagship capital commitments.
- Resale value preservation services:Certified appraisal and buyback programs for platinum settings with Canadian-mined diamonds can lock in customer lifetime value.
Industry Challenges
- Artisanal skill scarcity:Master craftspeople capable of heritage-level finishing are concentrated in aging cohorts, constraining boutique expansion plans.
- Certification timeline compression:Health Canada's expanded third-party testing requirements are extending product-to-market cycles for children's jewelry lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Luxury Jewelry Market |
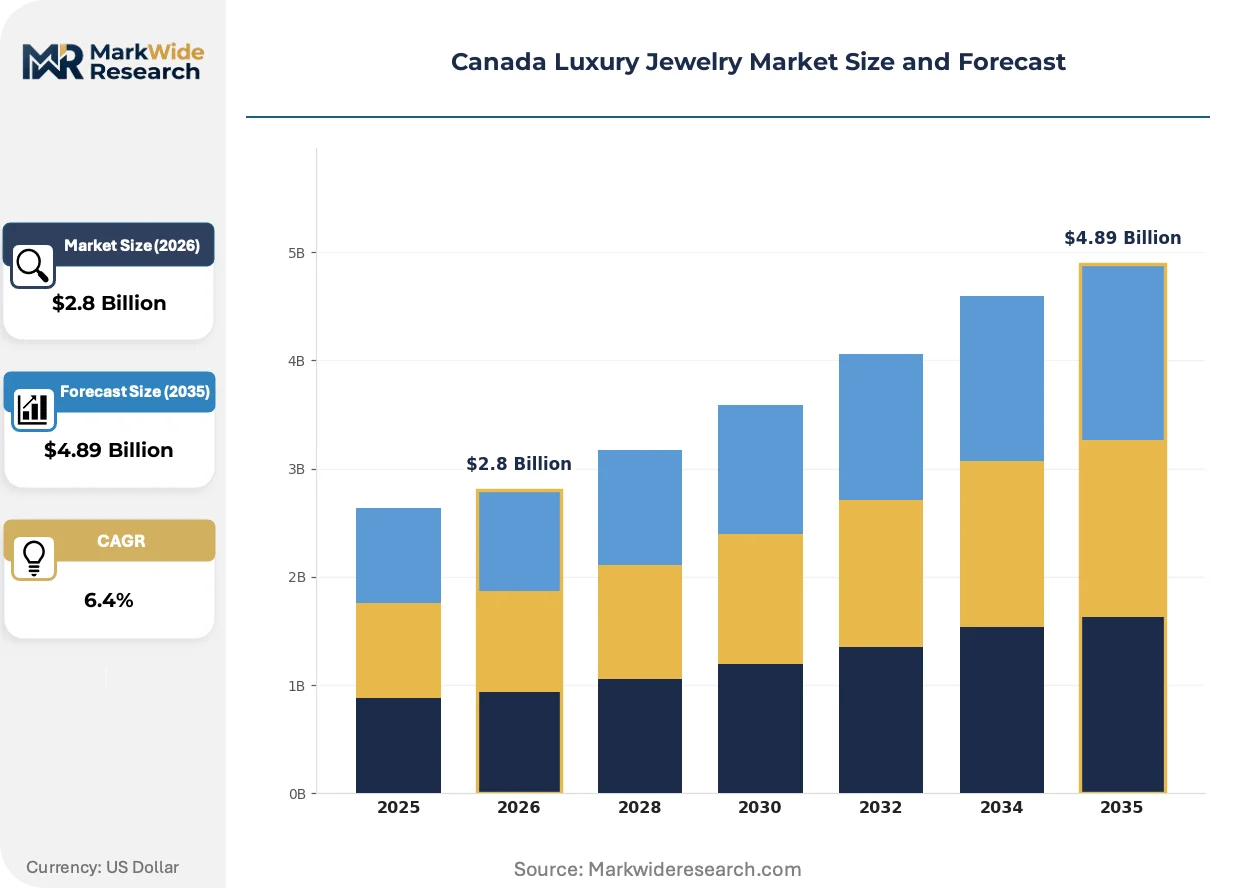
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Bracelets, Earrings Material: Gold, Platinum, Silver, Gemstones End User: Women, Men, Couples, Children Distribution Channel: Online Retail, Boutiques, Department Stores, Auction Houses |
| Companies Covered | Mejuri, Maison Birks, Anne Sportun, Biko, Jenny Bird, Wolf Circus, Spence Diamonds, Paris Jewellers, Sofia Zakia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Luxury Jewelry Market Trends and Innovations
Blockchain-enabled provenance tracking and direct-to-consumer data analytics are compressing traditional retail hierarchies and enabling precision inventory management across showroom networks.
Laser-inscribed diamond certification is migrating from niche security feature to standard expectation among Toronto and Vancouver buyers. Affluent millennials now demand microscopic serial numbers linking stones to Canadian mining origins. This technology is compressing information asymmetry between sellers and buyers, forcing traditional retailers to upgrade disclosure protocols or cede trust to transparent competitors.
Health Canada's Consumer Product Safety Program is enforcing stricter lead-content thresholds on jewelry marketed to children. The industrial consequence is wholesale reformulation of base-metal alloys across entry-luxury collections. Independent artisans in Quebec and Ontario are responding by abandoning costume-jewelry adjacent lines and pivoting toward certified precious-metal-only offerings.
Custom design consultation is displacing transactional retail encounters in high-net-worth districts. Spence Diamonds and comparable operators in Vancouver's Coal Harbour are converting showroom visits into bespoke order pipelines. This pattern is most visible in British Columbia, where controlled distribution through owned boutiques preserves margin pools eroded elsewhere by price-transparent digital channels.
Canada Luxury Jewelry Market Segmentation
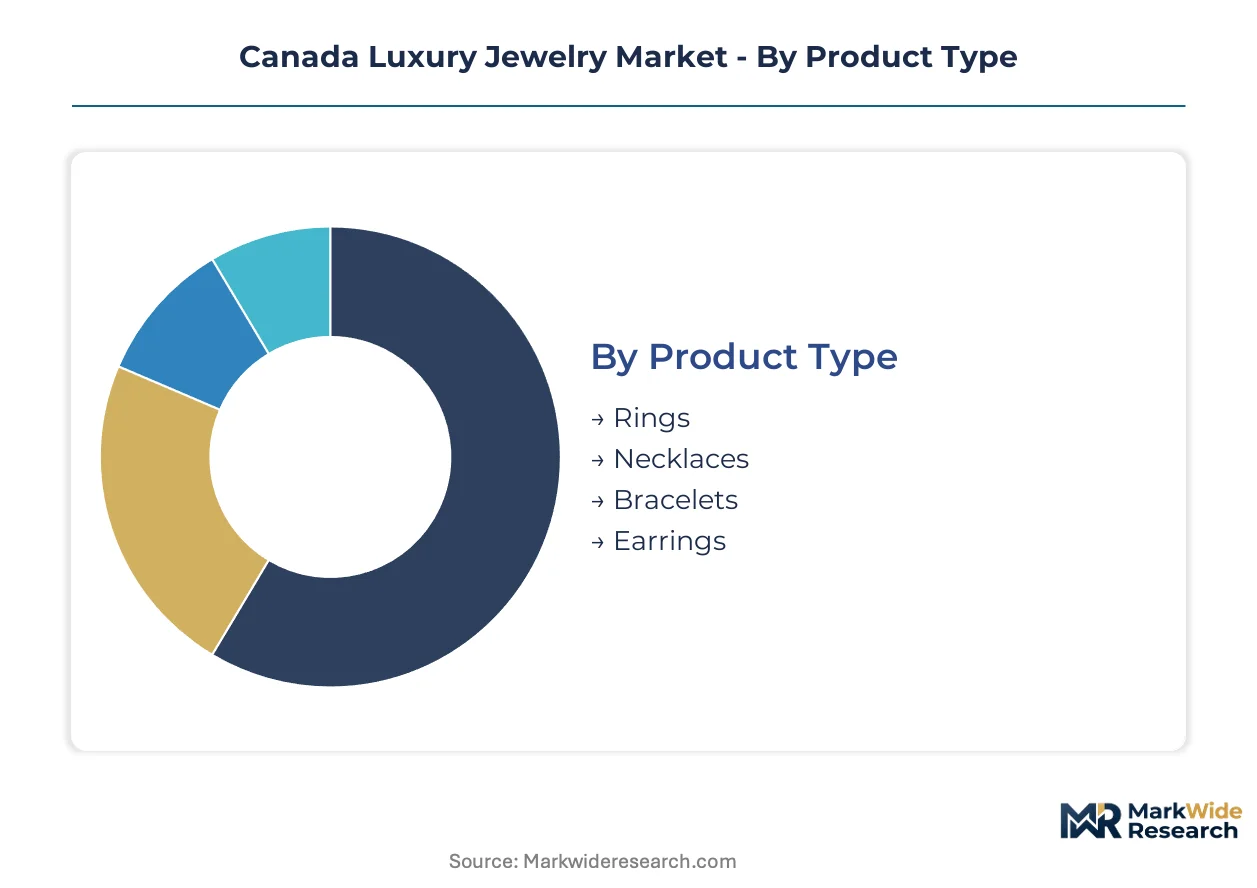
Segmentation in Canada's luxury jewelry market reveals how after-sales intensity varies dramatically across product categories and buyer profiles. Repair, resizing, and certification services generate recurring revenue streams that differ by material durability and purchase occasion.
Product Type:
After-sales-service intensity correlates directly with structural complexity and daily wear exposure across jewelry categories.
- Rings:Platinum and gold bands require periodic resizing and prong reinforcement due to continuous finger contact and mechanical stress. Toronto's bridal boutiques report the highest service attachment rates, with anniversary upgrades driving repeat visits.
- Necklaces:Chain repairs and clasp replacements dominate service requests for 18-karat gold and platinum pieces. Vancouver's consignment specialists leverage chain length adjustments to maintain customer relationships between primary purchases.
- Bracelets:Link maintenance and safety chain installations generate consistent workshop traffic for heavier gold designs. Calgary's emerging male buyer segment favors cuff styles with minimal servicing needs.
- Earrings:Post replacement and back upgrades constitute the primary service category for diamond studs and drop designs. Montreal artisans specialize in vintage earring restoration for estate collections.
Rings hold the largest share; momentum sits with bracelets as gendered purchasing norms erode.
Material:
Cost tier stratification determines margin architecture and customer lifetime value potential across precious inputs.
- Gold:18-karat and 22-karat alloys dominate bridal and investment-grade purchases in Ontario. Price volatility in COMEX futures compresses margin buffers for mid-tier collections.
- Platinum:Canadian-mined settings with laser-inscribed certification command premium positioning in Vancouver and Toronto. Hardness ratings suit daily wear with minimal maintenance.
- Silver:Entry-luxury accessibility recruits younger demographics in Quebec's urban centers. Sterling collections bridge costume jewelry abandonment under Health Canada's lead-content mandates.
- Gemstones:Ethically sourced sapphires and Canadian diamonds anchor provenance marketing. Third-party certification timelines extend product-to-market cycles for children's lines.
Gold captures the deepest revenue pool; platinum climbs the fastest on traceability premiums.
End User:
Application context shapes design specifications and purchasing ceremony intensity across buyer categories.
- Women:Self-purchase occasions and milestone gifts concentrate demand in Toronto's Yorkville and Vancouver's Coal Harbour districts. Custom consultation services convert transactional visits into bespoke pipelines.
- Men:Signet rings and heavy-link bracelets represent underpenetrated white space as workplace jewelry norms relax. Calgary and Vancouver show the steepest expansion trajectory for male-targeted collections.
- Couples:Matching band sets and coordinated necklace purchases drive dual-customer acquisition in bridal-focused retailers. Cross-selling opportunities extend to anniversary upgrades.
- Children:Health Canada's Consumer Product Safety Act lead thresholds have triggered wholesale line abandonment by independent artisans. Remaining suppliers compete on certified precious-metal-only positioning.
Women retain the dominant share; men gain share fastest on normalization of male ornamentation.
Distribution Channel:
Volume concentration and margin preservation trade off differently across physical and digital fulfillment modes.
- Online Retail:Direct-to-consumer data analytics enable precision inventory management for digitally native brands. Return logistics complexity limits penetration for high-value bespoke pieces.
- Boutiques:Controlled distribution through owned locations preserves margin pools eroded by price-transparent channels. Toronto's Yorkville and Vancouver's Gastown anchor flagship positioning.
- Department Stores:Foot traffic density supports entry-luxury silver collections targeting tourist and gift purchasers. Hudson's Bay Company concessions maintain heritage brand visibility.
- Auction Houses:Estate jewelry and rare gemstone sales concentrate in Toronto and Vancouver specialist houses. Provenance documentation requirements favor established consignors with archival capabilities.
Boutiques command the highest margin share; online retail expands most quickly on asset-light showroom testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada's Consumer Product Safety Act amendments are reshaping provincial manufacturing footprints, while provincial sales-tax harmonization debates in Ontario and British Columbia recalibrate cross-border e-commerce logistics for luxury jewelry fulfillment.
Ontario
Toronto's Yorkville district concentrates high-net-worth household demand for platinum settings with Canadian-mined diamonds. The provincial government's harmonized sales-tax framework discussions directly impact cross-border fulfillment economics for digitally native brands testing showroom concepts. Manufacturing clusters in Toronto's jewelry district supply certified precious-metal components to boutique operators.
British Columbia
Vancouver's Coal Harbour and Gastown neighborhoods anchor custom design consultation services converting showroom visits into bespoke order pipelines. Provincial environmental regulations on mining waste influence traceability marketing for Canadian-mined gemstones. Artisanal finishing workshops in Vancouver supply heritage-level craftsmanship to controlled-distribution boutiques.
Quebec
Montreal's estate jewelry restoration specialists serve vintage earring collections and archival consignment channels. The province's language regulations on commercial signage shape boutique positioning strategies in urban centers. Independent artisans in Montreal are abandoning base-metal alloy lines under federal lead-content mandates.
Alberta
Calgary's emerging male buyer segment drives demand for signet rings and heavy-link bracelets as workplace jewelry norms relax. Provincial energy-sector wealth concentration supports premium-tier purchasing for investment-grade gold pieces. Retail clusters in Calgary's downtown core test men's-focused collection expansions.
Atlantic Canada
Halifax's tourism-dependent retail corridors support entry-luxury silver collections targeting gift purchasers and cruise-ship visitors. Federal maritime regulations on precious-metal shipping influence inventory replenishment cycles for regional boutiques. Local artisans in Nova Scotia leverage Canadian Jewellers Association certification programs to differentiate provenance-verified offerings.
Canada Luxury Jewelry Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where heritage-owned boutiques preserve margin pools against digitally native entrants testing asset-light physical presence. The vendor base clusters around three strategic archetypes: direct-to-consumer data analytics operators, heritage craftsmanship anchors with controlled distribution, and custom design consultation specialists converting experiential retail into higher-margin bespoke pipelines. Dominant competitive moves include short-term leasing models for prime retail space and certified supply chain investments responding to Health Canada's tightened lead-content thresholds.
Among Toronto-based digitally native operators, Mejuri exemplifies the data-analytics-driven archetype optimizing inventory turns across showroom networks. Maison Birks anchors the heritage-controlled-distribution tier through owned boutiques preserving margin architecture. Spence Diamonds occupies the custom-consultation specialist position, converting in-store experiences into bespoke order pipelines particularly visible in Vancouver's high-net-worth districts.
| Leading Market Players |
|---|
| Mejuri |
| Maison Birks |
| Anne Sportun |
| Biko |
| Jenny Bird |
| Wolf Circus |
| Spence Diamonds |
| Paris Jewellers |
| Sofia Zakia |
| Others |
Pricing and Supply Chain Analysis
Canadian-mined diamond cutters in the Northwest Territories and Ontario anchor upstream supply concentration, concentrating margin pools with heritage-controlled-distribution boutiques in Toronto's Yorkville and Vancouver's Coal Harbour that command traceability premiums unavailable to price-transparent digital channels.
Pricing Analysis
Certification level through the Canadian Jewellers Association's voluntary programs creates the primary spread between entry-luxury silver collections and platinum settings with laser-inscribed provenance. Three-tier pricing structure across heritage-certified, contemporary-branded, and entry-luxury levels stratifies margin pools by after-sales service bundling and resale value preservation guarantees. Cost compression in mid-tier gold collections is intensifying because COMEX futures volatility compresses margin buffers for collections dependent on precious metal settings. Tourist and gift purchasers in department store channels exhibit highest price sensitivity; affluent millennials in Toronto and Vancouver demonstrate lowest sensitivity when traceability documentation accompanies purchases.
Supply Chain Analysis
Contract manufacturing for certified precious-metal components concentrates with Toronto's jewelry district workshops and Vancouver's artisanal finishing specialists. Geographic supply concentration rests on Canadian mining operations in the Northwest Territories, Belgian diamond cutting partnerships for non-Canadian stones, and Italian alloy suppliers for 18-karat and 22-karat gold inputs. Raw material dependencies hinge on platinum group metals from Russian and South African sources, ethically sourced sapphires from Sri Lankan and Madagascan mines, and certified Canadian diamonds flowing through limited approved cutter networks. Single-source vulnerability runs through the bottlenecked Canadian diamond certification pipeline. Distribution runs through owned boutiques preserving margin architecture, direct-to-consumer digital channels, and Hudson's Bay Company department store concessions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where blockchain-enabled provenance tracking and direct-to-consumer data analytics compress traditional retail hierarchies, rewarding operators that integrate physical showroom experiences with transparent digital infrastructure.
For Market Incumbents: Entrench heritage positioning by accelerating certified supply chain investments responding to Health Canada's tightened lead-content thresholds, while deploying short-term leasing models in Toronto's Yorkville and Vancouver's Gastown to test experiential retail formats without flagship capital commitments. Acquire or partner with blockchain provenance platforms to defend against digitally native entrants eroding trust advantages.
For New Entrants and Emerging Players: Calgary's male buyer segment represents the most penetrable white space as workplace jewelry norms relax and energy-sector wealth concentration supports premium-tier purchasing. Vancouver's custom design consultation pipeline offers a replicable go-to-market angle converting showroom visits into bespoke order flows. Target asset-light showroom testing in secondary high-net-worth districts before scaling.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digitally native brands that have proven direct-to-consumer unit economics but require physical presence scaling capital. Long-term viability across the analysis window favors operators controlling both certification infrastructure and owned distribution. Watch Health Canada enforcement patterns on lead-content thresholds as inflection indicator for regulatory-driven consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Supply Chain Investment | Health Canada's Consumer Product Safety Act compliance creates barrier to entry for uncertified competitors. |
| Asset-Light Showroom Expansion | Short-term leasing in Toronto's Yorkville enables digitally native brands to test physical presence without flagship commitments. |
| Blockchain Provenance Integration | Laser-inscribed diamond certification migrates from niche security feature to standard expectation among affluent millennials. |
| Men's Collection Development | Calgary and Vancouver show steepest expansion trajectory as gendered purchasing norms erode. |
| Resale Value Preservation Services | Certified appraisal and buyback programs for platinum settings lock in customer lifetime value. |
Research Methodology
Operator-level perspectives from boutique owners, custom design consultants, Canadian Jewellers Association certification administrators, and Health Canada compliance officers anchored the qualitative base. Primary interviews with Toronto and Vancouver showroom managers, Calgary retail expansion leads, and Montreal estate jewelry restoration specialists combined with secondary validation from Canadian Jewellers Association publications, Health Canada Consumer Product Safety Act guidance documents, and provincial sales-tax harmonization debate records. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates.
Scenario-bracketing around regulatory enforcement intensity and precious metal price volatility shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, material tier, end-user application, and distribution channel complexity. CAGRs derived from historical trajectory analysis adjusted for identified catalysts and restraints. Industry-specific forecast inputs incorporated Health Canada certification timeline compression effects and millennial wealth concentration patterns in Toronto and Vancouver.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digitally native brands with proven direct-to-consumer analytics capabilities would shift outcomes beyond modeled ranges. Quarterly review of Health Canada enforcement actions, Canadian diamond certification pipeline capacity, and provincial sales-tax harmonization developments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Smart Jewelry Market
Jewelry
Saudi Arabia Luxury Jewelry Market
Jewelry
Body Jewelry Market
Jewelry
Demi-Fine Jewelry Market
Jewelry
Jewelry Repair Market
Jewelry
Qatar Jewelry Market
Jewelry
Leather Jewellery Box Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
Quartz Ring Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Global Costume Jewelry Market
Jewelry
Crystal Bracelets Market
Jewelry
Imitation Jewelry Market
Jewelry
Germany Luxury Jewelry Market
Jewelry
Artificial Jewellery Market
Jewelry
China Luxury Jewelry Market