
 Latin America Jewelry Market | 2026-2036
Latin America Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Jewelry Market Foresight
Multi-source precious metal sourcing is expanding across Brazilian and Mexican supply chains as brands diversify away from single-mine dependencies. Vivara Participações S.A. anchors its position through captive gold refining operations in Minas Gerais. H Stern Jewelers Inc differentiates via proprietary gemstone cutting techniques developed in Rio de Janeiro. Pandora AS competes through vertically controlled silver recycling networks that lower raw material volatility.
Latin America jewelry encompasses ornamental items crafted from precious metals and gemstones, typically alloyed to 18-karat or 14-karat standards and set with locally extracted emeralds, amethysts, or topazes for personal adornment and wealth storage. Gold and silver materials dominate volume flows, with platinum gaining traction among high-net-worth buyers in São Paulo and Mexico City. Rings and necklaces generate the deepest margin pools, while online distribution channels capture the fastest expansion as digital payment infrastructure matures across the region.
Brazil's INMETRO hallmarking requirements and Mexico's PROFECO consumer protection standards shape product certification and retail transparency obligations for imported and domestic jewelry. Colombia's emerald export controls and Peru's mining sector environmental regulations further constrain supply chain configurations and sourcing compliance costs. Stakeholders must monitor evolving ESG disclosure rules and traceability mandates that will determine which suppliers retain market access.
Market Dynamics
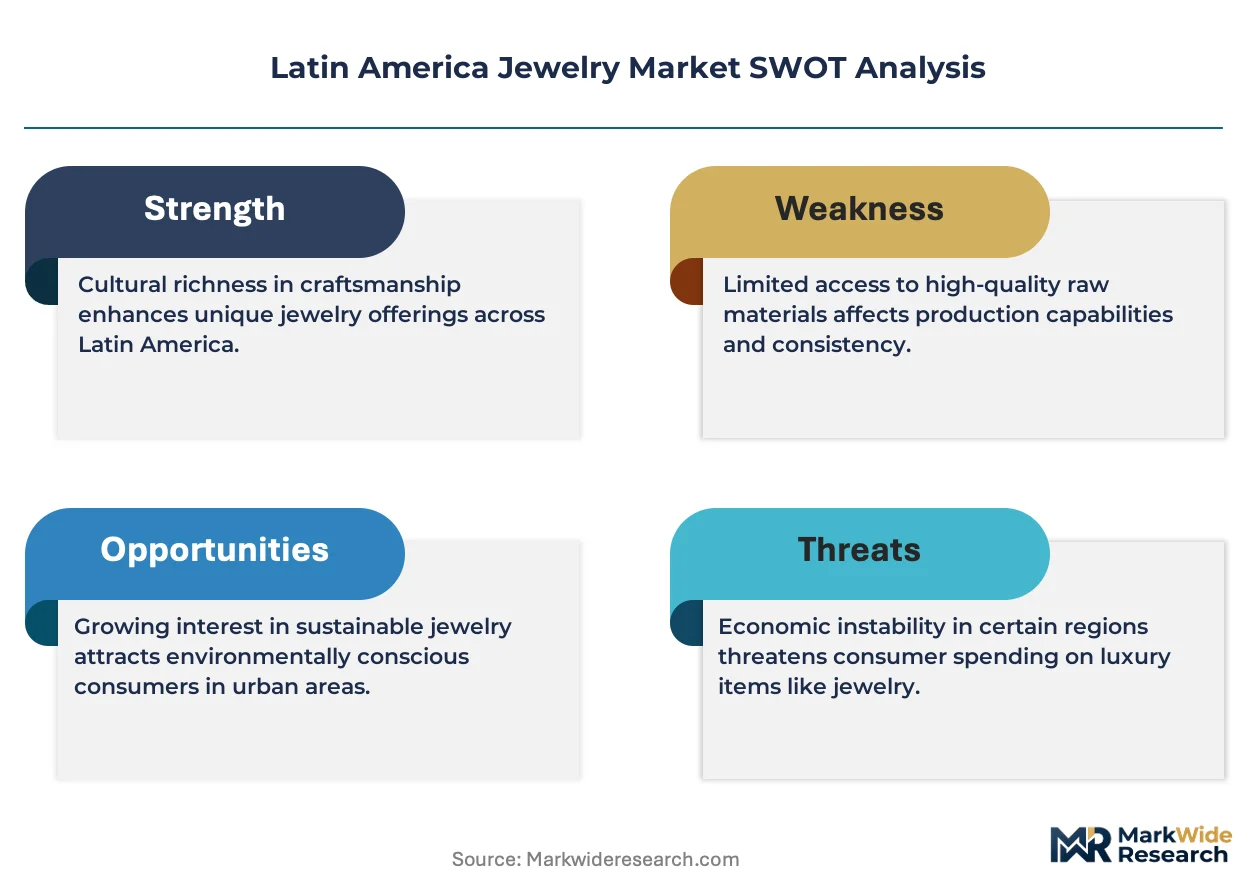
INMETRO hallmarking mandates and PROFECO consumer protection standards are compressing certification timelines across Brazilian and Mexican supply chains, forcing importers to restructure compliance workflows or forfeit retail access.
Growth Catalysts
- INMETRO Certification:Brazil's mandatory precious metal testing creates transparent quality benchmarks that reduce consumer hesitation and accelerate purchase decisions in bridal segments.
- Emerald Cluster Concentration:Colombia's Boyacá cutting workshops concentrate artisanal expertise for high-value gemstone settings, anchoring regional export competitiveness.
- Digital Payment Maturation:PIX instant settlement infrastructure across Brazilian e-commerce platforms eliminates friction in online jewelry transactions.
Market Restraints
- Gold Price Volatility:Input cost swings in São Paulo wholesale markets compress margin predictability for 18-karat alloy producers.
- Single-Mine Dependency:Concentrated sourcing from Minas Gerais gold operations exposes brands to disruption from localized environmental enforcement actions.
- Platinum Infrastructure Gap:Limited refining capacity outside Mexico City constrains high-net-worth product expansion.
Strategic Opportunities
- Peru Artisan Integration:Untapped Andean silver craft clusters offer backward integration potential for brands seeking distinctive hand-finished collections.
- Recycling Network Control:Captive silver recovery systems reduce raw material exposure while satisfying emerging ESG disclosure requirements.
- Cross-Border E-Commerce:Mercado Libre logistics integration enables direct-to-consumer penetration in secondary Argentine and Chilean urban markets.
Industry Challenges
- Gemstone Grading Standardization:Inconsistent emerald quality protocols across Colombian export channels create arbitration disputes and inventory markdowns.
- Legacy Hallmarking System Integration:PROFECO digital certificate requirements demand IT infrastructure investments that strain traditional family-owned retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Jewelry Market |
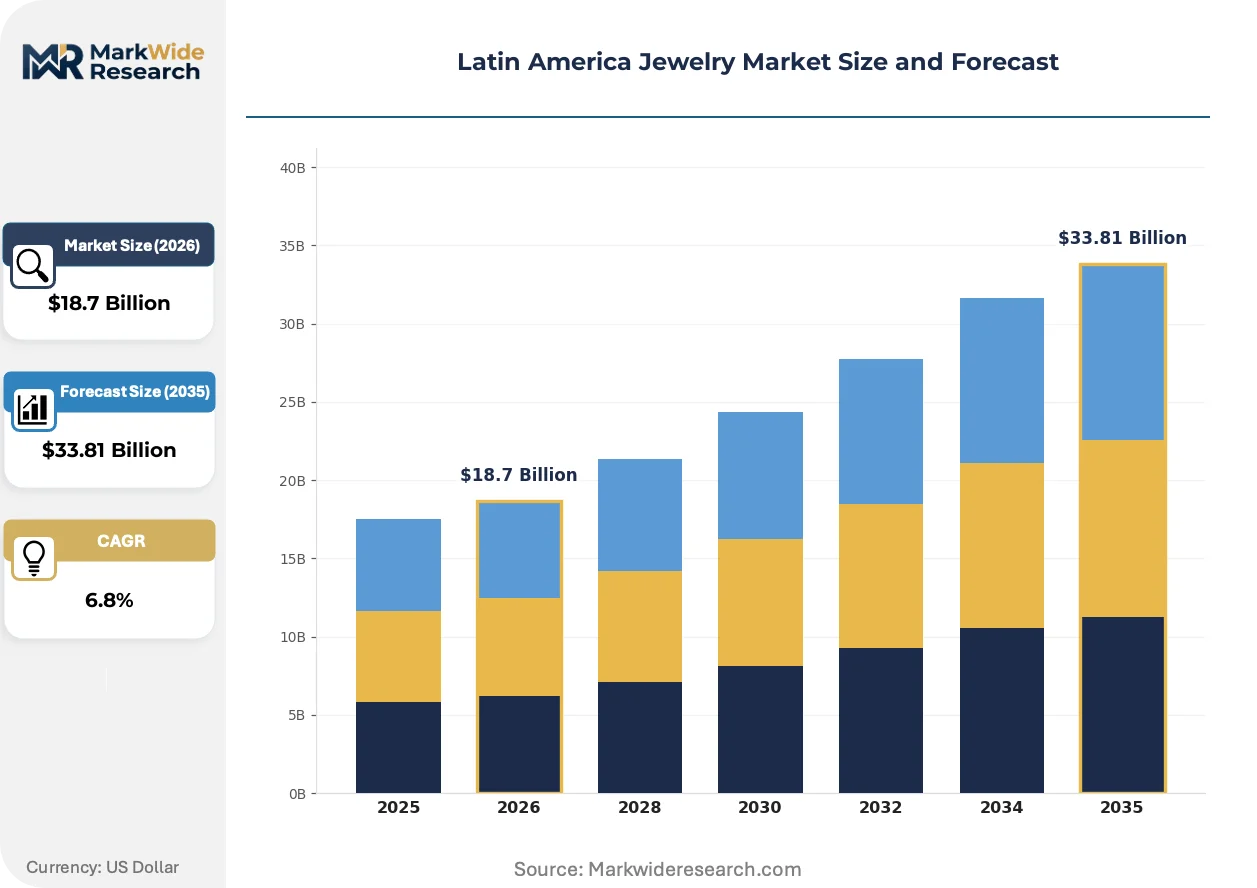
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Bracelets, Earrings Material: Gold, Silver, Platinum, Gemstones Distribution Channel: Online, Retail Stores, Artisans, Chain Stores End User: Women, Men, Children, Gift Buyers |
| Companies Covered | Compagnie Financière Richemont SA, Tous, Vivara Participações S.A., Bulgari, Cartier, H Stern Jewelers Inc, LVMH Moët Hennessy Louis Vuitton SE, Tiffany & Co., Pandora AS, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Jewelry Market Shifts & Advancements
Laser inscription traceability and blockchain-backed provenance systems are reconfiguring how Latin American brands demonstrate ethical sourcing to discerning buyers.
Blockchain-enabled supply chain verification is overtaking paper-based certificate storage across Brazilian luxury retailers. São Paulo-based bridal buyers now expect immutable gemstone origin records accessible via QR-linked digital vaults. This transparency infrastructure is compressing due diligence cycles and disqualifying suppliers lacking digitized audit trails.
PROFECO's updated hallmarking enforcement protocols now mandate third-party laboratory verification for all imported precious metal goods entering Mexican retail channels. Compliance costs have shifted toward smaller distributors lacking in-house metallurgical testing capacity. High-volume silver importers are consolidating supplier relationships to amortize certification expenses across larger shipment batches.
Subscription-based jewelry rental platforms are fragmenting traditional ownership models among urban professionals in Mexico City and Rio de Janeiro. These services displace conventional retail foot traffic for occasion-wear segments while capturing younger demographics prior to lifetime value conversion. Brazilian fintech-backed rental operators currently lead regional deployment velocity.
Latin America Jewelry Market Segmentation
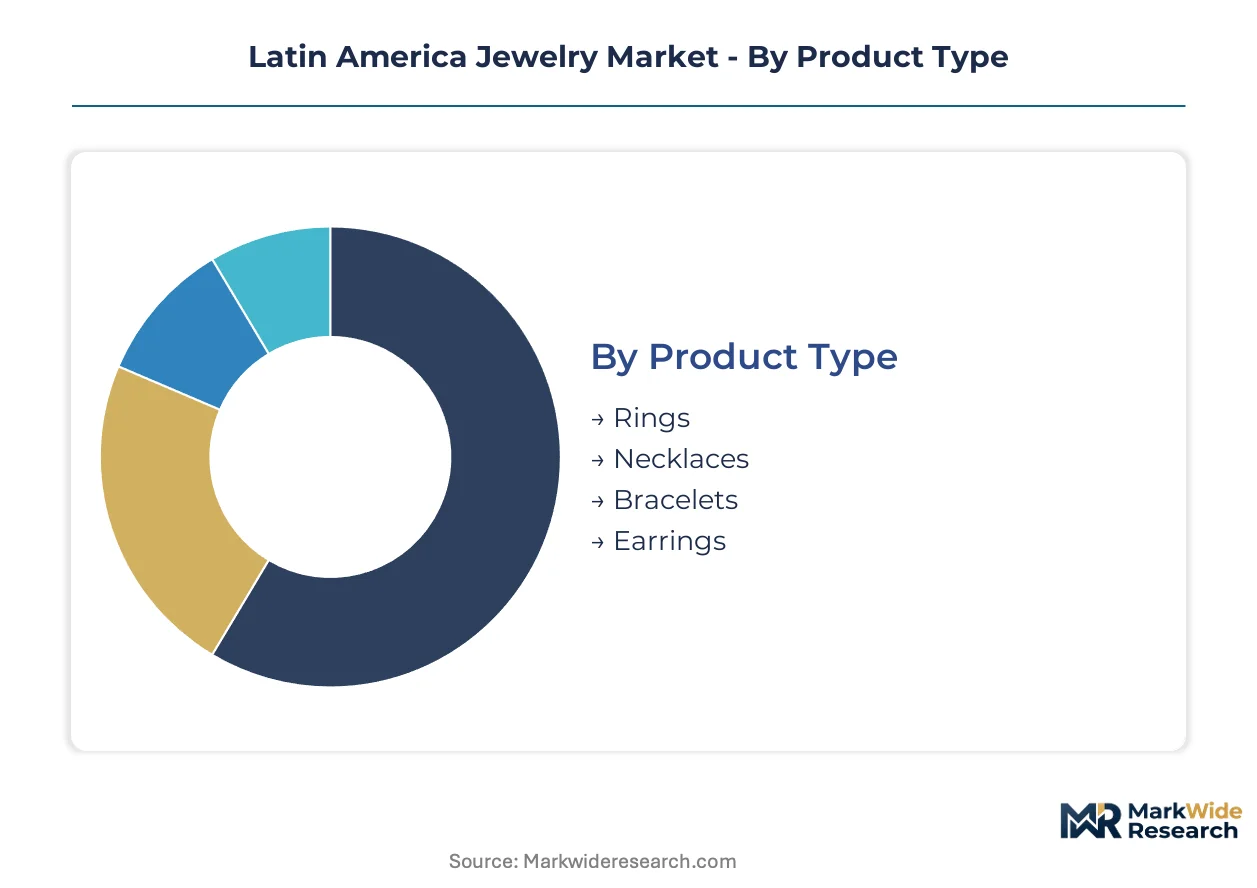
Jewelry segmentation in Latin America reveals how bridal traditions, hallmarking compliance, and digital payment maturation concentrate demand across distinct product-material-channel combinations. Understanding these intersections enables stakeholders to align certification investments with margin-rich segments.
Product Type:
Rings anchor standalone ceremonial purchases with deep emotional attachment, while necklaces and bracelets embed within broader wardrobe systems requiring repeat touchpoints.
- Rings:18-karat gold bands and solitaire settings dominate Brazilian bridal ceremonies, with INMETRO-certified hallmarks reducing purchase hesitation among São Paulo buyers. Engagement and wedding categories concentrate margin pools due to symbolic weight and upgrade cycles.
- Necklaces:Chain lengths and pendant configurations span daily wear to statement pieces, with Colombian emerald pendants commanding premium positioning in Bogotá artisan workshops. Layering trends among Mexico City professionals drive volume replenishment.
- Bracelets:Cuff and chain varieties serve both personal adornment and wealth storage functions, particularly silver iterations in Peruvian Andean craft traditions.
- Earrings:Stud and drop configurations offer accessible entry points for younger demographics, with lightweight designs prioritizing comfort in humid coastal climates.
Rings lead volumes today; necklaces are gaining share fastest through online channel expansion.
Material:
Cost tiers separate investment-grade precious metals from accessible alternatives, with platinum occupying an emerging premium position above established gold and silver baselines.
- Gold:14-karat and 18-karat alloys constitute the volume foundation, with Minas Gerais refining operations supplying Brazilian manufacturers and PIX-enabled installment plans broadening access. Price volatility in São Paulo wholesale markets compresses margin predictability for alloy producers.
- Silver:Sterling standards anchor mass-market accessibility, with Pandora's vertically controlled recycling networks demonstrating how captive recovery systems reduce raw material exposure. Mexican artisans in Taxco sustain hand-hammered traditions for export competitiveness.
- Platinum:Limited refining capacity outside Mexico City constrains supply, though high-net-worth buyers in São Paulo and Mexico City increasingly specify this metal for wedding bands.
- Gemstones:Colombian emeralds, Brazilian amethysts, and Argentine topazes provide regional differentiation, with Boyacá cutting workshops concentrating artisanal expertise for high-value settings.
Gold commands absolute revenue share; silver shows steepest expansion trajectory through recycling network investments.
Distribution Channel:
Customer type determines channel selection, with ceremonial buyers preferring physical verification while self-purchasers embrace digital convenience.
- Online:PIX instant settlement infrastructure eliminates friction in Brazilian e-commerce transactions, with Mercado Libre logistics integration enabling cross-border penetration into Argentine and Chilean secondary markets. Digital-native brands capture younger demographics prior to lifetime value conversion.
- Retail Stores:Full-service locations in São Paulo and Mexico City shopping districts provide hallmarking verification and customization services that bridal segments demand. PROFECO compliance investments strain traditional family-owned operators.
- Artisans:Independent craftsmen in Bogotá and Cusco offer bespoke emerald setting and silver hammering techniques unavailable through industrial production. These channels concentrate high-margin custom work.
- Chain Stores:Vivara and H Stern operate controlled retail networks with captive refining and proprietary cutting capabilities, amortizing compliance costs across volume bases.
Chain stores retain the largest footprint; online channels are climbing the fastest as payment infrastructure matures.
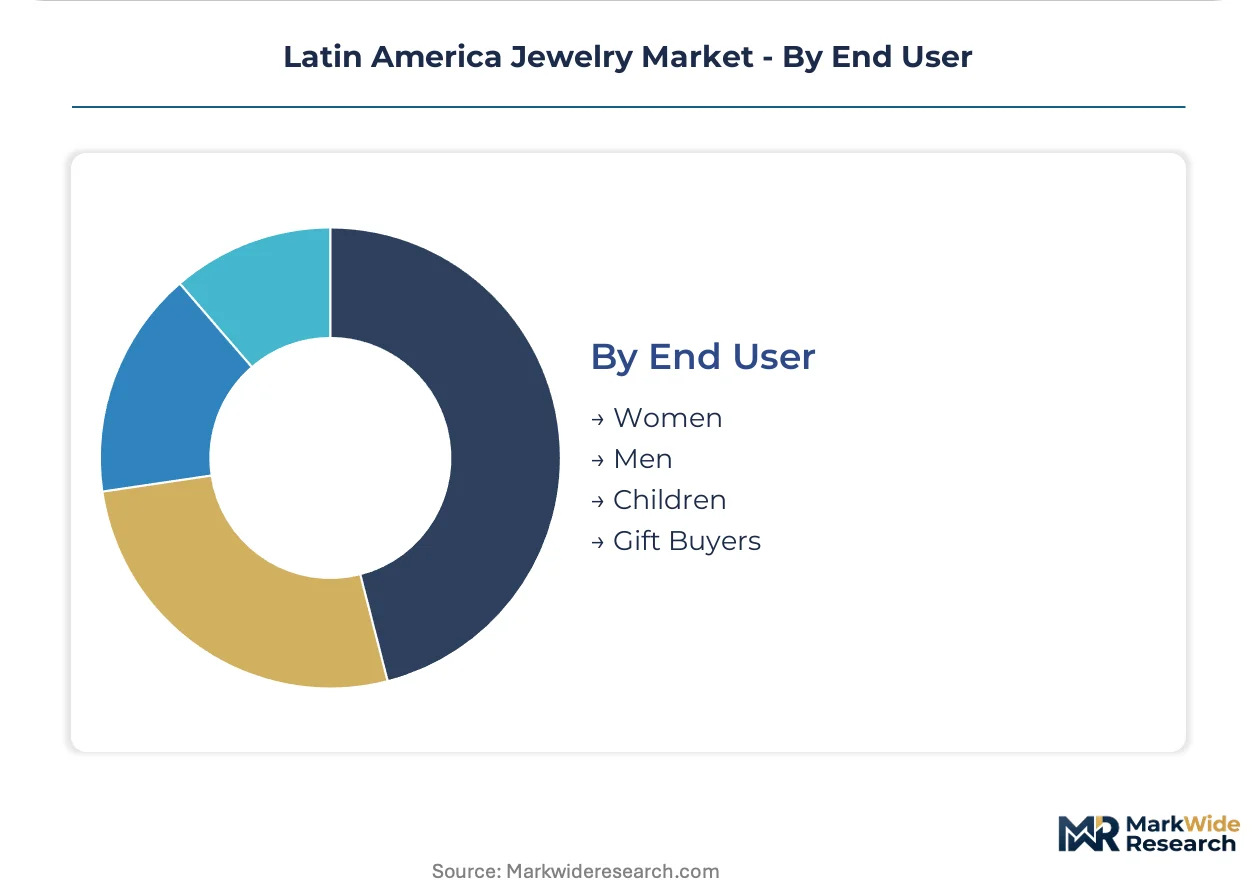
End User:
Gender-based purchasing patterns intersect with life-stage transitions, creating distinct occasion-based demand cycles.
- Women:Self-purchase and gift reception dominate volume, with professional women in Mexico City and Rio de Janeiro driving subscription rental platform adoption for occasion-wear segments.
- Men:Wedding band and watch accessory purchases concentrate demand, with platinum gaining traction among high-net-worth buyers seeking differentiation from traditional gold.
- Children:Baptism and communion ceremonies in Catholic-majority markets generate ceremonial jewelry demand, typically silver pieces with religious iconography.
- Gift Buyers:Seasonal purchasing around Mother's Day and Christmas drives volume spikes, with online channels capturing last-minute transactions through expedited shipping.
Women account for the predominant share; gift buyers expand most quickly through digital gifting interfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints across Latin America, with compliance cost differentials between INMETRO-certified Brazilian facilities and PROFECO-regulated Mexican operations driving supplier relocation decisions.
Brazil
Bridal ceremonies in São Paulo and Rio de Janeiro sustain concentrated demand for 18-karat gold bands, with PIX-enabled installment plans broadening access among middle-income households. INMETRO hallmarking mandates create transparent quality benchmarks that reduce consumer hesitation and compress purchase decision cycles. Minas Gerais refining clusters anchor captive gold processing for domestic brands seeking supply security.
Mexico
Taxco silver artisans sustain hand-hammered traditions that command export premiums in North American markets, while Mexico City professionals drive layering trends in necklace categories. PROFECO's updated enforcement protocols mandate third-party laboratory verification for all imported precious metal goods, shifting compliance costs toward smaller distributors. The Bajío Region concentrates emerging manufacturing investment as brands seek proximity to US distribution channels.
Colombia
Bogotá's emerald pendants command premium positioning among high-net-worth buyers seeking regional gemstone provenance, with Boyacá cutting workshops concentrating artisanal expertise for high-value settings. Export controls on rough emeralds constrain supply chain configurations and elevate sourcing compliance costs. Cartagena's cruise-ship retail corridors concentrate tourist-facing volume for lower-karat gold souvenir pieces.
Argentina
Buenos Aires professionals increasingly access Brazilian and Chilean e-commerce platforms through Mercado Libre logistics integration, displacing traditional retail foot traffic for occasion-wear segments. The country's central bank foreign exchange restrictions complicate import financing for precious metal inventory. Córdoba's secondary urban market shows rising subscription rental platform adoption among younger demographics.
Peru
Andean silver craft clusters in Cusco offer distinctive hand-finished collections that attract backward integration interest from brands seeking ESG-compliant sourcing narratives. The mining sector's environmental regulations constrain small-scale extraction and elevate traceability documentation requirements. Lima's upscale districts concentrate platinum demand among high-net-worth buyers, though limited refining capacity outside Mexico City constrains product expansion.
Latin America Jewelry Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital-native rental and subscription models that fragment traditional ownership patterns. The vendor base stratifies across three maturity tiers: heritage houses with captive refining infrastructure, mid-scale specialists with proprietary cutting techniques, and asset-light platforms leveraging fintech partnerships for customer acquisition. Competitive dynamics center on certification cost amortization and recycling network control rather than raw material scale.
Within the heritage-house tier, Compagnie Financière Richemont SA and LVMH Moët Hennessy Louis Vuitton SE occupy positions defined by vertically integrated European supply chains and regional retail footprints. Vivara Participações S.A. anchors the mid-scale Brazilian specialist category through its São Paulo-listed corporate structure and Minas Gerais refining presence. Pandora AS exemplifies the recycling-network archetype through its vertically controlled silver recovery systems that reduce raw material volatility exposure.
| Leading Market Players |
|---|
| Compagnie Financière Richemont SA |
| Tous |
| Vivara Participações S.A. |
| Bulgari |
| Cartier |
| H Stern Jewelers Inc |
| LVMH Moët Hennessy Louis Vuitton SE |
| Tiffany & Co. |
| Pandora AS |
| Others |
Supply & Pricing Matrix
London Bullion Market Association gold price benchmarks cascade through São Paulo wholesale markets into three distinct pricing tiers: INMETRO-certified 18-karat bridal bands, 14-karat mass-market alloys, and artisanal silver pieces from Taxco. This commodity-to-retail transmission concentrates margin compression risk among distributors lacking captive refining capacity.
Pricing Analysis
Input-cost pass-through from Minas Gerais gold refining operations determines retail pricing elasticity across Brazilian bridal segments. Three-tier pricing structure across premium, standard, and economy levels separates certified 18-karat wedding bands from 14-karat daily wear and silver entry pieces. Pricing pressure stems from PIX-enabled installment plans broadening access while compressing per-unit margins. Middle-income São Paulo households show highest price sensitivity; high-net-worth buyers in Mexico City exhibit lowest.
Supply Chain Analysis
Single-source vulnerability sits with Minas Gerais gold operations that feed Brazilian manufacturing clusters. Geographic supply concentration spans Brazil, Mexico, and Colombia for precious metals and gemstone cutting. Raw material dependencies center on gold ore, sterling silver feedstock, and Colombian rough emeralds. Supply chain risk manifests as localized environmental enforcement disrupting extraction. Distribution runs through controlled retail networks and Mercado Libre logistics integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America jewelry functions as a stable compounder anchored by ceremonial purchase traditions that resist discretionary spending volatility. Bridal and wedding segments generate predictable replacement cycles across economic conditions.
For Market Incumbents: To counter fintech-backed rental platforms fragmenting occasion-wear ownership, Vivara and H Stern should deepen backward integration into Minas Gerais refining and Boyacá cutting workshops. Captive supply control amortizes INMETRO and PROFECO compliance costs while disqualifying asset-light competitors lacking metallurgical testing infrastructure.
For New Entrants and Emerging Players: Mercado Libre logistics integration offers the lowest-friction entry path for direct-to-consumer penetration in Argentine and Chilean secondary markets. White-space targets include subscription rental platforms in Córdoba and Cusco, plus digital-native bridal brands capturing São Paulo professionals prior to lifetime value conversion. PIX-enabled installment plans provide the essential go-to-market mechanism.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically controlled recycling networks that reduce raw material volatility exposure. Long-term viability favors operators combining captive refining with ESG-compliant traceability documentation. The signal to watch is PROFECO digital certificate adoption rates among traditional family-owned retailers, indicating consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refining | Captive gold processing in Minas Gerais insulates Vivara from São Paulo wholesale price swings. |
| Blockchain Traceability Deployment | Immutable origin records via QR-linked vaults satisfy bridal buyers demanding ethical sourcing verification. |
| Recycling Network Expansion | Vertically controlled silver recovery systems reduce Pandora's exposure to commodity volatility. |
| Cross-Border E-Commerce Launch | Mercado Libre logistics integration enables direct penetration into underserved Argentine urban markets. |
| Artisan Cluster Acquisition | Taxco silver workshops or Boyacá cutting operations provide distinctive hand-finished collection differentiation. |
Research Methodology
Multiple input streams — primary interviews with jewelry brand executives and PROFECO compliance officers, secondary validation through INMETRO certification databases and Colombian emerald export records, plus customs trade data — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included bridal retailers in São Paulo, Taxco artisan cooperative representatives, and precious metal distributors in Mexico City. Secondary sources encompassed hallmarking regulatory filings, mining sector environmental disclosures, and e-commerce platform transaction data.
Data-stream reconciliation across product-material-channel combinations generated volume and value estimates throughout the forecast period. Segmentation dimensions modeled include product type, material grade, distribution channel, and end-user archetype. CAGRs were derived from trend extrapolation of PIX payment adoption, INMETRO certification expansion, and bridal ceremony incidence patterns. Industry-specific inputs incorporated gold price volatility indices and emerald export control enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for blockchain-backed provenance systems would alter the outlook if regulatory mandates accelerate or consumer willingness-to-pay for transparency disappoints. Forecasts reflect assumptions about PIX infrastructure maturation and PROFECO digital certificate penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Global Costume Jewelry Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
Mexico Luxury Jewelry Market
Jewelry
Quartz Ring Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Japan Jewellery Market
Jewelry
China Luxury Jewelry Market
Jewelry
Wedding Rings Market
Jewelry
Imitation Jewelry Market
Jewelry
Chalcedony Earrings Market
Jewelry
China Jewellery Market
Jewelry
Luxury Fine Jewellery Market
Jewelry
Colorful Gold Jewelry Market
Jewelry
Crystal Bracelets Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
Jewellery Box Market