
 China Jewellery Market | 2026-2036
China Jewellery Market Size, Share, and Industry Trends Forecast 2026-2036
China Jewellery Market Analysis
Guangdong province's jewellery manufacturing base is shifting toward automated casting and precision gem-setting to offset rising labor costs. Chow Tai Fook Jewellery Group anchors its position through an extensive omnichannel network spanning mainland China. LVMH Moët Hennessy Louis Vuitton competes by leveraging its heritage maisons to capture ultra-high-net-worth collectors. Guangdong Xuping Jewelry dominates mass-market alloy and silver production through vertically integrated foundries in Panyu and Shunde.
China jewellery encompasses ornamental pieces crafted from gold, silver, platinum, and precious gemstones, typically measured by karat purity, carat weight, and hallmark certification under national standards; these items serve ceremonial, investment, and personal adornment functions across consumer and institutional buyers. Gold jewellery commands the largest value pool given its dual role as wearable asset and inflation hedge, while online sales channels represent the fastest-expanding route as live-streaming commerce and mini-program stores reshape discovery and conversion. Traditional design styles retain strength in bridal gifting, though contemporary and custom segments gain traction among urban professionals seeking differentiated pieces.
SAMR enforces hallmarking and precious metal content labeling under GB standards, while the People's Bank of China monitors gold import quotas and exchange-traded bullion flows that directly affect raw material access. MEE regulations on electroplating wastewater and heavy metal discharge raise compliance costs for foundries clustered in Guangdong and Zhejiang. Stakeholders must track how evolving digital currency attitudes and platform antitrust enforcement reshape consumer payment behavior and channel economics in this market.
Market Dynamics
Live-streaming commerce is compressing traditional retail margins while simultaneously expanding addressable reach into tier-three and tier-four Chinese cities, forcing established distributors to rebuild their channel economics around real-time conversion metrics rather than foot traffic.
Growth Catalysts
- GB 11887 hallmarking enforcement:SAMR's stricter precious metal purity verification is elevating consumer trust in certified retailers and accelerating consolidation toward compliant national chains.
- Dual carbon policy alignment:Jewellery foundries adopting renewable-powered electroplating and recycled gold sourcing qualify for preferential MEE permitting and state procurement consideration.
- Self-purchase normalization:Urban professional women in Shanghai and Beijing increasingly view fine jewellery as personal asset allocation rather than ceremonial obligation, expanding purchase frequency.
Market Restraints
- Gold import quota rigidity:PBOC's controlled bullion inflow limits raw material availability during demand surges, creating inventory volatility for fabricators.
- Guangdong labor cost escalation:Precision gem-setting craftspeople command wage premiums that erode margin on mid-market silver and alloy pieces.
- Platinum substitution pressure:Palladium and white gold alloys displace platinum in bridal settings where price sensitivity dominates aesthetic preference.
Strategic Opportunities
- Western China penetration:Chengdu and Xi'an exhibit underdeveloped luxury jewellery infrastructure relative to disposable income growth, rewarding early omnichannel entrants.
- Digital collectible convergence:Blockchain-authenticated provenance records paired with physical pieces attract crypto-native collectors seeking verifiable scarcity.
- Heritage craft revival:Filigree and enamel techniques receive cultural ministry subsidies and state media promotion, creating differentiated positioning against mass-produced imports.
Industry Challenges
- Master craftsperson scarcity:Traditional jade carving and micro-pavé setting skills face generational attrition as younger workers prefer technology-sector employment.
- Cross-platform data fragmentation:Live-streaming sales across Douyin, Kuaishou, and WeChat mini-programs complicate unified customer relationship management and inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Jewellery Market |
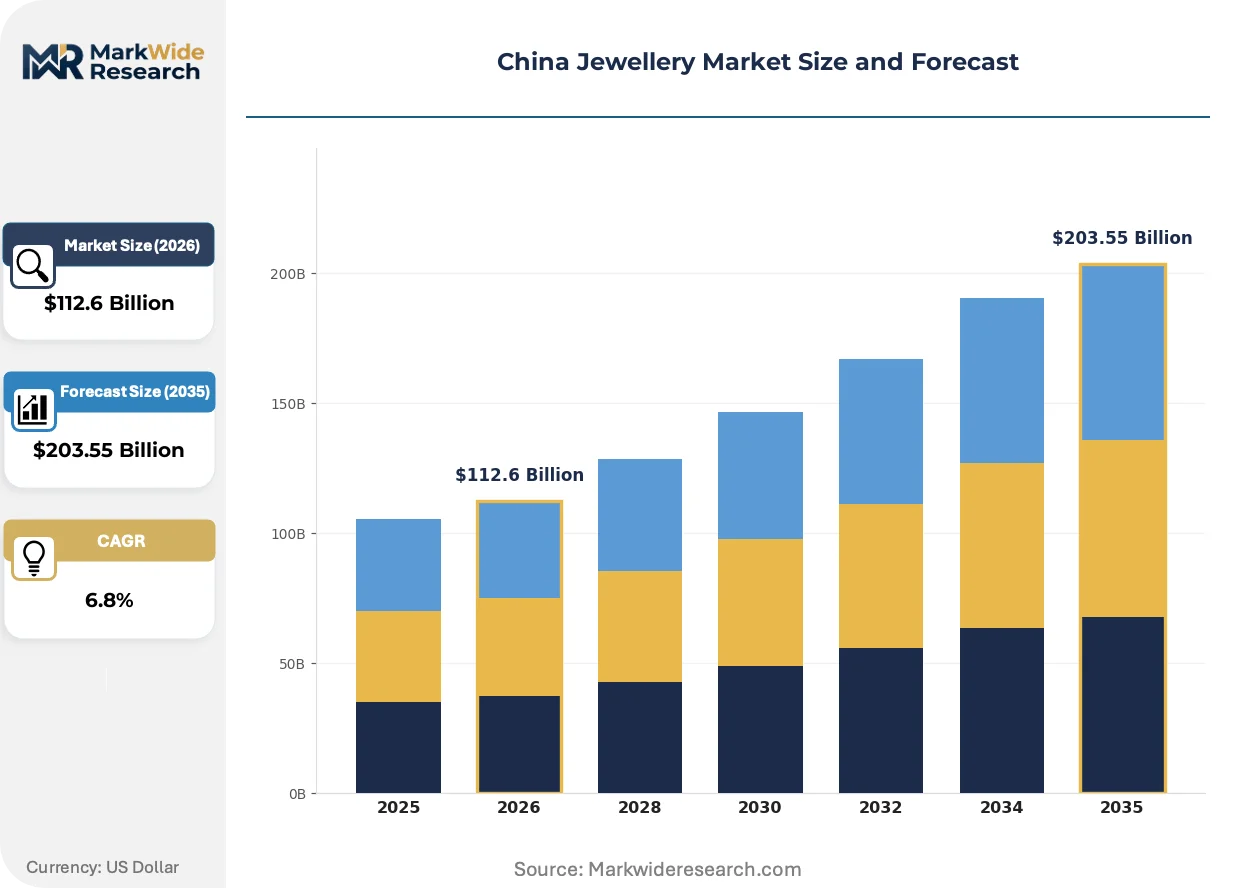
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gold, Silver, Platinum, Diamond, Gemstone End User: Women, Men, Kids, Collectors Sales Channel: Online, Offline, Retail Stores, Auction Houses Design Style: Traditional, Contemporary, Custom, Fashion, Ethnic |
| Companies Covered | Richemont, Guangdong Xuping Jewelry, LVMH Moët Hennessy Louis Vuitton, Swarovski Group, Wuzhou Zuanfa Jewelry, Pandora, Signet Jewelers, Tiffany & Co, Chow Tai Fook Jewellery Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Jewellery Market Emerging Trajectories
Digital-native discovery mechanisms are displacing conventional advertising while precision manufacturing technologies compress production timelines from weeks to days, enabling made-to-order at mass-market price points.
Artificial intelligence-driven design tools are integrating generative algorithms trained on historical Chinese motifs with parametric customization interfaces. Tier-one city millennials deploy these platforms to co-create unique pieces before fabrication. This capability is integrating traditional craftsmanship with scalable personalization, collapsing the historical tradeoff between bespoke quality and production efficiency.
SAMR's expanded precious metals labeling requirements under revised GB standards mandate blockchain-traceable supply chain documentation for all gold products above specified thresholds. Fabricators must retrofit foundry management systems to capture smelter origin, refining batch, and retail transaction data. Bridal segment participants face the steepest compliance investment given higher average transaction values and corresponding documentation intensity.
Live-streaming hosts now function as primary purchase influencers, with top performers commanding exclusive product lines and revenue-sharing arrangements that bypass traditional wholesale markup structures. Younger consumers in Shenzhen and Hangzhou complete transactions during broadcast sessions rather than visiting physical showrooms. This channel compression concentrates marketing spend on influencer cultivation while reducing mall-based retail footprint requirements for emerging brands.
China Jewellery Market Segmentation
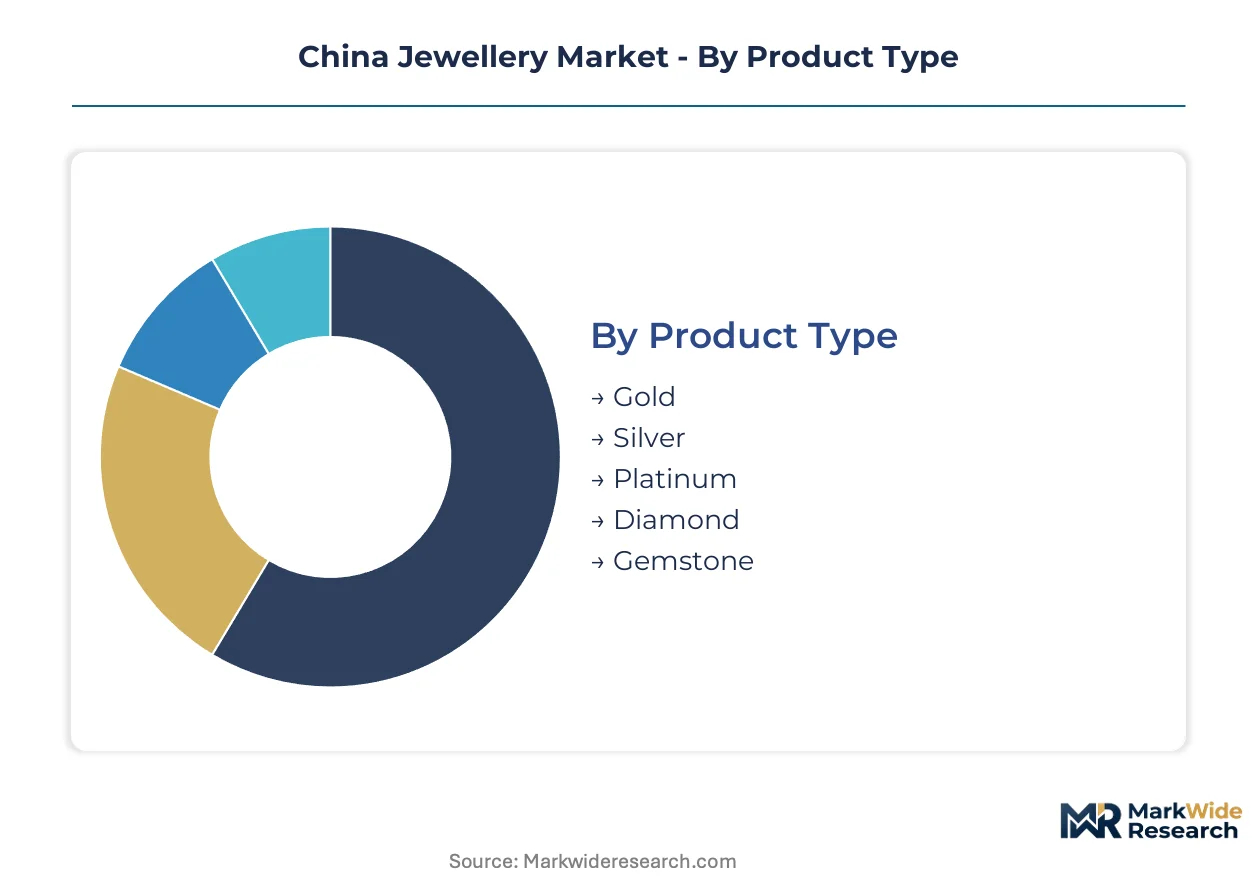
Segmentation in the China jewellery market reveals how purity standards, digital channel migration, and generational design preferences create distinct competitive arenas. Manufacturers and retailers must align inventory and certification investments with the specific technical and behavioral requirements of each slice.
Product Type:
Karat purity and hallmarking requirements differentiate fabrication complexity and regulatory burden across metal categories.
- Gold:24K and 22K pieces dominate bridal transactions in Shanghai and Beijing, where SAMR's GB 11887 certification mandates blockchain-traceable supply chain documentation above specified thresholds. Chow Tai Fook and Lao Feng Xiang anchor their market positions through certified purity guarantees that justify premium positioning.
- Diamond:Certified stones with GIA or NGTC grading reports concentrate in tier-one city self-purchase segments, where urban professional women treat certified diamonds as portable asset allocation. Import quota constraints under PBOC oversight create periodic inventory volatility for fabricators dependent on rough diamond inflows.
- Silver:925 sterling and alloy compositions serve mass-market daily wear in Guangdong's vertically integrated foundries, where automated casting offsets rising labor costs.
- Platinum:Pt950 bridal settings face substitution pressure from palladium and white gold alloys as price sensitivity reshapes aesthetic preferences in tier-two cities.
- Gemstone:Jade, ruby, and sapphire pieces draw from traditional carving clusters in Guangdong and Yunnan, where master craftsperson scarcity threatens generational skill transmission.
Mature deployment sits with Gold. Newer deployment is concentrated in Diamond.
End User:
Purchase frequency and average transaction value diverge sharply across demographic cohorts, reshaping channel economics and inventory turnover requirements.
- Women:Self-purchase normalization among Shanghai and Beijing professionals drives repeat transactions at 3-4x the frequency of ceremonial gifting, expanding addressable spend beyond traditional bridal peaks. Live-streaming hosts cultivate exclusive product lines targeting this segment's preference for real-time discovery.
- Collectors:Ultra-high-net-worth individuals in Shenzhen and Hangzhou pursue blockchain-authenticated provenance records paired with physical pieces, creating hybrid digital-physical scarcity plays. LVMH's heritage maisons compete for this wallet share through limited-edition releases.
- Men:Cufflinks, signet rings, and investment-grade bullion accessories concentrate in corporate gifting and personal asset allocation.
- Kids:Gold longevity locks and silver anklets sustain traditional gifting practices during lunar new year and birth celebrations.
Established volume concentrates in Women. Emerging volume is building in Collectors.
Sales Channel:
Channel selection determines margin structure, customer acquisition cost, and the feasibility of real-time personalization services.
- Online:Douyin and Kuaishou live-streaming commerce compresses traditional retail margins while expanding reach into tier-three and tier-four cities, forcing distributors to rebuild economics around conversion metrics rather than foot traffic. Mini-program stores on WeChat enable seamless payment integration for digital-native consumers.
- Retail Stores:Chow Tai Fook's omnichannel network maintains physical presence in Shanghai, Beijing, and Shenzhen luxury malls, where high-consideration bridal purchases still require tactile validation and in-person certification review.
- Offline:Wholesale counters and trading floors in Guangdong's Panyu and Shunde clusters serve B2B procurement for mass-market alloy and silver production.
- Auction Houses:Poly Auction and China Guardian handle estate jewellery and investment-grade jade, attracting collectors seeking verified provenance and price transparency.
Dominant transaction flow runs through Retail Stores. Steepest expansion trajectory belongs to Online.
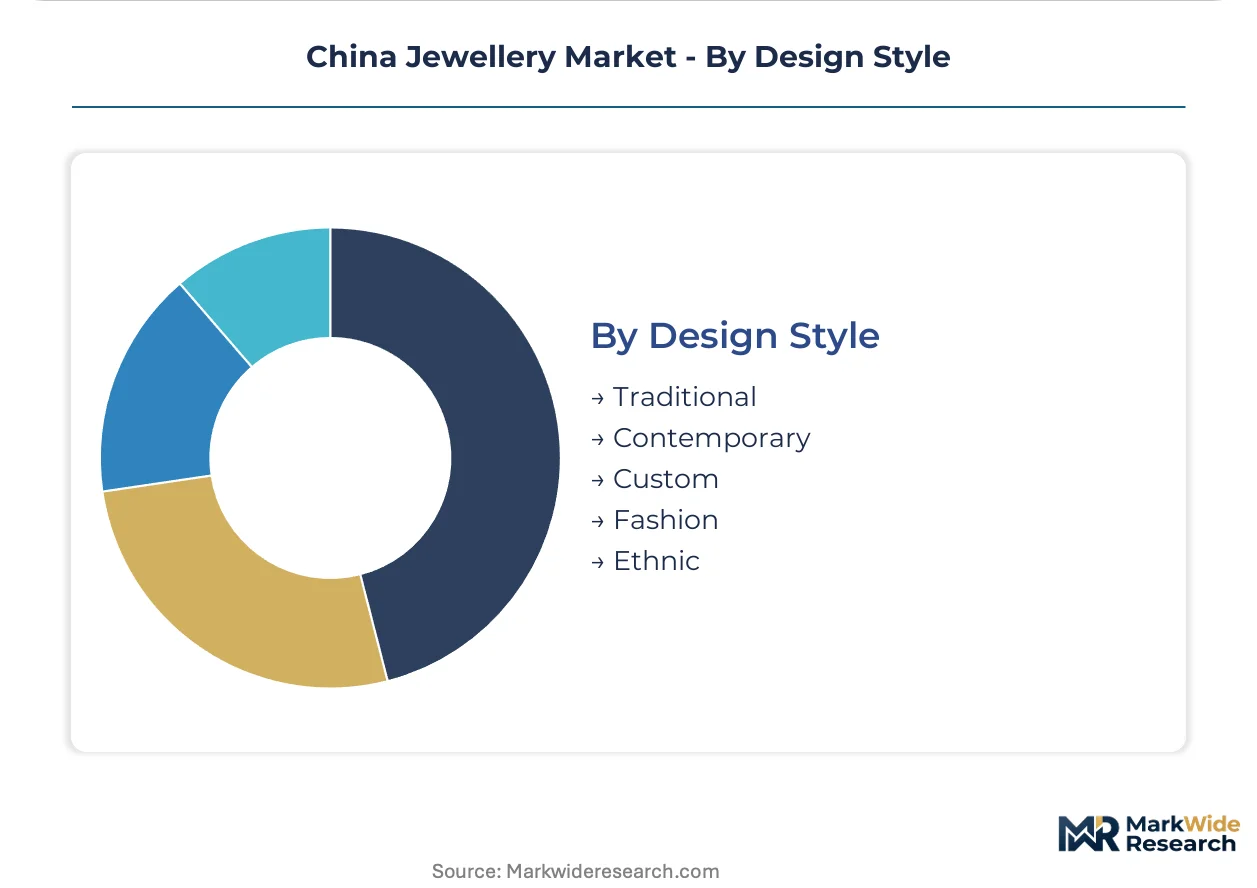
Design Style:
Aesthetic positioning determines manufacturing flexibility, craftsperson skill requirements, and the applicability of automated production technologies.
- Traditional:Dragon-phoenix bridal sets and filigree techniques receive cultural ministry subsidies and state media promotion, creating differentiated positioning against mass-produced imports. Master craftsperson scarcity limits scalable output despite strong ceremonial demand.
- Custom:AI-driven design platforms enable tier-one city millennials to co-create unique pieces before fabrication, collapsing the historical tradeoff between bespoke quality and production efficiency. Parametric interfaces trained on historical Chinese motifs accelerate design iteration.
- Contemporary:Minimalist geometries and mixed-metal compositions attract urban professionals seeking workplace-appropriate adornment.
- Fashion:Trend-responsive alloy and silver pieces rotate rapidly through live-streaming channels, requiring flexible foundry scheduling.
- Ethnic:Tibetan silver and Miao embroidery techniques serve regional tourism and cultural preservation objectives.
Volume leadership rests with Traditional. Fastest share gain is occurring in Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province's gold and silver foundry clusters anchor China's jewellery manufacturing geography, feeding raw material through vertically integrated supply chains into domestic retail and export channels.
Shanghai
Luxury mall concentration and digital-native consumer density drive self-purchase normalization among professional women. SAMR's GB 11887 enforcement elevates certified retailer trust. The Nanjing Road and Huaihai Road corridors host flagship omnichannel showrooms where bridal transactions still require tactile validation.
Beijing
State procurement consideration for dual carbon-aligned fabricators shapes supplier selection in ceremonial gifting segments. MEE regulations on electroplating wastewater raise compliance costs for foundry suppliers serving this market. Wangfujing and Sanlitun clusters concentrate high-consideration purchases among ultra-high-net-worth collectors.
Shenzhen
Crypto-native collector demand for blockchain-authenticated provenance records converges with physical piece acquisition. PBOC gold import quota monitoring affects raw material access for fabricators. The Luohu and Nanshan districts host live-streaming commerce studios that compress traditional retail margins while expanding reach.
Chengdu
Underdeveloped luxury jewellery infrastructure relative to disposable income growth rewards early omnichannel entrants. Cultural ministry subsidies for heritage craft revival create differentiated positioning opportunities. The Chunxi Road retail corridor exhibits rising demand for contemporary and custom design segments among urban professionals.
Xi'an
Western China penetration potential materializes through rising middle-class consumption and limited incumbent presence. GB standards compliance investments by national chains accelerate consolidation toward certified retailers. The Qujiang district's tourism-driven retail development attracts experiential showroom formats targeting domestic visitors.
China Jewellery Market Vendor Landscape
Global majors compete with regional champions across certification standards and channel economics, producing a tiered structure where heritage maisons, national omnichannel networks, and mass-market fabricators occupy distinct competitive arenas. Consolidation pressure from SAMR hallmarking enforcement favors scaled players with compliance infrastructure. Three archetypes dominate: vertically integrated foundry-to-retail operators, luxury brand licensors, and live-streaming-native digital retailers. Dominant competitive moves include M&A to secure craftsperson talent and capacity expansion into western China markets.
Within the heritage luxury tier, Richemont and LVMH Moët Hennessy Louis Vuitton represent global majors competing for ultra-high-net-worth collector wallet share through limited-edition releases and provenance authentication. Among China-based fabricators, Chow Tai Fook Jewellery Group anchors the national omnichannel archetype with extensive mainland retail infrastructure, while Guangdong Xuping Jewelry exemplifies mass-market vertical integration through foundry control in Panyu and Shunde. These three entities occupy positions that span the premium-to-mass spectrum, each facing distinct pressure from live-streaming commerce margin compression and regulatory compliance investment requirements.
| Leading Market Players |
|---|
| Richemont |
| Guangdong Xuping Jewelry |
| LVMH Moët Hennessy Louis Vuitton |
| Swarovski Group |
| Wuzhou Zuanfa Jewelry |
| Pandora |
| Signet Jewelers |
| Tiffany & Co |
| Chow Tai Fook Jewellery Group |
| Others |
Supply Flow & Price Mechanics
Gold bullion procurement costs cascade from PBOC import quota allocations through foundry fabrication tiers to retail markup structures, with certified 24K bridal pieces commanding premium positioning over uncertified alloy alternatives in Shanghai and Beijing.
Pricing Analysis
After-sales authentication and GB 11887 certification bundling separate premium-tier Chow Tai Fook bridal sets from unbundled mass-market silver pieces. Three-tier pricing structure across heritage luxury, certified national chains, and vertically integrated foundries reflects hallmark compliance investment and craftsperson wage premiums. Price erosion runs through mid-market alloy segments as Guangdong labor costs escalate and live-streaming hosts compress wholesale markups. Corporate gifting buyers in Beijing exhibit lowest price sensitivity, while tier-three city fashion jewellery purchasers drive volume at economy positioning.
Supply Chain Analysis
Regional distribution centers in Guangdong's Panyu and Shunde clusters feed hub-and-spoke patterns into Shanghai and Beijing luxury retail corridors. Raw material sourcing draws from PBOC-monitored gold import channels, rough diamond inflows under NGTC oversight, and recycled precious metal streams from domestic collection networks. Single-source vulnerability concentrates in master craftsperson talent for jade carving and micro-pavé settings. Distribution runs through vertically integrated foundry-to-retail operators, wholesale trading floors, and direct-to-consumer live-streaming studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation accelerates as SAMR hallmarking enforcement raises compliance fixed costs beyond smaller fabricator capacity, eliminating uncertified competitors from bridal and investment-grade segments.
For Market Incumbents: Anchor market position through backward integration into renewable-powered electroplating facilities that qualify for MEE preferential permitting. Secure exclusive craftsperson training pipelines with cultural ministry heritage subsidies to offset generational skill attrition. Defensive priority rests on blockchain-traceable supply chain documentation investment ahead of expanded GB standards thresholds. For New Entrants and Emerging Players: Crypto-native collectors seeking blockchain-authenticated provenance records represent the most penetrable buyer archetype with limited incumbent saturation. White-space concentration appears in Chengdu and Xi'an omnichannel infrastructure, where disposable income growth outpaces certified retailer presence. Go-to-market execution should leverage Douyin live-streaming studios with exclusive product line revenue-sharing arrangements that bypass traditional wholesale structures. For Investors and Strategic Acquirers: PBOC gold import quota expansion announcements are the leading indicator that raw material access constraints will ease for scaled fabricators. Long-term viability favors vertically integrated foundry operators with captive electroplating capacity and dual carbon policy alignment. Acquisition screening should prioritize targets with SAMR pre-certified hallmarking infrastructure and western China distribution footprint.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Craft Certification Investment | Cultural ministry subsidies for filigree and enamel techniques create differentiated positioning against mass-produced imports. |
| Blockchain Supply Chain Integration | GB standards mandate traceable documentation for gold products above specified thresholds, requiring foundry system retrofit. |
| Western China Omnichannel Expansion | Chengdu and Xi'an exhibit underdeveloped luxury infrastructure relative to income growth, rewarding early entrants. |
| Live-Streaming Commerce Studio Buildout | Douyin and Kuaishou hosts compress traditional retail margins while expanding reach into tier-three and tier-four cities. |
| Renewable-Powered Electroplating Transition | Dual carbon policy alignment qualifies fabricators for preferential MEE permitting and state procurement consideration. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary fieldwork incorporated structured interviews with jewellery foundry operations managers, SAMR compliance officers, live-streaming commerce platform executives, and tier-one city retail procurement directors. Secondary validation drew from PBOC gold flow disclosures, MEE electroplating facility permits, GB standards revision drafts, and China Gold Association production statistics. Bottom-up fabrication capacity estimates triangulated against top-down retail transaction value assessments.
Segmentation-level modeling tracked karat purity tiers, end-user demographic cohorts, sales channel economics, and design style positioning across the projection horizon. CAGRs were derived from time-series analysis of foundry output volumes, import quota utilization rates, and digital channel penetration trajectories. Industry-specific forecast inputs included generational wealth transfer patterns among millennial and Gen-Z consumers, plus live-streaming host commission structure evolution.
Revisions become necessary when PBOC adjusts gold import quota allocations, SAMR expands blockchain documentation thresholds, or MEE tightens electroplating wastewater discharge standards beyond current dual carbon baselines. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and digital channel adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Diamond Jewelry Market
Jewelry
Demi-Fine Jewelry Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Artificial Jewellery Market
Jewelry
Wedding Rings Market
Jewelry
Customized Jewelry Market
Jewelry
South Africa Luxury Jewelry Market
Jewelry
Qatar Jewelry Market
Jewelry
Global Gems and Jewelry Market
Jewelry
South Korea Luxury Jewelry Market
Jewelry
Jewelry Cleaners Market
Jewelry
Jewellery Box Market
Jewelry
Mexico Luxury Jewelry Market
Jewelry
Pearl Jewelry Market
Jewelry
Bead Products Market
Jewelry
Canada Luxury Jewelry Market