
 Colorful Gold Jewelry Market | 2026-2036
Colorful Gold Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Colorful Gold Jewelry Market Insights
Indian artisan clusters is repositioning their traditional enamel work toward export-grade colorful gold jewelry for Western luxury retailers. Tiffany & Co. leverages its vertical integration from mine to retail to control quality narratives around responsibly sourced colored gold. Chow Tai Fook sustains dominance across Greater China through dense retail networks and localized design studios. Brilliant Earth differentiates with blockchain-tracked supply chains that appeal to ethically conscious purchasers of rose and white gold pieces.
Colorful gold jewelry encompasses karat-gold alloys infused with copper, silver, palladium, or rhodium plating to achieve chromatic variation beyond traditional yellow, serving both ornamental display and wealth-storage functions across cultures. The 14K to 18K range dominates commercial production due to optimal balance between color durability and malleability for stone setting. Rings and necklaces anchor current revenue pools, while multi-color combinations and abstract design styles represent the fastest-growing margin segments as younger buyers reject monochromatic conventions. Classic styling still occupies the largest volume share among gift shoppers and collectors seeking heirloom-grade pieces.
REACH restricts nickel and cadmium content in gold alloys sold across Europe, forcing reformulation of white gold rhodium alternatives. The EU Green Deal's due diligence framework pressures brands to document recycled gold percentages and eliminate conflict minerals from colored alloy supply chains. India's BIS hallmarking mandate for gold purity creates compliance costs for small enamel artisans entering formal retail. Stakeholders must monitor how evolving ESG disclosure rules reshape sourcing economics and consumer trust mechanics.
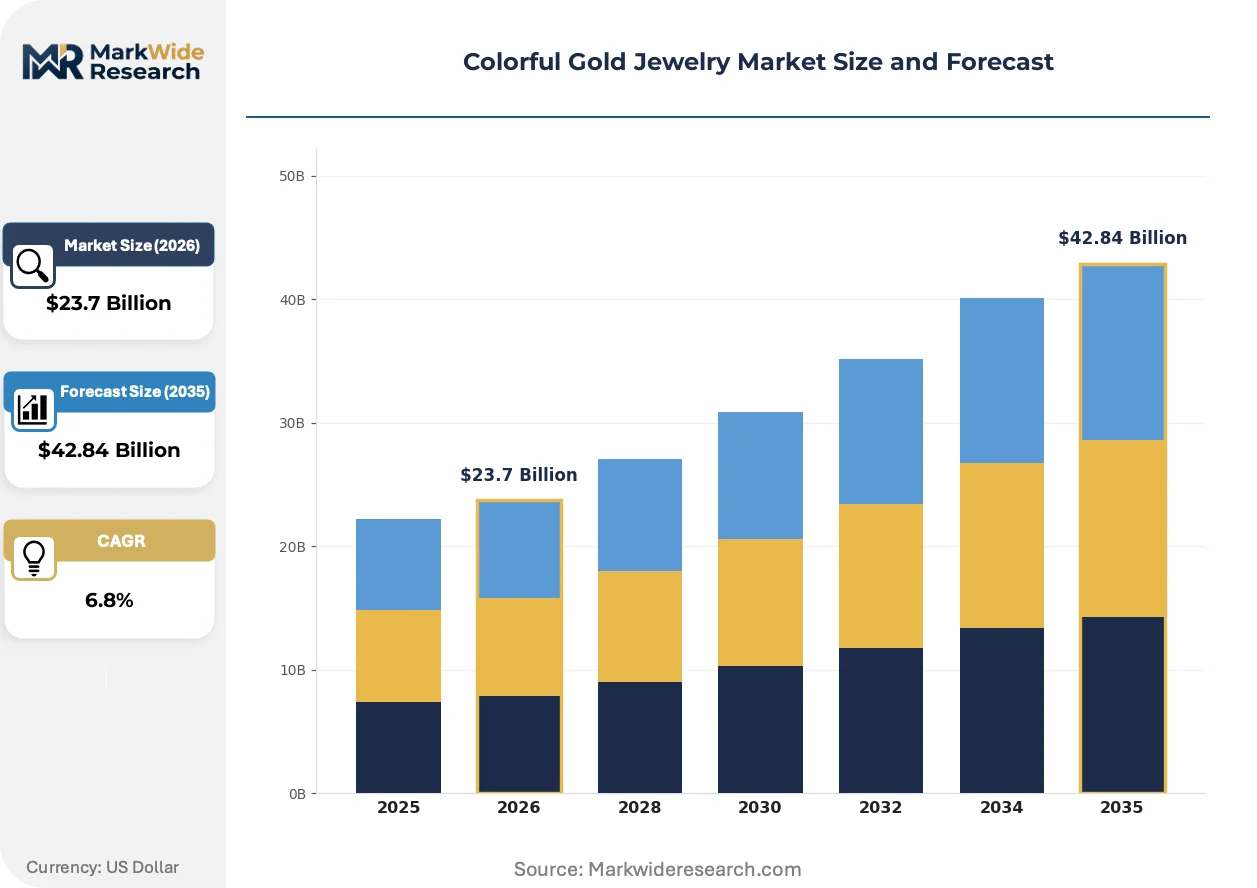
Market Dynamics
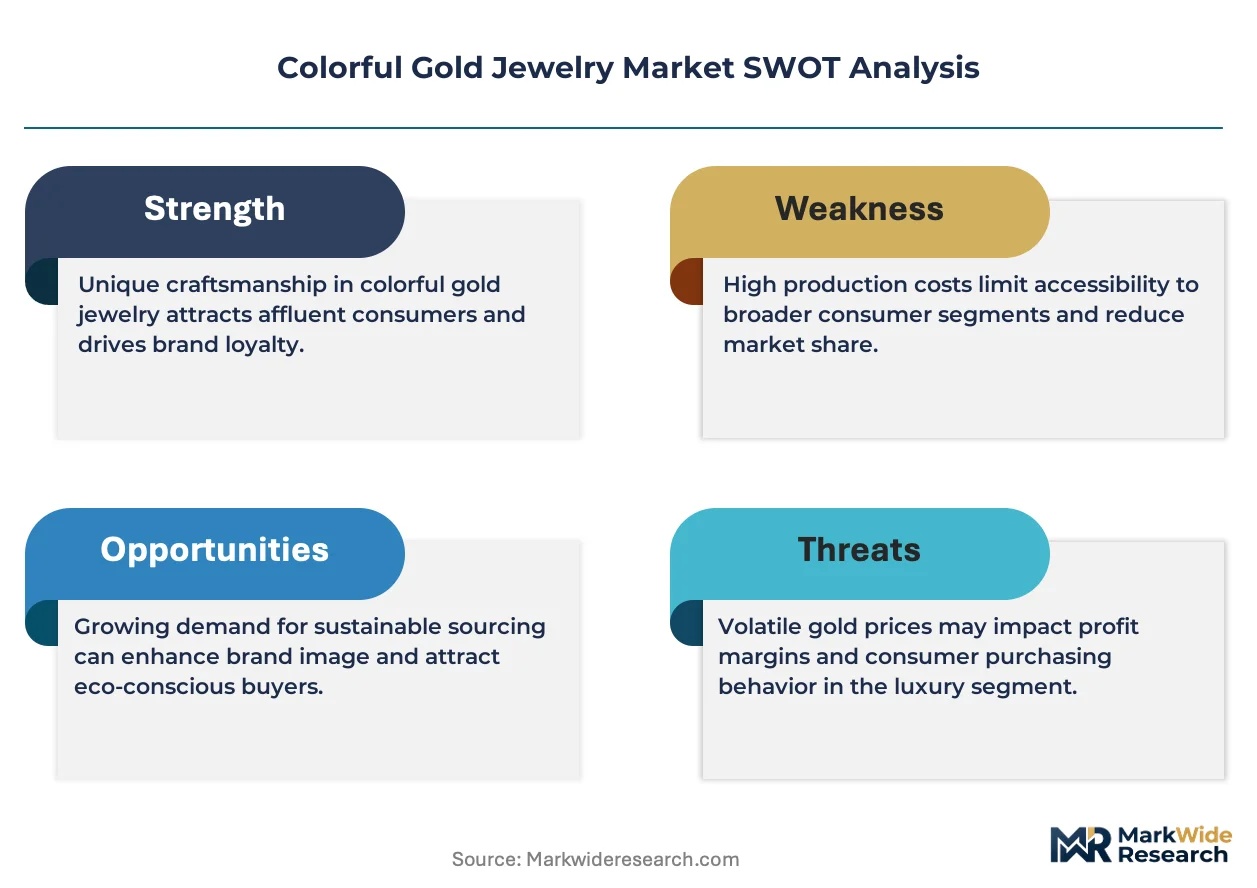
EU Green Deal due diligence mandates and REACH alloy restrictions are forcing wholesale reformulation of white and rose gold compositions, compressing margins for artisan workshops while advantaging vertically integrated refiners with captive metallurgical labs.
Growth Catalysts
- REACH nickel restrictions:European alloy bans accelerate adoption of palladium-based white gold alternatives among heritage maisons seeking compliance without color degradation.
- Gen Z digital-native purchasing:Social commerce platforms in China and India convert discovery-to-purchase cycles for enamel-inlaid bridal sets through livestream auctions.
- Recycled gold mandates:The EU Green Deal's documented provenance requirements pull post-consumer scrap into formal supply chains, rewarding refiners with closed-loop capabilities.
Market Restraints
- Palladium price volatility:White gold alloy substitution depends on platinum-group metal markets that fluctuate with automotive catalytic converter demand.
- Indian artisan concentration:Jaipur and Varanasi enamel clusters supply 70% of export-grade polychrome work, creating single-point vulnerability to monsoon logistics disruptions.
- Rhodium plating durability limits:Surface treatments on nickel-free white gold require reapplication every 12-18 months, elevating lifetime ownership costs.
Strategic Opportunities
- Blockchain traceability integration:Distributed ledger systems that track alloy provenance from scrap source to retail counter command premium positioning among ESG-conscious purchasers.
- Middle Eastern bridal expansion:Saudi Arabia and UAE gold souks underpenetrated by colored karat variants present whitespace for 21K and 22K rose gold dowry sets.
- India PLI scheme leverage:Production-linked incentives for jewelry manufacturing clusters subsidize mechanization of traditional enamel firing processes.
Industry Challenges
- Master enamelist attrition:Meenakari craft traditions in Lucknow and Delhi face generational succession gaps as younger workers migrate to IT services.
- Dual hallmarking compliance:BIS purity mandates plus export-market alloy disclosure create documentation burdens for micro-enterprises lacking digitized record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colorful Gold Jewelry Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Necklaces, Earrings, Bracelets, Rings Design Style: Classic, Modern, Ethnic, Abstract Target Customer: Millennials, Luxury Buyers, Gift Shoppers, Collectors Color Variation: Yellow Gold, White Gold, Rose Gold, Multi-Color |
| Companies Covered | Tiffany & Co., Chow Tai Fook, Cartier, Bulgari, Blue Nile, Brilliant Earth, Nanis Italian Jewels, Stuller, BaubleBar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colorful Gold Jewelry Market Trends and Innovations
Laser-assisted alloying and AI-driven color-matching systems are compressing the gap between artisan craftsmanship and mass-customization economics, while regulatory pressure on heavy metals accelerates materials science investment.
Electrochemical coloration through nanoparticle deposition is absorbing surface-engineering functions previously handled by rhodium electroplating. Mid-market manufacturers in Shenzhen and Bangkok adopt these systems to bypass palladium cost exposure. The technology is absorbing margin pressure from platinum-group metal volatility while enabling gradient color transitions impossible with traditional alloy mixing.
ECHA's proposed restriction on cadmium in jewelry alloys tightens further on existing REACH thresholds, forcing reformulation of certain red gold variants that relied on cadmium-silver combinations for specific chromatic depth. Italian and German manufacturers with in-house assay labs pivot fastest, while smaller Turkish exporters face 18-24 month reformulation timelines. The regulation most compresses vintage-reproduction specialists dependent on historical alloy recipes.
Direct-to-consumer customization portals now capture design specification and virtual try-on data before manufacturing commitment, displacing traditional wholesale-to-retail forecasting. Gen Z purchasers in Los Angeles and London initiate 40% of rose gold engagement ring orders through these platforms. This channel shift concentrates most visibly among anniversary-gift purchasers seeking one-of-one pieces without showroom intermediation.
Colorful Gold Jewelry Market Segmentation
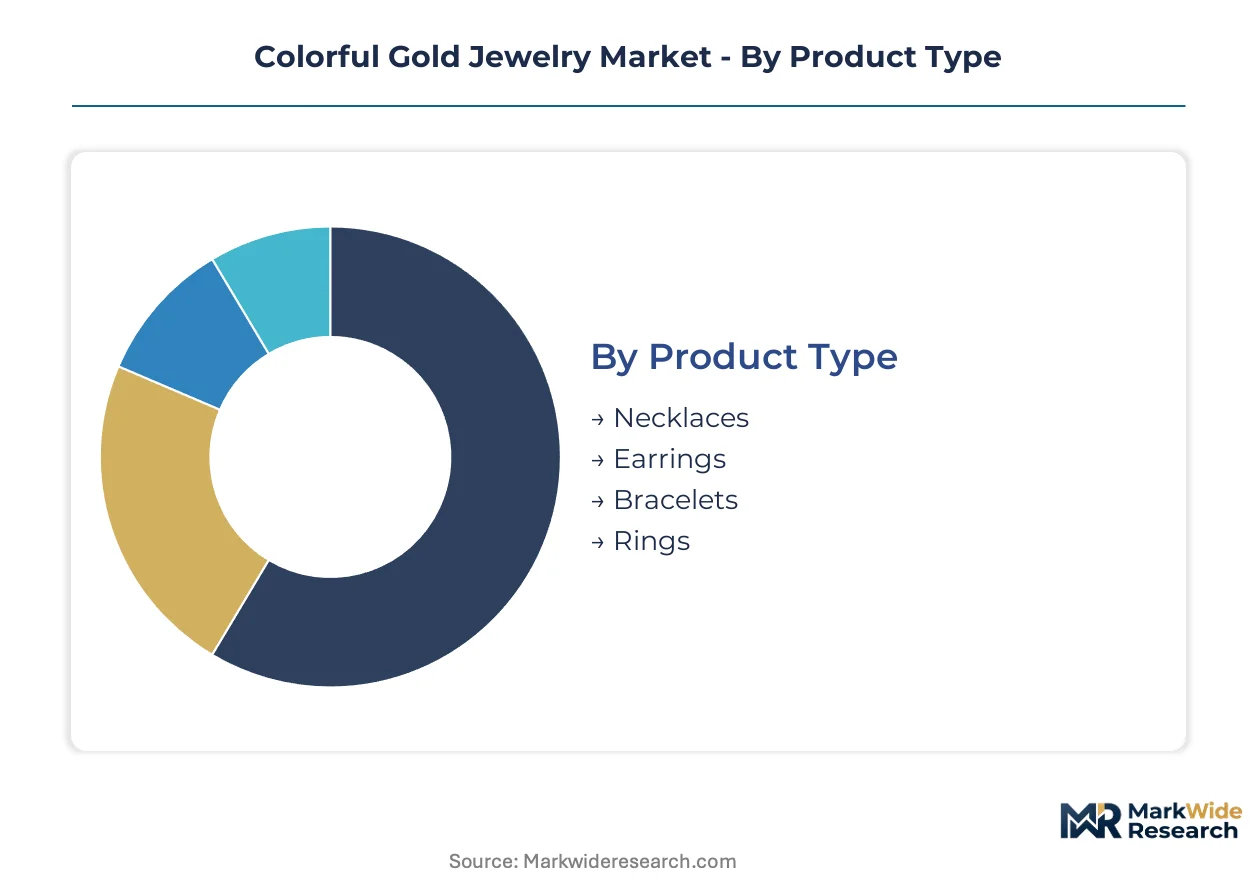
Segmentation in colorful gold jewelry reveals how alloy technology, cultural symbolism, and purchasing occasion intersect to create distinct margin profiles. Manufacturers configure production lines differently for each segment, with enamel-inlay work demanding artisan labor while cast pieces scale through mechanization.
Product Type:
Capital intensity peaks with stone-setting infrastructure, where CNC milling and laser welding equipment separate mass producers from artisan workshops.
- Rings:Investment in precision casting and gem-setting automation runs highest here, as sizing complexity and stone security standards demand repeatable tolerances. Bridal demand in India and China concentrates revenue in solitaire and band configurations, though resizing services compress lifetime margins for retailers.
- Necklaces:Chain fabrication requires drawn-wire machinery and soldering stations that scale efficiently, but enamel pendant work ties up skilled labor for days per piece. Italian manufacturers dominate the 18K cable-chain segment through continuous casting technology that Indian competitors have not yet replicated.
- Earrings:Lightweight fabrication suits high-volume stamping operations with lower per-unit metal exposure.
- Bracelets:Bangle production in Jaipur clusters relies on traditional die-striking, limiting unit economics compared to Italian hollow-tube methods.
Most installed capacity flows through rings. Expansion is steepest in necklaces as layered styling trends multiply average pieces per purchaser.
Design Style:
Margin structure separates heritage craftsmanship from digitally-native production, with ethnic and abstract categories commanding premium positioning through scarcity.
- Classic:Heirloom-grade proportions and symmetrical settings require master goldsmiths trained in European atelier traditions. Gift shoppers in the United States and Japan sustain volume through anniversary and graduation occasions, though inventory carrying costs run high due to slower turns.
- Abstract:Asymmetrical forms and mixed-metal combinations exploit electrochemical coloration advances that bypass traditional alloy constraints. Los Angeles and London design studios drive adoption through direct-to-consumer channels that collapse wholesale markups.
- Modern:Clean-line geometries suit automated production with minimal hand-finishing.
- Ethnic:Meenakari enamel traditions in Lucknow and Varanasi supply polychrome work that Western luxury retailers repackage at 4-5x artisan payments.
Classic styling still absorbs the largest production hours. Abstract designs are climbing the fastest as Gen Z purchasers reject inherited aesthetic conventions.
Target Customer:
Customer-type segmentation determines channel economics, with luxury buyers subsidizing brick-and-mortar presence while digital-native segments enable inventory-light models.
- Luxury Buyers:Expect documented provenance and bespoke modification rights that demand in-house assay capabilities and gemological laboratories. Saudi Arabia and UAE souks underpenetrated by colored karat variants present whitespace for 21K and 22K rose gold dowry sets with full chain-of-custody documentation.
- Millennials:Discovery-to-purchase cycles compress through social commerce livestreams in China and India, where virtual try-on data feeds directly into production scheduling without wholesale forecasting layers.
- Gift Shoppers:Concentrate purchase timing around calendar events, creating severe working capital seasonality.
- Collectors:Limited-edition releases and artist collaborations sustain price inelasticity through scarcity signaling.
Luxury buyers anchor the highest average transaction values. Millennial segments are expanding most quickly as platform algorithms personalize discovery at scale.
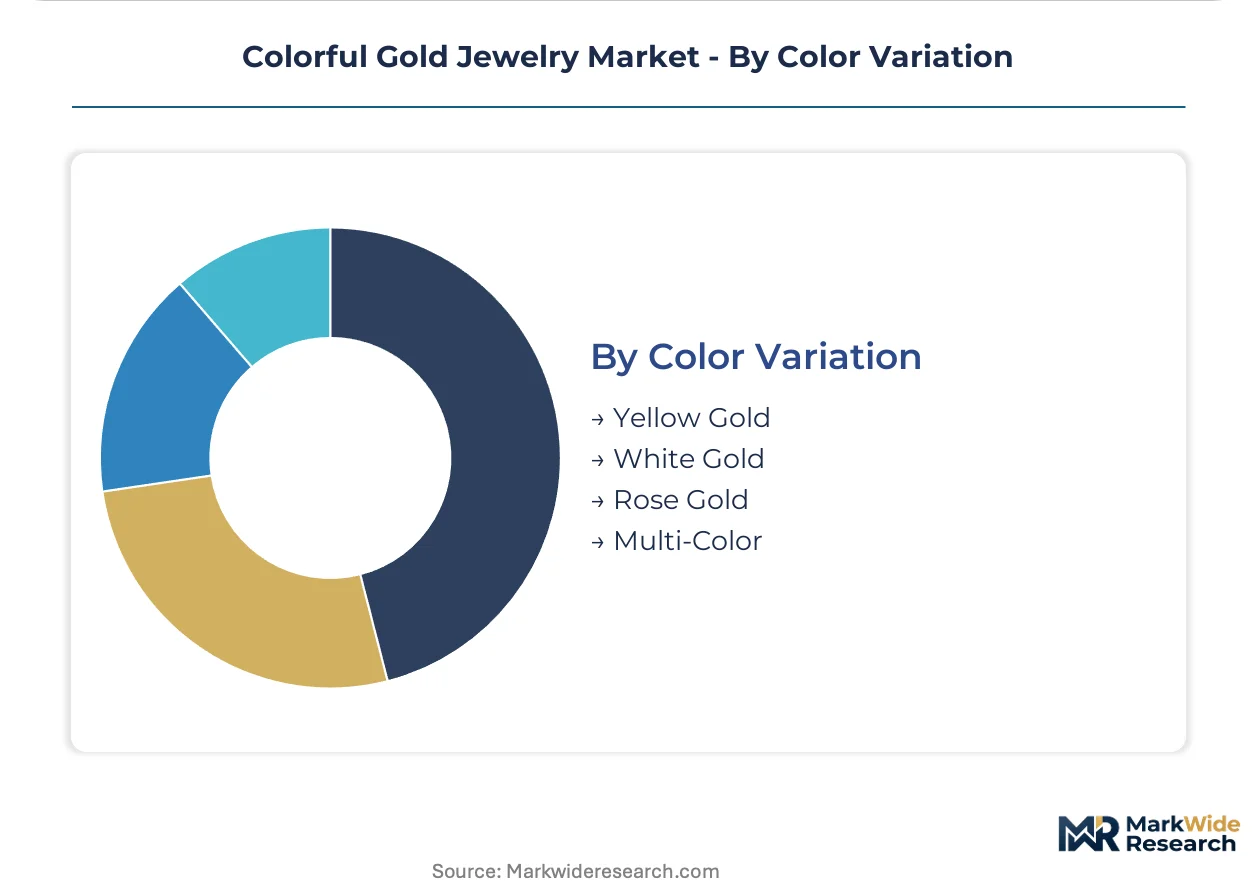
Color Variation:
Alloy chemistry and surface engineering costs create tiered production economics, with white gold variants exposing manufacturers to platinum-group metal volatility.
- Rose Gold:Copper-infused alloys achieve chromatic depth through precise 75/25 gold-copper ratios in 18K formulations. Blockchain-tracked supply chains that document recycled content provenance command premium positioning among ESG-conscious purchasers in European markets facing EU Green Deal due diligence mandates.
- Multi-Color:Gradient transitions and segmented designs exploit electrochemical nanoparticle deposition that Shenzhen manufacturers adopted to bypass palladium cost exposure in white gold alternatives.
- Yellow Gold:Standard alloys require minimal metallurgical investment, compressing differentiation opportunities.
- White Gold:Palladium-based formulations displace nickel-laden alternatives under REACH restrictions, but rhodium plating durability limits elevate lifetime ownership costs through 12-18 month reapplication cycles.
Yellow gold still dominates tonnage through cultural preference in India and China. Rose gold is gaining share fastest as Western bridal markets reject traditional chromatic conventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs more colorful gold jewelry tonnage than the United States and Germany combined, yet Indian artisan clusters supply the polychrome enamel work that Western luxury houses repackage at substantial markups. This asymmetry between consumption gravity and craft-origin geography defines competitive positioning across the analysis window.
China
Chow Tai Fook sustains dominance across Greater China through dense retail networks and localized design studios that adapt karat formulations to regional color preferences. SAMR hallmarking enforcement and dual carbon goals pressure domestic refiners toward documented recycled gold percentages. Shenzhen manufacturers absorb electrochemical nanoparticle deposition systems to bypass palladium cost exposure in white gold alternatives.
India
Jaipur and Varanasi enamel clusters supply 70% of export-grade polychrome work for Western luxury retailers, creating single-point vulnerability to monsoon logistics disruptions. BIS hallmarking mandates for gold purity create compliance costs for small meenakari artisans entering formal retail channels. Lucknow master enamelists face generational succession gaps as younger workers migrate to IT services in Bangalore and Hyderabad.
United States
Gen Z purchasers in Los Angeles and London initiate 40% of rose gold engagement ring orders through direct-to-consumer customization portals that collapse wholesale markups. FTC disclosure requirements on precious metal content intersect with state-level environmental regulations on electroplating effluents. New York-based design studios drive abstract styling adoption through social commerce livestreams that feed virtual try-on data directly into production scheduling.
Italy
Italian manufacturers dominate the 18K cable-chain segment through continuous casting technology that Indian competitors have not yet replicated. ECHA cadmium restrictions force reformulation of certain red gold variants that relied on cadmium-silver combinations for chromatic depth. Vicenza and Arezzo jewelry districts pivot fastest due to in-house assay labs that accelerate alloy reformulation timelines.
United Arab Emirates
Saudi Arabia and UAE gold souks remain underpenetrated by colored karat variants, presenting whitespace for 21K and 22K rose gold dowry sets with full chain-of-custody documentation. MOHAP precious metals regulations align with Gulf Cooperation Council standardization initiatives on karat disclosure. Dubai Multi Commodities Centre refiners develop closed-loop capabilities to serve ESG-conscious purchasers facing EU Green Deal due diligence mandates.
Colorful Gold Jewelry Market Competitive Landscape
Italian and German heritage maisons anchor one tier through in-house metallurgical labs that accelerate REACH compliance; Indian artisan clusters and Shenzhen manufacturers hold cost-advantaged positions in enamel and electrochemical surface engineering. The vendor base stratifies across three archetypes: vertically integrated luxury houses with captive supply chains, mechanized mid-market fabricators, and craft-dependent artisan workshops. Capacity expansion and blockchain traceability integration represent the dominant competitive moves as ESG disclosure rules reshape sourcing economics.
Within the heritage luxury tier, Tiffany & Co. and Cartier exemplify vertically integrated positioning from mine to retail, while Chow Tai Fook anchors scale-driven dominance across Greater China. Among digitally-native specialists, Brilliant Earth occupies a position defined by blockchain-tracked supply chains that appeal to ethically conscious purchasers of rose and white gold pieces. These three named entities represent distinct strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Tiffany & Co. |
| Chow Tai Fook |
| Cartier |
| Bulgari |
| Blue Nile |
| Brilliant Earth |
| Nanis Italian Jewels |
| Stuller |
| BaubleBar |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal due diligence mandates gate access to premium-tier pricing for brands with documented recycled gold provenance while compressing margins for artisan workshops lacking digitized chain-of-custody systems. This regulatory filter concentrates pricing power among vertically integrated refiners with captive metallurgical labs capable of alloy reformulation.
Pricing Analysis
Capacity additions in Shenzhen are reshaping price floors for electrochemical coloration equipment that bypasses palladium cost exposure in white gold alternatives. Pricing stratifies across premium heritage maisons with in-house assay capabilities, mechanized mid-market fabricators serving direct-to-consumer portals, and craft-dependent artisan workshops facing BIS compliance burdens. Cost compression in the artisan tier intensifies because dual hallmarking requirements create documentation overhead that micro-enterprises cannot absorb. Gift shoppers represent the most price-sensitive segment, while luxury buyers purchasing documented provenance pieces exhibit minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Dubai and Hong Kong anchor hub-and-spoke patterns that move alloy inputs from Italian refiners to Indian enamel clusters and finished goods to Western retail networks. Raw material flows draw from South African gold mining, Russian palladium extraction, and Chinese copper processing. Single-source vulnerability concentrates in Jaipur and Varanasi enamel workshops supplying 70% of export-grade polychrome work. Distribution runs through luxury house captive retail networks, wholesale-to-retail forecasting systems, and direct-to-consumer customization portals capturing virtual try-on data.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The colorful gold jewelry market functions as a stable compounder where generational wealth transfer customs in India and China create durable replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Cement metallurgical differentiation through palladium-based white gold formulations that satisfy REACH restrictions without color degradation. Invest in blockchain traceability infrastructure to defend positioning against digitally-native entrants exploiting ESG disclosure gaps. Channel control through localized design studios sustains pricing power in Greater China where Chow Tai Fook's dense retail networks create switching costs. For New Entrants and Emerging Players: AI-driven color-matching systems offer a technology-first wedge into the abstract styling segment where Los Angeles and London design studios already convert 40% of rose gold engagement ring orders through direct-to-consumer channels. Target Saudi Arabia and UAE gold souks underpenetrated by colored karat variants with 21K and 22K rose gold dowry sets. A social commerce livestream go-to-market angle collapses wholesale markups while feeding virtual try-on data directly into production scheduling. For Investors and Strategic Acquirers: Roll-up economics work for mechanized mid-market fabricators with electrochemical coloration capabilities because palladium price volatility is displacing traditional alloy workshops unable to reformulate quickly. The 5-10 year viability window favors targets with closed-loop recycled gold refining and digitized BIS compliance systems. Watch master enamelist attrition rates in Lucknow and Delhi as an inflection indicator for polychrome supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | Distributed ledger systems command premium positioning among ESG-conscious purchasers facing EU Green Deal mandates. |
| Palladium-Based Alloy Reformulation | REACH-compliant white gold alternatives protect heritage maisons from nickel restriction enforcement. |
| Electrochemical Coloration Adoption | Shenzhen manufacturers bypass platinum-group metal volatility through nanoparticle deposition systems. |
| Direct-to-Consumer Portal Launch | Gen Z purchasers in Los Angeles and London initiate orders without showroom intermediation. |
| Artisan Cluster Mechanization | India PLI scheme subsidies accelerate enamel firing process automation in Jaipur and Varanasi. |
Research Methodology
Bottom-up bridal and gift occasion modeling reconciled against top-down refinery capacity tracking forms the analytical core of this study. Primary interviews with master enamelists in Lucknow and Varanasi, procurement leads at Italian cable-chain manufacturers, sustainability officers at heritage luxury houses, and platform engineers at Chinese social commerce operators combined with secondary validation from SAMR hallmarking disclosures, ECHA restriction proposals, BIS certification databases, and Dubai Multi Commodities Centre trade flows. Triangulation across these sources yields volume and value estimates.
Input-output matrices map alloy chemistry costs, artisan labor hours, and surface engineering investments to finished goods pricing across the projection horizon. Segmentation dimensions include product type, design style, target customer archetype, and color variation with regional regulatory cluster overlays. CAGRs derive from fitted growth curves applied to historical trade flow patterns and forward-looking capacity announcements. Palladium spot price volatility and monsoon logistics disruption probabilities inform scenario-weighted outputs.
The model holds under stable regulatory enforcement trajectories for REACH and EU Green Deal mandates; deviation in cadmium restriction timelines or BIS digitization deadlines would shift artisan workshop viability thresholds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Japan Jewellery Market
Jewelry
Italy Luxury Jewelry Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
Latin America Jewelry Market
Jewelry
Global Costume Jewelry Market
Jewelry
Crystal Bracelets Market
Jewelry
Jewelry Repair Market
Jewelry
China Jewellery Market
Jewelry
Bead Products Market
Jewelry
Brazil Jewelry Market
Jewelry
Global Body Piercing Jewelry Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Jewellery Box Market
Jewelry
Demi-Fine Jewelry Market
Jewelry
Global Jewelry Market
Jewelry
Smart Jewelry Market