
 Artificial Jewellery Market | 2026-2036
Artificial Jewellery Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Jewellery Market Insights
Aftermarket repair and customization revenue is fragmenting across independent artisans, brand-certified workshops, and direct-to-consumer DIY kits. Swarovski Group leverages its crystal-cutting heritage to sustain premium positioning in bridge jewelry. PANDORA A/S anchors its growth through charm-system ecosystems that lock in repeat purchases. BaubleBar Inc. competes on velocity, dropping trend-responsive designs weekly through controlled digital channels.
Artificial jewellery denotes non-precious ornamental accessories fabricated from base metals, synthetic crystals, plated alloys, molded resins, and glass composites, typically electroplated or lacquer-coated to simulate precious materials at mass-market price points. Necklaces and earrings dominate unit volume, though rings command higher per-piece margins due to sizing complexity and metal-weight thresholds. Plastic and resin formulations expand fastest among materials, driven by lightweight comfort demands and hypoallergenic positioning for sensitive skin segments.
REACH nickel-release limits and California Proposition 65 labeling requirements constrain formulation choices and elevate compliance costs for cross-border suppliers. The EU Green Deal's circular economy action plan pressures brands to disclose recycled-content percentages and establish take-back infrastructure. Stakeholders must monitor evolving chemical-restriction schedules and decide between reformulation investments versus geographic market exclusion.
Market Dynamics
The artificial jewellery sector faces acute pressure from REACH nickel-release limits and California Proposition 65 mandates, which force simultaneous reformulation of base-metal alloys and expansion of compliant supply networks across multiple continents.
Growth Catalysts
- Festival Gifting Density:India's concentrated bridal and festival calendar sustains predictable volume spikes that justify dedicated production lines and inventory pre-positioning.
- Lightweight Resin Formulations:Advances in molded polymer composites address hypoallergenic positioning for sensitive-skin consumer segments while reducing shipping costs.
- EU Green Deal Circular Economy Mandates:Disclosure requirements for recycled-content percentages create first-mover advantages for suppliers with established take-back infrastructure.
Market Restraints
- Input Cost Volatility:Rhodium and palladium plating materials experience price swings that compress margin buffers for mid-tier electroplated products.
- Supply Concentration Risk:Crystal-cutting and precision-molding capabilities cluster in specific manufacturing corridors, creating single-source vulnerabilities.
- Substitution Threat:Lab-grown diamond jewellery at declining price points captures consumers seeking perceived authenticity without precious-metal premiums.
Strategic Opportunities
- Underpenetrated Secondary Cities:Tier-2 and Tier-3 urban centers in India present whitespace for organized retail formats with localized design adaptation.
- Direct-to-Consumer Digital Channels:Controlled weekly drops through owned platforms enable trend-responsive inventory turns without wholesale margin dilution.
- Technology Convergence:Integration of augmented reality try-on tools with social commerce platforms reduces return rates for size-sensitive categories like rings.
Industry Challenges
- Compliance Timeline Compression:Evolving chemical-restriction schedules force simultaneous multi-market reformulation with limited testing window overlap.
- Skill Scarcity in Precision Plating:Electroplating technicians with expertise in sub-micron thickness control remain concentrated in legacy manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Jewellery Market |
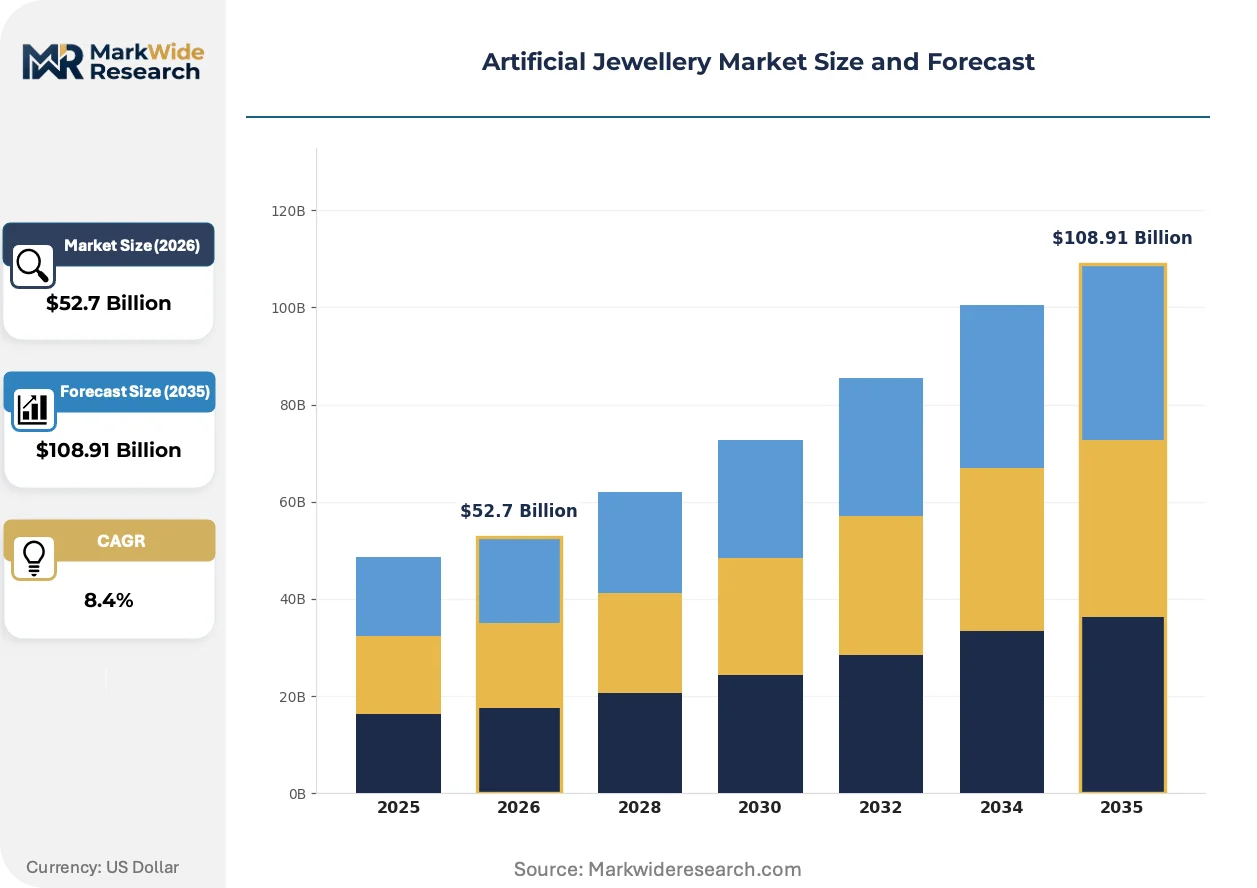
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Necklaces, Earrings, Bracelets, Rings Material: Plastic, Metal Alloy, Glass, Resin Sale Channel: Online Retail, Specialty Stores, Department Stores, Craft Fairs End User: Women, Men, Children, Fashion Enthusiasts |
| Companies Covered | Swarovski Group, PANDORA A/S, LVMH Moët Hennessy Louis Vuitton, Chanel S.A., Gianni Versace S.p.A., H & M Hennes & Mauritz AB, Gucci Group NV, The Colibri Group, BaubleBar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Jewellery Market Trends and Innovations
Material science advances and regulatory disclosure mandates are reconfiguring how artificial jewellery is formulated, certified, and brought to market across divergent regional standards.
Biocompatible resin compounds are migrating from medical-device applications into consumer accessories. Dermatology-sensitive millennials in North American and European markets are adopting these formulations at accelerating rates. This shift is compressing demand for nickel-bearing base metals in the bridge-jewellery tier and forcing electroplaters to diversify coating portfolios.
REACH nickel-release limits and the EU Green Deal's circular economy action plan now require granular recycled-content documentation. European brands must establish auditable take-back infrastructure or face market exclusion. Small-batch artisans and mass-market suppliers alike are reconfiguring supply chains to capture pre-consumer scrap from casting operations.
Social commerce integration is collapsing traditional wholesale-retail boundaries. Influencer-curated drops on TikTok Shop and Instagram Checkout are displacing department-store jewelry counters for trend-responsive purchases. This pattern concentrates in Southeast Asian and Latin American markets where mobile-first purchasing dominates accessory categories.
Artificial Jewellery Market Segmentation
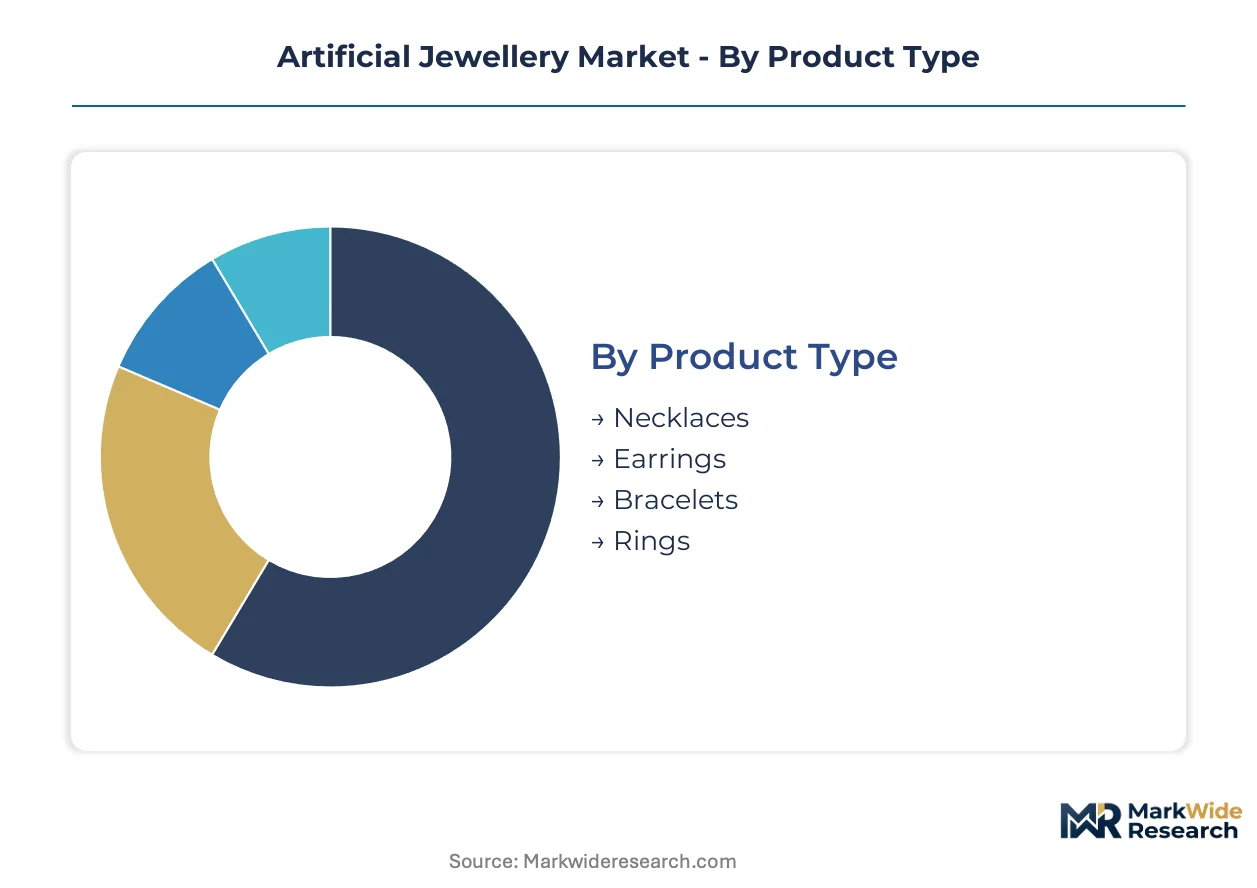
Segmentation in artificial jewellery reveals divergent margin profiles and service intensity requirements across product categories. Repair frequency, sizing complexity, and material durability vary substantially, reshaping how suppliers configure warranty programs and aftermarket support infrastructure.
Product Type:
After-sales-service intensity escalates with structural complexity and wear-pattern exposure across ornamental categories.
- Necklaces:Chain-link stress points and clasp mechanisms generate the highest return-for-repair rates among all product types. Bridal and festival gifting clusters in India concentrate demand for heavy-set statement pieces with intricate pendant attachments that require periodic soldering maintenance.
- Earrings:Post-bending and butterfly-back replacement dominate service tickets, though unit-level margins absorb these costs more easily than necklace repairs. Hypoallergenic coating degradation drives replacement cycles among dermatology-sensitive consumer segments in European markets governed by REACH nickel-release limits.
- Bracelets:Hinge and snap-closure failures concentrate service demand in expandable bangle formats popular across South Asian youth demographics.
- Rings:Sizing adjustments and stone resetting generate artisan-dependent service revenue, with rhodium replating required for white-metal finishes.
By volume, Necklaces leads. By growth pace, Rings is ahead.
Material:
Cost tier stratification separates premium-positioned formulations from mass-market commodity inputs.
- Plastic:Injection-molded acrylics and thermoplastic elastomers enable sub-dollar unit economics with minimal finishing labor. Fast-fashion retailers in Southeast Asian markets exploit this cost floor for weekly trend-responsive drops with compressed margin tolerance.
- Metal Alloy:Zinc-based die-cast substrates with electroplated overlays dominate bridge-jewellery positioning. REACH compliance costs and nickel-release testing burden European-bound production lines, forcing supplier consolidation toward certified plating facilities.
- Glass:Czech and Chinese crystal-cutting clusters supply precision-faceted components for mid-tier statement pieces.
- Resin:Biocompatible polymer formulations are expanding most quickly, capturing dermatology-sensitive millennials in North America with lightweight comfort positioning.
By installed base, Metal Alloy dominates. By volume trajectory, Resin is gaining share fastest.
Sale Channel:
Customer-type differentiation separates impulse purchasers from deliberate gift buyers across channel formats.
- Online Retail:Controlled digital channels enable weekly inventory turns without wholesale margin dilution. Augmented reality try-on tools reduce return rates for size-sensitive ring purchases among mobile-first demographics.
- Specialty Stores:Staff-assisted fittings and immediate resizing services justify premium pricing for occasion-driven purchases.
- Department Stores:Foot traffic dependency concentrates in aging retail corridors with declining relevance for trend-responsive accessories.
- Craft Fairs:Direct artisan-consumer relationships support customization premiums and limited-batch exclusivity positioning.
By transaction velocity, Online Retail leads. By margin retention, Craft Fairs sustains the steepest expansion trajectory.
End User:
Application context separates self-purchase occasions from gift-giving rituals with divergent price elasticity profiles.
- Women:Self-adornment and social signaling drive the broadest category penetration across age cohorts. Festival calendar density in India sustains predictable volume spikes for gold-tone bridal alternatives.
- Men:Chain-link necklaces and signet-ring formats concentrate demand, with minimalist styling preferences limiting SKU proliferation requirements.
- Children:Safety-clasp mandates and breakage-tolerant material specifications constrain design freedom.
- Fashion Enthusiasts:Collector behaviors and social-media-driven trend adoption generate the shortest replacement cycles and highest cross-category purchase frequency.
By absolute volume, Women leads. By purchase frequency, Fashion Enthusiasts is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crystal-cutting and precision-molding capabilities cluster in specific manufacturing corridors across India, China, Austria, and the Czech Republic. These production nodes feed distribution networks that span bridal markets in South Asia, fast-fashion retail in Western Europe, and direct-to-consumer digital channels in North America.
India
Bridal occasions and festival gifting sustain the highest absolute volume globally, with concentrated demand spikes around Diwali and wedding seasons. BIS certification mandates for base-metal jewellery impose testing burdens on domestic manufacturers and importers alike. Mumbai and Surat house the densest concentrations of electroplating facilities and costume-jewellery exporters serving Gulf and North American markets.
China
Yiwu and Guangzhou drive mass-market injection-molded acrylic and zinc-alloy production for fast-fashion retailers worldwide. GB standards for nickel release and heavy-metal content are tightening ahead of potential alignment with REACH-equivalent frameworks. The Pearl River Delta retains dominant clustering in precision die-casting and automated electroplating lines.
United States
Fashion-forward millennials and Gen Z consumers propel trend-responsive purchasing through TikTok Shop and Instagram Checkout channels. California Proposition 65 labeling requirements force disclosure of cadmium and lead content in base-metal accessories. Los Angeles and New York City host the primary design studios and influencer-marketing agencies that coordinate weekly product drops.
Germany
REACH nickel-release limits and the EU Green Deal's circular economy mandates constrain formulation choices for bridge-jewellery suppliers serving European markets. ECHA enforcement actions against non-compliant imports are accelerating supplier consolidation toward certified plating facilities. Pforzheim maintains its historical concentration of precision metalworking and jewellery-manufacturing expertise.
Austria
Premium crystal-cutting heritage sustains positioning in bridge-jewellery tiers despite pressure from resin and polymer alternatives. EU Green Deal disclosure requirements for recycled-content percentages are driving investment in pre-consumer scrap recovery systems. Wattens remains the definitive global center for precision crystal manufacturing and cutting technology.
Artificial Jewellery Market Competitive Landscape
Premium heritage houses and velocity-driven digital natives split the market into divergent margin and turnover profiles. Consolidation pressure concentrates among mid-tier electroplated suppliers facing simultaneous REACH compliance costs and rhodium price volatility. Three archetypes dominate: crystal-heritage brands with cutting-technology moats, charm-system ecosystem builders locking in repeat purchases, and fast-fashion velocity players dropping trend-responsive designs weekly. Competitive moves center on geographic expansion into Indian tier-2 cities and backward integration into captive plating facilities.
Within the heritage-crystal tier, Swarovski Group anchors premium positioning through precision-cutting technology developed over decades. Among ecosystem-focused players, PANDORA A/S exemplifies the charm-system model that generates recurring revenue through collectible component architectures. On the digital-velocity vector, BaubleBar Inc. occupies a position defined by controlled-channel inventory turns and social-commerce integration. These three represent distinct strategic postures rather than direct substitutability.
| Leading Market Players |
|---|
| Swarovski Group |
| PANDORA A/S |
| LVMH Moët Hennessy Louis Vuitton |
| Chanel S.A. |
| Gianni Versace S.p.A. |
| H & M Hennes & Mauritz AB |
| Gucci Group NV |
| The Colibri Group |
| BaubleBar Inc. |
| Others |
Pricing and Supply Chain Analysis
Rhodium and palladium price volatility determines both the compression of margin buffers in mid-tier electroplated products and the geographic clustering of certified plating facilities that can absorb input cost swings. REACH nickel-release limits and California Proposition 65 mandates simultaneously elevate compliance expenditures and reshape supplier consolidation patterns across export-oriented manufacturing corridors.
Pricing Analysis
REACH nickel-release limits dictate the pricing tier structure across bridge-jewellery and mass-market segments. Three-tier pricing structure across premium, standard, and economy levels separates Swarovski-heritage crystal positioning from zinc-alloy die-cast commodities and injection-molded resin floor products. Price differentiation rests on certification-grade electroplating and dermatology-sensitive hypoallergenic coatings. Cost compression in rhodium-finished white-metal tiers is intensifying because of plating material price swings. Fast-fashion retailers in Southeast Asian markets exhibit the highest price sensitivity, while heritage-crystal brands serving European bridal segments maintain the lowest.
Supply Chain Analysis
Export-control restrictions on precision crystal-cutting technology limit flow concentration in Austrian and Czech manufacturing nodes. Geographic supply concentration centers on China for injection-molded acrylic and zinc-alloy die-casting, India for electroplating and bridal-design adaptation, and Austria for precision-faceted crystal components. Raw material dependencies draw from rhodium and palladium plating solutions, nickel-bearing base metal alloys, and biocompatible resin polymer feedstocks. Single-source vulnerability concentrates in crystal-cutting capabilities clustered in Wattens and Jablonec nad Nisou. Distribution runs through direct-to-consumer digital channels for trend-responsive velocity players and specialty retail for occasion-driven purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lab-grown diamond jewellery at declining price points threatens artificial jewellery incumbents with authenticity-seeking consumer migration, demanding active substitution defense through material science differentiation and regulatory compliance moats.
For Market Incumbents: Insulate core margin pools by accelerating backward integration into captive electroplating facilities certified for REACH and Proposition 65 compliance, and by deepening resin formulation R&D to capture dermatology-sensitive segments before biocompatible polymer alternatives scale. Swarovski Group and PANDORA A/S demonstrate how cutting-technology heritage and charm-system ecosystems respectively defend against commodity substitution. For New Entrants and Emerging Players: Establish a beachhead in India's Tier-2 and Tier-3 urban centers where organized retail penetration remains sparse and localized bridal design adaptation commands premium positioning. Target lightweight resin formulations for North American millennials with sensitive-skin positioning, and deploy augmented reality try-on tools to reduce return rates in size-sensitive ring categories. For Investors and Strategic Acquirers: EU Green Deal circular economy mandates reshape the acquisition landscape by privileging suppliers with auditable take-back infrastructure and pre-consumer scrap recovery systems. Long-term viability hinges on exposure to compliance-ready plating networks rather than undifferentiated zinc-alloy commodity production. The signal to monitor is ECHA enforcement acceleration against non-compliant imports, which will accelerate supplier consolidation toward certified facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Plating | REACH-certified electroplating facilities in Pforzheim and Surat absorb compliance cost spikes. |
| Biocompatible Resin Formulation Launch | Dermatology-sensitive polymer compounds capture North American millennial migration from nickel-bearing alloys. |
| Direct-to-Consumer Digital Channel Expansion | Owned-platform weekly drops bypass wholesale margin dilution for trend-responsive inventory turns. |
| Pre-Consumer Scrap Recovery Infrastructure | EU Green Deal recycled-content disclosure requirements favor suppliers with casting-operation take-back systems. |
| Augmented Reality Try-On Integration | Social commerce platform tools reduce return rates for size-sensitive ring purchases among mobile-first demographics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with costume-jewellery brand managers, electroplating facility technical directors, fast-fashion retail procurement leads, and dermatology-focused product development heads. Secondary validation drew from customs and trade data, BIS certification registries, ECHA restriction proposal documentation, and SEC filings of publicly traded accessories retailers. Bottom-up unit-volume modeling and top-down value-chain triangulation were cross-referenced to reconcile segment-level estimates.
Calibration against historical volume spikes around India's Diwali and wedding seasons anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material formulation, sale channel, and end-user application context. CAGRs were derived from trend extrapolation moderated by regulatory compliance cost trajectories and substitution elasticity parameters. Industry-specific forecast inputs incorporated rhodium price volatility bands and REACH nickel-release limit phase-in schedules.
Stress conditions across plating material cost swings, ECHA enforcement intensity, and lab-grown diamond price erosion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding festival calendar density persistence and social commerce adoption curves. Material shifts in EU circular economy mandate implementation timelines or breakthrough biocompatible resin cost parity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Luxury Jewelry Market
Jewelry
South Korea Luxury Jewelry Market
Jewelry
Global Gems and Jewelry Market
Jewelry
Brazil Jewelry Market
Jewelry
3D Printed Jewelry Market
Jewelry
China Luxury Jewelry Market
Jewelry
Global Jewelry Market
Jewelry
Japan Jewellery Market
Jewelry
China Jewellery Market
Jewelry
Colorful Gold Jewelry Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
Leather Jewellery Box Market
Jewelry
Luxury Fine Jewellery Market
Jewelry
South Africa Luxury Jewelry Market
Jewelry
Jewellery Market
Jewelry
Pearl Jewelry Market