
 Italy Luxury Jewelry Market | 2026-2036
Italy Luxury Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Luxury Jewelry Market Insights
Market Context
High-net-worth individual demand is realigning toward bespoke artisanal pieces over mass-luxury collections. Bulgari leverages its Rome heritage and vertical control over colored gemstone sourcing to command premium positioning. Buccellati sustains intricate hand-engraving traditions that differentiate its gold collections from mechanized competitors. Gucci navigates fashion-jewelry crossovers, extending brand equity into accessible luxury tiers while maintaining atelier credibility.
Technical Definition and Segment Structure
Italy luxury jewelry comprises precious-metal ornaments crafted with minimum gold fineness standards, incorporating gemstones or enamelwork for personal adornment, investment retention, and ceremonial gifting. Platinum segments dominate margin pools due to scarcity-driven pricing and wedding-band permanence, while silver artisanal lines attract fashion enthusiasts seeking accessible Italian craftsmanship. Online retail channels represent the fastest-growing distribution vector, though exclusive showrooms in Milan and Florence still anchor brand prestige and high-consideration purchases.
Regulatory Framework and Outlook
Italian hallmarking requirements enforced by the Ministry of Economic Development guarantee precious metal purity, while EU REACH and conflict mineral regulations compel documented supply chain transparency from mine to retail. BIS-equivalent Italian standards and CE marking obligations for certain imported components shape material qualification and market access protocols. Stakeholders must monitor evolving EU Green Deal sustainability mandates that will redefine recycled precious metal content thresholds and carbon disclosure expectations.
Market Dynamics
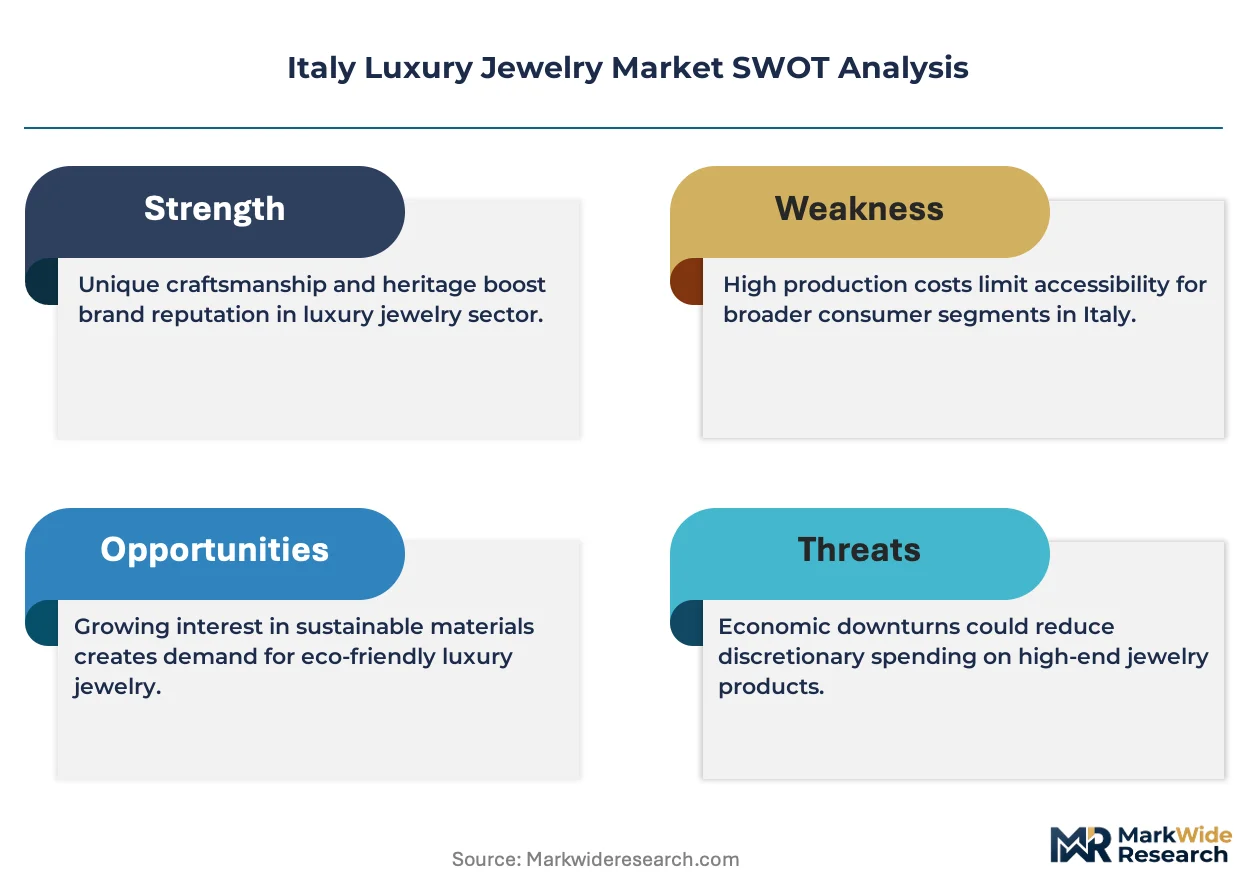
Affluent Italian consumers are pivoting from logo-driven acquisitions toward provenance-verified artisanal pieces, compressing margins for fashion-jewelry crossovers while amplifying rewards for heritage ateliers with documented supply chains.
Growth Catalysts
- EU Green Deal mandates:Recycled precious metal content thresholds are compelling refiners to restructure sourcing networks, creating first-mover advantages for Italian houses with established circular supply partnerships.
- Milan-Rome flagship concentration:Ultra-high-net-worth tourists and domestic collectors cluster in these cities, sustaining foot traffic that subsidizes experiential retail investments unavailable to digital-native entrants.
- Blockchain-based provenance tracking:Distributed ledger verification of gemstone origin is converging with consumer due diligence expectations, reducing friction in high-value transactions.
Market Restraints
- Platinum supply concentration:South African and Russian mine output dominates refined platinum availability, exposing Italian fabricators to geopolitical supply interruptions and price volatility.
- Artisan skill scarcity:Master engravers and filigree specialists in Valenza Po and Arezzo are aging out faster than apprenticeship pipelines replenish, constraining production scalability for heritage techniques.
- REACH compliance burdens:ECHA nickel release restrictions and cadmium prohibitions add testing costs and reformulation requirements that mechanized producers absorb more readily than micro-ateliers.
Strategic Opportunities
- Southern Italy underpenetration:Naples and Palermo lack flagship presence despite rising local wealth, offering whitespace for experiential showroom formats calibrated to regional ceremonial gifting customs.
- EU conflict mineral disclosure:Mandatory supply chain transparency is creating competitive differentiation for houses with mine-to-retail documentation already in place.
- Generational wealth transfer:Heirloom restyling services for inherited pieces are capturing younger collectors who reject passive asset holding in favor of wearable reinterpretation.
Industry Challenges
- Digital authentication integration:Embedding NFC chips and digital certificates into handcrafted pieces without compromising aesthetic integrity requires capital investment and technical partnerships unfamiliar to traditional goldsmiths.
- Cross-border VAT complexity:Intra-EU sales and non-EU tourist refund schemes demand specialized compliance infrastructure that fragments attention from core craft operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Luxury Jewelry Market |
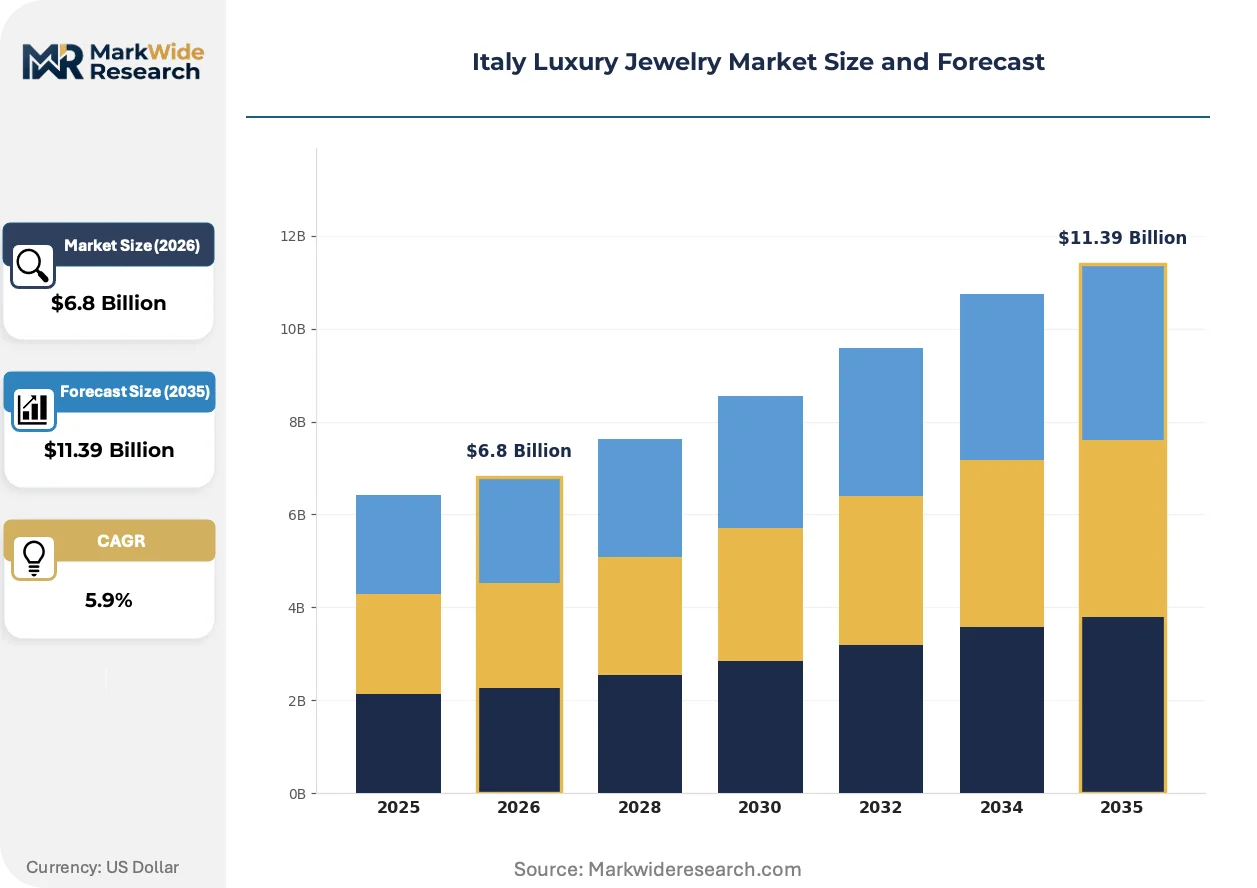
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diamonds, Gold, Silver, Platinum Customer Type: Affluent Consumers, High-Net-Worth Individuals, Gift Buyers, Fashion Enthusiasts Distribution Channel: Online Retail, Luxury Boutiques, Department Stores, Exclusive Showrooms Design Style: Classic, Contemporary, Artisanal, Vintage |
| Companies Covered | Buccellati, Bulgari, Gucci, Valentino, Picchiotti, Unoaerre, Giorgio Visconti, Pasquale Bruni, Veschetti, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Luxury Jewelry Market Trends and Innovations
Italian luxury jewelry is undergoing a material and experiential transformation where digital verification tools, circular sourcing mandates, and generational consumption pattern shifts are simultaneously reshaping production economics and brand-consumer relationships.
Laser-assisted micro-engraving and 3D-printed wax casting for lost-wax prototypes is converging with hand-finishing traditions, enabling ateliers to compress design-to-prototype cycles without sacrificing bespoke customization. Younger collectors in Milan and Rome are adopting these hybrid-manufactured pieces at accelerating rates. This convergence is compressing the competitive window for pure handcraft houses that lack digital integration capabilities.
EU Green Deal sustainability disclosure requirements are mandating carbon footprint reporting and recycled content verification across precious metal supply chains. Italian refiners and fabricators must now document smelter origins and energy inputs to maintain market access. Platinum wedding-band and investment-piece categories face the steepest compliance adjustments due to their reliance on newly mined material with higher embedded emissions.
Collector preferences are rotating from accumulation toward curation, with high-net-worth individuals reducing piece counts while increasing per-unit expenditure on documented provenance and restyling potential. Milanese consignment and resale platforms are displacing traditional secondary market opacity. This behavioral pivot is most visible among female collectors aged 35-50 who treat jewelry as liquid alternative assets requiring transparent resale pathways.
Italy Luxury Jewelry Market Segmentation
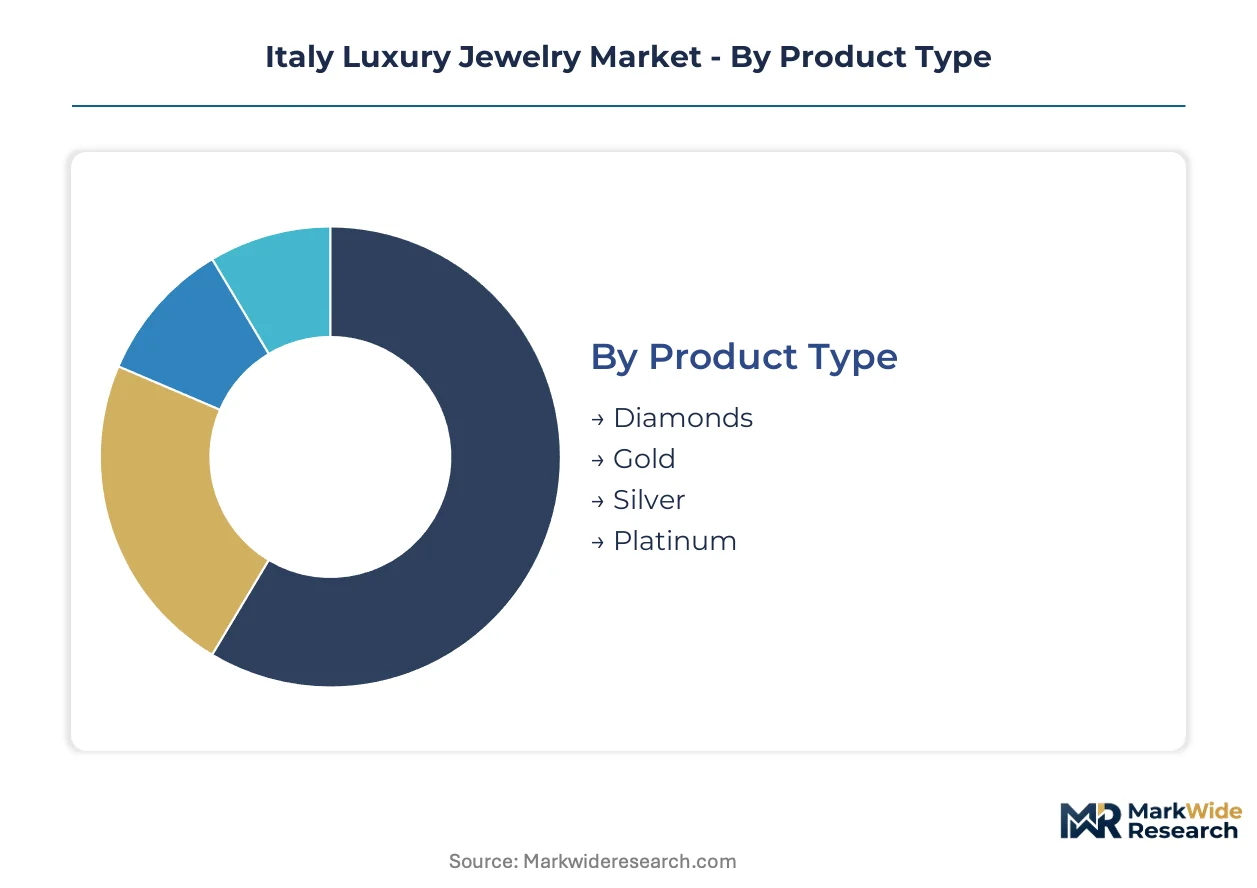
Segmentation in Italian luxury jewelry reveals how purchasing logic diverges across material preferences, customer psychology, and channel behavior. Understanding these splits enables targeted positioning against heritage ateliers and fashion-luxury crossovers competing for wallet share in Milan and Rome.
Product Type:
Integration depth varies sharply: gold and platinum segments anchor standalone investment and ceremonial purchases, while silver and diamond lines increasingly embed within fashion-jewelry crossovers and seasonal collections.
- Gold:18K and 22K yellow gold dominates Italian ceremonial gifting and wealth preservation, with Valenza Po fabricators supplying hand-engraved pieces to Roman collectors. Hallmarking requirements enforced by the Ministry of Economic Development guarantee purity standards that sustain premium positioning against lower-karat imports.
- Platinum:Scarcity-driven pricing and wedding-band permanence define this segment, though South African and Russian mine concentration exposes Italian fabricators to supply interruptions. EU Green Deal carbon disclosure mandates hit platinum hardest due to newly mined material's higher embedded emissions.
- Diamonds:Certified stones from Antwerp and Dubai cutters supply Milanese ateliers, with blockchain provenance tracking reducing friction in high-value transactions.
- Silver:Artisanal lines in Arezzo attract fashion enthusiasts seeking accessible Italian craftsmanship without precious metal entry barriers.
Gold leads volumes today; platinum is gaining share fastest among younger collectors prioritizing durability and hypoallergenic properties.
Customer Type:
Cost tier stratification separates passive asset holders from active collectors, with each group demanding different service intensity and provenance documentation.
- High-Net-Worth Individuals:Concentrated in Milan and Rome, these collectors pivot from logo-driven acquisitions toward provenance-verified artisanal pieces with documented supply chains and restyling potential.
- Affluent Consumers:Milanese professionals aged 35-50 treat jewelry as liquid alternative assets, driving demand for transparent resale pathways through consignment platforms.
- Fashion Enthusiasts:Younger adopters in Florence and Turin seek silver artisanal lines and contemporary designs that signal taste without heirloom price tags.
- Gift Buyers:Ceremonial purchasers across Southern Italy favor classic gold pieces for weddings and confirmations, with regional customs shaping weight and motif preferences.
High-Net-Worth Individuals dominate revenue per transaction; Fashion Enthusiasts are expanding most quickly as entry-luxury accessibility improves.
Distribution Channel:
Volume concentration clusters in experiential formats that subsidize brand prestige investments unavailable to digital-native competitors.
- Luxury Boutiques:Flagship locations on Via Monte Napoleone and Via Condotti anchor brand presence, with foot traffic from ultra-high-net-worth tourists sustaining personalized service models.
- Exclusive Showrooms:Appointment-only spaces in Florence and Vicenza serve collectors requiring private viewing environments for high-consideration purchases.
- Online Retail:Fastest-climbing channel among younger collectors comfortable with digital certificates and virtual try-on technologies.
- Department Stores:Rinascente and La Rinascente locations provide accessible entry points for gift buyers and tourists seeking authenticated Italian craftsmanship.
Luxury Boutiques capture the highest margin per square meter; Online Retail is expanding most quickly as authentication technologies mature.
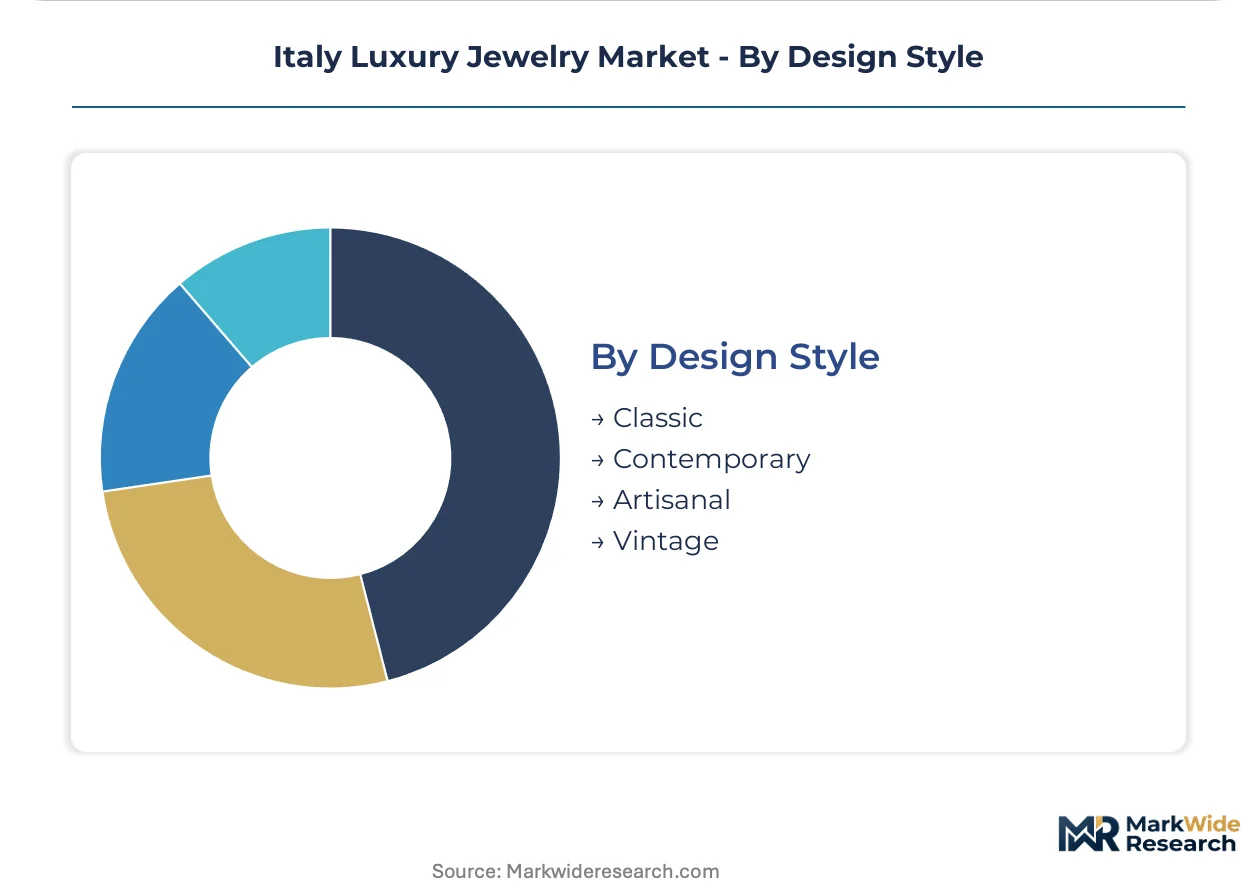
Design Style:
Maturity gradients separate centuries-old techniques from digitally enabled contemporary production, with hybrid manufacturing compressing the competitive window for pure handcraft houses.
- Artisanal:Hand-engraving and filigree traditions from Valenza Po and Arezzo differentiate heritage ateliers, though master craftsperson scarcity constrains production scalability.
- Classic:Timeless motifs dominate Southern Italian ceremonial markets, with generational wealth transfer driving heirloom restyling services.
- Contemporary:Laser-assisted micro-engraving and 3D-printed wax casting enable compressed design-to-prototype cycles without sacrificing customization.
- Vintage:Curated resale and restyling of inherited pieces captures younger collectors rejecting passive asset holding in favor of wearable reinterpretation.
Classic designs maintain the largest installed base; Contemporary styles are climbing the fastest as hybrid manufacturing adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Valenza Po anchors Italian luxury jewelry fabrication, with master goldsmiths in this Piedmontese cluster supplying hand-engraved ceremonial pieces to collectors nationwide. Regional demand patterns diverge sharply between Northern industrial centers and Southern ceremonial markets.
Lombardy
Milan concentrates ultra-high-net-worth collectors and flagship boutiques on Via Monte Napoleone. The Ministry of Economic Development enforces hallmarking standards that guarantee precious metal purity for pieces retailed here. Valenza Po fabricators maintain supply relationships with Milanese ateliers, shipping finished goldwork southward for final retail markup.
Lazio
Rome's collector base pivots toward provenance-verified artisanal pieces with documented supply chains. EU REACH regulations enforced by ECHA constrain nickel release and cadmium content in pieces sold through Roman showrooms. Bulgari's heritage presence on Via Condotti anchors brand prestige for tourists and domestic buyers seeking investment-grade colored gemstones.
Tuscany
Florence hosts appointment-only showrooms serving collectors requiring private viewing environments. The city's national pharmaceutical regulator equivalent oversees import documentation for Antwerp-sourced diamonds entering Tuscan ateliers. Arezzo silver artisans supply accessible craftsmanship lines to Florentine retailers targeting fashion enthusiasts.
Veneto
Vicenza's jewelry district specializes in mechanized production and export-oriented manufacturing. EU Green Deal sustainability mandates compel local refiners to document smelter origins and recycled content thresholds. The Vicenzaoro trade fair anchors international buyer access to Italian fabrication capabilities.
Campania
Naples lacks flagship luxury presence despite rising local wealth and ceremonial gifting customs. The country's central bank equivalent monitors cross-border VAT complexity for pieces entering Southern retail channels. Regional jewelers source from Northern fabricators, creating margin compression for independent operators without direct atelier relationships.
Italy Luxury Jewelry Market Competitive Landscape
Heritage positioning dominates the current landscape, with houses differentiating through documented craftsmanship traditions rather than scale economies. The vendor base concentrates among three strategic archetypes: heritage ateliers with master engraver networks, fashion-luxury crossovers leveraging apparel brand equity, and mechanized fabricators serving export markets. M&A activity targets distressed artisan workshops in Valenza Po, while capacity expansion concentrates in hybrid manufacturing facilities blending 3D-printed prototyping with hand-finishing.
Among heritage Italian houses, Buccellati, Bulgari, and Gucci occupy distinct positioning vectors. Buccellati exemplifies the master-engraver archetype with documented hand-craft traditions constraining production scalability. Bulgari anchors the colored-gemstone specialist tier through vertical control over sourcing pipelines. Gucci represents the fashion-luxury crossover model, extending brand equity into accessible jewelry tiers while maintaining atelier credibility for high-jewelry collections. These three structures illustrate how Italian competitors segment across price-positioning and craft-intensity axes without converging on identical operating models.
| Leading Market Players |
|---|
| Buccellati |
| Bulgari |
| Gucci |
| Valentino |
| Picchiotti |
| Unoaerre |
| Giorgio Visconti |
| Pasquale Bruni |
| Veschetti |
| Others |
Pricing and Supply Chain Analysis
Collector pivot toward provenance-verified artisanal pieces compels fabricators to absorb documentation and certification costs, compressing margins for mechanized producers while amplifying pricing power for heritage ateliers with established circular supply partnerships.
Pricing Analysis
Input-cost pass-through from South African and Russian platinum concentrate dominates margin structure for wedding-band fabricators, with scarcity-driven spot pricing amplifying volatility for houses lacking long-term offtake agreements. Three-tier pricing structure across heritage atelier, contemporary hybrid-manufactured, and fashion-jewelry crossover levels separates buyers by certification depth and restyling service bundling. Pricing pressure stems from REACH compliance testing burdens that mechanized producers absorb more readily than micro-ateliers. Fashion enthusiasts show highest price sensitivity, while high-net-worth individuals prioritize documented provenance over unit cost.
Supply Chain Analysis
EU conflict mineral disclosure and Italian hallmarking requirements enforced by the Ministry of Economic Development gate market access for refiners and fabricators, compelling documented smelter origins from mine to retail. South Africa, Russia, and Zimbabwe anchor platinum concentrate supply, while Antwerp and Dubai cutters feed certified diamonds to Milanese ateliers. Raw material dependencies center on newly mined platinum with higher embedded emissions, recycled gold feedstock, and Antwerp-sourced stones. Single-source vulnerability runs through South African mine concentration for platinum wedding bands. Distribution runs through flagship boutiques on Via Monte Napoleone and Via Condotti, with online retail climbing fastest among authenticated digital certificate adopters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where generational wealth transfer and heirloom restyling services are redirecting collector expenditure toward pieces with documented craftsmanship traditions and transparent resale pathways.
For Market Incumbents: Deepen master engraver apprenticeship pipelines in Valenza Po and Arezzo to constrain production scalability for competitors lacking equivalent craft networks. Fortify circular supply partnerships ahead of EU Green Deal recycled content thresholds to capture first-mover margin advantages. Channel control through exclusive showroom expansion in underpenetrated Southern Italy cities offers defensive positioning against digital-native entrants.
For New Entrants and Emerging Players: Virtual try-on technologies with blockchain-backed digital certificates offer the lowest-friction entry vector for younger collectors comfortable with remote authentication. Naples and Palermo present whitespace for experiential showroom formats calibrated to regional ceremonial gifting customs. Hybrid manufacturing facilities blending 3D-printed prototyping with hand-finishing compress capital requirements versus pure atelier establishment.
For Investors and Strategic Acquirers: Asymmetric upside sits with distressed artisan workshops in Valenza Po possessing documented craft traditions but lacking digital integration capabilities. Long-term viability hinges on generational replacement of master goldsmiths and filigree specialists. The inflection signal to watch is apprenticeship pipeline throughput relative to retiree replacement rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Master Craftsman Apprenticeship Expansion | Valenza Po and Arezzo workshops secure generational skill transfer against aging-out specialist scarcity. |
| Circular Supply Partnership Formation | Italian refiners document smelter origins to meet EU Green Deal recycled content mandates ahead of competitors. |
| Blockchain Provenance Integration | Distributed ledger verification reduces transaction friction for high-net-worth collectors demanding documented origin. |
| Southern Italy Flagship Expansion | Naples and Palermo showrooms capture rising local wealth absent incumbent heritage presence. |
| Heirloom Restyling Service Launch | Younger collectors convert passive inherited assets into wearable reinterpretations with transparent resale pathways. |
Research Methodology
Multiple input streams — primary interviews with heritage atelier owners, procurement leads at Milanese flagship boutiques, and master goldsmiths in Valenza Po, plus secondary validation through Italian Ministry of Economic Development hallmarking records, EU ECHA REACH compliance filings, and Antwerp diamond trade data — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, customer archetype, distribution channel, and regional production hub dimensions enabled segmentation-level modeling throughout the forecast period. CAGRs were derived from trend extrapolation of collector expenditure patterns and supply-side capacity constraints. Industry-specific forecast inputs incorporated EU Green Deal implementation timelines and master craftsperson demographic replacement rates.
The model assumes a particular technology adoption path for laser-assisted micro-engraving and 3D-printed wax casting; alternative pathways for pure handcraft preservation would alter the outlook for heritage atelier competitiveness. Forecasts reflect assumptions regarding apprenticeship pipeline replenishment and recycled precious metal feedstock availability. A model refresh is warranted upon material change in EU sustainability mandate enforcement or South African platinum supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Colorful Gold Jewelry Market
Jewelry
Global Body Piercing Jewelry Market
Jewelry
Canada Luxury Jewelry Market
Jewelry
3D Printing for Jewelry Market
Jewelry
Qatar Jewelry Market
Jewelry
Japan Jewellery Market
Jewelry
Artificial Jewellery Market
Jewelry
Mexico Luxury Jewelry Market
Jewelry
Global Costume Jewelry Market
Jewelry
Latin America Jewelry Market
Jewelry
Jewelry Cleaners Market
Jewelry
Brazil Jewelry Market
Jewelry
Jewellery Market
Jewelry
Luxury Jewelry Market
Jewelry
Crystal Bracelets Market
Jewelry
Quartz Ring Market